
 Commercial Panini Machine Market | 2026-2036
Commercial Panini Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Panini Machine Market Outlook
Modular countertop configurations with interchangeable plates and dual-zone heating is expanding buyer flexibility in commercial kitchens. Sirman leverages Italian engineering heritage to dominate European distribution channels for premium contact grills. The Vollrath Company anchors North American supply through extensive foodservice dealer networks and institutional contract strength. Globe Food Equipment competes on value-engineered platforms targeting independent restaurants with compact footprint designs.
A commercial panini machine is an electrically heated, clamshell-style contact grill constructed from cast iron or aluminum plates with ribbed or smooth surfaces, operating at temperatures between 175°C and 300°C to sear sandwiches, proteins, and flatbreads under controlled pressure and timing. The equipment serves quick-service restaurants, cafes, and catering operations requiring rapid, consistent thermal output with minimal operator skill. Contact grill configurations occupy the largest installed base due to versatility across menu categories from pressed sandwiches to proteins. Conveyor grill variants represent the fastest-expanding segment as high-volume chains automate throughput during peak service windows. Compact and medium sizes concentrate margin pools in the independent restaurant and food truck channels where space constraints override maximum output specifications.
NSF International standards govern food-contact surface safety and electrical certification for equipment deployed in US commercial kitchens, while the US Department of Energy regulates standby power consumption and thermal efficiency metrics. The European Union's Ecodesign Directive and CE marking requirements shape product development cycles for manufacturers exporting to EU member states. Stakeholders must monitor evolving energy-labeling thresholds and electrification incentives that will determine competitive positioning in replacement purchase decisions.
Market Dynamics
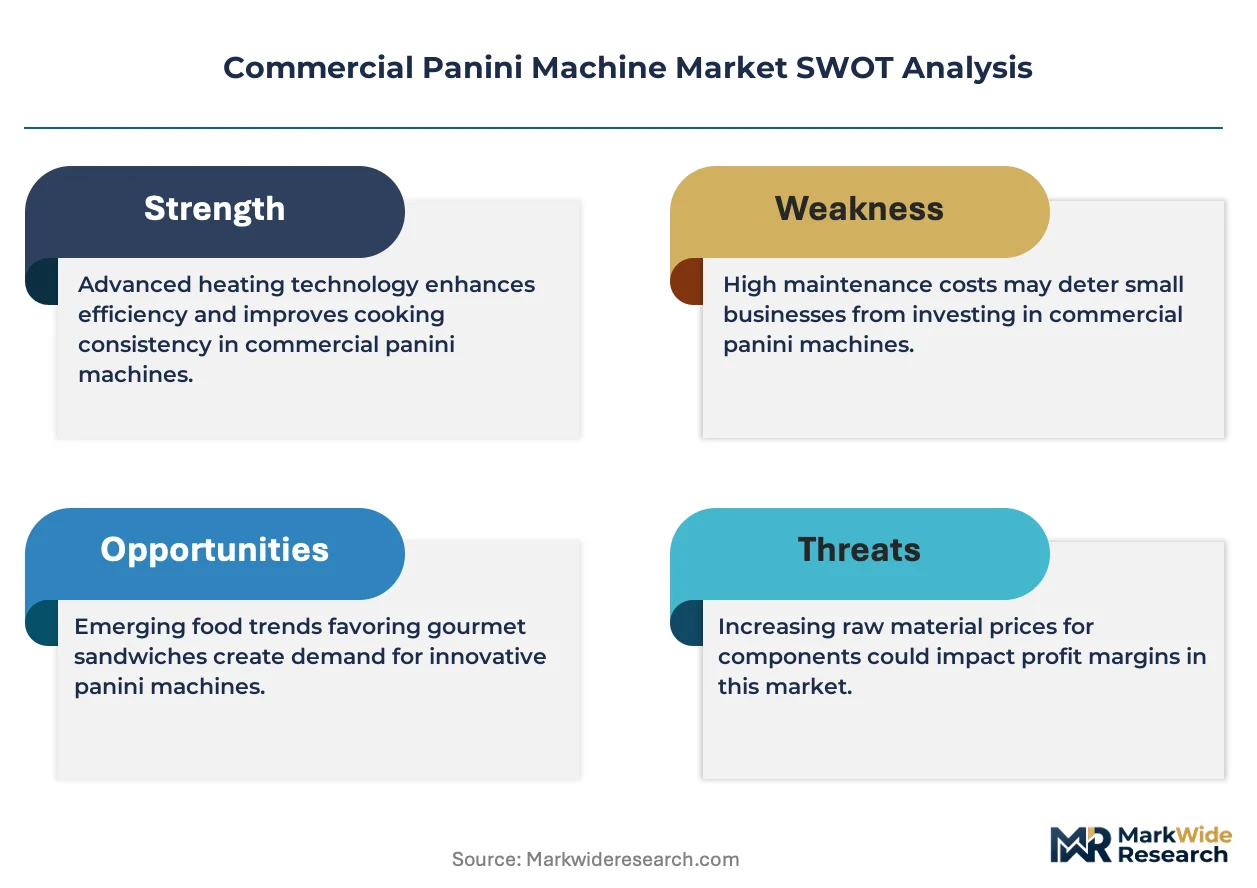
Foodservice labor shortages across North America and Western Europe are forcing operators to automate high-throughput grilling stations, compressing replacement cycles for programmable contact grills with minimal operator intervention requirements.
Growth Catalysts
- NSF International Certification Mandates:US commercial kitchen operators must replace non-certified equipment to maintain health department compliance, creating forced upgrade demand across independent restaurants and institutional cafeterias.
- Dual-Zone Heating Technology:Programmable temperature controls allow single units to handle proteins and sandwiches simultaneously, expanding menu versatility for fast-casual chains without additional footprint.
- German Energy Efficiency Standards:The EU Ecodesign Directive pushes manufacturers toward improved thermal insulation, accelerating replacement of legacy cast-iron models in European foodservice operations.
Market Restraints
- Aluminum and Cast Iron Input Volatility:Raw material price swings for plate construction compress margins for value-tier manufacturers dependent on commodity metal sourcing.
- European Supply Concentration:Premium contact grill production clusters in Northern Italy, creating geographic vulnerability for buyers seeking Italian-engineered equipment with extended lead times.
- Convection Oven Substitution:Multi-function convection units threaten standalone panini machine demand in space-constrained ghost kitchens and delivery-only operations.
Strategic Opportunities
- US Electrification Incentives:The Inflation Reduction Act offers tax credits for energy-efficient commercial kitchen equipment, creating procurement tailwinds for ENERGY STAR-certified contact grills in renovation cycles.
- Conveyor Automation Convergence:Integration of vision systems with conveyor grill platforms enables unattended operation during peak service windows for high-volume quick-service chains.
- Food Truck Channel Expansion:Compact countertop configurations with rapid heat-up cycles address power-constrained mobile foodservice operations seeking hot sandwich program expansion.
Industry Challenges
- NSF Certification Timeline Compression:Extended testing protocols for food-contact surface safety delay product launches, forcing manufacturers to front-load regulatory engagement in development cycles.
- Legacy Control System Integration:Kitchen Display System connectivity requirements for automated timing and pressure control create firmware complexity for equipment originally designed as standalone units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Panini Machine Market |
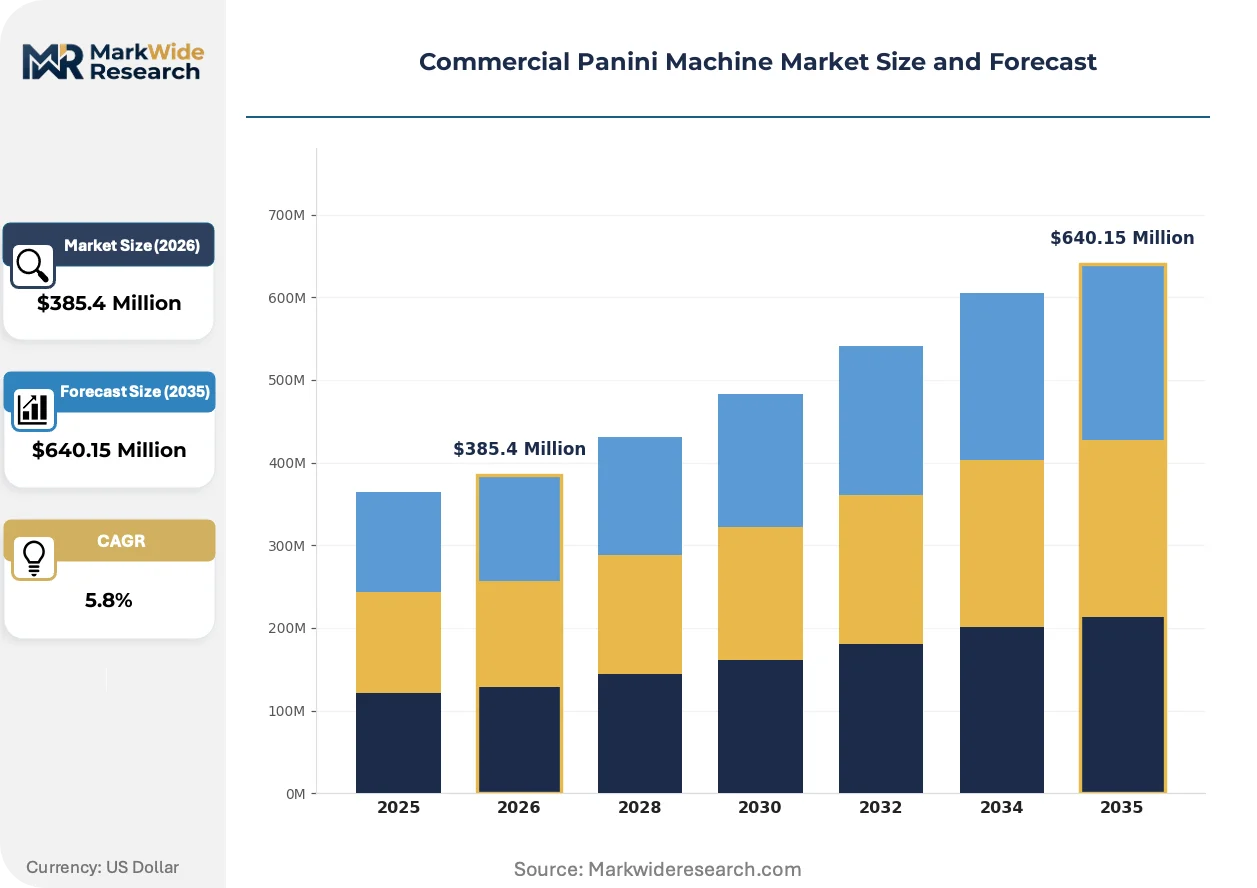
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Grill, Press Grill, Conveyor Grill, Multi-Function Grill End User: Restaurants, Cafes, Food Trucks, Catering Services Size: Compact, Medium, Large, Extra Large Power Rating: 500W, 1000W, 1500W, 2000W |
| Companies Covered | Sirman, The Vollrath Company, Cadco, Hatco, Globe Food Equipment, Sammic, Eurodib, Grindmaster-Cecilware, Nemco Food Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Panini Machine Market Strategic Shifts
Equipment architecture is fragmenting into configurable subsystems, allowing operators to reconfigure grilling surfaces and thermal zones without full unit replacement as menu strategies pivot.
Interchangeable plate systems with rapid-swap mechanisms are modularizing commercial kitchen capital planning. Fast-casual chains in the United States deploy single bases with ribbed, smooth, and grooved plate inserts across dayparts. This architecture compresses equipment counts per location while supporting menu innovation without additional footprint allocation.
EU Ecodesign Directive thresholds for standby power consumption are tightening product development cycles for manufacturers exporting to member states. The regulation forces redesign of control board architectures and heating element insulation. German and Italian equipment suppliers face the steepest compliance curves given their concentration in premium export markets.
Foodservice procurement patterns are compressing vendor consolidation timelines as multi-unit operators centralize equipment specification. Dealer networks in North America face disintermediation pressure from direct manufacturer relationships with national fast-casual accounts. This concentration is most visible in United States quick-service restaurant chains standardizing on single-source contact grill platforms across franchise systems.
Commercial Panini Machine Market Segmentation
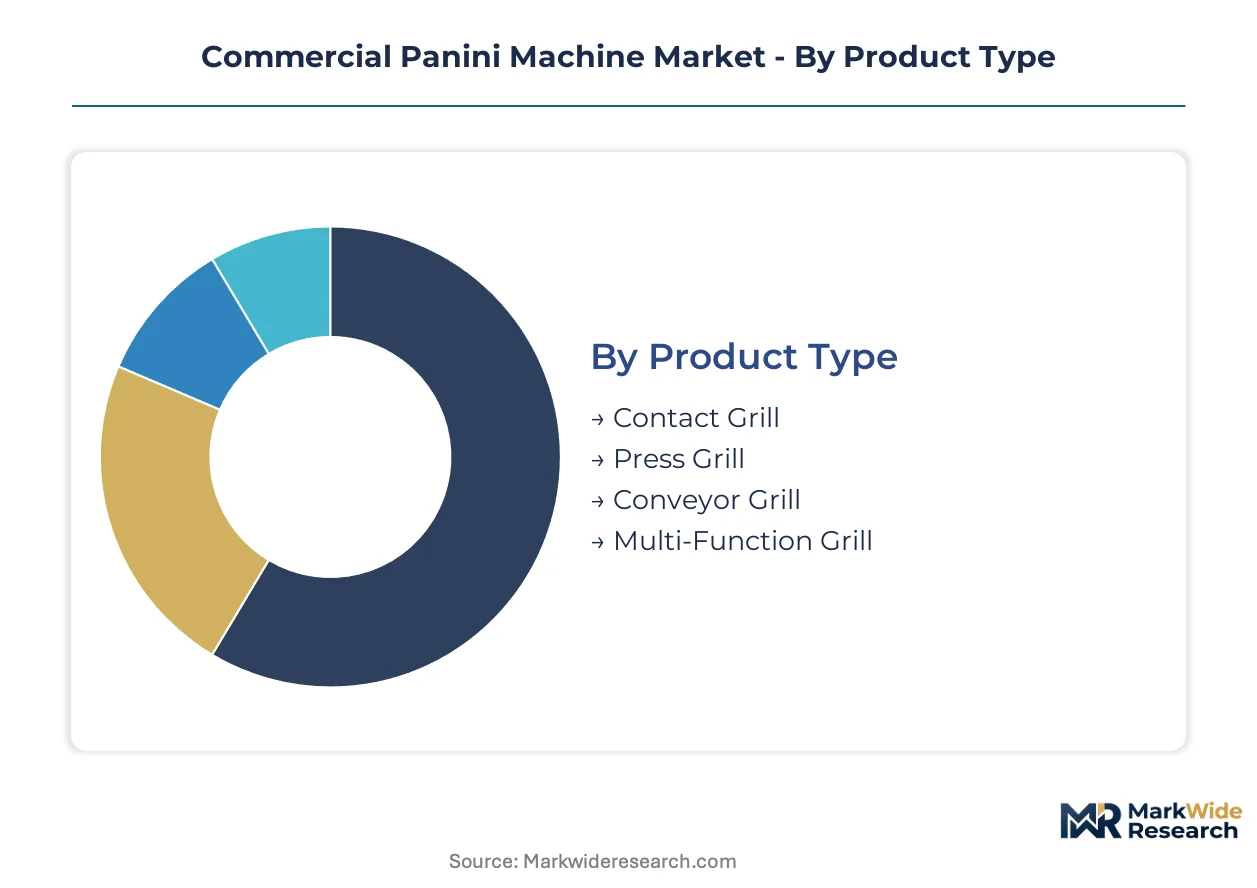
Equipment segmentation in the commercial panini machine market determines replacement cycle timing and capital allocation priorities across foodservice operators. Distinct product configurations, power specifications, and size categories align with specific operational constraints from urban cafes to high-volume catering halls.
Product Type:
Upgrade cycles vary sharply by product architecture, with programmable contact grills driving replacement demand as operators retire manual timer units for automated temperature control systems.
- Contact Grill:Clamshell-design units with cast iron or aluminum plates deliver direct surface heating for pressed sandwiches and proteins. Quick-service restaurants in the United States concentrate procurement here, prioritizing NSF-certified models with dual-zone temperature control to compress labor requirements during peak service windows.
- Conveyor Grill:Automated belt systems move product through fixed heating zones for unattended operation. High-volume chains expanding hot sandwich programs across Germany and Italy favor this configuration to address foodservice labor shortages while maintaining throughput consistency during lunch rushes.
- Press Grill:Manual lever-operated units with weighted top plates serve lower-volume operations seeking simple mechanical reliability without electronic control complexity.
- Multi-Function Grill:Modular platforms accepting interchangeable plate inserts for ribbed, smooth, or grooved surface configurations.
Contact Grill sits at the top of the volume ranking, with Conveyor Grill climbing the fastest.
End User:
Customer-type segmentation reveals divergent procurement patterns, with institutional buyers prioritizing energy efficiency certifications while independent operators emphasize unit footprint and rapid heat-up cycles.
- Restaurants:Full-service and fast-casual establishments deploy medium and large contact grills for hot sandwich programs and protein finishing. Chains across Italy and Germany specify EU Ecodesign Directive-compliant units to preempt regulatory retrofit requirements during renovation cycles.
- Food Trucks:Mobile operators face severe space and power constraints, driving demand for compact 1000W-1500W units with rapid thermal recovery. The United States food truck channel is expanding hot sandwich menus, prioritizing countertop configurations that minimize generator load while maintaining searing temperatures.
- Cafes:Coffee-focused operations with limited back-of-house space favor single-plate press grills for occasional sandwich service without dedicated equipment stations.
- Catering Services:Event-based foodservice requires portable, high-output units for off-site preparation with minimal setup time.
Restaurants command the largest installed base, while Food Trucks are gaining share fastest among end-user categories.
Size:
Footprint specifications directly determine addressable market scope, with urban real estate constraints in major metropolitan areas compressing demand toward compact and medium configurations.
- Compact:Countertop units under 18 inches in width target space-constrained operations. Food trucks and urban cafes in the United States specify these for hot sandwich program expansion without kitchen reconfiguration, accepting lower hourly throughput in exchange for operational flexibility.
- Medium:Mid-size platforms balance output capacity with footprint efficiency for independent restaurants. German fast-casual chains standardize on medium contact grills with programmable controls to automate peak-period grilling stations without expanding kitchen square footage.
- Large:Extended cooking surfaces serve high-volume catering and institutional cafeterias requiring simultaneous batch processing.
- Extra Large:Industrial-scale conveyor systems for centralized production kitchens and commissary operations feeding multiple locations.
Medium size configurations dominate current procurement volumes, with Compact units showing the steepest expansion trajectory among independent operators.
Power Rating:
Electrical load specifications segment the market by infrastructure compatibility, with 208V and 240V installation requirements filtering available options during replacement decisions.
- 1500W:Mid-range power draw balances thermal output with standard electrical service compatibility. Italian manufacturers concentrate production here for European export markets, aligning with EU Ecodesign Directive standby power thresholds while delivering sufficient searing capacity for protein finishing.
- 2000W:High-output units maximize surface temperature recovery during continuous loading. United States quick-service restaurants deploy these for conveyor grill automation, leveraging higher wattage to maintain consistent browning across unattended peak service periods.
- 500W:Low-power units for light-duty occasional use in cafes with minimal sandwich volume.
- 1000W:Entry-level power rating for compact configurations in power-constrained mobile foodservice operations.
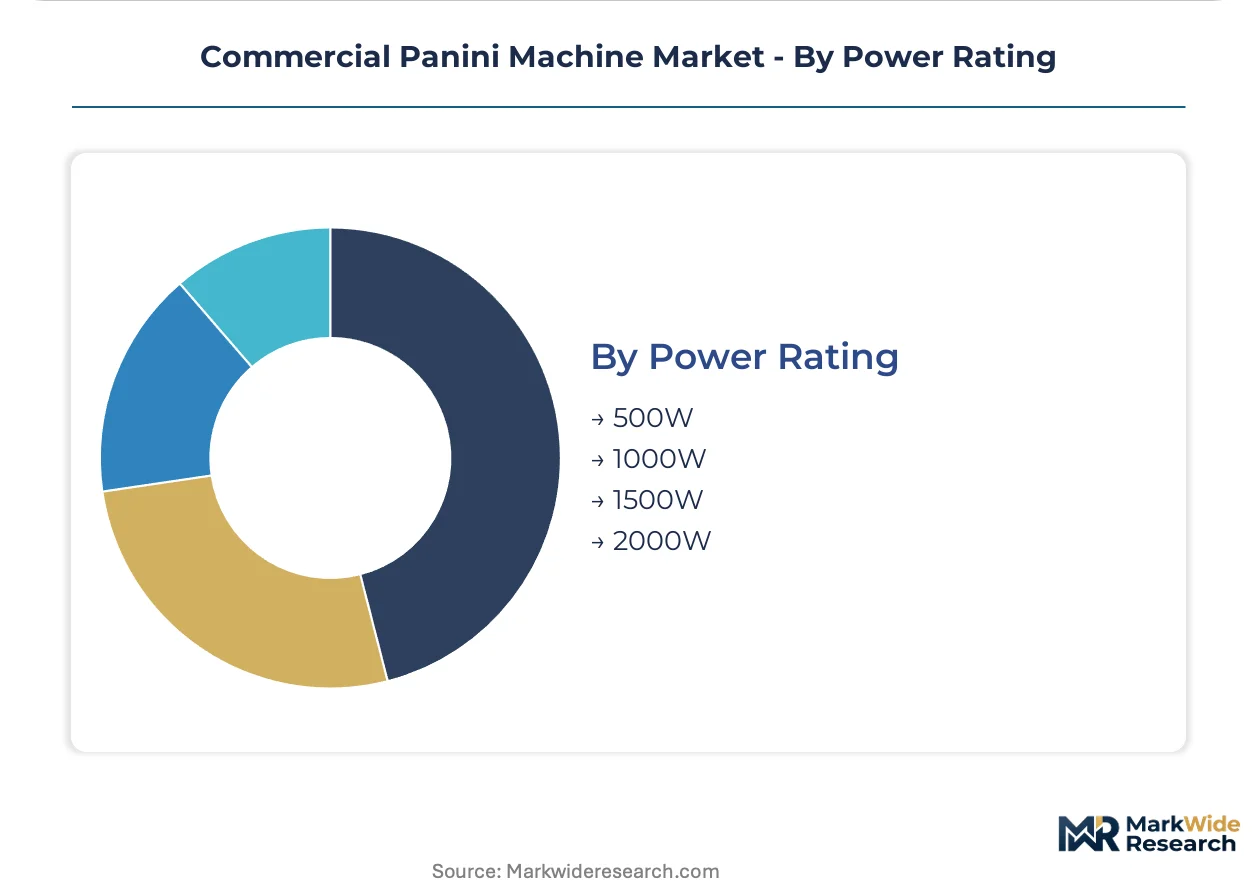
1500W units hold the largest share of current installations, with 2000W configurations expanding most quickly among high-volume chain specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian engineering workshops commercialized the contact grill format in the 1980s, establishing design conventions that persist across European and North American equipment specifications. Commercial panini machine demand now clusters in foodservice renovation corridors where labor automation intersects with energy compliance mandates.
United States
Quick-service restaurant chains compress replacement cycles for programmable contact grills as franchise systems standardize equipment specifications across thousands of locations. The US Department of Energy enforces standby power consumption thresholds that disqualify legacy cast-iron models from federal procurement contracts. Chicago and Dallas-Fort Worth anchor dealer network distribution, with regional foodservice equipment houses maintaining inventory for rapid renovation turnaround.
Germany
Fast-casual chains automate grilling stations to offset acute foodservice labor shortages in urban centers. The EU Ecodesign Directive mandates thermal insulation improvements that accelerate retirement of uninsulated plate designs. Bavaria concentrates premium equipment manufacturing, with Nuremberg-area fabricators supplying programmable dual-zone units across Central European markets.
Italy
Independent restaurants and cafe chains drive replacement demand for compact countertop configurations with rapid heat-up cycles. CE marking requirements under EU machinery directives shape control board architectures for export-bound equipment. Northern Italy, particularly the Veneto and Emilia-Romagna regions, hosts engineering clusters that supply ribbed-plate contact grills to European distribution networks.
France
Cafe and bistro operators seek space-efficient press grills for occasional hot sandwich service without dedicated kitchen stations. The country's national energy regulator enforces standby power thresholds that filter available equipment options during replacement decisions. The Île-de-France region concentrates procurement volume, with Paris-area foodservice distributors stocking medium-format units for urban renovation projects.
United Kingdom
Fast-casual expansion and ghost kitchen proliferation create demand for compact, high-output grilling equipment in space-converted urban premises. Health and Safety Executive guidelines for commercial kitchen electrical safety influence specification requirements for imported equipment. Greater London anchors volume concentration, with equipment dealers serving central business district renovation cycles and suburban chain rollouts.
Commercial Panini Machine Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification tiering and thermal control sophistication, with NSF International and ENERGY STAR compliance separating price bands. The vendor base organizes into three strategic archetypes: Italian-engineered premium specialists, North American institutional contract holders, and value-tier compact equipment fabricators. Dominant competitive moves include geographic distribution network expansion and product portfolio diversification into modular, interchangeable-plate configurations.
Among Italian-engineered specialists, Sirman exemplifies the premium-tier archetype through European distribution channel dominance. The Vollrath Company anchors North American institutional supply through extensive foodservice dealer networks. Globe Food Equipment occupies the value-engineered position, targeting independent restaurants with compact footprint designs. These three players represent distinct margin-tier strategies without overlapping positioning.
| Leading Market Players |
|---|
| Sirman |
| The Vollrath Company |
| Cadco |
| Hatco |
| Globe Food Equipment |
| Sammic |
| Eurodib |
| Grindmaster-Cecilware |
| Nemco Food Equipment |
| Others |
Value Chain & Pricing Dynamics
Foodservice labor automation mandates across the United States and Germany are compressing procurement timelines for NSF-certified and EU Ecodesign-compliant equipment, forcing manufacturers to absorb certification costs or sacrifice margin while buyers consolidate specifications around programmable dual-zone platforms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Italian-engineered contact grills with CE marking and extended warranties from value-tier compact units targeting independent restaurants. Price differentiation centers on certification grade and thermal control sophistication, with ENERGY STAR qualification commanding measurable premiums. Cost compression in the economy tier is intensifying because aluminum and cast iron input volatility squeezes fabricators dependent on commodity metal sourcing. Independent restaurants exhibit highest price sensitivity, while institutional buyers prioritize lifecycle operating costs over upfront capital outlay.
Supply Chain Analysis
NSF International and CE marking requirements filter supplier participation, with premium contact grill production clustering in Northern Italy, Bavaria, and domestic US fabrication centers serving institutional contracts. Raw material dependencies center on cast iron plate casting, aluminum extrusion for housing components, and control board assemblies sourced from East Asian electronics suppliers. Single-source vulnerability concentrates in Italian-engineered heating element supply for dual-zone configurations. Distribution runs through foodservice dealer networks in Chicago and Dallas-Fort Worth, with direct manufacturer relationships disintermediating regional houses for national fast-casual accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a geographic-arbitrage play where EU Ecodesign Directive compliance costs in Germany and Italy exceed US Inflation Reduction Act electrification incentives, creating procurement timing advantages for North American operators.
For Market Incumbents: Extend programmable control platform architectures into conveyor automation configurations to preempt substitution from multi-function convection ovens in ghost kitchen deployments. Deepen backward integration into cast iron plate casting to insulate margin from aluminum commodity volatility while securing NSF certification continuity. For New Entrants and Emerging Players: The Inflation Reduction Act in the United States opens a window for ENERGY STAR-certified compact equipment targeting food truck channel expansion with rapid heat-up cycles and generator-compatible power draws. White-space concentration sits with power-constrained mobile foodservice operations and urban cafe renovation cycles seeking countertop flexibility without kitchen reconfiguration. A direct-to-operator digital sales model bypasses entrenched dealer network gatekeeping. For Investors and Strategic Acquirers: Asymmetric upside sits with Italian-engineered premium specialists possessing established CE marking pathways and Northern European distribution density. Long-term viability over the mid-decade window favors manufacturers with modular platform architectures enabling plate interchangeability without full unit replacement. The signal to watch is consolidation velocity among US fast-casual chains standardizing equipment specifications across franchise systems.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Expansion | Interchangeable plate systems reduce capital intensity for fast-casual menu pivots. |
| Certification Pre-Loading | Early NSF and CE engagement compresses product launch timelines against regulatory drift. |
| Conveyor Automation Integration | Vision system partnerships enable unattended peak-period operation for high-volume chains. |
| Dealer Network Disintermediation | Direct national accounts relationships capture margin from fragmented foodservice distribution. |
| Energy Efficiency Repositioning | ENERGY STAR qualification unlocks Inflation Reduction Act procurement tailwinds. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with foodservice equipment procurement directors, commercial kitchen design consultants, NSF International certification engineers, and regional dealer network managers with secondary validation against US Department of Energy appliance standards filings, EU Ecodesign Directive implementation reports, and foodservice operator capex disclosures. Bottom-up unit economics and top-down market sizing triangulated volume and value estimates.
Historical reference periods anchored the projection horizon, with CAGRs derived from segmented growth trajectories across contact grill, conveyor grill, press grill, and multi-function grill configurations, further disaggregated by compact, medium, large, and extra-large size categories and 1500W versus 2000W power ratings. Input assumptions incorporated foodservice labor automation adoption curves, energy compliance threshold tightening schedules, and raw material cost pass-through elasticity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt commodity metal price spikes or accelerated EU standby power regulation tightening. A model refresh is warranted upon material change in US electrification incentive program continuity or major fast-casual chain equipment standardization announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Non Thermal Processing Market
Food Processing Equipment
Convection Ovens Market
Food Processing Equipment
Deep Fryer Market
Food Processing Equipment
Salmon Fish Scaling Machine Market
Food Processing Equipment
Bottling Line Machinery Market
Food Processing Equipment
Automatic Grilling Machine Market
Food Processing Equipment
Oven Market
Food Processing Equipment
Plastic Processing Machinery Market
Food Processing Equipment
Griddle Market
Food Processing Equipment
De-Agglomerating Equipment Market
Food Processing Equipment
Bread Processing Equipment Market
Food Processing Equipment
Food Disinfection Equipment Market
Food Processing Equipment
Flakes Making Machine Market
Food Processing Equipment
Global Commercial Refrigeration Market
Food Processing Equipment
Europe Household Food Waste Composting Machine Market
Food Processing Equipment
Tortilla Machine Market