
 Spiral Cooler Market | 2026-2036
Spiral Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Spiral Cooler Market Analytics
Market Context
China is fragmenting as domestic cold-chain infrastructure investment draws new entrants into spiral cooler manufacturing. GEA sustains European market presence through specialized hygienic designs for dairy and protein processing. Mayekawa dominates Asian installations with ammonia-based refrigeration systems for large-scale food factories. Mitsubishi Electric leverages precision inverter technology to compete in premium conveyor-cooling segments.
Technical Definition and Segment Structure
A spiral cooler is a continuous-belt heat exchange system that moves products through a helical path while forced air or cryogenic agents reduce core temperatures, typically achieving throughput rates from 500 kg to 15,000 kg per hour. The equipment serves food safety and shelf-life extension requirements in high-volume production environments where batch cooling creates bottlenecks. Horizontal coolers occupy the largest installed base due to compatibility with existing production lines and lower facility height requirements. Custom coolers capture disproportionate margin pools as engineering-intensive contracts for integrated freezing-cooling lines command premium pricing over standardized units. Thermoelectric technology remains nascent in spiral configurations but attracts R&D investment for small-footprint catering and supermarket display applications.
Regulatory Environment and Outlook
The US EPA regulates refrigerant transitions through SNAP approvals and AIM Act phasedowns, while the EU F-Gas Regulation mandates GWP thresholds that reshape equipment specifications across member states. China's GB energy-efficiency standards and SAMR certification requirements create compliance layers for imported and locally manufactured systems alike. Stakeholders must monitor refrigerant chemistry developments and regional efficiency benchmark revisions to align product roadmaps with shifting compliance timelines.
Market Dynamics
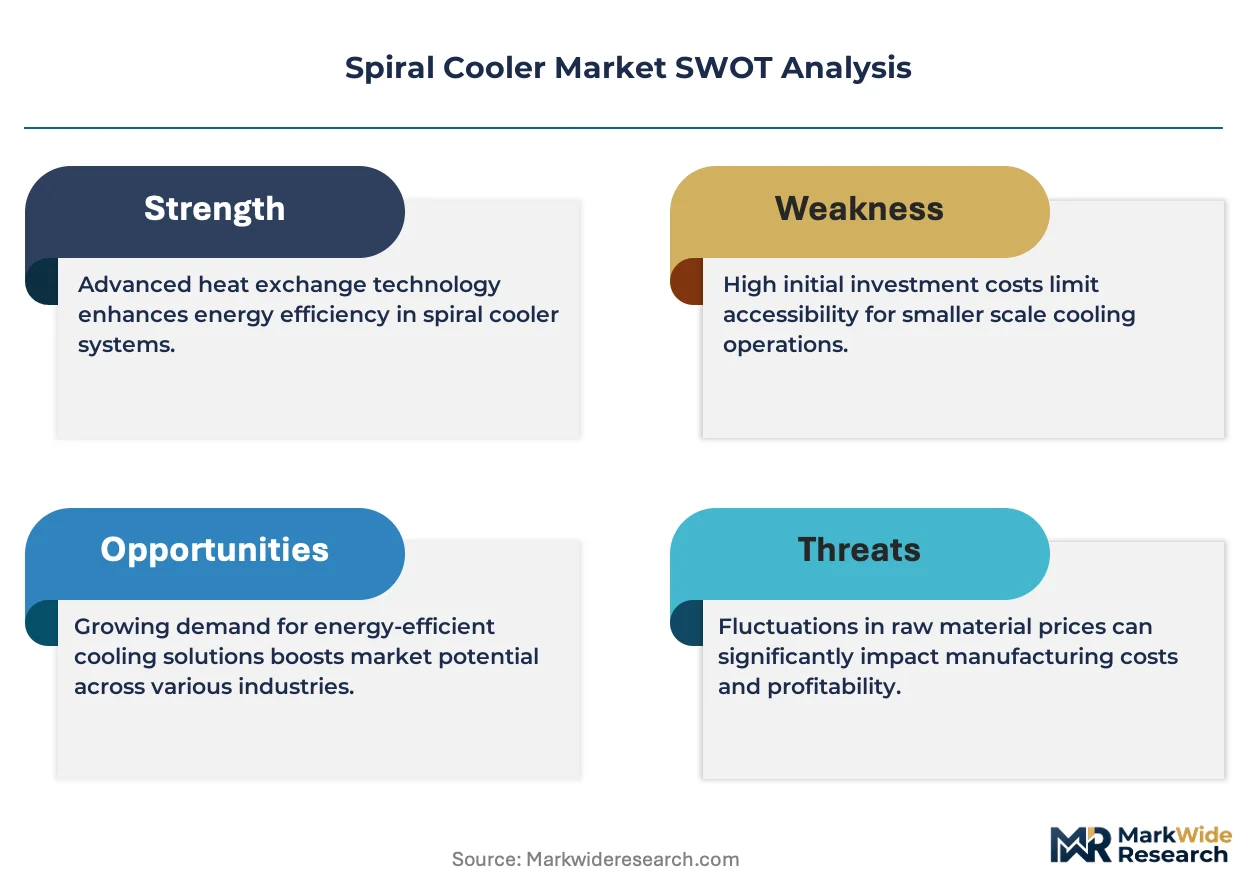
EU F-Gas Regulation mandates on hydrofluorocarbon phasedowns are forcing refrigerant chemistry transitions across installed spiral cooler bases, compressing replacement cycles and reshaping vendor technical roadmaps toward ammonia and CO2 architectures.
Growth Catalysts
- EU F-Gas Regulation:Mandated GWP thresholds accelerate equipment replacement in German and French industrial bakeries, pulling forward demand for next-generation low-refrigerant systems.
- Continuous processing:Ready-to-eal meal manufacturers adopt spiral configurations to eliminate batch-cooling bottlenecks and extend shelf-life compliance with FDA food safety protocols.
- China cold-chain investment:Domestic infrastructure buildouts create captive demand for locally manufactured spiral coolers in protein processing corridors around Shanghai and Guangzhou.
Market Restraints
- Refrigerant input volatility:Ammonia and CO2 supply constraints in European markets create procurement uncertainty for equipment manufacturers scaling production.
- Technical limitation:Thermoelectric cooling remains thermally inefficient above 500 kg per hour throughput, capping addressable market in high-volume segments.
- Regulatory friction:China's SAMR certification requirements impose extended approval timelines for imported European systems, delaying market entry.
Strategic Opportunities
- India protein processing:Underpenetrated automated poultry and seafood cooling infrastructure creates first-mover positioning for ammonia-based spiral installations.
- Technology convergence:Integration of precision inverter drives with IoT-enabled predictive maintenance architectures enables premium service revenue streams.
- US EPA SNAP program:Approved low-GWP refrigerant pathways create regulatory tailwind for equipment vendors targeting California and Northeast state markets.
Industry Challenges
- Refrigeration engineering talent gap:Scarce expertise in ammonia system design and safety protocols constrains vendor scaling and project execution timelines.
- Legacy integration complexity:Brownfield bakery and meat processing facilities require customized mechanical interfaces, extending engineering cycles and compressing margins on standardized product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spiral Cooler Market |
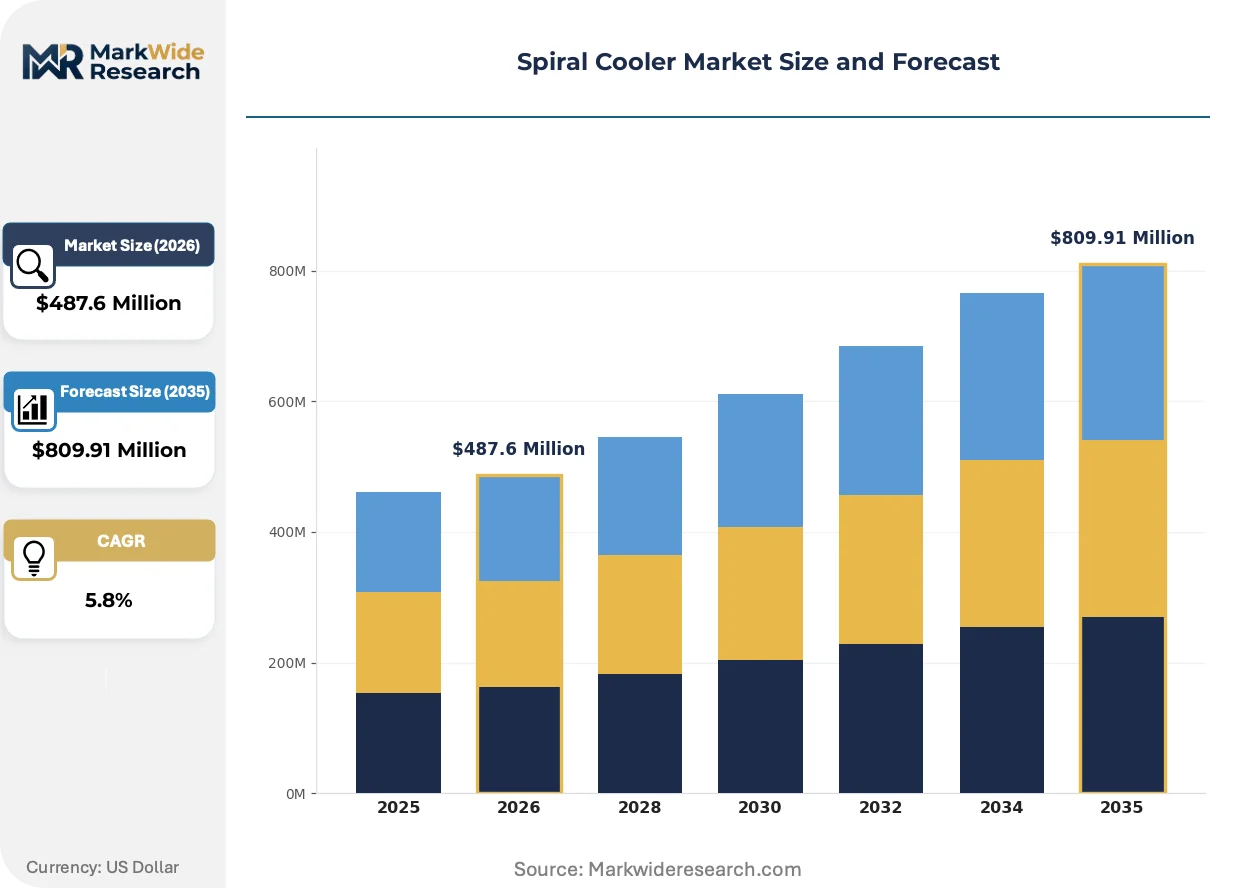
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Coolers, Vertical Coolers, Portable Coolers, Custom Coolers Application: Food Processing, Beverage Cooling, Bakery Applications, Industrial Use End User: Restaurants, Supermarkets, Food Manufacturers, Catering Services Technology: Refrigeration Systems, Thermoelectric Technology, Air Cooled, Water Cooled |
| Companies Covered | Trane, Johnson Controls, Mitsubishi Electric, Haier, GEA, Mayekawa, Linde, Air Products and Chemicals, Messer Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spiral Cooler Market Evolving Landscape
Refrigerant chemistry transitions and digital control architectures are compressing equipment lifecycles while opening service-based revenue models. Vendors must now engineer for regulatory compliance timelines rather than pure thermal efficiency benchmarks.
CO2 transcritical refrigeration is collapsing the technical barrier between industrial freezing and cooling applications. German dairy processors are piloting unified CO2 architectures that eliminate separate ammonia systems for medium-temperature cooling. This convergence is collapsing vendor product line differentiation and pressuring ammonia-specialist margins in European markets.
The EU F-Gas Regulation's 2024-2030 phasedown schedule mandates equipment-level GWP compliance, forcing redesign of compressor and heat exchanger specifications. Industrial bakery operators in France and Italy face accelerated replacement deadlines for installed HFC-based spiral coolers. Equipment vendors are responding with modular retrofit kits that preserve existing conveyor mechanics while replacing refrigerant circuits.
Buying committees in North American protein processing are unbundling after-sales service from initial equipment contracts, creating independent service markets. Third-party refrigeration contractors now compete directly with OEM service arms for maintenance and refrigerant management. This shift is most visible in Texas and Nebraska beef processing corridors where multi-vendor site standardization reduces captive service lock-in.
Spiral Cooler Market Segmentation
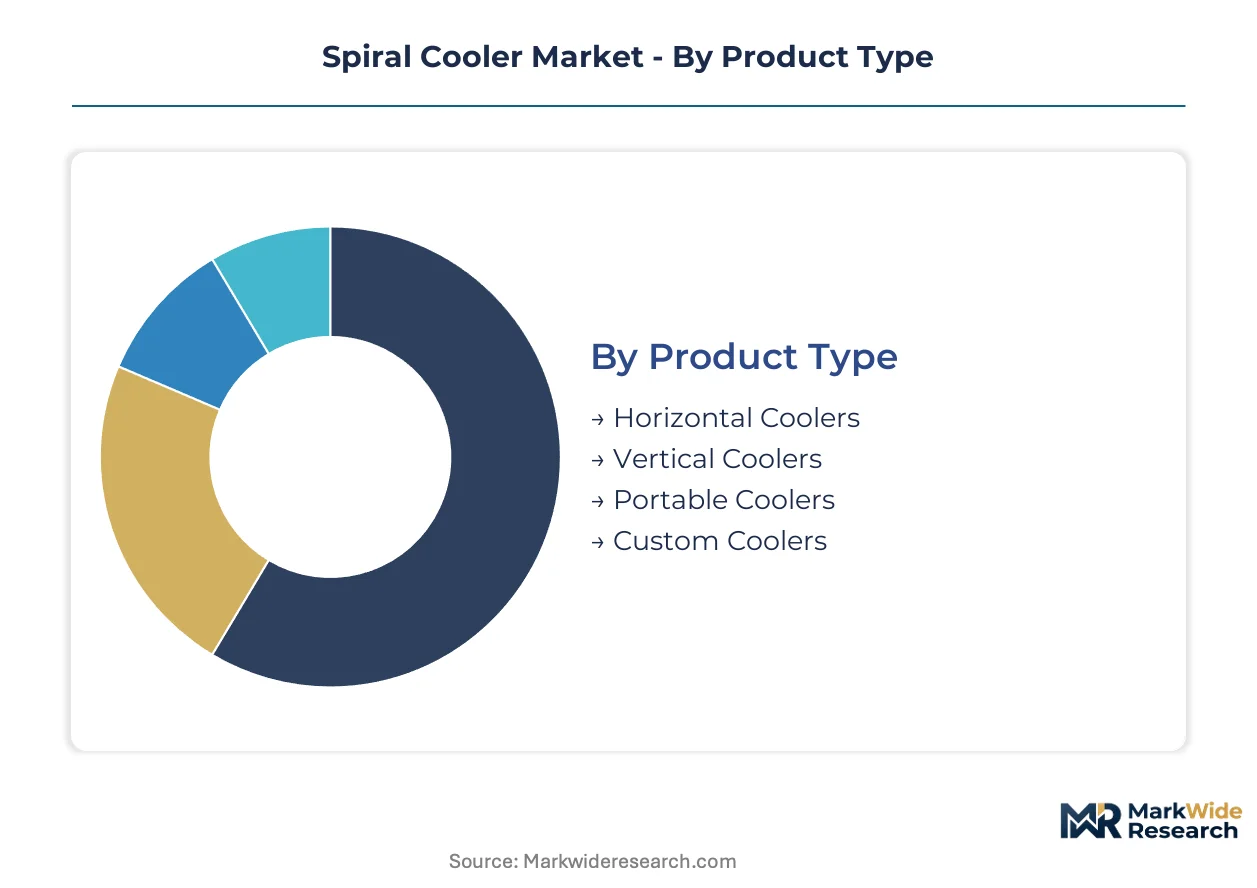
Spiral cooler procurement cycles vary dramatically by segment, with standardized horizontal units turning over every 7-10 years while custom-engineered systems extend to 15-year replacement windows. Understanding these velocity differentials helps vendors align inventory, service contracts, and R&D roadmaps with actual demand patterns rather than aggregate market movements.
Product Type:
Horizontal coolers rotate through replacement cycles fastest due to standardized designs and volume-driven depreciation schedules, while custom configurations persist longest through rebuild programs and modular retrofits.
- Horizontal Coolers:These units employ flat-belt helical configurations optimized for facility height constraints under 4 meters, dominating retrofit installations in legacy bakeries. German industrial bakeries in North Rhine-Westphalia concentrate procurement here, driven by EU F-Gas Regulation deadlines forcing refrigerant circuit replacements without structural modifications.
- Custom Coolers:Engineered-to-order systems integrate freezing-cooling lines with site-specific conveyor mechanics and ammonia safety protocols. French dairy processors around Laval commission these for unified CO2 transcritical architectures that collapse separate system requirements.
- Vertical Coolers:Tall helical towers exploit gravity for product handling in greenfield facilities with 6+ meter clearances.
- Portable Coolers:Compact units serve temporary capacity needs and pilot production lines with rapid deployment timelines.
Horizontal coolers anchor the volume base while custom configurations gain share at the steepest rate as regulatory complexity rewards engineering-intensive procurement.
Application:
Margin profiles diverge sharply across applications, with protein processing commanding premium pricing for hygienic design compliance while beverage cooling competes on throughput efficiency metrics.
- Food Processing:Meat and poultry operations require stainless-steel construction with IP69K washdown ratings and continuous core temperature monitoring. Texas beef processors unbundle after-sales service from equipment contracts, creating independent maintenance markets for spiral cooler fleets.
- Bakery Applications:Crust-firming and moisture-retention specifications drive belt speed precision within 2% variance. Italian industrial bakeries in Emilia-Romagna face accelerated HFC phaseout timelines under EU F-Gas Regulation, pulling forward demand for CO2 retrofit kits.
- Beverage Cooling:High-throughput can and bottle lines prioritize rapid pull-down rates over extended dwell times.
- Industrial Use:Non-food chemical and pharmaceutical applications impose validation documentation burdens distinct from food safety protocols.
Food processing commands the dominant revenue share while bakery applications expand most quickly amid regulatory compression of replacement cycles.
End User:
Procurement authority concentrates differently by end user type, with food manufacturers maintaining captive engineering teams while food service operators rely on distributor specification support.
- Food Manufacturers:High-volume producers specify integrated cooling-freezing lines with IoT-enabled predictive maintenance architectures. Shanghai protein processors source from domestic manufacturers under China's GB energy-efficiency standards, bypassing SAMR certification delays for imported European systems.
- Supermarkets:In-store bakery and prepared meal operations demand compact footprints with plug-and-play installation. Northeast US chains target California and state-level low-GWP mandates through EPA SNAP-approved refrigerant pathways.
- Restaurants:Central kitchen configurations prioritize reliability over efficiency optimization in franchise networks.
- Catering Services:Event-driven demand patterns favor rental and lease structures over capital acquisition.
Food manufacturers dominate installed base value while supermarkets climb the fastest as fresh-prepared meal expansion reconfigures retail refrigeration requirements.
Technology:
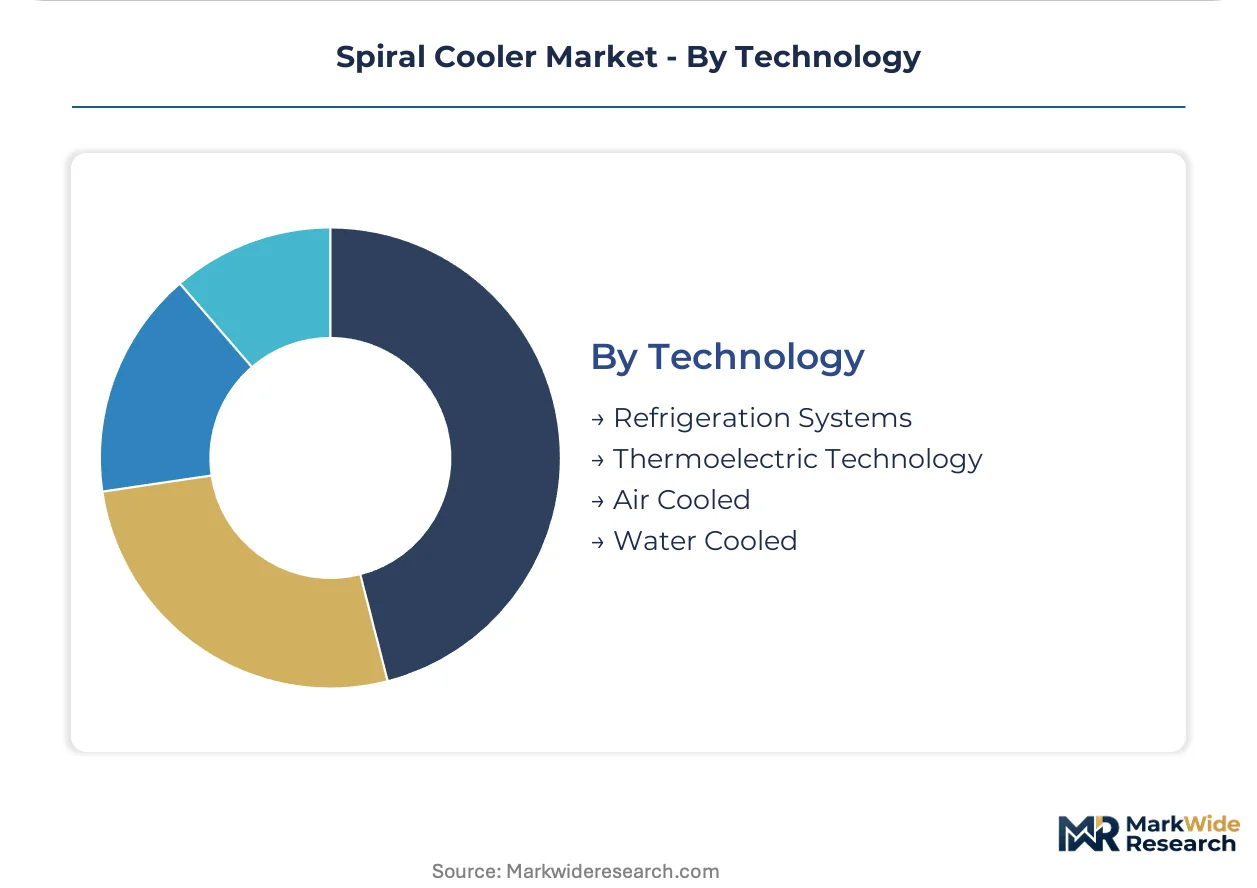
Capital intensity spreads widest across technology categories, with ammonia systems requiring specialized safety infrastructure while thermoelectric modules minimize installation costs at throughput penalties.
- Refrigeration Systems:Vapor-compression architectures using ammonia or CO2 refrigerants achieve throughput rates from 2,000 to 15,000 kg per hour. Mayekawa dominates Asian installations with ammonia-based systems for large-scale Japanese food factories, leveraging METI efficiency benchmarks.
- Thermoelectric Technology:Solid-state Peltier modules eliminate moving parts and refrigerant management but face thermal efficiency ceilings above 500 kg per hour. Japanese convenience store chains pilot these for small-footprint prepared meal displays in Tokyo metro corridors.
- Air Cooled:Fin-and-tube condensers suit water-scarce regions and simplified maintenance protocols.
- Water Cooled:Shell-and-tube configurations exploit available cooling tower infrastructure for efficiency gains in coastal installations.
Refrigeration systems anchor the volume base while thermoelectric technology gains share at the steepest rate in sub-500 kg throughput niches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabricators cluster in Germany and Japan, with Chinese manufacturers expanding capacity to serve domestic cold-chain buildouts. Demand concentrates in industrial bakery corridors and protein processing clusters where regulatory deadlines compress replacement cycles.
Germany
Industrial bakery automation and meat processing modernization drive replacement demand in North Rhine-Westphalia. The EU F-Gas Regulation mandates hydrofluorocarbon phasedowns, forcing refrigerant circuit redesigns. Equipment vendors in the Laval dairy cluster pilot unified CO2 transcritical architectures that eliminate separate ammonia systems.
United States
Protein processors in Texas and Nebraska unbundle after-sales service from equipment contracts, creating independent maintenance markets. The EPA's SNAP program approves low-GWP refrigerant pathways for California and Northeast state compliance. Beef processing corridors standardize on multi-vendor site configurations to reduce captive service lock-in.
China
Domestic cold-chain infrastructure investment draws new entrants into spiral cooler manufacturing around Shanghai and Guangzhou. SAMR certification requirements impose extended approval timelines for imported European systems. Protein processors in the Yangtze River Delta source from domestic manufacturers under GB energy-efficiency standards.
Japan
Large-scale food factories in the Kanto and Kansai regions deploy ammonia-based refrigeration systems for thermal efficiency. METI efficiency benchmarks shape vendor technical roadmaps and equipment specifications. Convenience store chains in Tokyo metro corridors pilot thermoelectric modules for small-footprint prepared meal displays.
France
Industrial bakery operators in Emilia-Romagna face accelerated HFC phaseout timelines under EU F-Gas Regulation. The 2024-2030 phasedown schedule forces equipment-level GWP compliance redesigns. French dairy processors commission custom-engineered systems with modular retrofit kits that preserve existing conveyor mechanics.
Spiral Cooler Market Competitive Landscape
Full-line refrigeration conglomerates and specialized hygienic equipment fabricators split the market between scale-driven standardization and engineering-intensive customization. The vendor base concentrates around three strategic archetypes: integrated HVAC-refrigeration multinationals with captive distribution, regional specialists in ammonia safety protocols, and emerging Asian fabricators competing on cost-adjusted delivery timelines. Consolidation pressure intensifies as refrigerant chemistry transitions force R&D scale thresholds, while partnership strategies dominate among mid-cap players seeking geographic coverage without capital-intensive greenfield investments.
Within the integrated multinational tier, Trane and Johnson Controls occupy positions spanning commercial refrigeration into industrial cooling applications. Japanese electrical conglomerates exemplify precision-control specialization, with Mitsubishi Electric anchoring premium conveyor-cooling segments through inverter technology integration. German hygienic design specialists like GEA sit within the engineering-intensive archetype, serving dairy and protein processing with customized configurations that command premium pricing over standardized units.
| Leading Market Players |
|---|
| Trane |
| Johnson Controls |
| Mitsubishi Electric |
| Haier |
| GEA |
| Mayekawa |
| Linde |
| Air Products and Chemicals |
| Messer Group |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese spiral cooler manufacturing compresses margin realization across standardized horizontal units, forcing German and Japanese fabricators toward custom-engineered configurations where refrigerant chemistry expertise sustains pricing power. EU F-Gas Regulation compliance costs feed directly into equipment quotations, bifurcating vendor strategies between low-cost volume plays and premium retrofit kit positioning.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across the spiral cooler market, separating ammonia-based custom systems from HFC retrofit configurations. Price differentiation rests on certification grade for hygienic design compliance and after-sales service bundling, with unbundled maintenance contracts gaining traction in North American protein processing. Cost compression in standardized horizontal units intensifies as domestic Chinese manufacturers undercut European imports on delivery timelines. Food service operators exhibit highest price sensitivity due to capital constraints, while integrated food manufacturers prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Export control regimes on precision inverter drives and specialized compressor technologies limit component flows from Japan and Germany to emerging Asian fabricators. Manufacturing concentrates in Germany, Japan, and China, with stainless steel belt assemblies and ammonia-compatible heat exchangers drawing from specialized metalworking corridors. Single-source vulnerability persists for CO2 transcritical compressor packages, where European and Japanese suppliers dominate qualified vendor lists. Distribution runs through OEM-direct channels for large food manufacturers and regional equipment distributors serving food service accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spiral cooler market sits at an inflection where refrigerant chemistry transitions compress equipment lifecycles and open recurring service revenue streams. The EU F-Gas Regulation's phasedown mandates create structural demand pull for next-generation low-GWP architectures.
For Market Incumbents: Pre-empt margin erosion in standardized horizontal units by accelerating backward integration into ammonia safety engineering capabilities and captive refrigerant management services. Consolidate regional service networks in Texas and Nebraska beef processing corridors before third-party contractors lock in multi-vendor maintenance contracts. Prioritize R&D scale thresholds for CO2 transcritical system integration to outpace mid-cap competitors on compliance-ready product roadmaps. For New Entrants and Emerging Players: Pursue white-space positioning in India's underpenetrated automated poultry and seafood cooling infrastructure, where ammonia system expertise remains scarce and first-mover advantage is attainable. Target supermarket in-store bakery segments in the Northeast United States with compact, EPA SNAP-approved low-GWP configurations that bypass incumbent service lock-in. Anchor go-to-market strategy through distributor specification support rather than direct sales investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with integrated IoT-enabled predictive maintenance architectures and captive refrigerant management contracts. Long-term viability favors engineering-intensive specialists with demonstrated EU F-Gas Regulation compliance track records and established relationships with French dairy and German industrial bakery clusters. Watch for inflection signals in SAMR certification timeline compression for European imports, which would reshape competitive dynamics in China's Yangtze River Delta protein processing corridor.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Circuit Retrofit Program | Modular kits preserve existing conveyor mechanics while achieving EU F-Gas Regulation GWP compliance deadlines. |
| Ammonia Safety Engineering Acquisition | Scarce expertise in system design and protocols constrains vendor scaling, creating consolidation opportunity. |
| IoT Predictive Maintenance Platform Launch | Precision inverter integration enables premium service revenue streams independent of equipment sales cycles. |
| CO2 Transcritical Architecture Partnership | Unified cooling-freezing lines collapse separate system requirements and pressure ammonia-specialist margins. |
| Domestic China Manufacturing Scale-Up | GB energy-efficiency standard compliance bypasses SAMR certification delays for imported European systems. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and equipment vendor technical documentation. Primary interviews engaged plant engineers at industrial bakeries and protein processors, aftermarket service heads at refrigeration contractors, and procurement leads at food manufacturing conglomerates. Secondary validation drew from EPA SNAP approval databases, EU F-Gas Regulation implementation guidance, SAMR certification registries, and METI efficiency benchmark disclosures. Bottom-up unit demand estimates triangulate against top-down market sizing across product type, application, and technology segmentation.
Forecast inputs incorporate refrigerant phasedown timelines, cold-chain infrastructure investment flows, and replacement cycle compression from regulatory compliance deadlines. Segmentation modeling spans product configuration, end-use industry, cooling technology architecture, and regional regulatory cluster. CAGRs derive from installed base turnover velocity analysis and new capacity absorption rates. Industry-specific inputs include ammonia safety protocol adoption curves and CO2 transcritical system pilot expansion patterns.
Macroeconomic conditions sit as an overlay; deviation in capital expenditure cycles at food manufacturers or construction cost inflation for greenfield facilities would shift the trajectory. Forecasts reflect assumptions on regulatory timeline adherence and refrigerant chemistry transition costs. Material shifts in EU F-Gas Regulation enforcement intensity or SAMR certification reciprocity agreements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
China Industrial Food and Beverages Filtration System Market
Food Processing Equipment
Shawarma Grill Machine Market
Food Processing Equipment
Fish Deboning Machine Market
Food Processing Equipment
Glass Processing Equipment Market
Food Processing Equipment
Destemmer Market
Food Processing Equipment
Food Disinfection Equipment Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Tomato Processing Machine Market
Food Processing Equipment
Gas Convection Oven Market
Food Processing Equipment
Ultrasonic Homogenizer Machines Market
Food Processing Equipment
Brewing Thermometer Market
Food Processing Equipment
Global Non-Thermal Pasteurization Market
Food Processing Equipment
Hot Food Processing Equipment Market
Food Processing Equipment
Optical Sorter Market
Food Processing Equipment
Global Food and Beverage Processing Equipment Market
Food Processing Equipment
Nugget Ice Machines Market