
 Electric Brewing System Market | 2026-2036
Electric Brewing System Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Brewing System Market Foresight
The electric brewing system market is decoupling along equipment sophistication and price architecture. Premium automated platforms with integrated fermentation management now command fundamentally different buyer economics than entry-level homebrewing kits. GEA Group leverages its process engineering heritage to dominate large-scale commercial installations across Europe. Alfa Laval anchors its position through heat exchanger specialization that extends into brewery thermal management. Grainfather competes aggressively in the hobbyist tier through compact footprint designs that occupy limited urban brewing spaces.
An electric brewing system comprises electrically heated vessels, pumps, and control interfaces that automate mashing, boiling, and wort transfer without direct fossil fuel combustion; typical commercial units operate at 208–480V with 10–50 kW heating elements and achieve temperature precision within 0.5°C via PID feedback loops. Automated brewing machines with Bluetooth connectivity represent the fastest-expanding technology segment as remote monitoring reduces labor overhead for small commercial operations. Commercial brew systems above 10-gallon capacity carry the densest margin pools because buyers prioritize throughput reliability and regulatory compliance documentation over upfront capital expenditure. Homebrewing kits face commoditization pressure as Asian contract manufacturers replicate basic electric kettle functionality at lower price points.
FDA food-contact material standards and NSF/ANSI commercial equipment certifications shape product design requirements for any system sold into foodservice or production brewery environments in the United States. The EU Machinery Directive and CE marking obligations impose additional safety interlock and documentation burdens on manufacturers targeting European commercial buyers. Stakeholders must monitor how evolving carbon border adjustment mechanisms and building electrification codes reshape total cost-of-ownership calculations for gas-to-electric brewery conversions.
Market Dynamics
Electrification mandates in commercial buildings are accelerating gas-to-electric brewery conversions, while induction heating technology is displacing traditional steam-jacketed vessels across production scales.
Growth Catalysts
- EU F-Gas Regulation:Breweries in Germany and Belgium are retrofitting electric systems to eliminate refrigerant-dependent cooling, creating immediate replacement demand for compliant thermal management equipment.
- Building electrification codes:Municipal mandates in California, New York, and Massachusetts prohibit new gas hookups in commercial food production facilities, forcing craft breweries toward all-electric brewhouse designs.
- Induction heating:This technology delivers 90%+ thermal efficiency versus 50-60% for gas-fired steam systems, slashing energy costs for high-volume production facilities.
Market Restraints
- Copper and stainless steel input volatility:Vessel fabrication depends on nickel-alloyed steel grades whose prices swing with mining output from Indonesia and the Philippines.
- Electrical infrastructure retrofit costs:Older brewery buildings require 480V three-phase service upgrades that add 30-40% to total project capex before equipment purchase.
- Natural gas price arbitrage:Regions with subsidized methane supply—particularly parts of Texas and Alberta—extend payback periods for electric conversion beyond typical investment horizons.
Strategic Opportunities
- Carbon border adjustment mechanisms:The EU's phased CBAM implementation will penalize imported beer from carbon-intensive production, incentivizing European brewers to electrify for export competitiveness.
- Bluetooth-enabled fermentation management:Remote monitoring platforms are converging with electric brewhouse controls to create integrated production ecosystems for distributed craft operations.
- Urban microbrewery proliferation:Compact electric systems enable brewing in mixed-use buildings where gas venting and fire codes previously prohibited production.
Industry Challenges
- Electrical trades shortage:Brewery commissioning requires certified electricians familiar with PID control systems and high-amperage heating element installation, a skill set concentrated in industrial automation hubs.
- NSF/ANSI certification timelines:Commercial foodservice validation for new electric kettle designs extends 8-14 months, delaying product launches and freezing R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Brewing System Market |
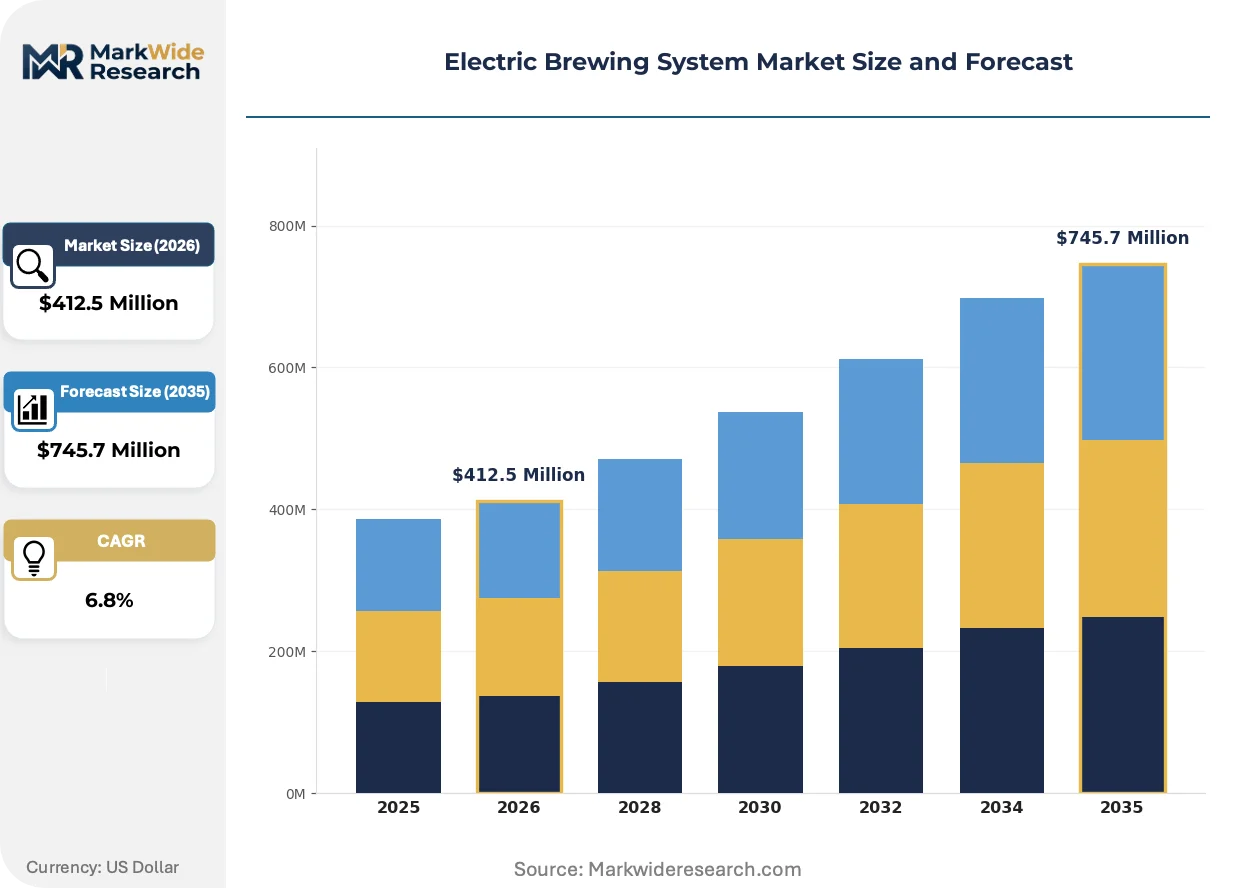
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homebrewing Kits, Commercial Brew Systems, Portable Brewers, Automated Brewing Machines Technology: Electric Heat Exchangers, PID Controllers, Induction Heating, Bluetooth Connectivity End User: Brewery Owners, Hobbyists, Restaurants, Events Organizers Capacity: 1 Gallon, 5 Gallon, 10 Gallon, 20 Gallon |
| Companies Covered | GEA Group, Alfa Laval, Krones, Grainfather, Blichmann Engineering, Speidel Tank & Equipment, PicoBrew, SS Brewing Technologies, BrewMaster Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Brewing System Market Shifts & Advancements
Digitalization of brewhouse operations is compressing the traditional separation between production equipment and data infrastructure, creating new competitive axes beyond thermal efficiency alone.
Induction heating modules are converging with solid-state power electronics to enable precise wattage modulation across mashing stages. Mid-sized craft breweries in the Pacific Northwest are adopting these systems fastest, replacing gas-fired vessels within 18-month replacement cycles. This convergence is compressing the price-performance gap between entry-level electric kettles and premium automated platforms.
The EU Machinery Directive's 2023 amendments impose stricter safety interlock requirements on automated brewing equipment with remote access capabilities. Manufacturers must now document failure-mode analyses for cloud-connected control systems before CE marking. European commercial buyers are demanding pre-certified platforms, favoring established process engineering suppliers over emerging hardware entrants.
Subscription-based equipment access is disrupting traditional capital purchase models for startup breweries. Leasing providers bundle electric brewhouse hardware with preventive maintenance and software updates, capturing recurring revenue from cash-constrained entrants. This model concentrates in urban clusters where real estate costs already strain brewery balance sheets.
Electric Brewing System Market Segmentation
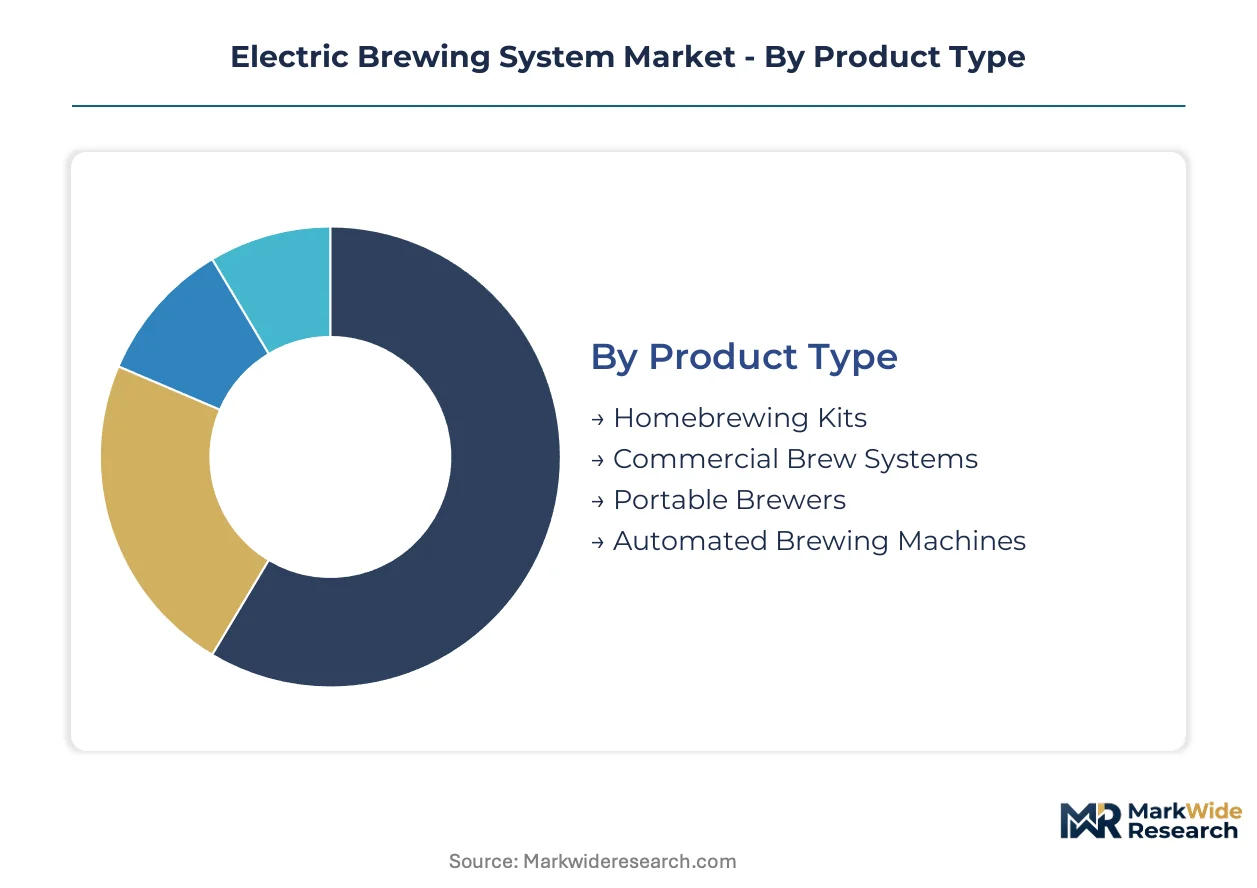
Electric brewing systems fragment across four distinct axes that reshape procurement economics. Product architecture, thermal technology, buyer sophistication, and batch scale each create separate margin pools and certification requirements.
Product Type:
Equipment sophistication determines whether buyers prioritize capital efficiency or throughput reliability.
- Commercial Brew Systems:These platforms integrate multiple vessels with automated wort transfer and CIP capability. German craft breweries retrofitting traditional brewhouses drive replacement demand as F-Gas Regulation deadlines approach.
- Automated Brewing Machines:Bluetooth-enabled units with cloud-connected fermentation monitoring compress labor overhead for distributed operations. California municipal electrification codes are forcing gas-to-electric conversions fastest in this tier.
- Homebrewing Kits:Compact electric kettles with basic temperature control serve urban hobbyists in space-constrained apartments. Asian contract manufacturers are replicating core functionality at compressed price points.
- Portable Brewers:Battery-compatible units with DC heating elements enable off-grid and event-based production. Demand concentrates with mobile catering operations and festival vendors.
Mature deployment sits with Commercial Brew Systems. Newer deployment is concentrated in Automated Brewing Machines.
Technology:
Thermal management approaches separate efficiency leaders from compliance-driven retrofits.
- Induction Heating:Solid-state power electronics deliver 90%+ thermal efficiency with precise wattage modulation across mashing stages. Pacific Northwest craft breweries are replacing gas-fired vessels within 18-month cycles.
- Bluetooth Connectivity:Remote monitoring platforms converge with brewhouse controls to create integrated production ecosystems. The EU Machinery Directive's 2023 amendments now impose stricter safety interlock documentation for cloud-connected systems.
- PID Controllers:Feedback loops maintain temperature precision within 0.5°C through continuous sensor adjustment. These controllers anchor both entry-level and premium system architectures.
- Electric Heat Exchangers:Stainless steel plate designs enable rapid wort chilling without refrigerant-dependent cooling systems. Belgium and Germany retrofitting activity concentrates demand here.
Established installations rely on PID Controllers and Electric Heat Exchangers. Steepest expansion trajectory belongs to Induction Heating and Bluetooth Connectivity.
End User:
Buyer category dictates whether procurement emphasizes regulatory documentation or user experience simplicity.
- Brewery Owners:Commercial operators require NSF/ANSI certification and 480V three-phase infrastructure. Massachusetts and New York building electrification mandates are accelerating their equipment replacement timelines.
- Hobbyists:Urban homebrewers prioritize compact footprint and 120V residential compatibility. Grainfather and similar brands compete aggressively for this price-sensitive segment.
- Restaurants:Foodservice operators need FDA food-contact material compliance and ventless operation for mixed-use buildings. Their procurement cycles align with kitchen renovation schedules.
- Events Organizers:Mobile operators demand rapid setup and breakdown with minimal utility dependencies. Festival circuits and wedding catering drive seasonal demand spikes.
Volume concentration rests with Brewery Owners. Fastest customer base expansion is occurring among Hobbyists and Events Organizers.
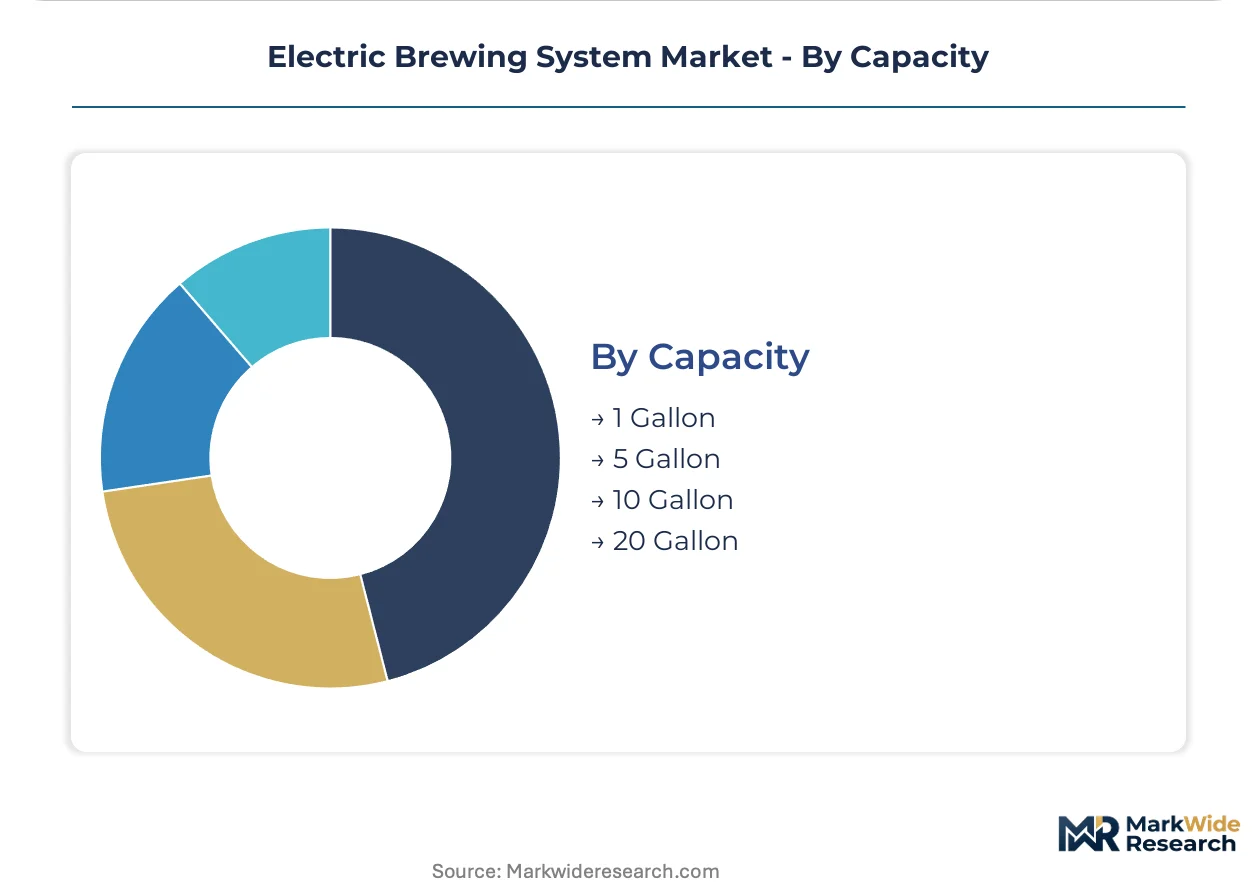
Capacity:
Batch scale directly correlates with electrical infrastructure requirements and margin structure.
- 10 Gallon:Systems at this threshold require 240V service and anchor the transition from hobbyist to nanobrewery production. Urban microbreweries in mixed-use buildings favor this footprint for regulatory compliance.
- 20 Gallon:Commercial units demand 480V three-phase power and professional electrical trades for commissioning. These systems carry the densest margin pools as buyers prioritize reliability documentation.
- 5 Gallon:Standard homebrewing scale compatible with residential 120V circuits and standard kitchen outlets. This capacity dominates e-commerce channel volume.
- 1 Gallon:Experimental and test-batch scale for recipe development and ingredient trials. Specialty retailers and direct-to-consumer channels serve this niche.
Revenue concentration aligns with 20 Gallon systems. Fastest volume growth is emerging at 10 Gallon and 5 Gallon tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portland anchors North American electric brewing system deployment through its dense craft brewery corridor and aggressive municipal decarbonization timelines.
United States
California building electrification codes and Massachusetts gas hookup prohibitions force immediate equipment replacement cycles. The FDA and NSF/ANSI certification requirements shape procurement documentation for foodservice entrants. Pacific Northwest craft clusters in Oregon and Washington replace gas-fired vessels within compressed 18-month timelines.
Germany
Traditional brewhouse retrofitting concentrates demand as F-Gas Regulation deadlines eliminate refrigerant-dependent cooling. The EU Machinery Directive and CE marking impose safety interlock documentation burdens on cloud-connected systems. Bavarian craft breweries anchor replacement activity, with Baden-Württemberg following for thermal efficiency upgrades.
Belgium
Trappist and abbey brewery heritage sites prioritize carbon intensity reductions for export competitiveness under phased CBAM implementation. The EU F-Gas Regulation drives heat exchanger retrofits without refrigerant dependencies. Flemish industrial zones concentrate equipment installation for mid-scale production facilities.
United Kingdom
Urban microbrewery proliferation in London and Manchester exploits compact electric systems for mixed-use building compliance. Building electrification codes across England and Wales accelerate gas-to-electric conversions. Scottish craft clusters in Edinburgh and Glasgow favor automated platforms with fermentation management integration.
Australia
Victoria and New South Wales craft breweries adopt induction heating modules for thermal efficiency gains against rising energy costs. State-level building electrification incentives complement federal decarbonization targets. Melbourne's dense urban brewery district leads installation density for space-constrained production.
Electric Brewing System Market Competitive Landscape
Capital-heavy process engineering conglomerates compete with asset-light brewing equipment specialists for margin pool capture. The vendor base stratifies across three tiers: integrated thermal management platforms, standalone vessel fabricators, and connected control system providers. Consolidation pressure concentrates among mid-scale automated platform providers. Dominant competitive moves include strategic partnerships for certification acceleration and geographic licensing agreements for regulatory compliance.
Within the integrated platform tier, GEA Group and Alfa Laval occupy positions anchored by process engineering heritage and heat exchanger specialization respectively. Krones represents the packaging-to-brewing integration archetype. Among standalone equipment specialists, Grainfather exemplifies the compact footprint strategy targeting urban space constraints. PicoBrew and Blichmann Engineering sit within the connected control tier, where Bluetooth-enabled fermentation management converges with brewhouse automation.
| Leading Market Players |
|---|
| GEA Group |
| Alfa Laval |
| Krones |
| Grainfather |
| Blichmann Engineering |
| Speidel Tank & Equipment |
| PicoBrew |
| SS Brewing Technologies |
| BrewMaster Systems |
| Others |
Supply & Pricing Matrix
Induction heating displacement of gas-fired steam systems simultaneously compresses manufacturing cost curves and concentrates component sourcing around solid-state power electronics foundries. This technology transition rewards vendors with captive semiconductor relationships while exposing others to spot-market volatility in IGBT modules and ferrite core materials.
Pricing Analysis
Throughput guarantees anchor value-based pricing for commercial brewhouse platforms, with buyers paying premiums for documented uptime performance and regulatory compliance bundling. Price differentiation separates NSF/ANSI-certified commercial tiers from uncertified hobbyist equipment, while California and Massachusetts electrification deadlines are intensifying cost compression in mid-scale automated systems. Hobbyists exhibit highest price sensitivity, demanding sub-$500 entry points for 5-gallon residential units. Commercial brewery owners prioritize total cost-of-ownership calculations over upfront capital, accepting 40-60% price premiums for integrated fermentation management and preventive maintenance inclusion.
Supply Chain Analysis
Single-source vulnerability sits with Indonesian and Philippine nickel-alloyed stainless steel suppliers, where mining output fluctuations transmit directly into vessel fabrication costs. Component sourcing draws from Germany for precision control systems, China for consumer-grade heating elements, and Taiwan for solid-state power electronics. Tariff exposure on steel imports from Southeast Asia represents the dominant structural risk. Distribution runs through regional equipment distributors for commercial tiers, direct-to-consumer e-commerce for homebrewing kits, and leasing providers for subscription-based brewery access models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric brewing system market sits in a technology-transition phase as induction heating modules displace legacy gas-fired steam infrastructure across production scales. This displacement creates asymmetric opportunity windows for positioned incumbents and agile entrants.
For Market Incumbents: Lock in certification moats by accelerating NSF/ANSI and CE marking timelines ahead of EU Machinery Directive enforcement waves. Prioritize backward integration into solid-state power electronics to secure IGBT module supply against foundry allocation constraints. Defend margin position by bundling predictive maintenance software with hardware platforms, creating switching costs for commercial brewery operators.
For New Entrants and Emerging Players: Enter via the 10-gallon nanobrewery tier where urban mixed-use building codes are prohibiting gas hookups fastest. Target Pacific Northwest craft clusters replacing gas-fired vessels within compressed 18-month cycles. Pursue white-label partnerships with established distributors lacking Bluetooth-enabled fermentation management capabilities.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays as mid-scale automated providers face R&D budget freezes from extended certification timelines. Long-term viability favors vendors with integrated thermal management and cloud-connected control architectures. Watch induction heating adoption rates among German retrofitting activity as the primary inflection signal for technology-transition completion.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Acceleration Investment | NSF/ANSI and CE pre-certification compresses 8-14 month validation timelines for European and North American commercial buyers. |
| Backward Integration into Power Electronics | Captive IGBT module sourcing insulates margin structures from Taiwan foundry allocation volatility. |
| Subscription Equipment Access Launch | Leasing bundling with preventive maintenance captures recurring revenue from cash-constrained urban microbrewery entrants. |
| Bluetooth Fermentation Management Integration | Remote monitoring convergence creates integrated production ecosystems for distributed craft operations. |
| Urban Microbrewery Geographic Expansion | Compact footprint designs exploit mixed-use building electrification codes prohibiting gas venting in California and Massachusetts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with brewery operations directors, equipment procurement managers, electrical contractors specializing in PID control installation, and regulatory compliance officers at FDA and EU notified bodies combined with secondary validation from Brewers Association membership databases, EU F-Gas Regulation implementation reports, and stainless steel import customs records. Bottom-up vessel shipment analysis and top-down energy consumption modeling triangulated market sizing across the projection horizon.
Granularity-level modeling disaggregated revenue and volume across product architecture tiers, thermal technology types, buyer sophistication categories, and batch capacity thresholds throughout the forecast period. CAGRs derived from segmented growth rate analysis incorporating electrification mandate implementation timelines, F-Gas Regulation deadline clustering, and craft brewery formation rates. Forecast inputs included municipal building code adoption curves for gas hookup prohibitions and nickel-alloyed steel price volatility indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU CBAM implementation or prolonged electrical trades shortages in North American industrial automation hubs. Forecasts reflect documented assumptions on regulatory enforcement intensity and commodity input stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Pizza Preparation Refrigerator Market
Food Processing Equipment
Ice Cream Machine Market
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
Deep Fryer Machine Market
Food Processing Equipment
Holding and Proofing Cabinet Market
Food Processing Equipment
North America Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Used Commercial Freezer Market
Food Processing Equipment
Automatic Liquid Dispenser Machine Market
Food Processing Equipment
Philippines Cold Storage Warehouse Market
Food Processing Equipment
Ribbon Blenders Market
Food Processing Equipment
Coconut Crushers Market
Food Processing Equipment
Global Snack Pellet Equipment Market
Food Processing Equipment
Brewery Heat Exchanger Market
Food Processing Equipment
Vacuum Cooling Equipment Market
Food Processing Equipment
Middle East and Africa Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Yogurt Makers Market