
 India Plant Protein Market | 2026-2036
India Plant Protein Market Size, Share, and Industry Trends Forecast 2026-2036
India Plant Protein Market Foresight
Modern trade and e-commerce channels is narrowing the access gap between plant protein ingredient suppliers and mid-tier food manufacturers across tier-two Indian cities. Ruchi Soya Industries leverages its integrated crushing and extrusion infrastructure to dominate bulk textured protein supply. Sonic Biochem Extractions sustains technical leadership in soy isolate purification for export-grade applications. ITC Limited anchors its position through backward integration into oilseed procurement networks in Madhya Pradesh and Rajasthan.
Plant protein comprises extracted, concentrated, or texturized protein fractions derived from leguminous and cereal sources, typically achieving protein content ranging from 50% in flours to 90% in isolate form through aqueous extraction and membrane filtration processes. These ingredients function primarily as functional nutrition inputs in meat analogues, sports nutrition powders, and fortified beverages. Soybean-derived isolates command the deepest margin pools due to established extraction economics and amino acid completeness, while pea protein concentrates represent the fastest-expanding source category as beverage formulators seek allergen-friendly alternatives to soy. Textured proteins lead volume consumption through their structural utility in ready-to-cook meat alternatives supplied to institutional foodservice.
FSSAI protein-labeling regulations and BIS quality benchmarks for soy products shape product formulation standards and import substitution incentives under the PLI scheme. CDSCO oversight of nutraceutical claims constrains how concentrate suppliers position products in the dietary supplement channel. State-level food safety commissioners in Gujarat and Maharashtra enforce additional testing protocols for aflatoxin and heavy metal limits in oilseed-derived ingredients. Stakeholders must monitor evolving FSSAI notification timelines for novel protein source approvals and align R&D investments with pending standards for fermented and precision-fermentation proteins.
Market Dynamics
Extrusion technology localization is compressing equipment import dependence and reconfiguring cost structures for textured protein manufacturers across western Indian states. Domestic machinery suppliers now capture mid-scale processing orders that previously flowed to European vendors.
Growth Catalysts
- FSSAI Protein-Labeling Standards:Tightening purity benchmarks for protein content claims are forcing formulation upgrades. This regulatory pressure accelerates isolate-grade ingredient adoption over commodity flour alternatives.
- Oilseed Processing Infrastructure:Maharashtra and Gujarat's established crushing capacity provides ready feedstock access. Proximity to soybean and groundnut supply clusters reduces logistics friction for protein extractors.
- Meat-Alternative Formulations:Institutional foodservice buyers are expanding textured soy procurement for ready-to-cook applications. Quick-service restaurant chains drive volume pull-through for structured protein ingredients.
Market Restraints
- Input Cost Volatility:Domestic soybean prices fluctuate with monsoon-dependent harvest cycles. Protein margin pools compress when oilseed availability tightens in deficit years.
- Technical Limitation:Pea protein extraction yields remain below soy economics due to starch-protein separation complexity. Concentrate purity gaps constrain beverage-grade applications.
- Regulatory Friction:CDSCO oversight of nutraceutical claims limits how concentrate suppliers position products in dietary supplement channels. Health claim restrictions narrow marketing vocabulary.
Strategic Opportunities
- Underpenetrated Geographies:Southern Indian states lack comparable oilseed processing density. Tamil Nadu and Karnataka present greenfield installation opportunities for integrated crush-extrusion facilities.
- Regulatory Tailwind:PLI scheme incentives for food processing machinery favor domestic equipment procurement. Capital subsidy structures reduce payback periods for extrusion line investments.
- Precision-Fermentation Convergence:Hybrid formulations combining plant isolates with microbial proteins address amino acid completeness gaps. Technology partnerships between extractors and fermentation startups create novel ingredient pipelines.
Industry Challenges
- Skill Gap in Extrusion Operations:Process engineers with screw-profile optimization expertise remain scarce. Training timelines extend commissioning schedules for new textured protein lines.
- Certification Timeline Compression:BIS quality benchmarks for soy products require laboratory validation cycles. Testing backlogs delay product launches for export-grade isolate certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Plant Protein Market |
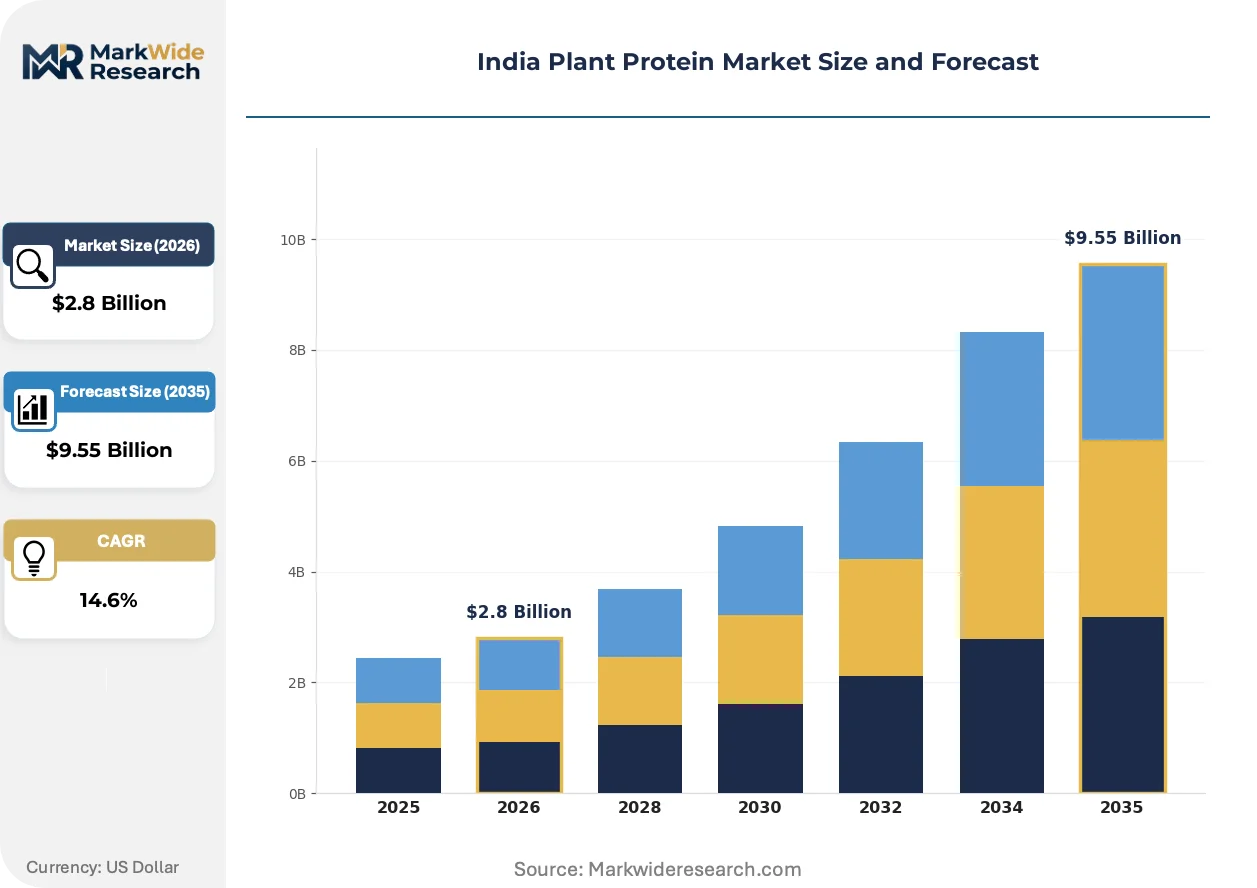
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured Protein, Isolates, Concentrates, Flours Source: Soybean, Pea, Rice, Lentil End User: Food Industry, Beverage Sector, Nutraceuticals, Animal Feed Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Ruchi Soya Industries Ltd, Sonic Biochem Extractions Pvt Ltd, Archer Daniels Midland Company, Cargill, ITC Limited, GoodDot Enterprises, PROWISE India, Marico Limited, Vezlay Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Plant Protein Market Shifts & Advancements
Digital process control systems are penetrating protein extraction facilities, enabling real-time parameter adjustment that was previously manual. This instrumentation shift is compressing batch-to-batch variability and tightening specification bands.
High-pressure processing technology is virtualizing traditional heat-based protein denaturation methods. Beverage formulators in Mumbai and Bangalore are adopting cold-extracted isolates to preserve functional solubility. This shift is virtualizing the thermal degradation trade-offs that previously constrained protein fortification in ambient-stable drinks.
FSSAI notification timelines for novel protein source approvals are tightening submission requirements for safety dossiers. Fermented and precision-fermentation proteins face extended evaluation periods pending toxicology data standards. Ingredient developers in Gujarat are front-loading clinical study investments to preempt regulatory bottlenecks.
Direct-procurement platforms are disintermediating traditional ingredient distributors for mid-tier food manufacturers. Tier-two city formulators in Pune and Ahmedabad now source isolates through B2B marketplaces with transparent pricing. This channel shift concentrates volume with suppliers maintaining digital inventory visibility and flexible minimum order quantities.
India Plant Protein Market Segmentation
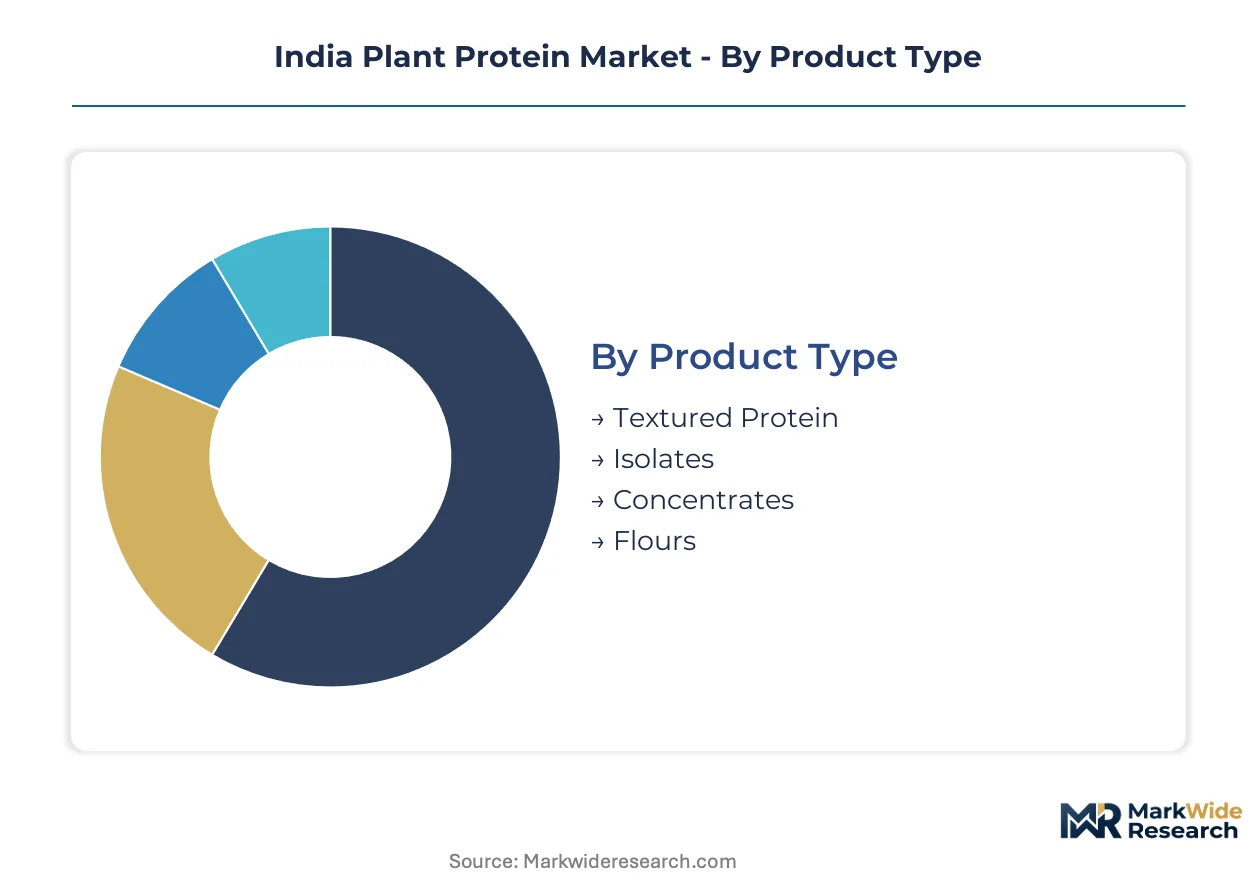
Segmentation in the India plant protein market reveals distinct procurement cycles and margin structures across product grades and channel configurations. Manufacturers in Maharashtra and Gujarat calibrate inventory strategies differently for commodity flours versus isolate-grade ingredients. Understanding these segment dynamics enables suppliers to align extrusion capacity with demand velocity patterns.
Product Type:
Cycle times vary sharply across protein grades, with textured proteins turning inventory fastest due to institutional foodservice pull, while isolates move slowly through nutraceutical certification pipelines.
- Textured Protein:Extruded soy or pea protein with fibrous structure mimicking meat tissue, typically 50-70% protein content. Quick-service restaurant chains in Mumbai and Ahmedabad drive rapid procurement cycles for ready-to-cook analogues, compressing supplier lead times to under two weeks.
- Isolates:Refined protein fractions achieving 90% purity through aqueous extraction and membrane filtration. Beverage formulators in Bangalore and Pune concentrate demand for cold-processed isolates with preserved solubility, though FSSAI purity documentation extends sales cycles.
- Concentrates:Intermediate protein grades at 60-80% content serving bakery and snack fortification.
- Flours:Ground oilseed meals at 50% protein for commodity feed and basic food applications.
Textured protein dominates installed base. Isolates are where expansion concentrates.
Source:
Cost tiers separate established oilseed crops from emerging alternatives, with soy commanding infrastructure scale advantages and pea protein carrying allergen-friendly positioning premiums.
- Soybean:Dominant source leveraging Maharashtra and Gujarat's crushing infrastructure, with established extraction economics and complete amino acid profiles. Madhya Pradesh procurement networks anchor supply security for major processors.
- Pea:Fastest-expanding source category as beverage formulators seek soy alternatives; starch-protein separation complexity keeps yields below soy benchmarks and prices elevated.
- Rice:Hypoallergenic protein for specialized infant nutrition and clinical formulations.
- Lentil:Emerging pulse protein with regional cultivation advantages in Rajasthan.
Soybean anchors volume scale. Pea protein is gaining share fastest.
End User:
Application maturity determines specification tolerance, with food industry buyers accepting wider protein content bands than nutraceutical clients demanding batch-level certification.
- Food Industry:Meat analogue manufacturers and bakery formulators across tier-two cities constitute the deepest demand pool, with textured soy procurement scaling for institutional clients.
- Beverage Sector:Sports nutrition and plant milk producers in metropolitan markets drive isolate-grade specifications, with cold-extraction requirements tightening supplier qualification.
- Nutraceuticals:CDSCO claim oversight constrains positioning; dietary supplement channels require extended safety dossiers.
- Animal Feed:Commodity protein meals for poultry and aquaculture operations in Andhra Pradesh.
Food industry commands installed base. Beverage sector is where expansion concentrates.
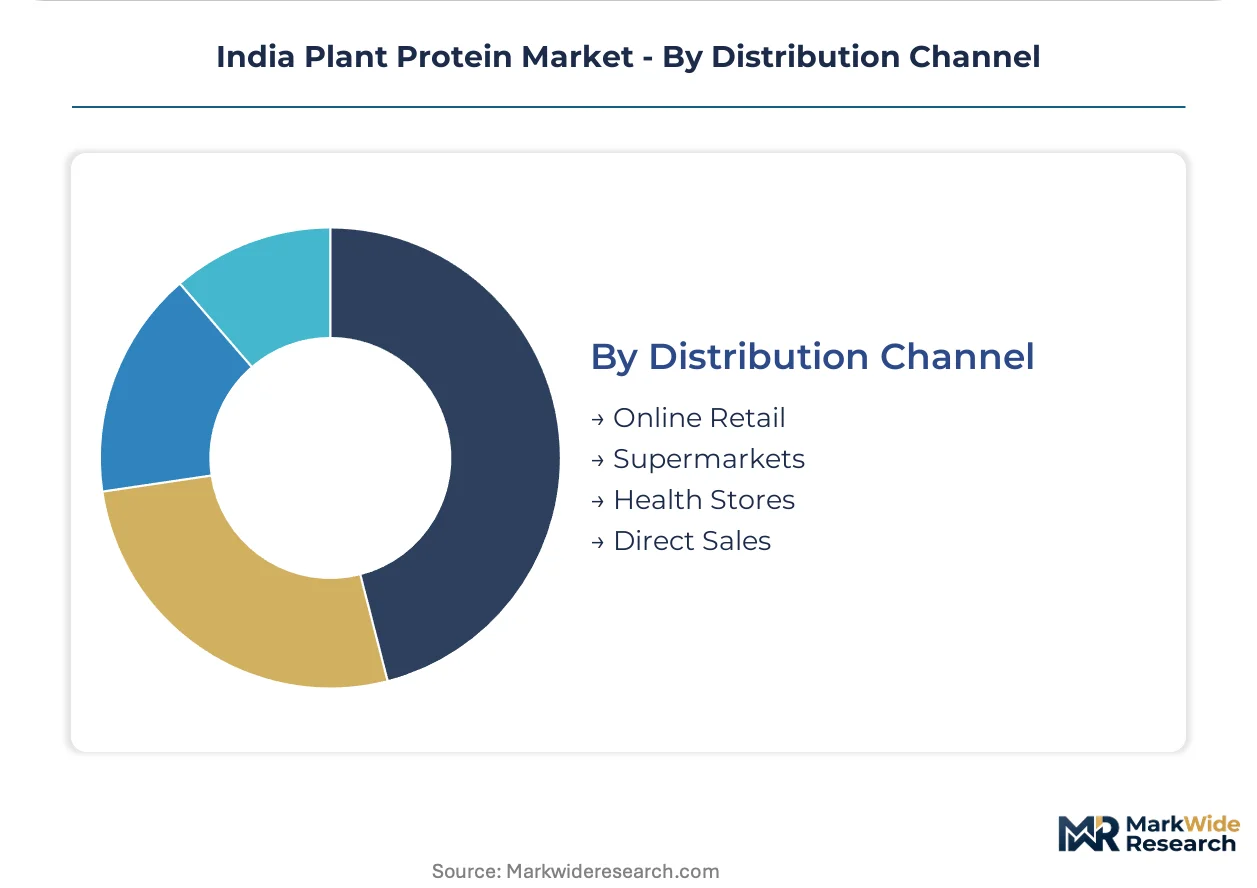
Distribution Channel:
Customer type stratification separates volume buyers seeking transparent pricing from formulators requiring technical support and flexible minimum orders.
- Direct Sales:Integrated processors in Gujarat maintain captive supply relationships with major food manufacturers, bypassing distributor margins and enabling specification co-development.
- Online Retail:B2B marketplaces disintermediate traditional distribution for mid-tier Pune and Ahmedabad formulators, concentrating volume with suppliers maintaining digital inventory visibility.
- Supermarkets:Branded ingredient retail for small-scale food entrepreneurs and artisan producers.
- Health Stores:Premium-positioned specialty proteins for consumer-direct sports nutrition brands.
Direct sales dominates installed base. Online retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI protein-labeling standards and PLI scheme incentives for food processing machinery anchor Maharashtra's dominance in India's plant protein landscape.
Maharashtra
Textured soy procurement from quick-service restaurant chains and institutional foodservice buyers drives demand velocity in Mumbai and Pune. FSSAI purity documentation requirements compress supplier lead times for export-grade isolates. The Mumbai-Ahmedabad industrial corridor concentrates extrusion capacity for meat-alternative formulations.
Gujarat
Soybean crushing infrastructure and groundnut processing clusters provide feedstock security for protein extractors in Ahmedabad and Vadodara. State-level food safety commissioners enforce additional aflatoxin testing protocols beyond central FSSAI mandates. Domestic machinery suppliers capture mid-scale extrusion orders previously flowing to European vendors.
Karnataka
Beverage formulators in Bangalore drive cold-extracted isolate specifications for sports nutrition and plant milk applications. CDSCO oversight of nutraceutical claims constrains dietary supplement channel positioning. The state's precision-fermentation startups are forming technology partnerships with established extractors.
Tamil Nadu
Underpenetrated oilseed processing density creates greenfield opportunities for integrated crush-extrusion facilities in Chennai and Coimbatore. PLI scheme capital subsidies reduce payback periods for new processing line investments. Regional procurement platforms are disintermediating traditional distributors for mid-tier formulators.
Madhya Pradesh
Backward integration into oilseed procurement networks anchors supply security for major processors. Monsoon-dependent harvest cycles create input cost volatility that compresses protein margin pools in deficit years. The state's soybean cultivation belts feed directly into western Indian extrusion facilities.
India Plant Protein Market Competitive Landscape
Integrated agribusiness conglomerates and specialized extraction specialists split the market along vertical integration versus technical purity vectors. The vendor base concentrates around three strategic archetypes: captive oilseed processors with crushing-to-extrusion infrastructure, isolate purification specialists serving export-grade applications, and diversified FMCG players leveraging backward integration into procurement networks. Competitive moves center on capacity expansion in underpenetrated southern states and technology licensing partnerships for precision-fermentation hybrid formulations.
Within the integrated processor tier, Ruchi Soya Industries represents the captive infrastructure archetype through its Maharashtra-based crushing and extrusion footprint. Sonic Biochem Extractions occupies the technical specialization position for soy isolate purification. ITC Limited anchors the diversified conglomerate vector through its procurement network control in Madhya Pradesh and Rajasthan.
| Leading Market Players |
|---|
| Ruchi Soya Industries Ltd |
| Sonic Biochem Extractions Pvt Ltd |
| Archer Daniels Midland Company |
| Cargill |
| ITC Limited |
| GoodDot Enterprises |
| PROWISE India |
| Marico Limited |
| Vezlay Foods |
| Others |
Supply & Pricing Matrix
The Mumbai-Ahmedabad industrial corridor's freight economics compress logistics costs for western Indian processors while amplifying price differentiation between isolate-grade and commodity flour tiers. Supply concentration in Maharashtra and Gujarat oilseed belts concentrates pricing power among integrated crushers, forcing tier-two formulators to absorb transport premiums or accept wider specification bands.
Pricing Analysis
Configured-to-order pricing for cold-extracted isolates commands spreads against standard textured protein grades due to FSSAI purity documentation requirements and beverage-sector solubility specifications. Three-tier pricing structure across premium, standard, and economy levels separates export-grade isolate certifications from domestic foodservice textured proteins and commodity feed meals. Pricing pressure stems from monsoon-dependent soybean harvest volatility that compresses margin pools in deficit years. Institutional foodservice buyers exhibit highest price sensitivity due to volume procurement scales, while nutraceutical formulators accept premiums for batch-level certification.
Supply Chain Analysis
Upstream feedstock security draws from Madhya Pradesh soybean cultivation belts, Gujarat groundnut clusters, and Rajasthan pulse-growing regions. Raw material dependencies center on oilseed availability, extrusion equipment procurement, and membrane filtration consumables for isolate purification. Single-source vulnerability concentrates in European-origin precision extrusion screws and digital process control systems. Distribution runs through direct sales relationships for integrated processors and B2B marketplaces disintermediating traditional distributors for mid-tier formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as precision-fermentation hybrid formulations and PLI scheme capital subsidies accelerate processing capacity buildout beyond current oilseed infrastructure saturation.
For Market Incumbents: Entrench crushing-to-extrusion infrastructure advantages through backward integration into Madhya Pradesh procurement networks and certification investments for FSSAI novel protein approvals. Defend against precision-fermentation startups by co-developing hybrid ingredient pipelines and locking institutional foodservice contracts with specification co-development clauses. For New Entrants and Emerging Players: Pursue greenfield crush-extrusion installations in Tamil Nadu and Karnataka where oilseed processing density remains underdeveloped relative to western states. Target beverage-sector isolate demand in Bangalore and Pune with cold-extraction capabilities and transparent digital inventory platforms that compress minimum order quantities for mid-tier formulators. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agribusiness conglomerates with underutilized oilseed processing assets and captive supply relationships with quick-service restaurant chains. Long-term viability hinges on regulatory positioning for fermented protein approvals and extrusion technology localization momentum. Watch FSSAI notification timelines for novel protein source safety dossier standards as inflection signals for R&D investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Precision-Fermentation Technology Partnership | Hybrid formulations with microbial proteins address amino acid completeness gaps in plant isolates. |
| Greenfield Crush-Extrusion Facility Installation | Tamil Nadu and Karnataka present first-mover advantages in underpenetrated southern geographies. |
| Cold-Extraction Process Certification | Beverage formulators in Bangalore demand isolates with preserved functional solubility for sports nutrition. |
| Direct-Procurement Platform Development | B2B marketplaces disintermediate distributors for tier-two city formulators seeking transparent pricing. |
| PLI Scheme Machinery Procurement | Domestic extrusion equipment subsidies reduce payback periods and compress import dependence. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with oilseed procurement managers, extrusion process engineers, beverage formulator R&D heads, and institutional foodservice category buyers. Secondary validation drew from FSSAI notification records, BIS quality benchmark documentation, PLI scheme disbursement filings, and customs data on processing equipment imports. Bottom-up volume modeling across protein grades and source categories was triangulated against top-down market sizing from crushing capacity utilization rates.
Calibration anchored volume and value outputs to historical crush-extrusion facility commissioning timelines and isolate purification yield benchmarks across the projection horizon. Segmentation dimensions modeled include product grade tier, oilseed source type, end-use application maturity, and regional processing infrastructure density. CAGRs were derived from elasticity-adjusted demand curves incorporating FSSAI regulatory adoption timelines and precision-fermentation technology cost trajectories. Forecast inputs included monsoon harvest variability coefficients and PLI scheme capital subsidy disbursement velocity.
Macroeconomic conditions sit as an overlay; deviation in monsoon precipitation patterns, oilseed import tariff structures, or PLI scheme extension decisions would shift the trajectory. Forecasts reflect documented assumptions on regulatory approval timelines and technology partnership formation rates. Quarterly review of FSSAI notification releases, extrusion equipment order backlogs, and precision-fermentation startup funding rounds is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
USA Plant-Based Creamers Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
United States Rice Protein Market
Plant Based Food
Vegan Dessert Market
Plant Based Food
China Rice Protein Market
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
Global Isolate Organic Soy Protein Market
Plant Based Food
Plant-Based Hot Dogs Market
Plant Based Food
Chickpea-Based Products Market
Plant Based Food
Targeting Pod Market
Plant Based Food
Plant-Based Bars Market
Plant Based Food
South America Rice Protein Market
Plant Based Food
Vegan Oatmeal Market
Plant Based Food
Europe Pea Protein Market
Plant Based Food
France Plant Protein Market
Plant Based Food
Asia-Pacific Plant-Based Seafood Market