
 Oceania Commercial Ice Machine Market | 2026-2036
Oceania Commercial Ice Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Oceania Commercial Ice Machine Market Analytics
Multi-source procurement among large hospitality chains is recalibrating how commercial ice machines enter the Oceania market. Hoshizaki Corporation leverages its established distribution network to anchor supply relationships with major Australian hotel operators. Electrolux Group competes through integrated kitchen equipment portfolios that bundle ice production with refrigeration systems. Manitowoc Ice (Welbilt Inc.) specializes in modular configurations that suit high-volume bar and restaurant installations across New Zealand.
A commercial ice machine produces frozen water in cube, flake, or nugget forms through vapor-compression refrigeration cycles, typically achieving production rates from 50 to 2,000-plus pounds per day using R290 or R448A refrigerants. The equipment serves food safety, beverage service, and cold-chain preservation requirements in licensed hospitality venues. Modular units dominate capital deployment in large-scale hotel kitchens where production flexibility outweighs footprint constraints. Under-counter systems capture fastest-growing interest among boutique cafes and bars seeking space-efficient installations. Floor-standing equipment retains stable replacement demand across established restaurant chains with predictable volume requirements.
Australia's E3 Program and MEPS standards govern minimum energy performance for commercial refrigeration, directly influencing product design specifications and import eligibility. New Zealand's equivalent E3 regulations and Building Code compliance requirements shape installation standards and operational efficiency benchmarks. Food Standards Australia New Zealand (FSANZ) codes dictate ice handling hygiene protocols that drive equipment material specifications and cleaning system features. Stakeholders must monitor refrigerant phase-down schedules and emerging state-level building efficiency mandates to align procurement timelines with compliance windows.
Market Dynamics
Australia's MEPS program and New Zealand's E3 regulations are compressing equipment replacement cycles across the hospitality sector, forcing operators to retire refrigerant-heavy legacy units ahead of schedule.
Growth Catalysts
- Tourism capacity rebuilding:Australian hotels in Sydney and Melbourne corridors are expanding kitchen footprints to capture inbound visitor volume, directly lifting modular ice machine procurement.
- FSANZ hygiene mandates:Food Standards Australia New Zealand codes on ice handling are compelling venues to upgrade to self-sanitizing equipment with antimicrobial contact surfaces.
- R290 refrigerant transition:Natural hydrocarbon systems are penetrating mid-scale venues as operators seek compliance-ready equipment ahead of phase-down deadlines.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger material costs are squeezing margin structures for domestic distributors reliant on Asian metal supply chains.
- Import concentration risk:Equipment assembly concentrates in Southeast Asian facilities, exposing lead times to regional logistics bottlenecks.
- Refrigerant retrofit limitations:Existing R404A and R134A systems face technical barriers to refrigerant conversion, accelerating full-unit replacement costs.
Strategic Opportunities
- New Zealand regional hospitality:Queenstown and Rotorua tourism infrastructure remains under-equipped relative to visitor growth trajectories.
- IoT-enabled predictive maintenance:Sensor-integrated units are opening subscription revenue streams for distributors serving multi-site hotel chains.
- Energy efficiency incentive stacking:Australian state-level building upgrade programs are layering rebates atop federal MEPS compliance windows.
Industry Challenges
- Refrigeration technician scarcity:Licensed hydrocarbon system installers are concentrated in metropolitan markets, constraining regional deployment timelines.
- Certification lag for new refrigerants:TGA and state-level electrical safety approvals are creating six-to-nine month product launch delays for imported equipment lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oceania Commercial Ice Machine Market |
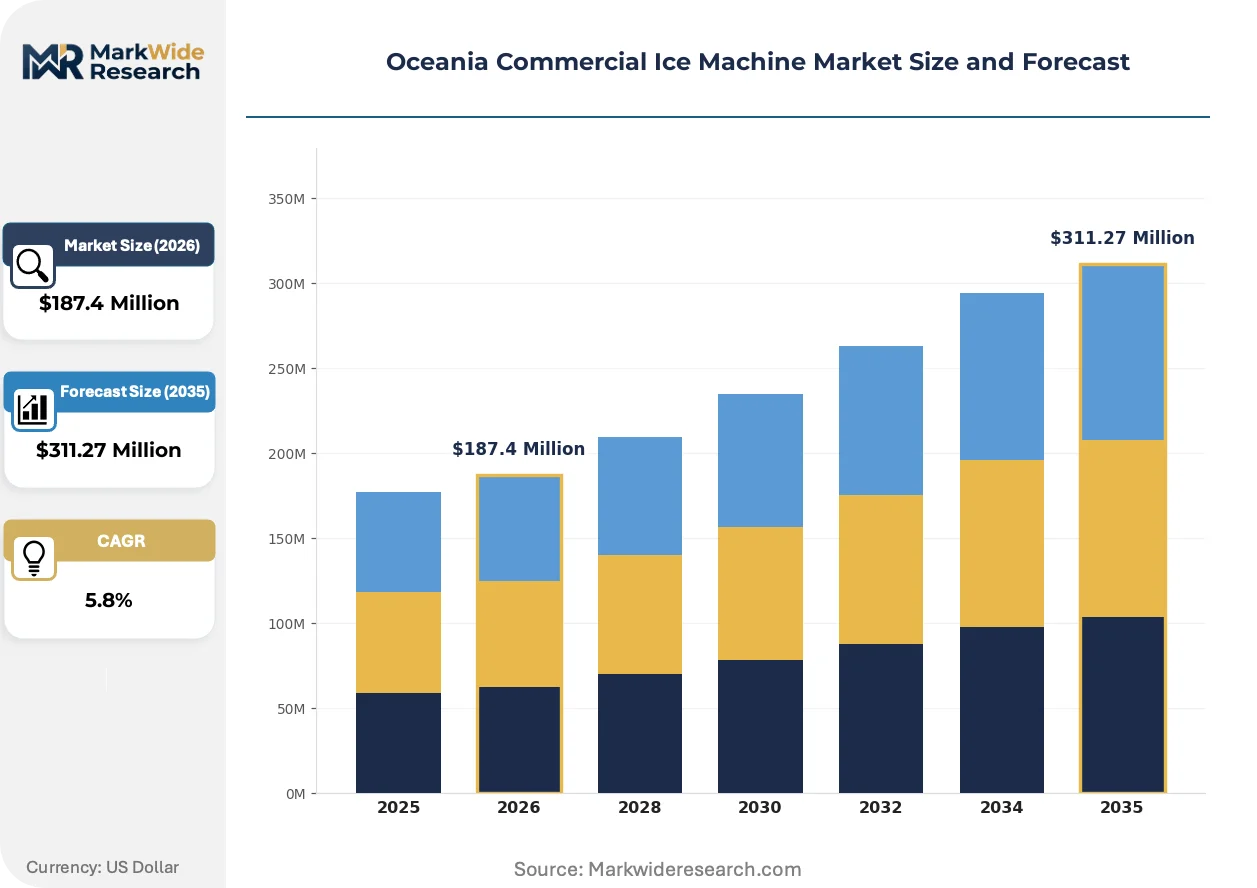
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular, Under-Counter, Floor-Standing, countertop Capacity: Small, Medium, Large, Extra-Large End User: Restaurants, Bars, Cafes, Hotels Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Ice-O-Matic, Electrolux Group, Hoshizaki Corporation, Ali Group, Focusun Refrigeration, Manitowoc Ice (Welbilt Inc.), Follett LLC, BREMA GROUP, Scotsman Ice Systems, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oceania Commercial Ice Machine Market Evolving Landscape
Equipment intelligence and refrigerant chemistry are converging to redefine operational economics for venue operators across Australia and New Zealand.
R290 natural hydrocarbon systems are absorbing the regulatory burden from phased synthetic refrigerants. These units achieve lower global warming potential ratings while maintaining production capacity. Sydney-based hotel chains are specifying R290-native equipment in new-build procurement to preempt compliance retrofit costs. The technology is absorbing capital that would otherwise flow to R448A transitional platforms, compressing the mid-tier equipment lifecycle.
Australia's E3 Program and MEPS standards are tightening minimum energy performance thresholds for commercial refrigeration equipment. These mandates are eliminating import eligibility for legacy product lines that fail to meet annual energy consumption benchmarks. New South Wales and Victorian hospitality operators are accelerating replacement schedules to capture state-level efficiency rebates before program windows close.
After-sales service unbundling is fragmenting traditional distributor relationships across Oceania. Large hotel chains are separating equipment procurement from maintenance contracts, engaging third-party refrigeration specialists for multi-brand fleet management. This pattern is most visible in Melbourne's corporate hospitality sector, where centralized procurement teams are negotiating direct manufacturer pricing while outsourcing technical support to regional service aggregators.
Oceania Commercial Ice Machine Market Segmentation
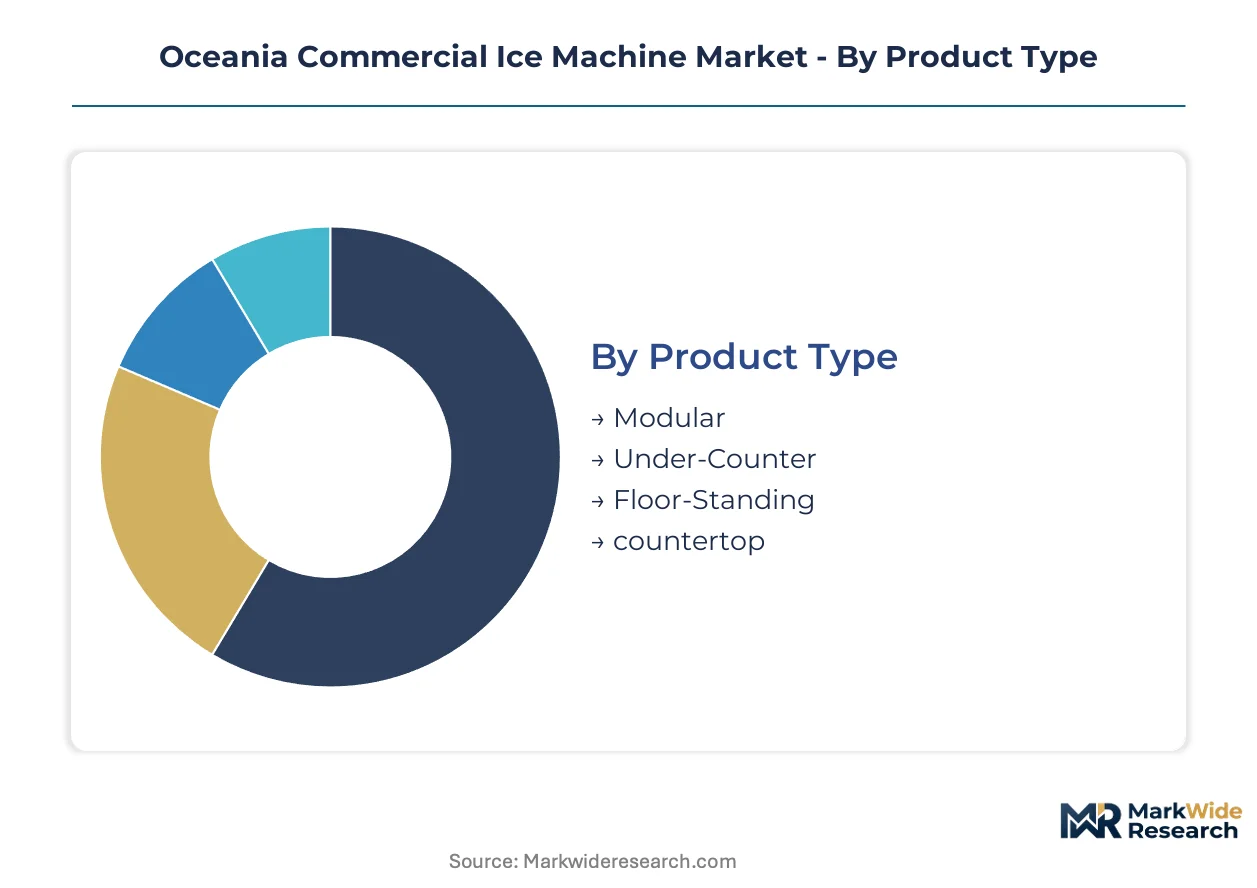
Equipment specification varies sharply across venue scale and operational intensity in Oceania's hospitality sector. Procurement patterns reflect divergent pressures from energy compliance timelines, space constraints, and volume throughput requirements that reshape how distributors configure their product portfolios.
Product Type:
Replacement cycles accelerate where Australia's MEPS program and New Zealand's E3 regulations disqualify legacy refrigerant platforms from import eligibility.
- Modular:Stackable ice production heads mount atop separate storage bins, enabling Sydney and Melbourne hotel kitchens to scale output from 500 to 2,000-plus pounds daily without footprint expansion. Procurement concentrates in new-build hospitality developments where production flexibility outweighs initial capital outlay.
- Under-Counter:Self-contained units fit beneath standard bar heights, serving space-constrained boutique venues in Auckland's hospitality corridors. Demand climbs fastest among cafes and small bars seeking compliance-ready R290 systems that avoid separate condenser installations.
- Floor-Standing:Integrated production and storage systems suit established restaurant chains with predictable volume requirements and dedicated equipment rooms.
- Countertop:Compact dispensers target low-volume beverage stations and staff kitchenettes where ice access convenience matters more than production speed.
Volume placements concentrate in Modular configurations across Australia's metropolitan hotel sector; the faster expansion belongs to Under-Counter systems penetrating New Zealand's regional cafe networks.
Capacity:
Energy efficiency mandates compress the viable operating range for each tier, forcing operators to right-size equipment against actual demand rather than peak buffering.
- Large:Systems producing 800-1,500 pounds daily dominate procurement for casino resorts and convention hotels in Queensland's Gold Coast corridor. TGA certification delays for high-capacity R290 platforms are stretching replacement timelines for venues with legacy R404A installations.
- Medium:300-800 pound daily output captures mainstream restaurant and bar deployments across Victoria and New South Wales. State-level building upgrade rebates are accelerating retirement of pre-MEPS equipment in this tier.
- Small:Sub-300 pound units serve satellite kitchenettes and limited-service cafes where ice is ancillary to core operations.
- Extra-Large:Industrial-scale systems exceed 1,500 pounds daily, reserved for centralized production facilities serving multi-venue hospitality groups.
Placement density peaks in Medium-capacity equipment; Extra-Large systems are climbing the fastest as hotel chains consolidate ice production into central commissaries.
End User:
FSANZ hygiene codes are segmenting equipment specifications by contact-surface requirements and sanitization protocol intensity.
- Hotels:Full-service properties across Sydney, Melbourne, and Brisbane specify modular R290-native systems with antimicrobial bin liners and automated cleaning cycles. Procurement teams negotiate direct manufacturer pricing while unbundling maintenance to third-party refrigeration specialists.
- Restaurants:Fine-dining and casual dining operators prioritize under-counter and floor-standing configurations that balance production reliability against kitchen workflow constraints.
- Bars:High-volume cocktail venues demand rapid ice recovery rates and specialty cube shapes, driving specification toward premium modular heads with separate storage.
- Cafes:Limited ice requirements focus procurement on compact, energy-efficient units where capital outlay minimization dominates vendor selection.
Equipment volume concentrates in Hotels; Bars are expanding their share fastest as Australia's licensed venue count rebounds.
Distribution Channel:
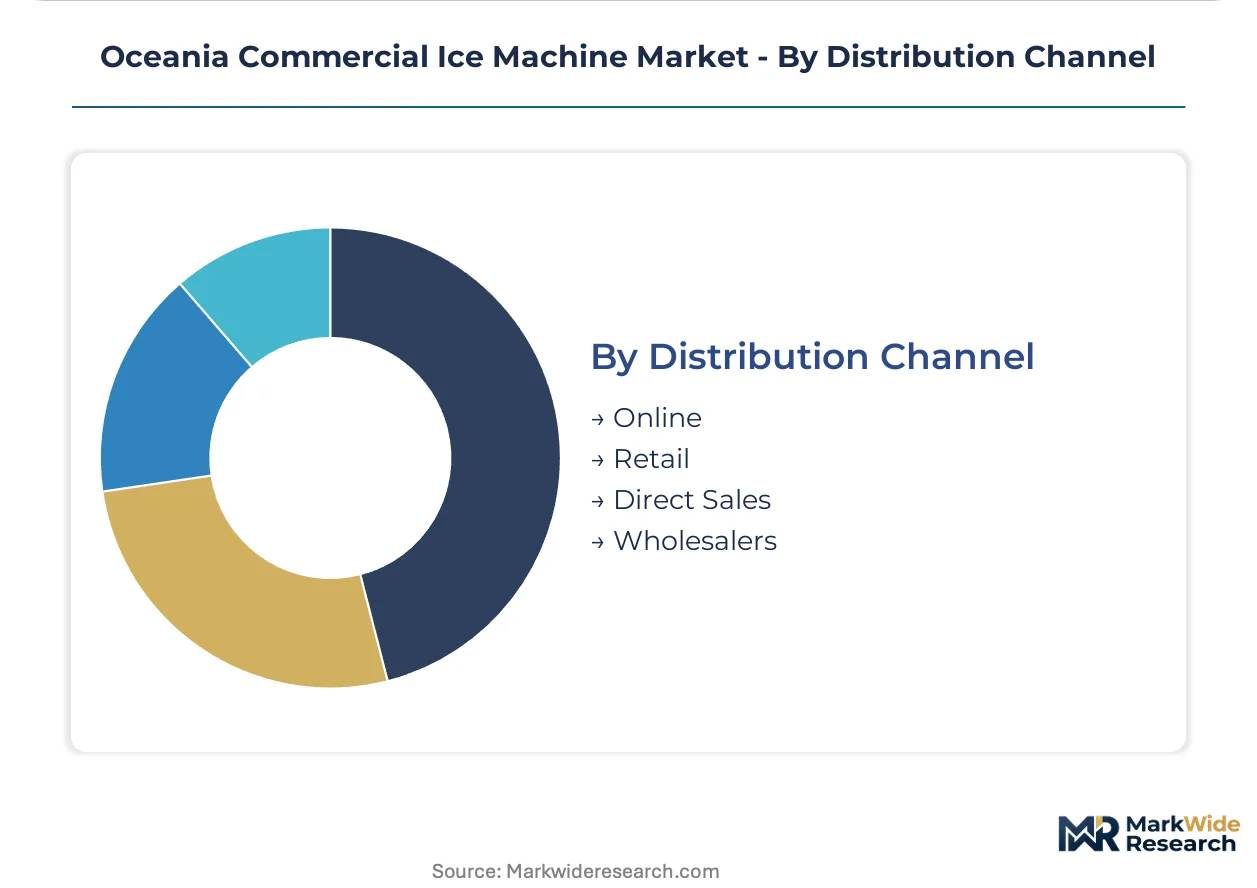
Channel selection tracks customer scale and technical service requirements, with fragmentation accelerating as large chains unbundle procurement from maintenance.
- Direct Sales:Manufacturer relationships with multi-site hotel groups bypass distributor margins, most visible in Melbourne's corporate hospitality sector where centralized procurement teams negotiate fleet-wide pricing.
- Wholesalers:Refrigeration supply houses dominate equipment flow to independent restaurants and regional venues, bundling installation with ongoing technical support.
- Retail:Equipment dealers serve small operators and replacement markets where immediate availability outweighs specification optimization.
- Online:E-commerce platforms capture specification-driven buyers comparing energy ratings and refrigerant compliance, though final purchase often routes through authorized dealers for warranty validation.
Transaction volume concentrates in Wholesaler channels; Direct Sales are gaining share fastest as hospitality chain consolidation proceeds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Australia's metropolitan hospitality corridors, where Sydney and Melbourne hotel operators are expanding kitchen infrastructure to capture rebounding tourism volumes. New Zealand's regional tourism markets present parallel expansion opportunities as infrastructure investment lags visitor growth trajectories.
Australia
Hotel procurement teams in Sydney and Melbourne are specifying modular R290-native ice production systems for new-build developments. Australia's MEPS program and E3 Program govern minimum energy performance thresholds, eliminating import eligibility for legacy refrigerant platforms. Queensland's Gold Coast corridor sees concentrated casino resort and convention hotel deployments of large-capacity systems.
New Zealand
Regional hospitality operators in Queenstown and Rotorua are accelerating equipment procurement as tourism infrastructure remains under-equipped relative to visitor arrivals. New Zealand's E3 regulations and Building Code compliance requirements shape installation standards and operational efficiency benchmarks. Auckland's hospitality corridors drive under-counter system demand among space-constrained boutique venues.
Papua New Guinea
Mining camp catering operations and Port Moresby hospitality venues sustain import demand for durable floor-standing equipment configurations. The country's national standards body applies adopted Australian technical regulations to commercial refrigeration imports. Supply chains route through Brisbane distribution hubs, extending lead times for replacement parts and technical service.
Fiji
Resort reconstruction following cyclone damage is lifting modular ice machine procurement across Viti Levu's tourism belt. The Fiji Commerce Commission oversees consumer protection standards that indirectly affect commercial equipment warranty enforcement. Nadi and Denarau Island hotel clusters are consolidating ice production into central commissaries to reduce energy costs.
French Polynesia
Tahiti's cruise ship provisioning infrastructure and Bora Bora resort operations import specialized equipment through Papeete distribution channels. French overseas territory status subjects commercial refrigeration to EU F-Gas Regulation and CE marking requirements. Papeete's limited technical service capacity constrains deployment of complex hydrocarbon-based systems.
Oceania Commercial Ice Machine Market Competitive Landscape
Portfolio diversification dominates the current landscape as equipment manufacturers bundle ice production with broader refrigeration and kitchen system offerings. The vendor base separates into three strategic tiers: integrated kitchen equipment conglomerates with multi-brand portfolios, specialized ice machine fabricators with dedicated production focus, and regional distributors with unbundled service capabilities. Two competitive moves define current positioning: direct manufacturer relationships with large hospitality chains that bypass traditional distributor margins, and after-sales service unbundling that fragments legacy procurement-maintenance bundles.
Among Japanese-origin specialists, Hoshizaki Corporation and Manitowoc Ice (Welbilt Inc.) occupy positions anchoring supply relationships with major Australian hotel operators and high-volume New Zealand bar installations respectively. Electrolux Group exemplifies the integrated conglomerate archetype, competing through bundled kitchen equipment portfolios that combine ice production with refrigeration systems. These three companies represent the dominant competitive vectors shaping procurement patterns across Oceania's metropolitan hospitality corridors.
| Leading Market Players |
|---|
| Ice-O-Matic |
| Electrolux Group |
| Hoshizaki Corporation |
| Ali Group |
| Focusun Refrigeration |
| Manitowoc Ice (Welbilt Inc.) |
| Follett LLC |
| BREMA GROUP |
| Scotsman Ice Systems |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap distributors across Australia and New Zealand anchor supply relationships with Asian manufacturing partners, translating refrigerant compliance costs into tiered equipment pricing that rewards early R290 adopters while penalizing legacy platform holdouts. Their concentrated ownership structures enable pricing discipline that resists margin erosion despite volatile copper and aluminum input costs.
Pricing Analysis
Volume placements concentrate in standard-tier equipment where MEPS compliance absorbs margin; premium-tier R290-native systems command pricing power through TGA certification scarcity and energy rebate eligibility. Price differentiation hinges on refrigerant platform maturity and state-level incentive stacking, with Australian hospitality chains showing lowest sensitivity due to unbundled procurement models. Cost compression in mid-tier modular systems is intensifying because Southeast Asian assembly concentration exposes landed costs to logistics bottlenecks.
Supply Chain Analysis
Single-source vulnerability sits with Thailand, Malaysia, and China's Guangdong province as the dominant assembly nodes for vapor-compression refrigeration platforms serving Oceania. Heat exchanger production draws from Indonesian copper smelters and Australian bauxite refinement, creating raw material dependencies that amplify tariff exposure from regional trade friction. Distribution runs through Brisbane and Sydney wholesaler networks for Australia, with Auckland refrigeration supply houses capturing New Zealand flow.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where Australia's MEPS program and New Zealand's E3 regulations erect barrier-to-entry moats that favor incumbent distributors with established certification pipelines and direct manufacturer relationships.
For Market Incumbents: Extend R290-native product portfolios ahead of refrigerant phase-down deadlines to capture replacement cycle acceleration from stranded legacy assets. Deepen direct sales relationships with multi-site hotel chains in Sydney and Melbourne corridors to defend against third-party service aggregators unbundling maintenance contracts. Capacity addition in Queensland's Gold Coast casino resort cluster offers geographic hedge against metropolitan saturation. For New Entrants and Emerging Players: New Zealand's E3 regulations in Queenstown and Rotorua open a window for regional hospitality infrastructure plays where incumbent coverage remains thin. Target under-counter system penetration in Auckland's boutique cafe networks as the most penetrable segment, leveraging compact R290 configurations that bypass separate condenser installation complexity. A go-to-market angle through refrigeration technician training partnerships addresses licensed hydrocarbon installer scarcity constraining regional deployment. For Investors and Strategic Acquirers: Distressed-cycle entries favor Australian distributors with stranded R404A inventory and concentrated Queensland resort exposure as interest rate pressure forces recapitalization. Mid-cap specialists with unbundled service capabilities and IoT-enabled maintenance subscriptions present viable acquisition profiles against a five-to-ten year compliance-driven replacement horizon. The signal to watch is TGA certification queue length for high-capacity R290 platforms as inflection indicator for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| R290 Refrigerant Platform Transition | Natural hydrocarbon systems preempt MEPS compliance retrofit costs for Sydney hotel operators. |
| IoT-Enabled Predictive Maintenance | Sensor-integrated units open subscription revenue streams for multi-site hospitality chains. |
| Direct Manufacturer Relationship Expansion | Bypassing wholesaler margins captures value in Melbourne corporate hospitality procurement consolidation. |
| Regional Service Network Buildout | Licensed hydrocarbon installer capacity unlocks Queenstown and Rotorua tourism infrastructure deployment. |
| Energy Efficiency Incentive Stacking | Australian state-level rebates layered atop federal MEPS windows accelerate pre-MEPS equipment retirement. |
Research Methodology
Trade customs records, E3 Program compliance filings, and FSANZ regulatory guidance documents formed the secondary backbone for equipment flow and energy efficiency mandate tracking. Primary interviews with hospitality procurement directors, refrigeration supply house managers, and licensed hydrocarbon system installers combined with this secondary validation through bottom-up installation database triangulation and top-down market sizing reconciliation.
Historical trendline analysis of equipment replacement cycles against regulatory phase-down schedules established baseline demand patterns across the projection horizon. Segmentation modeling captured product type, capacity tier, end-user vertical, and distribution channel dynamics alongside refrigerant platform transition velocity as a market-specific dimension. CAGRs derived from unit placement trajectories weighted by average selling price evolution, with TGA certification timelines and state-level rebate program windows as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for R448A transitional platforms or accelerated synthetic refrigerant phase-down would alter the outlook. Forecasts reflect assumptions about tourism capacity recovery velocity and technician training pipeline expansion that material supply constraints or demand shocks could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Commercial Food Dehydrators Market
Food Processing Equipment
Cake Cutting Machines Market
Food Processing Equipment
Food Slicer and Dicer Market
Food Processing Equipment
Nut Processing Machine Market
Food Processing Equipment
Bottling Machinery Market
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
Microbrewery Equipment Market
Food Processing Equipment
Small Brewery Equipment Market
Food Processing Equipment
Double Stack Oven Market
Food Processing Equipment
Automatic Grilling Machine Market
Food Processing Equipment
Freeze Thaw Chambers Market
Food Processing Equipment
Middle East and Africa Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Commercial Wood Fired Pizza Oven Market
Food Processing Equipment
Clean in Place Market
Food Processing Equipment
Canning Machine Market
Food Processing Equipment
Beverage Processing Equipment Market