
 United States Meat Substitutes Market | 2026-2036
United States Meat Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
United States Meat Substitutes Market Analytics
Asset-light contract manufacturing and co-packing arrangements are narrowing the capital barrier for new entrants in the United States meat substitutes space. Beyond Meat sustains large-scale extrusion capacity and direct retail distribution. Impossible Foods differentiates through heme protein technology and foodservice partnerships. Amy's Kitchen leverages its organic frozen food heritage to anchor shelf-stable positioning in natural channels.
Meat substitutes encompass protein-rich formulations engineered from plant biomass, microbial fermentation, or cultivated animal cells to replicate the sensory and nutritional properties of conventional meat, typically achieving protein densities of 15-25 grams per serving through extrusion, shear-cell processing, or precision fermentation. The primary commercial purpose centers on displacing animal agriculture in retail and foodservice protein procurement. Soy-derived products dominate current volume due to established supply chains and cost structures, while pea protein isolates represent the fastest-growing source category as allergen concerns and non-GMO positioning reshape formulation decisions. Frozen forms command the largest revenue pool, though refrigerated ready-to-eat formats are capturing margin-rich urban convenience segments.
The USDA and FDA share jurisdiction over meat substitute labeling and safety standards, with the FDA overseeing plant-based products and the USDA regulating cell-cultured meat through established meat inspection frameworks. USDA dietary guidelines influence institutional purchasing decisions in school nutrition programs and federal feeding initiatives. The Federal Trade Commission monitors advertising claims around environmental and health benefits, creating compliance complexity for brand messaging. Stakeholders must track evolving enforcement patterns across these agencies as product formats proliferate beyond traditional plant-based cuts into hybrid and cultivated categories.
Market Dynamics
Extrusion technology maturation is compressing production costs for texturized vegetable proteins, enabling mid-tier brands to achieve sensory parity with legacy leaders while FDA and USDA labeling clarifications reduce compliance uncertainty for new entrants.
Growth Catalysts
- USDA Dietary Guidelines:Federal nutrition standards for school meal programs are institutionalizing plant-based protein procurement, creating guaranteed offtake volumes for compliant suppliers.
- Pea protein isolate supply chains:Non-GMO seed breeding and Midwest processing infrastructure expansion are reducing input cost volatility for allergen-free formulations.
- California retail penetration:Dense natural grocery networks and foodservice operator experimentation on the West Coast are generating product feedback loops that accelerate formulation iteration.
Market Restraints
- Soy protein concentrate dependency:Domestic crushing capacity constraints and Brazilian export competition create raw material price instability for volume producers.
- Extrusion equipment oligopoly:German and Italian machinery suppliers control high-shear texturization technology, limiting domestic capital expenditure flexibility.
- Cell-cultured meat regulatory bifurcation:Joint FDA-USDA oversight frameworks impose dual inspection burdens that delay commercial launch timelines for cultivated protein ventures.
Strategic Opportunities
- Texas and Southeast institutional cafeterias:Underpenetrated K-12 and correctional feeding systems present volume contracts for price-competitive frozen formats.
- Precision fermentation capacity:Microbial heme and fat analog production is converging with existing pharmaceutical bioreactor infrastructure in the Northeast.
- Refrigerated convenience channel:Urban grab-and-go placement in drugstore and convenience retail is capturing incremental consumption occasions beyond traditional grocery.
Industry Challenges
- Food technologist talent scarcity:Formulation chemistry and extrusion engineering expertise concentrates with legacy meat processors and ingredient suppliers, constraining R&D velocity for emerging brands.
- Organic certification timelines:Three-year transition requirements for non-GMO soybean and pea sourcing delay premium positioning for conventional agriculture converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Meat Substitutes Market |
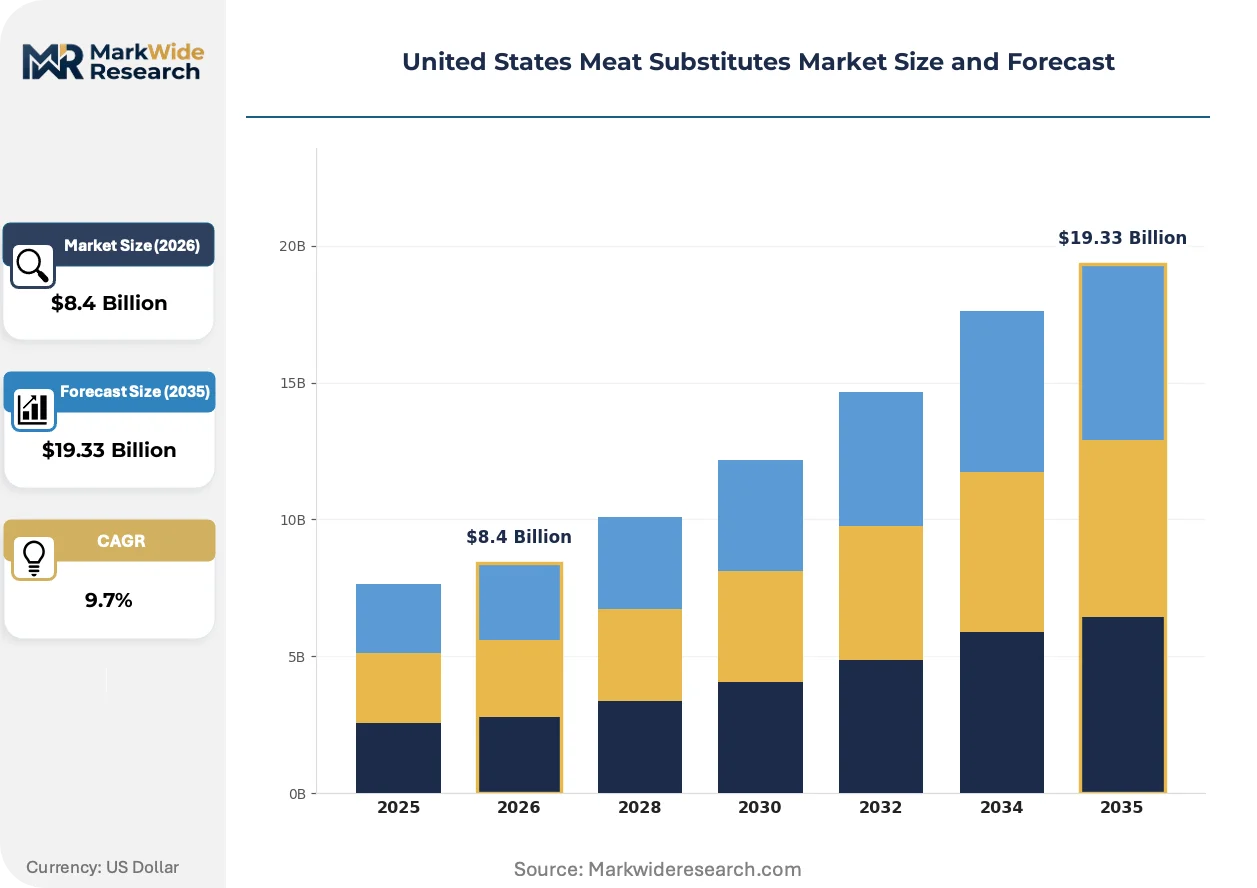
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.33 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tofu, Tempeh, Seitan, Textured Vegetable Protein Source: Soy, Pea, Wheat, Mushroom Form: Frozen, Refrigerated, Dry, Ready-to-Eat Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Foodservice |
| Companies Covered | Beyond Meat, Impossible Foods, Amy's Kitchen, Kellogg Company, Morningstar Farms, Tofurky, Tyson Foods, Unilever, Quorn Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Meat Substitutes Market Evolving Landscape
Digital process control and biosensor quality monitoring are penetrating production floors, replacing batch-based intuition with real-time protein texture optimization and yield management.
Shear-cell processing is digitizing plant protein texturization by enabling continuous-flow manufacturing with precise fiber alignment control. Mid-scale foodservice suppliers are adopting this equipment to reduce energy intensity versus legacy extrusion. The technology is digitizing quality consistency metrics that previously required post-production sensory panels.
The FDA's draft guidance on cell-cultured meat labeling is mandating distinct nomenclature standards that preempt state-level patchwork regulations. This federal preemption reduces multi-jurisdictional compliance costs for national distribution. Cultivated protein ventures are responding by accelerating GRAS self-determination filings ahead of formal USDA facility inspections.
Direct-to-foodservice procurement is consolidating buying power among contract management companies and multi-unit restaurant operators. Frozen patty and crumble specifications are displacing spot-market ingredient purchasing with annual volume commitments. This pattern is most visible in the Midwest, where institutional feeding contracts concentrate decision-making with three national distributors.
United States Meat Substitutes Market Segmentation
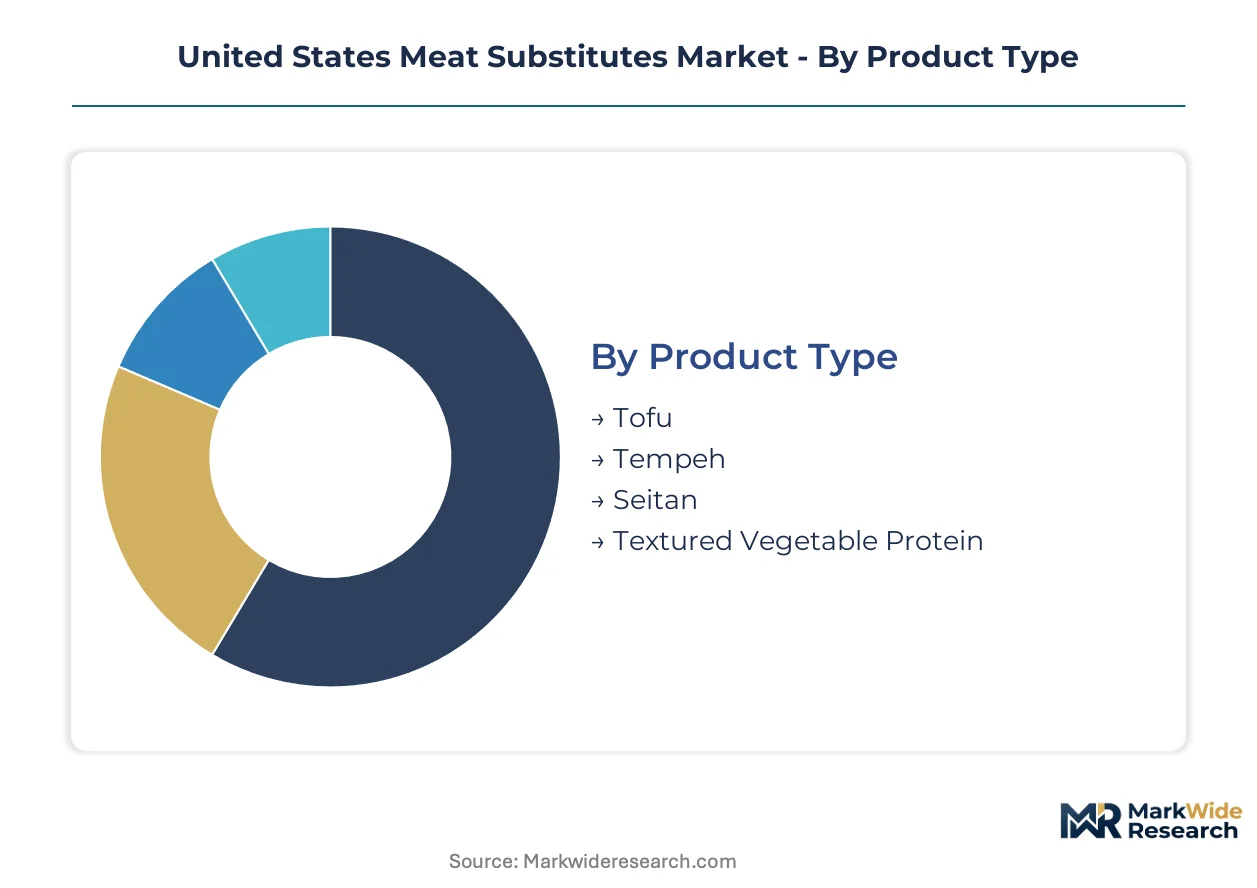
Segmentation in the United States meat substitutes market reveals how formulation choices, supply chain configurations, and channel strategies determine competitive viability. Distinct protein sources and product formats command different margin structures and regulatory treatment across retail and foodservice environments.
Product Type:
After-sales service intensity varies sharply across product types, with extrusion-based formats requiring technical support for texture optimization while traditional fermented products demand minimal post-purchase intervention.
- Tofu:Soybean curd produced through coagulation of soy milk delivers 8-15 grams protein per serving with minimal processing infrastructure. Demand concentrates in West Coast urban centers where Asian cuisine penetration and health-conscious demographics overlap, though refrigerated logistics constraints limit national distribution reach.
- Tempeh:Fermented whole soybean cake bound by Rhizopus mold mycelium offers higher fiber content and firmer texture than tofu. Foodservice operators in Pacific Northwest metropolitan areas favor tempeh for crumbled applications in bowls and tacos, driven by clean-label positioning and minimal ingredient lists.
- Seitan:Wheat gluten isolate with 25+ grams protein per serving targets high-protein fitness segments.
- Textured Vegetable Protein:Defatted soy flour extrusions serve as economical crumble and extender inputs for institutional feeding contracts.
Tofu holds the largest share; momentum sits with Textured Vegetable Protein as extrusion cost curves flatten.
Source:
Cost tier stratification in protein sourcing separates premium-positioned non-GMO and organic supply chains from conventional commodity inputs.
- Soy:Defatted soy flour and isolate dominate volume through established Midwest crushing infrastructure and Brazilian import flows. Frozen patty manufacturers in the Great Lakes region anchor procurement on soy concentrate specifications, constrained by price volatility from export market competition.
- Pea:Yellow pea protein isolate achieves 80%+ protein concentration with favorable amino acid profiles and reduced allergen labeling burdens. Fast-casual chains in California and Colorado are accelerating pea-based menu placements, responding to consumer preference surveys showing non-GMO and gluten-free demand clustering.
- Wheat:Vital wheat gluten supplies seitan production and hybrid texture systems.
- Mushroom:Mycelial biomass from submerged fermentation delivers umami depth without grain inputs.
Soy commands current volume leadership; pea is climbing the fastest as allergen-free formulations gain shelf space.
Form:
Application requirements dictate form selection, with foodservice operators prioritizing thaw stability and retail channels emphasizing visual freshness cues.
- Frozen:Blast-frozen patties, crumbles, and whole-muscle cuts sustain 12-18 month shelf life through cryogenic or mechanical freezing tunnels. Institutional cafeterias in Texas and the Southeast specify frozen formats for inventory flexibility, supported by national broadline distributor cold chain networks.
- Refrigerated:High-moisture extrudates in modified atmosphere packaging target premium urban convenience retail. Drugstore chains in Northeast metropolitan corridors are expanding refrigerated grab-and-go sets, capturing incremental consumption beyond traditional grocery weekly trips.
- Dry:Dehydrated granules and flakes require rehydration but minimize transport cost.
- Ready-to-Eat:Shelf-stable retort pouches and vacuum-sealed cuts serve camping and emergency preparedness segments.
Frozen holds the largest share; momentum sits with Refrigerated as urban convenience channels expand.
Distribution Channel:
Customer type fragmentation separates price-sensitive volume buyers from premium-positioned specialty purchasers across channel tiers.
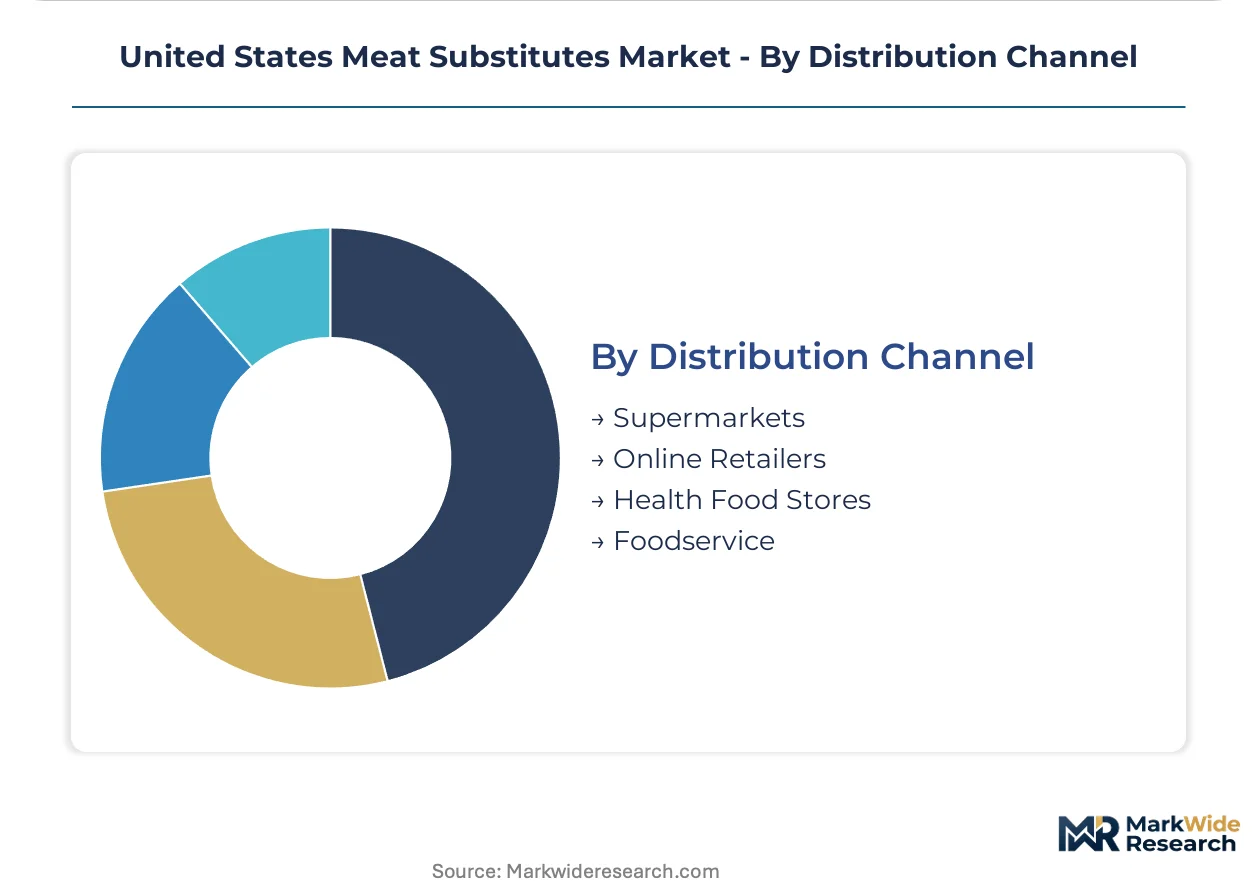
- Supermarkets:Conventional grocery chains and natural food supermarkets allocate linear feet based on velocity metrics and slotting fee structures. California-based retailers maintain the deepest shelf sets, with dedicated plant-based protein sections displacing traditional meat adjacencies in Los Angeles and San Francisco metro stores.
- Foodservice:Contract management companies and multi-unit restaurant operators consolidate procurement through annual specification agreements. Midwest institutional feeding contracts concentrate decision-making with three national distributors, locking in frozen patty volumes for K-12 and correctional systems.
- Online Retailers:Direct-to-consumer subscription and marketplace fulfillment bypass traditional retail margin stacking.
- Health Food Stores:Independent natural retailers and cooperative grocers emphasize certified organic and regional sourcing credentials.
Supermarkets hold the largest share; momentum sits with Foodservice as operator experimentation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a modest trade surplus in formulated plant proteins, exporting Midwest-processed soy isolates to Pacific Rim markets while importing specialty pea protein from Canadian Prairie processors. Import dependency for organic non-GMO feedstocks constrains margin capture in premium segments.
California
Los Angeles and San Francisco metropolitan areas concentrate the deepest retail shelf sets and fastest-casual menu penetration for meat substitutes. The California Air Resources Board's scoping plan incentivizes agricultural methane reduction, accelerating foodservice procurement shifts. Precision fermentation ventures cluster in South San Francisco biotech corridors, leveraging existing pharmaceutical bioreactor infrastructure.
Texas
Houston and Dallas institutional feeding systems present underpenetrated volume contracts for frozen patty formats in K-12 and correctional cafeterias. State procurement guidelines emphasize cost-per-protein-ounce metrics that favor textured vegetable protein specifications. Distribution hubs in Dallas-Fort Worth anchor cold chain networks reaching Southeastern markets.
Midwest
Illinois, Michigan, and Ohio house legacy extrusion capacity serving broadline distributor contracts for national institutional accounts. USDA commodity procurement for school nutrition programs flows through Chicago-based foodservice distributors. Soy crushing infrastructure in Iowa and Indiana supplies defatted flour inputs to regional patty manufacturers.
Pacific Northwest
Seattle and Portland metropolitan corridors favor tempeh and fermented whole-food formats driven by clean-label consumer preferences. Oregon Department of Agriculture organic certification programs support regional pea protein processing investments. Mycelial biomass fermentation facilities in Corvallis supply umami depth ingredients to West Coast formulation houses.
Northeast
New York Metro and Greater Boston corridors drive refrigerated ready-to-eat placement in drugstore and convenience retail channels. FDA GRAS determination filings for novel proteins concentrate in Cambridge and Research Triangle Park regulatory consulting clusters. Pharmaceutical bioreactor repurposing for precision fermentation heme production is accelerating in New Jersey contract manufacturing zones.
United States Meat Substitutes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient and equipment supply. The vendor base arranges into three functional layers: branded finished goods manufacturers, private-label co-packers, and input suppliers. Consolidation pressure concentrates at the branded tier where slotting fee structures and foodservice specification contracts create scale thresholds. Competitive moves center on extrusion capacity expansion and direct-to-foodservice procurement consolidation.
Within the branded platform tier, Beyond Meat, Impossible Foods, and Amy's Kitchen occupy distinct positioning archetypes. Beyond Meat exemplifies scale-driven retail distribution with captive extrusion infrastructure. Impossible Foods represents technology-differentiated foodservice penetration through proprietary protein engineering. Amy's Kitchen anchors heritage organic positioning in natural channel frozen sets. These three California-origin entities illustrate how formulation philosophy and channel strategy determine competitive viability without requiring identical operational models.
| Leading Market Players |
|---|
| Beyond Meat |
| Impossible Foods |
| Amy's Kitchen |
| Kellogg Company |
| Morningstar Farms |
| Tofurky |
| Tyson Foods |
| Unilever |
| Quorn Foods |
| Others |
Value Network & Pricing Analysis
German and Italian extrusion equipment suppliers anchor upstream supply concentration, directing margin capture toward machinery financing and aftermarket service tiers while compressing pricing flexibility for domestic patty manufacturers dependent on high-shear texturization technology.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across frozen patty and crumble specifications. Three-tier pricing structure across premium, standard, and economy levels separates certified organic formulations from conventional commodity inputs and private-label economy tiers. Cost compression in the standard tier is intensifying because Brazilian soy export competition and Midwest crushing capacity constraints create raw material price instability. K-12 and correctional feeding systems in Texas and the Southeast exhibit the highest price sensitivity, while West Coast natural channel retailers show the lowest.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for pea protein isolate procurement as Midwest processors compete with Canadian Prairie suppliers for non-GMO seed flows. Raw material sourcing draws from Brazilian soy export flows, Canadian yellow pea protein isolate, and domestic Midwest crushing output. Single-source vulnerability concentrates in German and Italian high-shear extrusion equipment, where domestic capital expenditure flexibility remains constrained. Distribution runs through three national broadline distributors anchoring Midwest institutional feeding contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward contract management companies and multi-unit restaurant operators as procurement consolidation accelerates across foodservice channels, fragmenting supplier pricing leverage.
For Market Incumbents: Harden captive extrusion capacity positions in the Midwest against emerging shear-cell processing entrants by expanding direct-to-foodservice specification contracts. Deepen backward integration into non-GMO pea protein isolate supply through Midwest seed breeding partnerships. Certification investment in USDA organic and non-GMO Project Verified tiers defends shelf space against private-label encroachment in California retail networks. For New Entrants and Emerging Players: Pursue underpenetrated K-12 and correctional cafeteria contracts in Texas and the Southeast through price-competitive textured vegetable protein specifications. The refrigerated convenience channel in Northeast urban drugstore chains offers the most penetrable white space beyond traditional grocery. A foodservice-first go-to-market angle leveraging co-packing arrangements minimizes capital barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision fermentation ventures in South San Francisco biotech corridors holding GRAS self-determination filings but awaiting USDA facility inspections. Long-term viability hinges on successful navigation of dual FDA-USDA oversight frameworks for cell-cultured meat commercialization. The signal to monitor is accelerated USDA inspection queue clearance for cultivated protein facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Extrusion Capacity Expansion | Captive high-shear texturization infrastructure locks in foodservice specification contracts with broadline distributors. |
| Pea Protein Isolate Backward Integration | Midwest non-GMO seed breeding partnerships reduce input cost volatility for allergen-free formulations. |
| Precision Fermentation Scale-Up | Pharmaceutical bioreactor repurposing in New Jersey accelerates microbial heme production timelines. |
| Direct-to-Foodservice Procurement Consolidation | Annual volume commitments with contract management companies displace spot-market ingredient purchasing. |
| Refrigerated Convenience Channel Expansion | Urban drugstore and convenience retail placement captures incremental consumption beyond weekly grocery trips. |
Research Methodology
A spread of perspectives from extrusion engineering directors, foodservice procurement managers at contract management companies, plant-based brand managers, and ingredient supplier technical sales converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from FDA GRAS determination filings, USDA commodity procurement databases, SEC 10-K disclosures from publicly traded food companies, and Nielsen retail audit data. Bottom-up volume modeling across protein source and form segments triangulated against top-down market sizing from trade flow analysis.
Demand-supply balance dynamics shaped the analytical framework throughout the forecast period. Segmentation dimensions modeled include protein source, product form, and distribution channel, with additional granularity on foodservice versus retail procurement patterns. CAGRs were derived from trend extrapolation of historical volume flows adjusted for regulatory milestone impacts. Forecast inputs incorporated USDA dietary guideline revision timelines and precision fermentation capacity buildout trajectories.
Sensitivities concentrate around FDA-USDA regulatory coordination pace, Brazilian soy export tariff exposure, and precision fermentation yield improvements. Forecasts reflect documented assumptions on extrusion cost curve trajectories and institutional procurement adoption rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Food Market
Plant Based Food
Plant Based Protein Market
Plant Based Food
New Jersey Vegan Products Market
Plant Based Food
United States Pea Protein Market
Plant Based Food
Vegan Dips Market
Plant Based Food
Fermented Plant Extracts Market
Plant Based Food
Vegan Dessert Market
Plant Based Food
Plant-Based Margarine Market
Plant Based Food
Plant Based Cheese Market
Plant Based Food
Vegan Oatmeal Market
Plant Based Food
Europe Textured Vegetable Protein Market
Plant Based Food
Plant Based Ice Cream Market
Plant Based Food
Global Plant Based Food Market
Plant Based Food
Targeting Pod Market
Plant Based Food
Vegan Chocolate Market
Plant Based Food
Vegan Spaghetti Market