
 North America MRI (Magnetic Resonance Imaging) Market | 2026-2036
North America MRI (Magnetic Resonance Imaging) Market Size, Share, and Industry Trends Forecast 2026-2036
North America MRI (Magnetic Resonance Imaging) Market Intelligence
The unbundling of software from hardware in MRI systems is rebalancing purchasing decisions for hospitals and diagnostic centers in North America. This shift allows for greater customization and integration with existing hospital IT infrastructure. Siemens Healthineers leverages its deep software expertise to offer advanced analytics platforms as standalone products. GE Healthcare competes by offering comprehensive service and hardware packages, while Canon Medical Systems Corporation differentiates with specialized ultra-high-field systems.
Magnetic Resonance Imaging is a non-invasive medical imaging technique that utilizes strong magnetic fields, measured in Tesla (T), and radio waves to generate detailed anatomical and physiological images. Its primary purpose is to visualize soft tissues, such as the brain, muscles, and organs, for disease diagnosis and monitoring without using ionizing radiation. High-field closed MRI systems dominate the clinical market for their image quality, but ultra-high-field MRI represents a high-margin niche in research institutes. While hospitals remain the largest end-user segment, standalone diagnostic centers are expanding service access for musculoskeletal applications.
The market operates under stringent regulatory oversight from the U.S. Food and Drug Administration (FDA) and Health Canada. These agencies' pre-market approval processes for new MRI devices and AI-powered diagnostic software directly govern product innovation and market entry timelines. System manufacturers and healthcare providers must navigate evolving reimbursement policies, which increasingly tie payment to diagnostic accuracy and patient outcomes.
Market Dynamics
The central force shaping the North America MRI market is the rapid integration of artificial intelligence into diagnostic workflows. This shift, supported by evolving FDA guidelines for software as a medical device, is moving value from hardware specifications to analytical capabilities.
Growth Catalysts
- Oncology Segment Expansion:The rising incidence of cancer across North America fuels demand for high-resolution MRI in tumor detection, staging, and treatment monitoring, particularly for soft tissue cancers where MRI provides superior contrast and detail.
- AI in Diagnostics:The adoption of AI-powered software for image analysis accelerates diagnostic speed and accuracy. This technology helps radiologists identify subtle anomalies and quantify disease progression, improving patient outcomes in neurology and cardiology.
- Favorable Reimbursement:Evolving reimbursement policies in the United States are increasingly tying payments to diagnostic accuracy and efficiency. This incentivizes hospitals and diagnostic centers to invest in advanced MRI systems that improve clinical results.
Market Restraints
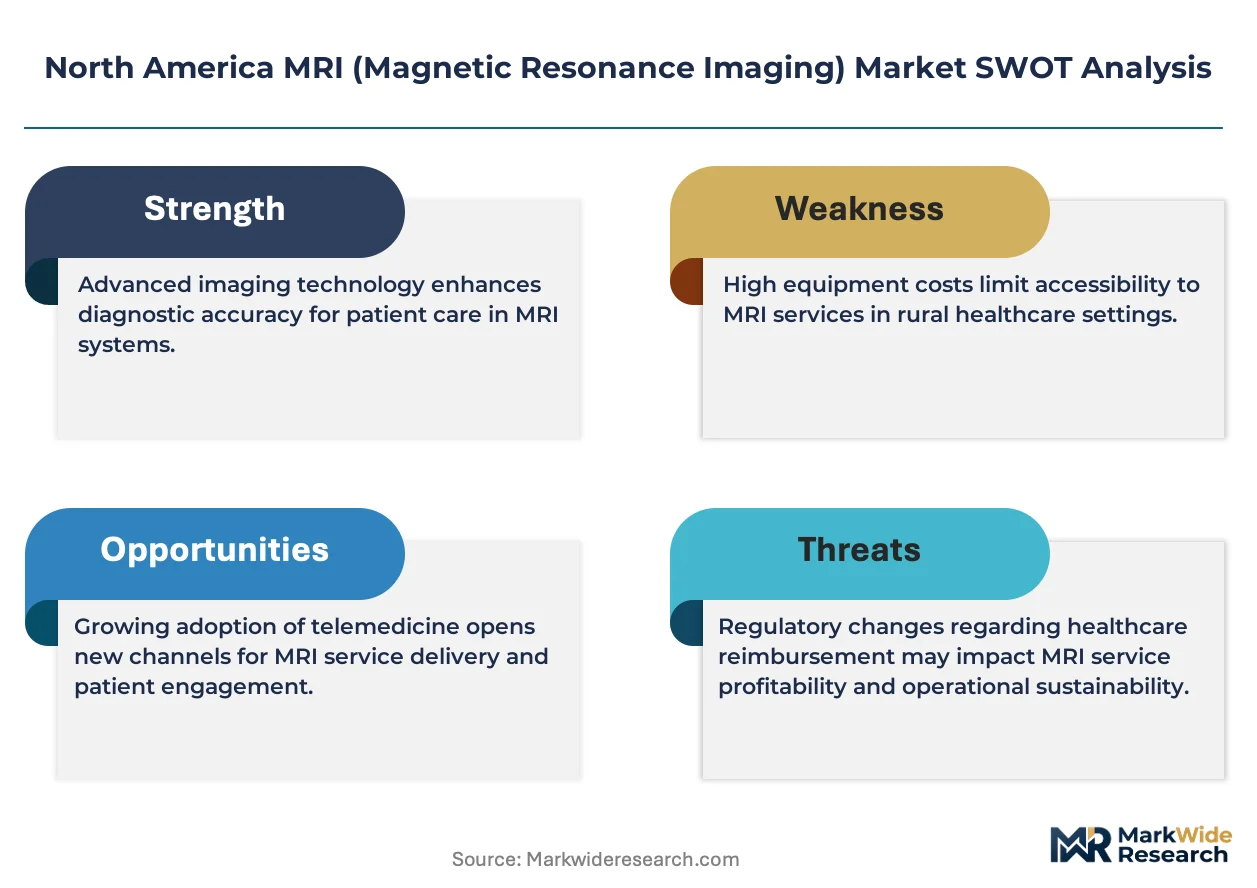
- High Capital Costs:The significant upfront investment required for high-field and ultra-high-field MRI systems, along with substantial maintenance and siting expenses, restricts adoption, especially for smaller healthcare facilities and clinics in both the U.S. and Canada.
- Helium Supply Scarcity:MRI systems rely on liquid helium as a cryogen for their superconducting magnets. Global supply chain volatility and rising costs for helium present a significant operational restraint for facilities operating these systems.
- Technical Limitations:Patient contraindications, such as the presence of certain metallic implants, and challenges like claustrophobia in closed-bore systems limit the eligible patient population. Image artifacts can also compromise diagnostic quality, requiring repeat scans.
Strategic Opportunities
- Portable MRI Systems:The development of low-field, portable MRI scanners creates an opportunity to expand diagnostic imaging to point-of-care settings like emergency rooms and intensive care units, addressing a critical need for rapid neurological assessment.
- Functional MRI (fMRI) Expansion:There is a growing opportunity in the use of fMRI for pre-surgical planning and in neuroscience research. This specialized application represents a high-value niche for academic medical centers and specialized neurological institutes.
- Tele-Radiology Integration:Expanding tele-radiology services allows for remote interpretation of MRI scans, alleviating radiologist shortages in rural and underserved areas of North America and improving access to specialized expertise.
Industry Challenges
- Technologist Skill Gaps:A persistent shortage of qualified MRI technologists trained to operate advanced systems and manage complex scanning protocols poses a significant operational bottleneck for healthcare providers across the United States and Canada.
- Data Interoperability:Integrating new MRI systems and their associated AI software with existing hospital IT infrastructure, including legacy Picture Archiving and Communication Systems (PACS), presents a major technical and logistical challenge.
- Regulatory Compliance Timelines:The stringent pre-market approval processes managed by the FDA and Health Canada for new MRI devices and AI algorithms can create long lead times, delaying the introduction of innovative technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America MRI (Magnetic Resonance Imaging) Market |
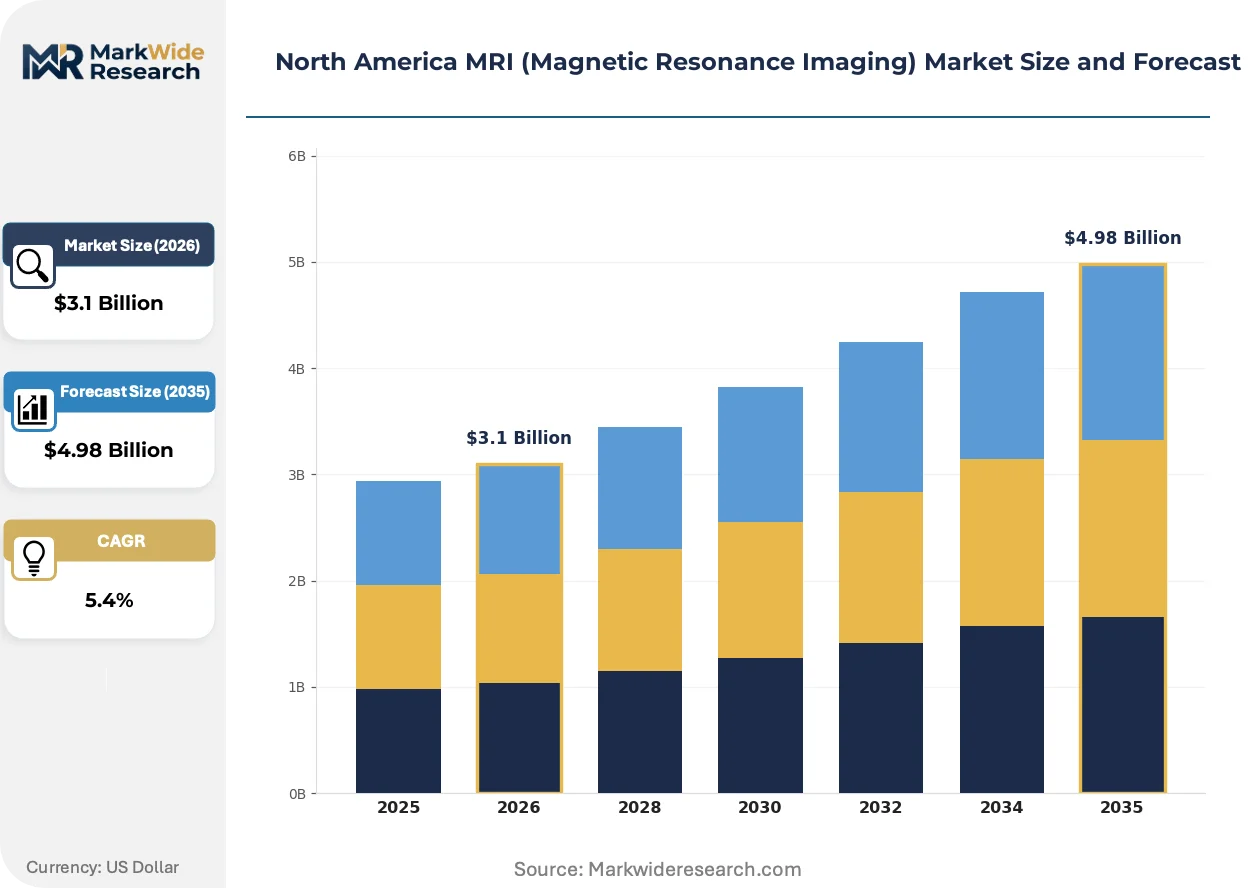
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Ultra-High-Field MRI, Portable MRI Application: Neurology, Musculoskeletal, Cardiovascular, Oncology, Abdominal Imaging, Pediatric Imaging End User: Hospitals, Diagnostic Centers, Ambulatory Surgical Centers, Research Institutes, Orthopedic Clinics Deployment: In-Hospital, Standalone Facilities, Mobile Units, University Medical Centers, Specialty Clinics |
| Companies Covered | Canon Medical Systems Corporation, Esaote SpA, GE Healthcare, United Imaging Healthcare, Neusoft Medical Systems, Siemens Healthineers, FUJIFILM Healthcare, Hologic Inc., Koninklijke Philips, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America MRI (Magnetic Resonance Imaging) Market Strategic Shifts & Innovations
The North American MRI market is being redefined by the convergence of advanced software analytics and hardware innovation. This is shifting the competitive focus from raw magnetic field strength to the generation of actionable diagnostic intelligence and operational efficiency.
Portable, low-field MRI technology provides point-of-care imaging capabilities without the need for specialized shielded rooms. Emergency departments and intensive care units are the primary adopters, seeking to perform urgent neurological scans at the bedside. This innovation is consolidating diagnostic workflows for conditions like stroke, reducing critical delays associated with transporting patients to a central radiology suite.
Evolving FDA guidance on Software as a Medical Device (SaMD) establishes a clearer pathway for the development and approval of AI-driven diagnostic tools. This regulatory framework directly encourages innovation in image analysis algorithms by providing predictable compliance requirements. MRI system manufacturers and independent software vendors are the most affected, accelerating the unbundling of advanced software from hardware sales.
Hospital procurement models are transitioning from large, one-time capital expenditures towards more flexible, long-term strategic partnerships. This change disrupts the traditional sales cycle, favoring vendors who offer comprehensive packages including service, software updates, and technology refreshes. This trend is most visible in large hospital networks across the United States aiming to manage technology lifecycle costs more effectively.
North America MRI (Magnetic Resonance Imaging) Market Segmentation
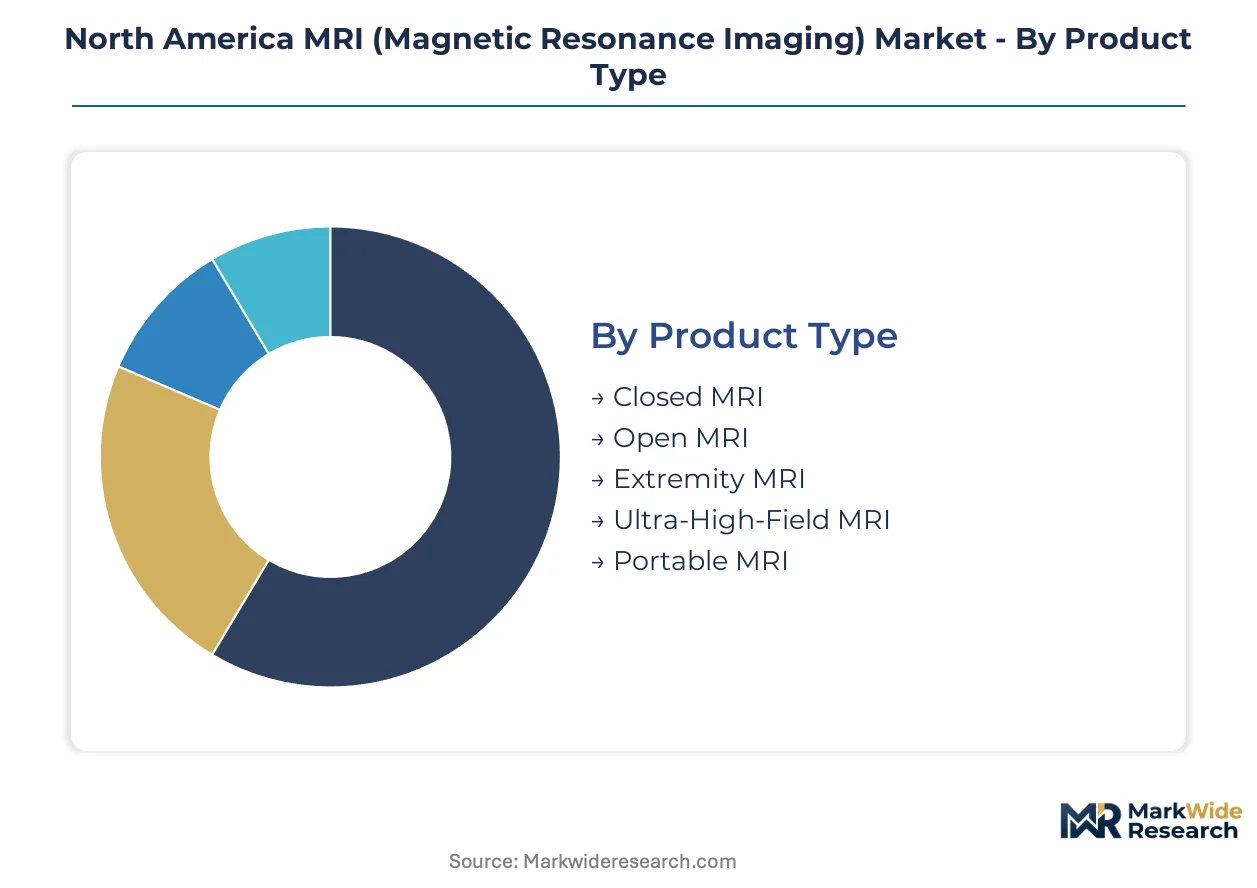
Understanding the North America MRI market through segmentation reveals distinct investment patterns and operational priorities for healthcare providers. Each segment reflects unique technological requirements, patient demographics, and regulatory considerations influencing purchasing decisions across the region. This granular view highlights where capital is deployed and services are concentrated.
Product Type:
The capital expenditure required for MRI systems varies significantly by product type, with high-field and specialized units demanding the most substantial upfront investment.
- Closed MRI:These systems utilize high-field superconducting magnets, typically 1.5T or 3T, enclosed in a cylindrical bore, offering superior image resolution and signal-to-noise ratio for detailed anatomical imaging. Demand is concentrated within large hospital networks in the United States, driven by the need for advanced diagnostic capabilities in complex cases.
- Open MRI:Featuring an open design, these systems alleviate claustrophobia and accommodate larger patients, typically operating at lower magnetic field strengths.
- Extremity MRI:These compact, dedicated scanners are optimized for imaging joints and limbs, providing high-resolution images of small anatomical structures.
- Ultra-High-Field MRI:Operating at 7T and above, these systems are primarily used in neuroscience research and specialized academic medical centers.
- Portable MRI:Low-field systems designed for bedside imaging, these units enable rapid diagnostic assessment in critical care environments without patient transport. Adoption is accelerating in emergency departments across North America, addressing urgent neurological assessment needs.
Most installed capacity flows through Closed MRI systems. Expansion is steepest in Portable MRI solutions.
Application:
The specific clinical application of MRI technology dictates the required system capabilities and image protocols, influencing purchasing decisions by diagnostic specialty.
- Neurology:MRI is indispensable for visualizing brain and spinal cord pathologies, including tumors, strokes, and degenerative diseases, offering superior soft tissue contrast. Demand is consistently high in major U.S. hospital systems, driven by the increasing incidence of neurological disorders and AI integration for image analysis.
- Musculoskeletal:This segment uses MRI for detailed imaging of joints, ligaments, tendons, and muscles, crucial for orthopedic diagnoses.
- Cardiovascular:MRI provides non-invasive assessment of heart structure and function, detecting abnormalities like congenital heart disease and myocardial infarction.
- Oncology:MRI plays a critical role in the detection, staging, and monitoring of various cancers, particularly soft tissue tumors where it offers excellent contrast resolution. Growth is fueled by the rising cancer incidence across North America, requiring precise imaging for treatment planning.
- Abdominal Imaging:This application focuses on visualizing abdominal organs like the liver, kidneys, and pancreas for disease diagnosis.
- Pediatric Imaging:Specialized MRI protocols image children, often requiring sedation and tailored sequences to minimize scan times.
Demand is primarily driven by Oncology, with Neurology showing consistent and high-value applications.
End User:
The operational scale and patient volume of different end-user segments directly influence their investment capacity and specific requirements for MRI system throughput and specialization.
- Hospitals:These institutions serve as primary sites for comprehensive diagnostic imaging, integrating MRI into a wide range of clinical departments from emergency to oncology. They represent the largest end-user segment in North America, driven by high patient volumes and the need for diverse imaging capabilities.
- Diagnostic Centers:Standalone facilities specializing in imaging services, offering convenient access for patients and often focusing on specific applications like musculoskeletal or neurological scans. These centers are expanding service access, particularly in suburban areas of the United States.
- Ambulatory Surgical Centers:These facilities perform outpatient surgical procedures, utilizing MRI for pre-operative planning and post-operative assessment in specific cases.
- Research Institutes:Academic and private research facilities use advanced MRI systems, including ultra-high-field units, for scientific studies and developing new diagnostic techniques.
- Orthopedic Clinics:Specialized clinics focusing on bone, joint, and muscle conditions, frequently employing MRI for detailed diagnosis of musculoskeletal injuries.
Hospitals represent the largest revenue contributor, while Diagnostic Centers are rapidly expanding their service footprint.
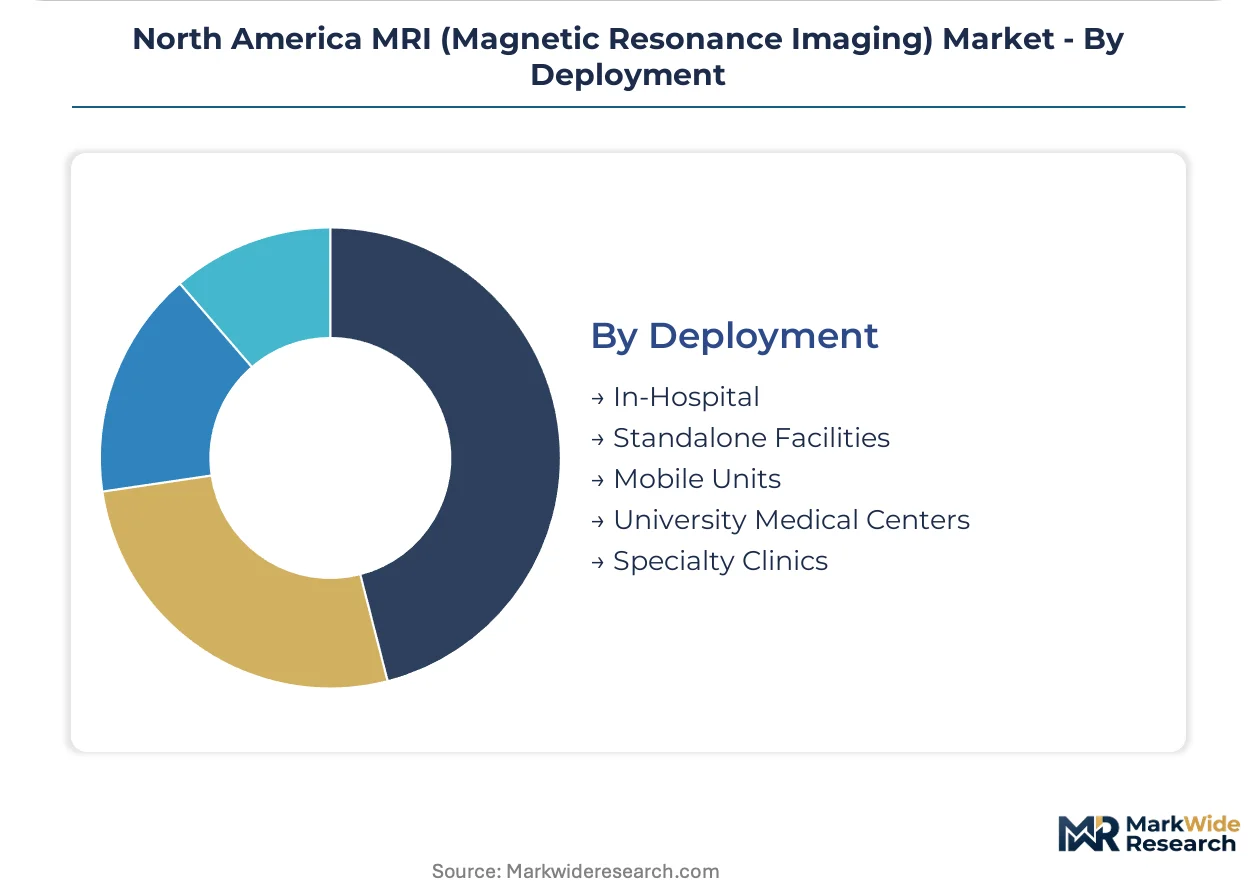
Deployment:
The physical location and operational model of MRI deployment significantly impact patient accessibility, logistical requirements, and the overall cost structure for healthcare providers.
- In-Hospital:MRI systems located within hospital premises, offering immediate access for inpatients, emergency cases, and complex diagnostic procedures requiring multidisciplinary care. This deployment model remains dominant across major urban centers in North America, ensuring integrated patient management.
- Standalone Facilities:Independent imaging centers separate from hospitals, providing specialized MRI services with a focus on patient convenience and cost-efficiency for routine scans. They are increasingly prevalent in suburban and rural areas, improving access to diagnostic imaging.
- Mobile Units:MRI scanners mounted on trucks or trailers, bringing imaging services to remote communities or serving multiple smaller facilities on a rotating schedule.
- University Medical Centers:These academic institutions combine clinical care, research, and education, housing cutting-edge MRI technology for diagnosis and scientific inquiry.
- Specialty Clinics:Dedicated clinics focusing on specific medical areas, such as neurology or orthopedics, that integrate MRI systems tailored to their particular diagnostic needs.
In-Hospital deployment forms the backbone of diagnostic services, and Standalone Facilities are improving patient access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America MRI market traces its origins to early diagnostic advancements, with significant scaling occurring across major medical institutions. This foundational development established a strong base for subsequent technological evolution and widespread clinical adoption. Regional dynamics now reflect diverse investment capacities and regulatory landscapes.
United States
The United States market for MRI systems maintains robust demand, particularly within the oncology segment and for AI-driven diagnostics. The U.S. Food and Drug Administration (FDA) stringently regulates device approvals, influencing market entry and innovation timelines. Large hospital networks in urban centers like New York City and Houston drive substantial capital investments in advanced MRI technology. Evolving reimbursement policies further incentivize improved diagnostic accuracy and efficiency across the healthcare system.
Canada
Canadian healthcare providers exhibit consistent demand for high-resolution MRI, fueled by rising cancer incidence and a need to expand diagnostic access. Health Canada's regulatory oversight ensures device safety and efficacy across all provinces, shaping procurement decisions. Major medical centers in Toronto and Vancouver concentrate significant research and clinical applications for advanced MRI systems. Tele-radiology integration is a strategic priority to address radiologist shortages in rural and underserved areas, enhancing service delivery.
Mexico
Mexico's MRI market experiences sustained demand from its developing healthcare infrastructure and increasing chronic disease burden, particularly in private sector facilities. The country's health regulatory body establishes guidelines for medical device imports and local deployment, impacting market access. Major metropolitan areas like Mexico City and Monterrey are seeing increased investment in specialized diagnostic centers for advanced imaging. These centers aim to improve patient access to advanced imaging services and enhance diagnostic capabilities regionally.
North America MRI (Magnetic Resonance Imaging) Market Key Industry Players
The competitive structure tilts toward established multinational corporations dominating the North America MRI market. This landscape is characterized by a mix of hardware-centric giants and specialized software innovators. Strategic archetypes include comprehensive system providers, advanced analytics developers, and niche ultra-high-field system manufacturers. Dominant competitive moves involve strategic partnerships for AI integration and continuous portfolio diversification to meet evolving clinical needs.
On the premium-tier vector, Siemens Healthineers exemplifies software expertise with its advanced analytics platforms offered as standalone products. GE Healthcare anchors comprehensive hardware and service packages, maintaining a strong presence across hospital networks and diagnostic centers. Canon Medical Systems Corporation represents specialized system providers with its differentiated ultra-high-field systems, catering to research institutes and academic medical centers. These companies collectively shape the market through their distinct approaches to technology and customer engagement, reflecting varied strategic priorities.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Esaote SpA |
| GE Healthcare |
| United Imaging Healthcare |
| Neusoft Medical Systems |
| Siemens Healthineers |
| FUJIFILM Healthcare |
| Hologic Inc. |
| Koninklijke Philips |
| Others |
Cost & Logistics Intelligence
Global helium supply volatility, a critical environmental resource constraint, gates both the qualified supply of high-field MRI systems and access to premium-tier diagnostic services. This scarcity directly impacts operational costs for healthcare providers.
Pricing Analysis
Contract-based long-term procurement structures dominate the North American MRI market, often incorporating comprehensive service and software updates. Price differentiation stems from system magnetic field strength, specifically 1.5T versus 3T units, and the integration of advanced AI analytics platforms. Cost compression in standard systems intensifies due to increasing competition and the availability of reconditioned units. Hospitals and large diagnostic centers exhibit lower price sensitivity for advanced systems that improve patient outcomes.
Supply Chain Analysis
Liquid helium supply rests heavily on a limited number of global producers, primarily from the United States, Qatar, and Australia. Manufacturing of specialized superconducting magnets and high-frequency radio coils relies on a complex network of precision engineering firms. Single-source vulnerability for critical cryogens represents a significant structural risk for MRI system manufacturers and operators. Distribution runs through direct sales forces and specialized medical equipment distributors to hospitals and diagnostic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America MRI market presents a margin-expansion story, driven by the increasing adoption of AI-powered diagnostic software that enhances efficiency and enables premium-tier service offerings. This technological shift allows providers to optimize workflows and improve diagnostic accuracy.
For Market Incumbents:
Deepen strategic partnerships with software developers to embed advanced AI algorithms directly into MRI system workflows, countering competitive threats from specialized analytics firms. Invest in comprehensive service contracts that include technology refreshes and ongoing technologist training to mitigate skill gaps. Focus R&D on portable MRI systems for point-of-care applications, expanding market reach beyond traditional hospital settings.
For New Entrants and Emerging Players:
Capture market share by focusing on niche applications like musculoskeletal imaging or specialized neurology diagnostics, particularly in standalone diagnostic centers in suburban areas. Develop cost-effective, low-field portable MRI solutions that address the high capital cost restraint for smaller facilities. A go-to-market angle emphasizing rapid deployment and simplified operational requirements offers a clear entry point.
For Investors and Strategic Acquirers:
Roll-up economics work for specialized diagnostic imaging networks because of the fragmented nature of standalone diagnostic centers and the opportunity for operational synergies. Long-term viability hinges on acquiring technology firms with proprietary AI imaging analysis platforms that can integrate across diverse MRI hardware. The increasing volume of outpatient imaging procedures across North America is a signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Development | Enhances diagnostic accuracy and speed for radiologists, driving clinical utility. |
| Portable MRI Commercialization | Expands diagnostic access to critical care settings, improving patient outcomes. |
| Technologist Training Programs | Addresses the persistent skill gap for advanced MRI system operation in hospitals. |
| Helium-Efficient System Design | Mitigates operational costs and supply chain risks for healthcare providers. |
| Tele-Radiology Platform Integration | Alleviates radiologist shortages in rural areas, improving service delivery. |
Research Approach
Coverage spans North America, with primary inputs from the United States and Canada, combining extensive primary interviews with secondary validation. Key stakeholders interviewed included hospital procurement managers, clinical radiologists, biomedical engineers, and medical device R&D leads. Secondary data sources encompassed FDA filings, Health Canada regulatory documents, GPO contracts, and medical device registries. This approach utilized both bottom-up market sizing and top-down validation.
Rate-of-change decomposition analyzes market dynamics across the analysis window, modeling shifts in product type, application, end-user, and deployment. This framework also segments by technology tier, such as 1.5T versus 3T systems. Compound annual growth rates were derived from historical trends and projected future demand. Key forecast inputs include cancer incidence rates and AI integration timelines in diagnostic workflows.
Regulatory changes from the FDA, helium supply chain disruptions, and technologist skill shortages are the dominant revision risks for market projections. Forecasts reflect assumptions about technology adoption and healthcare spending. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
3D Medical and Surgical Imaging Platform Market
Medical Imaging
Global AI for Radiology Market
Medical Imaging
Middle East and Africa Digital X-Ray Devices Market
Medical Imaging
X-Ray Film Market
Medical Imaging
Japan Computed Tomography Market
Medical Imaging
Wireless Intraoral Camera Market
Medical Imaging
Global Colposcopy Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
Global Elastography Imaging Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
Transesophageal Echocardiography (TEE) Market
Medical Imaging
AI Radiology Worklist Orchestration Market
Medical Imaging
Global Veterinary Diagnostic Imaging Market
Medical Imaging
China Digital X-Ray Market
Medical Imaging
Africa Nuclear Imaging Market
Medical Imaging
Whole-Body Imaging Market