
 China Digital X-Ray Market | 2026-2036
China Digital X-Ray Market Size, Share, and Industry Trends Forecast 2026-2036
China Digital X-Ray Market Outlook
Buyer concentration among provincial hospital consortia is restructuring procurement dynamics across China's medical imaging sector. Shanghai United Imaging Healthcare Co., Ltd. anchors its position through captive flat-panel detector production. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. leverages vertical integration across ultrasound and digital radiography portfolios. Wandong Medical Equipment dominates the installed base in northern provincial health networks through decades-long distributor relationships.
China digital X-ray systems employ flat-panel detectors with cesium iodide or gadolinium oxysulfide scintillator layers, converting X-ray photons into electrical signals for immediate digital output without chemical processing. Their primary purpose spans trauma assessment, chest screening, and orthopedic diagnosis across high-throughput hospital departments. Fixed systems occupy the revenue core in tier-one city hospitals where throughput justifies capital intensity, while portable systems represent the fastest-expanding segment as county-level facilities upgrade emergency and bedside imaging capacity. Direct Radiography technology leads technology-based margins due to superior dose efficiency and workflow speed versus Computed Radiography retrofits.
NMPA device registration rules and GB 9706 electrical safety standards shape product compliance costs and market access timelines for domestic and imported equipment alike. China's dual carbon goals are pressing manufacturers toward lower-power detector designs and reduced rare-earth content in scintillator formulations. Stakeholders must monitor how municipal health bureau bulk tenders balance total cost of ownership against localization requirements in upcoming procurement cycles.
Market Dynamics
Provincial hospital consortia are consolidating procurement authority, compressing vendor margins while favoring suppliers with captive flat-panel detector production and established distributor networks in Jiangsu, Guangdong, and Beijing municipal systems.
Growth Catalysts
- Dual carbon goals:MEE mandates on medical equipment energy efficiency are accelerating hospital replacement cycles for legacy high-power systems. Municipal health bureaus prioritize lower-consumption DR units in bulk tenders.
- County-level facility upgrades:Emergency and bedside imaging capacity expansion across tier-three hospitals and township health centers is pulling portable digital X-ray system demand.
- Direct Radiography superiority:Superior dose efficiency and workflow speed versus Computed Radiography retrofits is concentrating new capital allocation toward DR technology in high-throughput departments.
Market Restraints
- Scintillator material concentration:Cesium iodide and gadolinium oxysulfide supply chains face price volatility from rare-earth processing bottlenecks concentrated in specific mining jurisdictions.
- NMPA registration timelines:Device approval pathways for imported components extend market access windows, favoring domestic manufacturers with established regulatory relationships.
- Computed Radiography lock-in:Existing CR infrastructure in budget-constrained county hospitals delays full DR conversion, stretching replacement cycles beyond optimal equipment lifespans.
Strategic Opportunities
- Mobile unit penetration:Northern provincial health networks under Wandong Medical Equipment's distributor coverage present expansion white space for competing portable system vendors.
- AI-integrated diagnostic workflow:Convergence of machine learning algorithms with digital radiography output is creating premium pricing tiers for automated image analysis capabilities.
- GB 9706 electrical safety compliance:Tightening standards create regulatory tailwind for manufacturers with in-house testing infrastructure and pre-certified component libraries.
Industry Challenges
- Detector engineering talent scarcity:Flat-panel design and scintillator layer optimization require specialized photonics expertise concentrated in limited domestic talent pools.
- Legacy PACS integration complexity:County hospital information systems vary widely in vintage and vendor, complicating seamless digital radiography deployment without costly middleware.
- Localization verification burden:NMPA requirements for domestic component sourcing documentation add administrative overhead to supply chain reconfiguration efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Digital X-Ray Market |
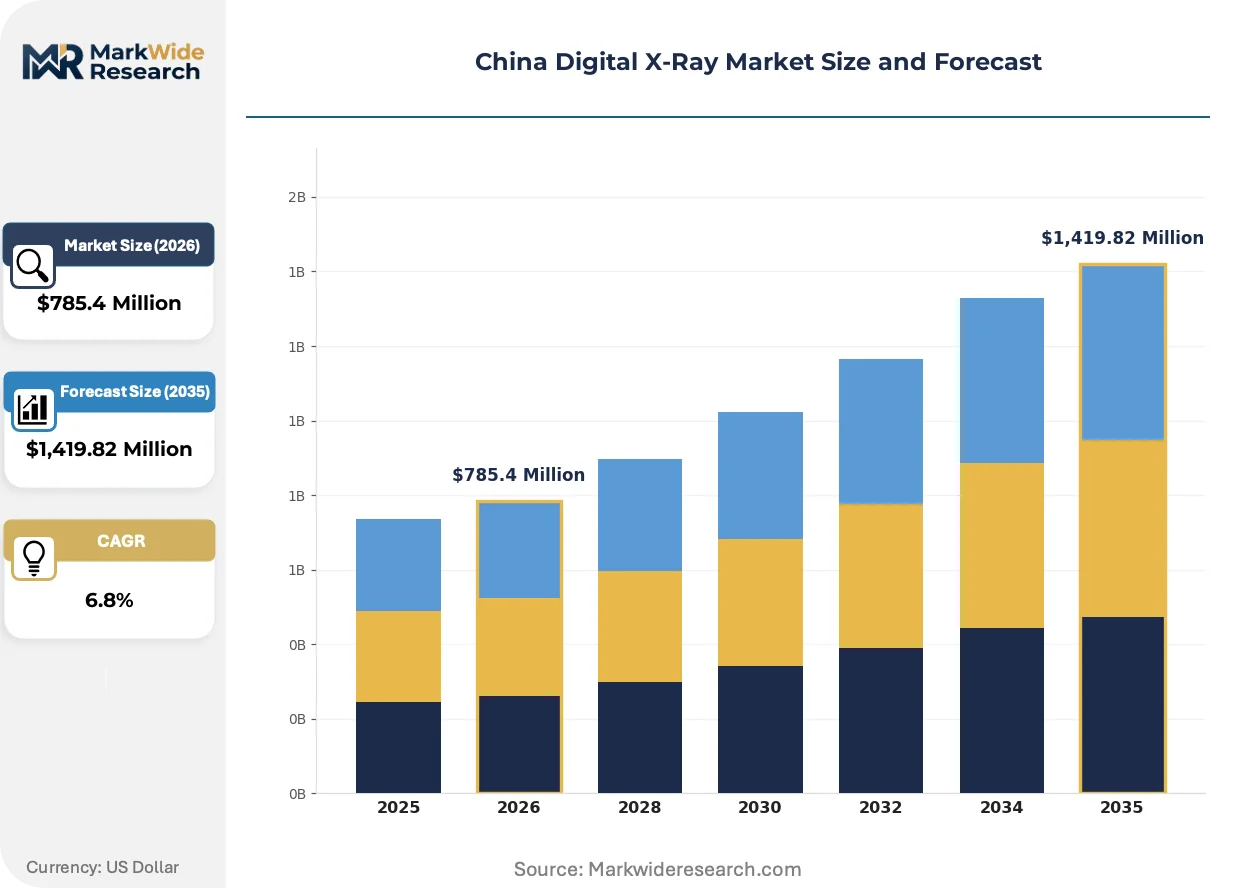
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,419.82 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable System, Fixed System, Mobile Unit, High-Definition Unit End User: Hospitals, Diagnostic Centers, Research Labs, Outpatient Facilities Technology: Computed Radiography, Direct Radiography, Analog, Hybrid Systems Installation: On-site, Off-site, Telecommunication, Centralized |
| Companies Covered | Shanghai Guangzheng Medical Equipment Co., Ltd., Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Shanghai United Imaging Healthcare Co., Ltd., Shanghai Handy Medical Equipment Co., Ltd., Wandong Medical Equipment, Orich Medical Equipment (Tianjin) Co., Ltd., Shanghai Jieying Medical Technology Co., Ltd., Shanghai IRAY Technology Co., Ltd., Shanghai Rixi Medical Equipment Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Digital X-Ray Market Strategic Shifts
Digital radiography hardware is fragmenting into configurable subsystems, allowing hospitals to mix detector specifications, gantry designs, and software modules rather than accepting monolithic platform bundles.
Wireless detector technology is modularizing traditional fixed-room installations, enabling retrofit of existing radiography suites without full construction disruption. Tier-two city hospitals are adopting detachable wireless panels at twice the pace of complete system replacement. This architecture is compressing capital deployment timelines and expanding vendor addressable market beyond greenfield construction cycles.
NMPA's tightened GB 9706.1-2020 electrical safety implementation timeline is forcing accelerated design validation cycles across domestic and imported equipment portfolios. Manufacturers must re-certify existing product lines or exit active tender participation. Portable system categories face the steepest compliance cost escalation due to battery subsystem complexity.
Bulk tender consolidation among provincial hospital networks is displacing single-facility purchasing autonomy with multi-year framework agreements covering dozens of institutions. Municipal health bureaus in Jiangsu and Guangdong are unbundling equipment supply from maintenance contracts, forcing vendors to compete on discrete service line pricing. This restructuring is most visible in Beijing municipal health system procurement, where total cost of ownership scoring now dominates capital allocation decisions.
China Digital X-Ray Market Segmentation
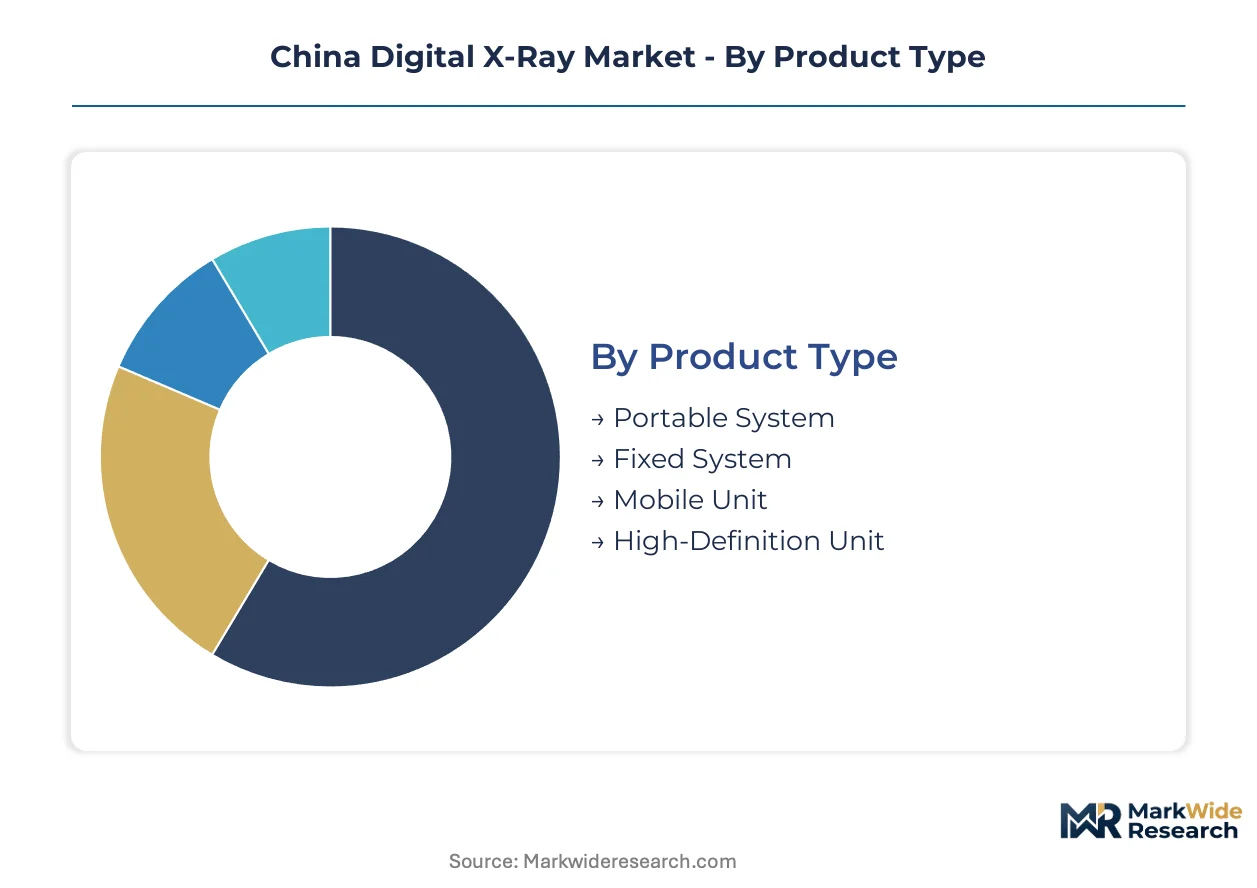
China's digital X-ray market fragments across four distinct dimensions that shape procurement priorities and vendor positioning. Product type and technology choices determine capital intensity and workflow integration, while end-user concentration and installation architecture dictate regional deployment patterns and service model requirements.
Product Type:
Hospital procurement committees differentiate capital allocation by throughput requirements and physical deployment constraints.
- Fixed System:Permanent room-based installations with ceiling-suspended or floor-mounted tube stands dominate tier-one municipal hospital radiology departments. Jiangsu provincial health networks prioritize these systems for trauma centers where patient volume justifies dedicated infrastructure investment.
- Portable System:Battery-powered wheeled units with wireless detector panels serve emergency departments and intensive care units requiring bedside imaging capability. County-level hospitals in Guangdong are expanding portable fleets to reduce patient transport risks and ICU turnaround times.
- Mobile Unit:Self-contained radiography vehicles with onboard power and climate control enable rural screening campaigns and temporary facility surge capacity. Township health centers deploy these for tuberculosis screening programs in remote northern provinces.
- High-Definition Unit:Sub-millimeter resolution systems with advanced scintillator layers target orthopedic and mammography applications requiring fine structural visualization.
Fixed systems lead volumes today; portable systems are gaining share fastest.
End User:
Purchasing authority and reimbursement pathways create distinct buying behaviors across facility types.
- Hospitals:Three-tier hospital classification system (tertiary, secondary, primary) structures equipment specifications and tender participation eligibility. Tertiary hospitals in Beijing municipal systems command the largest single-facility procurement budgets.
- Diagnostic Centers:Independent imaging facilities operating outside hospital networks prioritize throughput-optimized systems with rapid patient turnaround. These operators favor DR technology over CR retrofits to maximize daily examination volumes.
- Research Labs:Academic medical centers and pharmaceutical trial sites require specialized high-resolution configurations with DICOM-compliant archival integration.
- Outpatient Facilities:Community health service centers with limited radiographer staffing demand simplified user interfaces and automated exposure protocols.
Hospitals absorb the dominant procurement share; diagnostic centers are expanding most quickly as referral networks fragment.
Technology:
Image acquisition methodology determines dose efficiency, workflow speed, and total cost of ownership calculations in municipal tender scoring.
- Direct Radiography:Flat-panel detectors with immediate digital readout eliminate chemical processing and cassette handling. NMPA registration timelines favor domestic DR manufacturers with established GB 9706 compliance documentation.
- Computed Radiography:Photostimulable phosphor plates requiring laser scanning digitization persist in budget-constrained county hospitals with existing CR infrastructure. MEE energy efficiency mandates are accelerating replacement cycles toward DR conversion.
- Analog:Film-screen radiography survives only in isolated township facilities with obsolete PACS infrastructure and limited capital access.
- Hybrid Systems:Configurable platforms supporting both CR plate digitization and DR flat-panel operation provide transitional flexibility for mixed-technology departments.
Direct Radiography commands new capital allocation; Computed Radiography retains installed base concentration.
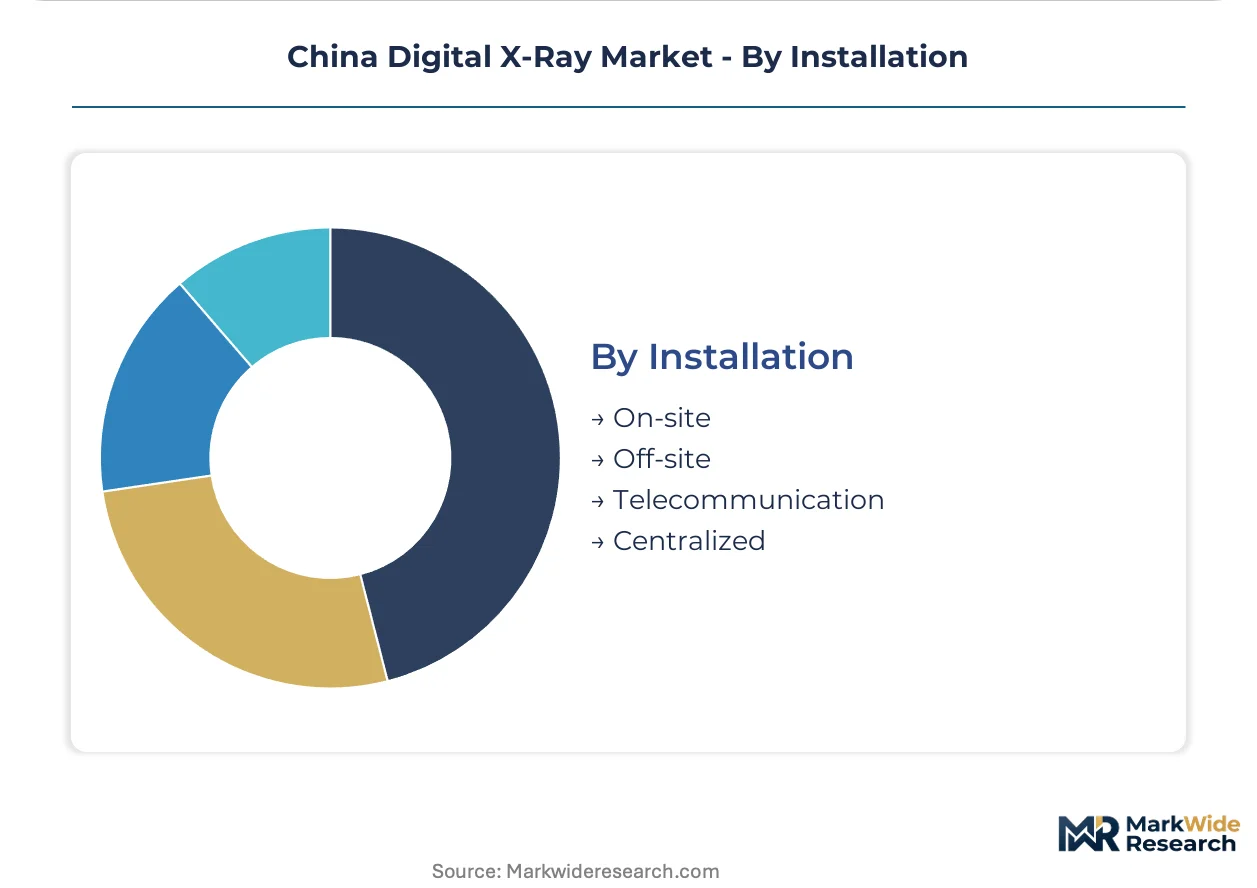
Installation:
Physical deployment architecture shapes construction timelines, regulatory compliance scope, and ongoing service contract structures.
- On-site:Conventional radiography room construction with lead shielding, HVAC integration, and fixed electrical supply represents the standard deployment model for hospital new-build projects.
- Off-site:Prefabricated modular radiography units manufactured off-premises and transported to final location compress construction disruption and permit parallel regulatory approval pathways.
- Telecommunication:Network-connected systems enabling remote radiologist interpretation and centralized quality assurance are expanding in county hospital consortiums with teleradiology partnerships.
- Centralized:Hub-and-spoke imaging networks with single high-throughput facility serving multiple satellite clinics concentrate specialized equipment and radiographer expertise.
On-site installation maintains volume dominance; telecommunication configurations are climbing the fastest as provincial networks consolidate interpretation services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's digital X-ray infrastructure development outpaces India's comparable medical imaging modernization by roughly five years in regulatory maturity and installed base density, though both markets now converge on similar portable system adoption curves.
Beijing-Tianjin-Hebei
Tertiary hospital consolidation and municipal health bureau bulk tenders concentrate procurement authority in this northern corridor. NMPA registration pathways for imported components extend approval timelines, favoring domestic manufacturers with established regulatory relationships. Beijing municipal health systems now mandate total cost of ownership scoring over upfront capital expenditure in framework agreements.
Yangtze River Delta
Jiangsu provincial health networks prioritize fixed DR installations for trauma centers where patient throughput justifies dedicated infrastructure. Dual carbon goals from MEE accelerate replacement cycles for legacy high-power systems in Shanghai municipal hospitals. Suzhou and Nanjing anchor detector component manufacturing clusters with captive flat-panel production capabilities.
Pearl River Delta
Guangdong county-level hospitals expand portable fleets to reduce ICU patient transport risks and emergency department turnaround times. GB 9706.1-2020 electrical safety implementation forces accelerated design validation for battery-powered mobile units. Shenzhen and Guangzhou dominate both equipment assembly and diagnostic center operator consolidation.
Sichuan-Chongqing
Western China healthcare infrastructure investment targets township health center upgrades with mobile screening vehicles for tuberculosis programs. Provincial hospital consortia consolidate interpretation services through teleradiology partnerships. Chengdu anchors the regional hub for PACS integration and radiographer training programs.
Shandong Peninsula
Secondary hospital digitization campaigns in Qingdao and Jinan concentrate Computed Radiography replacement with Direct Radiography systems. Local health commissions emphasize lower-dose protocols for pediatric and orthopedic applications. The region's industrial base supplies scintillator materials and gantry fabrication components to national OEM networks.
China Digital X-Ray Market Competitive Environment
Shanghai-based producers anchor one tier; Beijing-Tianjin specialists hold procurement relationships in northern provincial networks. Market structure tilts toward consolidation as municipal bulk tenders favor vendors with captive detector production and decade-long distributor coverage. Three archetypes dominate: integrated platform builders with in-house flat-panel manufacturing, regional equipment assemblers serving county hospital price points, and mobile system specialists targeting screening campaign logistics. Competitive dynamics center on regulatory pre-certification speed and service contract unbundling under provincial framework agreements.
Among Shanghai-based fabricators, Shanghai United Imaging Healthcare Co., Ltd., Shanghai Guangzheng Medical Equipment Co., Ltd., and Shanghai Handy Medical Equipment Co., Ltd. exemplify the integrated platform archetype with proximity to Yangtze River Delta component clusters. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. represents the diversified medical technology conglomerate model spanning multiple imaging modalities. Wandong Medical Equipment anchors northern provincial coverage through established distributor relationships in Beijing-Tianjin-Hebei health networks. Orich Medical Equipment (Tianjin) Co., Ltd. occupies a position within the regional specialist tier serving secondary hospital price sensitivity.
| Leading Market Players |
|---|
| Shanghai Guangzheng Medical Equipment Co., Ltd. |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Shanghai United Imaging Healthcare Co., Ltd. |
| Shanghai Handy Medical Equipment Co., Ltd. |
| Wandong Medical Equipment |
| Orich Medical Equipment (Tianjin) Co., Ltd. |
| Shanghai Jieying Medical Technology Co., Ltd. |
| Shanghai IRAY Technology Co., Ltd. |
| Shanghai Rixi Medical Equipment Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between NMPA-registered domestic systems and import-dependent configurations shapes both procurement premiums and component sourcing strategies across China's digital X-ray sector. Municipal health bureaus in Jiangsu and Guangdong apply total cost of ownership scoring that rewards captive flat-panel detector production while penalizing extended regulatory approval timelines for foreign-sourced subsystems.
Pricing Analysis
Capacity additions in Suzhou and Nanjing detector manufacturing clusters are reshaping price floors for mid-tier DR systems serving county-level hospitals. Three-tier pricing structure across premium, standard, and economy levels reflects NMPA registration tier, GB 9706 electrical safety pre-certification status, and after-sales service bundling. Cost compression in standard-tier portable units is intensifying because municipal bulk tenders unbundle equipment from maintenance contracts. County hospital procurement committees exhibit highest price sensitivity; tertiary trauma centers in Beijing municipal systems demonstrate lowest.
Supply Chain Analysis
Freight cost escalation from rare-earth processing jurisdictions is elevating landed costs for cesium iodide and gadolinium oxysulfide scintillator materials. Manufacturing concentration centers on China, South Korea, and Japan for flat-panel detector substrates and readout electronics. Component sourcing draws from Jiangsu rare-earth refineries, Taiwan semiconductor foundries, and German precision motor suppliers. Single-source vulnerability in scintillator layer deposition equipment creates procurement bottlenecks. Distribution runs through provincial hospital consortia framework agreements with authorized distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's digital X-ray market compounds steadily through county-level facility upgrade mandates that institutionalize replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Acquire wireless detector engineering teams to defend against modular retrofit threats from portable system specialists. Deepen backward integration into scintillator material processing to offset rare-earth price volatility. Secure NMPA pre-certification documentation libraries ahead of GB 9706.1-2020 enforcement deadlines. For New Entrants and Emerging Players: Capture mobile unit penetration white space in northern provincial health networks where Wandong Medical Equipment's distributor coverage remains dominant. Target township health centers in Sichuan-Chongqing tuberculosis screening programs with self-contained radiography vehicle offerings. Pursue teleradiology partnership routes to bypass direct hospital procurement committee barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated platform builders possessing captive flat-panel detector production and established municipal health bureau relationships. Five-to-ten-year viability hinges on regulatory pre-certification speed rather than pure manufacturing scale. Monitor provincial bulk tender unbundling trends as inflection signal for service contract margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Registration Fast-Track Investment | Accelerated market access timelines compress competitive windows for import-dependent rivals. |
| Wireless Detector Platform Development | Modular retrofit architecture expands addressable market beyond greenfield construction cycles. |
| Provincial Distributor Network Acquisition | Coverage in Jiangsu, Guangdong, and Beijing municipal systems secures framework agreement participation. |
| AI-Integrated Diagnostic Software Companion | Automated image analysis capabilities create premium pricing tiers in tertiary hospital segments. |
| Scintillator Material Backward Integration | Captive rare-earth processing reduces supply chain exposure to mining jurisdiction volatility. |
Study Parameters
Multiple input streams — hospital procurement database analysis, NMPA registration filing review, and municipal health bureau tender documentation — were reconciled to construct market size estimates. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and flat-panel detector manufacturing executives informed demand segmentation. Secondary validation drew from customs trade records, GB standards documentation, and provincial health infrastructure investment disclosures. Bottom-up equipment shipment analysis and top-down healthcare capital expenditure triangulation cross-checked volume assumptions.
Data-stream reconciliation across product type, technology generation, end-user tier, and installation architecture dimensions anchored projection modeling. CAGRs were derived from equipment replacement cycle analysis, municipal budget trajectory assessment, and regulatory mandate implementation schedules. NMPA approval timeline distributions, MEE energy efficiency compliance deadlines, and county hospital digitization campaign pacing served as industry-specific forecast inputs throughout the modeling period.
Regulatory enforcement delays, rare-earth supply disruptions, and provincial procurement consolidation reversals are the dominant revision risks to baseline assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Small Animal Imaging (in-Vivo) Market
Medical Imaging
India Mammography Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
US Diagnostic Imaging Services Market
Medical Imaging
India Digital Radiology Market
Medical Imaging
Medical Imaging Management Market
Medical Imaging
Nuclear Medicine Software Market
Medical Imaging
Medical X-Ray Films Market
Medical Imaging
Australia Computed Tomography Market
Medical Imaging
Fluorescence Microscopy Market
Medical Imaging
Mexico Digital Radiology Market
Medical Imaging
MRI Ferromagnetic Detection Systems Market
Medical Imaging
Spain Magnetic Resonance Imaging Market
Medical Imaging
Global Automated Breast Ultrasound System (ABUS) Market
Medical Imaging
North America Medical Imaging Software Market
Medical Imaging
Mobile Vascular Imaging Market