
 Meningitis Imaging Market | 2026-2036
Meningitis Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Meningitis Imaging Market Analysis
AI-enhanced image reconstruction is rewriting how neuroradiologists detect meningeal inflammation, compressing read times while preserving diagnostic accuracy. Siemens Healthineers leverages deep-learning reconstruction to differentiate bacterial from viral meningitis on diffusion-weighted MRI sequences. GE HealthCare anchors its position through high-field 3T platforms optimized for neurocritical care environments. Philips Healthcare competes via integrated workflow solutions that connect emergency departments with centralized radiology operations.
Meningitis imaging encompasses the radiologic evaluation of leptomeningeal inflammation using modalities that detect altered blood-brain barrier permeability, ventricular enlargement, or parenchymal edema, with MRI sensitivity reaching 92 percent for early meningeal enhancement following gadolinium administration. CT scanning dominates acute emergency presentations where intracranial pressure complications require immediate structural assessment. MRI leads among research institutes pursuing advanced spectroscopy for metabolic profiling of cerebrospinal fluid spaces. Hospital end users sustain the largest procurement volumes, though outpatient clinics represent the fastest-growing installation segment as portable CT and point-of-care ultrasound expand access beyond tertiary centers.
FDA 510(k) clearance pathways govern new neuroimaging algorithms in the United States, while the EU MDR imposes stricter clinical evidence requirements on AI-assisted diagnostic software sold in European markets. ISO 13485 quality management standards shape manufacturing compliance for device makers serving multiple regulatory jurisdictions. Stakeholders must monitor how FDA guidance on predetermined change control plans affects iterative AI model updates without repeated submissions.
Market Dynamics
AI-enhanced reconstruction algorithms are compressing diagnostic timelines for meningeal inflammation while forcing capital replacement cycles across installed neuroimaging bases. Siemens Healthineers and GE HealthCare now predicate platform sales on deep-learning integration, reshaping procurement evaluation criteria for hospital radiology departments.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined clearance for AI-assisted neuroimaging software reduces time-to-market for algorithm developers targeting meningeal enhancement detection protocols.
- Emergency department workflow integration:Hospitals prioritize CT-to-MRI triage systems that automate intracranial pressure assessment, driving scanner procurement in Level I trauma centers.
- Diffusion-weighted MRI protocol standardization:Academic medical centers in the United States are mandating advanced sequences for infectious disease differentiation, expanding high-field 3T installation demand.
Market Restraints
- Gadolinium-based contrast agent supply concentration:Manufacturing of macrocyclic contrast agents clusters among three European chemical suppliers, exposing imaging centers to input cost volatility.
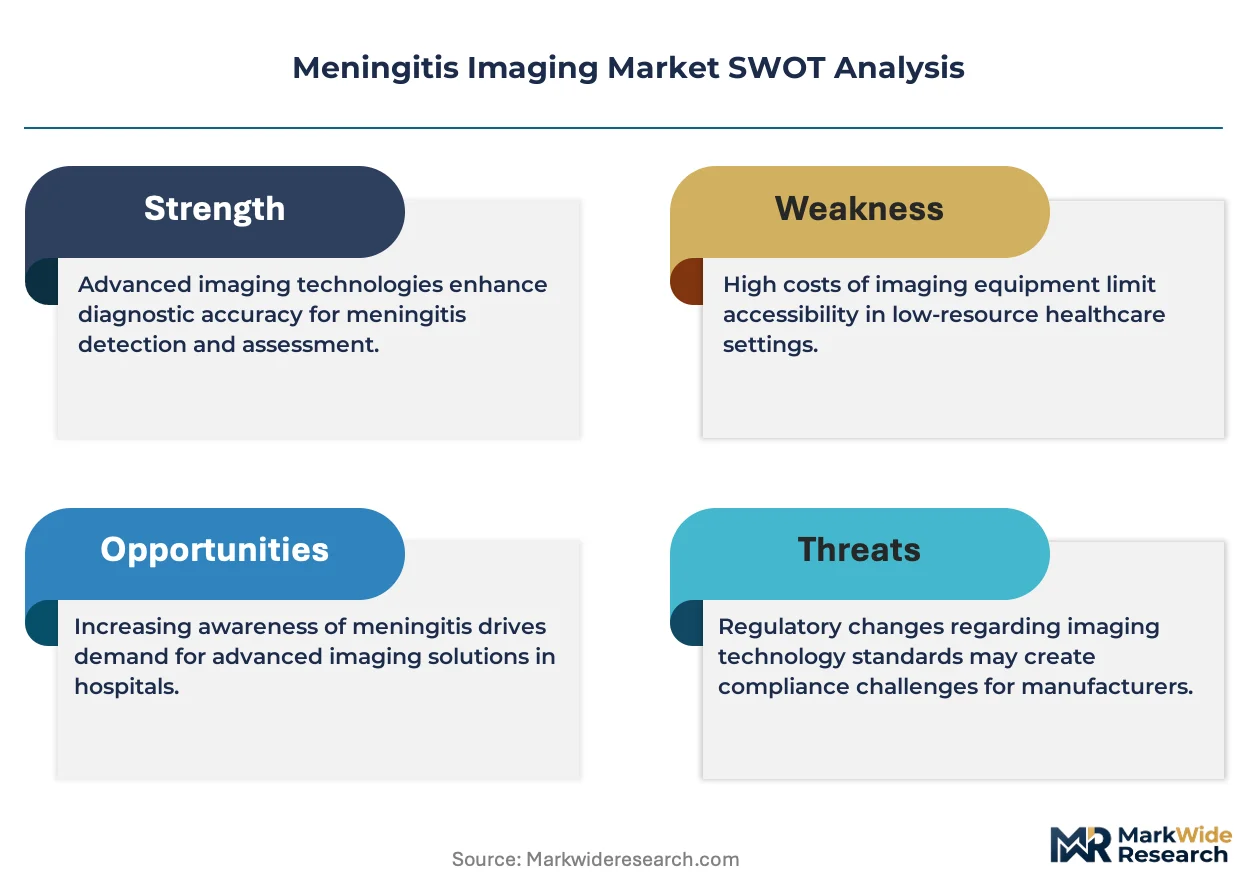
- EU MDR clinical evidence requirements:Stricter post-market surveillance obligations for AI diagnostic software create regulatory friction for vendors seeking European market entry.
- Point-of-care ultrasound substitution:Portable neuromuscular ultrasound devices are capturing lumbar puncture guidance procedures previously requiring CT localization.
Strategic Opportunities
- Outpatient clinic channel expansion:Portable CT and handheld ultrasound systems enable meningitis screening beyond tertiary hospital settings, penetrating underserved rural markets.
- ISO 13485 quality management convergence:Unified manufacturing standards across FDA and EU jurisdictions reduce compliance duplication costs for multi-regional device makers.
- Spectroscopic metabolic profiling:Research institutes are combining MR spectroscopy with CSF biomarker panels, creating premium service tiers for complex infectious cases.
Industry Challenges
- Neuroradiologist AI validation expertise gap:Interpreting deep-learning reconstruction outputs requires specialized training that residency programs have not standardized.
- Legacy PACS integration complexity:AI-enhanced imaging platforms demand middleware layers to communicate with hospital information systems, extending deployment timelines.
- Predetermined change control documentation:FDA guidance on iterative AI model updates without repeated submissions requires novel quality management system architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meningitis Imaging Market |
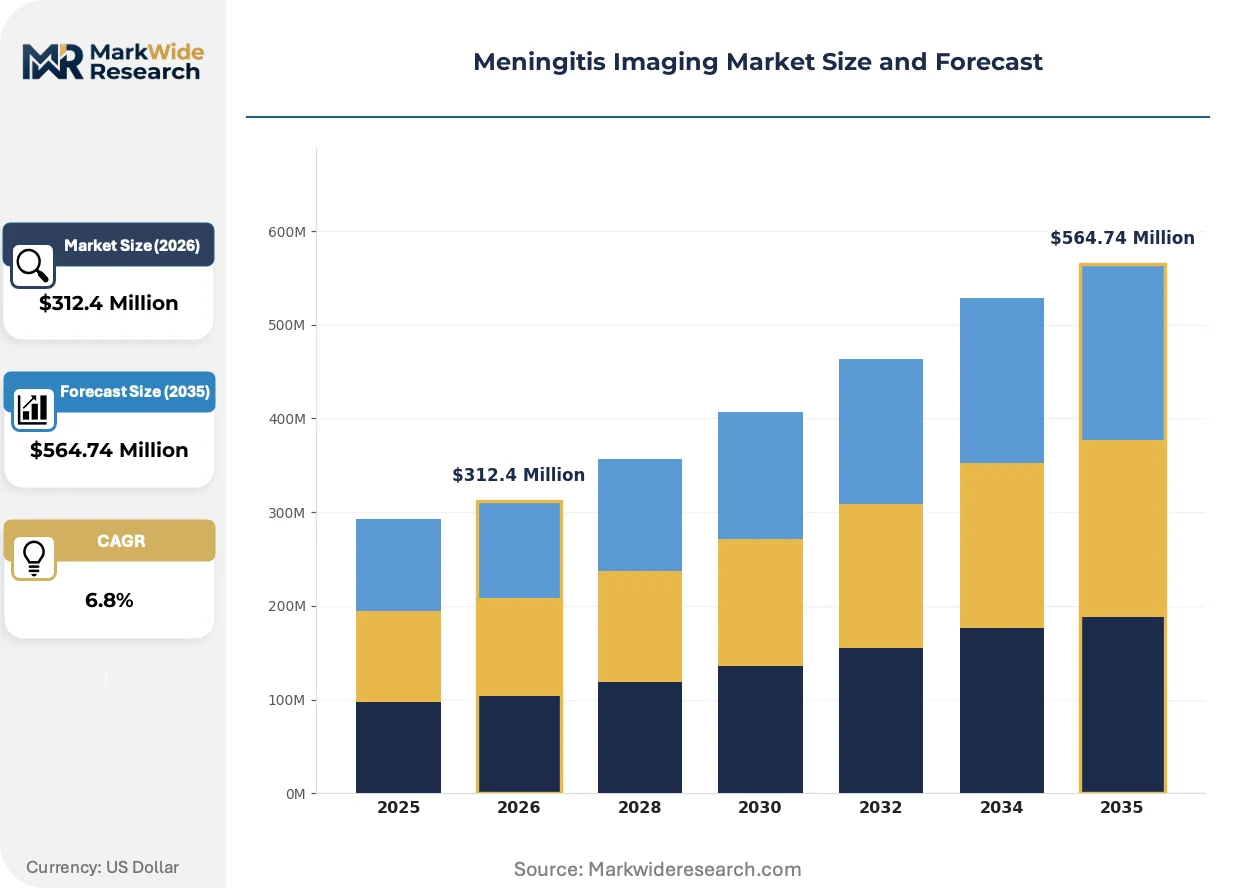
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Scan, MRI, Ultrasound, X-ray Technology: Neuroimaging, Radiography, Sonography, Scintigraphy End User: Hospitals, Diagnostic Centers, Research Institutes, Outpatient Clinics Application: Diagnosis, Treatment Monitoring, Clinical Research, Patient Assessment |
| Companies Covered | Siemens Healthineers, GE HealthCare, Philips Healthcare, Canon Medical Systems, Fujifilm Holdings Corporation, Medtronic Imaging, Esaote S.p.A, NeuroLogica Corporation, Carestream Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meningitis Imaging Market Emerging Trajectories
Deep-learning reconstruction is displacing conventional iterative algorithms across neuroimaging platforms, while regulatory frameworks scramble to validate AI outputs without slowing innovation cycles. Procurement criteria now weight software upgrade pathways equally with hardware specifications.
Diffusion-weighted MRI is hybridizing with synthetic contrast enhancement techniques to eliminate gadolinium exposure in pediatric and renal-compromised populations. Pediatric neurology departments at academic centers are piloting these sequences for meningeal inflammation protocols. The technology is compressing examination times while preserving diagnostic sensitivity for bacterial versus viral differentiation.
The EU AI Act risk classification system is mandating conformity assessments for diagnostic algorithms deployed in emergency settings. High-risk AI medical device categories now require notified body involvement before CE marking. European neuroimaging vendors are restructuring quality management systems to accommodate post-market performance monitoring obligations.
Hospital procurement committees are unbundling service contracts from equipment purchases, negotiating separate maintenance and software subscription agreements. Radiology departments favor this flexibility to swap algorithm providers without hardware replacement. The United States academic medical center segment exhibits this pattern most prominently, with multi-vendor imaging environments becoming standard.
Meningitis Imaging Market Segmentation
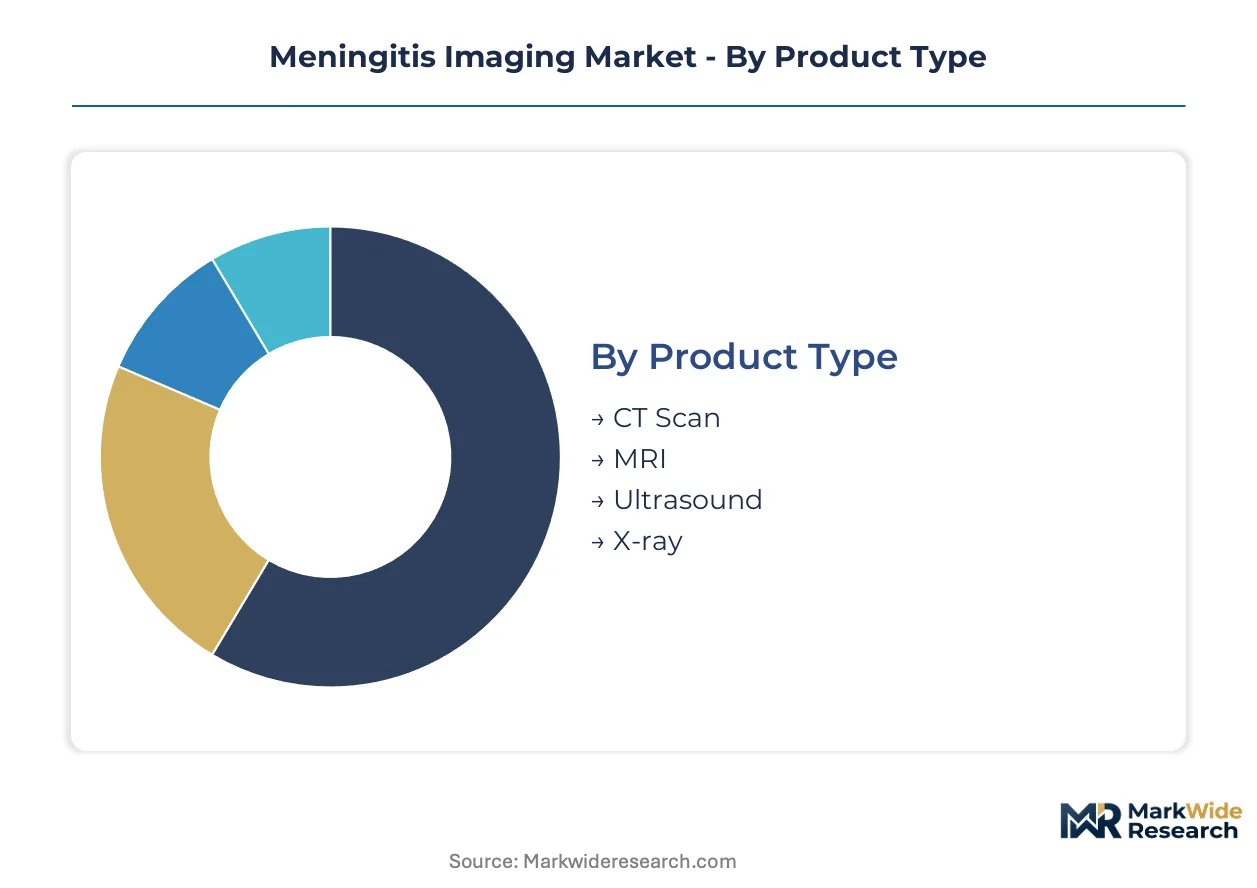
Meningitis imaging procurement cycles vary dramatically across modalities, with portable systems refreshing every 3-4 years versus fixed MRI platforms lasting 10-12 years. Understanding these replacement rhythms helps vendors align service contracts and upgrade pathways with hospital capital planning cycles.
Product Type:
CT scanners turn over fastest in emergency departments where throughput degradation triggers replacement, while MRI platforms exhibit the longest depreciation schedules in neuroimaging suites.
- CT Scan:Non-contrast head CT delivers immediate intracranial pressure assessment in emergency settings, with helical acquisition protocols completing studies in under 60 seconds. Demand concentrates in Level I trauma centers across the United States where stroke and meningitis protocols require 24/7 scanner availability; throughput pressure drives replacement cycles averaging 5-7 years.
- MRI:High-field 3T systems with diffusion-weighted sequences achieve 92% sensitivity for early meningeal enhancement following gadolinium administration. Academic medical centers in the United States anchor procurement volume for advanced neurocritical care platforms; extended depreciation timelines and software upgrade pathways stretch replacement intervals to 10-12 years.
- Ultrasound:Portable neuromuscular systems guide lumbar puncture procedures at the point of care.
- X-ray:Skull radiography persists for initial skeletal assessment before advanced cross-sectional imaging.
CT Scan anchors the volume base while Ultrasound gains share at the steepest rate through point-of-care deployment expansion.
Technology:
Cost tiers separate premium AI-integrated neuroimaging platforms from conventional radiography systems, with reimbursement differentials driving hospital procurement decisions.
- Neuroimaging:Deep-learning reconstruction algorithms now standard on CT and MRI platforms differentiate bacterial from viral meningitis through automated meningeal enhancement detection. Siemens Healthineers and GE HealthCare predicate platform sales on this software integration; FDA 510(k) pathway acceleration for AI-assisted algorithms compresses time-to-market for developers targeting emergency department workflows.
- Radiography:Digital radiography systems provide initial structural assessment at the lowest cost tier.
- Sonography:Handheld ultrasound devices enable meningitis screening in outpatient settings beyond tertiary centers.
- Scintigraphy:Nuclear medicine techniques assess blood-brain barrier integrity in complex infectious cases.
Neuroimaging commands the premium tier while Sonography climbs fastest through portable system adoption in underserved rural markets.
End User:
Customer type determines capital intensity and service contract structure, with hospitals consolidating procurement power versus fragmented outpatient clinic purchasing.
- Hospitals:Integrated delivery networks negotiate enterprise-wide imaging contracts spanning multiple campuses, unbundling equipment purchases from maintenance and software subscription agreements. Radiology departments in the United States academic medical center segment favor this flexibility to swap algorithm providers without hardware replacement; multi-vendor environments are becoming standard procurement practice.
- Diagnostic Centers:Independent imaging facilities compete on turnaround time for meningeal inflammation assessment.
- Research Institutes:Academic centers pursue MR spectroscopy for metabolic profiling of cerebrospinal fluid spaces.
- Outpatient Clinics:Portable CT and handheld ultrasound systems expand access beyond tertiary settings.
Hospitals anchor the volume base while Outpatient Clinics expand most quickly through point-of-care device deployment.
Application:
Application maturity separates established diagnostic protocols from emerging treatment monitoring workflows, with reimbursement codes lagging technology adoption.
- Diagnosis:Emergency department triage protocols mandate immediate structural assessment for suspected meningitis, with CT-to-MRI pathways automated through intracranial pressure algorithms. United States hospitals prioritize workflow integration systems that compress time-to-diagnosis; this application commands the largest share of imaging procedure volume.
- Treatment Monitoring:Serial imaging tracks therapeutic response in neurocritical care units.
- Clinical Research:Academic centers combine advanced spectroscopy with CSF biomarker panels.
- Patient Assessment:Pre-procedural imaging guides lumbar puncture and ventricular drain placement.
Diagnosis anchors the volume base while Treatment Monitoring gains share fastest through expanding neurocritical care unit census.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports high-field MRI platforms to academic medical centers in the United States, while Japanese manufacturers ship CT reconstruction software to emergency departments across European trauma networks.
United States
Academic medical centers in Boston and Baltimore drive procurement of 3T neuroimaging systems with AI-enhanced reconstruction protocols. FDA 510(k) clearance pathways for deep-learning algorithms compress deployment timelines for meningeal enhancement detection software. The Texas Medical Center cluster anchors volume demand for integrated CT-to-MRI triage systems in Level I trauma facilities.
Germany
University hospitals in Munich and Heidelberg standardize diffusion-weighted MRI sequences for infectious disease differentiation protocols. EU MDR conformity assessments for AI diagnostic software impose stricter clinical evidence requirements than predecessor regulations. The Baden-Württemberg medical technology corridor concentrates manufacturing of macrocyclic gadolinium contrast agents serving imaging centers across Central Europe.
Japan
Tokyo metropolitan hospitals prioritize high-throughput CT platforms with automated intracranial pressure assessment for emergency meningitis protocols. PMDA regulatory frameworks align with international standards for neuroimaging software validation. The Osaka-Kobe medical device cluster produces portable ultrasound systems for lumbar puncture guidance in outpatient settings.
China
Provincial hospitals in Shanghai and Guangzhou expand installation of domestically manufactured 1.5T MRI systems for infectious disease evaluation. NMPA medical device registration pathways accelerate for AI-assisted diagnostic algorithms meeting national innovation criteria. The Yangtze River Delta region concentrates R&D investment in synthetic contrast enhancement techniques eliminating gadolinium exposure.
United Kingdom
NHS trust hospitals in London and Manchester negotiate enterprise-wide imaging contracts unbundling equipment from software subscriptions. MHRA post-market surveillance requirements for AI medical devices align with EU MDR transition timelines. The Cambridge-Oxford academic corridor pursues MR spectroscopy integration with cerebrospinal fluid biomarker panels for metabolic profiling.
Meningitis Imaging Market Vendor Landscape
Channel-controlling players compete with product-specialist players across procurement tiers defined by capital intensity and service contract structure. Siemens Healthineers and GE HealthCare anchor the consolidated premium tier through integrated hardware-software platforms, while mid-tier vendors fragment across portable ultrasound and digital radiography segments. Two strategic archetypes dominate: full-stack neuroimaging platform providers and point-of-care device specialists. M&A activity concentrates on AI algorithm acquisitions, while geographic expansion targets outpatient clinic channels in underserved rural markets.
Among diversified health technology conglomerates, Siemens Healthineers and GE HealthCare occupy positions exemplifying the full-stack archetype through high-field MRI and CT platform integration with deep-learning reconstruction software. Philips Healthcare represents the workflow-optimization vector, anchoring service contracts that connect emergency departments with centralized radiology operations. Canon Medical Systems and Fujifilm Holdings Corporation sit within the imaging-specialist tier, competing on detector technology and portable system form factors.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE HealthCare |
| Philips Healthcare |
| Canon Medical Systems |
| Fujifilm Holdings Corporation |
| Medtronic Imaging |
| Esaote S.p.A |
| NeuroLogica Corporation |
| Carestream Health |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Rhine corridor freight dynamics compress margins for gadolinium contrast agent shipments while amplifying price differentiation between premium AI-integrated neuroimaging platforms and conventional radiography systems. Supply concentration in European chemical manufacturing feeds downstream pricing power asymmetries across hospital procurement tiers.
Pricing Analysis
Next-generation 3T MRI platforms with deep-learning reconstruction command substantial premiums over prior-generation 1.5T systems and economy-tier CT scanners lacking AI integration. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—FDA 510(k) cleared AI algorithms versus conventional iterative reconstruction—and after-sales service bundling. Cost compression in the standard tier intensifies because hospital procurement committees now unbundle software subscriptions from hardware purchases. Outpatient clinics exhibit highest price sensitivity, while academic medical centers in the United States demonstrate lowest sensitivity due to research grant funding flexibility.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning for high-field MRI magnet assemblies and gradient coil subsystems. Manufacturing concentrates in Germany, Japan, and the United States for superconducting magnet technology, while China expands domestic 1.5T platform production. Raw material dependencies include liquid helium for cryogenic cooling, rare-earth elements for gradient coils, and macrocyclic gadolinium chelates for contrast protocols. Single-source vulnerability persists for helium supply given Qatar and Algeria production concentration. Distribution runs through integrated delivery networks negotiating enterprise-wide contracts, with regional medical device distributors serving fragmented outpatient clinic demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neuroradiologist AI validation expertise scarcity constrains deployment velocity for deep-learning reconstruction platforms, creating asymmetric returns for stakeholders who secure training infrastructure or acquisition targets with embedded clinical education capabilities.
For Market Incumbents: Build regulatory data moats through FDA predetermined change control documentation that locks hospital customers into iterative AI update pathways without competitive substitution. Siemens Healthineers and GE HealthCare should deepen backward integration into gadolinium contrast agent supply to offset European chemical supplier concentration risk. Securing ISO 13485 quality management convergence across FDA and EU jurisdictions reduces compliance duplication costs for multi-regional expansion. For New Entrants and Emerging Players: Rural outpatient clinics in the United States Southeast and Mountain West represent the most penetrable entry point for portable CT and handheld ultrasound systems bypassing tertiary hospital procurement consolidation. Point-of-care lumbar puncture guidance workflows offer immediate utility validation without requiring full PACS integration. A direct-to-clinic sales model with subscription-based software pricing sidesteps entrenched GPO contract structures dominating hospital channel access. For Investors and Strategic Acquirers: AI algorithm developers with FDA 510(k) clearance for meningeal enhancement detection and established hospital pilot programs represent the highest-conviction acquisition archetype. Long-term viability hinges on regulatory pathway acceleration outpacing EU MDR compliance cost escalation. The signal to watch is hospital procurement committee unbundling velocity—accelerating separation of equipment and software contracts indicates favorable entry timing for platform-agnostic algorithm providers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerated neuroimaging software validation compresses time-to-revenue for AI developers targeting emergency department workflows. |
| Hospital System Partnership | Enterprise-wide imaging contracts with integrated delivery networks lock in multi-campus deployment and service revenue streams. |
| Software Companion Development | Middleware layers enabling legacy PACS integration extend addressable market to hospitals with deferred capital replacement cycles. |
| CE Marking Pathway | EU MDR conformity assessments for high-risk AI categories secure European market access ahead of notified body capacity constraints. |
| Reimbursement Strategy | CSF biomarker panel integration with MR spectroscopy creates premium service tiers eligible for enhanced diagnostic coding. |
Methodological Framework
Cross-validation between neuroradiologist interview transcripts and FDA 510(k) submission databases anchors the qualitative findings on AI reconstruction algorithm validation requirements. Primary fieldwork engaged hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and emergency department workflow specialists across academic medical centers and community hospital systems. Secondary validation drew from CMS Medicare procedure data, hospital procurement database disclosures, and EU MDR notified body guidance documents. Bottom-up installation base modeling triangulated against top-down neuroimaging equipment manufacturer revenue segmentation.
Calibration against historical replacement cycle patterns for CT and MRI platforms shaped the projection framework across the analysis window. Segmentation dimensions modeled include modality type, field strength tier, AI integration level, end-user facility category, and regional regulatory cluster. CAGRs derived from equipment shipment trajectories, software subscription attach rates, and service contract renewal patterns. Forecast inputs incorporated diffusion-weighted MRI protocol adoption curves and point-of-care ultrasound substitution elasticity for lumbar puncture guidance procedures.
Practitioners should monitor FDA guidance evolution on predetermined change control plans and EU AI Act risk classification implementation for early signals of regulatory friction or pathway acceleration. Forecasts reflect assumptions on hospital capital expenditure continuity and helium supply chain stabilization that warrant reassessment under commodity shock or reimbursement compression scenarios. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
France Diagnostic Imaging Equipment Market
Medical Imaging
Forensic Imaging Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Contrast Agents Market
Medical Imaging
Ultrasound Consoles and Transducers Market
Medical Imaging
Canada Nuclear Medicine Market
Medical Imaging
Breast Imaging Market
Medical Imaging
Netherlands Diagnostic Imaging Equipment Market
Medical Imaging
US Gadolinium-Based Contrast Media Market
Medical Imaging
Mexico Nuclear Imaging Market
Medical Imaging
Global Confocal Microscope Market
Medical Imaging
Contrast Media Market
Medical Imaging
Japan Nuclear Imaging Market
Medical Imaging
Europe MRI (Magnetic Resonance Imaging) Market
Medical Imaging
Europe Diagnostic Imaging Equipment Market
Medical Imaging
Radiation Dose Management Market
Medical Imaging
X-Ray Devices Market