
 Oral Cancer Diagnostics Market | 2026-2036
Oral Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Cancer Diagnostics Market Outlook
The Oral Cancer Diagnostics Market is restructuring around a widening gap between premium molecular testing platforms and commodity imaging services. Siemens Healthineers anchors the premium tier through integrated PET-CT systems with AI-enhanced lesion detection. Thermo Fisher Scientific leverages its PCR and NGS portfolio to dominate laboratory-based molecular workflows. QIAGEN competes in sample preparation automation, sustaining margins through consumable recurring revenue.
Oral cancer diagnostics encompasses the detection, characterization, and monitoring of malignant lesions in the oral cavity through histopathological examination, molecular biomarker analysis, and advanced imaging modalities, with sensitivity thresholds for salivary biomarker assays typically targeting detection limits below one nanogram per milliliter. The primary purpose is enabling early-stage intervention before metastasis, thereby improving five-year survival outcomes and reducing treatment complexity. Imaging and biopsy together occupy the largest revenue share, reflecting established reimbursement and clinical familiarity, while molecular testing and salivary diagnostics represent the fastest-expanding margin pools as liquid biopsy technologies mature. Point-of-care delivery modes are gaining traction in resource-limited settings, though in-laboratory processing retains higher average selling prices due to pathologist oversight requirements.
FDA premarket approval pathways shape product development timelines and commercialization strategies for novel diagnostic assays in the United States, while the EMA's In Vitro Diagnostic Regulation enforces stricter clinical evidence standards across European markets. India's CDSCO and the country's PLI scheme for medical devices are accelerating domestic manufacturing capacity for affordable screening tools. Stakeholders must monitor evolving reimbursement codes for salivary diagnostics and prepare for interoperability demands from integrated electronic health record systems.
Market Dynamics
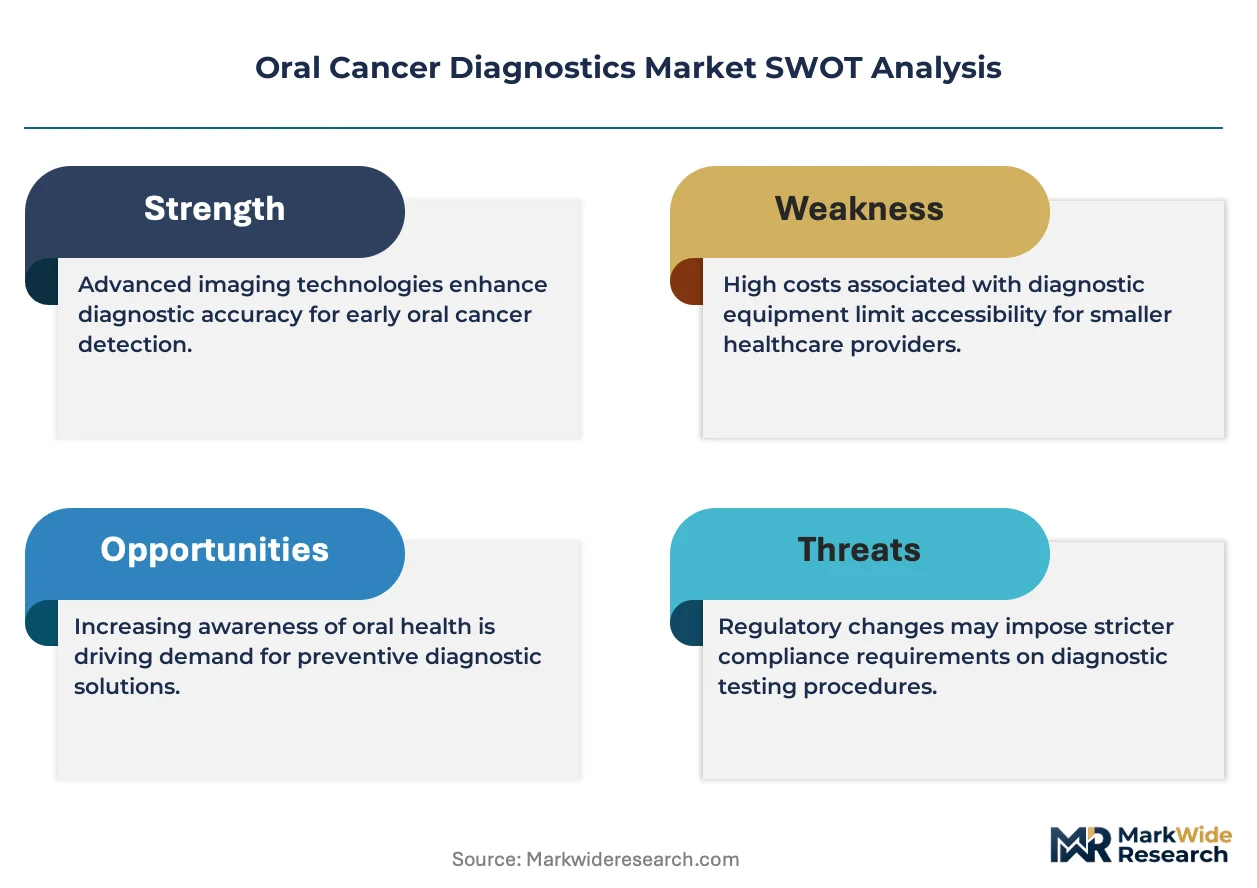
Hospital-based screening programs are compressing diagnostic workflows toward non-invasive salivary assays, forcing incumbent imaging providers to defend reimbursement positions against liquid biopsy platforms that promise earlier detection with lower per-test costs.
Growth Catalysts
- FDA Liquid Biopsy Pathways:Accelerated premarket review timelines for salivary biomarker assays are compressing commercialization cycles for molecular diagnostic developers in the United States.
- India PLI Scheme:Domestic manufacturing incentives under CDSCO oversight are expanding affordable screening device production for tobacco-burdened patient populations.
- AI-Enhanced Lesion Detection:Machine learning integration into PET-CT systems is improving sensitivity thresholds and reducing false-positive rates in hospital radiology departments.
Market Restraints
- Pathologist Oversight Requirements:Regulatory mandates for laboratory-based diagnostic review maintain high fixed costs and limit point-of-care test penetration in resource-constrained settings.
- Consumable Supply Concentration:Sample preparation automation depends on proprietary reagent kits from concentrated suppliers, creating margin pressure for independent laboratories.
- Reimbursement Code Gaps:Salivary diagnostics lack established CPT coding in multiple markets, forcing providers to absorb upfront costs or delay adoption.
Strategic Opportunities
- Rural India Penetration:Mobile screening units paired with telepathology networks address diagnostic infrastructure gaps in high-prevalence districts outside tier-one cities.
- EMA MDR Harmonization:Stricter clinical evidence standards are creating first-mover advantages for assay developers with robust prospective trial data.
- PCR-NGS Convergence:Integrated platforms combining rapid amplification with sequencing depth are opening multiplexed biomarker panels for monitoring applications.
Industry Challenges
- Interoperability Demands:Electronic health record integration requires HL7-FHIR compliance investments that strain mid-cap diagnostic developers.
- Biomarker Validation Timelines:Prospective clinical studies for novel salivary markers demand multi-year follow-up periods before regulatory submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Cancer Diagnostics Market |
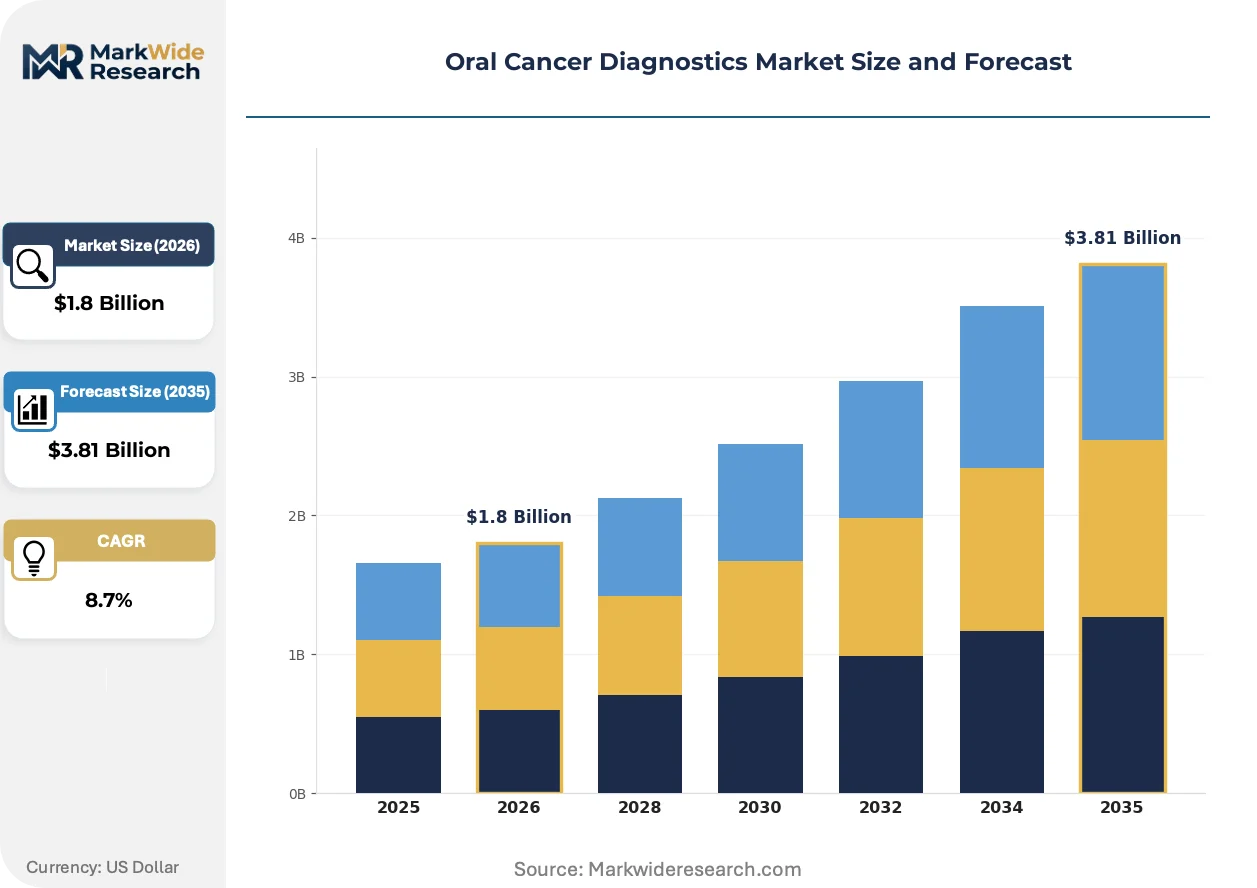
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsy, Imaging, Molecular Testing, Salivary Diagnostics Technology: Histopathology, Immunohistochemistry, PCR, Next-Generation Sequencing End User: Hospitals, Diagnostic Laboratories, Academic Institutions, Research Centers Delivery Mode: In-Laboratory, Point-of-Care, Home Testing, Telehealth |
| Companies Covered | Siemens Healthineers AG, Koninklijke Philips N.V., Thermo Fisher Scientific Inc., PerkinElmer Inc, Bio-Rad Laboratories Inc, F. Hoffmann-La Roche Ltd, Danaher Corporation, Illumina Inc, QIAGEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Cancer Diagnostics Market Strategic Shifts
Diagnostic modality boundaries are dissolving as molecular platforms absorb imaging functions and point-of-care devices encroach on laboratory territory, compressing traditional segment definitions.
Multiplexed salivary biomarker panels are unifying detection, characterization, and monitoring functions into single-sample workflows. Community health centers in high-burden districts are piloting these platforms for same-day risk stratification. This convergence is collapsing the historical separation between screening and diagnostic testing tiers.
EMA's In Vitro Diagnostic Regulation is enforcing stricter clinical evidence standards across European markets. Manufacturers must now submit prospective performance data rather than retrospective analytical validations. Assay developers with existing FDA clearances face parallel EMA submission costs that favor larger portfolio holders.
Hospital procurement committees are consolidating vendor relationships around integrated platform contracts that bundle imaging, molecular testing, and informatics. Independent reference laboratories are losing share to health system captive laboratories with captive patient volumes. This concentration is most pronounced in United States integrated delivery networks with centralized capital allocation authority.
Oral Cancer Diagnostics Market Segmentation
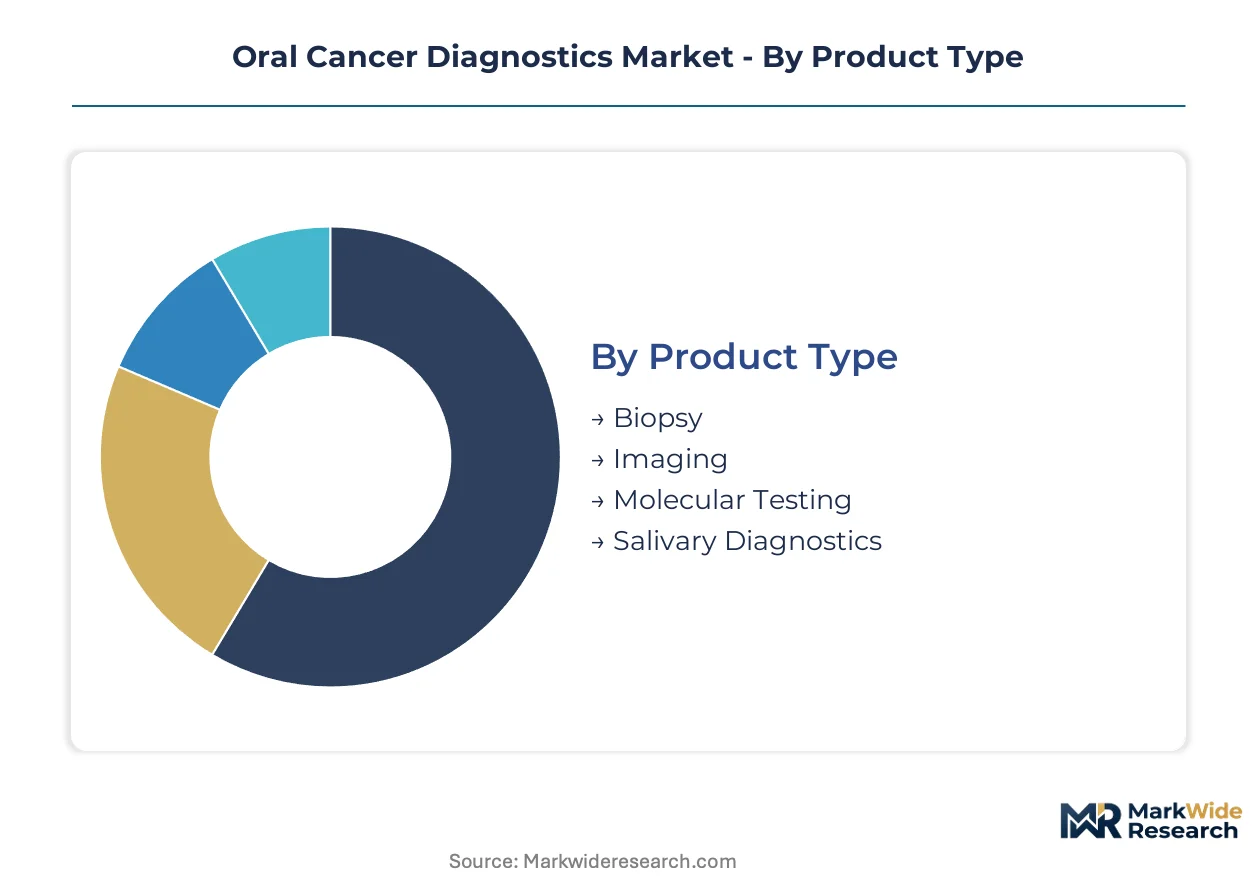
Oral cancer diagnostics segments by product type, technology, end user, and delivery mode reflect divergent capital requirements and reimbursement pathways. Understanding these divisions clarifies where margin pools concentrate and which modalities face commoditization pressure.
Product Type:
Capital intensity varies sharply across modalities, with imaging systems demanding seven-figure equipment investments while salivary assays require minimal fixed infrastructure.
- Biopsy:Tissue extraction followed by histopathological examination remains the diagnostic gold standard. Hospital pathology departments in the United States absorb the majority of procedural volume, constrained by pathologist availability and frozen section turnaround requirements.
- Imaging:PET-CT and MRI systems with AI-enhanced lesion detection command premium pricing through integrated hardware-software contracts. Siemens Healthineers anchors this segment through bundled service agreements with integrated delivery networks.
- Molecular Testing:PCR and NGS platforms for biomarker profiling.
- Salivary Diagnostics:Non-invasive liquid biopsy assays for early detection.
Imaging absorbs the bulk of installed capacity; salivary diagnostics is expanding most quickly.
Technology:
Technology selection tracks the maturity of biomarker validation and regulatory clearance pathways, with established methods defending reimbursement against novel molecular platforms.
- Histopathology:Microscopic tissue examination using hematoxylin and eosin staining constitutes the foundational diagnostic layer. Academic medical centers in India maintain high throughput for tobacco-related squamous cell carcinoma cases, though automation penetration lags Western benchmarks.
- Immunohistochemistry:Antibody-based protein detection enables subtype classification and treatment stratification. Diagnostic laboratories in Germany leverage this technology for HPV-driven oropharyngeal carcinoma differentiation under EMA oversight.
- PCR:Amplification-based detection of oncogenic mutations and viral DNA.
- Next-Generation Sequencing:Comprehensive genomic profiling for precision oncology applications.
Histopathology retains the deepest installed base; next-generation sequencing demonstrates the steepest expansion trajectory.
End User:
End-user segmentation reveals a tug-of-war between centralized hospital laboratories capturing referral volume and independent diagnostic laboratories competing on turnaround time.
- Hospitals:Integrated cancer centers with captive pathology and molecular capabilities. These institutions in the United States consolidate procurement through centralized capital committees, favoring multi-year platform contracts.
- Diagnostic Laboratories:Independent reference laboratories and regional chains. CDSCO-registered facilities in India are expanding capacity under PLI scheme incentives to serve tobacco-burdened districts.
- Academic Institutions:Research-focused centers driving biomarker discovery and clinical trial enrollment.
- Research Centers:Dedicated oncology research facilities advancing assay development.
Hospitals command the largest revenue share; diagnostic laboratories are gaining share fastest through specialization.
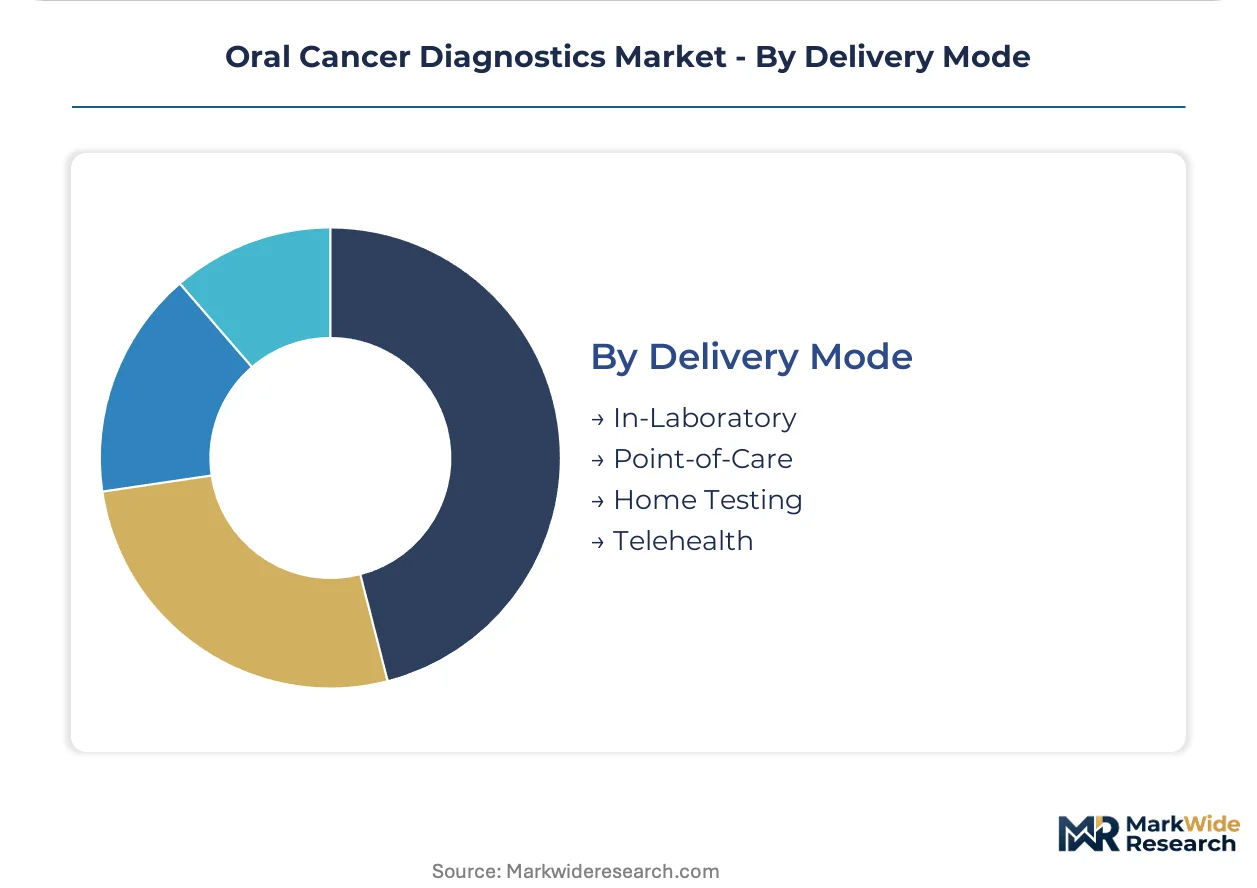
Delivery Mode:
Delivery mode fragmentation reflects tension between laboratory quality assurance requirements and patient convenience demands in screening applications.
- In-Laboratory:Centralized processing with pathologist oversight and established reimbursement codes. This mode sustains higher average selling prices in the United States through CPT-coded technical and professional components.
- Point-of-Care:Rapid testing at community health centers and mobile screening units. Rural India deployments pair these devices with telepathology networks to address infrastructure gaps outside tier-one cities.
- Home Testing:Self-collected saliva samples for risk stratification.
- Telehealth:Remote consultation integrated with digital pathology review.
In-Laboratory processing dominates revenue concentration; point-of-care is climbing the fastest through government screening program adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's medical technology corridor anchors North American diagnostic innovation, with academic medical centers driving biomarker validation and FDA premarket submission pipelines for liquid biopsy platforms.
United States
Hospital-based screening programs in the United States compress diagnostic workflows toward non-invasive salivary assays. FDA accelerated premarket review timelines compress commercialization cycles for molecular diagnostic developers. Integrated delivery networks in the Northeast and California consolidate procurement through centralized capital committees favoring multi-year platform contracts.
Germany
Diagnostic laboratories in Germany leverage immunohistochemistry for HPV-driven oropharyngeal carcinoma differentiation. EMA's In Vitro Diagnostic Regulation enforces stricter clinical evidence standards requiring prospective performance data. The Rhine-Ruhr metropolitan region maintains high-throughput pathology infrastructure serving cross-border referral volumes from neighboring European markets.
India
Tobacco-related oral cancer prevalence in India drives diagnostic infrastructure investment across high-burden districts. CDSCO oversight combined with PLI scheme incentives expands affordable screening device production. Mobile screening units paired with telepathology networks address diagnostic gaps outside tier-one cities in Maharashtra and Gujarat.
United Kingdom
NHS England procurement frameworks favor integrated platform contracts bundling imaging and molecular testing capabilities. MHRA post-Brexit regulatory autonomy creates parallel submission requirements for assay developers. London's academic medical centers drive biomarker discovery through prospective clinical trial enrollment.
Japan
PMDA regulatory pathways for companion diagnostics align with global FDA standards, accelerating technology transfer timelines. METI industrial policy supports domestic manufacturing of precision oncology platforms. The Kanto region surrounding Tokyo concentrates hospital-based cancer centers with captive pathology and molecular capabilities.
Oral Cancer Diagnostics Market Competitive Environment
Capital-heavy producers compete with asset-light designers across diagnostic modality boundaries. The market structure concentrates around three tiers: integrated imaging-hardware vendors defending reimbursement through bundled service agreements, laboratory-focused molecular platform specialists capturing margin from consumable recurring revenue, and emerging point-of-care developers targeting government screening program adoption. Strategic moves center on M&A for technology portfolio expansion and capacity partnerships for geographic reach into high-prevalence districts.
Among diversified health technology conglomerates, Siemens Healthineers AG and Koninklijke Philips N.V. occupy positions anchoring premium imaging system supply through integrated hardware-software contracts. Thermo Fisher Scientific Inc. exemplifies the laboratory-focused archetype, with its corporate structure supporting broad molecular workflow penetration. These three entities represent distinct competitive vectors: imaging-hardware bundling, diagnostic laboratory supply, and integrated platform consolidation.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| Thermo Fisher Scientific Inc. |
| PerkinElmer Inc |
| Bio-Rad Laboratories Inc |
| F. Hoffmann-La Roche Ltd |
| Danaher Corporation |
| Illumina Inc |
| QIAGEN |
| Others |
Value Chain & Pricing Dynamics
Pathologist concentration in the United States Northeast and Germany's Rhine-Ruhr corridor creates labor-cost differentials that widen pricing-tier spreads between premium molecular platforms and commodity imaging services.
Pricing Analysis
Value-based pricing anchored to five-year survival outcomes and lesion detection sensitivity thresholds stratifies the market. Three-tier pricing structure across premium, standard, and economy levels separates AI-enhanced PET-CT systems from conventional imaging and basic histopathology services. Price differentiation stems from FDA clearance tier and pathologist oversight requirements. Cost compression in point-of-care tiers intensifies because CDSCO-registered manufacturers in India undercut Western benchmarks. Community health centers exhibit highest price sensitivity; integrated delivery networks in the United States show lowest sensitivity due to bundled procurement authority.
Supply Chain Analysis
Cold-chain logistics for salivary assay reagents and specialized fluorodeoxyglucose for PET-CT imaging elevate freight costs disproportionately for temperature-sensitive inputs. Manufacturing concentrates in the United States, Germany, and China for imaging hardware; India and China for consumable reagents. Supply chains draw from optical sensors, semiconductor detectors, and polymerase enzymes as critical inputs. Single-source vulnerability in CRISPR guide RNA synthesis creates structural risk. Distribution runs through hospital procurement committees and GPO contracts in developed markets, direct government tender in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race as players pursue captive control over consumable reagent supply to defend margins against independent laboratory price pressure.
For Market Incumbents: Hedge against liquid biopsy displacement by locking multi-year platform contracts with integrated delivery networks before salivary diagnostics achieve full CPT coding. Acquire sample preparation automation specialists to secure proprietary reant kit revenue streams. CDSCO-registered manufacturing in India under PLI scheme incentives offers cost-base protection against emerging point-of-care competitors.
For New Entrants and Emerging Players: Rural district hospitals in Maharashtra and Gujarat represent the most penetrable buyer archetype given diagnostic infrastructure gaps and government screening program procurement windows. Mobile screening unit operators seeking telepathology partnerships provide a channel-ready entry point. Prioritize EMA MDR-compliant assay development to capture first-mover advantage as retrospective validation pathways close.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-cap specialists combining NGS platform ownership with CDSCO manufacturing footprints given India's PLI scheme acceleration. Five-to-ten-year viability hinges on reimbursement code expansion rather than technology differentiation alone. Monitor FDA premarket approval timeline compression as the inflection signal for molecular diagnostic valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Liquid Biopsy Submission | Accelerated premarket review timelines compress commercialization cycles for salivary biomarker developers. |
| CDSCO Manufacturing Registration | PLI scheme incentives expand affordable screening device production for tobacco-burdened Indian districts. |
| Hospital System Partnership | Integrated delivery network procurement committees consolidate vendor relationships around bundled platform contracts. |
| Software Companion Development | AI-enhanced lesion detection integration into PET-CT systems improves sensitivity thresholds in radiology departments. |
| Reimbursement Strategy | CPT code establishment for salivary diagnostics determines commercial viability versus cost-absorption models. |
Study Parameters
Document review covered FDA premarket submission databases, EMA In Vitro Diagnostic Regulation guidance documents, CDSCO medical device registration records, and hospital procurement databases, complemented by interviews with molecular diagnostic platform engineers, hospital purchasing committee members, pathology laboratory directors, and GPO contracts managers. Secondary validation drew from CMS Medicare reimbursement data, ClinicalTrials.gov biomarker study registrations, and SEC 10-K filings of listed diagnostic manufacturers. Bottom-up demand modeling and top-down market sizing triangulated segment-level outputs.
Market value and volume projections across the analysis window applied epidemiological prevalence modeling for tobacco-related oral cancer cases, technology adoption curves for liquid biopsy platforms, and reimbursement scenario analysis for salivary diagnostics. Segmentation dimensions spanned product type, technology modality, end-user facility tier, and delivery mode. CAGRs derived from regression analysis against historical diagnostic procedure volumes and capital equipment replacement cycles. Forecast inputs incorporated FDA review timeline distributions and PLI scheme capacity buildout schedules.
Revisions become necessary when FDA premarket approval pathways extend beyond historical baselines, when EMA MDR enforcement creates parallel submission cost barriers, or when India's PLI scheme incentives shift toward alternative medical device categories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Tumor Marker Testing Market
Clinical Diagnostics
Global Apoptosis Assays Market
Clinical Diagnostics
Global Clinical Chemistry Analyzers Market
Clinical Diagnostics
Blood Group Typing Market
Clinical Diagnostics
Latin America Melanoma Diagnostics and Therapeutics Market
Clinical Diagnostics
Chromosomal Aberration Test Market
Clinical Diagnostics
Clinical Refractometer Market
Clinical Diagnostics
Global Monocyte Activation Tests Market
Clinical Diagnostics
Clinical Diagnostics Market
Clinical Diagnostics
Angiogenesis Assays Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
Serum Free Light Chain Assays (Sflc) Market
Clinical Diagnostics
Clinical Trial Kits Market
Clinical Diagnostics
Mitochondrial Myopathy Diagnosis and Treatment Market
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
Heart Failure Testing Market