
 Middle East and Africa Digital X-Ray Devices Market | 2026-2036
Middle East and Africa Digital X-Ray Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Digital X-Ray Devices Market Foresight
Hospital procurement channels across the Middle East and Africa is fragmenting as government tenders, private group purchasing organizations, and direct manufacturer agreements compete for contract flow. Siemens Healthineers leverages its installed base of imaging suites to sustain service revenue streams across Gulf state health systems. Canon Medical Systems Corporation anchors its position through localized technical support hubs in Dubai and Johannesburg. GE Healthcare competes by bundling digital X-ray platforms with enterprise-wide asset management software.
Digital X-ray devices convert ionizing radiation into electronic signals for diagnostic imaging, typically employing flat panel detectors with cesium iodide or gadolinium oxysulfide scintillators to achieve spatial resolution exceeding 3.5 line pairs per millimeter. These systems replace analog film-based radiography to enable immediate image review, lower radiation dose protocols, and seamless integration with hospital picture archiving and communication systems. Portable digital X-ray units lead volume uptake in emergency and intensive care settings across the region's tertiary hospitals. Computed radiography systems retain share in cost-sensitive clinics though flat panel detector technology captures the fastest expansion trajectory. Hybrid systems command premium positioning by combining fluoroscopy and general radiography in single-platform configurations that optimize capital expenditure for imaging labs.
South Africa's Health Products Regulatory Authority, Saudi Arabia's SFDA, and the UAE's MOHAP collectively enforce medical device registration, electromagnetic compatibility standards, and radiation safety protocols that determine market access timelines. CE marking requirements under the EU MDR influence procurement specifications for Gulf health systems that reference European technical benchmarks. Stakeholders must monitor evolving national preference policies and localization mandates that increasingly shape tender evaluation criteria across the region's public health sectors.
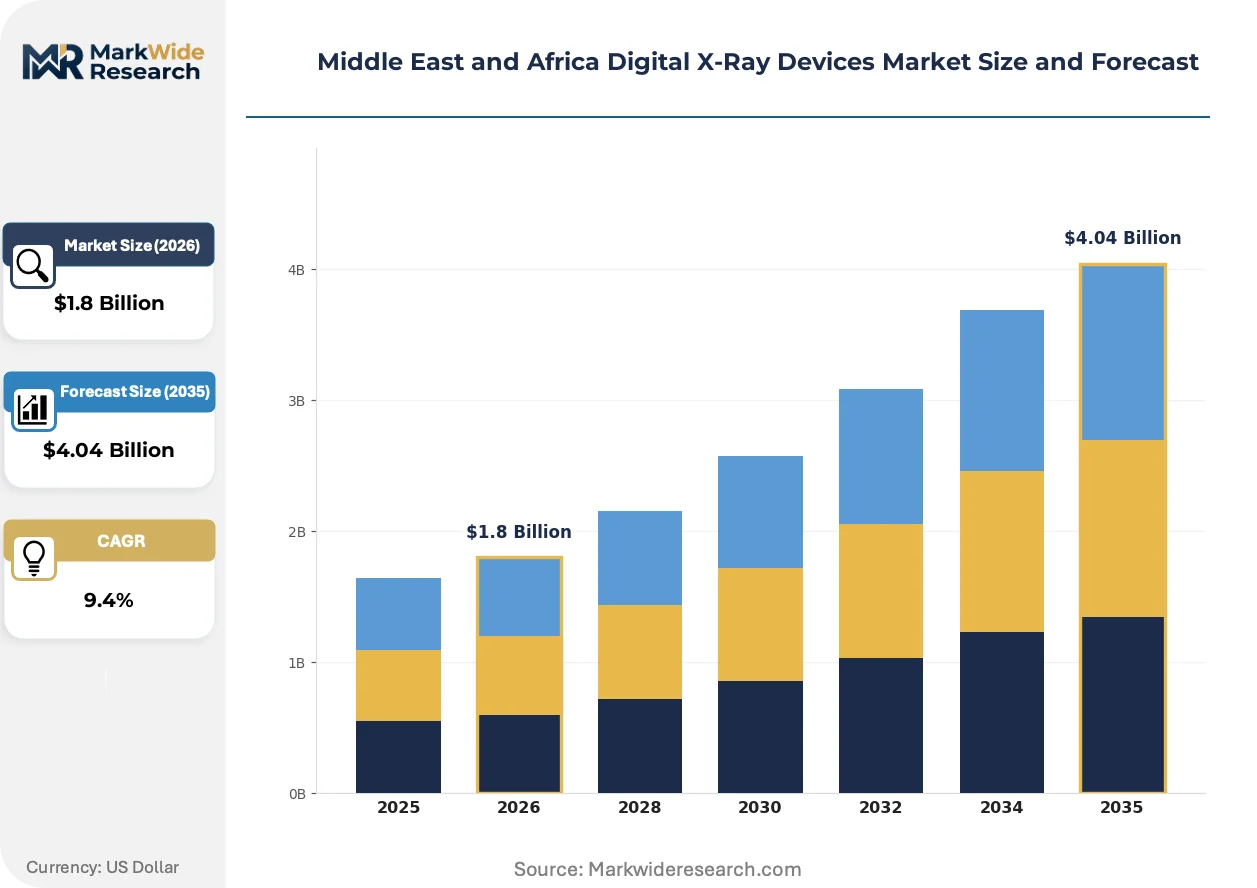
Market Dynamics
Retrofit programs across Gulf hospital networks are accelerating replacement of analog film-based radiography with flat panel detector systems, compressing capital equipment cycles from ten-year horizons toward seven-year refresh schedules.
Growth Catalysts
- Vision 2030 Infrastructure:Saudi Arabia's health modernization mandate prioritizes diagnostic imaging equipment in new hospital construction tenders.
- SFDA Registration Protocols:Stricter Saudi Food and Drug Authority equipment standards accelerate obsolescence of legacy analog systems.
- Flat Panel Detectors:Cesium iodide scintillator technology delivers immediate image review capabilities that emergency departments prioritize.
Market Restraints
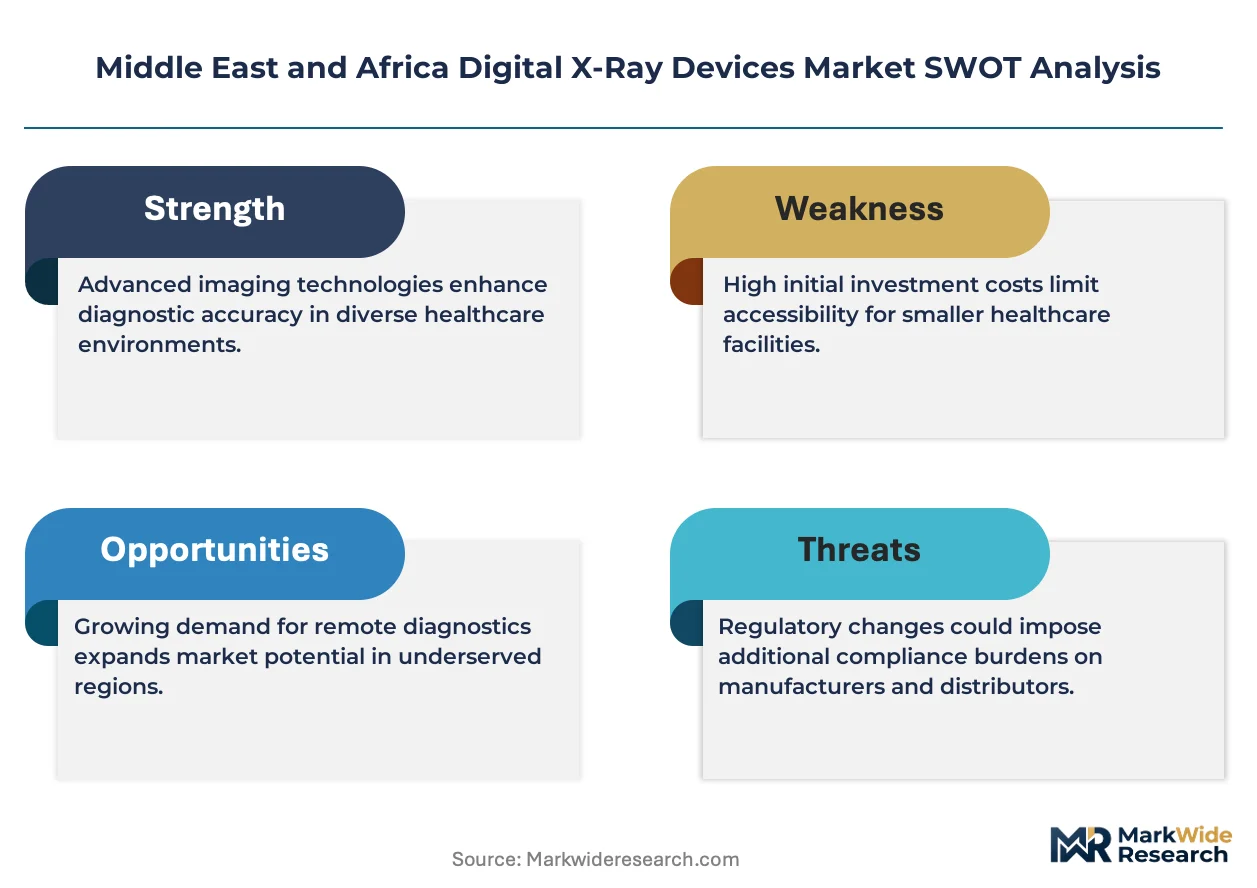
- Capital Intensity:Full-room digital radiography suites require substantial upfront investment that cost-sensitive clinics cannot absorb.
- Supply Concentration:Flat panel detector manufacturing concentrates among East Asian component suppliers, creating import dependency.
- Technical Limitations:Portable digital units sacrifice spatial resolution compared to fixed-room installations, constraining certain diagnostic applications.
Strategic Opportunities
- MOHAP Localization Mandates:UAE Ministry of Health and Prevention procurement criteria increasingly favor technical support infrastructure within the Emirates.
- Computed Tomography Convergence:Digital X-ray platforms are hybridizing with cone-beam CT capabilities for orthopedic and dental imaging workflows.
- Johannesburg Technical Hubs:South Africa's private hospital groups present aftermarket service contract expansion potential.
Industry Challenges
- Biomedical Engineering Talent:Flat panel detector calibration and cesium iodide scintillator maintenance require specialized technicians scarce across the region.
- PACS Integration Complexity:Legacy hospital information systems in older Egyptian and Moroccan facilities resist seamless picture archiving connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Digital X-Ray Devices Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, Mobile, Computed End User: Hospitals, Clinics, Diagnostic Centers, Imaging Labs Technology: Flat Panel Detector, Computed Radiography, Hybrid Systems, Other Application: Orthopedics, Dental, Cardiovascular, Veterinary |
| Companies Covered | Canon Medical Systems Corporation, Shimadzu Corporation, Siemens Healthineers, Hitachi Ltd, Hologic Inc, GE Healthcare, Fujifilm Holdings Corporation, Agfa-Gevaert Group, Koninklijke Philips NV, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Digital X-Ray Devices Market Shifts & Advancements
Equipment manufacturers are bundling hardware with predictive maintenance software to capture recurring revenue streams, while regulatory bodies tighten electromagnetic compatibility standards for networked imaging devices.
Dual-energy subtraction technology is hybridizing bone and soft tissue visualization into single-exposure workflows. Tertiary hospitals in Saudi Arabia and the UAE are adopting these systems for chest and trauma imaging. The convergence is compressing demand for separate dedicated fluoroscopy suites.
South Africa's Health Products Regulatory Authority now mandates IEC 60601 electromagnetic compatibility certification for all new digital radiography registrations. This extends market access timelines by four to six months for non-compliant manufacturers. Gulf procurement offices increasingly reference these South African standards in tender specifications.
Group purchasing organizations are consolidating buying power across private hospital networks in the UAE and Qatar. Direct manufacturer agreements are displacing traditional distributor relationships for high-volume digital X-ray contracts. Egypt's emerging private healthcare sector shows the fastest behavioral shift toward centralized procurement.
Middle East and Africa Digital X-Ray Devices Market Segmentation
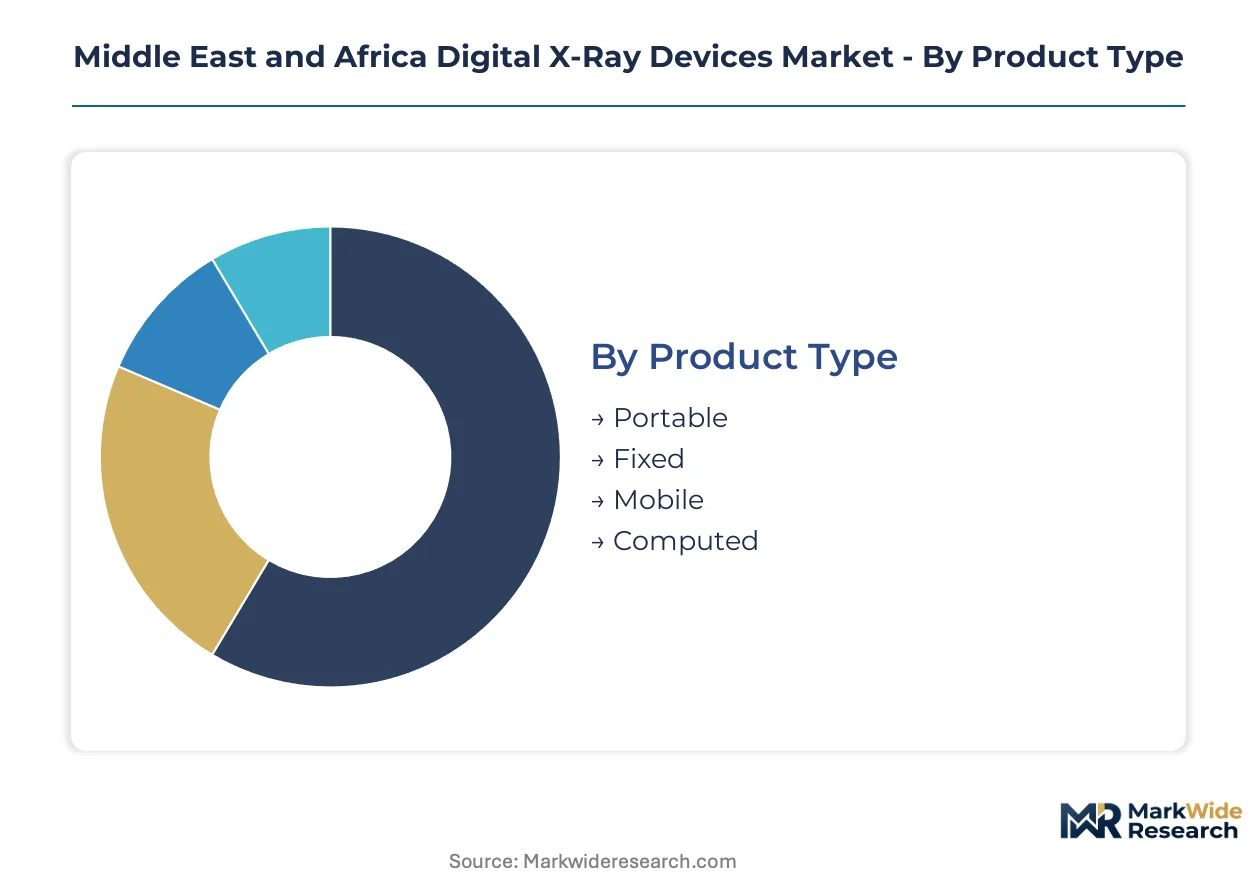
Equipment replacement cycles vary dramatically across digital X-ray segments. Flat panel detector systems compress refresh schedules to seven years while computed radiography retains decade-long depreciation. Procurement channels fragment further as portable units penetrate emergency departments and fixed-room installations anchor imaging lab capital budgets.
Product Type:
Portable systems turn over fastest as battery degradation and detector calibration drift accelerate obsolescence. Fixed installations depreciate slowest due to structural integration and shielding investments. Mobile units bridge both cycles with wheeled chassis extending service life beyond handheld equivalents.
- Portable:Battery-powered units with wireless detector panels serve intensive care and emergency departments across Saudi tertiary hospitals. Demand concentrates in Riyadh and Jeddah where Vision 2030 hospital construction prioritizes point-of-care imaging capability.
- Fixed:Ceiling-suspended tube stands and wall-mounted bucky systems occupy dedicated radiography rooms. South African private hospital networks in Johannesburg and Cape Town favor these configurations for high-throughput outpatient workflows.
- Mobile:Motorized units with on-board generators navigate between wards in UAE Ministry of Health facilities. Dubai's Rashid Hospital deploys fleets for bedside trauma imaging.
- Computed:Cassette-based photostimulable phosphor systems persist in Egyptian and Moroccan cost-sensitive clinics. Replacement pressure builds as SFDA and MOHAP registration protocols tighten.
Fixed systems dominate installed base across Gulf hospital networks. Portable configurations are where expansion concentrates as emergency department throughput demands escalate.
End User:
Capital allocation patterns split between government tenders funding hospital infrastructure and private group purchasing organizations consolidating clinic procurement. Diagnostic centers occupy a middle tier with equipment financing structures distinct from both.
- Hospitals:Tertiary institutions across the GCC deploy hybrid fluoroscopy-radiography platforms. King Faisal Specialist Hospital in Riyadh exemplifies the trend toward single-platform capital optimization.
- Clinics:Primary care facilities in Nigeria and Kenya favor refurbished computed radiography systems. Price sensitivity limits flat panel detector penetration outside major urban corridors.
- Diagnostic Centers:Standalone imaging chains in South Africa's Gauteng province bundle X-ray with ultrasound and mammography. Netcare and Life Healthcare operate centralized procurement for multi-site equipment standardization.
- Imaging Labs:Specialized orthopedic and dental radiography providers in Qatar's Doha cluster command premium pricing for subspecialty interpretations. Volume per machine exceeds general hospital deployment.
Hospitals anchor equipment vendor relationships through decade-long service contracts. Diagnostic centers are climbing the fastest as private equity consolidates fragmented imaging capacity.
Technology:
Component sourcing geography shapes technology selection as East Asian flat panel detector supply concentrates procurement risk. Hybrid architectures emerge where fluoroscopy and radiography workflows overlap.
- Flat Panel Detector:Amorphous silicon arrays with cesium iodide scintillators deliver spatial resolution exceeding 3.5 line pairs per millimeter. Saudi Arabia's SFDA now mandates IEC 60601 electromagnetic compatibility certification for all new registrations.
- Computed Radiography:Photostimulable phosphor plates require laser scanning digitization before PACS integration. Egyptian public hospitals retain substantial installed base despite replacement pressure from digital radiography tenders.
- Hybrid Systems:Combined fluoroscopy and general radiography platforms reduce capital expenditure for imaging labs with constrained floor space. UAE private hospitals in Abu Dhabi adopt these for interventional and diagnostic workflow consolidation.
- Other:Line-scan detector arrays and photon-counting architectures remain experimental across the region. Research installations at South African academic medical centers evaluate clinical viability.
Computed radiography retains substantial legacy presence in North African public health systems. Flat panel detector technology is gaining share fastest as Gulf procurement specifications harden around immediate image review requirements.
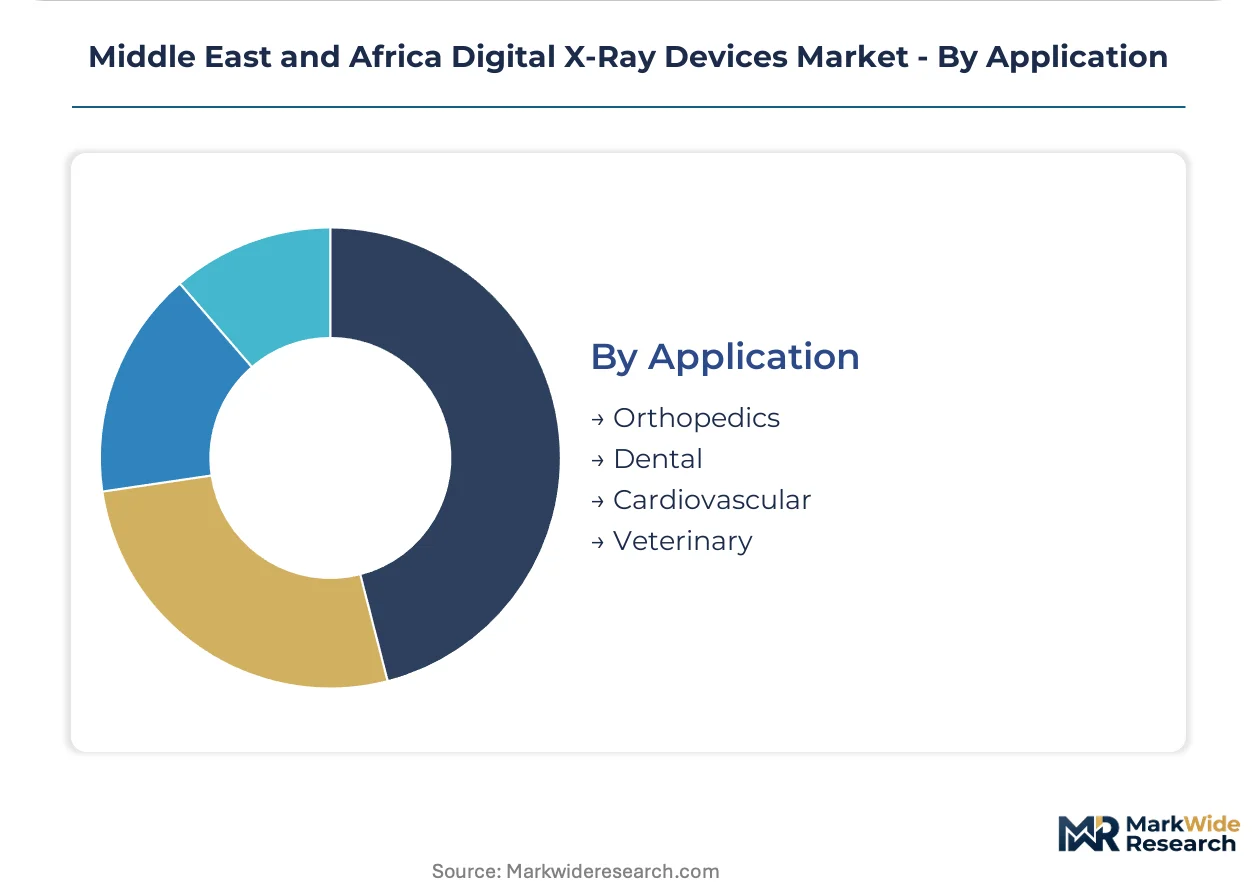
Application:
Reimbursement structures and referral patterns determine application-specific equipment allocation. Orthopedic and dental imaging support higher capital intensity than general chest radiography.
- Orthopedics:Weight-bearing extremity imaging and long-leg alignment studies demand specialized bucky configurations. South African sports medicine clinics in Cape Town and Pretoria invest in dedicated trauma suites.
- Dental:Cone-beam CT convergence with panoramic radiography compresses demand for standalone digital X-ray. Saudi dental chains in Jeddah and Dammam favor hybrid platforms for implant planning workflows.
- Cardiovascular:Chest radiography for device placement verification and post-interventional monitoring. Cardiac catheterization labs across Qatar's Hamad Medical Corporation integrate fixed detectors with hemodynamic monitoring.
- Veterinary:Equine imaging in South Africa's KwaZulu-Natal racing industry and small-animal practice in UAE expatriate communities. Regulatory oversight remains lighter than human medical device registration.
Orthopedic applications dominate revenue per machine across private hospital networks. Dental imaging is expanding most quickly as specialist clinic chains proliferate in Gulf urban centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Fahd Causeway connects Saudi Arabia and Bahrain, enabling rapid equipment transit across Gulf Cooperation Council health systems. This infrastructure underwrites the region's role as a digital X-ray distribution hub.
Saudi Arabia
Vision 2030 hospital construction and diagnostic imaging modernization drive procurement volumes. The Saudi Food and Drug Authority enforces stricter equipment registration protocols that accelerate legacy system replacement. King Faisal Specialist Hospital in Riyadh deploys hybrid fluoroscopy-radiography platforms for capital optimization.
United Arab Emirates
MOHAP localization mandates reshape tender evaluation criteria toward in-country technical support infrastructure. The Ministry of Health and Prevention prioritizes procurement specifications referencing immediate image review capabilities. Dubai's Rashid Hospital operates mobile X-ray fleets for bedside trauma imaging across wards.
South Africa
Private hospital networks in Gauteng province consolidate procurement through centralized group purchasing organizations. The Health Products Regulatory Authority mandates IEC 60601 electromagnetic compatibility certification, extending market access timelines. Netcare and Life Healthcare standardize multi-site equipment configurations across Johannesburg and Cape Town.
Egypt
Public hospitals retain substantial computed radiography installed base amid cost-sensitive procurement environments. The emerging private healthcare sector exhibits the fastest behavioral shift toward centralized procurement channels. Cairo-based imaging chains face replacement pressure as Gulf procurement specifications harden around flat panel detector requirements.
Qatar
Hamad Medical Corporation integrates fixed detectors with hemodynamic monitoring in cardiac catheterization labs. The country's national health system prioritizes single-platform capital expenditure optimization for constrained imaging lab floor space. Doha's specialist orthopedic and dental radiography providers command premium pricing for subspecialty interpretations.
Middle East and Africa Digital X-Ray Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in detector manufacturing and scintillator supply. The vendor base concentrates among diversified medical technology conglomerates with imaging suite installed bases. Three archetypes dominate: full-platform manufacturers bundling hardware with asset management software, regional service specialists leveraging localized technical hubs, and component suppliers controlling flat panel detector supply. Competitive moves center on predictive maintenance software bundling and strategic partnerships with Gulf hospital networks for decade-long service contracts.
Among diversified platform manufacturers, Siemens Healthineers, GE Healthcare, and Canon Medical Systems Corporation exemplify distinct strategic positioning. Siemens Healthineers leverages its installed base across Gulf state health systems to sustain recurring service revenue streams. GE Healthcare competes through enterprise-wide asset management software bundling with digital X-ray platforms. Canon Medical Systems Corporation anchors its regional position through localized technical support infrastructure in Dubai and Johannesburg.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Shimadzu Corporation |
| Siemens Healthineers |
| Hitachi Ltd |
| Hologic Inc |
| GE Healthcare |
| Fujifilm Holdings Corporation |
| Agfa-Gevaert Group |
| Koninklijke Philips NV |
| Others |
Supply & Pricing Matrix
Flat panel detector import dependency on East Asian component suppliers compresses pricing tier spreads while elongating procurement lead times for Gulf hospital networks and South African private health systems. SFDA and MOHAP electromagnetic compatibility certification requirements add regulatory chokepoint costs that concentrate margin pressure on economy-tier computed radiography vendors serving Egyptian and Moroccan clinics.
Pricing Analysis
Volume-discount tiering structures separate enterprise hospital network contracts from standalone diagnostic center purchases across the Middle East and Africa digital X-ray devices market. Three-tier pricing structure across premium, standard, and economy levels differentiates hybrid fluoroscopy-radiography platforms from fixed-room installations and portable units, with after-sales service bundling commanding additional margin capture. Pricing pressure stems from group purchasing organization consolidation among UAE and Qatar private hospital networks. Clinics in Nigeria and Kenya exhibit highest price sensitivity, constrained to refurbished computed radiography systems, while Saudi tertiary hospitals under Vision 2030 tenders demonstrate lowest sensitivity for immediate image review capabilities.
Supply Chain Analysis
Contract manufacturing concentration for flat panel detectors sits with amorphous silicon array fabricators in South Korea, Japan, and Taiwan, with cesium iodide scintillator crystal growth anchored in Japanese and Chinese specialty chemical facilities. Component sourcing draws from East Asian photolithography equipment and rare earth phosphor suppliers, creating single-source vulnerability for gadolinium oxysulfide scintillator formulations. Tariff exposure on semiconductor-grade silicon wafers threatens cost structures for detector assembly. Distribution runs through Dubai and Johannesburg technical hub infrastructure serving Gulf Cooperation Council and sub-Saharan hospital networks respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa digital X-ray devices market sits at a platform-economics inflection where PACS interoperability and predictive maintenance software bundling determine vendor stickiness. King Faisal Specialist Hospital's hybrid platform deployment signals ecosystem consolidation around single-vendor imaging suites.
For Market Incumbents: Insulate service revenue streams by embedding predictive maintenance algorithms into flat panel detector firmware, locking Gulf hospital networks into decade-long technical support contracts. Deepen backward integration into cesium iodide scintillator production to offset East Asian supply concentration risk. Prioritize SFDA and MOHAP certification maintenance as regulatory barriers against emerging competitors.
For New Entrants and Emerging Players: Egyptian private healthcare sector consolidation presents the most penetrable white-space target, with centralized procurement behavior shifting fastest among Cairo-based imaging chains. Nigeria and Kenyan primary care clinics offer secondary entry through refurbished computed radiography trade-in programs. Pursue direct manufacturer agreements displacing traditional distributor relationships to capture margin.
For Investors and Strategic Acquirers: The market sits at a replacement-cycle acceleration phase that favors technical service specialists with localized biomedical engineering talent. Long-term viability hinges on software companion development capabilities and hospital system partnership depth. Monitor SFDA registration protocol tightening as inflection indicator for legacy system obsolescence velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance accelerates Gulf procurement specifications referencing European technical benchmarks. |
| Hospital System Partnership | Decade-long service contracts with Saudi tertiary hospitals under Vision 2030 anchor recurring revenue. |
| Software Companion Development | Predictive maintenance bundling captures aftermarket value from flat panel detector installed base. |
| Localization Infrastructure | MOHAP technical support mandates favor Dubai and Johannesburg hub investments for market access. |
| Reimbursement Strategy | Diagnostic imaging tariff alignment with Saudi and UAE national health insurance schemes drives procurement. |
Research Methodology
Operator-level perspectives from hospital procurement managers, biomedical engineering directors, GPO contracts specialists, and radiology department heads anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against SFDA registration databases, MOHAP tender specifications, South African Health Products Regulatory Authority filings, and hospital equipment procurement records. Bottom-up unit demand estimates triangulated with top-down healthcare infrastructure spending analysis.
Scenario-bracketing framed low-base-high projections across the modeling period, with segmentation dimensions spanning product type, end user, technology, and application. CAGRs derived from equipment replacement cycle compression analysis and diagnostic imaging modernization budget trajectories. Forecast inputs incorporated Vision 2030 capital allocation schedules and electromagnetic compatibility certification timeline assumptions.
Practitioners should monitor SFDA protocol amendments, MOHAP localization mandate evolution, and flat panel detector supply lead times for early signals of forecast revision. Quarterly review of Gulf hospital tender awards and South African GPO consolidation patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Diagnostic Imaging Markers Market
Medical Imaging
Medical Imaging Software Market
Medical Imaging
Germany Digital Radiology Market
Medical Imaging
Medical Imaging Management Market
Medical Imaging
Refurbished Medical Imaging Devices Market
Medical Imaging
Mammography Detectors Market
Medical Imaging
India Ultrasound Devices Market
Medical Imaging
Medical Imaging Outsourcing Market
Medical Imaging
Argentina Computed Tomography Market
Medical Imaging
Australia Computed Tomography Market
Medical Imaging
Brain PET-MRI Systems Market
Medical Imaging
Precision Cancer Imaging Market
Medical Imaging
Germany Mammography Market
Medical Imaging
Pre-Clinical Imaging System Market
Medical Imaging
Global Image Guided Therapy System Market
Medical Imaging
Global Dental Panoramic Radiography Market