
 Japan Computed Tomography Market | 2026-2036
Japan Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Computed Tomography Market Foresight
Equipment leasing and managed service contracts is rewriting competitive access for mid-tier hospitals that previously deferred capital outlays. Siemens Healthineers leverages its dual-source installed base to sustain service revenue streams across Japan's prefectural medical centers. Canon Medical Systems anchors domestic manufacturing through its Otawara production complex, competing on shortened delivery cycles for spiral CT systems. GE Healthcare differentiates through AI-integrated reconstruction software that occupies the premium tier of hospital procurement tenders.
Computed tomography denotes an X-ray-based cross-sectional imaging modality utilizing rotating gantry assemblies with detector arrays capturing attenuation data reconstructed into volumetric slices, typically achieving spatial resolution below 0.5 millimeters for diagnostic applications. The technology serves primarily to detect neoplastic lesions, vascular pathologies, and traumatic injuries with speed unattainable by magnetic resonance methods. Spiral CT systems dominate current installed capacity across Japanese diagnostic centers, though photon-counting CT represents the fastest-growing technology segment as spectral imaging capabilities expand oncology staging precision. Hospitals command the largest end-user share by procurement value, while research facilities concentrate demand for preclinical cone-beam CT configurations in pharmaceutical development settings.
PMDA governs device approval pathways and post-market surveillance obligations, while METI coordinates industrial policy supporting domestic medical equipment manufacturing through targeted R&D subsidies. JIS standards establish baseline safety and performance benchmarks that shape product design requirements for vendors seeking national reimbursement eligibility. Stakeholders must monitor how photon-counting detector qualification timelines intersect with hospital capital planning cycles to anticipate procurement windows.
Market Dynamics
Photon-counting detector technology is compressing replacement cycles across Japan's metropolitan hospital networks as spectral imaging capabilities redefine diagnostic precision thresholds for oncology and cardiology protocols.
Growth Catalysts
- PMDA reimbursement revisions:Expanded cardiac imaging protocols now reimburse CT coronary angiography procedures, pulling forward procurement timelines at prefectural medical centers previously constrained by budget cycles.
- Domestic manufacturing concentration:Canon Medical Systems' Otawara production complex shortens delivery cycles for spiral CT systems, reducing lead times for hospitals facing urgent equipment failures.
- Equipment leasing structures:Managed service contracts now dominate mid-tier hospital procurement, converting capital outlays into operational expenditures and expanding vendor access beyond tertiary centers.
Market Restraints
- Detector material supply concentration:Cadmium zinc telluride crystal production concentrates among limited specialty suppliers, creating input cost volatility for photon-counting CT manufacturers.
- JIS certification timelines:Baseline safety and performance benchmarks require extensive validation protocols, extending product launch windows and freezing R&D returns across development cycles.
- Magnetic resonance substitution:Soft tissue imaging without ionizing radiation attracts pediatric and repeat-scan protocols, constraining CT volume growth in specific diagnostic categories.
Strategic Opportunities
- Chugoku region underpenetration:Rural prefectural hospitals operate aging 16-slice and 32-slice systems, creating replacement demand as mobile screening programs expand to Hiroshima and Okayama prefectures.
- AI-integrated reconstruction convergence:Deep learning algorithms paired with iterative reconstruction techniques reduce radiation dose while maintaining image quality, opening premium-tier positioning for software-differentiated vendors.
- METI R&D subsidies:Industrial policy targeting domestic medical equipment manufacturing funds photon-counting detector qualification programs, accelerating technology transfer from research facilities to commercial production.
Industry Challenges
- Clinical physicist scarcity:Specialized training for spectral imaging protocol optimization lags hardware deployment, creating utilization gaps at hospitals that procured photon-counting systems.
- Legacy PACS integration:Hospital information systems built around DICOM standards from 2005-2015 require expensive middleware layers to process spectral CT data streams, complicating deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Computed Tomography Market |
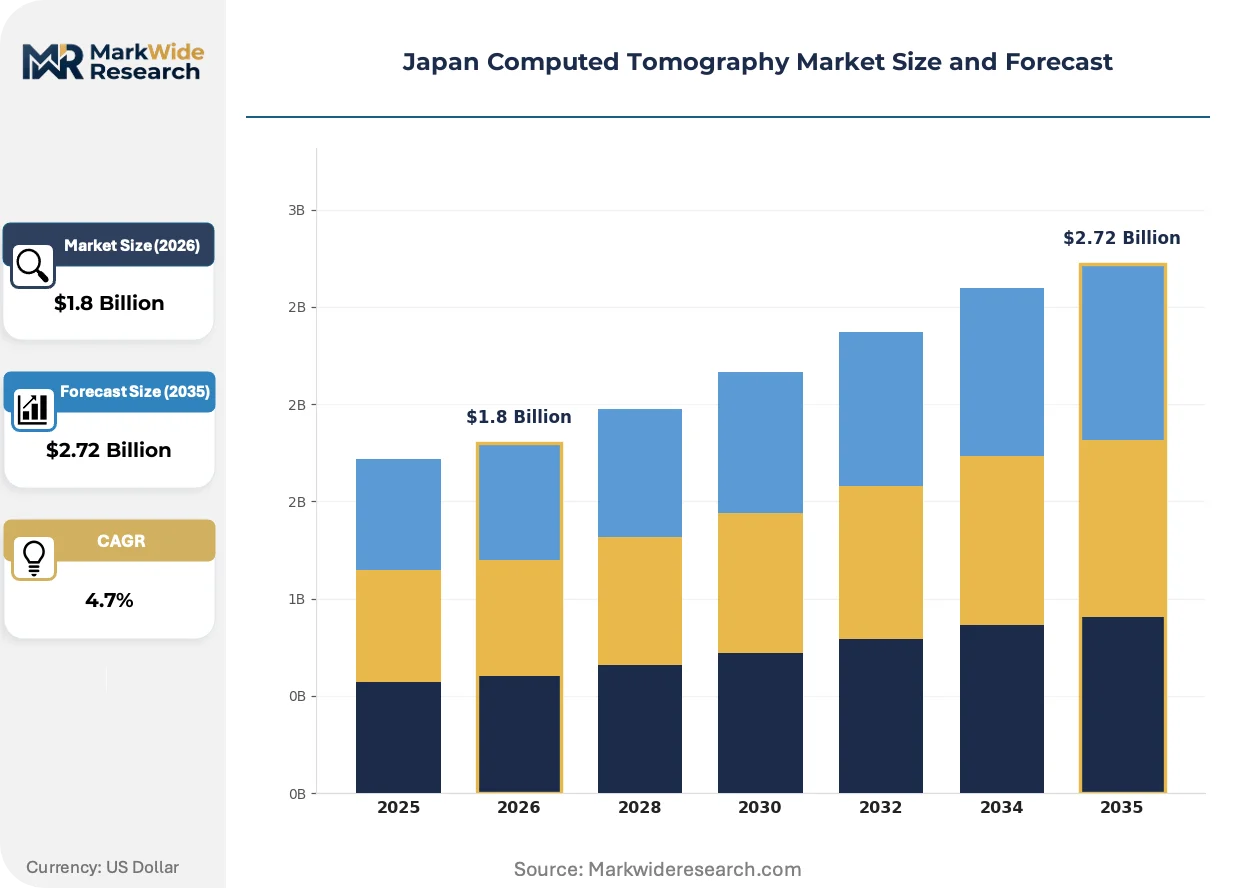
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
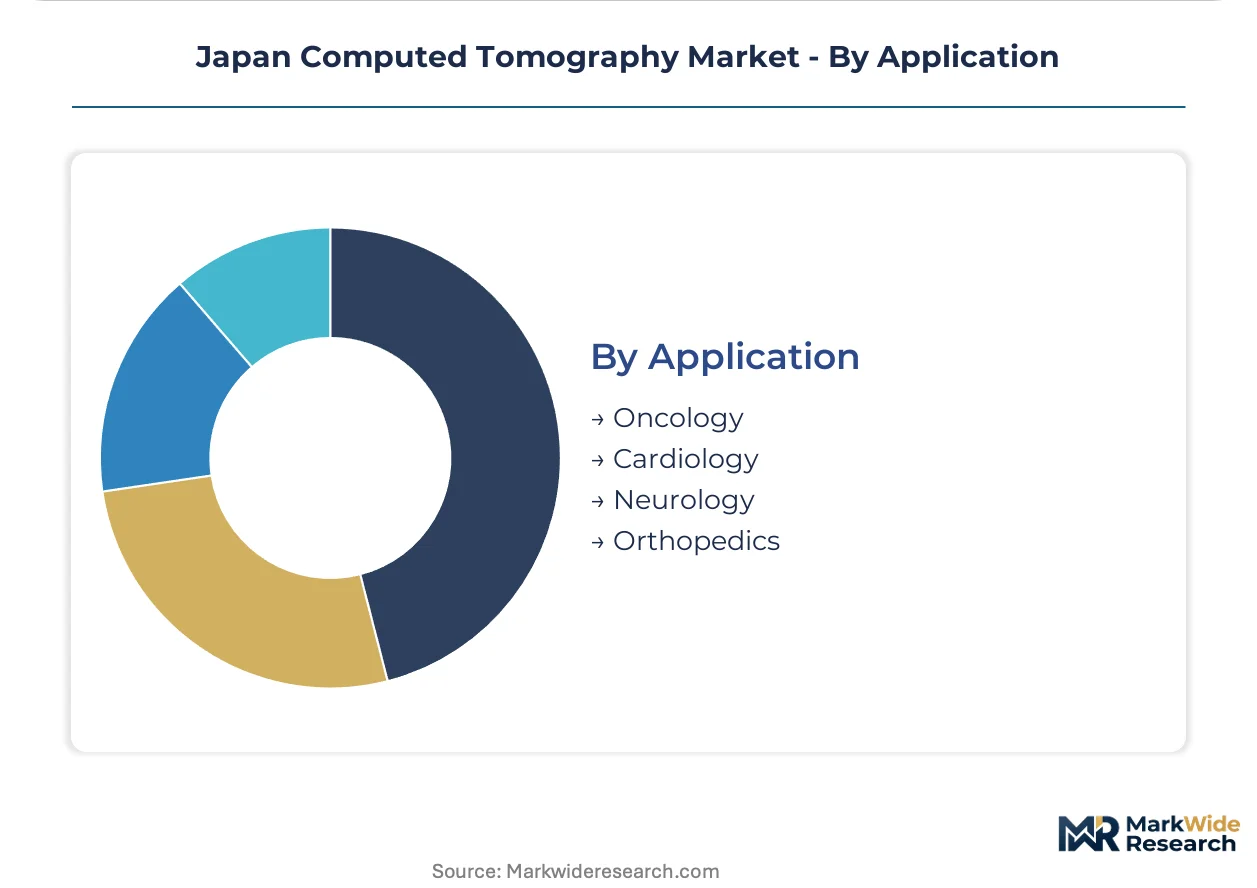
| Segmentation | Product Type: Conventional CT, Spiral CT, Portable CT, Cone Beam CT End User: Hospitals, Diagnostic Centers, Research Facilities, Clinics Technology: Multislice CT, Dual-source CT, Photon-counting CT, Contrast-enhanced CT Application: Oncology, Cardiology, Neurology, Orthopedics |
| Companies Covered | Canon Medical Systems, Siemens Healthineers, GE Healthcare, Koninklijke Philips, Fujifilm Holdings Corporation, Hitachi Medical Corporation, NEUSOFT Japan, Shanghai United Imaging Healthcare, J. Morita Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Computed Tomography Market Shifts & Advancements
Software-defined reconstruction architectures are displacing hardware-centric imaging pipelines across Japanese diagnostic centers. Three interconnected developments are compressing traditional technology adoption curves.
Photon-counting detector arrays are virtualizing the signal processing chain that previously required analog-to-digital conversion layers. Urban tertiary centers in Tokyo and Osaka are adopting these systems at twice the pace of provincial hospitals. This virtualization is collapsing the distinction between hardware acquisition and software upgrade cycles, enabling vendors to monetize capability enhancements through subscription rather than equipment replacement.
PMDA post-market surveillance obligations now mandate real-world performance tracking for AI-integrated diagnostic devices. Manufacturers must submit periodic safety reports based on clinical deployment data, increasing compliance overhead. Premium-tier procurement tenders increasingly weight algorithmic transparency and traceability, favoring vendors with established domestic regulatory affairs infrastructure.
Prefectural medical centers are unbundling service contracts from equipment purchases, treating maintenance and software updates as separately negotiable line items. Independent service organizations are capturing aftermarket revenue previously monopolized by original equipment manufacturers. This disintermediation is most visible in Kanto region hospital networks, where procurement committees now mandate multi-vendor service quotes for systems beyond warranty periods.
Japan Computed Tomography Market Segmentation
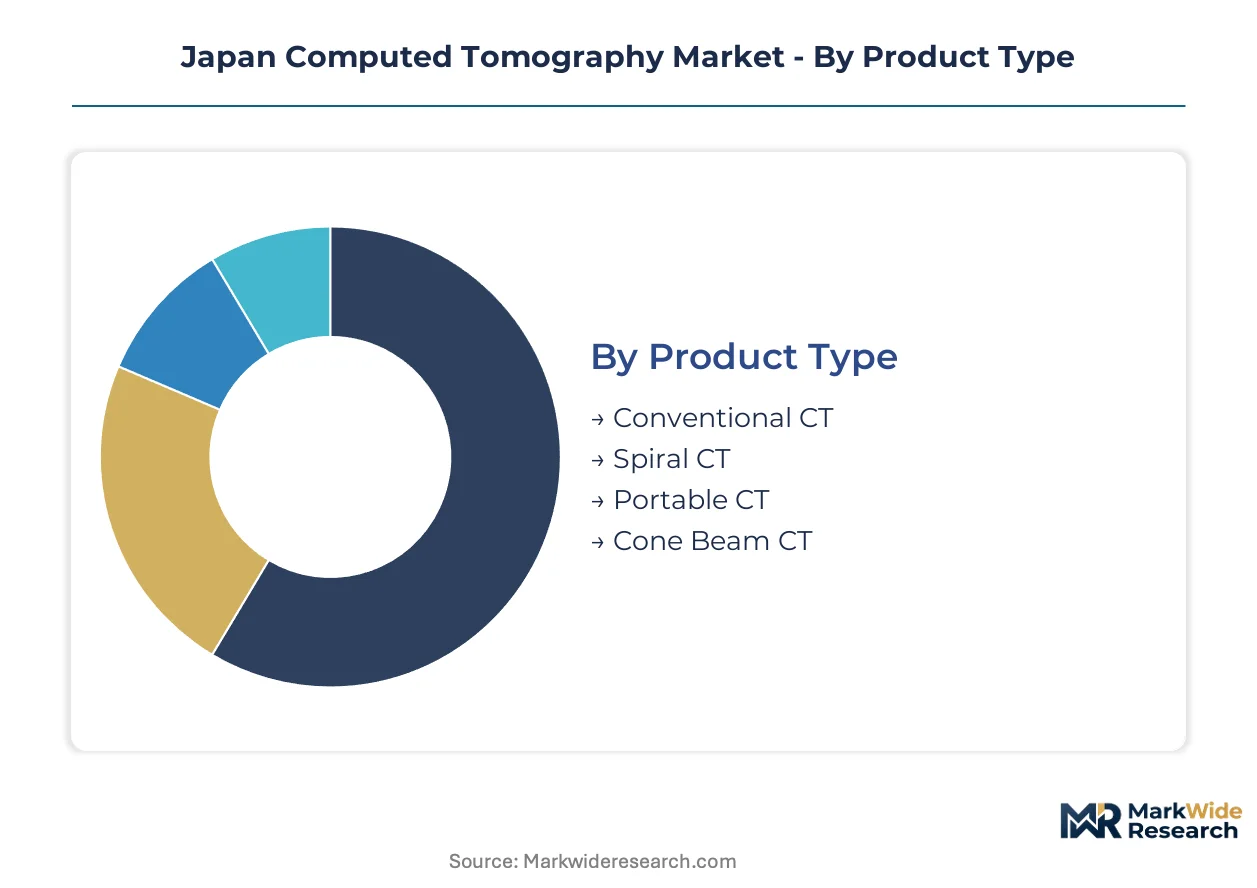
Segmentation reveals how procurement priorities diverge across Japan's hospital networks. Equipment replacement cycles, reimbursement pathways, and clinical specialization create distinct demand clusters that vendors must navigate separately.
Product Type:
After-sales-service intensity varies sharply across product categories, with spiral CT systems demanding the most intensive maintenance protocols due to rotating gantry assemblies and detector calibration requirements.
- Spiral CT:Continuous rotation gantry systems acquire volumetric data during single breath-hold sequences. Demand concentrates in Tokyo metropolitan hospital networks where cardiac imaging protocols under PMDA reimbursement revisions pull replacement cycles forward for aging 64-slice installations.
- Conventional CT:Sequential slice-by-slice acquisition systems with step-and-shoot mechanics dominate rural prefectural facilities with constrained capital budgets. Okayama and Hiroshima prefectures retain substantial installed bases awaiting mobile screening program expansions.
- Portable CT:Self-contained mobile units with battery power and compact footprints serve emergency departments and intraoperative imaging suites.
- Cone Beam CT:Flat-panel detector systems optimized for high-resolution dental and extremity imaging occupy orthopedic and maxillofacial specialties.
Spiral CT holds the largest share; momentum sits with portable CT configurations as point-of-care protocols expand.
End User:
Procurement authority concentrates differently across customer types, with hospitals consolidating purchasing decisions through centralized medical equipment committees while clinics negotiate individual managed service contracts.
- Hospitals:Tertiary medical centers with 24-hour emergency departments and interventional suites command the highest procurement values. Kanto region networks drive replacement demand as spectral imaging capabilities redefine diagnostic precision thresholds.
- Diagnostic Centers:Specialized outpatient imaging facilities optimized for high patient throughput operate on compressed equipment depreciation schedules. Chugoku region underpenetration creates replacement windows for aging 16-slice and 32-slice systems.
- Research Facilities:Academic medical centers and pharmaceutical development sites prioritize preclinical cone-beam CT configurations for translational studies.
- Clinics:Small-format general practice and specialty outpatient settings favor refurbished systems and leasing structures to convert capital outlays into operational expenditures.
Hospitals dominate procurement value; diagnostic centers are gaining share fastest as outpatient imaging volumes expand.
Technology:
Detector architecture determines both upfront capital requirements and ongoing service revenue potential, with photon-counting systems commanding premium positioning through spectral imaging capabilities.
- Photon-counting CT:Direct x-ray photon measurement eliminates electronic noise and enables material decomposition imaging. Urban tertiary centers in Tokyo and Osaka adopt at twice provincial hospital rates as cadmium zinc telluride crystal supply constraints limit manufacturing scale.
- Multislice CT:Parallel detector array configurations with 64 to 320 simultaneous slice acquisition remain the workhorse technology across prefectural medical centers.
- Dual-source CT:Twin x-ray tube assemblies enable temporal resolution below 75 milliseconds for cardiac imaging without beta-blockade.
- Contrast-enhanced CT:Protocol-optimized acquisition sequences synchronized with iodinated contrast injection timing dominate oncology staging applications.
Multislice CT holds the largest installed base; photon-counting CT is climbing the fastest as METI R&D subsidies accelerate domestic qualification programs.
Application:
Clinical indication shapes hardware specification requirements, with cardiac and oncological protocols driving the highest detector performance thresholds and software reconstruction demands.
- Oncology:Whole-body staging and treatment response monitoring protocols require spectral imaging capabilities for lesion characterization. Photon-counting detector deployment concentrates in cancer centers where material decomposition improves tumor boundary delineation.
- Cardiology:Coronary CT angiography expansion under PMDA reimbursement revisions pulls procurement timelines forward at prefectural medical centers previously constrained by budget cycles.
- Neurology:Perfusion imaging and stroke protocol optimization demand rapid scan acquisition with motion artifact correction.
- Orthopedics:Weight-bearing extremity and metal artifact reduction protocols favor cone-beam and dual-energy configurations.
Oncology commands the highest equipment specification tier; cardiology is expanding most quickly as reimbursement coverage broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's CT equipment trade balance tilts toward import dependency for high-end detector materials, though domestic assembly at Canon Medical Systems' Otawara complex reduces finished system import intensity. Metropolitan hospital networks in Kanto and Kansai drive procurement volumes that exceed regional production capacity for photon-counting components.
Kanto
Tokyo's metropolitan hospital networks command replacement cycles for aging 64-slice scanners as cardiac imaging protocols expand under PMDA reimbursement revisions. METI coordinates industrial policy supporting domestic manufacturing through targeted R&D subsidies concentrated in this corridor. Yokohama and Saitama prefectures host tertiary medical centers adopting photon-counting detector systems at twice the national average rate.
Kansai
Osaka's urban tertiary centers match Tokyo's adoption velocity for spectral imaging capabilities in oncology staging applications. PMDA governs device approval pathways that shape procurement timelines for prefectural medical centers across Hyogo and Kyoto. The Osaka-Kobe industrial cluster anchors service revenue streams for dual-source CT installations at university-affiliated hospitals.
Chubu
Nagoya's manufacturing base supplies precision components for rotating gantry assemblies deployed nationwide. JIS standards establish safety benchmarks that shape product design requirements for vendors seeking national reimbursement eligibility. Aichi prefecture's diagnostic centers operate aging 16-slice systems awaiting replacement as mobile screening programs expand.
Kyushu
Fukuoka's regional medical centers face clinical physicist scarcity that lags hardware deployment for spectral imaging protocol optimization. The national pharmaceutical regulator mandates post-market surveillance obligations that increase compliance overhead for AI-integrated devices. Kumamoto and Kagoshima prefectures retain substantial conventional CT installed bases with constrained capital budgets.
Tohoku
Sendai's tertiary hospitals manage legacy PACS integration challenges requiring expensive middleware layers for spectral CT data streams. Reimbursement revisions for coronary CT angiography pull procurement timelines forward at prefectural medical centers previously constrained by budget cycles. Miyagi and Fukushima prefectures concentrate demand for portable CT configurations in emergency departments.
Japan Computed Tomography Market Competitive Landscape
On the supply side, the industry is consolidating around technology-differentiated tiers rather than pure scale advantages. Domestic manufacturing concentration through Canon Medical Systems' Otawara complex competes against multinational service networks. Three archetypes dominate: integrated manufacturers with captive detector supply, software-differentiated premium vendors, and regional leasing specialists converting capital outlays to operational expenditures. Competitive intensity centers on AI-integrated reconstruction capabilities and managed service contract structures.
Among Japan-based fabricators, Canon Medical Systems and Hitachi Medical Corporation occupy positions anchored to domestic production infrastructure. Siemens Healthineers and GE Healthcare exemplify the multinational premium tier competing through algorithmic transparency and established regulatory affairs infrastructure. Koninklijke Philips sits within the integrated imaging portfolio archetype alongside Fujifilm Holdings Corporation. These six entities represent the core competitive set, with NEUSOFT Japan and Shanghai United Imaging Healthcare expanding presence through cost-positioned alternatives.
| Leading Market Players |
|---|
| Canon Medical Systems |
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips |
| Fujifilm Holdings Corporation |
| Hitachi Medical Corporation |
| NEUSOFT Japan |
| Shanghai United Imaging Healthcare |
| J. Morita Corporation |
| Others |
Supply & Pricing Matrix
Cadmium zinc telluride crystal production concentrates among limited specialty suppliers in Japan and Germany, anchoring margin capture at the detector substrate tier and compressing pricing flexibility for finished photon-counting CT systems at domestic manufacturers.
Pricing Analysis
Hospital procurement committees anchor pricing negotiations through unbundled service contracts and multi-vendor quote requirements. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated reconstruction systems from conventional multislice configurations and refurbished legacy installations. Cost compression in the economy tier is intensifying because independent service organizations capture aftermarket revenue previously monopolized by original equipment manufacturers. Mid-tier prefectural hospitals exhibit highest price sensitivity due to constrained capital budgets, while Tokyo metropolitan networks prioritize spectral imaging capabilities over unit cost.
Supply Chain Analysis
Tariff exposure between Japan and China dominates supply chain risk planning for rotating gantry assemblies and flat-panel detector substrates. Manufacturing draws from Japanese precision component clusters in Aichi prefecture, German detector crystal foundries, and Chinese rare earth processing facilities for scintillator materials. Single-source vulnerability concentrates at the cadmium zinc telluride crystal tier where qualification timelines extend product launch windows. Distribution runs through Canon Medical Systems' Otawara production complex for domestic assembly, supplemented by direct OEM shipments for premium-tier photon-counting configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's CT market is recovering from deferred replacement cycles as PMDA reimbursement revisions for cardiac imaging protocols pull procurement timelines forward at capital-constrained prefectural medical centers.
For Market Incumbents: Insulate service revenue streams by converting installed dual-source and photon-counting bases into subscription-based software upgrade contracts. Deepen backward integration into detector substrate supply through METI R&D subsidy capture for cadmium zinc telluride qualification programs. Prioritize clinical physicist training partnerships to close utilization gaps at hospitals that procured spectral imaging hardware ahead of protocol optimization capabilities.
For New Entrants and Emerging Players: Pursue leasing and managed service contract structures that convert capital outlays into operational expenditures for mid-tier hospitals in Chugoku and Tohoku regions. Target diagnostic centers in Hiroshima and Okayama prefectures operating aging 16-slice and 32-slice systems awaiting mobile screening program expansions. Lead with AI-integrated reconstruction software positioned for premium-tier procurement tenders requiring algorithmic transparency and PMDA post-market surveillance compliance.
For Investors and Strategic Acquirers: Capital is best deployed toward domestic manufacturing specialists with captive detector supply and established regulatory affairs infrastructure serving the premium hospital tier. Long-term viability rests on photon-counting technology transfer acceleration from research facilities to commercial production. Monitor cadmium zinc telluride crystal supply expansion announcements as the inflection indicator for manufacturing scale and pricing power shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Reimbursement Strategy | Expanded cardiac imaging protocol coverage pulls forward procurement timelines at prefectural medical centers. |
| Photon-Counting Detector Qualification | METI R&D subsidies accelerate technology transfer from research facilities to commercial production scale. |
| Managed Service Contract Expansion | Leasing structures convert capital outlays into operational expenditures for mid-tier hospital access. |
| Clinical Physicist Training Partnership | Protocol optimization capabilities close utilization gaps at hospitals with deployed spectral imaging systems. |
| AI-Integrated Reconstruction Development | Deep learning algorithms reduce radiation dose while maintaining image quality for premium-tier positioning. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, biomedical engineers, clinical physicists, and GPO contracts directors; and secondary validation against PMDA device approval databases, hospital procurement registries, METI industrial policy filings, and JIS standards documentation. Bottom-up equipment shipment analysis triangulated against top-down reimbursement volume projections.
Forecast inputs include technology adoption curves for photon-counting detector deployment, replacement cycles segmented by installed base vintage, and reimbursement pathway expansion timelines across the analysis window. Segmentation dimensions modeled encompass product type, end-user category, detector architecture, and clinical application. CAGRs derive from installed base turnover rates and capital expenditure elasticity to reimbursement revisions.
Sensitivities concentrate around PMDA qualification timeline delays, cadmium zinc telluride crystal supply constraints, and magnetic resonance substitution acceleration in pediatric protocols. Forecasts reflect assumptions about spectral imaging protocol standardization and clinical physicist training pipeline expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Medical Holography Market
Medical Imaging
Australia Computed Tomography Market
Medical Imaging
Mexico Diagnostic Imaging Equipment Market
Medical Imaging
Digital Pathology Scanner Calibration and Image Quality Test Systems Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
Global Pediatric Magnetic Resonance Imaging (MRI) Market
Medical Imaging
United States Digital X-Ray Devices Market
Medical Imaging
Radiology Services Market
Medical Imaging
India Mammography Market
Medical Imaging
France Computed Tomography Market
Medical Imaging
Magnetic Resonance Imaging Equipment Coils Market
Medical Imaging
Canada Nuclear Medicine Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
Digital Pathology Market
Medical Imaging
Global Image Guided Therapy System Market
Medical Imaging
Radiation Dose Management Market