
 Global Elastography Imaging Market | 2026-2036
Global Elastography Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Elastography Imaging Market Foresight
Oncology departments are recalibrating their imaging portfolios toward tissue stiffness quantification for tumor margin assessment. Siemens Healthineers leverages its MR elastography platform to anchor premium positioning in academic medical centers across Germany and the United States. Philips competes through integrated ultrasound-elastography workflows that streamline biopsy guidance in European breast screening programs.
Elastography imaging measures tissue mechanical properties by tracking deformation responses to applied stress, typically quantifying stiffness in kilopascals through shear-wave propagation or strain-ratio analysis. Ultrasound elastography dominates installed base volumes due to lower capital requirements and real-time operability, while magnetic resonance elastography captures complex cases requiring whole-organ mapping with superior spatial resolution. Diagnostic imaging centers represent the fastest-growing end-user channel as outpatient operators seek to differentiate service lines without full hospital infrastructure.
FDA 510(k) clearance pathways and EMA Medical Device Regulation conformity assessments shape product development timelines and geographic launch sequencing for manufacturers. Japan's PMDA maintains stringent clinical evidence requirements for novel elastography biomarkers, delaying market entry for systems lacking Japanese trial data. Stakeholders must monitor reimbursement coding decisions for liver stiffness measurement in Medicare and national health service frameworks to anticipate volume inflection points.
Market Dynamics
Hospital radiology departments are consolidating procurement around non-invasive liver assessment systems as EMA guidance on hepatic fibrosis staging eliminates invasive biopsy protocols from first-line diagnostic pathways. This regulatory pivot compresses capital cycles and forces vendors to demonstrate reimbursement alignment before purchase authorization.
Growth Catalysts
- EMA Medical Device Regulation conformity:Updated hepatic fibrosis staging protocols mandate elastography as standard-of-care in EU tertiary networks, accelerating system replacement cycles.
- Diagnostic imaging centers:Outpatient operators are expanding service differentiation through shear-wave platforms without full hospital infrastructure overhead.
- Shear-wave propagation technology:Real-time kilopascal quantification enables point-of-care liver assessment, displacing referral-dependent workflows in community settings.
Market Restraints
- Capital intensity of MR elastography:Whole-organ mapping systems require dedicated magnet infrastructure, limiting deployment to academic medical centers with established MRI footprints.
- PMDA clinical evidence requirements:Japan's pharmaceutical and medical device agency demands domestic trial data for novel elastography biomarkers, delaying market entry for non-Japanese manufacturers.
- Ultrasound elastography substitution:Lower-cost strain-ratio systems capture routine cases, compressing margins for premium shear-wave platforms in price-sensitive procurement environments.
Strategic Opportunities
- Indian outpatient diagnostic chains:PLI scheme incentives for medical device manufacturing create localized production pathways for mid-range ultrasound-elastography systems.
- Oncology tumor margin assessment:Tissue stiffness quantification is expanding from liver applications into breast and thyroid nodule characterization.
- Integrated biopsy guidance workflows:Convergence of elastography with real-time needle tracking streamlines European breast screening program protocols.
Industry Challenges
- Reimbursement coding alignment:Medicare and national health service frameworks lack standardized liver stiffness measurement codes, forcing vendors to pursue parallel coverage determinations across jurisdictions.
- MR elastography technologist shortage:Complex whole-organ acquisition protocols require specialized training that outpaces current radiology residency curricula in most markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Elastography Imaging Market |
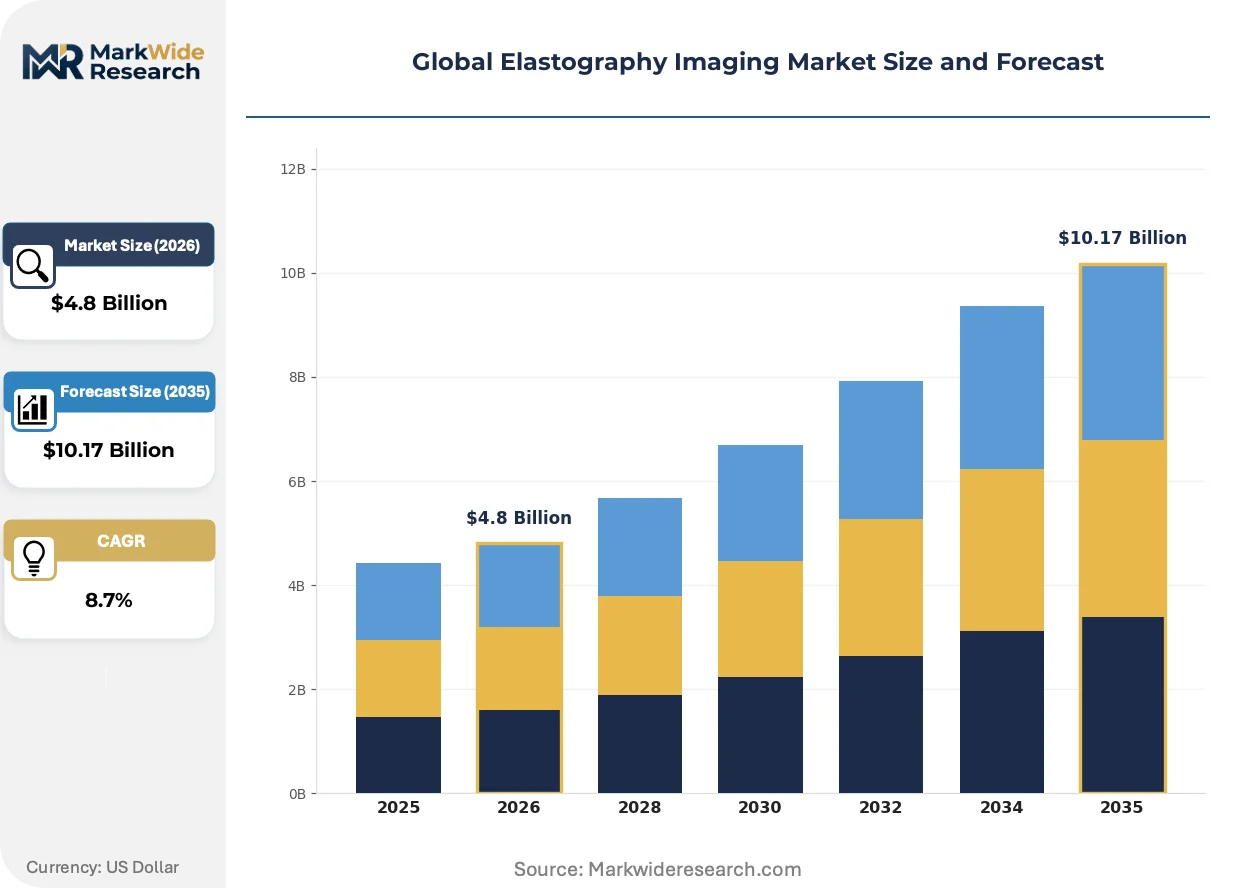
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shear Wave Elastography, Strain Elastography, Transient Elastography, Acoustic Radiation Force Imaging Application: Liver Fibrosis Assessment, Breast Lesion Characterization, Thyroid Nodule Evaluation, Musculoskeletal Diagnosis Technology: Ultrasound Elastography, Magnetic Resonance Elastography, Optical Elastography, Electromechanical Elastography End User: Diagnostic Imaging Centers, Medical Research Institutes, Ambulatory Care Facilities, Specialty Clinics |
| Companies Covered | Canon Medical Systems Corporation, Samsung Medison Co., Ltd., GE Healthcare, Hitachi, Ltd., Mindray Bio-Medical Electronics Co., Ltd., Siemens Healthineers, Fujifilm Holdings Corporation, Esaote SpA, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Elastography Imaging Market Shifts & Advancements
Artificial intelligence integration is compressing acquisition times and standardizing stiffness measurements across operator skill levels. Vendors are embedding machine learning directly into acquisition consoles to reduce inter-observer variability.
Shear-wave elastography is overtaking strain-ratio methods in European breast screening programs due to superior reproducibility. Philips and Siemens Healthineers are retrofitting installed ultrasound bases with shear-wave modules rather than forcing full system replacement. The technology is compressing the competitive window for standalone strain-imaging vendors.
FDA 510(k) clearance pathways are narrowing for novel elastography biomarkers as the agency demands longitudinal clinical validation data. Liver stiffness measurement devices now require prospective outcome studies rather than technical equivalence demonstrations. Academic medical centers in the United States are prioritizing systems with existing FDA-cleared AI-assisted acquisition protocols.
Diagnostic imaging centers are unbundling after-sales service contracts from capital purchases, negotiating per-scan maintenance fees instead of fixed annual agreements. This procurement model shift pressures vendors to demonstrate uptime reliability through transparent remote monitoring dashboards. The trend is most visible in German and Dutch outpatient networks where radiologist-owned centers dominate volume.
Global Elastography Imaging Market Segmentation
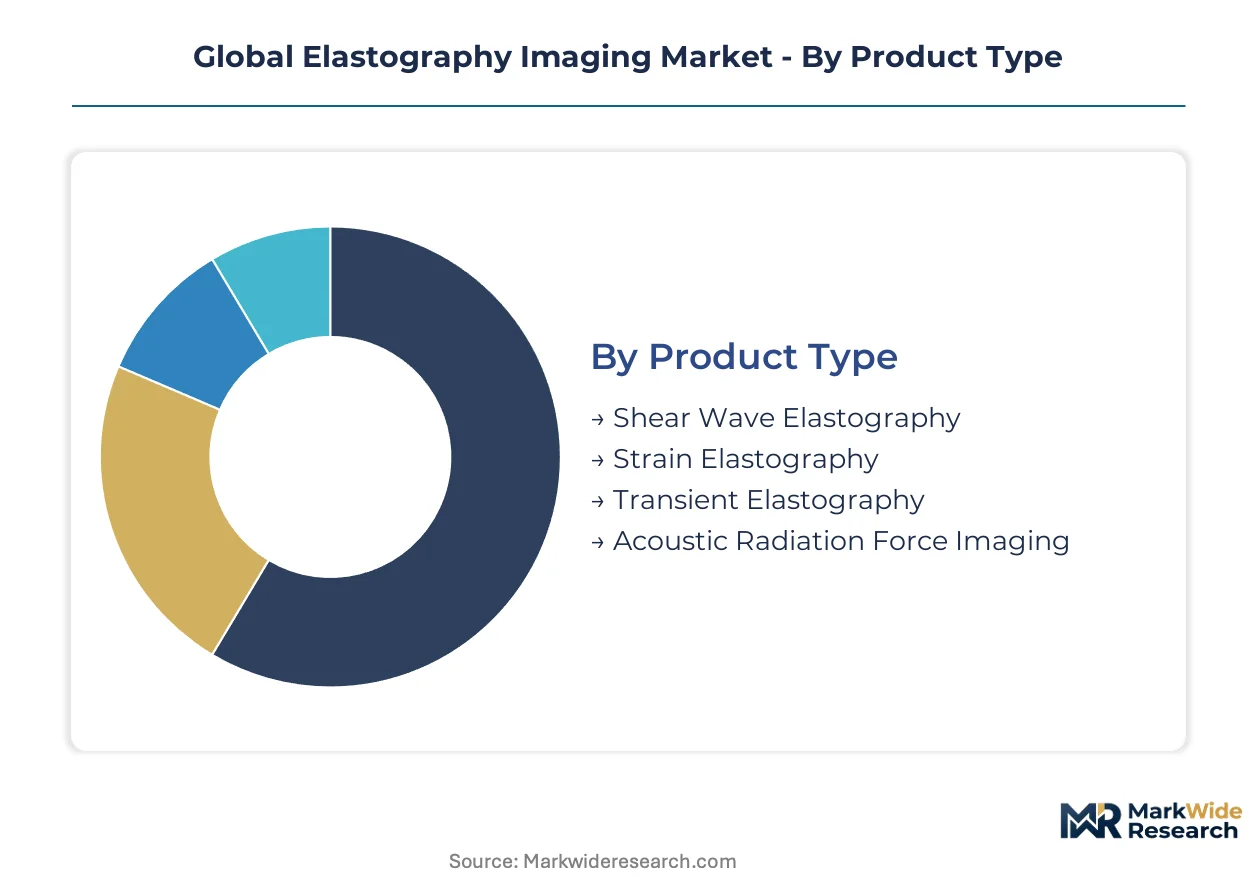
Product differentiation in elastography imaging follows distinct technical architectures that determine capital deployment, operator training requirements, and reimbursement pathways. Each segmentation axis reveals competing pressure points between precision diagnostics and cost-efficient screening workflows.
Product Type:
Technical sophistication separates shear-wave platforms from legacy strain-based systems, with propagation mechanics dictating reproducibility thresholds and clinical acceptance curves.
- Shear Wave Elastography:Quantitative stiffness mapping through acoustic radiation force impulse generates real-time kilopascal measurements with superior inter-operator reliability. German tertiary care networks prioritize these systems for hepatic fibrosis staging following EMA protocol updates that eliminated invasive biopsy from first-line pathways.
- Strain Elastography:Compression-based displacement analysis requires manual tissue depression, yielding qualitative elasticity ratios rather than absolute stiffness values. Cost-sensitive procurement in Indian outpatient diagnostic chains favors these systems despite higher variability, as PLI scheme incentives for localized manufacturing compress acquisition costs for mid-range ultrasound platforms.
- Transient Elastography:FibroScan-class systems deliver dedicated liver assessment through controlled vibration pulses without full imaging capability.
- Acoustic Radiation Force Imaging:ARFI-based point shear-wave measurement enables focused stiffness quantification at specific anatomical depths.
Shear Wave Elastography leads on scale; Transient Elastography leads on momentum in community screening deployments.
Application:
Clinical utility concentrates where tissue stiffness correlates with pathological progression, creating divergent volume trajectories across organ systems.
- Liver Fibrosis Assessment:Hepatic stiffness quantification has displaced percutaneous biopsy as the standard-of-care staging tool in EU tertiary networks, with Siemens Healthineers and Philips anchoring premium positioning through integrated shear-wave modules. Medicare reimbursement coding decisions for non-invasive liver measurement remain fragmented across US jurisdictions, forcing vendors to pursue parallel coverage determinations.
- Breast Lesion Characterization:Tissue stiffness mapping distinguishes malignant from benign masses during European screening program workflows, with real-time needle tracking convergence streamlining biopsy guidance protocols. Philips competes aggressively through ultrasound-elastography integration that reduces procedure time in high-volume radiology departments.
- Thyroid Nodule Evaluation:Elastography reduces fine-needle aspiration rates for indeterminate nodules, particularly in Japanese screening populations where PMDA evidence requirements have delayed novel biomarker introductions.
- Musculoskeletal Diagnosis:Tendon and muscle stiffness assessment remains underdeveloped commercially, constrained by limited reimbursement codes and operator training infrastructure.
Liver Fibrosis Assessment commands installed base concentration; Breast Lesion Characterization climbs the fastest as oncology departments recalibrate imaging portfolios.
Technology:
Modal selection reflects capital intensity thresholds against spatial resolution requirements, with ultrasound platforms dominating volume and magnetic resonance systems capturing complex cases.
- Ultrasound Elastography:Real-time operability and lower capital requirements drive installed base dominance, with shear-wave modules retrofitting existing Philips and Siemens Healthineers ultrasound bases rather than forcing full system replacement. Diagnostic imaging centers in German and Dutch outpatient networks unbundle after-sales contracts in favor of per-scan maintenance fees.
- Magnetic Resonance Elastography:Whole-organ mapping with superior spatial resolution requires dedicated magnet infrastructure, limiting deployment to academic medical centers in the United States and Germany with established MRI footprints. MR elastography technologist shortage constrains expansion as specialized training outpaces radiology residency curricula.
- Optical Elastography:Experimental coherence tomography approaches target ocular and dermatological applications with limited commercial scale.
- Electromechanical Elastography:External vibration systems remain confined to research settings without regulatory clearance pathways.
Ultrasound Elastography leads on scale; Magnetic Resonance Elastography leads on momentum in academic medical center procurement cycles.
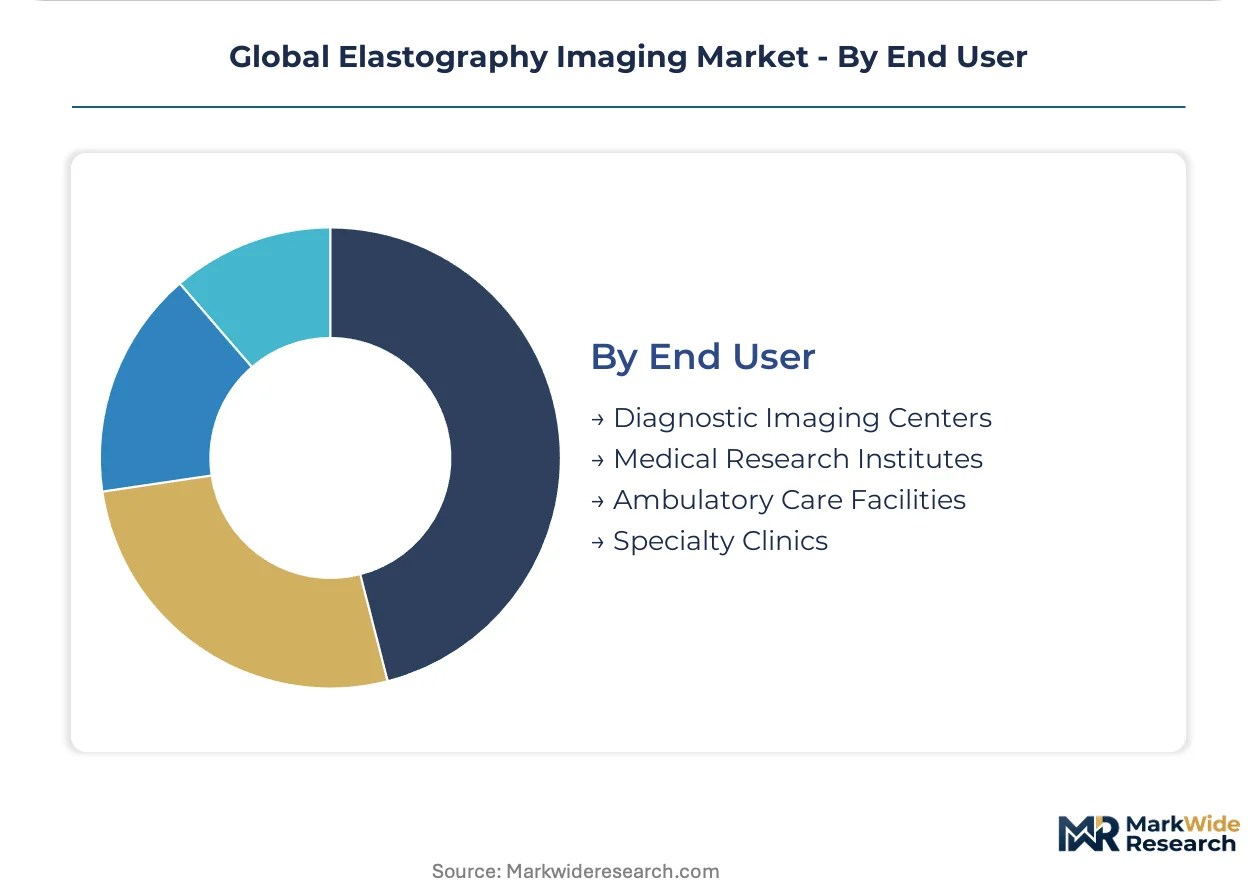
End User:
Facility type determines workflow integration requirements, with outpatient operators seeking service differentiation without full hospital infrastructure overhead.
- Diagnostic Imaging Centers:Outpatient operators represent the fastest-expanding channel, deploying shear-wave platforms to capture community liver assessment volume without referral-dependent workflows. German radiologist-owned centers negotiate transparent remote monitoring dashboards to demonstrate uptime reliability.
- Medical Research Institutes:Academic medical centers in the United States prioritize FDA-cleared AI-assisted acquisition protocols, with machine learning integration compressing inter-observer variability in longitudinal studies.
- Ambulatory Care Facilities:Point-of-care deployment in community settings favors portable ultrasound-elastography systems with simplified operator interfaces.
- Specialty Clinics:Hepatology and endocrinology practices concentrate procedure volume in Japan, where PMDA domestic trial requirements delay system entry for non-Japanese manufacturers.
Diagnostic Imaging Centers lead on scale; Specialty Clinics lead on momentum as hepatology practices consolidate non-invasive assessment capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German tertiary care networks command premium elastography system deployment following EMA hepatic fibrosis protocol updates. Siemens Healthineers and Philips anchor supply relationships across academic medical centers in Munich and Heidelberg.
United States
Academic medical centers in Boston and Houston prioritize FDA-cleared AI-assisted acquisition protocols for MR elastography platforms. Medicare reimbursement fragmentation for liver stiffness measurement forces vendors into parallel coverage determinations across state Medicaid programs. The Mayo Clinic Rochester campus serves as a training hub addressing technologist shortages in whole-organ acquisition protocols.
Germany
Radiologist-owned outpatient centers in Hamburg and Cologne negotiate per-scan maintenance contracts rather than fixed annual service agreements. EMA Medical Device Regulation conformity assessments accelerate system replacement cycles in university hospitals. The Baden-Württemberg medical technology cluster around Stuttgart drives retrofit module development for existing ultrasound bases.
Japan
PMDA domestic trial requirements delay market entry for non-Japanese manufacturers of novel elastography biomarkers. Specialty hepatology practices in Tokyo and Osaka consolidate non-invasive liver assessment capabilities. The Kobe biomedical innovation corridor hosts validation studies for thyroid nodule evaluation protocols.
India
PLI scheme incentives for medical device manufacturing attract localized production of mid-range ultrasound-elastography systems. Outpatient diagnostic chains in Mumbai and Bangalore deploy shear-wave platforms for community liver screening without referral-dependent workflows. The Karnataka medical technology zone near Bangalore supports cost-sensitive procurement for strain-ratio systems.
Netherlands
Transparent remote monitoring dashboards demonstrate uptime reliability in Dutch radiologist-owned centers negotiating unbundled service contracts. Philips integrated ultrasound-elastography workflows dominate breast screening program procurement in Amsterdam and Rotterdam. The Eindhoven health technology cluster advances real-time needle tracking convergence for biopsy guidance protocols.
Global Elastography Imaging Market Competitive Landscape
Portfolio diversification dominates the current landscape as established imaging conglomerates retrofit shear-wave modules onto installed ultrasound bases rather than forcing full system replacement. The vendor structure concentrates around diversified medical technology conglomerates with existing radiology department relationships, compressing competitive windows for standalone elastography specialists. Three archetypes define positioning: full-platform conglomerates with magnetic resonance capabilities, ultrasound-focused mid-tier integrators, and point-of-care portable specialists. Technology licensing agreements and strategic distribution partnerships represent the dominant competitive moves as regulatory clearance timelines extend.
Within the full-platform conglomerate tier, Siemens Healthineers and Philips occupy anchor positions across German and Dutch tertiary networks, while Canon Medical Systems Corporation exemplifies the ultrasound-integrated archetype competing through modular retrofit strategies. These three entities represent distinct geographic and technical positioning without overlapping core market territories.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Samsung Medison Co., Ltd. |
| GE Healthcare |
| Hitachi, Ltd. |
| Mindray Bio-Medical Electronics Co., Ltd. |
| Siemens Healthineers |
| Fujifilm Holdings Corporation |
| Esaote SpA |
| Koninklijke Philips N.V. |
| Others |
Supply & Pricing Matrix
Diagnostic imaging centers in Germany and the Netherlands are unbundling after-sales service contracts from capital purchases, forcing manufacturers to restructure pricing models around per-scan maintenance fees and transparent uptime guarantees rather than fixed annual agreements.
Pricing Analysis
Input-cost pass-through from precision transducer manufacturing and AI-acquisition module development anchors pricing stratification across premium, standard, and economy tiers. Premium shear-wave platforms command substantial markups through FDA-cleared AI-assisted protocols and integrated biopsy guidance, while mid-range ultrasound-elastography systems face cost compression from Indian PLI scheme subsidies. Price differentiation hinges on certification tier and after-sales bundling, with Philips and Siemens Healthineers extracting brand premiums in academic medical centers. Hospital radiology departments exhibit lowest price sensitivity due to EMA-mandated procurement timelines, whereas outpatient diagnostic chains in India prioritize acquisition cost over performance specifications.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for mid-range ultrasound platforms, compelling manufacturers to establish localized assembly operations near Bangalore and Hyderabad. Component manufacturing concentrates in Germany, Japan, and South Korea, with precision piezoelectric crystals and specialized acoustic lenses drawing from established electronics corridors. Raw material dependencies include rare-earth elements for transducer arrays, high-purity silicon for signal processing chips, and specialized polymers for probe housings. Single-source vulnerability from concentrated Japanese suppliers of advanced ceramic materials threatens continuity. Distribution runs through radiology equipment distributors with established hospital system relationships, supplemented by direct procurement channels for large academic medical center networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in AI-integrated acquisition modules and unbundled service contracts, as software-enabled standardization reduces operator training costs while premium-tier positioning captures EMA-mandated replacement cycles.
For Market Incumbents: Extend retrofit module strategies to compress competitive windows for standalone elastography specialists, anchoring hospital relationships through shear-wave upgrades to installed ultrasound bases rather than forcing full system replacement. Defend against ultrasound-elastography substitution by embedding machine learning directly into acquisition consoles to reduce inter-observer variability. Prioritize reimbursement strategy investment to secure Medicare coding alignment for liver stiffness measurement ahead of state Medicaid fragmentation. For New Entrants and Emerging Players: Begin with portable point-of-care systems targeting ambulatory care facilities in community settings, where simplified operator interfaces and lower capital thresholds overcome incumbent brand loyalty. White-space concentration appears in musculoskeletal diagnosis applications, where limited reimbursement codes and training infrastructure have suppressed commercial development. Pursue PLI scheme partnerships with Indian manufacturing zones to access cost-sensitive outpatient diagnostic chains through localized production pathways. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-acquisition software specialists possessing FDA-cleared protocols but lacking capital equipment manufacturing scale. Long-term viability over the projection horizon favors platforms with demonstrated reimbursement traction across multiple jurisdictions. Acquisition targets should exhibit installed base retrofit potential rather than greenfield replacement dependency. Monitor EMA Medical Device Regulation conformity assessment timelines as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Acquisition Protocol Development | FDA 510(k) clearance for machine learning modules compresses inter-observer variability in hepatic fibrosis staging. |
| Shear-Wave Module Retrofit Program | Philips and Siemens Healthineers extend installed base relationships without forcing full ultrasound system replacement. |
| PLI Scheme Manufacturing Localization | Mid-range ultrasound-elastography production in Karnataka medical technology zone captures Indian outpatient diagnostic volume. |
| Per-Scan Maintenance Contract Structure | German radiologist-owned centers negotiate transparent remote monitoring dashboards demonstrating uptime reliability. |
| Reimbursement Strategy Investment | Parallel coverage determinations across Medicare and state Medicaid programs secure liver stiffness measurement codes. |
Research Methodology
Coverage spans Germany, the United States, Japan, India, and the Netherlands, with primary inputs from each market gathered through structured interviews with hospital purchasing committee members, radiology department heads, biomedical engineers, GPO contracts managers, and outpatient diagnostic chain operators. Secondary validation drew from FDA 510(k) clearance databases, EMA Medical Device Regulation conformity assessment records, CMS Medicare reimbursement coding decisions, Japanese PMDA submission filings, and Indian PLI scheme beneficiary disclosures. Bottom-up volume modeling triangulated against top-down market sizing from installed base estimates and replacement cycle analysis.
Granularity-level modeling disaggregated the analysis window by product type, application, technology, and end user, with additional dimensionality from regional regulatory cluster and procurement channel. CAGRs were derived through logistic adoption curve fitting for emerging technologies and replacement cycle analysis for mature platforms. Forecast inputs incorporated EMA protocol update implementation timelines, Medicare coverage determination trajectories, and PMDA domestic trial requirement compliance patterns.
Caveats apply where reimbursement coding fragmentation, MR elastography technologist training bottlenecks, or ultrasound-elastography substitution acceleration could materially shift the outlook beyond modeled boundaries. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Portable MRI Market
Medical Imaging
United States Nuclear Imaging Market
Medical Imaging
Mexico Mammography Market
Medical Imaging
India Nuclear Imaging Market
Medical Imaging
Ultrasound Elastography Systems Market
Medical Imaging
Mexico Digital X-Ray Devices Market
Medical Imaging
Preclinical Brain Imaging Market
Medical Imaging
Automated Contouring Radiotherapy Software Market
Medical Imaging
Canada Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Whole-Body Imaging Market
Medical Imaging
US Diagnostic Imaging Services Market
Medical Imaging
Mobile Computed Tomography Scanners Market
Medical Imaging
Japan Digital Radiology Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
Precision Cancer Imaging Market
Medical Imaging
Europe Digital Radiology Market