
 Japan Magnetic Resonance Imaging Market | 2026-2036
Japan Magnetic Resonance Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Magnetic Resonance Imaging Market Foresight
Gadolinium-based contrast agents are yielding to macrocyclic chelates and iron oxide nanoparticles, a material transition that is realigning procurement economics for scanner operators. Siemens Healthineers leverages its installed base in university hospitals to sustain service revenue streams. Canon Medical Systems anchors domestic manufacturing through its Otawara facility, while Fujifilm Healthcare differentiates via software-integrated diagnostic workflows.
Magnetic Resonance Imaging deploys superconducting magnets generating field strengths from 0.2 to 7.0 Tesla, paired with gradient coil assemblies and radiofrequency detection systems, to produce tomographic images of soft tissue without ionizing radiation. Closed MRI systems dominate hospital procurement due to superior signal-to-noise ratios, though open architectures gain traction in pediatric and claustrophobic patient populations. High-field systems capture the majority of replacement demand, while software solutions represent an expanding margin pool as artificial intelligence-enhanced reconstruction reduces scan times.
PMDA governs device approval pathways under Japan's Pharmaceutical and Medical Device Act, while METI coordinates industrial policy for domestic manufacturing competitiveness. JIS standards specify safety and performance benchmarks that shape product development priorities for vendors serving Japanese institutions. Stakeholders must monitor reimbursement rate adjustments for advanced MRI procedures and the pace of regulatory harmonization between PMDA and FDA standards for AI-enabled diagnostic software.
Market Dynamics
Japan's MRI market is compressing around reimbursement-driven replacement cycles, where PMDA approval pathways and METI industrial policy jointly determine which vendors can capture service revenue from aging installed bases.
Growth Catalysts
- Reimbursement Revisions:Japan's Ministry of Health, Labour and Welfare has adjusted diagnostic imaging fee schedules to favor advanced MRI procedures, accelerating hospital capital expenditure on high-field replacements.
- Aging Demographics:Patient populations in Tokyo and Osaka metropolitan corridors are expanding demand for neurovascular and oncological screening, concentrating scanner utilization in Kanto and Kansai academic centers.
- Contrast Agent Transition:Gadolinium-based formulations are yielding to macrocyclic chelates and iron oxide nanoparticles, creating procurement refresh cycles as operators update injection protocols and software configurations.
Market Restraints
- Helium Supply Concentration:Superconducting magnet cooling depends on helium imports from Qatar and the United States, exposing Japanese operators to price volatility and supply disruption risks.
- Capital Intensity Barriers:Ultra-high-field 7.0 Tesla systems require specialized siting, shielding, and power infrastructure that limits deployment to a narrow tier of university-affiliated institutions.
- Regulatory Harmonization Friction:Divergence between PMDA software validation requirements and FDA 510(k) pathways for AI-enabled reconstruction algorithms delays product launches and fragments vendor development priorities.
Strategic Opportunities
- Open Architecture Penetration:Pediatric hospitals and clinics serving claustrophobic patient populations in Hokkaido and Kyushu remain underpenetrated by open MRI systems, offering expansion runway for specialized configurations.
- AI-Enhanced Workflow Integration:Artificial intelligence reconstruction algorithms are compressing scan durations and reducing motion artifacts, creating differentiation opportunities for vendors bundling software with hardware procurement.
- Domestic Manufacturing Incentives:METI industrial policy coordinates supply chain localization through JIS standards compliance, favoring vendors maintaining captive production facilities within Japanese territory.
Industry Challenges
- Specialized Engineering Talent Scarcity:Superconducting magnet maintenance and cryogenic system servicing require technicians with hybrid physics-electrical engineering competencies that Japanese vocational pipelines underproduce.
- Legacy System Integration Complexity:Hospital information systems and PACS architectures in established Tokyo and Osaka institutions retain proprietary data formats that resist seamless integration with next-generation AI-enabled reconstruction platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Magnetic Resonance Imaging Market |
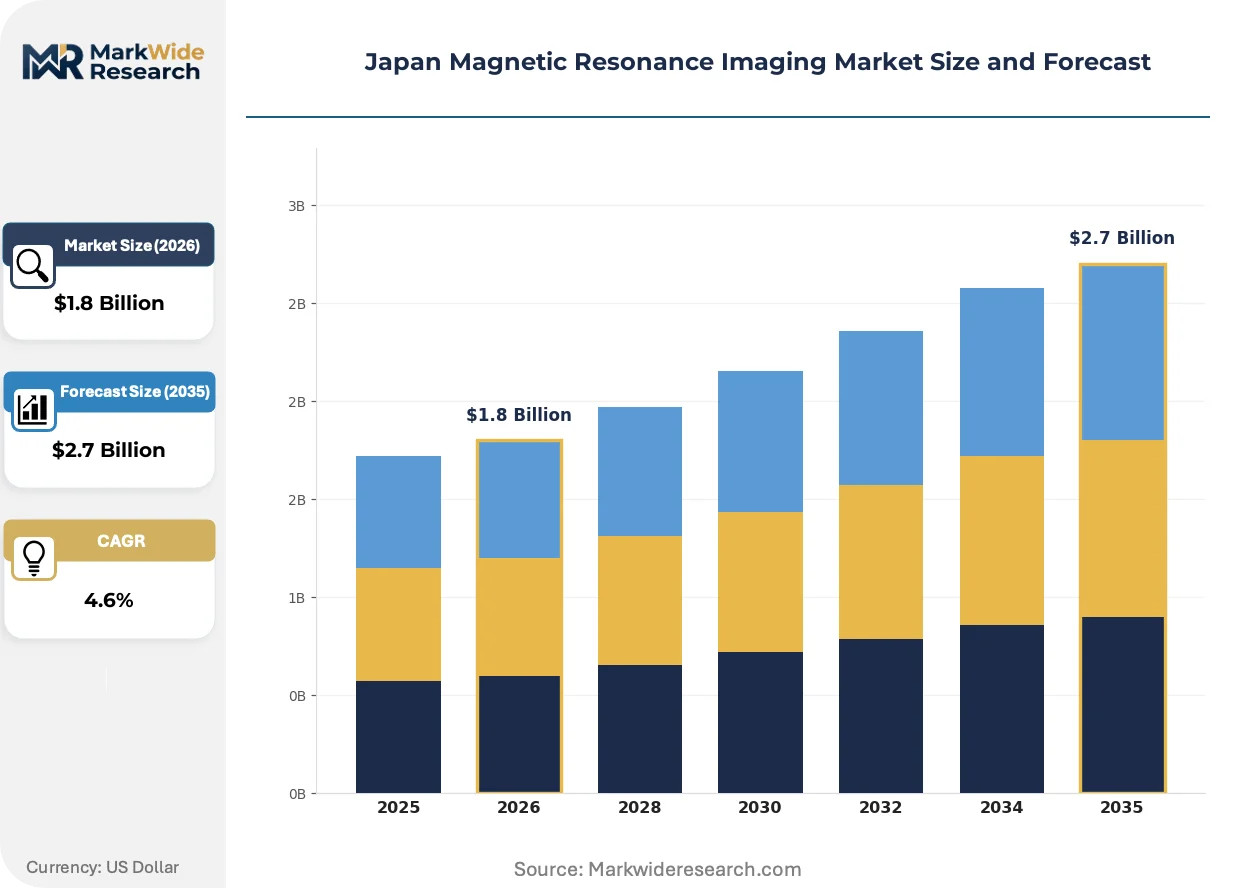
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Functional MRI Technology: High-Field Systems, Low-Field Systems, Ultra-High-Field Systems, Software Solutions Application: Oncology, Neurology, Musculoskeletal, Cardiology End User: Hospitals, Imaging Centers, Research Institutions, Diagnostic Laboratories |
| Companies Covered | Koninklijke Philips, United Imaging Healthcare, Siemens Healthineers, Shimadzu, Esaote, Canon Medical Systems, Fujifilm Healthcare, Hitachi, GE Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Magnetic Resonance Imaging Market Shifts & Advancements
Software-defined diagnostic workflows are displacing hardware-centric value capture, while regulatory pressure on contrast agent safety and artificial intelligence validation protocols restructures vendor competitive priorities.
Compressed sensing reconstruction algorithms are modularizing MRI system architectures by separating image acquisition physics from computational post-processing. Academic medical centers in Osaka and Nagoya are piloting these configurations to halve scan durations without magnet upgrades. This modularization is enabling vendors to unbundle software subscriptions from hardware sales, expanding recurring revenue streams independent of replacement cycles.
PMDA's evolving guidance on AI-enabled diagnostic software under Japan's Pharmaceutical and Medical Device Act is tightening validation requirements for machine learning-based image reconstruction. Vendors must now submit clinical performance data from Japanese patient cohorts, extending approval timelines and favoring incumbents with established regulatory affairs capabilities. Domestic manufacturers with Otawara-based production facilities are responding by pre-integrating software validation into product development roadmaps.
After-sales service contracts are unbundling from equipment financing packages as hospital procurement departments in Kanto region academic centers demand itemized pricing transparency. Third-party service providers specializing in superconducting magnet maintenance are capturing share from OEM service organizations by offering performance-based uptime guarantees. This disintermediation is most visible in Tokyo metropolitan hospitals with dedicated biomedical engineering departments capable of managing multi-vendor service relationships.
Japan Magnetic Resonance Imaging Market Segmentation
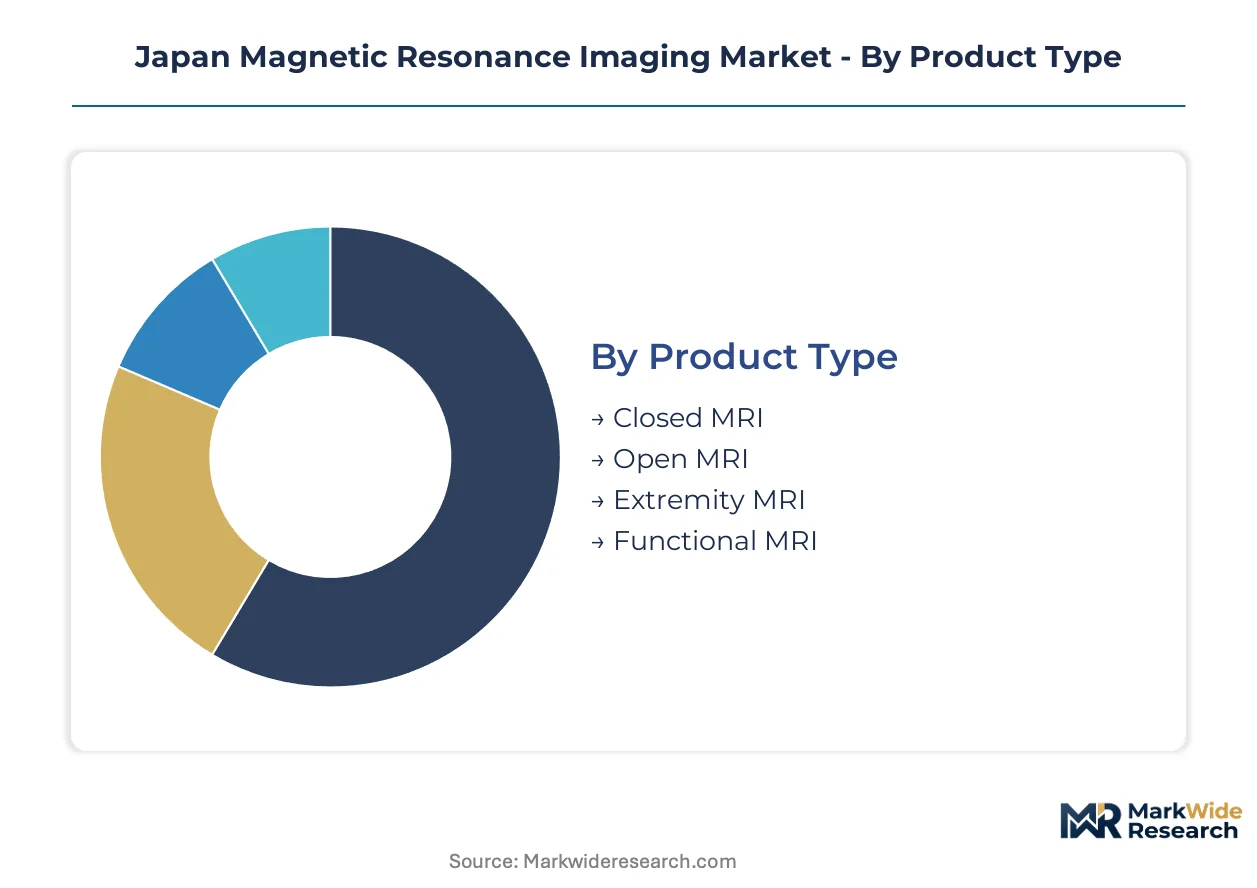
Scanner configurations in Japan stratify sharply between volume-oriented hospital installations and specialized research deployments. Procurement decisions hinge on reimbursement eligibility, helium infrastructure access, and the technical specifications required for aging-population diagnostics.
Product Type:
Closed-bore systems dominate procurement economics due to signal-to-noise performance, while open architectures address accessibility gaps in pediatric and claustrophobic patient populations.
- Closed MRI:Superconducting cylindrical bore designs generate field strengths from 1.5 to 3.0 Tesla, delivering diagnostic precision for neurovascular and oncological screening. Tokyo and Osaka academic medical centers concentrate replacement demand here, driven by Ministry of Health, Labour and Welfare reimbursement revisions favoring advanced diagnostic imaging.
- Open MRI:Permanent magnet or resistive coil configurations eliminate enclosed tunnel geometry, reducing patient anxiety and enabling pediatric positioning. Hokkaido and Kyushu regional hospitals show underpenetrated demand for these systems, particularly for claustrophobic and bariatric patient protocols.
- Extremity MRI:Dedicated limb-focused scanners with compact footprints and lower field strengths serve orthopedic outpatient workflows in Kansai region sports medicine clinics.
- Functional MRI:Blood-oxygen-level-dependent imaging capabilities map neural activation patterns for pre-surgical planning and cognitive research at University of Tokyo and Osaka University facilities.
Closed MRI leads on scale; functional MRI leads on momentum.
Technology:
Field strength tiers separate routine diagnostic installations from research-grade capital commitments, with software layers emerging as independent revenue pools.
- High-Field Systems:1.5 Tesla and 3.0 Tesla superconducting platforms constitute the replacement cycle core, balancing image resolution against siting infrastructure requirements. Kanto region hospitals anchor installed base expansion here, responding to aging demographic demand for neurovascular screening.
- Low-Field Systems:Sub-1.0 Tesla permanent magnet designs reduce helium dependency and shielding costs for rural clinics and mobile screening units. Kyushu prefectures deploy these where specialized engineering talent for cryogenic maintenance remains scarce.
- Ultra-High-Field Systems:7.0 Tesla research platforms require dedicated Faraday cage construction and liquid helium supply security. National Center for Neurology and Psychiatry in Kodaira and select Osaka University laboratories represent the narrow addressable market.
- Software Solutions:Artificial intelligence reconstruction algorithms and compressed sensing protocols unbundle from hardware sales, creating subscription revenue streams for scan-time reduction and motion artifact correction.
High-field systems command installed base volume; software solutions are expanding most quickly.
Application:
Clinical use cases track Japan's disease burden distribution, with oncological and neurological indications consuming the majority of scanner utilization hours.
- Oncology:Tumor staging and treatment response monitoring drive high-field system utilization in Tokyo metropolitan cancer centers. Contrast agent transitions from gadolinium-based to macrocyclic chelates reshape injection protocols here.
- Neurology:Cerebrovascular disease screening and dementia diagnostics concentrate demand among Kansai region academic hospitals serving elderly populations.
- Musculoskeletal:Sports injury and degenerative joint disease imaging flows through orthopedic specialty clinics in Osaka and Nagoya metropolitan corridors.
- Cardiology:Cardiac MRI for ischemia and cardiomyopathy assessment remains underdeveloped relative to CT angiography, constrained by reimbursement rate disparities and scan duration requirements.
Oncology leads on scale; cardiology leads on momentum.
End User:
Institutional purchasing power and technical sophistication determine vendor access and service contract structures across the Japanese market.
- Hospitals:Integrated delivery networks in Tokyo and Osaka metropolitan areas command bulk procurement leverage, negotiating itemized pricing transparency for equipment and service unbundling.
- Imaging Centers:Outpatient-focused operators in Kanto region suburbs optimize throughput per scanner hour, prioritizing software-integrated workflow solutions.
- Research Institutions:University-affiliated facilities in Nagoya and Fukuoka access METI industrial policy incentives for domestic manufacturing partnerships and AI validation collaboration.
- Diagnostic Laboratories:Chain-operated testing networks represent emerging demand for compact, low-field systems in community-based screening configurations.
Hospitals lead on scale; diagnostic laboratories lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kanto metropolitan corridor anchors Japan's MRI installed base concentration, with Tokyo academic medical centers driving ultra-high-field adoption and service revenue capture for domestic and multinational vendors alike.
Kanto/Tokyo
Neurovascular screening demand from aging patient populations and university hospital research budgets sustain replacement cycles for 3.0 Tesla systems. METI coordinates domestic manufacturing incentives through JIS standards compliance requirements. National Center for Neurology and Psychiatry in Kodaira pilots 7.0 Tesla platforms for pre-surgical planning applications.
Kansai/Osaka
Oncological diagnostics and dementia screening concentrate scanner utilization among Osaka metropolitan corridor hospitals serving elderly demographics. PMDA approval pathways for AI-enabled reconstruction software favor established vendors with regulatory affairs capabilities. Osaka University laboratories anchor ultra-high-field research deployment alongside commercial diagnostic operators.
Chubu/Nagoya
Musculoskeletal imaging flows through orthopedic specialty clinics responding to sports injury and degenerative joint disease prevalence. Ministry of Health, Labour and Welfare reimbursement revisions for advanced MRI procedures accelerate capital expenditure in Aichi prefecture medical centers. Nagoya University-affiliated facilities access METI industrial policy partnerships for domestic manufacturing collaboration.
Kyushu
Claustrophobic and pediatric patient populations drive underpenetrated demand for open MRI architectures in Fukuoka and surrounding prefectures. Helium supply logistics constraints favor low-field permanent magnet systems where cryogenic maintenance talent remains scarce. Regional hospitals optimize procurement around reduced shielding and power infrastructure requirements.
Hokkaido
Rural clinic networks and mobile screening units deploy compact low-field systems for community-based diagnostic access. JIS safety and performance benchmarks shape product development priorities for vendors serving dispersed patient populations. Sapporo metropolitan hospitals concentrate the region's high-field replacement demand.
Japan Magnetic Resonance Imaging Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and service network density, producing a tiered structure where installed base ownership determines recurring revenue capture. Siemens Healthineers and GE Healthcare leverage multinational scale against Canon Medical Systems and Fujifilm Healthcare domestic manufacturing advantages. Three archetypes dominate: integrated diagnostics conglomerates with captive magnet production, precision engineering specialists with software-integrated workflows, and multinational health technology platforms with service unbundling expertise. Competitive moves concentrate on AI-enabled reconstruction algorithm development and after-sales contract restructuring toward performance-based uptime guarantees.
Among Japan-based healthcare technology groups, Canon Medical Systems and Fujifilm Healthcare exemplify the integrated diagnostics archetype through Otawara facility manufacturing and software-embedded procurement offerings. Siemens Healthineers anchors the multinational platform position. These three occupy distinct competitive vectors: domestic manufacturing compliance, AI validation pathway navigation, and service revenue capture from aging installed bases.
| Leading Market Players |
|---|
| Koninklijke Philips |
| United Imaging Healthcare |
| Siemens Healthineers |
| Shimadzu |
| Esaote |
| Canon Medical Systems |
| Fujifilm Healthcare |
| Hitachi |
| GE Healthcare |
| Others |
Supply & Pricing Matrix
Cryogenic engineering talent scarcity in the Kanto region widens pricing spreads between premium service-bundled systems and economy-tier permanent magnet configurations. Labor-cost differentials between Tokyo metropolitan maintenance specialists and Kyushu regional technicians translate directly into tiered procurement economics for hospital buyers.
Pricing Analysis
Helium cost pass-through from Qatar and United States supply sources dominates pricing volatility for superconducting platforms. Three-tier pricing structure across premium, standard, and economy levels separates 7.0 Tesla research systems from 3.0 Tesla hospital replacements and sub-1.0 Tesla rural clinic configurations. Price differentiation hinges on JIS certification tier and after-sales service bundling intensity. Cost compression in economy-tier permanent magnet systems is intensifying because domestic manufacturers exploit Otawara facility localization. Academic medical centers show least price sensitivity; diagnostic laboratories in regional prefectures exhibit highest procurement cost consciousness.
Supply Chain Analysis
Freight costs for liquid helium cryogenic containers from Qatar and the United States expose Japanese operators to bunker fuel surcharge volatility. Magnet superconductor niobium-titanium wire draws from Japan, Germany, and United States fabrication facilities. Gradient coil assemblies rest on copper winding supply from China and South Korea. Single-source vulnerability concentrates in United States helium export infrastructure. Distribution runs through Siemens Healthineers and Canon Medical Systems captive service networks with third-party disintermediation emerging in Tokyo biomedical engineering departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's MRI market functions as a regulatory compounder where PMDA reimbursement revisions for advanced diagnostic imaging procedures accelerate capital replacement cycles and reshape vendor competitive priorities.
For Market Incumbents: Hedge against third-party service disintermediation by restructuring after-sales contracts toward performance-based uptime guarantees with itemized pricing transparency. Canon Medical Systems and Siemens Healthineers should deepen backward integration into superconducting magnet maintenance training pipelines to offset specialized engineering talent scarcity threatening service revenue capture. For New Entrants and Emerging Players: AI-enhanced reconstruction algorithms offer technology-first wedge positioning against hardware-incumbent bundling practices. Target underpenetrated open MRI demand in Hokkaido and Kyushu pediatric hospital networks. Pursue software-only procurement pathways that bypass PMDA hardware validation timelines through METI industrial policy AI validation partnerships. For Investors and Strategic Acquirers: Diagnostic imaging conglomerates with captive magnet production are the most active acquirer in this space, consolidating software-defined workflow capabilities. Long-term viability centers on recurring revenue share from aging installed base service relationships rather than replacement cycle dependence. Monitor PMDA-FDA regulatory harmonization progress on AI-enabled reconstruction as inflection indicator for software vendor valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | AI reconstruction algorithms bundled with hardware procurement compress scan durations for Tokyo academic centers. |
| Reimbursement Strategy | Alignment with Ministry of Health, Labour and Welfare fee schedule revisions accelerates high-field replacement demand. |
| Hospital System Partnership | Integrated delivery networks in Osaka negotiate itemized service unbundling from equipment financing packages. |
| Backward Integration | Otawara facility localization captures METI industrial policy incentives for domestic JIS standards compliance. |
| Regulatory Harmonization | PMDA-FDA convergence on AI validation protocols determines software vendor launch timeline competitiveness. |
Research Methodology
Multiple input streams — hospital procurement committee interviews, biomedical engineering director consultations, GPO contracts analysis, and PMDA filing record review — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged hospital purchasing managers, MRI service technicians, radiology department heads, and METI industrial policy officers across Kanto, Kansai, and Kyushu regions. Secondary validation incorporated Ministry of Health, Labour and Welfare reimbursement schedule publications, JIS standards documentation, and vendor SEC disclosure segments.
Historical shipment data cross-referenced against expert panel input established baseline installed base estimates across the projection horizon. Segmentation dimensions modeled include field strength tier, product architecture type, clinical application area, and end-user institutional category. CAGRs derived from replacement cycle velocity analysis weighted against aging demographic demand curves. Forecast inputs incorporated helium supply price trajectories and PMDA approval timeline distributions for AI-enabled software.
The model holds under stable reimbursement policy conditions; deviation in Ministry of Health, Labour and Welfare fee schedule adjustments or METI domestic manufacturing incentive revisions would shift replacement cycle timing assumptions. Forecasts reflect documented assumptions regarding regulatory harmonization pace and contrast agent safety protocol evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Japan Computed Tomography Market
Medical Imaging
Mexico Nuclear Imaging Market
Medical Imaging
Pediatric Imaging Market
Medical Imaging
Australia Mammography Market
Medical Imaging
Japan Diagnostic Imaging Equipment Market
Medical Imaging
Image-Guided Biopsy Market
Medical Imaging
Europe Open System MRI Market
Medical Imaging
Asia-Pacific Digital Pathology Market
Medical Imaging
Medical Imaging Agent-Producing System Market
Medical Imaging
Germany Magnetic Resonance Imaging Market
Medical Imaging
Global Nuclear Imaging Equipment Market
Medical Imaging
Pre-Clinical Imaging System Market
Medical Imaging
New Born Eye Imaging Systems Market
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
Weightbearing Low Dose (CT) Systems Market
Medical Imaging
Industrial X-Ray Machine Market