
 X-Ray Film Market | 2026-2036
X-Ray Film Market Size, Share, and Industry Trends Forecast 2026-2036
X-Ray Film Market Outlook
Radiologic technologist shortages across mature healthcare systems is unwinding the pace of digital radiology conversion, preserving residual demand for analog film workflows. Fujifilm Holdings Corporation leverages its vertically integrated silver halide supply chain to sustain cost leadership in traditional film manufacturing. Agfa-Gevaert NV anchors European hospital procurement through long-term service contracts that bundle film with processing chemistry. Carestream Health Inc. competes by specializing in veterinary and industrial niches where digital upgrade cycles stretch longer than in human medical imaging.
X-ray film comprises a flexible polyester base coated with silver halide emulsion that darkens proportionally to ionizing radiation exposure, enabling latent image formation for subsequent chemical processing into visible radiographs. Medical imaging applications dominate volume consumption as hospitals and diagnostic centers retain film for specific orthopedic and mammography protocols where resolution requirements exceed budget-tier digital detectors. Traditional film maintains structural importance in dental imaging practices serving price-sensitive patient populations, while industrial inspection represents a faster-growing application segment driven by pipeline integrity mandates and aerospace component certification requirements.
FDA diagnostic imaging quality standards govern film manufacturing specifications and processing chemistry compositions in the United States, while ISO 7004 and IEC 60601 frameworks establish international baseline performance criteria for silver halide systems. The EU MDR and associated CE marking requirements for medical devices influence film processor validation protocols and traceability documentation across European distribution channels. Stakeholders must monitor regulatory divergence between digital radiology equipment approval pathways and enduring film-based diagnostic requirements to calibrate portfolio allocation between legacy chemistry and detector technology investments.
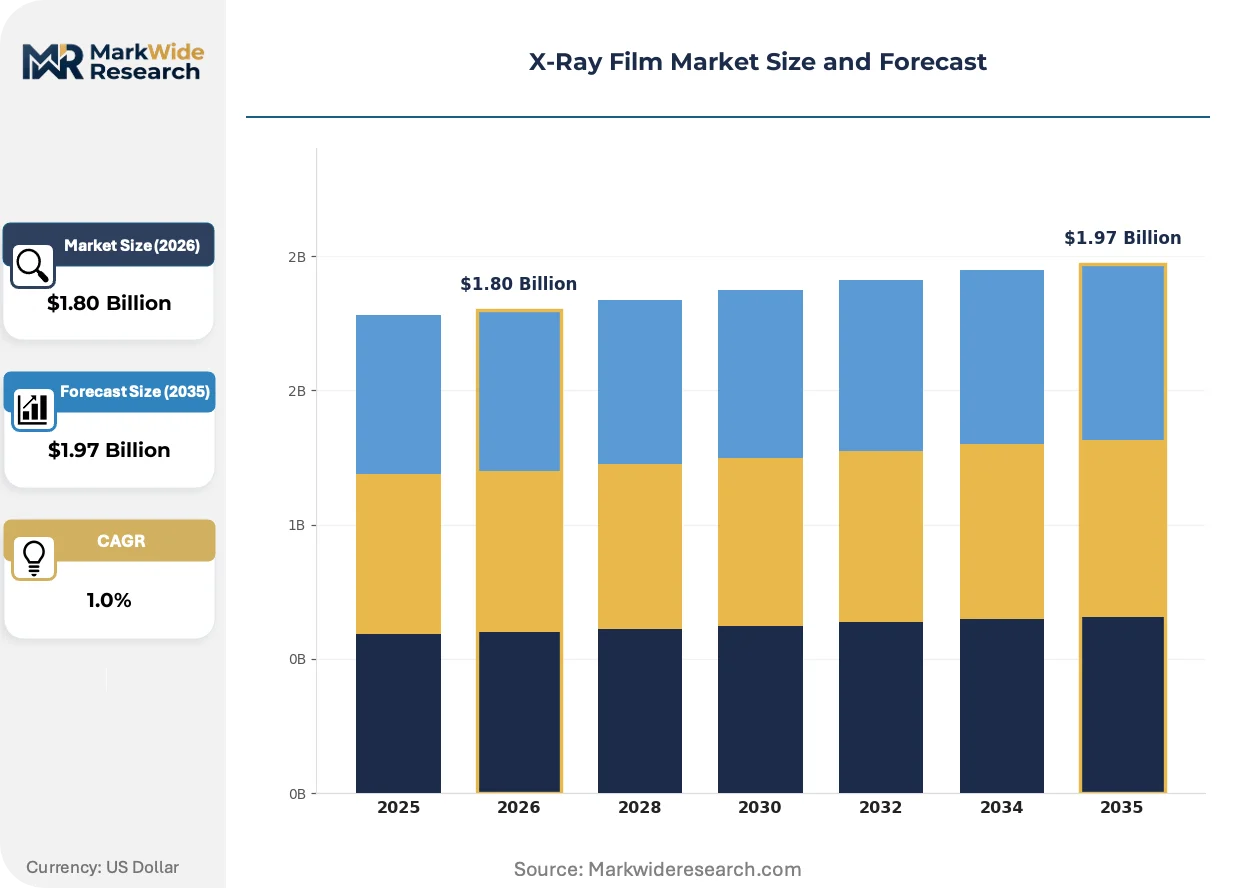
Market Dynamics
The X-Ray Film Market faces sustained pressure from digital radiology conversion, yet radiologic technologist shortages across mature healthcare systems preserve residual analog workflows. Silver halide supply chain concentration and veterinary retention of film-based systems create countervailing stabilization forces against terminal decline.
Growth Catalysts
- FDA Diagnostic Imaging Standards:Quality mandates for mammography and orthopedic protocols sustain film procurement in US hospital networks where digital detector resolution falls short of diagnostic thresholds.
- Veterinary Retention Patterns:Rural North American clinics and price-sensitive dental practices maintain film workflows due to extended digital upgrade cycles and capital constraints.
- Industrial NDT Expansion:Pipeline integrity mandates and aerospace component certification requirements drive faster-growing consumption in non-destructive testing applications.
Market Restraints
- Silver Price Volatility:Film manufacturing cost structures remain exposed to precious metal commodity swings, compressing margin buffers for producers without captive mining assets.
- Digital Detector Substitution:Flat-panel radiography and computed radiography systems displace film in human medical imaging, constraining volume growth in the largest historical consumption segment.
- Processing Chemistry Regulations:EPA effluent standards and EU REACH restrictions on silver thiosulfate disposal increase compliance burdens for film processing facilities.
Strategic Opportunities
- India Tier-2 Infrastructure:Public health expansion in secondary cities outpaces digital radiology budgets, creating sustained procurement windows for cost-effective film systems.
- Service Contract Bundling:Long-term chemistry supply agreements anchored to film volumes lock in recurring revenue streams across European hospital procurement.
- Industrial-Aerospace Convergence:Composite material inspection requirements and additive manufacturing quality protocols expand addressable demand beyond traditional medical applications.
Industry Challenges
- Radiologic Technologist Shortages:Training pipeline deficits in the US and EU delay digital workflow transitions, forcing continued reliance on analog systems that require specialized darkroom expertise.
- Dual Compliance Architecture:Manufacturers must simultaneously maintain ISO 7004 film specifications and IEC 60601 digital equipment standards, doubling validation costs.
- Processor Fleet Obsolescence:Aging automatic film processing infrastructure lacks replacement parts availability, threatening service continuity for retained film operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X-Ray Film Market |
| Market Size in 2026 | $1.80 Billion |
| Market Size in 2035 | $1.97 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Film, Traditional Film, Screen Film, Non-Screen Film Application: Medical Imaging, Dental Imaging, Industrial Inspection, Security Screening End User: Hospitals, Diagnostic Centers, Research Laboratories, Clinics Distribution Channel: Direct Sales, Online Retail, Medical Supply Distributors, Wholesalers |
| Companies Covered | Fujifilm Holdings Corporation, Agfa-Gevaert NV, Carestream Health Inc., Konica Minolta Inc., Sony Corporation, Nantong Lide Xray Film Co., Ltd, Foma Bohemia Ltd., Codonics Inc., China Lucky Group Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X-Ray Film Market Strategic Shifts
Digital radiology hardware is compressing addressable demand, yet hybrid workflow persistence and industrial inspection digitization create technology evolution vectors. Regulatory divergence between film-based and digital diagnostic pathways shapes competitive positioning.
Computed radiography phosphor plate systems are displacing traditional screen-film combinations in orthopedic and general radiography departments. Mid-tier hospitals in India and Southeast Asia adopt these transitional technologies to bridge resolution requirements and budget constraints. This displacement pattern preserves silver halide demand only in specialized mammography and extremity imaging protocols where spatial resolution thresholds remain unmatched.
EU MDR medical device regulations impose enhanced traceability documentation and post-market surveillance obligations on film processor manufacturers. CE marking validation protocols now require clinical evidence packages that previously applied only to digital equipment. European distribution channels respond by consolidating supplier relationships toward vertically integrated manufacturers capable of unified chemistry-film-processor compliance.
Diagnostic procurement in US hospital networks unbundles film supply from historical chemistry service contracts. Group purchasing organizations negotiate direct film sourcing while outsourcing processing to centralized regional laboratories. This channel restructuring concentrates volume among distributors with logistics scale, compressing margins for local independent suppliers serving single-site imaging centers.
X-Ray Film Market Segmentation
X-ray film segmentation reveals divergent channel economics between medical and industrial applications. Product specifications, procurement protocols, and end-user sophistication create distinct commercial pathways that manufacturers must navigate simultaneously.
Product Type:
Channel mix varies sharply by emulsion chemistry—traditional and screen film flow through established medical supply distributors with bundled chemistry contracts, while digital-compatible formats increasingly route through direct OEM partnerships.
- Traditional Film:Silver halide emulsion on polyester base delivers diagnostic resolution for mammography and extremity imaging where spatial precision exceeds budget detector capabilities. Demand concentrates in India's tier-2 cities where public health infrastructure expansion outpaces digital radiology capital budgets, sustained by FDA quality mandates for specific orthopedic protocols.
- Screen Film:Intensifying screen combinations reduce radiation dose while maintaining image clarity for general radiography departments. Veterinary clinics across rural North America retain these systems due to extended digital upgrade cycles and capital constraints, creating residual volume streams.
- Digital Film:Laser-imagable and thermal substrates bridge analog workflows with PACS integration for hybrid departments transitioning equipment fleets.
- Non-Screen Film:Direct-exposure formats serve industrial NDT applications requiring fine grain structure for crack detection in pipeline welds and aerospace castings.
Traditional film dominates installed base. Non-screen film is where expansion concentrates.
Application:
Cost tier stratification separates premium diagnostic segments from price-sensitive screening volumes, with industrial applications commanding margin premiums through specialized certification requirements.
- Medical Imaging:Hospitals and diagnostic centers deploy film for mammography and pediatric protocols where ALARA principles intersect with resolution thresholds. US hospital networks sustain procurement through FDA diagnostic imaging standards that preserve film workflows where digital detector performance falls short.
- Industrial Inspection:Pipeline integrity mandates under EPA and international pressure vessel codes drive non-destructive testing consumption. Aerospace component certification requirements for additive manufacturing quality protocols expand addressable demand beyond traditional medical applications.
- Dental Imaging:Price-sensitive practices serving uninsured patient populations retain film-based panoramic and intraoral systems.
- Security Screening:Explosives detection and cargo inspection applications utilize high-speed film processing for throughput-critical checkpoint operations.
Medical imaging commands volume leadership. Industrial inspection exhibits the steepest expansion trajectory.
End User:
Customer type determines procurement complexity—hospitals negotiate enterprise contracts with chemistry bundling, while independent clinics purchase through distributor networks with shorter replenishment cycles.
- Hospitals:Integrated delivery networks leverage group purchasing organization scale to unbundle film supply from historical processing service contracts. Group purchasing organizations negotiate direct film sourcing while outsourcing processing to centralized regional laboratories, concentrating volume among distributors with logistics scale.
- Diagnostic Centers:Specialized imaging facilities retain film for specific orthopedic and mammography protocols where resolution requirements exceed budget-tier digital detectors.
- Clinics:Rural and price-sensitive settings maintain analog workflows due to radiologic technologist shortages that delay digital transition.
- Research Laboratories:Academic medical centers utilize film for comparative studies and archival documentation requirements.
Hospitals anchor procurement volume. Diagnostic centers concentrate margin opportunity.
Distribution Channel:
Volume scale determines channel selection—wholesalers and medical supply distributors handle replenishment for retained film operations, while direct sales capture industrial NDT contracts with specialized technical service requirements.
- Medical Supply Distributors:Regional logistics networks serve retained hospital film operations with just-in-time chemistry replenishment and processor maintenance bundling. Long-term service contracts anchored to film volumes lock in recurring revenue streams across European hospital procurement.
- Direct Sales:OEM and manufacturer-direct channels capture industrial inspection contracts requiring application engineering support and certification documentation. EU MDR medical device regulations impose enhanced traceability documentation obligations that favor vertically integrated manufacturers capable of unified compliance.
- Wholesalers:Aggregated procurement serves independent imaging centers and veterinary practices with standardized product configurations.
- Online Retail:E-commerce penetration remains limited due to cold chain and chemistry compatibility requirements for professional-grade film.
Medical supply distributors retain channel dominance. Direct sales is where value capture concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. The United States retains film for specialized diagnostic protocols, while India sustains volume through infrastructure expansion and Germany anchors European procurement through bundled service contracts.
United States
FDA diagnostic imaging standards preserve film workflows for mammography and orthopedic applications where digital detector resolution falls short. EPA effluent regulations constrain processing chemistry disposal, raising operational costs for retained analog operations. Texas and Florida hospital networks concentrate procurement through group purchasing organizations that unbundle film supply from historical service contracts.
India
Public health infrastructure expansion in tier-2 cities outpaces digital radiology capital budgets, sustaining cost-effective film procurement. CDSCO quality standards govern diagnostic imaging specifications across hospital networks and diagnostic chains. Maharashtra and Karnataka medical device clusters anchor distribution logistics for retained screen-film systems serving price-sensitive patient populations.
Germany
EU MDR medical device regulations impose enhanced traceability documentation on film processor manufacturers, consolidating supplier relationships toward vertically integrated providers. CE marking validation protocols now require clinical evidence packages comparable to digital equipment standards. Bavaria and North Rhine-Westphalia hospital procurement anchors European chemistry bundling contracts.
Japan
PMDA oversight maintains stringent manufacturing specifications for silver halide emulsion systems serving domestic diagnostic networks. METI industrial policy supports precision manufacturing quality protocols that extend to non-destructive testing applications. Kanto and Kansai metropolitan imaging centers retain hybrid workflows bridging analog and digital radiology transitions.
Brazil
ANVISA regulatory frameworks govern medical device quality standards for diagnostic imaging equipment across public and private healthcare networks. Price-sensitive dental practices and veterinary clinics sustain residual film demand amid delayed digital conversion cycles. São Paulo and Rio de Janeiro diagnostic chains concentrate procurement volume for retained analog systems.
X-Ray Film Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. The upper tier commands chemistry-film-processor bundling relationships and captive silver halide supply chains. The specialist tier occupies veterinary, dental, and industrial niches where extended upgrade cycles preserve addressable demand. Dominant competitive moves include long-term service contract anchoring and geographic expansion into tier-2 infrastructure markets.
Among Asia-Pacific-based manufacturers, Fujifilm Holdings Corporation exemplifies the integrated archetype through upstream control over emulsion chemistry and polyester substrate production. Agfa-Gevaert NV anchors European positioning through bundled hospital procurement contracts spanning film, processing chemistry, and equipment validation. Carestream Health Inc. occupies the specialist tier, representing niche-focused positioning in veterinary and industrial segments where digital substitution lags human medical imaging.
| Leading Market Players |
|---|
| Fujifilm Holdings Corporation |
| Agfa-Gevaert NV |
| Carestream Health Inc. |
| Konica Minolta Inc. |
| Sony Corporation |
| Nantong Lide Xray Film Co., Ltd |
| Foma Bohemia Ltd. |
| Codonics Inc. |
| China Lucky Group Corp. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at silver halide emulsion plants in Japan and Belgium shapes price floors across medical and industrial film tiers, concentrating margin leverage among manufacturers with backward integration into precious metal refining and polyester substrate production. Long-term chemistry bundling contracts in European hospital networks insulate integrated suppliers from spot silver volatility while compressing margins for distributors dependent on third-party processing infrastructure.
Pricing Analysis
Contract-based long-term offtake agreements dominate hospital procurement, with European service contracts bundling film volumes to chemistry supply spanning three-to-five year terms. Price differentiation rests on FDA certification tier and volume scale, with mammography-grade emulsions commanding premiums over general radiography stock. Cost compression in standard-tier screen film is intensifying because Indian tier-2 procurement consolidates toward regional distributors with logistics scale. Price-sensitive independent veterinary clinics in rural North America resist premium tier migration, while least-sensitive aerospace NDT buyers prioritize traceability documentation over unit cost.
Supply Chain Analysis
Japan and Belgium anchor silver halide emulsion manufacturing, with China and India expanding coating capacity for regional medical film demand. Raw material dependencies draw from silver bullion markets, polyester substrate feedstock, and gelatin chemistry formulations. Single-source vulnerability concentrates in refined silver supply from mining consortiums in Peru and Mexico. Distribution runs through medical supply distributors with cold-chain logistics for chemistry compatibility, supplemented by direct sales channels for industrial NDT contracts requiring certification documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection centers on PACS interoperability standards that threaten to commoditize film-processor combinations while creating data-layer value capture opportunities for integrated diagnostics vendors.
For Market Incumbents: Compound chemistry-film bundling relationships into software-enabled service contracts that capture recurring revenue from retained hybrid workflows. Defend against flat-panel radiography substitution by securing FDA mammography protocol exemptions through resolution benchmarking studies. Prioritize captive silver refining capacity to buffer margin compression from precious metal volatility.
For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships unlocks European hospital procurement channels currently consolidated around legacy suppliers. Target India's tier-2 public health infrastructure expansion, where digital radiology capital constraints preserve film procurement windows. Pursue industrial-aerospace NDT segments with additive manufacturing quality protocols as the most penetrable white-space application.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with unified chemistry-film-processor compliance capabilities over pure-play film coaters. Long-term viability hinges on industrial inspection diversification beyond terminal medical decline. Watch radiologic technologist training pipeline recovery as the inflection signal for digital transition acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver Refining | Captive precious metal supply buffers Fujifilm and Agfa-Gevaert against commodity volatility in emulsion production. |
| CE Marking Pathway Investment | EU MDR traceability requirements favor unified compliance manufacturers over fragmented processor suppliers. |
| Hospital System Partnership | Group purchasing organization consolidation in Texas and Florida concentrates volume among logistics-scale distributors. |
| Industrial NDT Certification Program | Pipeline integrity mandates under EPA regulations expand aerospace and energy inspection addressable demand. |
| Software Companion Development | PACS integration for hybrid workflows preserves film relevance in orthopedic and mammography diagnostic protocols. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases maintained by group purchasing organizations. Primary interviews engaged radiologic technologist training program directors, biomedical equipment procurement managers at integrated delivery networks, silver halide chemistry plant operations heads, and veterinary clinic practice owners across rural North America. Secondary validation drew from customs trade data for silver halide emulsion imports, SEC 10-K disclosures from integrated manufacturers, and CDSCO medical device registration records. Bottom-up volume modeling triangulated against top-down expenditure estimates from public health infrastructure budget allocations.
Segmentation dimensions modeled include emulsion chemistry type, diagnostic versus industrial application, end-user facility scale, and geographic regulatory cluster. Volume projections across the analysis window derived from installed base depreciation curves, digital substitution elasticity estimates, and infrastructure expansion budget trajectories. Industry-specific forecast inputs incorporated radiologic technologist workforce pipeline data from ARRT certification statistics and silver price forward curves from precious metal exchanges.
Underlying assumptions cover sustained FDA quality mandates for mammography film, stable silver commodity price bands, and continued radiologic technologist shortages delaying digital transition, with deviation risk concentrated in accelerated flat-panel radiography cost reductions or regulatory harmonization favoring digital-only diagnostic pathways. Recalibration cycles align with material shifts in healthcare labor market dynamics and precious metal supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Fluoroscopy Devices Market
Medical Imaging
Multiphoton Microscopy Market
Medical Imaging
Angiography Imaging Systems Market
Medical Imaging
Asia Pacific Nuclear Imaging Devices Market
Medical Imaging
Global Single-Photon Emission Computed Tomography (SPECT) Market
Medical Imaging
Digital Breast Tomosynthesis (DBT) Equipment Market
Medical Imaging
Cone Beam Computed Tomography (CBCT) System Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
Precision Cancer Imaging Market
Medical Imaging
Medical Imaging Management Market
Medical Imaging
Global Elastography Imaging Market
Medical Imaging
Breast Imaging Equipment Market
Medical Imaging
Computed Tomography (CT) Scanners Market
Medical Imaging
Digital Pathology Scanner Calibration and Image Quality Test Systems Market
Medical Imaging
Global Medical Imaging Reagents Market
Medical Imaging
Handheld Dental X-Ray Systems Market