
 Neurological Disorder Drugs Market | 2026-2036
Neurological Disorder Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Neurological Disorder Drugs Market Outlook
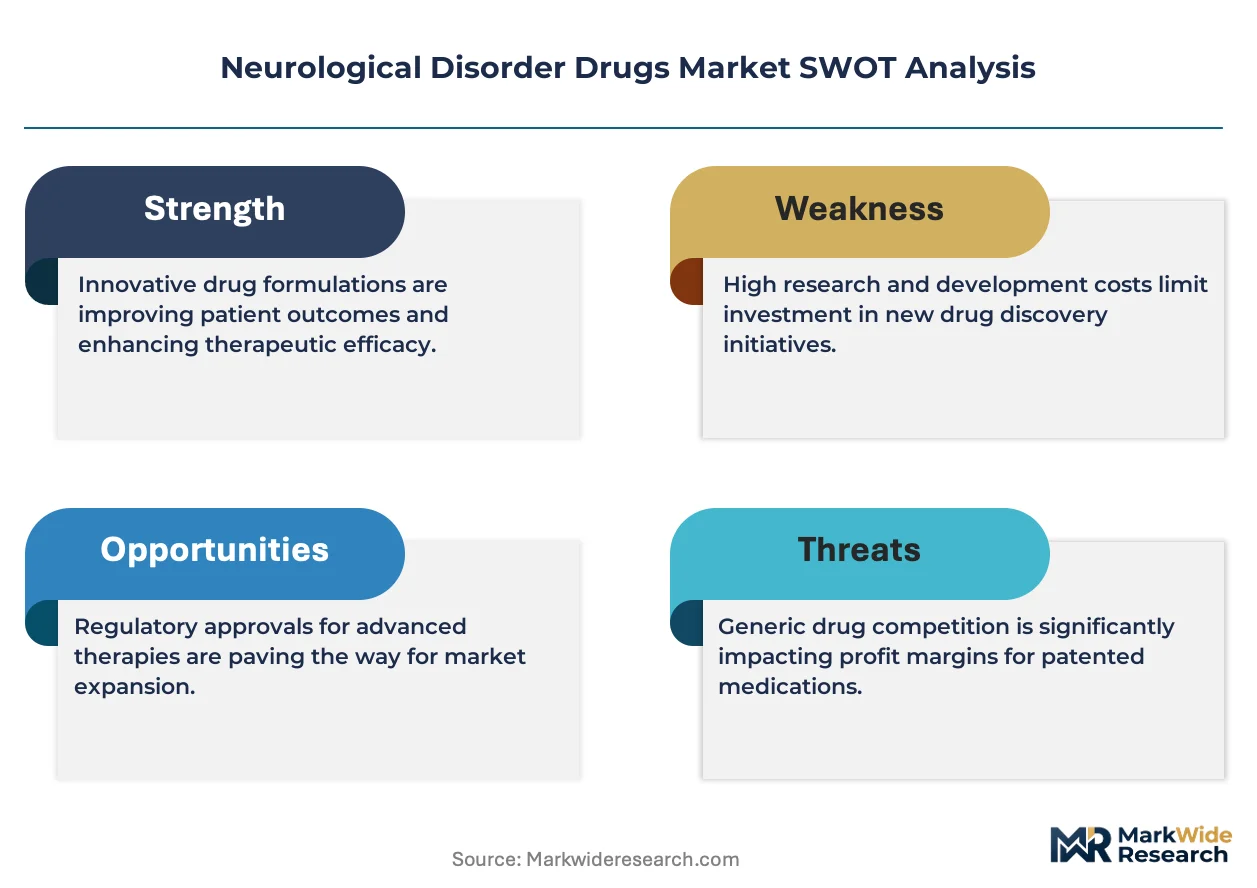
Gene therapy vector engineering is reshaping how neurological disorder drugs are developed and manufactured, shifting production from small-molecule chemistry to viral-platform biologics. Pfizer Inc. leverages its mRNA manufacturing infrastructure to scale nucleic acid therapies for rare neurological conditions. Novartis AG anchors its competitive position through CAR-T and gene therapy assets in neurodegenerative disease pipelines. Biogen Inc. specializes in antisense oligonucleotide platforms for spinal muscular atrophy and amyotrophic lateral sclerosis.
Neurological disorder drugs comprise pharmaceutical agents targeting central and peripheral nervous system pathologies, formulated as small molecules, biologics, or nucleic acid therapies with blood-brain barrier penetration as a critical functional parameter. Their primary commercial purpose is modifying disease progression, managing symptoms, or correcting genetic drivers in conditions with high unmet medical need. Anticonvulsants command established revenue pools across epilepsy and neuropathic pain indications, while gene therapy delivery through intrathecal injection represents the fastest-growing modality as manufacturers build specialized infusion infrastructure. Oral antidepressants and antipsychotics retain volume dominance in psychiatric neurology, though margin compression from generic competition redirects R&D investment toward injectable long-acting formulations.
FDA accelerated approval pathways and EMA conditional marketing authorization frameworks compress development timelines for Alzheimer's and Parkinson's therapies, reshaping how sponsors design Phase II evidence packages. The EU AI Act and FDA guidance on AI-enabled drug discovery are introducing validation requirements for machine learning models used in patient stratification and biomarker identification. Stakeholders must monitor how blood-brain barrier delivery technology maturation alters competitive moats between platform biotechs and integrated pharmaceutical manufacturers.
Market Dynamics
FDA and EMA accelerated approval pathways are compressing clinical development timelines for Alzheimer's and Parkinson's therapies, forcing sponsors to redesign Phase II evidence packages around surrogate biomarkers rather than traditional cognitive endpoints.
Growth Catalysts
- Biologics manufacturing expansion:Hospital procurement channels are scaling viral-vector production capacity for gene therapies targeting spinal muscular atrophy and amyotrophic lateral sclerosis.
- EU AI Act validation requirements:Machine learning frameworks for patient stratification are gaining regulatory credibility, accelerating biomarker identification pipelines.
- Intrathecal delivery infrastructure:Specialized infusion centers in the United States, Germany, and Japan are building dedicated suites for central nervous system gene therapy administration.
Market Restraints
- Plasmid DNA supply concentration:Viral vector production depends on a limited network of contract manufacturers, creating bottlenecks for AAV-based neurological therapies.
- Blood-brain barrier penetration failure:Small-molecule candidates face attrition rates above ninety percent in preclinical translation due to efflux transporter mechanisms.
- IRA price negotiation timelines:Medicare reimbursement uncertainty is compressing commercialization windows for novel neurology assets in the United States.
Strategic Opportunities
- Japan's aging demographic concentration:Patient pools for Parkinson's and Alzheimer's exceed comparable Western markets on a per-capita basis, creating premium pricing tolerance for disease-modifying therapies.
- Antisense oligonucleotide platform extension:Spinal muscular atrophy approvals are validating repeat-dose intrathecal protocols for Huntington's and frontotemporal dementia indications.
- Long-acting injectable substitution:Psychiatric neurology is pivoting from oral generics to depot formulations with adherence-monitoring digital companions.
Industry Challenges
- Viral vector manufacturing talent scarcity:Cell culture specialists with AAV suspension experience command compensation premiums that strain mid-cap biotech burn rates.
- Legacy IT integration friction:Real-world evidence platforms for post-market neurodegenerative drug monitoring require reconciliation with existing pharmacovigilance databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurological Disorder Drugs Market |
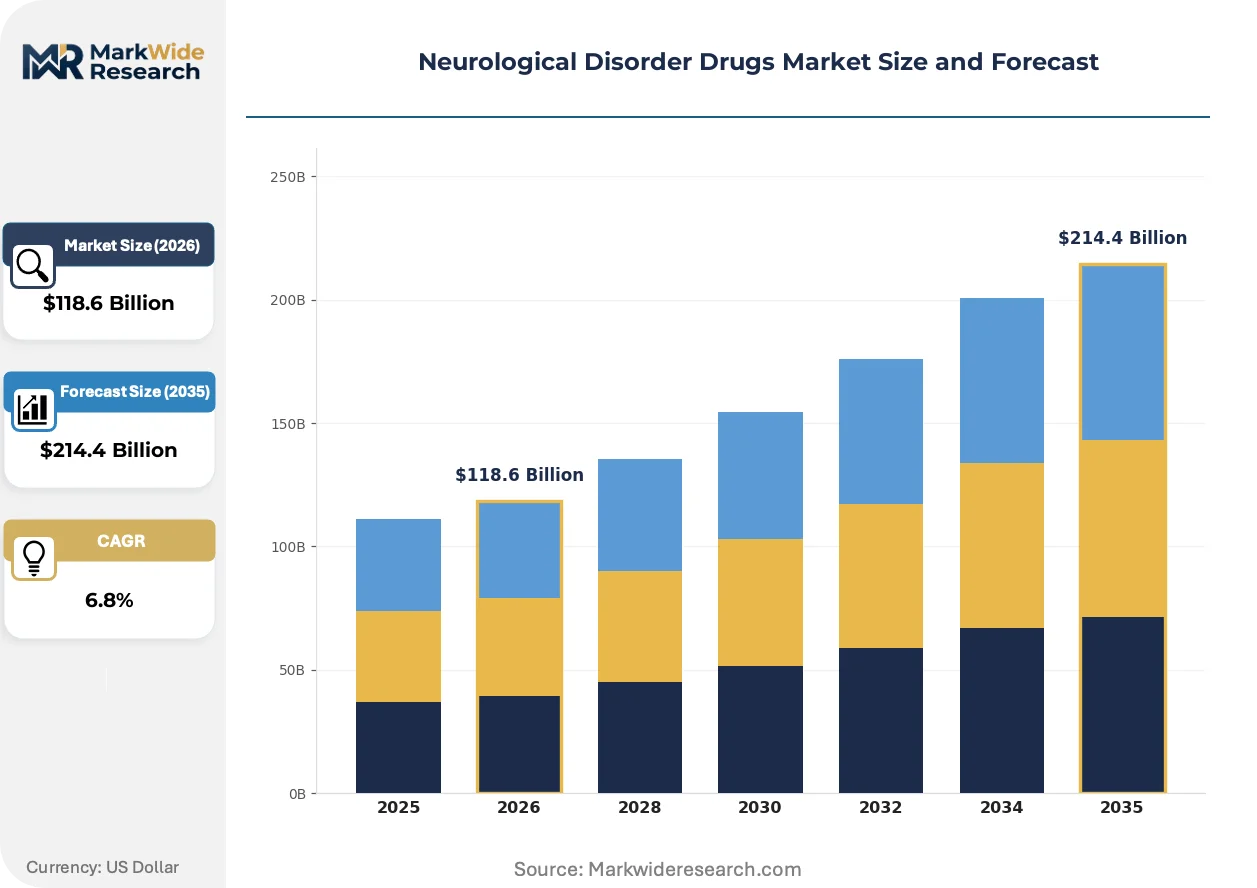
| Market Size in 2026 | $118.6 Billion |
| Market Size in 2035 | $214.4 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antidepressants, Antipsychotics, Anticonvulsants, Stimulants Therapy Area: Alzheimer's, Parkinson's, Epilepsy, Migraine Delivery Mode: Oral, Injectable, Intravenous, Transdermal End User: Hospitals, Clinics, Homecare, Rehabilitation Centers |
| Companies Covered | Pfizer Inc., Novartis AG, F. Hoffmann-La Roche Ltd., Johnson & Johnson, Merck KGaA, Sanofi, Bayer AG, Biogen Inc., Eisai Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurological Disorder Drugs Market Strategic Shifts
Gene therapy vector engineering is displacing small-molecule chemistry as the dominant R&D modality, while regulatory frameworks and procurement models co-evolve to accommodate single-administration curative pricing.
Adeno-associated virus capsid engineering is virtualizing how neurological disorder drugs achieve central nervous system access. Biotech sponsors are licensing next-generation serotypes with enhanced blood-brain barrier transcytosis from platform technology holders. This capsid innovation is virtualizing the competitive moat between viral delivery specialists and traditional pharmaceutical manufacturers.
EMA conditional marketing authorization frameworks are compressing approval timelines for amyloid-targeting Alzheimer's therapies. The industrial consequence is a shift toward adaptive trial designs with integrated biomarker readouts. Neurology-focused contract research organizations in Germany and the Netherlands are expanding biomarker laboratory capacity to serve this demand.
Hospital pharmacy procurement is consolidating gene therapy purchasing decisions into centralized value-analysis committees. Academic medical centers are displacing traditional distributor relationships with direct manufacturer contracts for intrathecal biologics. This concentration is most visible in the United States, where integrated delivery networks are capturing infusion site referrals from independent neurology practices.
Neurological Disorder Drugs Market Segmentation
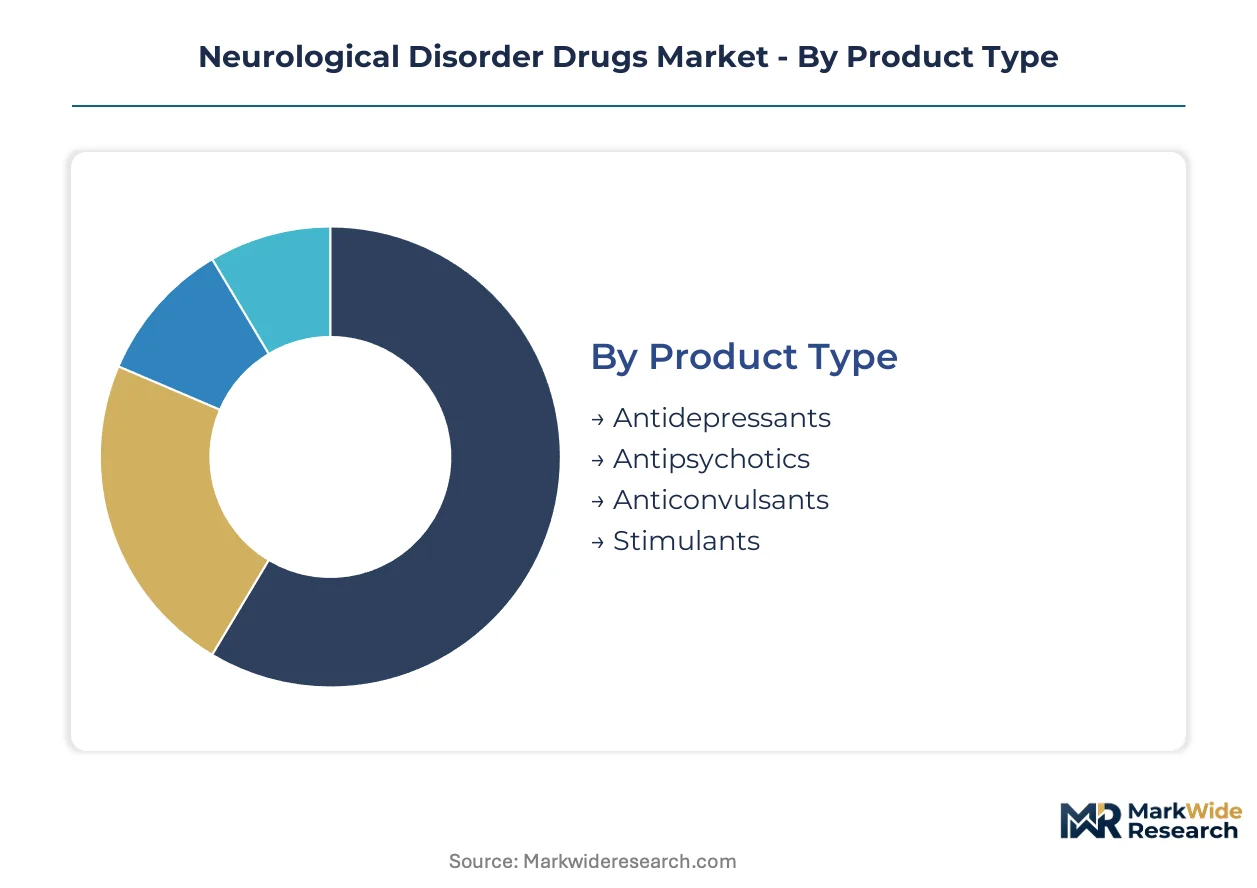
Segmentation in neurological disorder drugs reveals how formulation chemistry, disease pathology, and care setting intersect to determine commercial strategy. Manufacturers must align R&D investment with the specific penetration requirements of blood-brain barrier delivery and the reimbursement frameworks governing each therapy area.
Product Type:
Anticonvulsants anchor hospital procurement volumes for epilepsy and neuropathic pain, while gene therapy platforms are displacing small-molecule chemistry in rare disease indications.
- Anticonvulsants:Small-molecule agents modulating voltage-gated sodium channels or enhancing GABAergic inhibition. Demand concentrates in the United States and Germany where epilepsy prevalence and diagnostic rates support volume contracting with integrated delivery networks. Generic competition has compressed margins, redirecting investment toward extended-release formulations.
- Antipsychotics:Dopamine receptor antagonists and partial agonists addressing schizophrenia and bipolar disorder. Long-acting injectable depot formulations are gaining share in the United States as adherence-monitoring programs demonstrate reduced hospitalization rates versus oral generics.
- Antidepressants:SSRIs and SNRIs retain volume dominance in psychiatric neurology despite therapeutic stagnation. Japan's aging demographic sustains premium pricing for novel multimodal agents targeting treatment-resistant depression.
- Stimulants:Catecholamine reuptake inhibitors and releasing agents for attention deficit disorders. Regulatory scrutiny on scheduling classification limits pharmacy distribution channels in the United States.
Established volume favors anticonvulsants; emerging adoption favors antipsychotics.
Therapy Area:
Cost tier stratification separates chronic symptomatic management from one-time curative gene therapies with seven-figure pricing.
- Alzheimer's:Disease-modifying antibodies targeting amyloid-beta require specialized infusion infrastructure and biomarker confirmation protocols. FDA accelerated approval pathways have compressed development timelines, though Medicare coverage determination remains contested.
- Parkinson's:Levodopa formulations and dopamine agonists face generic saturation, while subthalamic deep brain stimulation and gene therapy delivery via intrathecal injection represent premium intervention tiers.
- Epilepsy:Antiseizure medications span generic oral tablets to branded extended-release formulations. Germany's statutory health insurance funds negotiate reference pricing that erodes differentiation between bioequivalent products.
- Migraine:CGRP monoclonal antibodies and small-molecule antagonists have displaced triptans in preventive treatment protocols. United States commercial plans favor step-therapy requirements that delay access to biologics.
Revenue concentration sits with Alzheimer's development pipelines; volume accessibility sits with epilepsy maintenance therapy.
Delivery Mode:
Supply concentration in viral vector manufacturing is elevating injectable and intravenous modalities above oral chemistry in strategic priority.
- Injectable:Subcutaneous and intramuscular routes dominate biologic administration. Long-acting formulations for psychiatric indications require cold-chain logistics that favor integrated delivery network contracts over independent pharmacy distribution.
- Intravenous:Infusion-center administration for Alzheimer's monoclonal antibodies and gene therapies demands specialized nursing capacity. Academic medical centers in the United States and Japan are consolidating these services into dedicated neurodegenerative disease suites.
- Oral:Small-molecule tablets and capsules retain patient preference for chronic symptomatic management. Bioavailability challenges from efflux transporter activity at the blood-brain barrier limit therapeutic efficacy for many candidates.
- Transdermal:Patch formulations for Parkinson's disease and neuropathic pain offer steady-state pharmacokinetics. Manufacturing complexity and adhesion failure rates constrain adoption relative to oral alternatives.
Patient preference sustains oral dominance; therapeutic efficacy and curative potential favor intravenous expansion.
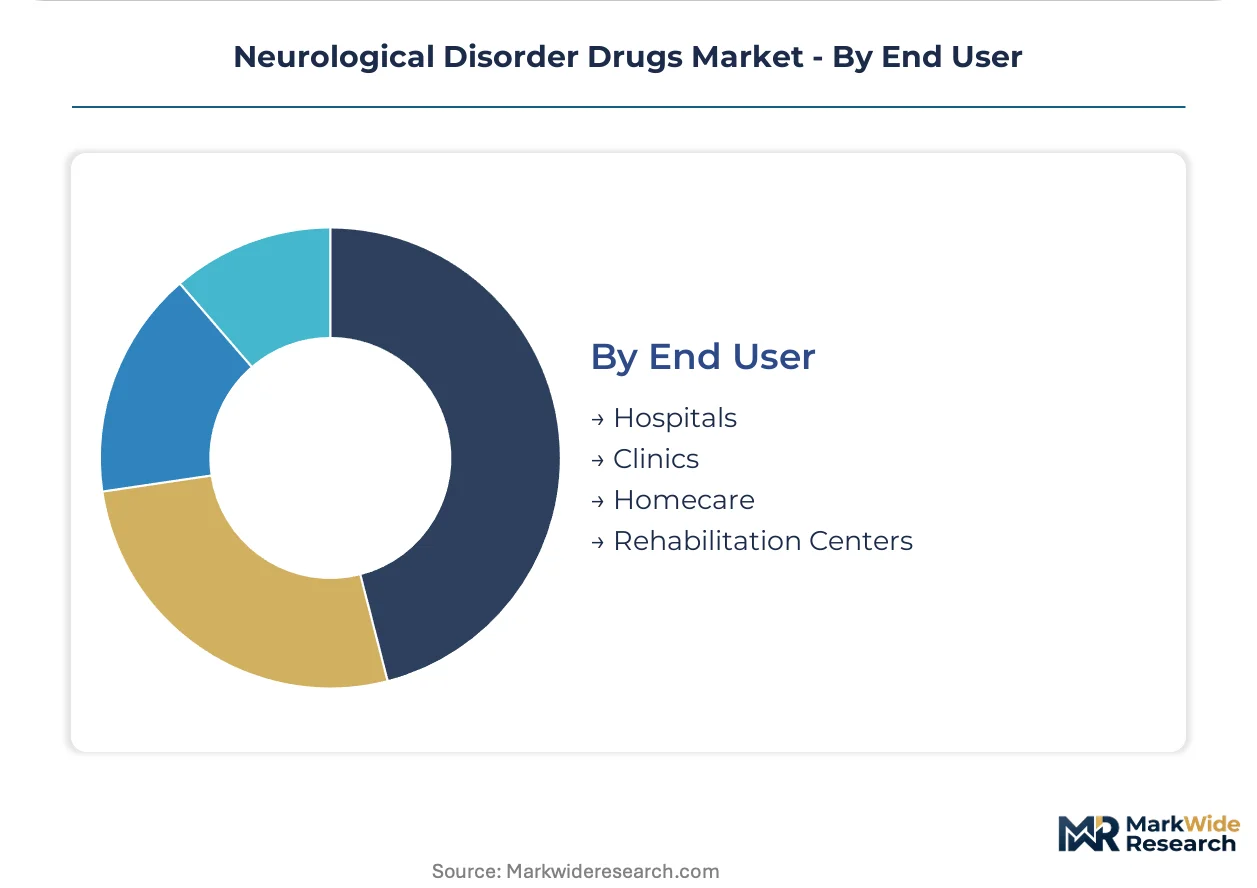
End User:
Procurement authority is shifting toward centralized hospital value-analysis committees as gene therapy pricing concentrates purchasing decisions.
- Hospitals:Academic medical centers and integrated delivery networks control access to intrathecal gene therapies and infusion-based biologics. Pharmacy and therapeutics committees in the United States require outcomes-based contracting for high-cost neurology assets.
- Homecare:Subcutaneous self-administration of CGRP antibodies and long-acting psychiatric injectables is expanding beyond clinic settings. Reimbursement codes for home nursing visits vary across German regional sickness funds.
- Clinics:Independent neurology practices face referral capture by hospital-owned infusion centers. Medicare site-of-service differentials penalize office-based administration of intravenous therapies.
- Rehabilitation Centers:Post-acute facilities manage medication reconciliation for stroke and traumatic brain injury patients. Formulary constraints limit access to newer anticoagulant and neuroprotective agents.
Procurement consolidation favors hospitals; patient convenience and cost containment favor homecare expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital pharmacy directors and neurology procurement committees concentrate purchasing power in aging economies with established infusion infrastructure and gene therapy reimbursement frameworks. Buyer archetypes span integrated delivery networks in the United States, statutory health insurance funds in Germany, and hospital value-analysis committees in Japan.
United States
Medicare site-of-service differentials and IRA price negotiation timelines compress commercialization windows for novel neurology assets. FDA accelerated approval pathways for Alzheimer's therapies reshape Phase II evidence requirements around surrogate biomarkers. Academic medical centers in Boston and the Research Triangle consolidate intrathecal gene therapy administration into dedicated neurodegenerative disease suites.
Germany
Statutory health insurance funds negotiate reference pricing for antiseizure medications that erodes differentiation between bioequivalent products. EMA conditional marketing authorization frameworks compress approval timelines for amyloid-targeting therapies. Biomarker laboratory capacity in Heidelberg and Munich expands to serve adaptive trial designs with integrated readouts.
Japan
Patient pools for Parkinson's and Alzheimer's exceed comparable Western markets on a per-capita basis, creating premium pricing tolerance for disease-modifying therapies. PMDA review pathways for regenerative medicine products accelerate gene therapy timelines. The Kanto region around Tokyo anchors domestic clinical trial infrastructure for intrathecal delivery protocols.
Switzerland
Swissmedic's streamlined authorization procedures attract sponsors seeking parallel EMA access with reduced regulatory friction. Geneva and Basel host concentrated contract manufacturing for viral vector production serving European neurological therapy pipelines. The country's reimbursement authority evaluates one-time curative gene therapies through outcomes-based installment frameworks.
United Kingdom
NICE technology appraisals for Alzheimer's monoclonal antibodies create contested coverage determination precedents affecting European pricing negotiations. The MHRA's post-Brexit recognition framework maintains alignment with EMA standards while enabling accelerated access pathways. London's academic hospital networks pilot real-world evidence platforms for post-market neurodegenerative drug monitoring.
Neurological Disorder Drugs Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure that concentrates gene therapy procurement authority in integrated delivery networks while fragmenting oral generic volumes. Tiered competition separates platform biotechs with viral-vector manufacturing capabilities from traditional pharmaceutical manufacturers reliant on small-molecule chemistry. Strategic archetypes include antisense oligonucleotide specialists, mRNA infrastructure deployers, and CAR-T pipeline anchors. Dominant competitive moves encompass capacity expansion in AAV suspension production and strategic partnerships for next-generation capsid licensing.
Within the platform technology tier, Pfizer Inc. and Novartis AG exemplify divergent infrastructure strategies for nucleic acid therapy scaling, while Biogen Inc. occupies a position as an antisense specialization anchor. These three companies represent how manufacturing modality choices—mRNA, CAR-T, and oligonucleotide respectively—determine competitive positioning in neurological disorder drug development.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| F. Hoffmann-La Roche Ltd. |
| Johnson & Johnson |
| Merck KGaA |
| Sanofi |
| Bayer AG |
| Biogen Inc. |
| Eisai Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
AAV suspension capacity underutilization in the United States and Germany is forcing contract manufacturers to accept cost-plus contracts with raw-material indexation, compressing margins for viral-vector platforms while concentrating pricing power among hospital value-analysis committees negotiating outcomes-based installments for intrathecal gene therapies.
Pricing Analysis
Cost-plus contracts with plasmid DNA and cell-culture media indexation dominate gene therapy procurement between biotech sponsors and contract manufacturers. Price differentiation separates one-time curative intrathecal administrations from chronic oral maintenance regimens, with adherence-monitoring digital companions commanding service premiums. Pricing pressure intensifies in anticonvulsant and antidepressant oral generics as statutory health insurance reference pricing erodes brand premiums. Hospital pharmacy committees exhibit lowest price sensitivity for disease-modifying Alzheimer's antibodies requiring biomarker confirmation protocols.
Supply Chain Analysis
Export-control restrictions on gene-therapy manufacturing equipment limit technology transfer to emerging viral-vector production hubs, constraining capacity expansion outside established clusters. Plasmid DNA supply concentrates in the United States, Germany, and Switzerland, while AAV capsid engineering intellectual property draws from platform technology holders in the United States and academic licensors in Germany. Single-source vulnerability in cell-culture media creates bottlenecks for suspension-based manufacturing. Distribution runs through academic medical center direct contracts, displacing traditional wholesale channels for intrathecal biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy vector engineering is creating platform-economics inflection as hospital value-analysis committees consolidate procurement authority and interoperability requirements for real-world evidence platforms reshape competitive moats.
For Market Incumbents: Build manufacturing moats through captive AAV suspension capacity in the Research Triangle and Basel clusters, securing cell-culture talent pools before compensation premiums exhaust mid-cap biotech burn rates. Backward integration into plasmid DNA production reduces single-source dependency. Outcomes-based contracting with integrated delivery networks locks in referral capture from independent neurology practices threatened by Medicare site-of-service differentials. For New Entrants and Emerging Players: Build out antisense oligonucleotide platform extensions for Huntington's and frontotemporal dementia, exploiting validated repeat-dose intrathecal protocols from spinal muscular atrophy precedents. Japan's aging demographic concentration offers premium pricing tolerance for disease-modifying therapies with PMDA regenerative medicine acceleration. Partner with academic medical centers for dedicated neurodegenerative disease suite access rather than competing for independent clinic referrals. For Investors and Strategic Acquirers: Long-term, this sits as a manufacturing-capability play because viral-vector production talent scarcity and AAV suspension expertise concentration create durable competitive barriers against small-molecule incumbents. Target platform biotechs with next-generation capsid licensing portfolios and established hospital value-analysis committee relationships. Watch for IRA price negotiation timeline clarity as inflection signal for United States commercialization window viability.| Strategic Initiative | Industry Significance |
|---|---|
| AAV Suspension Capacity Expansion | Captive viral-vector production reduces plasmid DNA supply concentration risk for gene therapy pipelines. |
| Next-Generation Capsid Licensing | Enhanced blood-brain barrier transcytosis serotypes from platform holders displace first-generation AAV delivery. |
| Intrathecal Infusion Infrastructure Buildout | Academic medical center dedicated suites in Boston and Tokyo consolidate gene therapy administration access. |
| Real-World Evidence Platform Integration | Post-market neurodegenerative drug monitoring reconciles with FDA and EMA pharmacovigilance database requirements. |
| Outcomes-Based Contracting Frameworks | Hospital pharmacy and therapeutics committees in integrated delivery networks adopt installment pricing for curative therapies. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA accelerated approval pathway filings, EMA conditional marketing authorization submissions, ClinicalTrials.gov neurology trial registries, and Medicare coverage determination databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation cross-checked segmentation outputs across therapy areas and delivery modes.
Calibration against historical approval timelines and reimbursement decision lags anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include therapy area, formulation chemistry, administration route, and regional regulatory cluster. CAGRs were derived from patient pool expansion rates, pricing trajectory assumptions for curative versus chronic modalities, and manufacturing capacity buildout schedules. Gene therapy vector engineering maturation and blood-brain barrier delivery technology advancement served as industry-specific forecast inputs.
Stress conditions across IRA price negotiation implementation, AAV manufacturing yield variability, and EMA conditional marketing authorization conversion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding patient diagnostic rates, hospital infusion capacity expansion, and biomarker laboratory throughput. Material shifts in Medicare coverage determination precedents for amyloid-targeting therapies or plasmid DNA supply network consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Sarcoidosis Drugs Market
Pharmaceuticals
Emergency Contraceptive Pills Market
Pharmaceuticals
Small Molecule Innovator CDMO Market
Pharmaceuticals
Global Testosterone Replacement Therapy Market
Pharmaceuticals
Critical Care Antiarrhythmic Drugs Market
Pharmaceuticals
Global Acne Medication Market
Pharmaceuticals
Global Human Rabies Vaccine Market
Pharmaceuticals
Global Ceftiofur Market
Pharmaceuticals
Cerumenolytic Agents Market
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Nesiritide Market
Pharmaceuticals
India Opioids Market
Pharmaceuticals
Canine Dilated Cardiomyopathy Drugs Market
Pharmaceuticals
Pharmaceutical Elixir Market
Pharmaceuticals
Injectable Benzodiazepine Market
Pharmaceuticals
Soft Capsules Drugs CMO Market