
 Global Colposcopy Market | 2026-2036
Global Colposcopy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Colposcopy Market Foresight
CMOS image sensors are restructuring optical economics in colposcopy, displacing legacy CCD architectures with lower-cost, higher-resolution alternatives that compress unit manufacturing expenses. Carl Zeiss Meditec AG leverages its optical heritage to sustain premium positioning in high-definition visualization systems. CooperSurgical Inc. anchors North American distribution through its gynecology-focused channel infrastructure. Olympus Corporation competes on integrated endoscopy-to-colposcopy workflow platforms that extend its hospital system relationships.
Colposcopy denotes a magnified examination of the cervix, vagina, and vulva using a binocular microscope with variable magnification typically ranging from 4x to 40x and integrated green or blue filter illumination to enhance vascular pattern detection; the procedure serves as the diagnostic bridge between abnormal cytology and histopathological confirmation. Digital colposcopes now dominate capital procurement budgets as hospitals prioritize image capture, storage, and teleconsultation compatibility. Cervical cancer screening applications absorb the majority of installed base utilization, though HPV detection workflows represent the fastest-growing segment as co-testing protocols expand. Cloud-enabled deployment configurations are gaining traction where multi-site health systems seek centralized quality assurance and remote expert consultation capabilities.
The U.S. FDA regulates colposcopes as Class II medical devices under 21 CFR 884.6190, requiring substantial equivalence demonstrations for market clearance, while the EU Medical Device Regulation mandates enhanced clinical evidence and post-market surveillance for CE marking. India's CDSCO aligns with BIS standards for imported diagnostic equipment, creating compliance complexity for multinational suppliers. Stakeholders must monitor evolving reimbursement thresholds for digital and AI-augmented colposcopy procedures as payors recalibrate coverage policies around precision screening modalities.
Market Dynamics
CMOS sensor commoditization is compressing optical subsystem costs while simultaneously elevating performance thresholds, forcing incumbent manufacturers to defend margin positions through software differentiation and service bundling rather than hardware premiums alone.
Growth Catalysts
- India's National Health Mission:Government-funded cervical cancer screening programs are scaling colposcopy deployment across district hospitals and primary health centers, creating sustained public-sector procurement volume.
- FDA 21 CFR 884.6190 pathway:Streamlined substantial equivalence clearance for digital colposcope iterations accelerates product refresh cycles and reduces time-to-market for sensor upgrades.
- HPV co-testing protocols:Expanded adoption of cytology-HPV dual screening workflows in hospital outpatient departments is amplifying diagnostic procedure volume and device utilization rates.
Market Restraints
- Optical component supply concentration:Precision lens assemblies and specialized illumination modules concentrate among German and Japanese optical specialists, exposing procurement to geographic supply risk.
- EU MDR clinical evidence requirements:Enhanced post-market surveillance obligations and notified body capacity constraints extend CE marking timelines and elevate compliance expenditure for market entry.
- Point-of-care molecular diagnostics:Emerging HPV genotyping and methylation assays at the primary screening level threaten to compress colposcopy's role in diagnostic cascades.
Strategic Opportunities
- Cloud-enabled multi-site configurations:Health systems in the United States are centralizing quality assurance and remote expert consultation through networked digital colposcope deployments.
- Teleconsultation integration:AI-augmented image analysis paired with real-time specialist connectivity opens rural and underserved access models in Brazil and South Africa.
- Japan's METI digital health acceleration:Reimbursement pathway development for AI-diagnostic support creates regulatory tailwind for algorithm-enabled colposcopy platforms.
Industry Challenges
- Colposcopist training pipeline:Specialized gynecologic pathology visualization expertise requires extended apprenticeship, constraining workforce expansion in high-volume screening environments.
- Legacy PACS integration:Digital colposcope image formats and DICOM compliance variations create friction with existing hospital information system architectures.
- CE marking notified body queues:EU MDR transition backlog delays market access timelines and compresses revenue recognition windows for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Colposcopy Market |
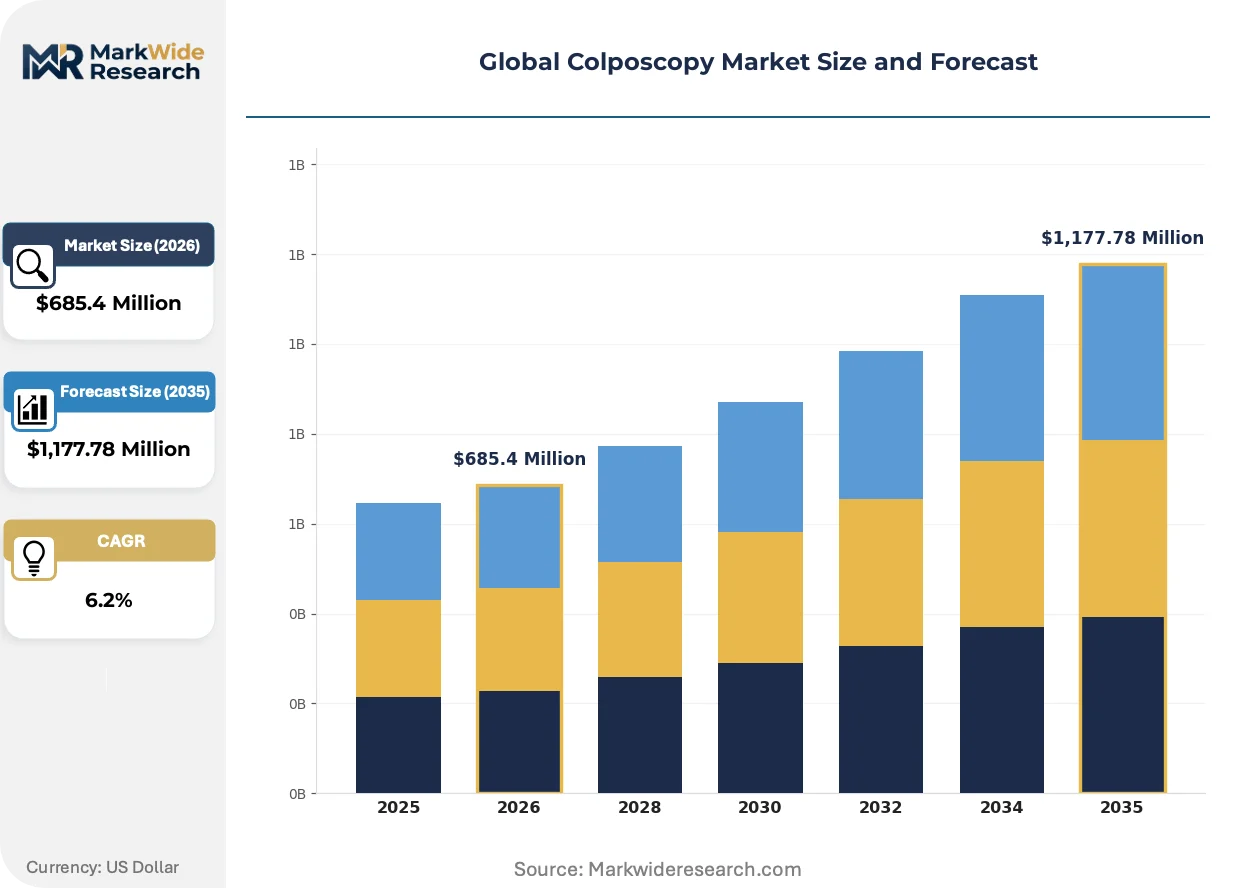
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Colposcopes, Video Colposcopes, Optical Colposcopes, Portable Colposcopes, Others Application: Cervical Cancer Screening, Precancerous Lesion Diagnosis, HPV Detection, Vaginal Lesions Assessment, Vulvar Lesions Examination End User: Gynecologists, Oncology Clinics, Diagnostic Centers, Women's Health Clinics, Research Institutes Deployment: On-Premise, Cloud-Enabled, Mobile Integration, Standalone Systems |
| Companies Covered | DYSIS Medical Inc., ATMOS MedizinTechnik GmbH & Co. KG, Carl Zeiss Meditec AG, CooperSurgical Inc., Leisegang GmbH, Olympus Corporation, Hill-Rom, McKesson Medical-Surgical Inc., MedGyn Products Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Colposcopy Market Shifts & Advancements
Computational imaging and artificial intelligence are redefining diagnostic workflow economics, shifting value capture from optical hardware toward algorithmic interpretation and connected service platforms.
Deep learning-based cervical lesion classification is electrifying diagnostic accuracy benchmarks. Academic medical centers in South Korea and the United States are piloting FDA-cleared algorithms for real-time acetowhite pattern analysis. This capability is compressing specialist consultation dependency and enabling task-shifting to mid-level providers in resource-constrained settings.
The EU Medical Device Regulation's enhanced clinical evidence requirements are restructuring product development resourcing. Manufacturers now allocate substantial pre-market expenditure to prospective validation studies and post-market clinical follow-up infrastructure. High-definition visualization systems with integrated documentation software face the steepest compliance burden given their classification as active therapeutic devices.
Hospital procurement committees are unbundling capital equipment from service contracts and prioritizing interoperability certifications. Buyers in Germany and the United Kingdom now mandate HL7 FHIR connectivity and cloud-native architecture as pre-qualification criteria. This behavioral shift favors vendors with software-native platform strategies over legacy hardware specialists dependent on proprietary ecosystem lock-in.
Global Colposcopy Market Segmentation
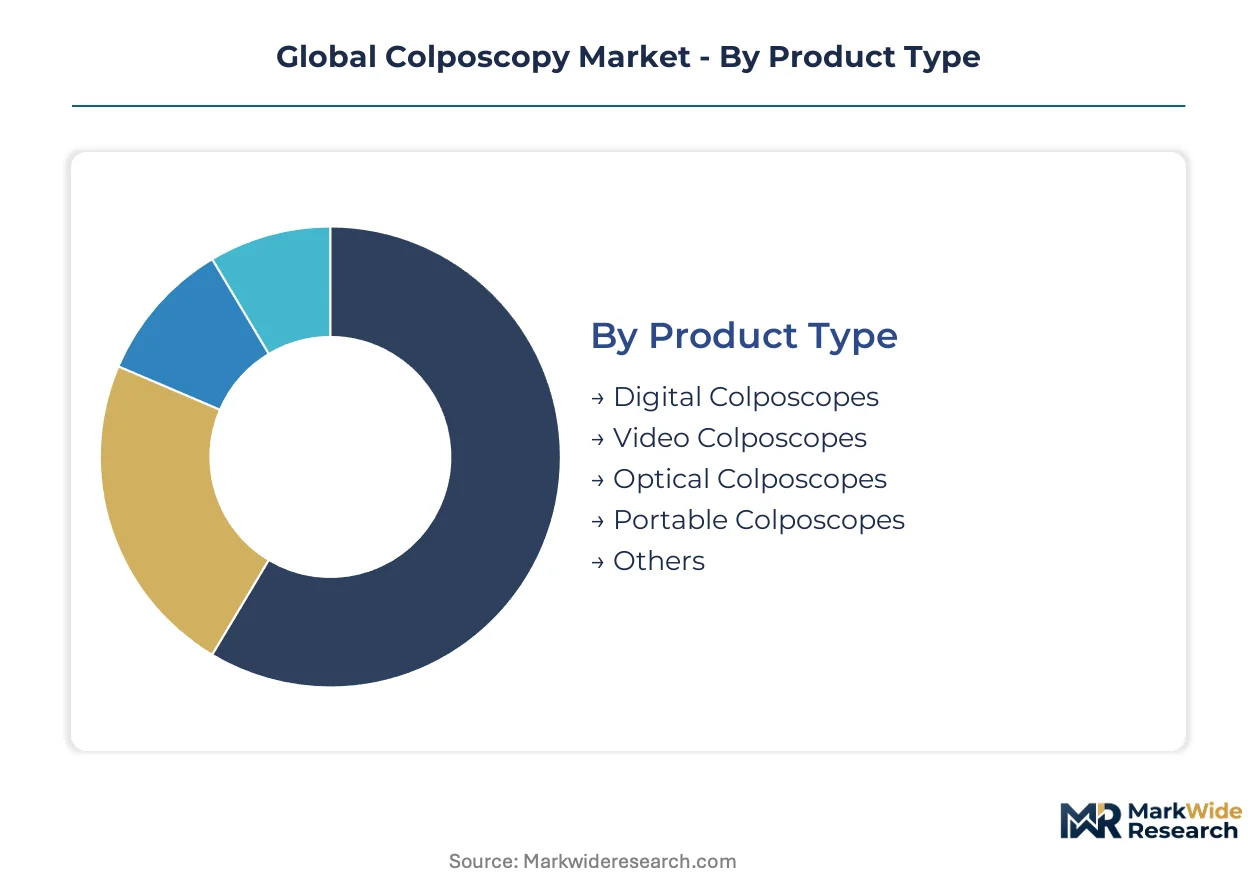
Segmentation in the colposcopy market reveals how procurement priorities diverge across healthcare delivery models. Understanding these fault lines illuminates where capital investment concentrates and where next-generation platforms gain traction first.
Product Type:
Optical subsystem sourcing concentrates among German and Japanese precision manufacturers, creating tiered cost structures that cascade through finished device pricing.
- Digital Colposcopes:Integrated CMOS sensors deliver high-resolution image capture with direct PACS connectivity and DICOM compliance. Hospital outpatient departments in the United States prioritize these systems for their documentation and teleconsultation capabilities, though legacy PACS integration friction persists.
- Video Colposcopes:Real-time video output enables immediate clinical review and resident training applications. Demand clusters in academic medical centers where procedural documentation requirements are most stringent, with CMOS commoditization compressing unit costs.
- Optical Colposcopes:Traditional binocular microscope architectures with variable 4x-40x magnification and integrated green filter illumination.
- Portable Colposcopes:Battery-powered, lightweight configurations designed for field deployment in rural screening programs.
- Others:Specialized configurations including colposcope-integrated hysteroscopy platforms and research-grade systems.
Digital colposcopes absorb the bulk of installed capacity; portable colposcopes are expanding most quickly through government-funded screening initiatives.
Application:
Clinical utility varies sharply by disease prevalence and screening protocol maturity, with reimbursement pathways determining where device utilization concentrates.
- Cervical Cancer Screening:The dominant procedure volume driver, bridging abnormal cytology to histopathological confirmation. India's National Health Mission is scaling district hospital deployment, creating sustained public-sector procurement volume despite specialist training pipeline constraints.
- HPV Detection:Co-testing protocols amplify diagnostic procedure volume as dual screening workflows expand. This segment is gaining share fastest where payors recalibrate coverage policies around precision screening modalities.
- Precancerous Lesion Diagnosis:Acetowhite pattern analysis and vascular assessment for CIN grading.
- Vaginal Lesions Assessment:Post-hysterectomy surveillance and DES-exposure follow-up examinations.
- Vulvar Lesions Examination:Differentiated intraepithelial neoplasia evaluation requiring specialized illumination.
Cervical cancer screening commands the majority of procedure volume; HPV detection workflows show the steepest expansion trajectory.
End User:
Customer concentration patterns reflect workforce distribution and capital budget accessibility across care delivery settings.
- Gynecologists:Private practice and hospital-based specialists performing the majority of diagnostic procedures. Cloud-enabled configurations are gaining traction where multi-site health systems seek centralized quality assurance capabilities.
- Oncology Clinics:Cancer center integration demands interoperability with radiation oncology and surgical planning systems.
- Diagnostic Centers:High-throughput screening facilities prioritizing throughput and standardized image quality.
- Women's Health Clinics:Community-based settings with budget constraints favoring refurbished equipment and service bundling.
- Research Institutes:Academic centers piloting FDA-cleared AI algorithms for real-time lesion classification.
Gynecologists anchor the installed base; oncology clinics are climbing the fastest as cancer center networks expand.
Deployment:
Architecture choices increasingly hinge on health system scale and interoperability mandates rather than standalone device performance.
- Cloud-Enabled:Networked configurations supporting multi-site quality assurance and remote expert consultation. Procurement committees in Germany and the United Kingdom now mandate HL7 FHIR connectivity as pre-qualification criteria.
- On-Premise:Local server-based image storage with institutional data governance control.
- Mobile Integration:Tablet and smartphone-connected platforms for point-of-care documentation.
- Standalone Systems:Self-contained units without network dependencies for resource-constrained settings.
On-premise systems retain the majority of legacy installations; cloud-enabled configurations are gaining share fastest among integrated delivery networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India's medical device corridors concentrate assembly operations for government procurement tenders, while precision optics clusters in Germany and Japan anchor high-end component sourcing.
United States
Hospital outpatient departments drive replacement demand as FDA 21 CFR 884.6190 guidance accelerates digital colposcope refresh cycles. The reimbursement pathway for AI-augmented procedures under CMS is expanding coverage for precision screening modalities. Manufacturing concentrates in Minnesota's medical technology corridor where established gynecology device specialists maintain distribution infrastructure.
Germany
EU MDR compliance requirements elevate clinical evidence thresholds for CE marking, extending timelines for high-definition visualization systems. The notified body capacity constraint in Frankfurt and Munich clusters compresses revenue recognition windows for new product introductions. Baden-Württemberg's precision optics ecosystem supplies specialized illumination modules to finished device assemblers.
India
The National Health Mission funds district hospital deployment across 28 states, creating sustained public-sector procurement volume despite specialist training pipeline constraints. CDSCO alignment with BIS standards for imported diagnostic equipment creates compliance complexity for multinational suppliers. Tamil Nadu's medical device park near Chennai anchors assembly operations for portable configurations targeting rural screening programs.
Japan
METI digital health acceleration programs develop reimbursement pathways for AI-diagnostic support, creating regulatory tailwind for algorithm-enabled platforms. Aging demographics amplify cervical cancer screening protocol maturity in Tokyo and Osaka metropolitan areas. Kanagawa Prefecture's imaging technology cluster supports integration with endoscopy workflow platforms.
Brazil
Teleconsultation integration pilots open rural access models in Minas Gerais and Pernambuco where specialist density remains low. ANVISA regulatory frameworks for imported diagnostic equipment shape procurement preferences in São Paulo's private hospital networks. The Southeast region concentrates installed base utilization where gynecology residency programs expand visualization training capacity.
Global Colposcopy Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with optical heritage firms defending premium positioning while CMOS commoditization enables new entrants in portable configurations. The vendor base stratifies into three tiers: precision optics incumbents with integrated software platforms, regional distributors with service bundling capabilities, and emerging specialists in AI-augmented diagnostics. Consolidation pressure concentrates among mid-scale players lacking backward integration into sensor sourcing. Dominant competitive moves include cloud-native architecture development and strategic partnerships with telemedicine platforms.
Among German precision manufacturers, Carl Zeiss Meditec AG and Leisegang GmbH occupy positions anchored by optical subsystem expertise. ATMOS MedizinTechnik GmbH & Co. KG exemplifies the mid-tier specialist archetype with gynecology-focused channel infrastructure. Olympus Corporation represents the integrated workflow platform approach, leveraging hospital system relationships across endoscopy and colposcopy segments.
| Leading Market Players |
|---|
| DYSIS Medical Inc. |
| ATMOS MedizinTechnik GmbH & Co. KG |
| Carl Zeiss Meditec AG |
| CooperSurgical Inc. |
| Leisegang GmbH |
| Olympus Corporation |
| Hill-Rom |
| McKesson Medical-Surgical Inc. |
| MedGyn Products Inc. |
| Others |
Supply & Pricing Matrix
Hospital procurement committees unbundling capital equipment from service contracts force manufacturers to absorb optical subsystem cost volatility or surrender margin. CMOS sensor commoditization compresses hardware premiums while software differentiation and AI-augmented service tiers capture residual value.
Pricing Analysis
Short lead-time premiums for EU MDR-compliant systems run 15-25 percent above standard delivery schedules as notified body queues extend. Three-tier pricing structure across premium, standard, and economy levels stratifies by optical resolution, DICOM certification grade, and bundled teleconsultation modules. Cost compression in mid-tier configurations intensifies because Indian government tenders prioritize portable units with stripped documentation software. Diagnostic centers exhibit highest price sensitivity; oncology clinics least.
Supply Chain Analysis
Dual-sourcing requirements for precision lens assemblies now mandate qualified suppliers in Germany and Japan after COVID-19 disruption exposed single-source vulnerability. CMOS sensors draw from South Korean and Taiwanese foundries; specialized green-filter illumination modules rest on Baden-Württemberg optics clusters. Tariff exposure on Japanese optical components elevates landed cost unpredictability for North American assemblers. Distribution runs through gynecology-focused channel specialists and hospital GPO contracts rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players pursue backward integration into CMOS sensor sourcing to escape foundry pricing power and compress bill-of-materials exposure.
For Market Incumbents: Anticipate margin compression from AI-native entrants by accelerating cloud-native platform development and locking hospital systems through multi-year service contracts. Defend against point-of-care molecular diagnostics substituting colposcopy referrals by embedding algorithmic decision-support into screening workflows. Priority lever: captive supply of high-resolution optical subsystems. For New Entrants and Emerging Players: Begin with portable configurations for India's National Health Mission rural screening tenders, where specification thresholds favor cost-optimized CMOS architectures over legacy CCD heritage. Brazil's teleconsultation pilots offer white-space access where specialist density constraints amplify remote expert connectivity value. Go-to-market angle: smartphone-integrated documentation bypassing legacy PACS friction. For Investors and Strategic Acquirers: The window for entry favors mid-scale AI-augmented diagnostics specialists with FDA-cleared algorithms and cloud deployment infrastructure. Long-term viability hinges on reimbursement pathway maturation for precision screening modalities. Signal to watch: CMS coverage determinations for AI-diagnostic support codes.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Development | HL7 FHIR connectivity satisfies German and UK hospital procurement pre-qualification mandates. |
| AI Algorithm FDA Submission | Real-time acetowhite pattern analysis compresses specialist consultation dependency in screening workflows. |
| Backward Integration into CMOS Sourcing | Captive sensor supply insulates margin from Taiwanese foundry pricing volatility. |
| Hospital System Partnership | Multi-site quality assurance contracts lock integrated delivery network replacement cycles. |
| Reimbursement Strategy | Japan METI pathway development for AI-diagnostic support creates regulatory tailwind for algorithm-enabled platforms. |
Research Methodology
Multi-period observation of FDA 510(k) clearance volumes, EU MDR notified body queue lengths, and Indian government tender awards anchored the trend analysis, supplemented by interviews with hospital purchasing committee chairs, gynecology department heads, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 21 CFR 884.6190 filing databases, CDSCO import registration records, CMS Medicare reimbursement schedules, and hospital procurement databases. Bottom-up unit economics triangulated against top-down expenditure flow analysis.
Input-output matrices modeled colposcope shipments by product type, application workflow, end-user setting, and deployment architecture across the analysis window. CAGRs derived from segmented growth rate reconciliation against aggregate market trajectory. Forecast inputs incorporated HPV co-testing protocol expansion rates and government screening program budget allocations.
Underlying measurement precision varies by segment; digital colposcope unit forecasts carry tighter precision than portable configuration projections given tender timing opacity. Forecasts reflect documented assumptions around regulatory clearance timelines and reimbursement policy stability. Deviation in EU MDR notified body capacity or Indian state-level procurement execution would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Intraoperative Imaging Market
Medical Imaging
Brazil Diagnostic Imaging Equipment Market
Medical Imaging
Global Vendor-Neutral Archive (VNA) and PACS Market
Medical Imaging
Europe Nuclear Medicine Market
Medical Imaging
Europe Intraoperative Imaging Market
Medical Imaging
Italy Diagnostic Imaging Equipment Market
Medical Imaging
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market
Medical Imaging
Molecular Imaging Market
Medical Imaging
Weightbearing Low Dose (CT) Systems Market
Medical Imaging
Medical Imaging Displays Market
Medical Imaging
Orthopedic Radiology Equipment Market
Medical Imaging
Handheld Ultrasound Scanners Market
Medical Imaging
Point of Care (POC) CT Imaging Systems Market
Medical Imaging
Spain Mammography Market
Medical Imaging
Wireless Intraoral Camera Market
Medical Imaging
Global Electroretinography Market