
 3D Medical and Surgical Imaging Platform Market | 2026-2036
3D Medical and Surgical Imaging Platform Market Size, Share, and Industry Trends Forecast 2026-2036
3D Medical and Surgical Imaging Platform Market Outlook
Modular platform bundling is pivoting buyer choice away from standalone imaging hardware toward integrated surgical ecosystems. Siemens Healthineers leverages its Angiography-CT hybrid suites to anchor high-acuity hospital contracts across Europe. GE HealthCare competes through deep R&D intensity in photon-counting CT detectors that sharpen intraoperative tissue differentiation. Brainlab AG specializes in neuronavigation software layers that extend hardware utility without requiring full system replacement.
A 3D medical and surgical imaging platform combines volumetric data acquisition hardware with reconstruction algorithms and real-time visualization software to produce spatially accurate anatomical models during diagnostic or interventional procedures. These systems typically process sub-millimeter slice thicknesses through iterative reconstruction methods to enable surgical planning, intraoperative guidance, and postoperative assessment across complex anatomical regions. CT Imaging and MRI Imaging occupy the largest installed base segments, with CT dominating trauma and orthopedic workflows where speed and bone resolution matter most. Cloud-Based Imaging represents the fastest-expanding technology category as hospital networks seek centralized image archives and remote surgical consultation capabilities. Fluoroscopy retains stronghold status in cardiology applications where live catheter guidance demands continuous radiation-based visualization.
FDA 510(k) premarket notification requirements govern device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for Class III surgical navigation systems entering European markets. Japan's PMDA enforces Good Quality Management System Practices that extend approval timelines but elevate product reliability benchmarks for manufacturers seeking access. Stakeholders must monitor evolving cybersecurity guidance from FDA and IEC 81001-5-1 as network-connected imaging platforms become standard surgical infrastructure.
Market Dynamics
Modular platform bundling is compressing buyer decision cycles toward integrated surgical ecosystems rather than discrete hardware procurement, forcing vendors to anchor contracts through software layers and service continuity.
Growth Catalysts
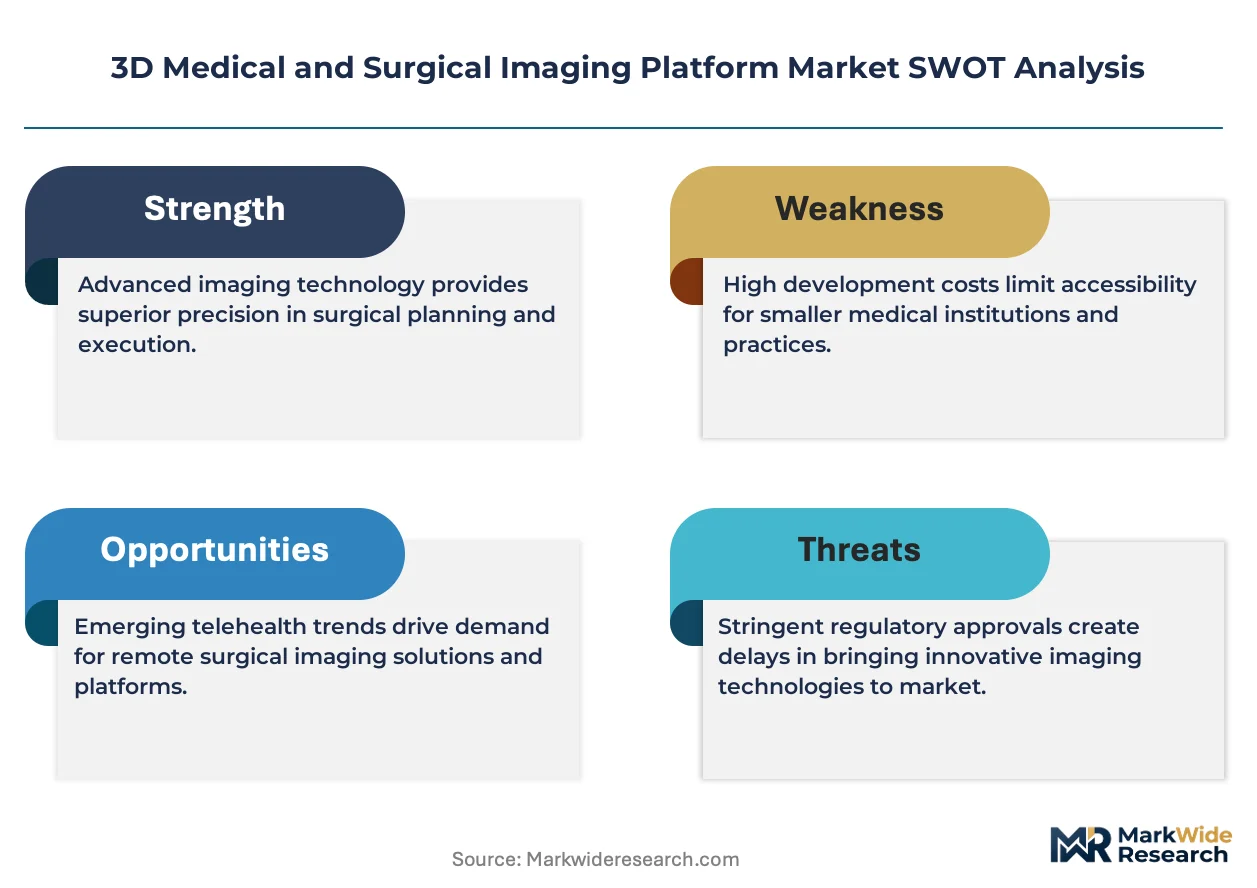
- EU Medical Device Regulation:Stricter clinical evidence standards for Class III surgical navigation systems are elevating product reliability benchmarks, creating competitive separation for compliant manufacturers.
- Cloud-Based Imaging:Hospital networks are consolidating image archives and enabling remote surgical consultation, expanding addressable infrastructure beyond physical suite installation.
- German surgical imaging cluster:Dense concentration of innovation around Siemens Healthineers and Brainlab AG accelerates knowledge spillover and talent pooling for adjacent vendors.
Market Restraints
- Photon-counting CT detector costs:Deep R&D intensity requirements for intraoperative tissue differentiation sharpen capital intensity barriers for mid-tier hardware entrants.
- Japan PMDA timelines:Extended Good Quality Management System Practices enforcement compresses revenue recognition windows for manufacturers seeking market access.
- Fluoroscopy radiation exposure limits:Continuous radiation-based visualization in cardiology faces substitution pressure from magnetic navigation alternatives in pediatric segments.
Strategic Opportunities
- FDA 510(k) pathway compression:AI-augmented surgical navigation tools benefit from accelerated premarket notification timelines, rewarding modular software-first development strategies.
- Intraoperative 3D imaging suite expansion:Orthopedic and neurological procedure volumes in high-acuity hospitals create replacement demand for legacy 2D C-arm systems.
- Neuronavigation software extension:Hardware-agnostic visualization layers enable recurring revenue capture without requiring full capital equipment replacement cycles.
Industry Challenges
- IEC 81001-5-1 cybersecurity compliance:Network-connected imaging platforms require continuous vulnerability management as standard surgical infrastructure, stretching IT integration capabilities.
- Iterative reconstruction algorithm talent:Sub-millimeter slice processing expertise concentrates among specialized academic programs, constraining vendor R&D scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Medical and Surgical Imaging Platform Market |
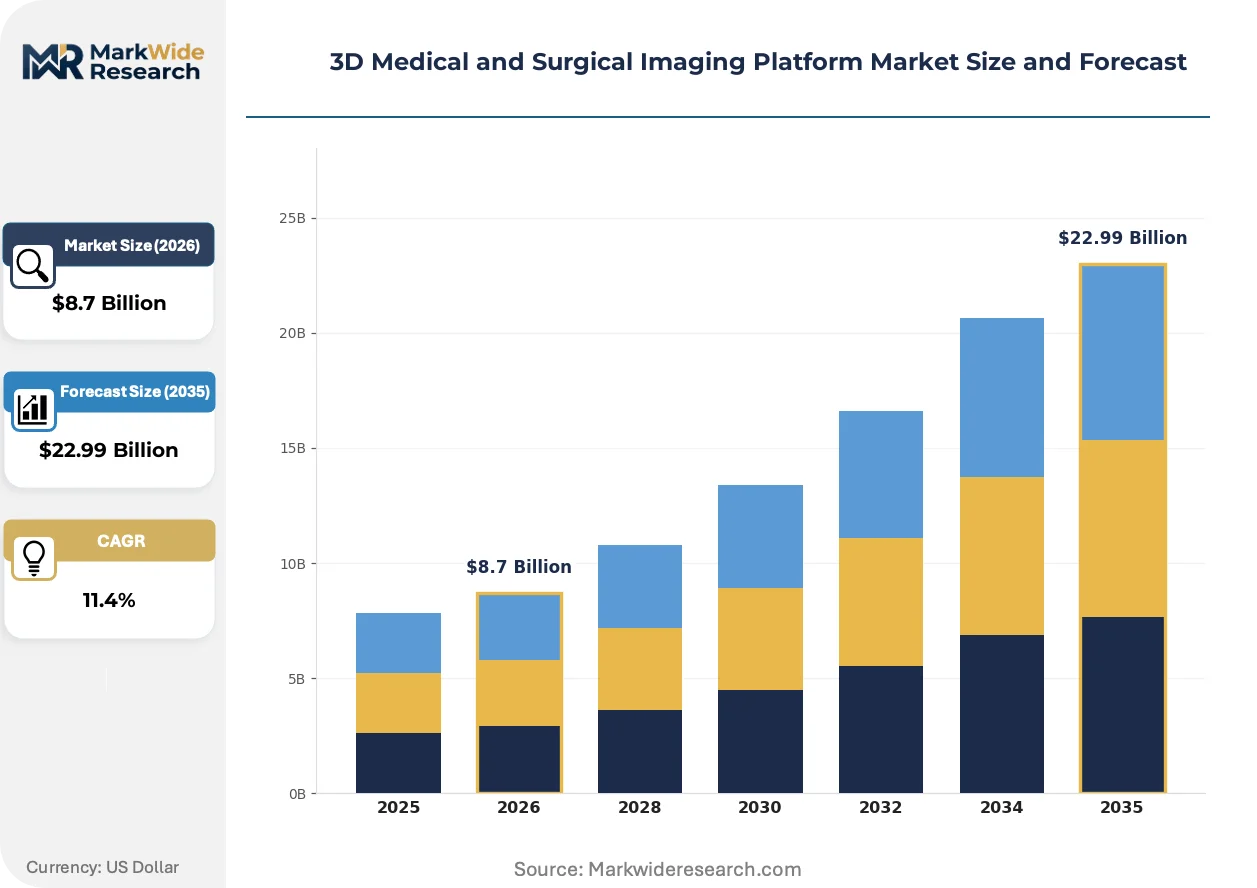
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Imaging, MRI Imaging, Ultrasonography, Fluoroscopy Technology: 3D Reconstruction, Image Processing, Real-Time Visualization, Cloud-Based Imaging End User: Hospitals, Surgical Centers, Research Institutions, Academic Medical Centers Application: Orthopedics, Cardiology, Oncology, Neurology |
| Companies Covered | Medtronic Inc., Stryker Corp., GE HealthCare, Olympus Corporation, Canon Medical Systems Ltd, Siemens Healthineers, Brainlab AG, Fujifilm, Koninklijke Philips NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Medical and Surgical Imaging Platform Market Strategic Shifts
Reconstruction algorithms and real-time visualization software are displacing hardware-centric value capture, compressing differentiation cycles toward computational performance and interoperability architecture.
AI-augmented surgical navigation is automating intraoperative anatomical registration and instrument tracking, reducing reliance on manual landmark identification by operating theater staff. Academic medical centers and high-volume orthopedic hospitals are deploying these tools at compressed procurement cycles compared to traditional capital equipment. This automation is compressing training timelines for surgical teams and expanding eligible procedure volumes to community hospital settings previously excluded from complex navigation workflows.
FDA cybersecurity guidance evolution is mandating premarket submission of software bill of materials and vulnerability management plans for network-connected imaging platforms. Device manufacturers must embed security-by-design into iterative reconstruction pipelines rather than retrofitting post-clearance. Surgical navigation systems with embedded AI inference engines face the steepest compliance burden, driving consolidation toward vendors with captive cybersecurity expertise.
Hospital procurement committees are unbundling after-sales service contracts from initial hardware purchase agreements, compressing vendor margin structures toward discrete performance-based maintenance. Integrated surgical ecosystem vendors face disintermediation risk as third-party service specialists capture preventive maintenance and software update revenue. This unbundling is most visible in German and United States markets where hospital procurement sophistication and alternative service provider density are highest.
3D Medical and Surgical Imaging Platform Market Segmentation
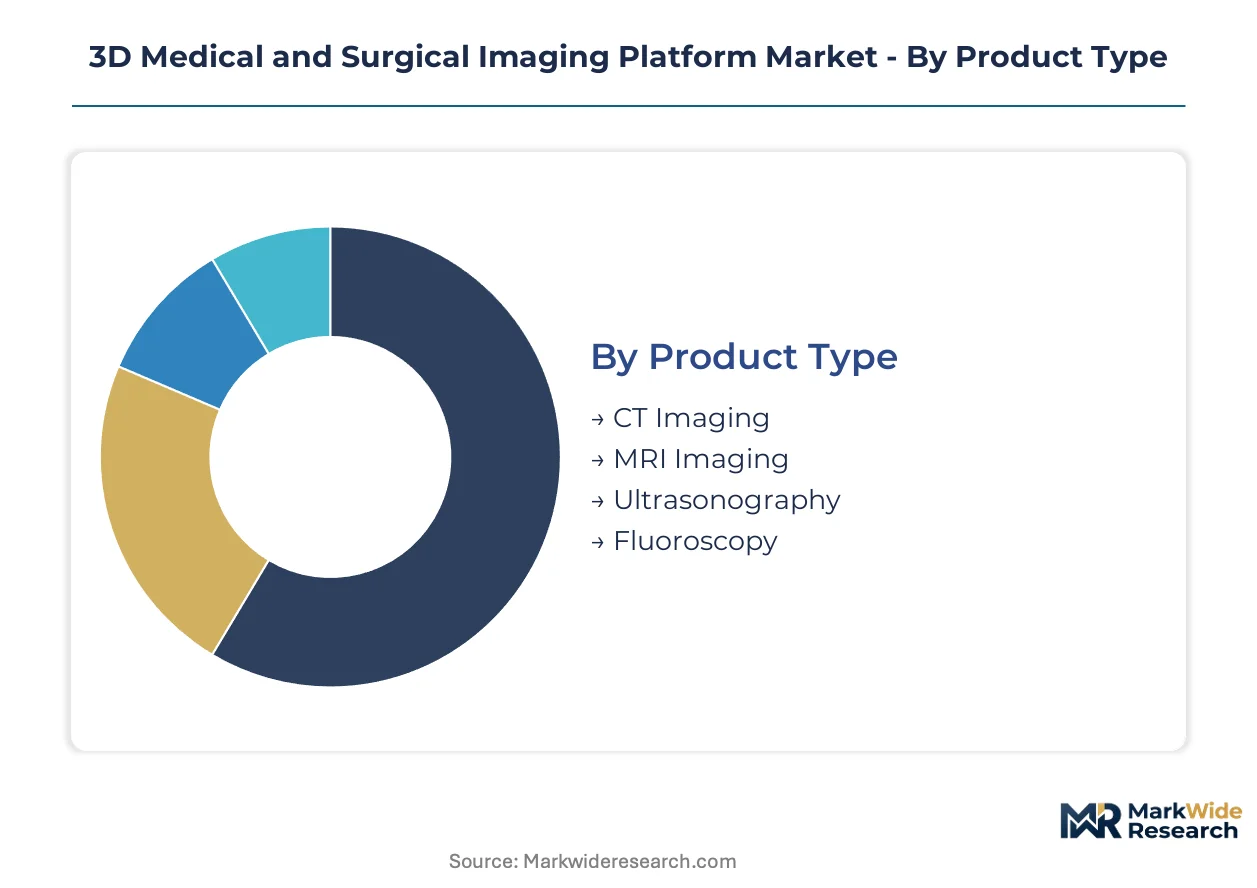
Segmentation in surgical imaging platforms tracks how capital equipment cycles, software licensing models, and procedure volumes concentrate revenue across hardware configurations and institutional tiers. Buyers evaluate total cost of ownership across replacement timelines rather than acquisition price alone.
Product Type:
Replacement cycles vary sharply across modalities, with trauma and orthopedic workflows driving faster refresh rates for bone-optimized systems than soft-tissue platforms.
- CT Imaging:Volumetric acquisition systems using rotating X-ray sources and detector arrays generate sub-millimeter isotropic datasets for intraoperative navigation. Demand concentrates in high-acuity hospitals across Germany and the United States where orthopedic trauma volumes justify dedicated intraoperative suites.
- MRI Imaging:Magnetic resonance platforms provide superior soft-tissue contrast without ionizing radiation, enabling neurological and oncological interventions. Adoption in academic medical centers accelerates as intraoperative MRI suites expand resection accuracy for brain tumor procedures.
- Ultrasonography:Piezoelectric transducer arrays deliver real-time imaging without radiation exposure, dominating pediatric and obstetric applications where safety protocols restrict alternative modalities.
- Fluoroscopy:Continuous X-ray projection systems maintain installed base dominance in cardiology catheterization labs despite radiation exposure substitution pressures.
CT Imaging sits at the top of the volume ranking, with MRI Imaging climbing the fastest as intraoperative soft-tissue navigation protocols mature.
Technology:
Software and computational layers now capture margin that hardware once monopolized, with cloud architectures enabling recurring revenue models distinct from capital sale cycles.
- 3D Reconstruction:Iterative algorithms transform raw projection data into volumetric models through computed tomography or magnetic resonance source data. German hospital networks deploy these tools for preoperative surgical planning across orthopedic and maxillofacial service lines.
- Image Processing:Noise reduction, contrast enhancement, and artifact correction pipelines prepare raw acquisitions for clinical interpretation. Research institutions in the United States drive demand for research-grade processing workstations supporting quantitative imaging biomarker development.
- Real-Time Visualization:GPU-accelerated rendering engines project 3D anatomical models onto 2D displays for intraoperative guidance, compressing the latency between data acquisition and surgical decision.
- Cloud-Based Imaging:Centralized PACS architectures with web-native viewers enable remote consultation and multi-site image sharing without local infrastructure replication.
Image Processing commands the largest installed base, while Cloud-Based Imaging gains share fastest as hospital consolidation creates multi-site network demand.
End User:
Procurement authority and budget scale determine access to integrated platform ecosystems versus standalone device configurations.
- Hospitals:Integrated delivery networks with centralized capital planning committees negotiate enterprise contracts for angiography-CT hybrid suites and service bundling.
- Surgical Centers:Ambulatory facilities prioritize compact footprint systems with rapid workflow optimization for high-volume orthopedic procedures.
- Research Institutions:Preclinical imaging cores require research-use-only configurations with flexible reconstruction algorithm access for method development.
- Academic Medical Centers:Teaching hospitals combine clinical service demands with resident training requirements, driving procurement of navigation platforms with simulation and recording capabilities.
Hospitals dominate procurement volume, with Surgical Centers expanding most quickly as outpatient migration accelerates joint replacement and spine procedure shifts.
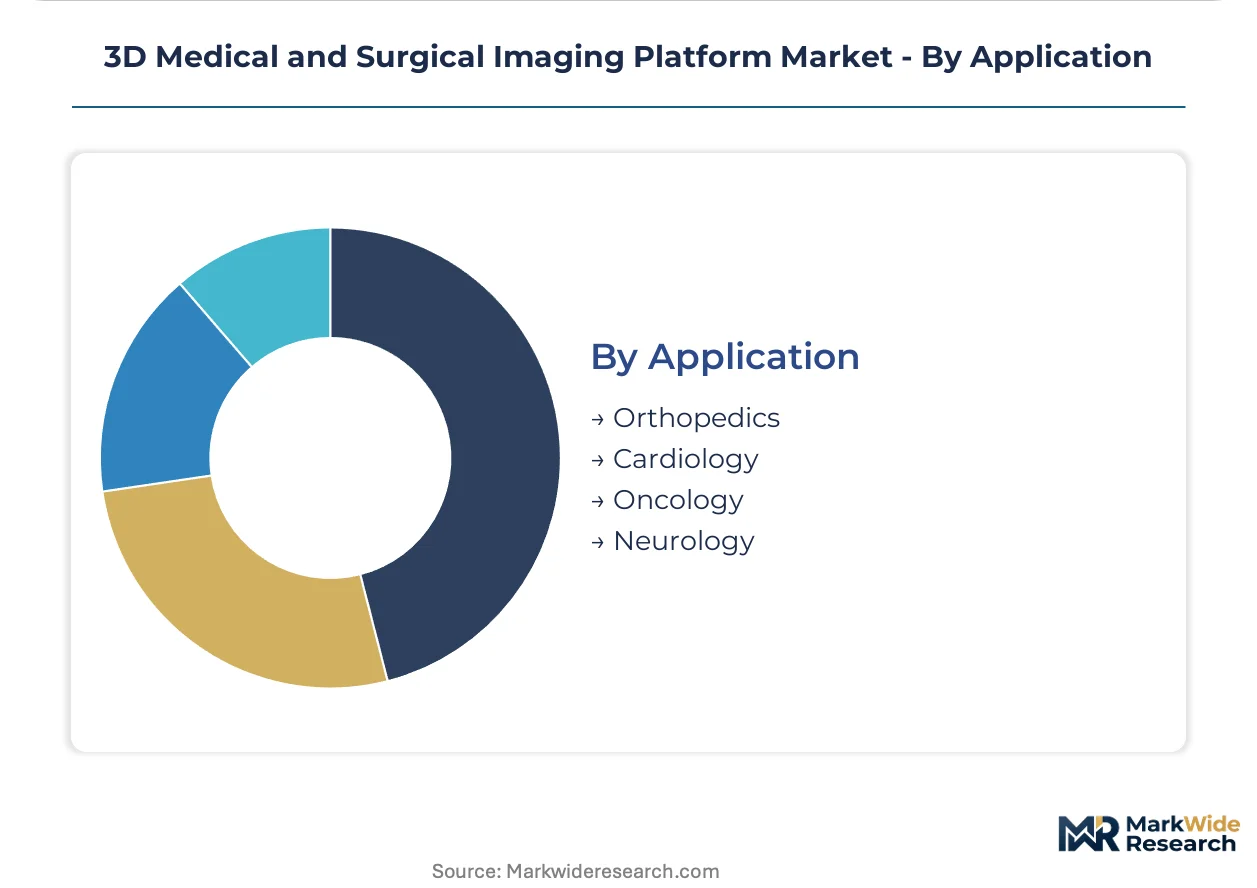
Application:
Procedure reimbursement levels and clinical outcome evidence determine capital allocation priority across surgical service lines.
- Orthopedics:Joint replacement and spinal fusion procedures leverage 3D navigation for implant positioning accuracy, with revision surgery cost avoidance justifying platform investment.
- Cardiology:Structural heart interventions and electrophysiology ablations depend on fluoroscopy and CT guidance for catheter navigation, though radiation exposure drives magnetic navigation substitution research.
- Oncology:Tumor resection margin assessment and radiation therapy planning utilize MRI and CT platforms for target delineation and treatment response monitoring.
- Neurology:Deep brain stimulation placement and epilepsy focus resection require sub-millimeter stereotactic accuracy, anchoring demand for neuronavigation-integrated imaging suites.
Orthopedics leads procedure volume, with Neurology posting the steepest expansion trajectory as functional neurosurgery indications broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The 3D medical and surgical imaging platform industry traces its commercial origins to German precision engineering clusters and post-war American hospital infrastructure buildouts. These two geographies established the foundational hardware-software integration models that subsequent markets adapted. Today, procurement patterns and regulatory frameworks diverge sharply across national healthcare systems.
United States
FDA 510(k) premarket notification pathways compress product development timelines for AI-augmented surgical navigation tools. The agency's evolving cybersecurity guidance mandates software bill of materials submission for network-connected imaging platforms. Academic medical centers in Boston and the Research Triangle anchor demand for intraoperative MRI suites and neuronavigation research programs.
Germany
The EU Medical Device Regulation imposes stricter clinical evidence standards for Class III surgical navigation systems entering European markets. Siemens Healthineers and Brainlab AG anchor a dense innovation cluster around Munich and Karlsruhe. German hospital networks deploy 3D reconstruction tools for preoperative orthopedic and maxillofacial surgical planning.
Japan
PMDA enforcement of Good Quality Management System Practices extends approval timelines but elevates product reliability benchmarks for manufacturers seeking market access. METI industrial policy supports domestic imaging component supply chains. Tokyo and Osaka metropolitan areas concentrate installed base expansion for intraoperative CT and fluoroscopy systems.
China
NMPA regulatory harmonization efforts accelerate market entry for multinational imaging platform vendors while tightening cybersecurity review for network-connected devices. The country's hospital tier system concentrates premium system procurement in tertiary facilities. Shanghai and Beijing medical centers drive adoption of hybrid angiography-CT suites for complex interventional procedures.
United Kingdom
NHS procurement frameworks emphasize total cost of ownership evaluation across replacement timelines rather than acquisition price alone. MHRA post-Brexit regulatory autonomy enables differentiated approval pathways from EU MDR synchronization. London and Manchester academic hospital trusts lead deployment of cloud-based imaging archives and remote surgical consultation infrastructure.
3D Medical and Surgical Imaging Platform Market Competitive Environment
Premium-margin players sit above commodity-margin players across software-software integration depth and service continuity architecture. The market structure concentrates around diversified health technology conglomerates with captive imaging hardware portfolios and specialized surgical navigation software boutiques. Three archetypes dominate: integrated ecosystem vendors bundling hardware-software-service, modular software specialists extending legacy hardware utility, and component suppliers capturing value at detector and reconstruction algorithm layers. Competitive moves center on M&A absorption of AI navigation startups and strategic partnerships between hardware OEMs and cloud infrastructure providers.
Among diversified health technology conglomerates, Siemens Healthineers AG, GE HealthCare, and Medtronic Inc. exemplify contrasting strategic positions. Siemens Healthineers anchors European high-acuity hospital contracts through angiography-CT hybrid suite bundling. GE HealthCare occupies a position emphasizing photon-counting CT detector R&D intensity for intraoperative tissue differentiation. Medtronic Inc. sits within the surgical navigation tier, representing hardware-agnostic software layer strategies that capture recurring revenue without full capital equipment replacement cycles.
| Leading Market Players |
|---|
| Medtronic Inc. |
| Stryker Corp. |
| GE HealthCare |
| Olympus Corporation |
| Canon Medical Systems Ltd |
| Siemens Healthineers |
| Brainlab AG |
| Fujifilm |
| Koninklijke Philips NV |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement committees unbundling after-sales service contracts from hardware purchase agreements forces vendors to absorb service costs into upfront pricing or surrender margin to third-party specialists. This disintermediation pressure concentrates in German and United States markets where alternative service provider density is highest, compressing integrated ecosystem vendor profitability toward discrete performance-based maintenance models.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates angiography-CT hybrid suites from modular software layers and standalone detector arrays. Certification grade under FDA 510(k) and EU MDR pathways, combined with after-sales service bundling, drives price differentiation between compliant and non-compliant tiers. Cost compression in mid-tier hardware is intensifying because photon-counting CT detector R&D requirements sharpen capital barriers. Surgical centers exhibit the highest price sensitivity, while academic medical centers prioritize performance over acquisition cost.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States anchor hub-and-spoke patterns for detector arrays, reconstruction algorithm licenses, and GPU-accelerated rendering engines. Manufacturing draws from specialized semiconductor foundries for photon-counting sensors, rare earth magnet suppliers for MRI components, and precision optics fabricators in Japan and Germany. Single-source vulnerability concentrates in iterative reconstruction algorithm talent pools anchored at specialized academic programs. Distribution runs through hospital GPO contracts and direct OEM-to-health system agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on software layer monetization decoupled from capital equipment cycles, with AI-augmented navigation tools capturing recurring revenue without full system replacement.
For Market Incumbents: Acquire AI navigation startups specializing in neuronavigation software layers to anchor recurring revenue streams independent of hardware refresh cycles. Absorb cybersecurity expertise to meet FDA software bill of materials requirements. Backward integration into photon-counting detector fabrication secures supply against single-source vulnerability while differentiating tissue differentiation performance. For New Entrants and Emerging Players: Capture cloud-based imaging infrastructure contracts in United Kingdom and United States hospital networks consolidating multi-site archives. Target ambulatory surgical centers migrating joint replacement procedures from inpatient settings, where compact footprint systems with rapid workflow optimization face less entrenched vendor relationships. Position through hardware-agnostic visualization software that extends legacy C-arm utility without requiring full capital replacement. For Investors and Strategic Acquirers: Asymmetric upside sits with modular software specialists commanding neuronavigation and real-time visualization layers that extract value from installed hardware bases. Long-term viability favors vendors with captive cybersecurity compliance capabilities and FDA 510(k) pathway expertise. Watch for hospital procurement committee unbundling acceleration as signal for service revenue disintermediation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Navigation | Accelerated premarket timelines reward modular software-first development strategies for AI-augmented tools. |
| Hospital System Partnership | Enterprise contracts for angiography-CT hybrid suites lock in high-acuity facilities across German networks. |
| Software Companion Development | Neuronavigation layers extend hardware utility without requiring full capital equipment replacement cycles. |
| CE Marking Pathway | EU MDR compliance creates competitive separation for Class III surgical navigation system vendors. |
| Reimbursement Strategy | Outcome-based contracting aligns platform investment with revision surgery cost avoidance in orthopedics. |
Study Parameters
Bottom-up hospital and surgical center procurement modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and neuroradiology department heads combined with secondary validation from FDA 510(k) filings, EU MDR certification databases, hospital procurement records, and CMS Medicare reimbursement data. Triangulation across these sources ensures segmentation integrity across product type, technology, and end-user dimensions.
Input-output matrices map installed base expansion, replacement cycle timing, and software licensing attach rates to revenue generation across the projection horizon. Segmentation dimensions include imaging modality, deployment architecture, institutional tier, and regional regulatory cluster. CAGRs derive from procedure volume elasticity, capital equipment refresh patterns, and cloud infrastructure adoption curves. Forecast inputs incorporate photon-counting CT detector cost trajectories and AI-augmented navigation tool regulatory clearance velocity.
Underlying measurement precision varies by segment; cloud-based imaging and AI-augmented navigation carry tighter precision than legacy fluoroscopy installed base estimates. Forecasts reflect documented assumptions regarding hospital consolidation pace, regulatory harmonization progress, and cybersecurity compliance cost absorption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Dental Panoramic Radiography Market
Medical Imaging
C-Arms Market
Medical Imaging
AI Surgical Video Intelligence System Market
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
United Kingdom Magnetic Resonance Imaging Market
Medical Imaging
Malaysia Digital Radiography Market
Medical Imaging
France Digital X-Ray Devices Market
Medical Imaging
Mobile Radiography Systems Market
Medical Imaging
Forensic Imaging Market
Medical Imaging
SPECT Scanning Services Market
Medical Imaging
Global Pediatric Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Mexico Nuclear Imaging Market
Medical Imaging
China Mammography Market
Medical Imaging
Veterinary Computed Tomography Scanner Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
United Kingdom Mammography Market