
 Schizoaffective Disorders Treatment Market | 2026-2036
Schizoaffective Disorders Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Schizoaffective Disorders Treatment Market Outlook
Long-acting injectable (LAI) formulations of second-generation antipsychotics is rebalancing the cost structure of maintenance therapy by reducing hospitalization frequency and improving medication adherence metrics. Johnson & Johnson leverages its established LAI portfolio across inpatient and outpatient channels. Eli Lilly and Company sustains competitive positioning through concentrated R&D investment in novel antipsychotic mechanisms. Lundbeck A/S anchors European market access with specialized psychiatric commercial infrastructure.
Schizoaffective disorders treatment encompasses pharmacological and psychosocial interventions targeting the dual symptom dimensions of psychosis and mood disturbance, with long-acting injectable risperidone and paliperidone formulations representing critical technical specifications for maintenance-phase therapy. The product type dimension shows antipsychotics commanding the largest revenue pool while psychotherapy segments expand fastest through integrated care mandates. The end user dimension reveals hospitals retaining dominant volume share as rehabilitation centers capture disproportionate growth from step-down care program expansion.
FDA approval pathways for novel antipsychotic entities and EMA centralized marketing authorization procedures shape clinical trial design and commercial launch sequencing across North America and Europe. The Drug Enforcement Administration and state-level controlled substance boards impose distribution constraints on certain mood stabilizer compounds, limiting channel flexibility. Stakeholders must monitor evolving FDA guidance on digital therapeutics adjuncts and corresponding payer coverage determinations to anticipate reimbursement disruption.
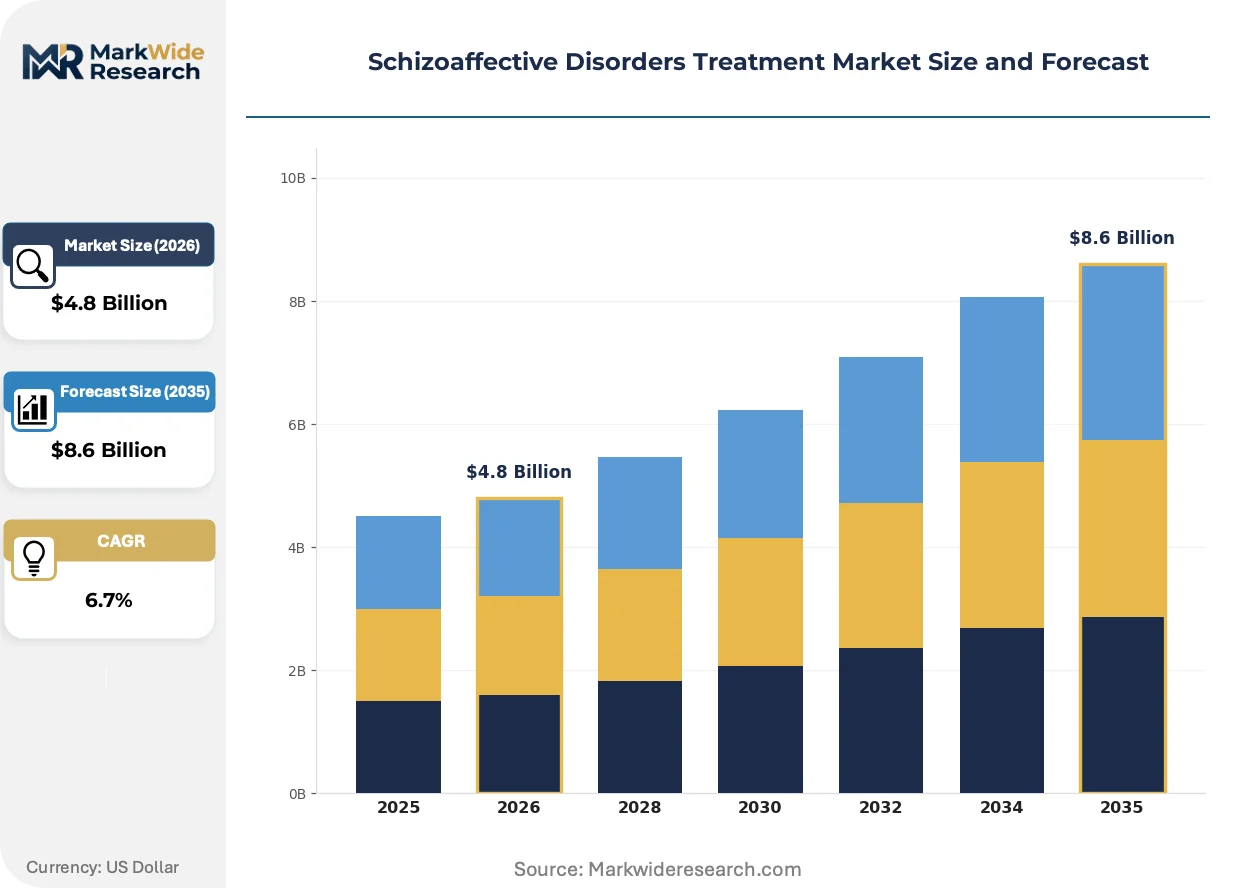
Market Dynamics
Long-acting injectable formulations are restructuring maintenance therapy economics by compressing hospitalization cycles and anchoring outpatient reimbursement models around adherence metrics rather than acute intervention frequency.
Growth Catalysts
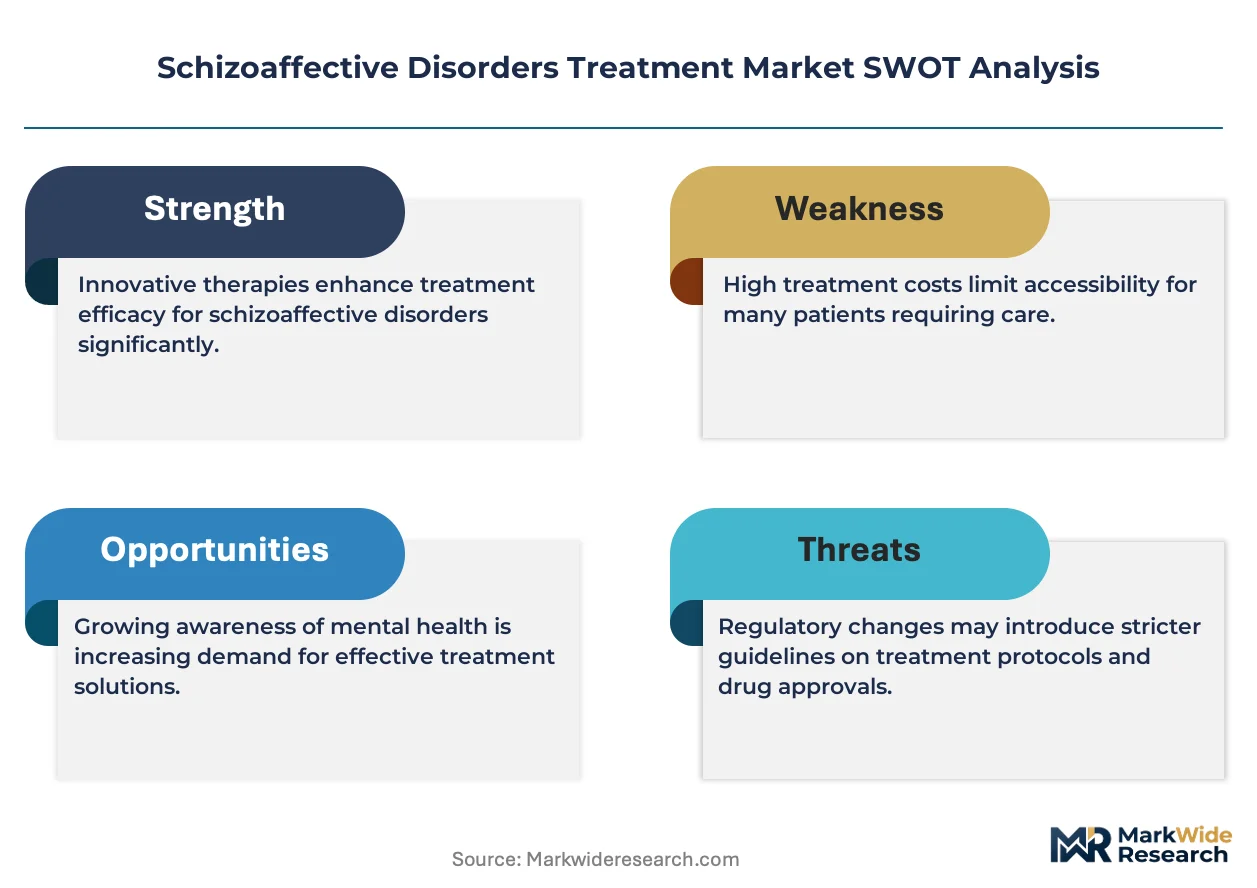
- CMS Reimbursement Expansion:Medicare payment reforms for psychiatric hospital outpatient departments now explicitly cover LAI administration costs, incentivizing facility-based program investment.
- Integrated Care Mandates:State-level behavioral health parity enforcement in California and New York requires commercial payers to cover psychotherapy alongside pharmacotherapy without prior authorization barriers.
- Patient Adherence Technology:Digital medication monitoring platforms embedded in specialty pharmacy workflows enable real-time compliance tracking that satisfies managed care contract requirements.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for atypical antipsychotics clusters among Indian and Chinese contract manufacturers, exposing formulation sponsors to import inspection delays.
- Specialty Workforce Scarcity:Board-certified psychiatrist availability constraints in rural Texas and Mississippi counties limit LAI program expansion regardless of capital deployment.
- DEA Distribution Controls:Schedule II classification of certain mood stabilizer compounds imposes vault storage and chain-of-custody requirements that elevate pharmacy infrastructure costs.
Strategic Opportunities
- Step-Down Care Networks:Community mental health centers in Florida and Ohio represent underpenetrated channels for LAI maintenance programs transitioning patients from inpatient settings.
- Telehealth-Enabled Medication Management:FDA guidance on remote therapeutic monitoring creates regulatory runway for virtual LAI injection supervision models in federally qualified health centers.
- Psychotherapy Reimbursement Codes:New CPT billing categories for cognitive behavioral therapy for psychosis allow providers to bundle pharmacological and psychosocial interventions under single-case rates.
Industry Challenges
- Psychiatric Nurse Practitioner Training Bottlenecks:Accelerated LAI administration certification programs face accreditation backlogs that constrain clinic staffing velocity.
- EHR Interoperability Friction:State prescription drug monitoring program integration with commercial electronic health record platforms requires costly custom interface development for multi-site practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Schizoaffective Disorders Treatment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antipsychotics, Mood Stabilizers, Antidepressants, Psychotherapy Therapy Area: Bipolar Disorder, Major Depressive Disorder, Schizophrenia, Others End User: Hospitals, Rehabilitation Centers, Outpatient Clinics, Home Care Delivery Mode: Injections, Oral, Intravenous, Transdermal |
| Companies Covered | Pfizer Inc., Johnson & Johnson, Eli Lilly and Company, AstraZeneca plc, Bristol-Myers Squibb Company, Otsuka Pharmaceutical Co., Ltd., Lundbeck A/S, AbbVie Inc., Alkermes Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Schizoaffective Disorders Treatment Market Strategic Shifts
Digital therapeutics and remote patient monitoring are converging with pharmacological protocols to create hybrid care models that redefine where and how schizoaffective disorder maintenance therapy is delivered.
Subcutaneous long-acting injectable delivery systems are consolidating the technical landscape for second-generation antipsychotics by enabling smaller injection volumes and reduced site-reaction profiles. Community mental health centers in Pennsylvania and Illinois are adopting these platforms at accelerating pace to support same-day discharge protocols. The technology is consolidating patient preference around less frequent clinic visits and expanding the addressable population for outpatient maintenance programs.
FDA draft guidance on prescription digital therapeutics for serious mental illness is reshaping trial design requirements and predicate device pathways for adjunctive schizophrenia applications. The framework imposes novel clinical endpoint validation standards that extend development timelines for software-based interventions. Psychiatric hospital systems are responding by establishing internal digital health evaluation committees to assess vendor capabilities ahead of formal coverage determinations.
Specialty pharmacy carve-out arrangements are displacing traditional retail distribution for high-cost antipsychotic formulations as payers seek tighter utilization management. These models centralize patient onboarding, adherence counseling, and outcomes reporting through contracted pharmacy benefit managers. The shift is most visible in Medicaid managed care plans across Michigan and Arizona where state contracts mandate exclusive specialty pharmacy networks for behavioral health medications.
Schizoaffective Disorders Treatment Market Segmentation
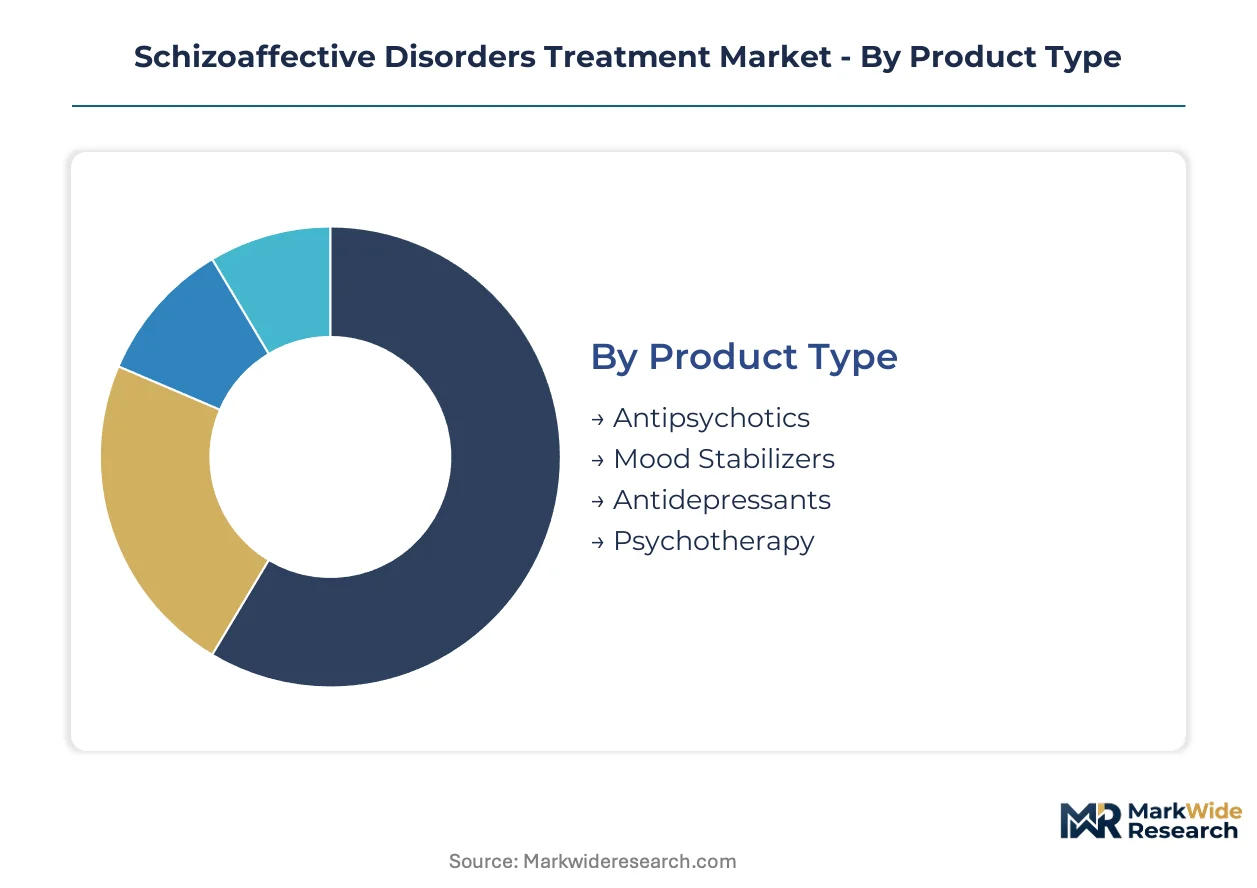
Treatment modality selection in schizoaffective disorders follows distinct clinical pathways where maintenance-phase economics favor long-acting formulations. Segmentation reveals how reimbursement structures and prescriber training distribution concentrate volume in specific channels and delivery mechanisms.
Product Type:
Supply concentration for active pharmaceutical ingredients clusters among contract manufacturers in India and China, creating formulation bottlenecks that shape competitive positioning across therapeutic categories.
- Antipsychotics:Second-generation agents including risperidone and paliperidone formulations constitute the clinical backbone of maintenance therapy. Demand concentrates in United States specialty psychiatric hospitals where CMS reimbursement for long-acting injectable administration drives formulary placement decisions.
- Mood Stabilizers:Lithium compounds and anticonvulsant derivatives target the affective dimension of schizoaffective presentations. United States demand clusters in state Medicaid programs where prior authorization requirements for newer agents sustain generic prescribing patterns.
- Antidepressants:Selective serotonin reuptake inhibitors and adjunctive agents address depressive polarity episodes.
- Psychotherapy:Cognitive behavioral therapy for psychosis and family interventions represent non-pharmacological standards of care.
Today's leader: Antipsychotics. Tomorrow's challenger: Psychotherapy.
Therapy Area:
Diagnostic coding specificity determines reimbursement rates and influences prescriber specialty referral patterns across institutional settings.
- Bipolar Disorder:Mood stabilizer combinations with atypical antipsychotics dominate maintenance protocols. Rehabilitation centers in Florida capture disproportionate volume from step-down care mandates requiring integrated mood and psychosis management.
- Schizophrenia:Long-acting injectable antipsychotics anchor maintenance-phase economics. United States community mental health centers in Ohio and Pennsylvania drive adoption of subcutaneous delivery systems enabling reduced injection frequency.
- Major Depressive Disorder:Antidepressant augmentation strategies address psychotic features in depressive presentations.
- Others:Residual diagnostic categories capture treatment-resistant presentations requiring polypharmacy approaches.
Bipolar Disorder commands current volume. Schizophrenia applications are climbing the fastest.
End User:
Facility-based reimbursement differentials create channel arbitrage opportunities that redistribute patient volume across care settings.
- Hospitals:Inpatient psychiatric units and emergency departments manage acute exacerbations requiring rapid stabilization. United States specialty psychiatric hospitals retain dominant volume share through established long-acting injectable administration infrastructure.
- Rehabilitation Centers:Residential and intensive outpatient programs bridge acute and community care. Florida and Ohio centers expand fastest through Medicaid managed care contracts mandating step-down placement for extended stays.
- Outpatient Clinics:Federally qualified health centers and private psychiatric practices deliver maintenance therapy.
- Home Care:Visiting nurse services support medication adherence for geographically isolated patients.
Hospitals anchor current revenue. Rehabilitation Centers present the steepest expansion trajectory.
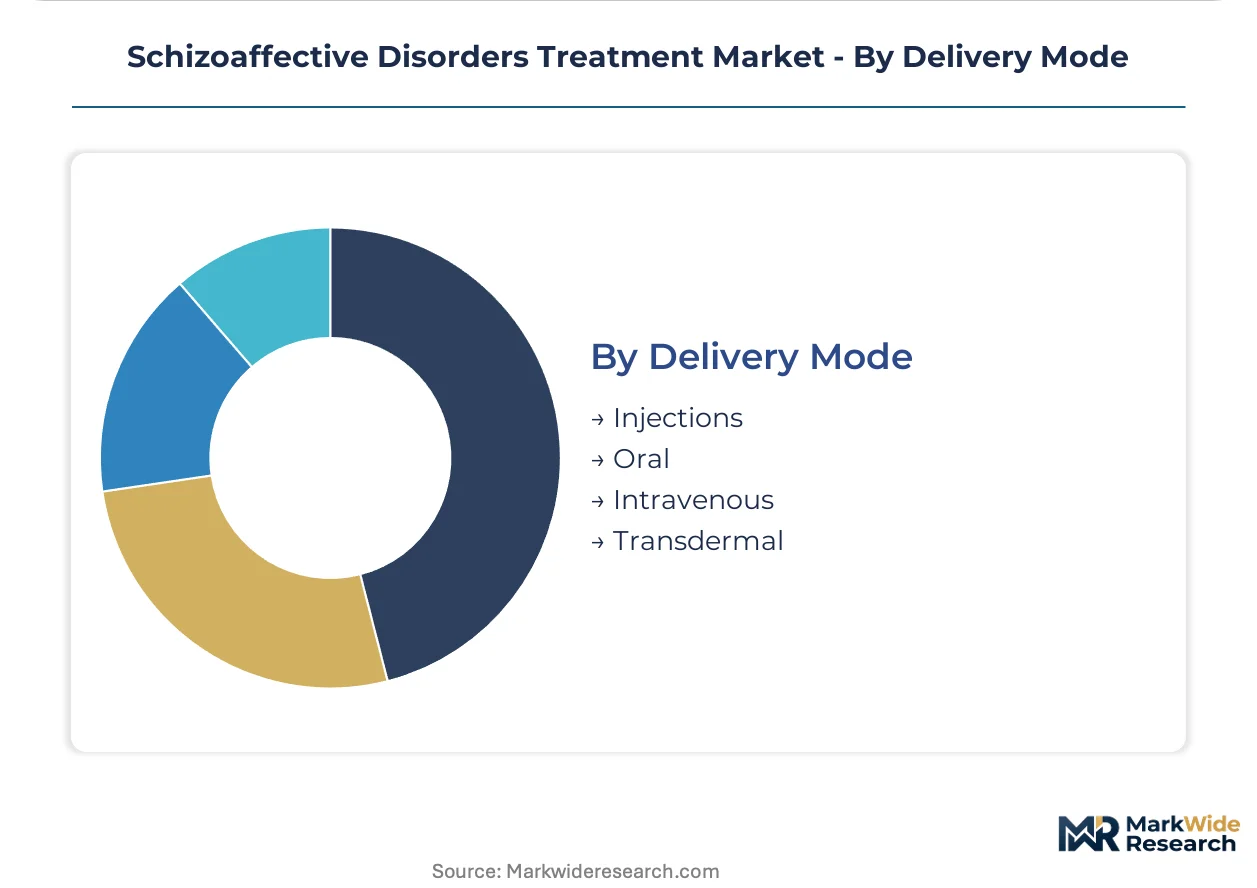
Delivery Mode:
Pharmacokinetic profile requirements and patient preference data reshape formulation development priorities across administration routes.
- Injections:Long-acting intramuscular and subcutaneous depot formulations eliminate daily adherence requirements. United States specialty pharmacy networks in Michigan and Arizona centralize distribution through exclusive Medicaid managed care carve-out arrangements.
- Oral:Immediate-release and extended-release tablets dominate initiation-phase prescribing. Retail pharmacy displacement by specialty channels accelerates as payers tighten utilization management for high-cost antipsychotic formulations.
- Intravenous:Acute agitation management in emergency psychiatric settings employs short-acting parenteral agents.
- Transdermal:Patch delivery systems address specific patient populations with swallowing difficulties or adherence barriers.
Injections lead maintenance-phase economics. Oral formulations retain initiation-phase dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty psychiatric hospitals in the United States anchor the dominant industrial cluster for schizoaffective disorder maintenance therapy, with reimbursement frameworks under CMS driving long-acting injectable program expansion across inpatient and outpatient channels.
United States
FDA approvals for atypical antipsychotic formulations concentrate prescriber behavior in specialty psychiatric hospitals, while Medicare payment reforms explicitly cover LAI administration costs. State-level behavioral health parity enforcement in California and New York mandates commercial payer coverage for integrated psychotherapy and pharmacotherapy without prior authorization barriers. Community mental health centers in Ohio and Pennsylvania accelerate adoption of subcutaneous delivery systems to support same-day discharge protocols.
Germany
EMA centralized marketing authorization procedures shape clinical trial sequencing for novel antipsychotic entities seeking European market entry. The country's statutory health insurance system maintains reimbursement pathways for long-acting injectable maintenance therapy through outpatient psychiatric clinics. Industrial concentration in Baden-Württemberg and Bavaria supports specialized pharmaceutical commercial infrastructure for psychiatric therapeutic categories.
United Kingdom
NICE technology appraisals determine formulary placement for second-generation antipsychotic formulations across NHS mental health trusts. The Medicines and Healthcare products Regulatory Agency imposes pharmacovigilance requirements that extend post-market surveillance obligations for LAI products. Greater London and the Southeast retain dominant patient volume through established community mental health team networks administering depot formulations.
Japan
PMDA regulatory pathways for psychiatric medications require domestic clinical trial data that extends development timelines for multinational sponsors. The Ministry of Health, Labour and Welfare maintains reimbursement listings that favor established antipsychotic formulations with demonstrated cost-effectiveness profiles. Industrial clusters in the Kanto region around Tokyo concentrate psychiatric pharmaceutical distribution and specialty pharmacy services.
India
CDSCO approval processes for imported psychiatric formulations create regulatory complexity for multinational sponsors seeking market access. The country's generic pharmaceutical manufacturing base supplies active pharmaceutical ingredients for atypical antipsychotics to global formulation sponsors. Maharashtra and Gujarat host contract manufacturing facilities that cluster API production for risperidone and paliperidone derivatives.
Schizoaffective Disorders Treatment Market Competitive Environment
Global majors compete with regional champions across long-acting injectable formulation expertise and psychiatric commercial infrastructure. The market structure consolidates around diversified pharmaceutical conglomerates with established CNS portfolios, while specialized neuropsychiatric firms occupy differentiated positions in maintenance therapy segments. Three archetypes dominate: integrated pharma conglomerates with broad psychiatric pipelines, specialized CNS-focused companies with concentrated commercial infrastructure, and generic manufacturers supplying API and formulation components. Competitive moves center on strategic partnerships for digital therapeutics integration and capacity expansion in subcutaneous delivery system manufacturing.
Within the integrated pharmaceutical tier, Johnson & Johnson and Eli Lilly and Company exemplify archetypal positioning through established long-acting injectable portfolios and concentrated psychiatric R&D investment. Lundbeck A/S occupies a specialized position anchoring European market access through dedicated neuropsychiatric commercial infrastructure. These three entities represent the competitive core around which reimbursement frameworks and prescriber relationships organize across North American and European markets.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| Eli Lilly and Company |
| AstraZeneca plc |
| Bristol-Myers Squibb Company |
| Otsuka Pharmaceutical Co., Ltd. |
| Lundbeck A/S |
| AbbVie Inc. |
| Alkermes Inc. |
| Others |
Value Chain & Pricing Dynamics
Active pharmaceutical ingredient spot indices for risperidone and paliperidone intermediates cascade through three-tier pricing structures across premium, standard, and economy levels, compressing margins for generic formulation sponsors while specialty pharmacy carve-outs consolidate buyer leverage in United States Medicaid managed care networks.
Pricing Analysis
Input-cost pass-through from Indian and Chinese API contract manufacturers drives pricing stratification across premium, standard, and economy tiers, with FDA-certified formulations commanding brand premiums over CDSCO-registered alternatives. Price differentiation hinges on bioequivalence certification status and specialty pharmacy distribution access, with cost compression in standard-tier oral generics intensifying due to Medicaid formulary preference for long-acting injectable alternatives. Hospital procurement committees exhibit lowest price sensitivity, while community mental health centers in rural Texas and Mississippi face acute budget constraints.
Supply Chain Analysis
Direct-to-specialty-pharmacy channels handle high-cost antipsychotic formulation distribution, bypassing traditional retail networks through exclusive Medicaid managed care carve-outs in Michigan and Arizona. API manufacturing concentrates in Maharashtra and Gujarat, India, and Jiangsu and Zhejiang, China, with formulation finishing clustered in United States and European sterile injectable facilities. The supply chain rests on risperidone base, paliperidone palmitate, and microsphere delivery system inputs, with single-source vulnerability in subcutaneous depot technology licensing creating bottleneck exposure for subcutaneous delivery system adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with prescriber demand shifting decisively toward long-acting injectable formulations that reduce hospitalization frequency and satisfy CMS reimbursement metrics.
For Market Incumbents: Hedge API supply exposure by qualifying secondary contract manufacturers in alternative Indian states beyond Maharashtra, while deepening captive production of paliperidone microsphere delivery systems to defend against emerging generic entrants with subcutaneous formulation capabilities. Lock in exclusive specialty pharmacy network contracts ahead of state Medicaid managed care re-procurement cycles.
For New Entrants and Emerging Players: FDA draft guidance on prescription digital therapeutics for serious mental illness opens a window for software-based adjunctive interventions that bundle with pharmacological protocols, targeting community mental health centers in Ohio and Pennsylvania as the most penetrable channel for remote therapeutic monitoring adoption. Pursue CPT code stacking for cognitive behavioral therapy for psychosis to enable bundled reimbursement submissions.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized CNS-focused companies with concentrated long-acting injectable formulation expertise and established psychiatric hospital system relationships. Five-to-ten-year viability hinges on digital therapeutics integration capabilities and subcutaneous delivery system manufacturing assets. Watch FDA approval velocity for novel antipsychotic mechanisms as the critical inflection signal for portfolio rebalancing toward next-generation maintenance therapy platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Injectable Manufacturing Scale-Up | Expands capacity to serve CMS-reimbursed outpatient psychiatric hospital programs and community mental health center networks. |
| Digital Therapeutics Regulatory Pathway | Positions adjunctive software interventions for FDA breakthrough designation under serious mental illness guidance. |
| Specialty Pharmacy Network Exclusivity | Secures preferred distribution status in Michigan and Arizona Medicaid managed care behavioral health carve-outs. |
| Subcutaneous Delivery System Licensing | Enables reduced injection volume offerings that accelerate same-day discharge protocol adoption in Pennsylvania. |
| Psychotherapy Reimbursement Bundling | Captures new CPT billing categories for cognitive behavioral therapy for psychosis under integrated care mandates. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors at United States specialty psychiatric hospitals, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulated segment-level estimates.
Segment-weighting approaches distributed value across antipsychotic, mood stabilizer, antidepressant, and psychotherapy product types, with further stratification by delivery mode, therapy area, and end-user channel across the projection horizon. CAGRs derived from historical prescription trajectory analysis and forward-looking reimbursement policy impact assessment, incorporating FDA approval timelines, state-level behavioral health parity enforcement patterns, and specialty pharmacy network expansion rates as key forecast inputs.
Revisions become necessary when FDA guidance on digital therapeutics finalizes, CMS reimbursement rules for remote therapeutic monitoring crystallize, or DEA scheduling decisions alter mood stabilizer distribution requirements. Forecasts reflect documented assumptions regarding LAI program expansion velocity and psychotherapy integration mandates. Periodic stress-testing of base assumptions against prescriber survey data and state Medicaid budget appropriations is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Maternal Mental Health Market
Mental Health Services
Seasonal Affective Disorder (SAD) Market
Mental Health Services
Behavioral Health Care Software and Services Market
Mental Health Services
Postpartum Depression Management Market
Mental Health Services
Global Behavioral Health Market
Mental Health Services
Post-Partum Depression Market
Mental Health Services
Mental Health Software Market
Mental Health Services
North America Maternal Mental Health Market
Mental Health Services
Global Anxiety Disorder Treatment Market
Mental Health Services
Global Mental Health Apps Market
Mental Health Services
Global Workplace Stress Management Market
Mental Health Services
Mental Health Market
Mental Health Services
Agoraphobia Treatment Market
Mental Health Services
US Behavioral Health Market
Mental Health Services
Depression Treatment Market
Mental Health Services
Spain Post-Traumatic Stress Disorder Treatment Market