
 North America Milk Powder Market | 2026-2036
North America Milk Powder Market Size, Share, and Industry Trends Forecast 2026-2036
North America Milk Powder Market Intelligence
Canada's Prairie provinces is reconfiguring North American skim milk powder availability through expanded drying capacity. Dairy Farmers of America leverages its cooperative structure to anchor bulk ingredient supply contracts across the Midwest. Saputo Inc. competes through integrated cheese and powder operations that sustain margin capture from fluid milk volatility. Lactalis American Group specializes in nutritional-grade powders for infant formula clients.
Milk powder comprises dehydrated dairy solids produced via spray-drying or roller-drying of pasteurized milk, typically achieving moisture content below 5% and protein specifications ranging from 26% to 36% depending on fat retention, serving as shelf-stable inputs for formulated foods and direct reconstitution. Whole milk powder retains butterfat for bakery and confectionery applications where flavor carry-through commands premium positioning, while skim milk powder dominates volume flows into infant formula and sports nutrition where protein standardization is critical. The food processing end-user channel controls the largest value pool through long-term contracting, whereas online stores represent the fastest-growing distribution channel as bulk buyers shift procurement to digital platforms.
The FDA enforces Grade A Pasteurized Milk Ordinance standards that dictate pathogen limits and compositional specifications for interstate milk powder commerce, while USDA grading programs certify quality tiers that influence export eligibility and price premiums. Health Canada's Food and Drug Regulations parallel these requirements for cross-border product movement, creating dual compliance obligations for processors serving both markets. Stakeholders must monitor evolving protein fortification claims and front-of-package labeling mandates that will reshape product formulation decisions and customer communication strategies.
Market Dynamics
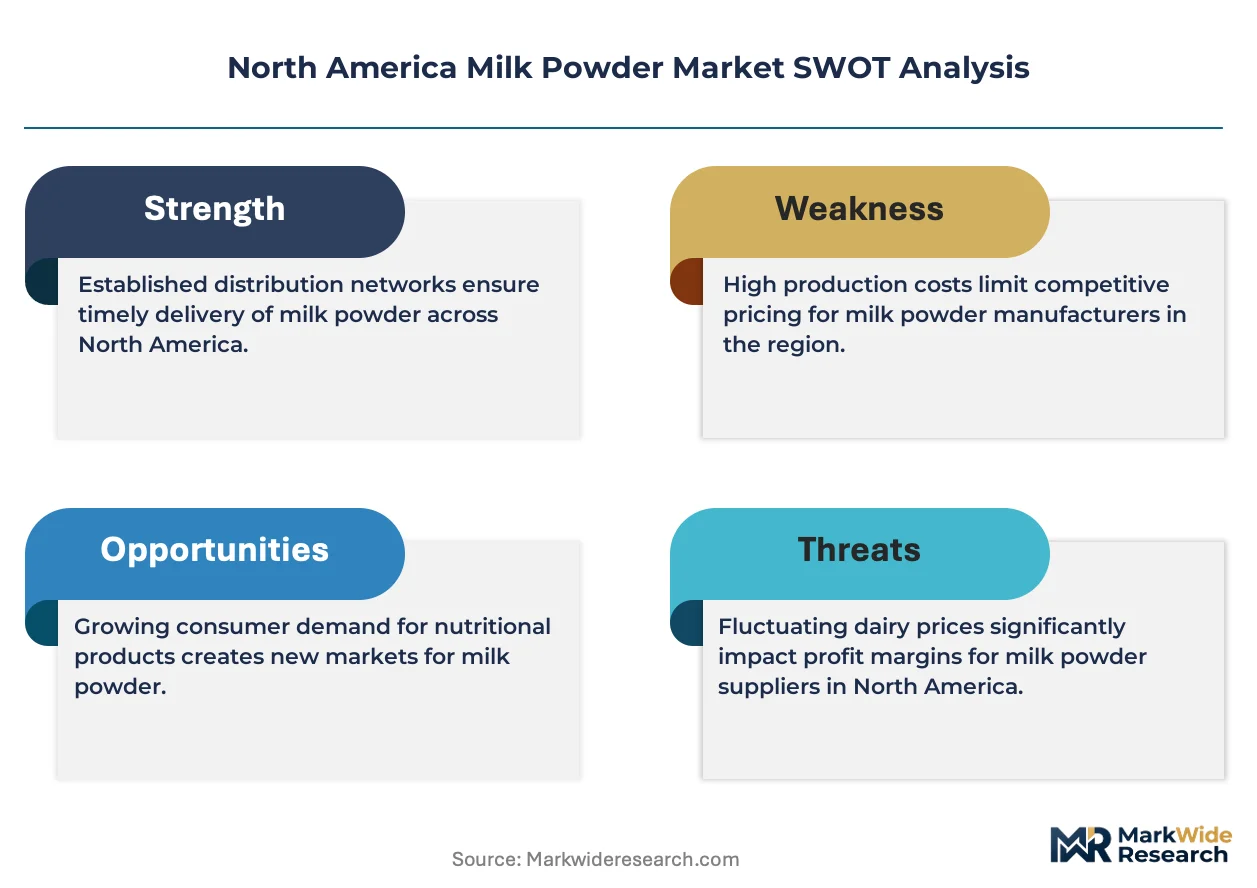
The North America milk powder market is experiencing structural compression from FDA protein declaration tightening, which forces reformulation across infant formula and sports nutrition channels while California's Central Valley processing corridor concentrates spray-drying capacity.
Growth Catalysts
- Infant formula procurement expansion:Mexican manufacturers are accelerating skim milk powder offtake to serve domestic birth-rate stabilization and export positioning into Central America.
- USDA grading certification:Quality-tier programs are unlocking premium export eligibility for processors meeting compositional thresholds, particularly into Asian nutritional markets.
- Spray-drying technology advancement:New atomization systems are reducing thermal degradation of whey proteins, enabling higher-value nutritional-grade powder production.
Market Restraints
- Fluid milk price volatility:Input cost swings from Dairy Farmers of America cooperative pricing mechanisms compress margin predictability for independent processors.
- Supply concentration risk:California's Central Valley corridor controls disproportionate spray-drying capacity, creating geographic single-point vulnerability.
- Plant-based substitution:Oat and pea protein isolates are capturing formulation share in sports nutrition where protein standardization is less stringent.
Strategic Opportunities
- Underpenetrated Canadian Prairie expansion:Saskatchewan and Alberta drying capacity additions are creating surplus skim milk powder availability for cross-border arbitrage.
- Digital procurement platforms:Bulk buyers are migrating from traditional broker networks to direct-to-processor online stores, compressing channel margins.
- Health Canada alignment:Harmonized Food and Drug Regulations with FDA standards are reducing dual-compliance costs for integrated North American operations.
Industry Challenges
- Protein analysis skill scarcity:Laboratory capacity for Kjeldahl and Dumas protein verification is constraining batch release velocity.
- Capex intensity for Grade A compliance:Pathogen testing infrastructure and aseptic packaging lines demand capital deployment that smaller cooperatives struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Milk Powder Market |
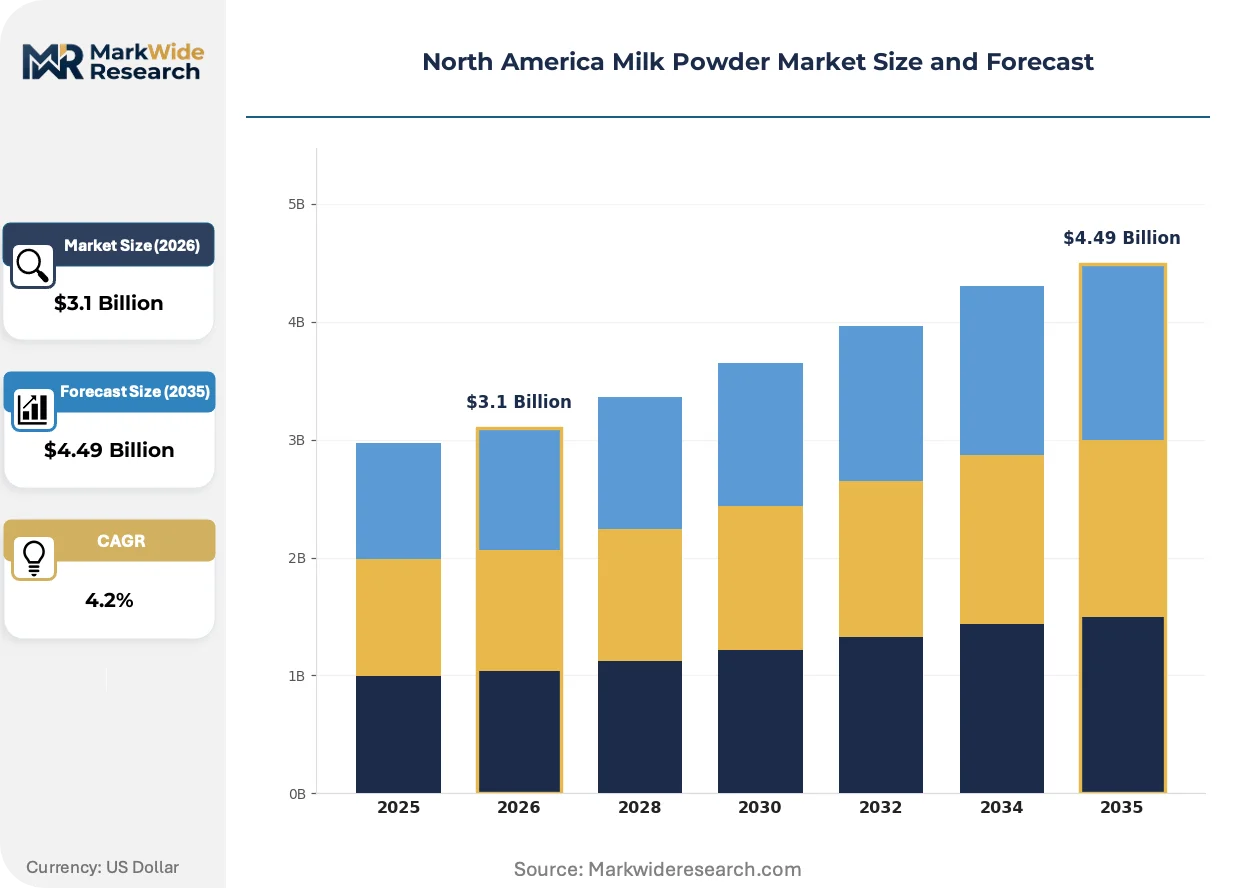
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Milk Powder, Skim Milk Powder, Dairy Cream Powder, Casein Application: Infant Formula, Bakery Products, Sports Nutrition, Dietary Supplements End User: Household, Foodservice, Food Processing, Nutritional Supplements Distribution Channel: Supermarkets, Online Stores, Specialty Stores, Wholesale |
| Companies Covered | Dairy Farmers of America, Saputo Inc., Land O'Lakes, Agropur Cooperative, The Kraft Heinz Company, Nestle, Lactalis American Group, Schreiber Foods, Dean Foods, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Milk Powder Market Strategic Shifts & Innovations
Membrane filtration advances and protein fractionation technologies are rewriting powder economics, while regulatory alignment pressures and buyer procurement digitization are compressing traditional channel structures across the continent.
Microfiltration and ultrafiltration systems are collapsing the cost differential between commodity skim milk powder and protein concentrates. Infant formula manufacturers in Mexico and the US Midwest are adopting these systems at accelerated replacement cycles. The technology is collapsing the historical premium capture of specialized whey protein isolate suppliers by enabling in-house protein standardization.
FDA updated dairy labeling standards are mandating nitrogen-to-protein conversion factor revisions that tighten protein content declarations. Processors must reformulate or restate specifications across product lines, triggering reformulation costs. Infant formula and sports nutrition segments are responding by investing in third-party laboratory verification capacity to preempt enforcement actions.
Bulk buyers are consolidating procurement through direct digital platforms that disintermediate traditional dairy brokers and cooperatives. Food processing end-users with annual volume thresholds above 500 metric tons are negotiating direct contracts with California and Prairie province dryers. The shift is most visible in California's Central Valley, where processors report 40% of new contracts originate through platform-based discovery rather than relationship-based brokerage.
North America Milk Powder Market Segmentation
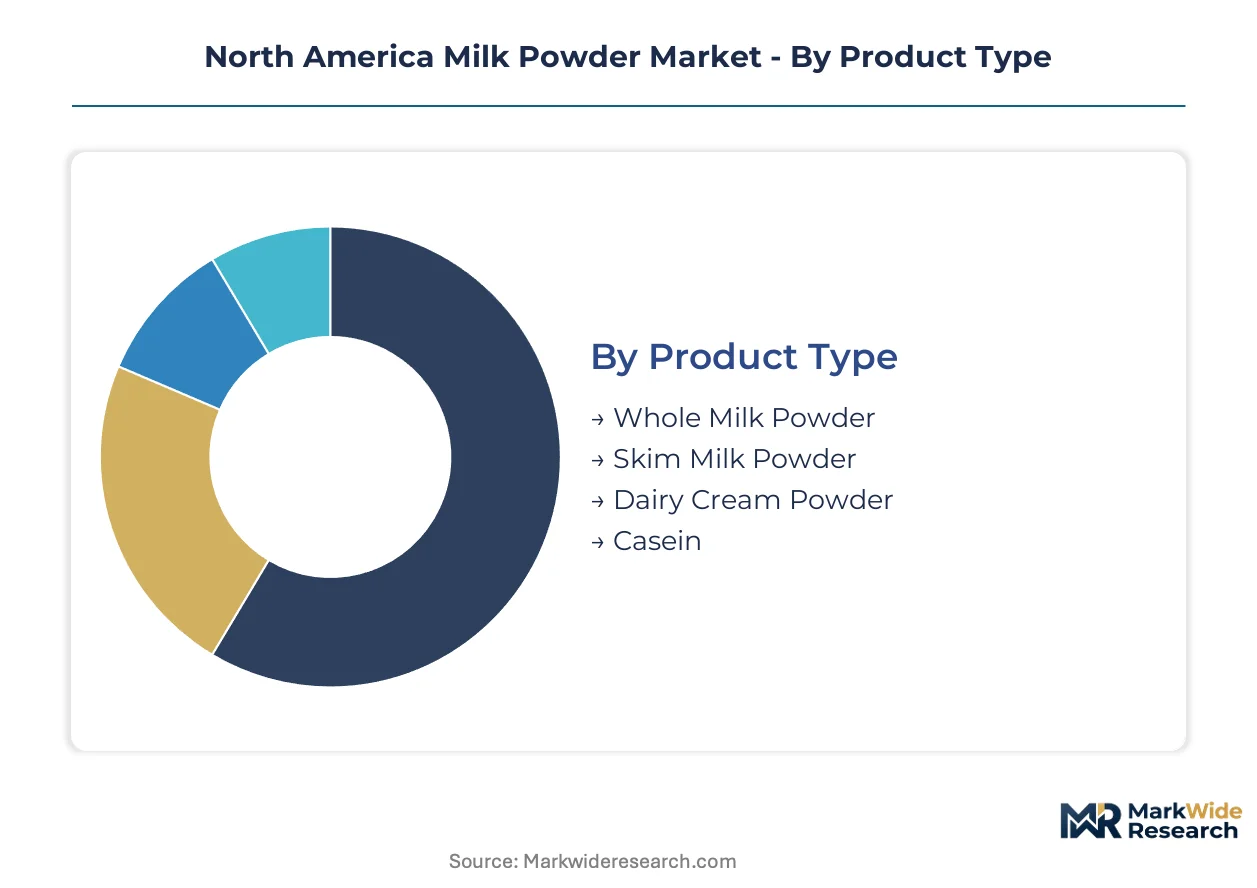
Segmentation in the North America milk powder market reveals how protein specifications, shelf stability requirements, and procurement scale reshape competitive positioning across distinct buyer profiles. Understanding these divides exposes where margin capture concentrates and where digital disruption is reordering channel economics.
Product Type:
After-sales intensity varies sharply across powder categories, with nutritional-grade specifications demanding laboratory verification support that commodity grades do not require.
- Skim Milk Powder:Dehydrated non-fat milk solids achieving 34-36% protein content through spray-drying, standardized for infant formula protein fortification. Mexican manufacturers are accelerating procurement to serve Central America export positioning while California's Central Valley processors expand drying capacity. FDA protein declaration tightening is forcing reformulation investments across this segment.
- Whole Milk Powder:Retains 26-28% butterfat content for flavor carry-through in bakery and confectionery applications where organoleptic performance commands premium positioning. Demand concentrates in California's processing corridor where integrated butter-powder operations sustain margin capture from fluid milk volatility.
- Dairy Cream Powder:Higher fat retention powder serving foodservice reconstitution and industrial sauce applications.
- Casein:Protein isolate segment for specialized nutritional and industrial binding applications.
Skim milk powder holds the largest share; momentum sits with whole milk powder as bakery and confectionery channels prioritize flavor differentiation.
Application:
Cost tier stratification separates commodity food processing applications from nutritional-grade segments where third-party certification commands price premiums.
- Infant Formula:The most stringently regulated application requiring USDA grading certification and FDA Grade A Pasteurized Milk Ordinance compliance for interstate commerce. Mexican manufacturers are expanding procurement to serve domestic birth-rate stabilization and Central America export markets. Health Canada alignment with FDA standards is reducing dual-compliance costs for cross-border processors.
- Sports Nutrition:Protein standardization-critical segment where membrane filtration advances are collapsing cost differentials between commodity powders and protein concentrates. Plant-based isolates from oat and pea proteins are capturing formulation share where protein specifications are less stringent.
- Bakery Products:Volume-driven channel for whole milk powder in flavor-sensitive applications.
- Dietary Supplements:Nutritional-grade powder segment for direct-to-consumer protein fortification.
Food processing channels dominate volume; sports nutrition is expanding most quickly as membrane filtration enables in-house protein standardization.
End User:
Customer type determines contract structure, with annual volume thresholds above 500 metric tons unlocking direct-to-processor negotiations that bypass traditional brokerage.
- Food Processing:Controls the largest value pool through long-term contracting for formulated foods and industrial ingredient inputs. Bulk buyers are migrating from traditional broker networks to direct digital procurement platforms, compressing channel margins.
- Nutritional Supplements:Fastest-growing end-user channel as sports nutrition and direct-to-consumer protein fortification expand. Laboratory capacity for Kjeldahl and Dumas protein verification is constraining batch release velocity for this quality-sensitive segment.
- Foodservice:Reconstitution-driven demand for cream powders and standard-grade skim milk powder.
- Household:Retail-packaged segment for direct reconstitution and emergency food storage applications.
Food processing holds the largest share; momentum sits with nutritional supplements as protein fortification claims reshape consumer purchasing.
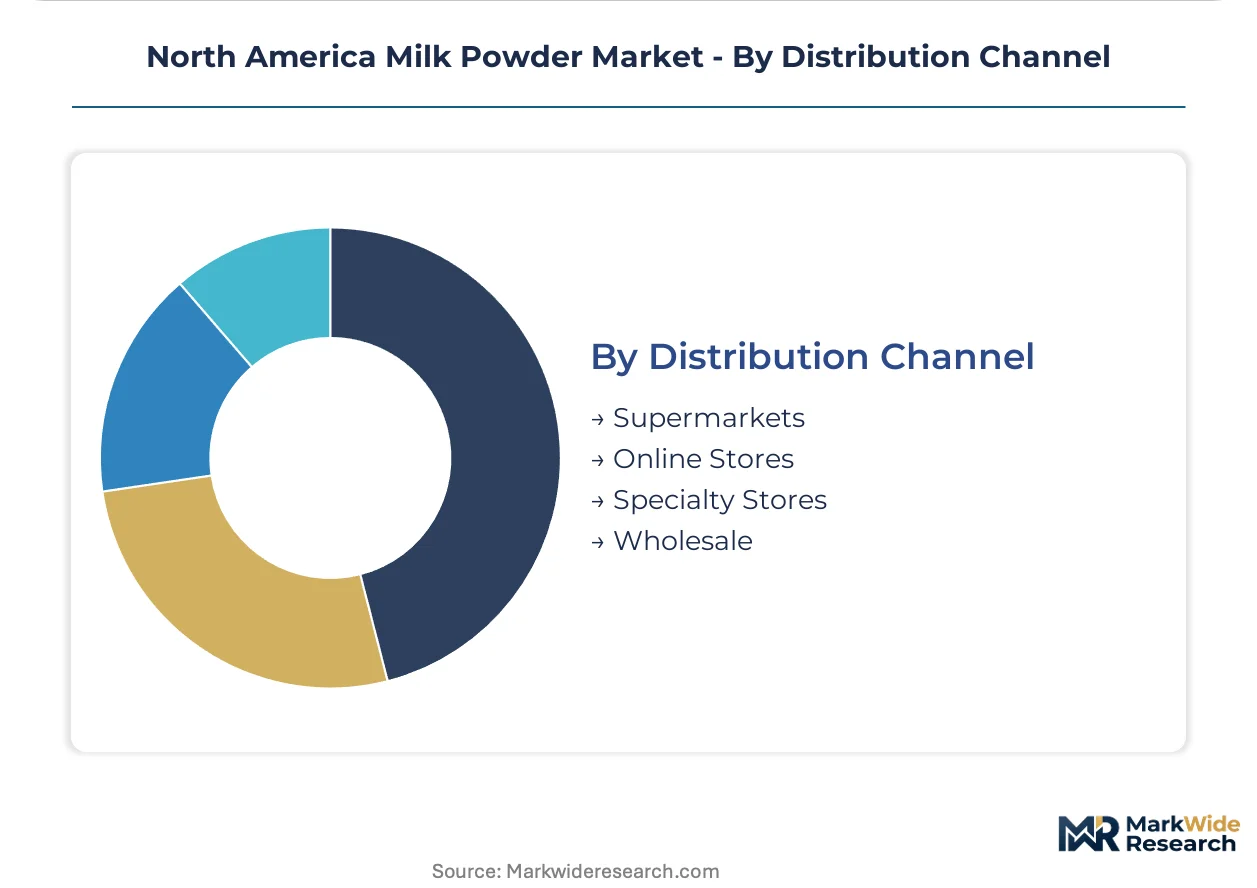
Distribution Channel:
Geographic concentration in California's Central Valley and Canada's Prairie provinces dictates fulfillment network configuration and inventory positioning.
- Online Stores:Fastest-growing distribution channel as bulk buyers shift procurement to digital platforms. California Central Valley processors report 40% of new contracts originate through platform-based discovery rather than relationship-based brokerage. Food processing end-users with annual volume thresholds above 500 metric tons are negotiating direct contracts through these channels.
- Wholesale:Traditional bulk channel for food processing and foodservice procurement. Dairy Farmers of America leverages cooperative structure to anchor supply contracts across the Midwest through this channel.
- Supermarkets:Retail channel for household reconstitution and specialty baking applications.
- Specialty Stores:Niche channel for organic-certified and nutritional-grade powder products.
Wholesale holds the largest share; online stores are gaining share fastest as procurement digitization disintermediates traditional dairy brokers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spray-drying capacity concentrates in California's Central Valley corridor and Canada's Prairie provinces, creating geographic dualism that shapes cross-border powder flows and arbitrage opportunities.
United States
FDA Grade A Pasteurized Milk Ordinance enforcement drives compliance investments across interstate processors. California's Central Valley anchors the continent's largest spray-drying cluster, where integrated butter-powder operations capture margin from fluid milk volatility. Dairy Farmers of America leverages cooperative scale to lock bulk supply contracts across Midwest processing nodes.
Canada
Health Canada's Food and Drug Regulations parallel FDA standards, reducing dual-compliance burdens for cross-border operators. Saskatchewan and Alberta drying capacity expansions are reconfiguring skim milk powder availability for US arbitrage. Saputo Inc. maintains integrated cheese and powder operations that sustain margin capture from Prairie province milk supply swings.
Mexico
Infant formula manufacturers accelerate skim milk powder procurement to serve domestic birth-rate stabilization and Central America export positioning. Mexican processors face no equivalent Grade A federal standard, creating regulatory asymmetry with US suppliers. Northern border states concentrate reconstitution facilities that source powder from California and Texas dryers.
North America Milk Powder Market Key Industry Players
Cooperative structures and publicly traded dairy conglomerates split the market into distinct governance models with divergent capital access and pricing power. The vendor base organizes around three strategic archetypes: farmer-owned cooperatives with captive milk supply, integrated dairy processors with multi-product portfolios, and specialized nutritional-grade powder specialists. Dominant competitive moves include backward integration into fluid milk sourcing and membrane filtration technology licensing to collapse protein concentrate cost differentials.
Within the cooperative tier, Dairy Farmers of America and Land O'Lakes exemplify farmer-owned governance structures that anchor bulk ingredient supply contracts across the Midwest. Saputo Inc. and Lactalis American Group occupy positions as integrated processors with multi-product diversification, while Nestle represents multinational nutritional specialists with infant formula channel dominance. These archetypes illustrate how governance structure and product breadth determine competitive positioning in a market where protein standardization requirements are tightening.
| Leading Market Players |
|---|
| Dairy Farmers of America |
| Saputo Inc. |
| Land O'Lakes |
| Agropur Cooperative |
| The Kraft Heinz Company |
| Nestle |
| Lactalis American Group |
| Schreiber Foods |
| Dean Foods |
| Others |
Cost & Logistics Intelligence
Rail corridors connecting California's Central Valley to Midwest processing nodes transmit cost volatility that both concentrates supply-side pricing power among integrated cooperatives and forces downstream buyers into long-term offtake commitments to hedge freight exposure.
Pricing Analysis
FDA Grade A Pasteurized Milk Ordinance dictates the pricing tier structure across interstate commerce, separating USDA-certified nutritional-grade premiums from standard commodity tiers. Three-tier pricing structure across premium, standard, and economy levels reflects protein content certification, volume scale thresholds above 500 metric tons, and third-party laboratory verification bundling. Cost compression in standard-grade skim milk powder is intensifying because membrane filtration collapses historical whey protein isolate premiums. Food processing end-users with direct digital procurement access exhibit lowest price sensitivity, while smaller foodservice operators face margin erosion from broker disintermediation.
Supply Chain Analysis
Tariff exposure between Canada and the United States dominates cross-border powder flows despite regulatory harmonization efforts. Geographic supply concentrates in California, the Canadian Prairie provinces of Saskatchewan and Alberta, and northern Mexico border states. Raw material dependencies rest on fluid milk supply swings from Dairy Farmers of America cooperative pricing, whey protein concentrate imports, and packaging materials for aseptic lines. Single-source vulnerability concentrates in California's Central Valley spray-drying cluster. Distribution runs through cooperative broker networks, direct-to-processor digital platforms, and foodservice redistribution warehouses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement digitization fragments traditional brokerage structures, creating white-space opportunities for specialized nutritional-grade processors and membrane filtration technology licensors.
For Market Incumbents: Harden laboratory verification capacity to preempt FDA enforcement actions on protein declaration tightening. Anchor captive milk supply through cooperative membership expansion in the Prairie provinces. Defend margin position by licensing membrane filtration systems to infant formula manufacturers, collapsing external whey protein isolate dependency. For New Entrants and Emerging Players: Pursue underpenetrated sports nutrition channels where plant-based substitution pressure is weakest. Target Canadian Prairie surplus skim milk powder availability for US cross-border arbitrage. Establish direct digital procurement platform relationships with California Central Valley dryers to bypass legacy cooperative brokerage. For Investors and Strategic Acquirers: FDA updated dairy labeling standards reshape the acquisition landscape toward third-party certified laboratory assets. Five-to-ten year viability favors processors with integrated Grade A compliance infrastructure and membrane filtration licensing portfolios. Monitor protein analysis skill scarcity as the inflection signal for laboratory service provider valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Licensing | Collapses whey protein isolate premiums for infant formula manufacturers adopting in-house standardization. |
| Prairie Province Capacity Expansion | Creates surplus skim milk powder availability for US cross-border arbitrage and Midwest supply security. |
| Digital Procurement Platform Integration | Disintermediates traditional dairy brokers as 40% of California Central Valley contracts migrate to direct discovery. |
| Third-Party Laboratory Verification Investment | Preempts FDA enforcement risk from protein declaration tightening across nutritional-grade segments. |
| Cooperative Backward Integration | Secures captive fluid milk supply against Dairy Farmers of America pricing volatility for independent processors. |
Research Approach
Operator-level perspectives from spray-drying plant managers, infant formula procurement directors, cooperative supply planners, and FDA regulatory affairs specialists anchored the qualitative base. Secondary validation drew from USDA grading program certifications, Health Canada Food and Drug Regulations filings, FDA Pasteurized Milk Ordinance enforcement records, and customs trade data on cross-border powder flows. Bottom-up capacity modeling triangulated against top-down demand segmentation across product type, application, and distribution channel.
Scenario-bracketing framed volume and value outputs across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use application intensity, procurement scale threshold, and regional regulatory cluster alignment. CAGRs derived from capacity utilization trajectories, birth-rate stabilization patterns in Mexico, and membrane filtration adoption curves. Forecast inputs incorporated fluid milk price volatility indices and digital procurement platform penetration rates.
Sensitivities concentrate around FDA enforcement intensity on protein declarations, Prairie province drying capacity completion timelines, and oat/pea protein isolate substitution acceleration in sports nutrition. Forecasts reflect documented assumptions on regulatory alignment pace and cooperative pricing mechanism stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
United States Camel Dairy Market
Dairy Products
North America Sour Cream Market
Dairy Products
Mexico Whey Protein Market
Dairy Products
Ricotta Market
Dairy Products
Cheese Crumbles Market
Dairy Products
Low-Fat Sour Cream Market
Dairy Products
Organic Milk Market
Dairy Products
Ultra High Temperature Milk Market
Dairy Products
Natural Cheese Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
Table Butter Market
Dairy Products
South America Yogurt Market
Dairy Products
United States Dairy Market
Dairy Products
Parmesan Cheese Market
Dairy Products
Halloumi Cheese Market
Dairy Products
Fermented Milk Products Market