
 Organic Milk Market | 2026-2036
Organic Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Milk Market Outlook
Buyer concentration among large-format grocery retailers is hardening across major organic milk markets. Organic Valley leverages cooperative ownership structures to sustain farm-gate premiums and shield member-producers from commodity volatility. Arla Foods amba anchors its position through Arla Organic brand distribution across northern European retail banners. Horizon Organic dominates the US conventional retail channel with broad supermarket placement and long-standing USDA Organic certification.
Organic milk denotes fluid dairy from cattle raised on certified organic feed without synthetic hormones or antibiotics, with pasteurization temperatures and butterfat minimums varying by jurisdiction. The product serves household consumption, foodservice ingredient applications, and institutional nutrition programs requiring clean-label protein sources. Whole milk occupies the premium tier in organic fluid dairy, while flavored milk competes for younger demographics through reduced-sugar formulations. Tetra packs capture shelf-stable demand in regions with limited cold-chain infrastructure, and online stores represent the fastest-expanding distribution vector for subscription-based organic dairy delivery.
USDA Organic certification, EU Organic Regulation, and FSSAI standards in India each mandate pasture-access minimums and prohibit synthetic growth promoters, creating divergent compliance architectures for multinational processors. The EU F-Gas Regulation indirectly shapes organic milk packaging decisions by pressuring converters toward lower-carbon refrigeration and aseptic filling technologies. Stakeholders must monitor evolving feed-cost inflation and regulatory harmonization pressures as organic livestock operations face competing land-use demands from alternative protein feedstocks.
Market Dynamics
Private-label expansion by retail grocery chains is compressing branded shelf space while EU Organic Regulation feed-sourcing mandates raise producer compliance burdens across the value chain.
Growth Catalysts
- EU Organic Regulation pasture-access mandates:Certification requirements for outdoor grazing create product differentiation that commands shelf price premiums in German and French retail channels.
- Clean-label protein demand from institutional nutrition programs:School districts and hospital systems specify organic dairy to meet sodium-reduction and additive-free procurement standards.
- Tetra pack aseptic filling technology:Shelf-stable packaging extends distribution reach into Indian and Southeast Asian markets with limited cold-chain infrastructure.
Market Restraints
- Organic feed grain cost volatility:Corn and soybean price swings in US and Brazilian commodity markets directly squeeze farm-gate margins for certified producers.
- Processing concentration in northern European cooperatives:Limited independent bottling capacity outside Denmark, Germany, and the Netherlands creates supply bottlenecks for new market entrants.
- Oat and almond milk substitution:Plant-based alternatives capture younger demographics in urban US and UK markets through lower price positioning and carbon-footprint marketing.
Strategic Opportunities
- Subscription-based direct-to-home delivery:E-commerce platforms bypass retail slotting fees while capturing recurring revenue from high-income households in London, New York, and Sydney metro areas.
- FSSAI organic certification harmonization:India's national food safety regulator streamlines import recognition for EU and USDA-certified products, opening formal channel access.
- Reduced-sugar flavored milk formulations:Product development targets school-age children through natural sweetener systems that meet USDA school meal sodium and sugar thresholds.
Industry Challenges
- Veterinarian certification for organic livestock health:Qualified practitioners capable of treating mastitis and metabolic disorders without synthetic antibiotics remain scarce in rural US and Australian dairy regions.
- Pasture land conversion timelines:Three-year organic transition periods for conventional cropland constrain herd expansion plans despite retail demand signals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Milk Market |
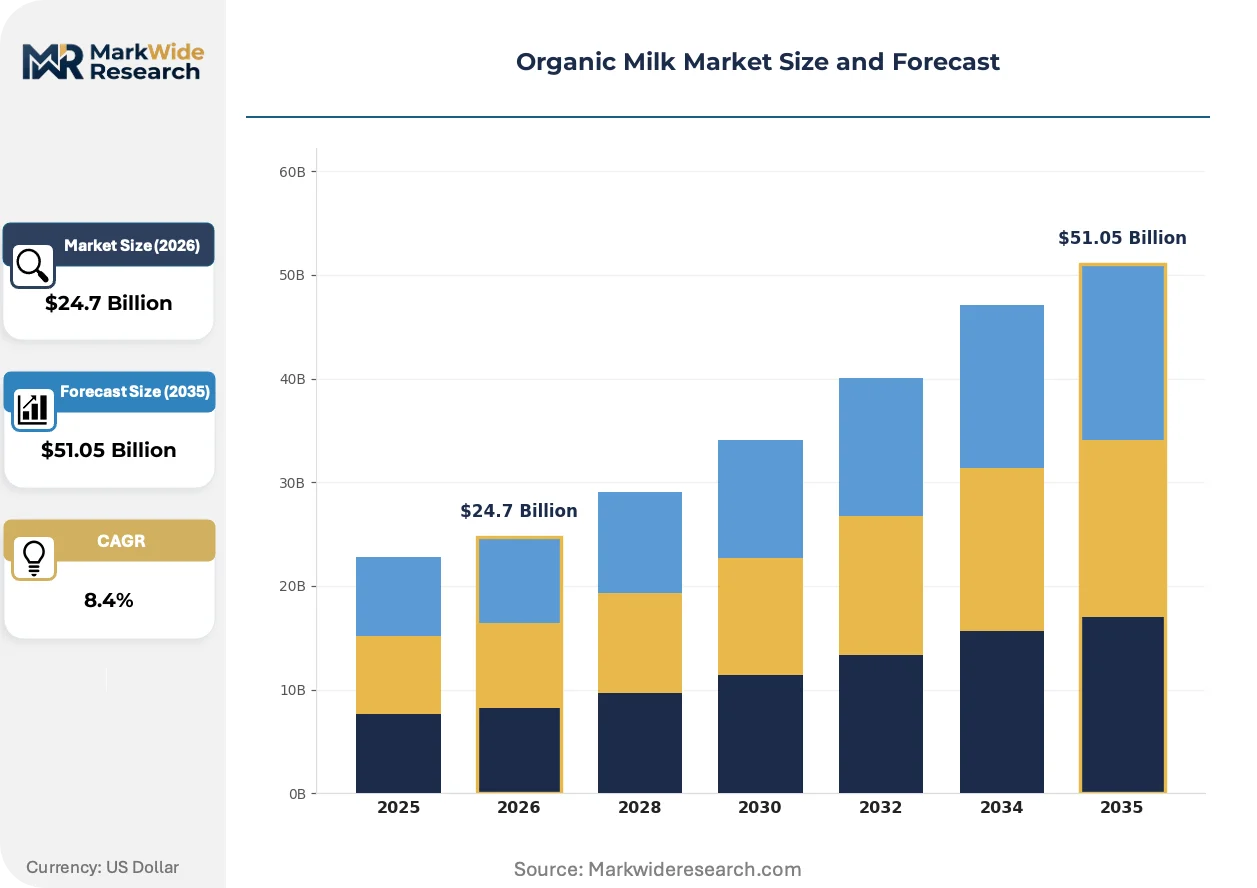
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $51.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Milk, Skim Milk, Low-Fat Milk, Flavored Milk Packaging Type: Cartons, Bottles, Pouches, Tetra Packs Distribution Channel: Supermarkets, Online Stores, Health Food Stores, Farmers' Markets End User: Households, Cafés, Restaurants, Schools |
| Companies Covered | Organic Valley, Arla Foods amba, Horizon Organic, Aurora Organic Dairy, Groupe Danone, Groupe Lactalis, Fonterra Co-operative Group, Nestlé, Maple Hill Creamery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Milk Market Strategic Shifts
Aseptic processing and renewable packaging materials are reshaping how organic milk reaches consumers outside traditional cold-chain networks, while regulatory pressure on livestock welfare intensifies.
Extended-shelf-life (ESL) processing technology is expanding into premium organic segments previously limited to conventional dairy. German and Danish processors deploy microfiltration and advanced thermal treatments to achieve 45-60 day ambient stability. Retail buyers in Middle Eastern and Southeast Asian markets adopt these formats to reduce spoilage losses in climates with unreliable refrigeration, compressing the historical trade-off between organic certification and distribution reach.
The EU F-Gas Regulation mandates phasedown of hydrofluorocarbon refrigerants used in dairy cold storage and transport. Processors face capital expenditure requirements for CO2 or ammonia-based refrigeration systems. German retailers and French dairy cooperatives are most affected, accelerating retrofit timelines to avoid penalties while passing compliance costs through supplier negotiations.
Household purchasing through subscription platforms is displacing conventional supermarket replenishment among high-frequency organic buyers. UK and US consumers lock in weekly delivery schedules for whole and semi-skimmed variants, bypassing retail price volatility. This channel shift concentrates volume with specialized logistics operators capable of temperature-controlled last-mile service, fragmenting historical wholesale relationships.
Organic Milk Market Segmentation
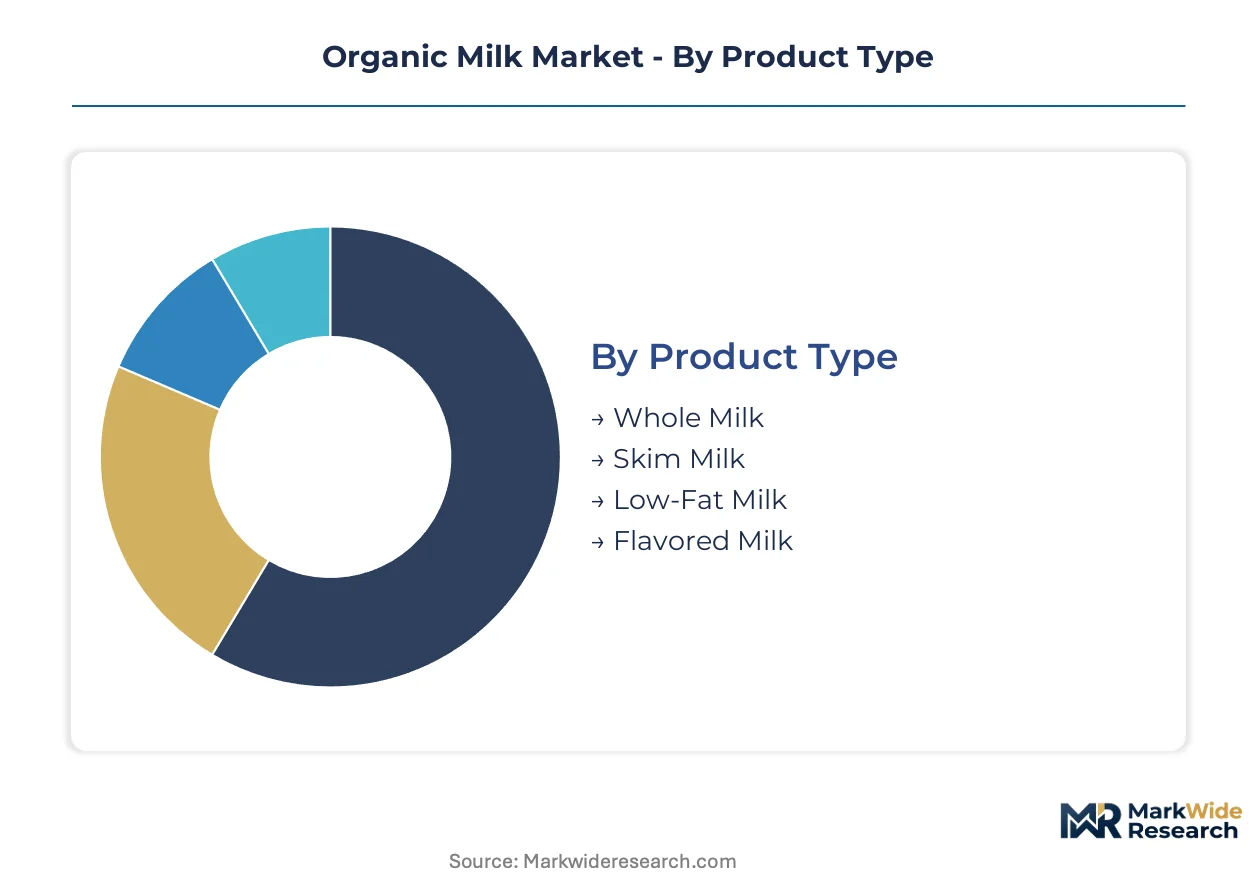
Organic milk segmentation reveals how certification requirements, packaging technology, and channel economics fragment demand across distinct buyer profiles. Each category carries specific compliance burdens that shape margin structures and competitive entry barriers.
Product Type:
USDA Organic and EU Organic Regulation standards apply uniformly across all fluid categories, though whole milk commands stricter butterfat minimums in certain jurisdictions. Whole milk and flavored milk carry the highest formulation complexity and certification scrutiny.
- Whole Milk:Minimum butterfat content of 3.25% under USDA standards creates premium positioning in German and US retail channels. Household demand concentrates among high-income demographics seeking clean-label protein density for children and athletic nutrition programs.
- Flavored Milk:Natural sweetener systems and reduced-sugar formulations require additional formulation validation under FDA and EFSA additive guidelines. School procurement contracts in the US and UK specify these variants for sodium-compliant meal programs.
- Skim Milk:Fat removal below 0.5% butterfat meets institutional nutrition program specifications for cardiac-care menus in hospital systems.
- Low-Fat Milk:1-2% butterfat range captures price-sensitive household segments in urban UK and Australian supermarkets.
Whole milk sits at the top of the volume ranking, with flavored milk climbing the fastest.
Packaging Type:
Cost tiers separate segments by shelf-life extension technology and cold-chain dependency. Aseptic formats command material premiums but unlock geographic expansion.
- Tetra Packs:Aseptic filling technology achieves 45-60 day ambient stability through multi-layer barrier laminates. Indian and Southeast Asian distributors adopt these formats to bypass unreliable refrigeration infrastructure in tier-2 cities.
- Cartons:Gable-top paperboard dominates conventional retail in Germany and France with 7-14 day refrigerated shelf life. Retail slotting fees concentrate volume with Arla Foods and Organic Valley cooperative members.
- Bottles:HDPE and PET formats serve fresh-channel replenishment in US supermarkets with high turnover velocity.
- Pouches:Flexible film reduces material cost for price-positioned entries in emerging markets with developing organic certification frameworks.
Cartons retain the dominant share position, while Tetra Packs expand most quickly into climate-constrained distribution zones.
Distribution Channel:
Customer type and purchase frequency differentiate channel economics. Subscription platforms bypass traditional wholesale markups while capturing recurring revenue.
- Online Stores:Direct-to-home subscription models lock in weekly delivery schedules for London, New York, and Sydney metro households. Temperature-controlled last-mile logistics fragment historical supermarket relationships.
- Supermarkets:Private-label expansion by Tesco, Kroger, and Rewe compresses branded shelf space while raising slotting fee barriers for new entrants.
- Health Food Stores:Specialty retailers in Germany and the US maintain premium positioning through exclusive cooperative-brand relationships.
- Farmers' Markets:Direct farm sales capture locavore demand in rural US and French regions with shorter organic transition timelines.
Supermarkets anchor current volume, with online stores gaining share fastest among high-frequency organic buyers.
End User:
Application maturity separates institutional procurement from discretionary household purchasing. Nutrition program specifications create formal demand anchors.
- Schools:USDA school meal standards and UK Department for Education procurement rules mandate organic dairy for sodium-reduction compliance. District-level contracts lock in multi-year supply agreements.
- Households:Weekly replenishment patterns concentrate in dual-income suburban segments with children under 12. Subscription platforms capture highest lifetime value per account.
- Cafés:Specialty coffee chains in Melbourne and Copenhagen specify organic milk for flat white and cortado preparation standards.
- Restaurants:Fine-dining establishments in Paris and San Francisco menu organic dairy for clean-label dessert and sauce applications.
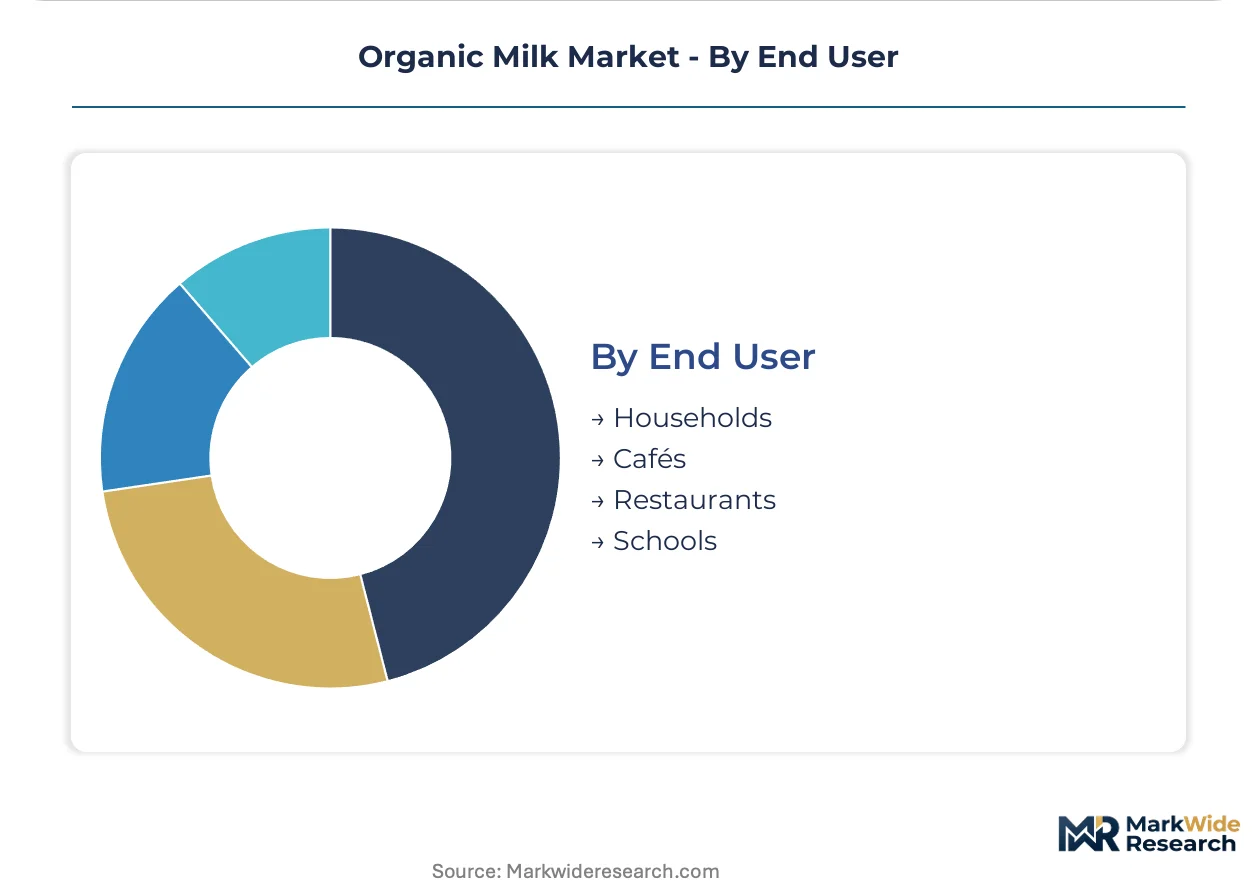
Households dominate absolute consumption, with schools showing the steepest procurement specification trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's discounter penetration of organic milk exceeds that of France, where cooperative structures dominate procurement. The United States anchors conventional retail channel volume through supermarket distribution networks. India and Southeast Asian markets bypass cold-chain limitations through shelf-stable packaging adoption.
United States
Household replenishment patterns concentrate in suburban segments with children under 12. USDA National Organic Program standards tighten feed-sourcing and livestock-welfare rules, raising compliance costs for domestic producers. Horizon Organic maintains broad supermarket placement across the Northeast and California metro corridors.
Germany
Discounter penetration of organic milk exceeds other European markets through Aldi and Lidl private-label expansion. EU Organic Regulation pasture-access mandates create product differentiation commanding shelf price premiums. The northern dairy belt around Lower Saxony anchors cooperative processing capacity for Arla Foods distribution.
France
Clean-label protein demand from institutional nutrition programs drives hospital and school procurement specifications. ANSM and national organic certifiers enforce additive-free standards parallel to EU baseline requirements. The Brittany dairy cluster supplies fluid organic milk for Parisian retail banners and foodservice channels.
India
Tetra pack aseptic filling technology extends distribution reach into tier-2 cities with unreliable refrigeration infrastructure. FSSAI organic certification harmonization streamlines import recognition for EU and USDA-certified products. Maharashtra and Gujarat processing hubs capture formal channel growth as metro household incomes rise.
United Kingdom
Subscription-based direct-to-home delivery displaces conventional supermarket replenishment among high-frequency organic buyers. UK Department for Education procurement rules mandate organic dairy for sodium-reduction compliance in school meal programs. London metro logistics operators fragment historical wholesale relationships through temperature-controlled last-mile service.
Organic Milk Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across certification tiers and distribution channels. Cooperative ownership structures shield member-producers from commodity volatility while multinational processors leverage brand equity for retail slotting fee negotiations. Two strategic archetypes dominate: vertically integrated dairy cooperatives and diversified food conglomerates with organic portfolio units. Competitive moves concentrate on private-label contract manufacturing and subscription platform partnerships.
Within the cooperative archetype, Organic Valley and Arla Foods amba exemplify farm-gate premium sustainability through member ownership models. Horizon Organic occupies a position representing conventional retail channel dominance through long-standing USDA Organic certification. Among diversified conglomerates, Groupe Danone and Nestlé anchor multinational organic dairy portfolios spanning multiple certification jurisdictions.
| Leading Market Players |
|---|
| Organic Valley |
| Arla Foods amba |
| Horizon Organic |
| Aurora Organic Dairy |
| Groupe Danone |
| Groupe Lactalis |
| Fonterra Co-operative Group |
| Nestlé |
| Maple Hill Creamery |
| Others |
Value Chain & Pricing Dynamics
Chicago Board of Trade organic corn futures volatility cascades through feed costs into farm-gate milk pricing, compressing margins for non-vertically integrated processors while amplifying premiums for cooperative members with captive grain supply.
Pricing Analysis
Capacity additions in Denmark and the Netherlands are reshaping price floors for private-label contract manufacturing. Three-tier pricing structure across premium cooperative brands, standard private-label, and economy conventional milk segments dominates retail negotiations. Price differentiation hinges on EU Organic Regulation certification tier and pasture-access verification documentation. Pricing pressure stems from Aldi and Lidl private-label expansion in Germany, squeezing branded shelf space. Price-sensitive households in urban UK and Australian markets gravitate toward low-fat variants, while premium whole milk captures least price-sensitive athletic nutrition and pediatric segments.
Supply Chain Analysis
Dual-sourcing mandates from Tesco, Kroger, and Rewe require processors to qualify backup cooperatives for organic milk procurement. Supply concentrates in Denmark, Germany, and the Netherlands for cooperative processing capacity. Raw material dependencies center on certified organic corn, soybeans, and alfalfa hay from US and Brazilian commodity markets. Supply chain risk manifests as organic feed grain price volatility tied to conventional crop futures correlation. Distribution runs through temperature-controlled retail wholesale networks for refrigerated cartons, with aseptic Tetra pack formats bypassing cold-chain requirements for Indian and Southeast Asian market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
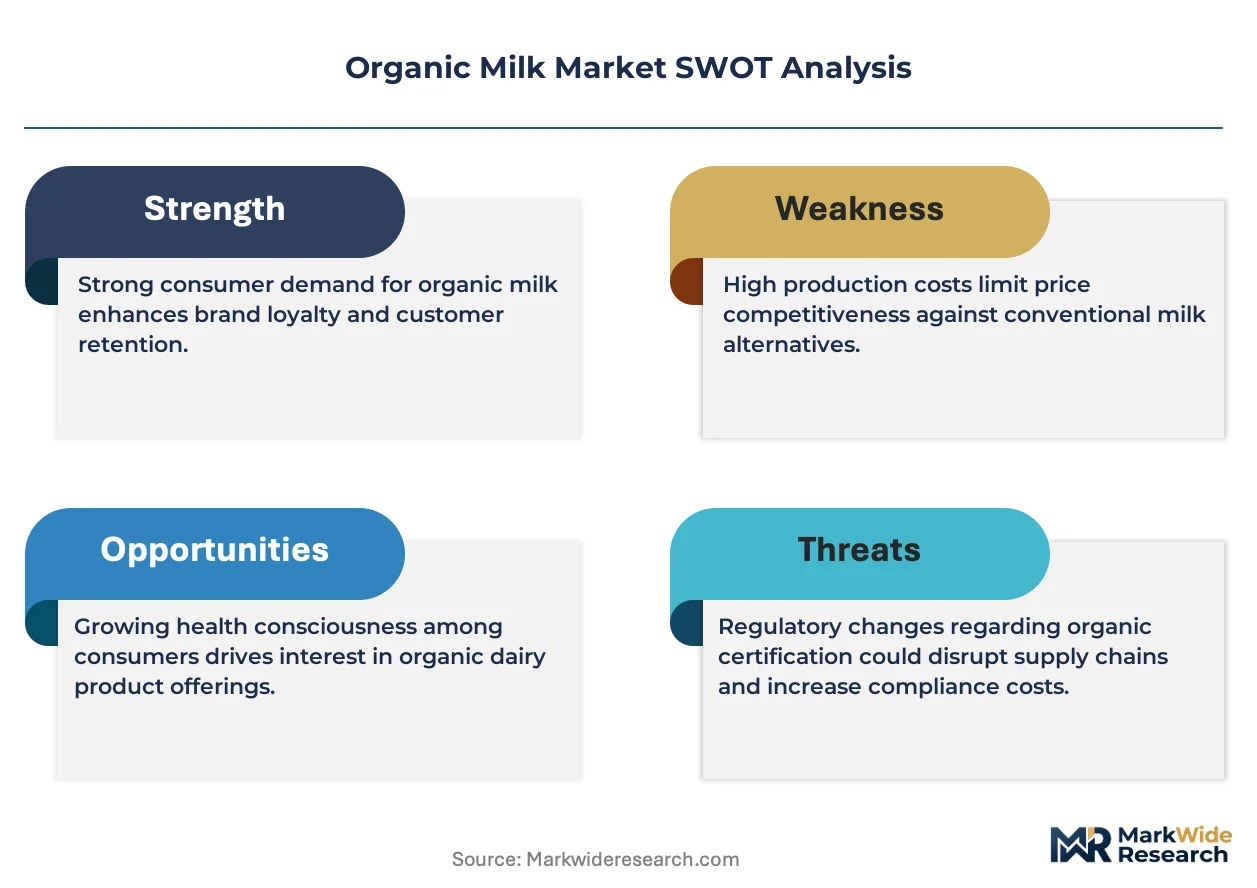
This market functions as a geographic-arbitrage play between EU Organic Regulation compliance costs in northern Europe and FSSAI harmonization benefits for EU-certified imports into India, where feed and labor cost differentials widen processor margins.
For Market Incumbents: Deploy backward integration into certified organic feed production to shield margins from Chicago Board of Trade volatility. Horizon Organic and Arla Foods should lock in long-term pasture-lease agreements in Lower Saxony and Brittany to preempt three-year organic transition bottlenecks. Oat milk substitution in UK and US urban markets threatens volume retention; counter with subscription platform partnerships capturing recurring household revenue. For New Entrants and Emerging Players: Aseptic processing technology for ambient-stable Tetra pack formats offers the clearest wedge against incumbent refrigerated-carton dominance. Target tier-2 Indian cities with unreliable cold-chain infrastructure, where FSSAI import recognition streamlines EU-certified product entry. White-space exists in reduced-sugar flavored milk for USDA school meal procurement; pursue direct district-level contracting bypassing retail slotting fees. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale cooperatives possessing uncommitted pasture capacity in Germany and France. Long-term viability favors processors with dual EU-USDA certification enabling transatlantic sourcing flexibility. Watch organic corn-soybean price spread compression as the inflection signal for vertical integration urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Feed Production | Captive corn and soybean supply shields Arla Foods members from CBOT volatility. |
| Aseptic Tetra Pack Capacity Expansion | Shelf-stable formats unlock Indian tier-2 distribution beyond cold-chain constraints. |
| Subscription Platform Partnership | Direct-to-home delivery locks recurring revenue from London and Sydney metro households. |
| FSSAI Certification Harmonization | Import recognition streamlines EU-certified organic milk entry into formal Indian channels. |
| Pasture-Lase Preemption in Northern Europe | Three-year organic transition timelines make Lower Saxony land acquisition time-sensitive. |
Study Parameters
Bottom-up household consumption modeling reconciled against top-down dairy cooperative production tracking forms the analytical core of this study. Primary interviews with dairy cooperative procurement managers, retail category buyers at Tesco and Kroger, EU Organic Regulation certification auditors, and FSSAI import registration officials combined with secondary validation from USDA National Organic Program enrollment data, EU Farm Accountancy Data Network reports, Chicago Board of Trade organic grain futures, and Indian customs import records. Triangulation across these sources reconciles farm-gate production estimates with retail scanner data.
Input-output matrices map organic feed grain costs through herd nutrition models to fluid milk output volumes across the projection horizon. Segmentation dimensions include product type, packaging technology, distribution channel, and end-use application, with regional regulatory cluster as an added industry-specific layer. CAGRs derive from compound growth path modeling calibrated against historical organic certification enrollment trajectories and pasture-access compliance cost indices.
The model holds under stable EU Organic Regulation enforcement intensity and FSSAI import recognition continuity; deviation in feed grain price volatility or regulatory harmonization delays would shift the outlook materially. Forecasts reflect documented assumptions about cooperative processing capacity expansion timelines and cold-chain infrastructure development in target emerging markets. Deviation in Aldi and Lidl private-label penetration rates would shift volume concentration and pricing power dynamics substantially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Europe Drinkable Yogurt Market
Dairy Products
Dairy Based Dressings Market
Dairy Products
Europe Yogurt Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Flavoured Milk Market
Dairy Products
Blue Cheese Market
Dairy Products
Sheep Milk Market
Dairy Products
United States Casein Market
Dairy Products
China Lactose-Free Dairy Market
Dairy Products
Sweet Whey Market
Dairy Products
Sheep Milk Cheese Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Organic Dairy Products Market
Dairy Products
Europe Dairy Based Beverages Market
Dairy Products
Flavored Yogurt Market
Dairy Products
Low-Fat Sour Cream Market