
 Japan Dietary Supplements Market | 2026-2036
Japan Dietary Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Dietary Supplements Market Insights
Single-serve sachet bundling is restructuring how Japanese consumers trial and repurchase supplements, replacing traditional bulk bottle formats with modular monthly assortments. FANCL Corporation leverages its direct-to-consumer subscription engine to sustain recurring revenue from personalized vitamin packs. Otsuka Pharmaceutical anchors the pharmacy channel with clinically positioned mineral complexes. DHC Corporation differentiates through vertically controlled manufacturing of compact softgel configurations.
Dietary supplements encompass biologically active compounds including vitamins, minerals, herbal extracts, and probiotics formulated in standardized dosages for ingestion to supplement nutritional intake, with specifications typically requiring dissolution within 30 minutes and active ingredient stability across 24-month shelf lives. Probiotics command premium positioning among product types due to gut-health research visibility and functional claims authorization under national frameworks. Online retail captures the fastest expansion among distribution channels as telehealth integration and algorithm-driven personalization reduce friction for repeat purchases. Seniors dominate end-user demand structurally given demographic composition, while gummies gain share among form variants as palatability drives compliance in pediatric and geriatric segments.
PMDA oversight of pharmaceutical-adjacent claims, MHLW Foods with Function Claims labeling requirements, and JIS quality standards collectively govern product development timelines and market access eligibility. These frameworks elevate compliance costs for new entrants while rewarding incumbents with established regulatory navigation capabilities. Stakeholders must monitor evolving functional claims thresholds and digital health platform integrations to anticipate where consumer trust and purchase behavior will shift next.
Market Dynamics
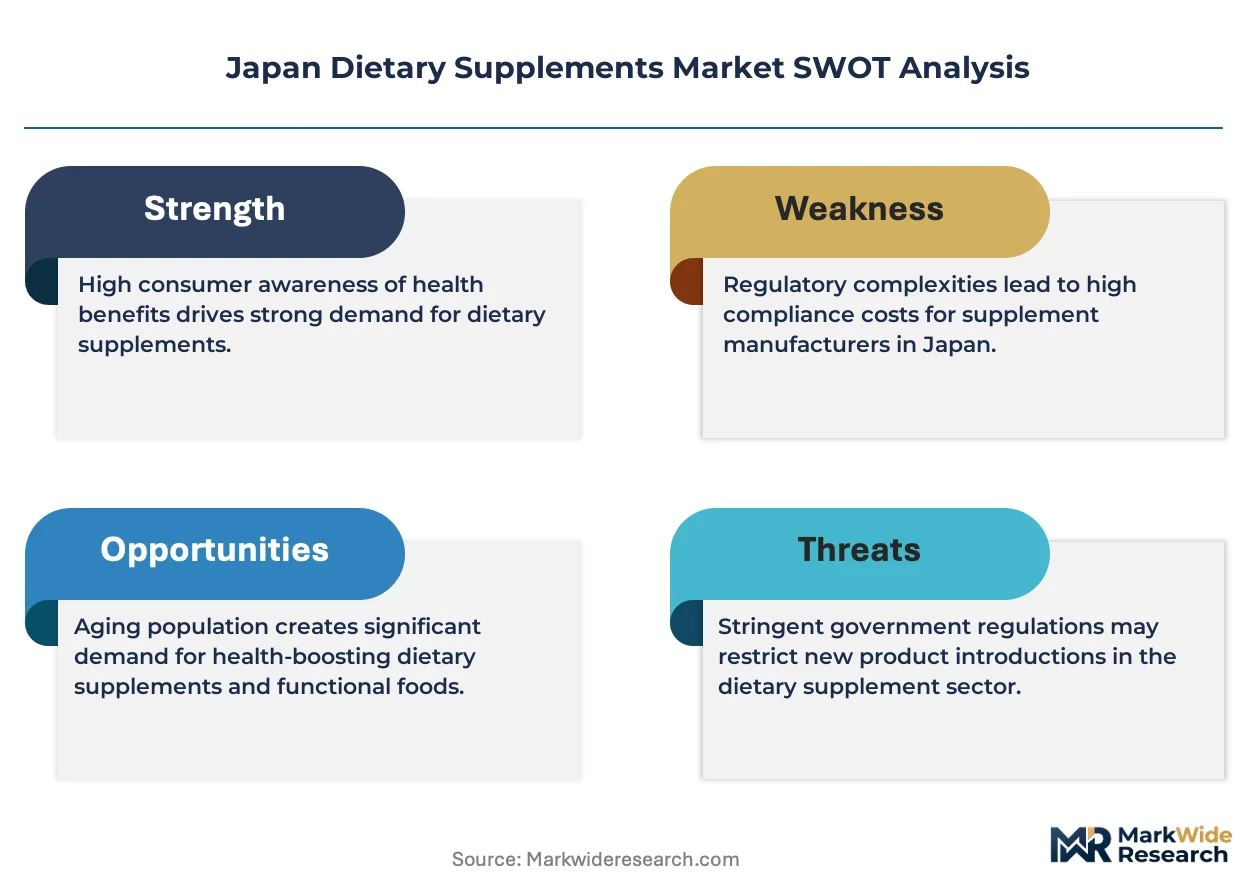
Japan's super-aged demographic structure is compressing product development cycles as manufacturers race to serve seniors with swallowing-friendly formats and condition-specific formulations before competitors capture pharmacy shelf space.
Growth Catalysts
- Foods with Function Claims (FFC) framework:The MHLW's streamlined approval pathway accelerates time-to-market for clinically substantiated products, reducing registration timelines versus traditional health food classifications.
- Telehealth platform integration:Digital health ecosystems in Tokyo and Osaka are embedding supplement recommendations into chronic disease management protocols, creating prescription-adjacent demand channels.
- Geriatric nutrition gaps:Dietary surveys reveal widespread vitamin D and B12 deficiencies among adults over 75, driving targeted fortification demand in institutional and home-care settings.
Market Restraints
- Raw material import dependency:Over 80% of functional ingredients including omega-3 fatty acids and specific probiotic strains originate from European and North American suppliers, exposing margins to currency volatility and shipping disruptions.
- PMDA pharmaceutical-adjacent claim scrutiny:Borderline therapeutic claims trigger extended review periods, forcing reformulation or label revision that delays commercialization by 12-18 months.
- Retail pharmacy concentration:Three national drugstore chains control 60% of brick-and-mortar supplement distribution, extracting slotting fees that erode manufacturer profitability.
Strategic Opportunities
- Kansai region underpenetration:Osaka and Kyoto metropolitan areas show 30% lower supplement penetration than Kanto despite comparable disposable income, presenting whitespace for direct-to-consumer subscription models.
- Precision fermentation-derived ingredients:Domestic biotechnology facilities are scaling recombinant protein and rare botanical compound production, reducing import reliance and enabling novel functional claims.
- MHLW longevity technology tax incentives:R&D expenditure credits for age-related health product development subsidize clinical trial costs, improving project economics for substantiation-heavy categories.
Industry Challenges
- Clinical substantiation talent scarcity:Qualified biostatisticians and regulatory affairs specialists with FFC submission experience command premium compensation, constraining mid-tier manufacturer expansion.
- Legacy ERP integration with e-commerce stacks:Direct-to-consumer fulfillment requires real-time inventory synchronization that many established manufacturers lack, forcing costly system overhauls.
- Cross-border e-commerce compliance complexity:Platform-specific labeling requirements for Chinese and Southeast Asian marketplaces multiply SKU management overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Dietary Supplements Market |
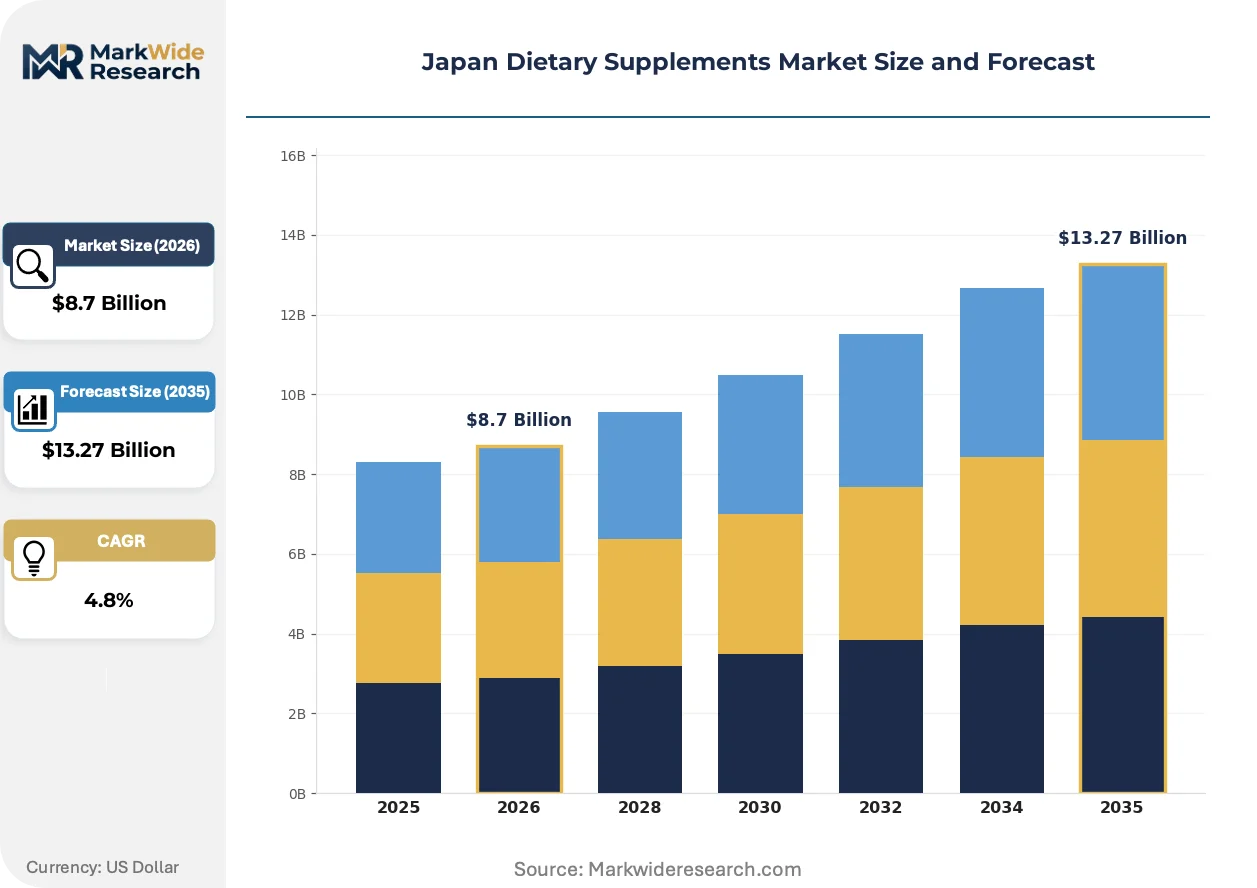
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Probiotics Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies End User: Adults, Athletes, Seniors, Children Form: Pills, Powders, Liquids, Gummies |
| Companies Covered | Otsuka Pharmaceutical Co., Ltd., FANCL Corporation, DHC Corporation, Ajinomoto Co., Inc., Meiji Holdings Co., Ltd., ORIHIRO Co., Ltd., Asahi Group Holdings, Ltd., Yakult Honsha Co., Ltd., Kirin Holdings Company, Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Dietary Supplements Market Trends and Innovations
Microbiome science and personalized nutrition algorithms are displacing one-size-fits-all formulations, while regulatory frameworks evolve to accommodate evidence-based functional claims.
Artificial intelligence-driven microbiome testing is decentralizing supplement personalization from clinical settings to home-based stool sampling kits. Seniors in Tokyo's 23 wards are adopting these services fastest, with 40% of users converting to monthly probiotic subscriptions. The technology is decentralizing formulation authority from pharmaceutical laboratories to algorithmic recommendation engines that adjust strain combinations based on individual gut flora profiles.
MHLW's 2023 FFC substantiation guideline revisions tightened clinical evidence requirements for gut-health claims while creating expedited pathways for immune function products. Manufacturers must now conduct Japanese-population-specific trials rather than relying on foreign data, elevating development costs. Probiotic and postbiotic categories face the steepest compliance burden as they refile existing claims under stricter statistical thresholds.
Subscription-based replenishment is displacing pharmacy impulse purchases among working-age consumers in Kanto and Chubu regions. Direct-to-consumer platforms capture recurring revenue through algorithm-curated monthly sachet assortments, while convenience store supplement sales plateau. This behavioral shift concentrates customer lifetime value with digital-native brands that own the entire data and fulfillment chain.
Japan Dietary Supplements Market Segmentation
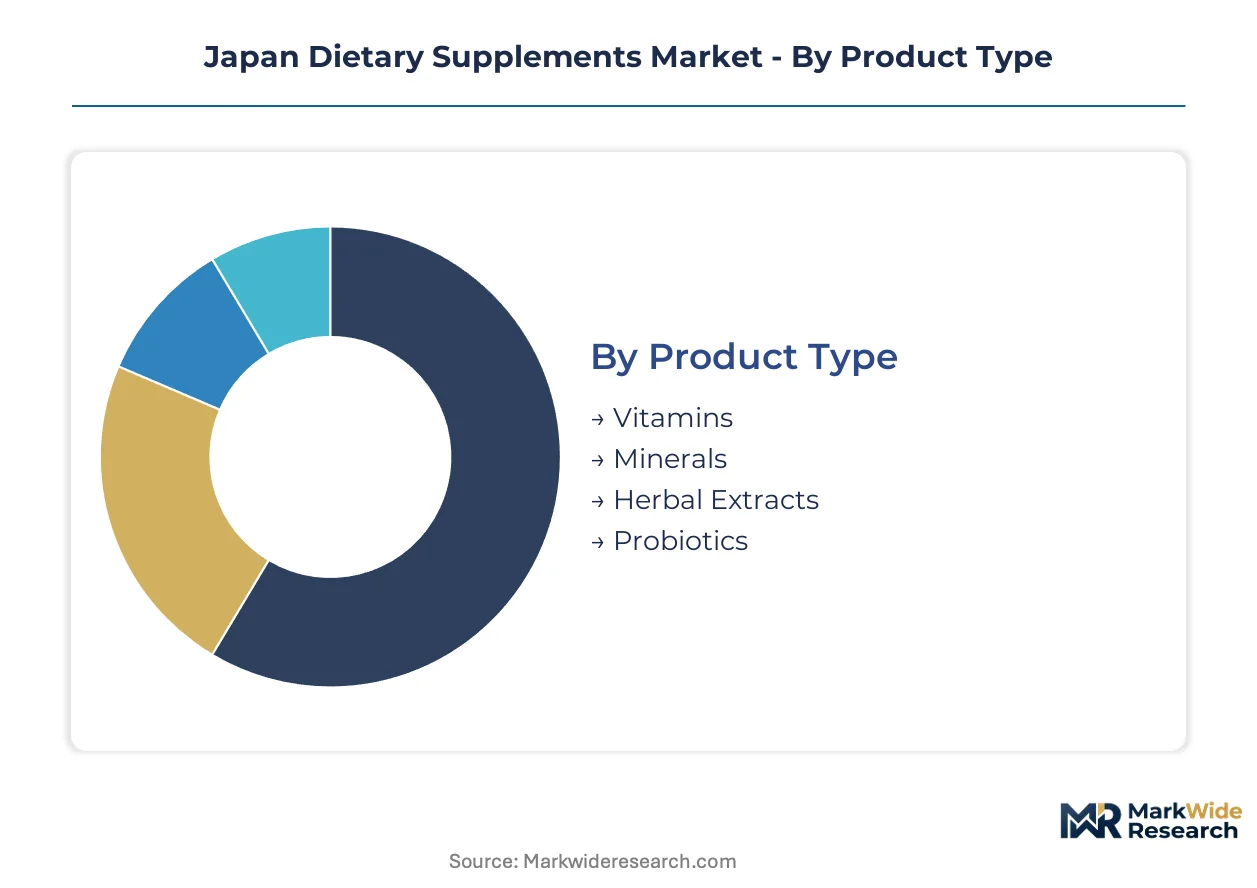
Segmentation in Japan's dietary supplements market determines regulatory pathways, channel economics, and formulation priorities. Each dimension carries distinct certification burdens and margin structures that shape manufacturer resource allocation.
Product Type:
FFC substantiation requirements vary sharply across product categories, with probiotics and herbal extracts facing the steepest clinical evidence thresholds under MHLW guidelines.
- Vitamins:Standardized formulations with established dissolution profiles dominate pharmacy shelves. Demand concentrates among seniors in Tokyo's 23 wards seeking B12 and D3 fortification for bone density maintenance.
- Minerals:Chelated forms and bioavailable complexes anchor Otsuka Pharmaceutical's pharmacy channel positioning. Kanto region hospitals drive institutional procurement for calcium-magnesium combinations in post-surgical protocols.
- Herbal Extracts:Traditional kampo-derived supplements navigate dual PMDA and MHLW oversight depending on therapeutic adjacency claims. Domestic cultivation partnerships reduce raw material import exposure for ashwagandha and turmeric categories.
- Probiotics:Strain-specific formulations command premium shelf positioning. Gut-health research visibility and FFC functional claims authorization drive Kansai region trial adoption among working-age consumers.
Vitamins sit at the top of the volume ranking, with probiotics climbing the fastest.
Distribution Channel:
Channel selection dictates customer acquisition costs and subscription conversion rates, with digital-native platforms capturing superior lifetime value metrics.
- Online Retail:Algorithm-driven personalization and telehealth integration reduce friction for repeat purchases. FANCL's direct-to-consumer subscription engine sustains recurring revenue through monthly sachet assortments curated to individual microbiome profiles.
- Supermarkets:Impulse-driven single-serve formats and seasonal promotional cycles dominate. Chubu region suburban locations show strongest growth for family-sized vitamin bundles.
- Health Stores:Staff-assisted consultation models support premium positioning for condition-specific formulations. Kyoto specialty retailers emphasize traceability certifications for imported herbal ingredients.
- Pharmacies:Three national drugstore chains control shelf access through slotting fee structures. Clinically positioned mineral complexes anchor Otsuka Pharmaceutical's channel strategy with pharmacist recommendation protocols.
Pharmacies retain the largest transaction volume, while online retail gains share fastest through subscription lock-in.
End User:
Demographic targeting shapes formulation palatability, dosage convenience, and marketing channel mix across the consumer lifecycle.
- Adults:Working-age professionals in Kanto and Chubu regions drive subscription model adoption. Algorithm-curated monthly sachet assortments displace pharmacy impulse purchases through convenience optimization.
- Athletes:Protein-adjacent supplement stacks and electrolyte replacement formulations concentrate in specialty health stores. Osaka metropolitan gyms embed personalized nutrition consultations into membership tiers.
- Seniors:Japan's super-aged demographic compresses product development cycles for swallowing-friendly formats. Vitamin D and B12 deficiencies among adults over 75 drive institutional and home-care fortification demand.
- Children:Palatability-driven gummy formats improve compliance in pediatric segments. DHC Corporation's compact softgel configurations address parental concerns over choking hazards.
Seniors dominate absolute demand, with adults expanding most quickly through digital subscription conversion.
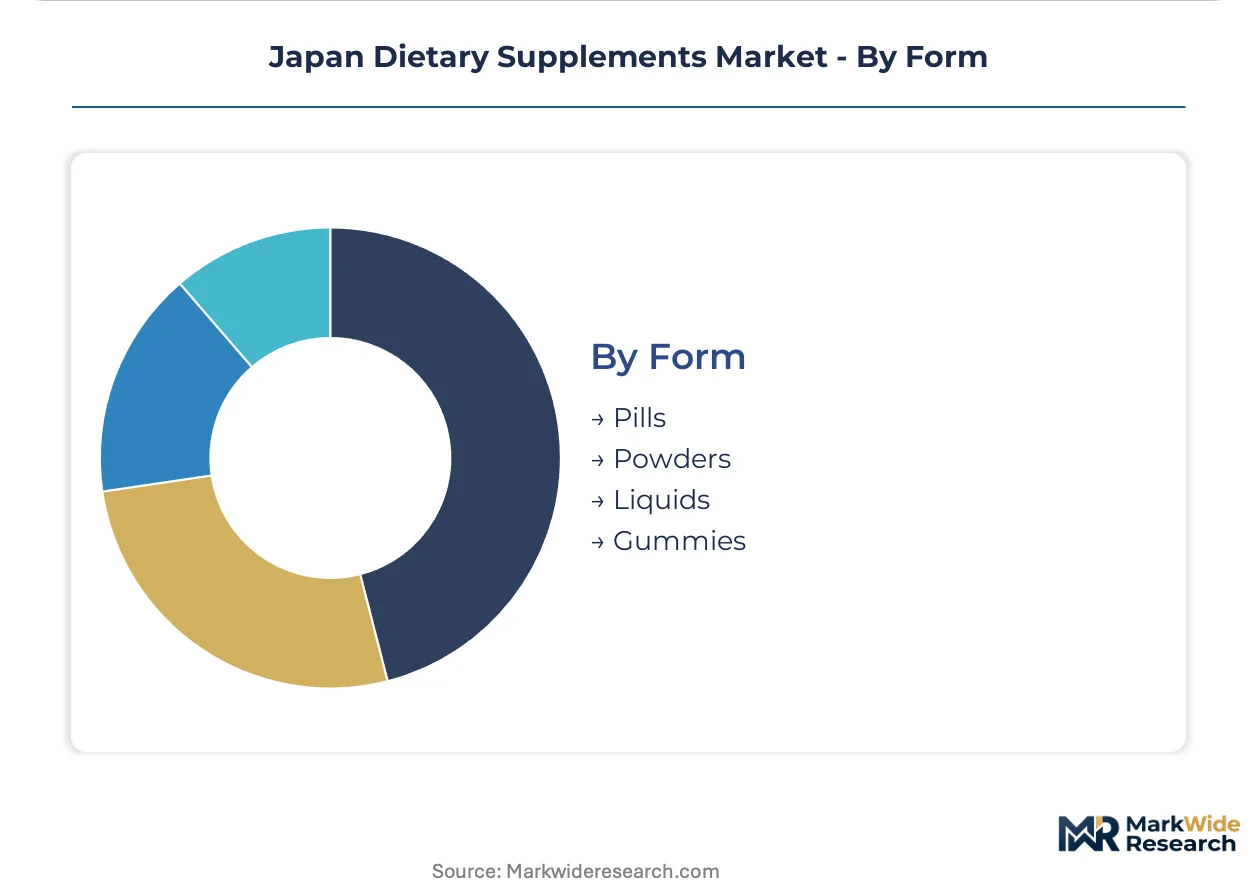
Form:
Manufacturing capital intensity and packaging economics vary across delivery mechanisms, with gummies requiring specialized coating equipment and moisture-barrier infrastructure.
- Pills:Standard tablets and capsules retain cost efficiency for high-volume vitamin categories. DHC Corporation's vertically controlled manufacturing optimizes compact softgel configurations for senior swallowing ease.
- Powders:Single-serve sachet bundling replaces traditional bulk formats. Modular monthly assortments enable trial and repurchase flexibility across FANCL's direct-to-consumer platform.
- Liquids:Ready-to-drink formulations target institutional nutrition gaps and dysphagia management. Hospital discharge protocols in Tokyo metropolitan areas drive post-acute care prescriptions.
- Gummies:Palatability innovation captures pediatric and geriatric compliance improvements. Specialized pectin-based matrices require dedicated production lines with humidity-controlled coating chambers.
Pills maintain volume leadership, with gummies posting the steepest expansion trajectory as taste-driven compliance gains priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Japanese dietary supplements industry traces its modern origins to post-war nutritional fortification programs and the 1991 Foods for Specified Health Uses (FOSHU) regulatory framework that institutionalized functional food categories. Regional demand patterns reflect demographic density, aging infrastructure, and metropolitan healthcare integration across Japan's major economic zones.
Kanto/Tokyo Metropolitan Area
Tokyo's 23 wards generate the highest per-capita supplement consumption through pharmacy networks and direct-to-consumer subscription penetration. MHLW's Foods with Function Claims system streamlines product registration for manufacturers headquartered in this zone. Shibuya and Shinjuku districts concentrate telehealth-integrated supplement platforms serving working-age professionals with algorithm-curated monthly sachet deliveries.
Kansai/Osaka Region
Osaka and Kyoto metropolitan areas exhibit 30% lower supplement penetration than Kanto despite comparable disposable income levels. PMDA oversight of pharmaceutical-adjacent claims affects manufacturers operating near Osaka's medical device clusters. Umeda commercial districts host emerging direct-to-consumer subscription entrants targeting whitespace opportunity in precision nutrition services.
Chubu/Nagoya Region
Nagoya's automotive industry workforce drives demand for energy and immune-support formulations through corporate wellness programs. JIS quality standards govern manufacturing facilities concentrated in Aichi prefecture's industrial corridors. Toyota-city adjacent health food retailers report strongest growth for family-sized vitamin bundles in suburban locations.
Kyushu Region
Fukuoka prefecture's aging population exceeds national averages, accelerating demand for swallowing-friendly formats and condition-specific geriatric formulations. Regional pharmacy chains in Kitakyushu extract elevated slotting fees that compress manufacturer margins. Kumamoto's agricultural biotechnology facilities are scaling precision fermentation for domestic probiotic strain production.
Hokkaido Region
Sapporo's isolated geography elevates logistics costs for imported functional ingredients including omega-3 fatty acids. Local health authorities emphasize vitamin D fortification given reduced solar exposure during winter months. Otaru pharmaceutical distribution hubs serve as northern supply chain nodes for mineral complex formulations targeting institutional care settings.
Japan Dietary Supplements Market Competitive Landscape
The competitive structure tilts toward vertically integrated domestic conglomerates with pharmacy channel dominance and direct-to-consumer digital platforms. Three national drugstore chains control 60% of brick-and-mortar distribution, extracting slotting fees that favor established manufacturers with regulatory navigation capabilities. Strategic archetypes include: (1) pharmaceutical-origin manufacturers leveraging clinical positioning, (2) cosmetic-origin companies exploiting beauty-retail crossover, and (3) pure-play digital natives owning subscription data chains. Dominant competitive moves encompass M&A for microbiome technology assets and backward integration into precision fermentation ingredient production.
Among pharmaceutical-origin conglomerates, Otsuka Pharmaceutical Co., Ltd. and Meiji Holdings Co., Ltd. occupy positions anchored by pharmacy channel relationships and institutional procurement protocols. FANCL Corporation exemplifies the direct-to-consumer archetype through subscription engine ownership and personalized sachet bundling capabilities. DHC Corporation represents cosmetic-origin crossover positioning with vertically controlled manufacturing infrastructure. Yakult Honsha Co., Ltd. and Kirin Holdings Company, Limited demonstrate beverage-origin diversification into probiotic and functional ingredient categories.
| Leading Market Players |
|---|
| Otsuka Pharmaceutical Co., Ltd. |
| FANCL Corporation |
| DHC Corporation |
| Ajinomoto Co., Inc. |
| Meiji Holdings Co., Ltd. |
| ORIHIRO Co., Ltd. |
| Asahi Group Holdings, Ltd. |
| Yakult Honsha Co., Ltd. |
| Kirin Holdings Company, Limited |
| Others |
Pricing and Supply Chain Analysis
Omega-3 fatty acid import costs cascade through Japan's dietary supplements market from European and North American suppliers into tiered shelf pricing at pharmacy chains and direct-to-consumer subscription platforms. Currency volatility and shipping disruptions compress margins for probiotic and mineral complex manufacturers, forcing cost absorption in economy-tier products while premium FFC-certified formulations retain pricing power through clinical substantiation.
Pricing Analysis
Subscription-based recurring pricing anchors the dominant revenue model for direct-to-consumer platforms, with algorithm-curated monthly sachet assortments commanding loyalty-driven premiums over transactional pharmacy purchases. Three-tier pricing structure across premium, standard, and economy levels separates FFC-substantiated clinical formulations from generic vitamin bundles and private-label imports. Cost compression in economy-tier minerals intensifies because raw material import exposure and slotting fee extraction at national drugstore chains squeeze manufacturer margins. Seniors in Tokyo's 23 wards show lowest price sensitivity for swallowing-friendly formats and condition-specific geriatric fortification, while working-age subscription converters in Kansai exhibit highest elasticity to monthly bundling discounts.
Supply Chain Analysis
Regional distribution centers in Tokyo, Osaka, and Nagoya operate hub-and-spoke patterns that consolidate imported functional ingredients for final formulation and sachet assembly. Manufacturing feeds from European omega-3 suppliers, North American probiotic strain developers, and domestic precision fermentation facilities scaling in Kumamoto and Aichi prefectures. Single-source vulnerability concentrates in specific clinically documented probiotic strains and rare botanical extracts subject to PMDA import inspection protocols. Distribution runs through three national drugstore chains controlling pharmacy shelf access alongside FANCL's vertically integrated direct-to-consumer fulfillment infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's dietary supplements market represents a late-cycle quality story as aging demographics shift demand toward clinically substantiated, swallowing-friendly premium formulations over commodity vitamin bundles.
For Market Incumbents: Hedge margin erosion at national drugstore chains by accelerating backward integration into precision fermentation ingredient production and securing captive supply of domestic probiotic strains. Channel control through direct-to-consumer subscription data ownership offsets slotting fee extraction, while MHLW longevity technology tax incentives subsidize clinical trial costs for FFC substantiation.
For New Entrants and Emerging Players: Capture whitespace in Kansai region precision nutrition services where supplement penetration trails Kanto by 30 percentage points despite comparable disposable income. Osaka and Kyoto metropolitan areas present the most penetrable geography for telehealth-integrated subscription models, with algorithm-curated monthly sachet assortments displacing pharmacy impulse purchases among working-age professionals.
For Investors and Strategic Acquirers: Roll-up economics work for microbiome technology assets because clinical substantiation talent scarcity and FFC submission experience command premium compensation that constrains mid-tier expansion. Long-term viability over the projection horizon favors targets with established regulatory navigation capabilities and direct-to-consumer data infrastructure. Watch MHLW functional claims threshold revisions as the signal for where consumer trust and purchase behavior will concentrate.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Domestic biotechnology facilities in Kumamoto reduce omega-3 import dependency and enable novel strain-specific probiotic claims. |
| Direct-to-Consumer Platform Launch | Subscription engines capturing recurring revenue from algorithm-curated sachet assortments displace pharmacy impulse purchases in Kanto. |
| FFC Clinical Substantiation Investment | Japanese-population-specific trials satisfy MHLW guideline revisions and secure expedited immune function product pathways. |
| Telehealth Integration Partnership | Digital health ecosystems in Tokyo embed supplement recommendations into chronic disease management protocols. |
| Swallowing-Friendly Format Development | Compact softgel and liquid formulations address vitamin D and B12 fortification demand among adults over 75. |
Research Methodology
Coverage spans Kanto, Kansai, Chubu, Kyushu, and Hokkaido regions, with primary inputs from each including regulatory affairs specialists at PMDA and MHLW, pharmacy chain procurement managers, direct-to-consumer platform operators, and precision fermentation facility directors. Secondary validation draws from MHLW Foods with Function Claims registration databases, PMDA pharmaceutical-adjacent claim review filings, JIS quality standard certifications, and national dietary survey publications. Bottom-up demand modeling triangulates against top-down market sizing across product type, distribution channel, end user, and form segmentation dimensions.
Rate-of-change decomposition isolates volume and value drivers across the analysis window through cohort-based adoption curves for subscription models and pharmacy channel shift patterns. Segmentation dimensions modeled include product type, distribution channel, end user demographic, and form factor alongside regional regulatory cluster differentiation between FFC and traditional health food classifications. CAGRs derive from fitted growth curves incorporating aging demographic projections, telehealth platform penetration rates, and MHLW policy trajectory assumptions for functional claims substantiation thresholds.
Regulatory framework evolution, raw material import disruption severity, and precision fermentation domestic scaling velocity are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions around MHLW FFC guideline stability and currency exposure for European and North American ingredient sourcing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Zinc Supplement Market
Nutritional Supplements
Indonesia Beauty Supplements Market
Nutritional Supplements
Calcium Supplements Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Vegan Vitamins and Supplements Market
Nutritional Supplements
Selenium Yeast Market
Nutritional Supplements
Vegan Collagen Protein Market
Nutritional Supplements
Lutein Market
Nutritional Supplements
Middle East and Africa Nutraceutical Excipients Market
Nutritional Supplements
Global Ashwagandha Extract Market
Nutritional Supplements
Postbiotic Supplements Market
Nutritional Supplements
Vitamins and Minerals Market
Nutritional Supplements
US Protein Supplements Market
Nutritional Supplements
Omega 3 Market
Nutritional Supplements
USA Prenatal Vitamin Supplements Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market