
 United States Dairy Market | 2026-2036
United States Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
United States Dairy Market Insights
FDA enforcement of updated nutrition labeling and Grade A Pasteurized Milk Ordinance revisions is decoupling small-scale fluid processors from national retail distribution. Leprino Foods leverages vertical integration across mozzarella production to sustain cost advantages in foodservice cheese. Dairy Farmers of America anchors cooperative milk procurement across the Upper Midwest, while Land O'Lakes differentiates through branded butter and ingredient solutions. Schreiber Foods competes as a private-label cheese specialist serving quick-service restaurant chains.
United States dairy encompasses fluid milk, cheese, butter, and cultured products derived from bovine lactation, standardized to minimum fat and solids-not-fat content through centrifugal separation and thermal processing. Pasteurization at 72°C for 15 seconds or equivalent time-temperature profiles eliminates pathogens while preserving functional proteins for cheese manufacturing and extended shelf-life applications. Cheese commands the largest value pool among product types due to aged inventory carrying costs and export-grade specifications. Yogurt is expanding fastest through Greek-style and high-protein formulations, though fluid milk in bottles and cartons retains volume dominance in retail and institutional channels.
USDA administers Federal Milk Marketing Orders that establish minimum prices paid to producers, while FDA enforces safety standards under the Pasteurized Milk Ordinance and Food Safety Modernization Act. State departments of agriculture in Wisconsin and California supplement federal oversight with additional somatic cell count limits and antibiotic residue testing protocols. Stakeholders must monitor how proposed changes to milk pricing formulas and plant-based labeling disputes reshape competitive boundaries between conventional dairy and alternative protein entrants.
Market Dynamics
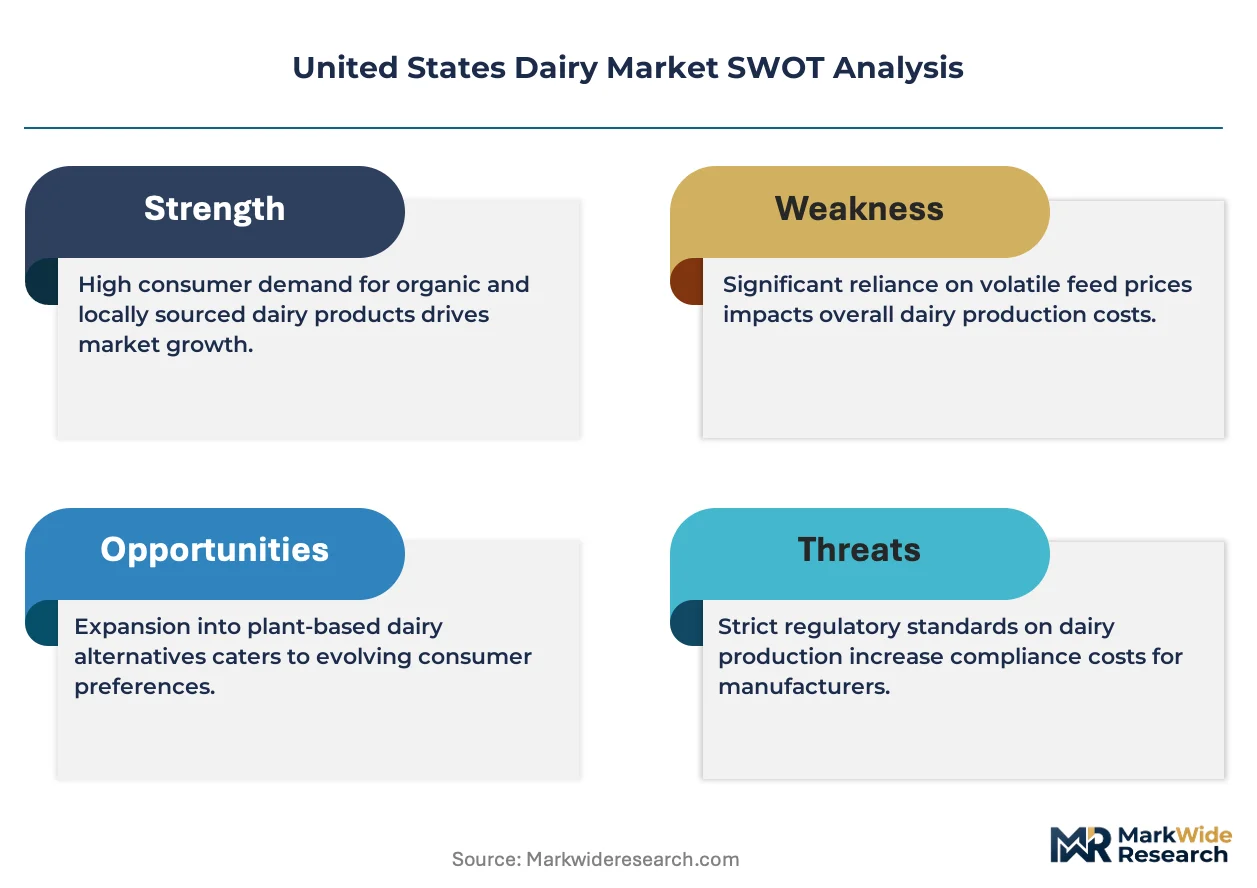
Federal Milk Marketing Order reforms are compressing processor margins while consolidating procurement power among large cooperatives, forcing mid-tier fluid milk handlers to exit or specialize in extended-shelf-life formats.
Growth Catalysts
- Extended-shelf-life processing:Ultra-high-temperature pasteurization and aseptic packaging are capturing institutional foodservice contracts from conventional fluid milk distributors.
- FDA nutrition labeling modernization:Updated serving-size declarations and added-sugar line items are repositioning flavored milk and protein-fortified beverages in school nutrition programs.
- Wisconsin-California procurement concentration:Cooperative scale in these states is driving backward integration into whey processing and ingredient fractionation.
Market Restraints
- Feed cost volatility:Corn and soybean meal price swings transmit directly to farm-gate milk production economics, squeezing independent producer margins.
- Plant-based substitution:Oat and almond beverage formulations are displacing fluid milk volume in retail refrigerated cases and coffee-shop channels.
- Grade A Pasteurized Milk Ordinance compliance burden:Small-scale processors face capital-intensive facility upgrades that bar national retail distribution access.
Strategic Opportunities
- Precision fermentation dairy proteins:Whey and casein production via microbial hosts is converging with conventional cheese manufacturing to reduce bovine herd dependency.
- USDA bioengineered food disclosure standard:Labeling clarity requirements are creating first-mover advantage for verified non-GMO fluid milk positioning in natural retail channels.
- Direct-to-institutional channels:K-12 school districts and healthcare systems are consolidating dairy procurement through cooperative purchasing agreements bypassing traditional distributors.
Industry Challenges
- Aseptic packaging technician scarcity:Extended-shelf-life line operation requires specialized thermal process engineering expertise concentrated among a limited workforce pool.
- Legacy ERP integration with traceability mandates:FSMA Section 204 food traceability rules are forcing dairy processors to retrofit batch-tracking systems onto decades-old plant software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Dairy Market |
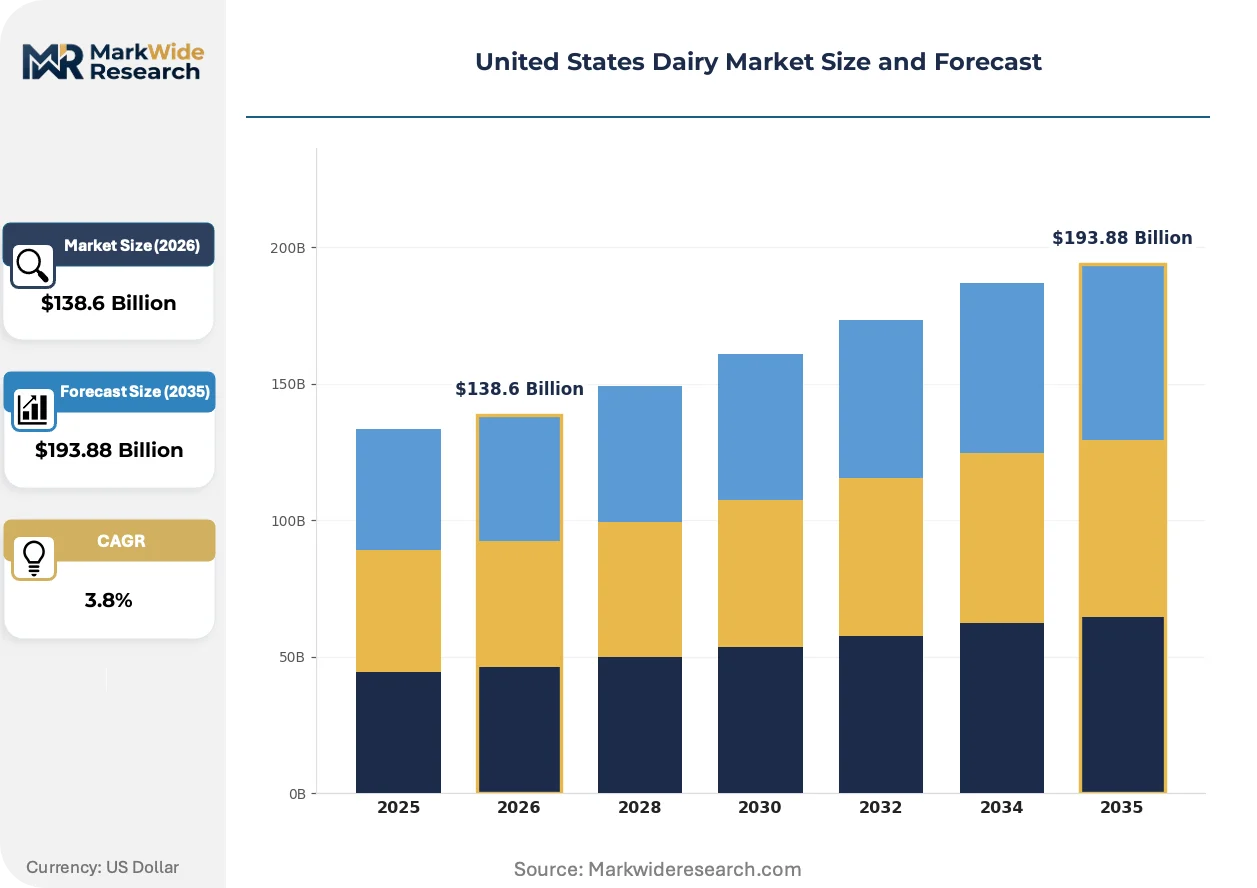
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $193.88 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Butter, Yogurt End User: Retail, Foodservice, Consumer, Bakery Distribution Channel: Online, Supermarkets, Wholesalers, Convenience Stores Packaging Type: Bottles, Tetra Packs, Cartons, Bags |
| Companies Covered | Leprino Foods, Edge Dairy Farm Cooperative, Dairy Farmers of America, Prairie Farms Dairy, California Dairies, Land O'Lakes, Foremost Farms USA, Saputo, Schreiber Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Dairy Market Trends and Innovations
Processing technology and regulatory disclosure requirements are compressing traditional product lifecycles while opening white space in protein ingredient and functional dairy categories.
Membrane filtration technology is converging with chromatographic separation to enable native whey protein isolate recovery at industrial scale. Large mozzarella and whey processors are installing ceramic microfiltration systems to capture immunoglobulins and lactoferrin for sports nutrition and infant formula applications. This convergence is collapsing the historical boundary between commodity cheese production and high-value ingredient manufacturing.
FDA enforcement of the Food Safety Modernization Act's preventive controls for human food rule is mandating hazard analysis and risk-based preventive controls across all dairy manufacturing facilities. Fluid milk processors must now implement environmental monitoring programs for Listeria monocytogenes and validate kill-step processes for unpasteurized dairy ingredients. Small-scale artisan cheese operations in Vermont and New York are responding by exiting interstate commerce or consolidating under larger cooperative inspection umbrellas.
Foodservice operators are unbundling dairy procurement from broadline distribution contracts to negotiate direct pricing with cooperative-owned processing plants. Quick-service restaurant chains and institutional feeding operations are establishing volume commitments with Dairy Farmers of America and Land O'Lakes in exchange for price caps and supply security. This disintermediation is most visible in the Upper Midwest, where processor-owned logistics networks can bypass traditional foodservice redistribution warehouses.
United States Dairy Market Segmentation
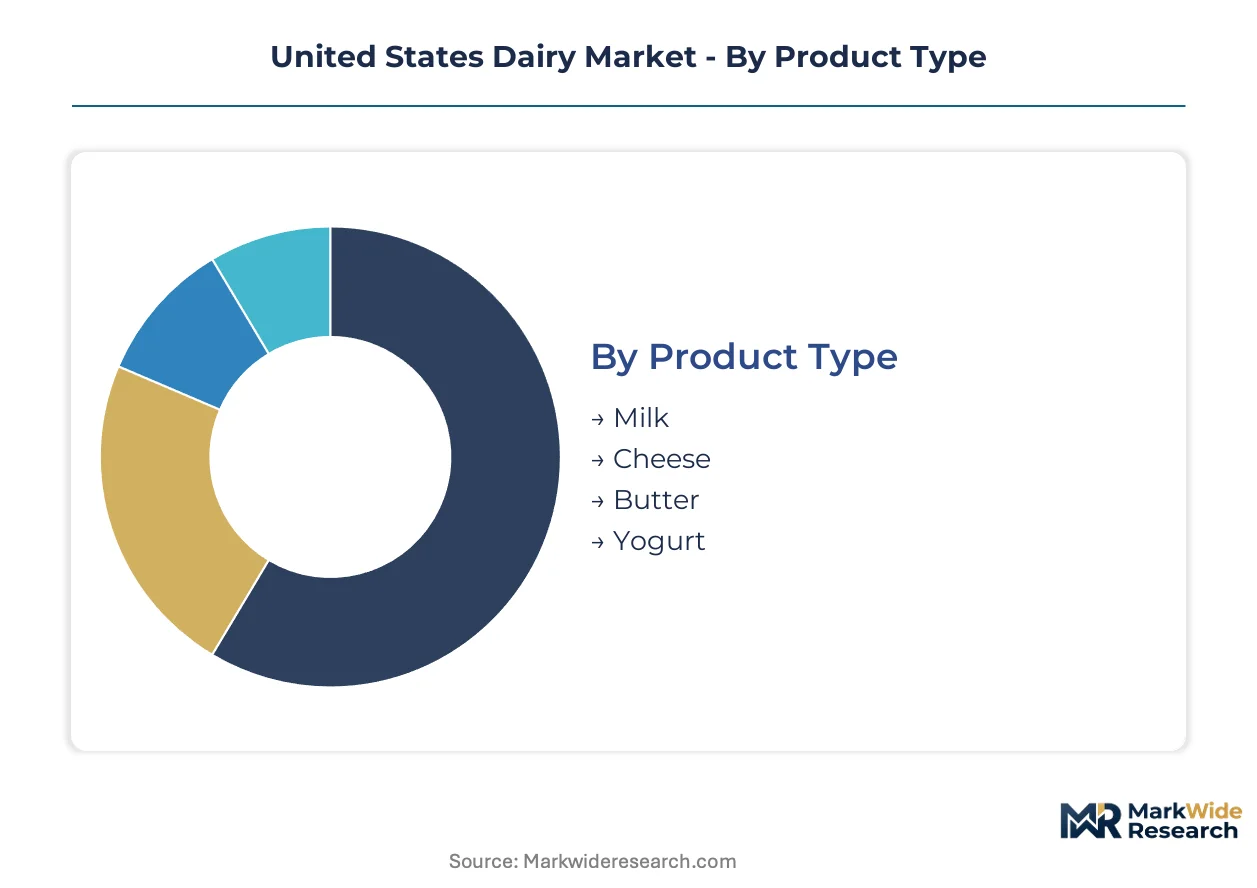
Segmentation in the United States dairy market reveals how processing technology and channel economics partition value capture. Distinct product specifications, packaging requirements, and temperature controls create specialized competitive arenas where scale advantages vary dramatically.
Product Type:
Standalone consumption formats dominate retail velocity, while embedded ingredient applications anchor foodservice procurement.
- Milk:Fluid milk requires Grade A Pasteurized Milk Ordinance compliance with standardized fat content from 0% to 3.25%. Extended-shelf-life aseptic packaging is capturing institutional foodservice contracts in K-12 schools and healthcare systems, displacing conventional fluid distributors.
- Cheese:Natural and processed cheese categories span fresh mozzarella through aged cheddar, with moisture content and milkfat standards codified by FDA. Wisconsin and California processors concentrate aged inventory carrying costs and export-grade specifications, driving backward integration into whey fractionation.
- Butter:Minimum 80% milkfat content separates sweet cream from cultured butter variants.
- Yogurt:Greek-style and high-protein formulations are expanding through refrigerated retail cases.
Volume placements concentrate in milk; the faster expansion belongs to yogurt.
End User:
Direct-to-consumer channels maintain price stability, while intermediate processing buyers demand volume-flexible contracting.
- Retail:Supermarket and mass merchandiser channels require case-ready packaging with front-of-label nutrition disclosure compliance. Private-label fluid milk and cheese programs are consolidating shelf space under cooperative-owned brands like Dairy Farmers of America and Land O'Lakes.
- Foodservice:Quick-service restaurant chains and institutional feeding operations negotiate direct procurement agreements with cooperative processing plants. Leprino Foods and Schreiber Foods anchor mozzarella and private-label cheese supply through disintermediated logistics networks bypassing broadline distributors.
- Consumer:Direct purchasing through farmers markets and subscription services.
- Bakery:Butter and concentrated milk solids for industrial baking applications.
Foodservice procurement is climbing the fastest; retail retains the largest absolute volume position.
Distribution Channel:
Cold-chain infrastructure requirements segment channel economics by temperature integrity investment.
- Supermarkets:Refrigerated dairy cases command premium placement fees and temperature-controlled receiving protocols. Cooperative-owned brands leverage direct-store-delivery networks to maintain margin control against conventional wholesaler markups.
- Online:E-commerce fulfillment requires insulated packaging and same-day cold-chain logistics that favor extended-shelf-life products.
- Wholesalers:Broadline redistribution warehouses face disintermediation pressure from direct cooperative contracts.
- Convenience Stores:Grab-and-go fluid milk and single-serve cheese snacks target immediate consumption occasions.
Supermarket placements dominate current volume; online channels show the steepest expansion trajectory.
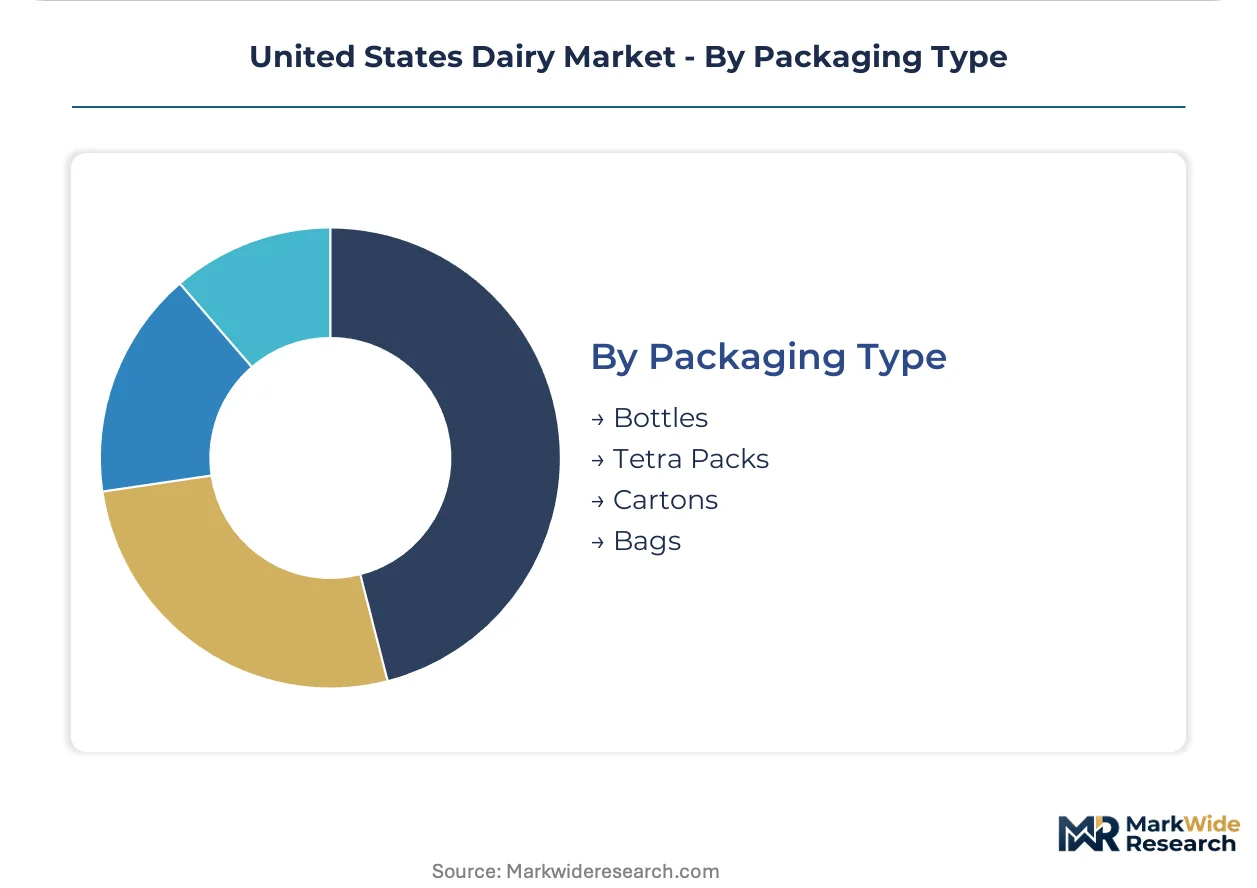
Packaging Type:
Barrier properties and shelf-life extension capabilities determine packaging selection across temperature regimes.
- Tetra Packs:Aseptic carton technology enables ambient distribution of UHT-processed fluid milk and cream, unlocking institutional procurement contracts without refrigerated logistics. FDA nutrition labeling modernization requires updated serving-size declarations on these formats.
- Bottles:HDPE and PET containers retain dominance in refrigerated retail fluid milk with established curbside recycling infrastructure.
- Cartons:Gable-top refrigerated cartons serve school nutrition programs with portion-controlled servings.
- Bags:Flexible pouch formats reduce shipping cube for bulk foodservice deliveries.
Bottle volume concentrates in retail dairy cases; Tetra Pack adoption is gaining share fastest in institutional channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluid milk demand concentrates in Wisconsin and California, where cooperative scale and processor consolidation dominate procurement patterns. These two states anchor national cheese production and ingredient fractionation capacity. Regional specialization is deepening as Federal Milk Marketing Order reforms reshape pooling arrangements across state boundaries.
California
Central Valley dairies supply mozzarella and whey protein isolate for quick-service restaurant chains and sports nutrition brands. California Department of Food and Agriculture enforces additional somatic cell count limits beyond federal standards. Tulare and Merced counties concentrate milk production volume, with processors installing ceramic microfiltration systems for immunoglobulin recovery.
Wisconsin
Green Bay and Madison corridors anchor aged cheddar and specialty cheese manufacturing for export-grade specifications. Wisconsin Department of Agriculture, Trade and Consumer Protection supplements FDA oversight with antibiotic residue testing protocols. Fond du Lac and Dodge counties host cooperative-owned processing plants that bypass traditional foodservice redistribution warehouses through direct logistics networks.
Idaho
Magic Valley dairies supply milk solids for industrial baking and concentrated dairy ingredients. Idaho State Department of Agriculture monitors Grade A Pasteurized Milk Ordinance compliance for interstate shipment authorization. Twin Falls and Jerome counties attract processor investment in extended-shelf-life aseptic packaging lines for institutional foodservice contracts.
New York
Champlain Valley and Finger Lakes regions sustain artisan cheese operations and fluid milk bottling for metropolitan distribution. New York State Department of Agriculture and Markets enforces environmental monitoring programs for Listeria monocytogenes under FSMA preventive controls. Small-scale processors in Vermont and upstate New York face capital-intensive facility upgrades or consolidation under cooperative inspection umbrellas.
Texas
Panhandle dairies supply fluid milk and cream for southwestern retail and foodservice channels. Texas Department of State Health Services coordinates with FDA on Pasteurized Milk Ordinance enforcement and nutrition labeling modernization. Lubbock and Plainview processing clusters capture institutional contracts through ultra-high-temperature pasteurization and Tetra Pack distribution without refrigerated logistics.
United States Dairy Market Competitive Landscape
Wisconsin producers anchor one tier; California specialists hold concentrated mozzarella and whey processing capacity. The market structures around cooperative-owned scale operations and private-label specialists, with mid-tier fluid handlers facing margin compression from Federal Milk Marketing Order reforms. Three archetypes dominate: vertically integrated cheese processors, cooperative procurement anchors, and private-label foodservice suppliers. Competitive moves concentrate on direct-to-institutional contracting and backward integration into ingredient fractionation.
Within the cooperative tier, Dairy Farmers of America and Land O'Lakes occupy positions as procurement anchors across the Upper Midwest, while Schreiber Foods exemplifies the private-label specialist archetype serving quick-service restaurant chains. Leprino Foods represents vertical integration across mozzarella production, sustaining cost advantages through captive whey processing. These three companies illustrate how scale, cooperative structure, and foodservice specialization partition competitive positioning in an environment of disintermediated logistics and direct institutional contracting.
| Leading Market Players |
|---|
| Leprino Foods |
| Edge Dairy Farm Cooperative |
| Dairy Farmers of America |
| Prairie Farms Dairy |
| California Dairies |
| Land O'Lakes |
| Foremost Farms USA |
| Saputo |
| Schreiber Foods |
| Others |
Pricing and Supply Chain Analysis
Ultra-high-temperature pasteurization and aseptic packaging adoption simultaneously compresses per-unit processing costs and concentrates procurement leverage among cooperative-owned plants with capital to install these lines. This technology transition redraws competitive boundaries between extended-shelf-life specialists and conventional fluid handlers.
Pricing Analysis
Volume placements in conventional fluid milk generate thin margins while extended-shelf-life and ingredient fractionation command premium returns. Three-tier pricing structure separates organic-certified fluid milk from conventional Grade A and private-label economy tiers. Pricing pressure stems from Federal Milk Marketing Order reforms that compress handler spreads. School nutrition programs and quick-service restaurant chains exhibit highest price sensitivity; sports nutrition brands purchasing native whey protein isolate show lowest.
Supply Chain Analysis
Feed grain supply rests on Midwest corn and soybean meal markets, with protein supplement inputs drawing from South American soybean exports. Ceramic microfiltration membranes and aseptic packaging equipment sources from European and Japanese specialty manufacturers. Single-source vulnerability concentrates in extended-shelf-life line engineering expertise. Distribution runs through cooperative-owned direct-store-delivery networks bypassing broadline redistribution warehouses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation technology for dairy protein production is displacing conventional bovine-sourced whey and casein, forcing incumbent processors to reposition around hybrid manufacturing or specialty ingredient niches.
For Market Incumbents: Lock in institutional foodservice contracts through volume commitments and price caps before precision fermentation proteins achieve cost parity. Secure captive whey processing capacity to defend margin position against microbial protein substitutes. Extend environmental monitoring capabilities to meet FSMA preventive controls without reliance on third-party inspection umbrellas. For New Entrants and Emerging Players: FDA nutrition labeling modernization in the United States opens a window for clean-label fluid milk positioning in natural retail channels underserved by cooperative brands. Target direct-to-institutional procurement in K-12 school districts consolidating dairy purchasing. Enter through verified non-GMO certification and front-of-package transparency claims that legacy processors cannot match without reformulation costs. For Investors and Strategic Acquirers: Exit pathways concentrate in cooperative acquisition of distressed mid-tier fluid handlers unable to fund Grade A facility upgrades. Long-term viability favors processors with backward integration into whey fractionation and ingredient recovery. Watch precision fermentation cost curves as the inflection indicator for conventional dairy protein margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Shelf-Life Line Installation | UHT and aseptic capacity captures institutional contracts from conventional fluid distributors in K-12 and healthcare channels. |
| Backward Integration into Whey Processing | Captive immunoglobulin and lactoferrin recovery feeds sports nutrition and infant formula ingredient demand. |
| Direct-to-Institutional Contracting | Bypassing broadline distributors secures volume commitments with price caps from quick-service restaurant chains. |
| Precision Fermentation Partnership | Microbial dairy protein sourcing reduces bovine herd dependency while maintaining cheese manufacturing functionality. |
| FSMA Traceability System Upgrade | Batch-tracking retrofit enables compliance with Section 204 food traceability mandates for interstate distribution. |
Research Methodology
Independent corroboration across cooperative procurement managers, fluid milk plant engineers, foodservice category buyers, and dairy ingredient sales directors underwrites the qualitative findings. Secondary validation draws from USDA Federal Milk Marketing Order announcements, FDA Pasteurized Milk Ordinance revisions, state agriculture department inspection protocols, and cooperative financial disclosures. Bottom-up volume estimates from processor capacity and top-down demand segmentation triangulate market sizing.
Rate-of-change decomposition separates volume growth from value expansion across product type, end user, distribution channel, and packaging format dimensions throughout the forecast period. CAGRs derive from segment-level growth rate blending anchored in historical production data and forward-looking procurement contract analysis. Feed cost volatility, plant-based substitution rates, and extended-shelf-life adoption curves feed the projection model.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation dairy proteins would alter the outlook. Forecasts reflect assumptions about Federal Milk Marketing Order stability and Grade A compliance enforcement without revision. A small set of triggers—regulatory pricing formula changes, microbial protein cost breakthroughs, and aseptic packaging technician availability—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Dry Whole Milk Powder Market
Dairy Products
United States Casein and Caseinate Market
Dairy Products
Cream Powder Market
Dairy Products
Ultra High Temperature Milk Market
Dairy Products
High Protein Yogurt Market
Dairy Products
Halal Cheese Market
Dairy Products
White Cheese Market
Dairy Products
Plain Yogurt Market
Dairy Products
Mozzarella Cheese Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Malted Milk Powder Market
Dairy Products
Cream and Soft Cheese Market
Dairy Products
Qatar Dairy Products Market
Dairy Products
Saudi Arabia Dairy Products Market
Dairy Products
South America Dairy Market
Dairy Products
Global Lipolyzed Butter Fat Market