
 United States Camel Dairy Market | 2026-2036
United States Camel Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
United States Camel Dairy Market Intelligence
Camel milk powder is hardening as the preferred shelf-stable format over refrigerated liquid milk, cutting logistics costs for producers serving dispersed U.S. markets. Desert Farms leverages direct-to-consumer subscription channels to sustain repeat purchase rates among allergen-sensitive households. Oasis Camel Dairy anchors its position through on-farm agritourism and educational programming that builds brand loyalty. Camel Culture competes by specializing in small-batch fermented products with distinctive regional flavor profiles.
United States camel dairy encompasses the commercial production, processing, and distribution of milk and milk-derived products from Camelus dromedarius and Camelus bactrianus species, typically yielding milk with lower lactose content and higher vitamin C concentration than bovine alternatives. The primary commercial purpose centers on serving consumers with cow milk protein allergies, autoimmune conditions, and specialized nutritional requirements who seek functional food alternatives. Milk and nutritional products represent established revenue streams with predictable margin profiles, while functional foods and infant formulas emerge as faster-expanding categories driven by pediatric nutrition research and clean-label formulation trends. Specialty stores and direct sales channels capture premium pricing power, whereas supermarket placement signals mainstream normalization and volume scaling potential.
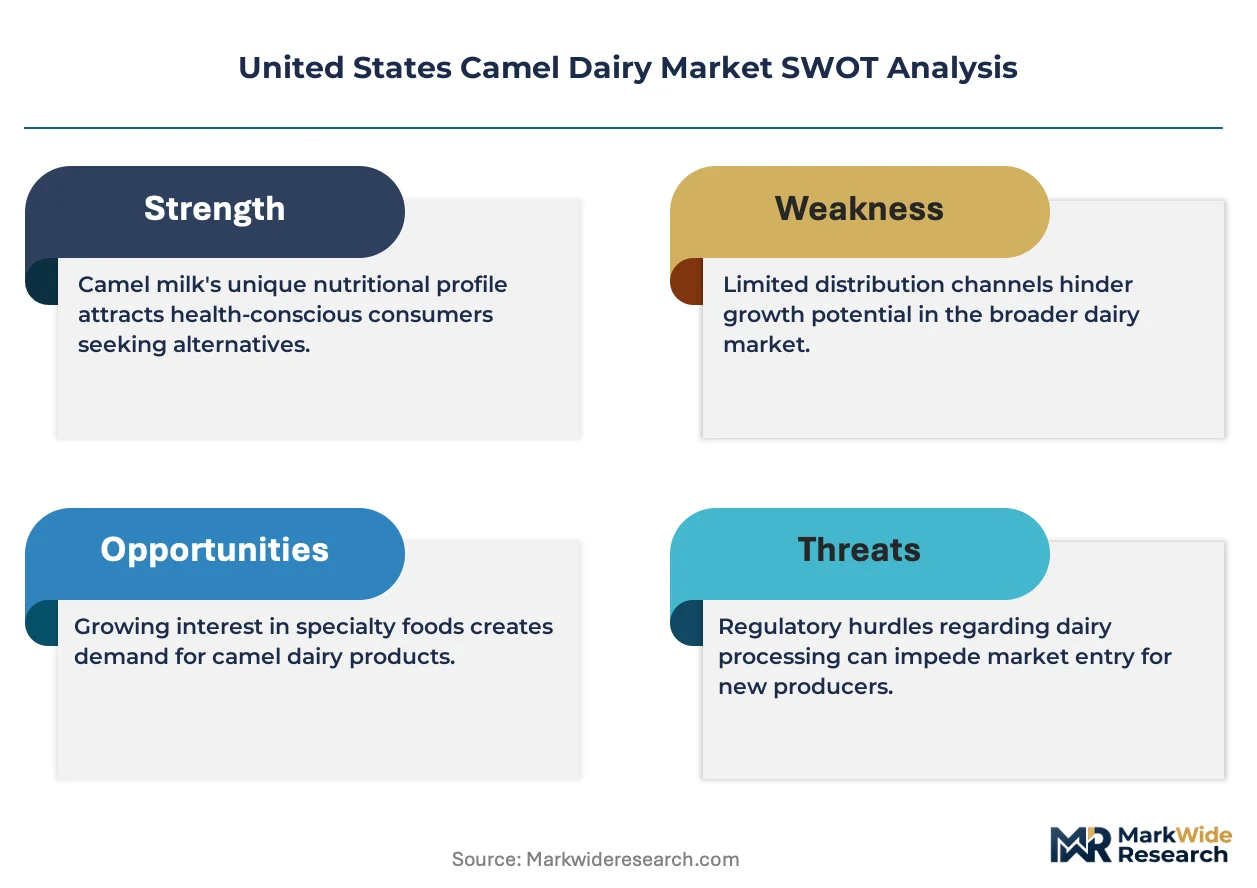
FDA standards for interstate milk shipment and state agricultural department inspections govern product safety, labeling, and market access across the fragmented U.S. regulatory landscape. USDA organic certification and state-level raw milk permits create tiered compliance thresholds that filter producer participation and shape consumer price stratification. Stakeholders must monitor evolving FDA guidance on alternative dairy nomenclature and state legislative movements affecting raw camel milk sales, as these regulatory determinations will dictate channel expansion feasibility and competitive positioning for emerging entrants.
Market Dynamics
FDA labeling requirements for alternative dairy products and state-level raw milk regulations are fragmenting commercialization pathways, forcing producers to navigate divergent compliance thresholds across California, Texas, and emerging state markets.
Growth Catalysts
- Lactose-intolerant consumer base:Camel milk's naturally lower lactose content attracts households seeking functional alternatives to bovine dairy, expanding the addressable market beyond traditional specialty health-food channels.
- USDA organic certification pathways:Tiered compliance thresholds filter producer participation while enabling premium price stratification for certified operations serving wellness-focused buyer segments.
- California-Texas production clustering:Established camel ranches and direct-to-consumer operations concentrate near major metropolitan distribution corridors, reducing last-mile logistics costs for refrigerated and shelf-stable formats.
Market Restraints
- Input cost volatility:Camel feed and veterinary care costs fluctuate with drought cycles affecting hay and forage supply in Southwestern states, compressing margin predictability for ranch-scale producers.
- Supply concentration risk:Domestic camel herd size remains concentrated among fewer than two hundred commercial operations, creating bottleneck vulnerability if disease or climate events affect regional breeding stock.
- Interstate shipment friction:FDA standards for interstate milk shipment impose pasteurization and testing requirements that block raw camel milk distribution across state lines, limiting market access for unpasteurized product advocates.
Strategic Opportunities
- Pediatric nutrition formulations:Functional foods and infant formulas emerge as faster-expanding categories driven by emerging clinical research on camel milk protein digestibility in early childhood.
- Direct-to-consumer subscription channels:Digital-native households with allergen-sensitive children sustain repeat purchase rates through automated replenishment models bypassing traditional retail markups.
- On-farm agritourism integration:Educational programming and ranch visitation experiences build brand loyalty while capturing margin-rich experiential revenue streams alongside core dairy sales.
Industry Challenges
- Veterinary specialist scarcity:Camel-specific veterinary expertise remains concentrated in academic and research institutions, forcing producers to rely on modified bovine protocols or expensive consultant arrangements.
- State-by-state compliance complexity:Raw milk permits, organic certification timelines, and alternative dairy nomenclature disputes create fragmented regulatory navigation costs that scale with geographic expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Camel Dairy Market |
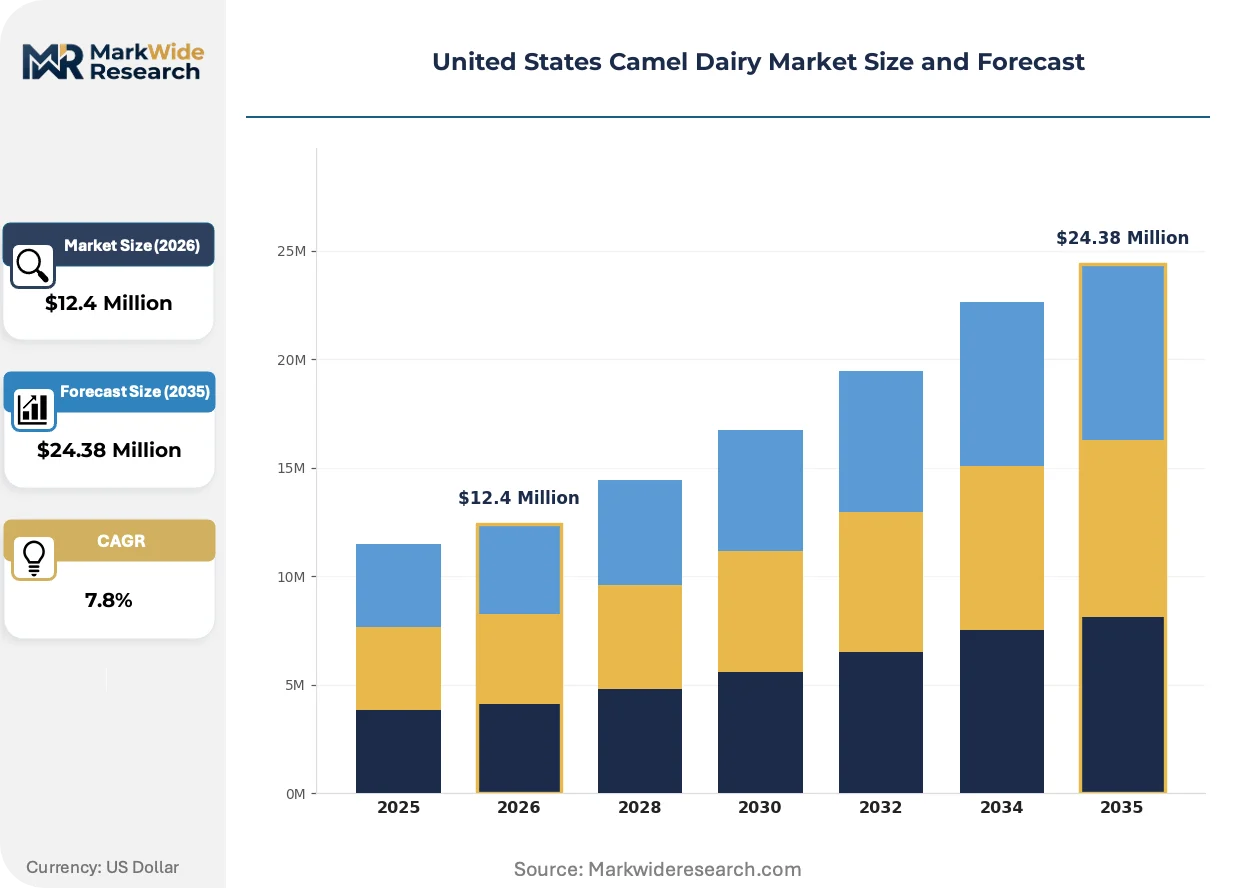
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $24.38 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Ice Cream End User: Retail Consumers, Hotels, Restaurants, Cafeterias Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales Application: Nutritional Products, Infant Formulas, Functional Foods, Cosmetics |
| Companies Covered | Humpback Dairy, Sahara Camel Milk, Desert Farms, River Jordan Camel Dairy, Camel Culture, Oasis Camel Dairy, Camel Milk USA, Nutra Wellness, Camelot Camel Dairy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Camel Dairy Market Strategic Shifts & Innovations
Shelf-stable processing formats and digital distribution infrastructure are compressing traditional cold-chain dependencies, enabling producers to serve dispersed households without metropolitan proximity.
Spray-drying and freeze-drying technologies for camel milk powder is unifying production economics across dispersed geographies. Small-batch producers in Arizona and New Mexico adopt these systems to reach East Coast buyers without refrigerated freight. The technology is unifying margin structures previously split between local fresh markets and national powder distribution.
State agricultural department inspection protocols are tightening traceability requirements for alternative dairy products. California and Texas now mandate batch-level testing documentation for intrastate raw milk sales. Producers serving multi-state markets must maintain parallel compliance systems or abandon raw product lines entirely.
Subscription-based replenishment models displace intermittent retail purchasing among allergen-sensitive households. Desert Farms and similar direct-to-consumer operations capture lifetime value through automated delivery schedules. This behavioral shift concentrates most visible in California and Texas metropolitan corridors where digital-native parents prioritize convenience over supermarket availability.
United States Camel Dairy Market Segmentation
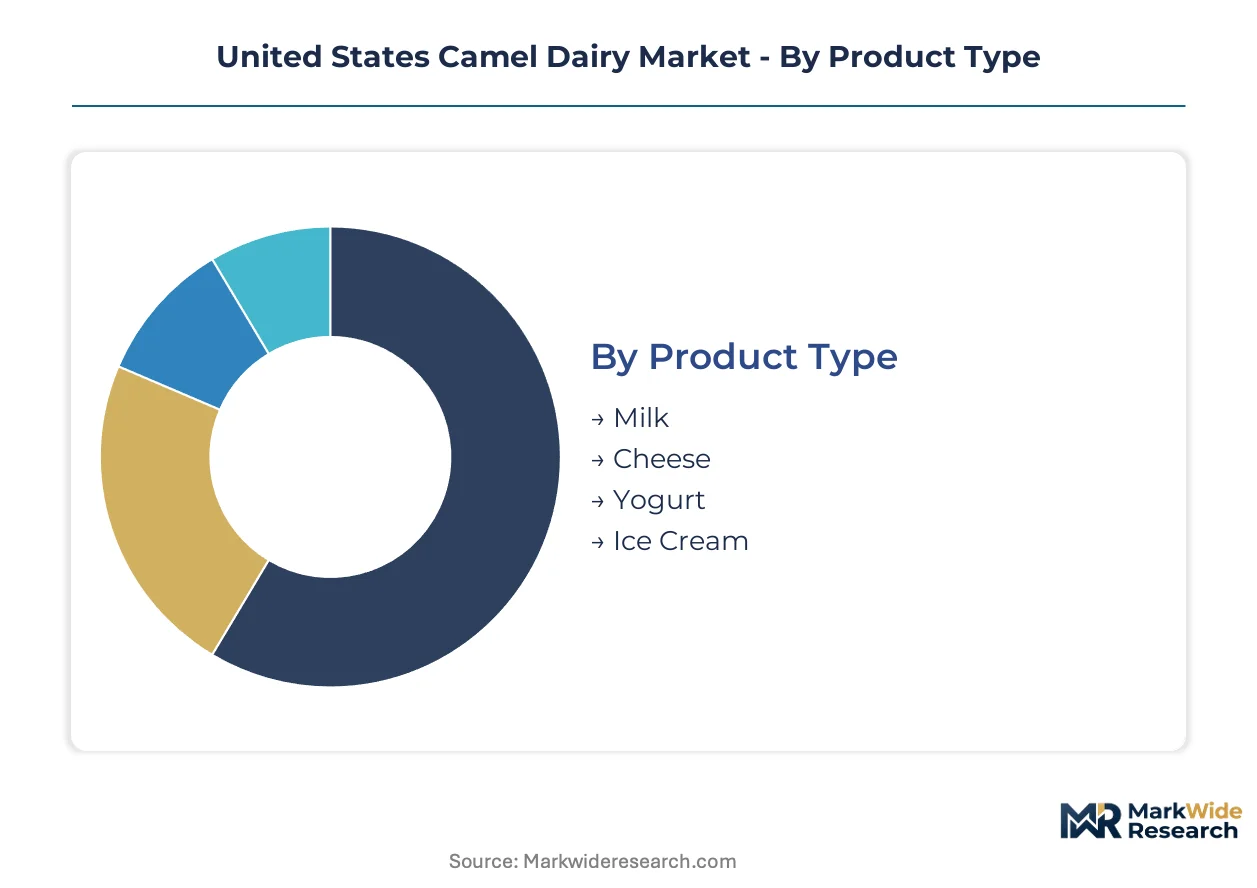
Product format and distribution channel configurations determine margin capture for U.S. camel dairy operators navigating fragmented state regulations. End-user concentration in allergen-sensitive households versus foodservice buyers shapes formulation priorities and shelf-life requirements.
Product Type:
Standalone liquid formats serve immediate consumption needs while processed derivatives embed camel milk into longer supply chains for specialized nutrition and foodservice applications.
- Milk:Raw and pasteurized liquid milk delivers the highest per-unit nutrient density with preserved immunoglobulin structures. Demand clusters in California and Texas metropolitan corridors where direct-to-consumer operations bypass interstate shipment restrictions. FDA pasteurization mandates for cross-border distribution compress margins for operators seeking national reach.
- Cheese:Fermented curd products require extended aging protocols adapted from small-ruminant cheesemaking traditions. Specialty retailers in Arizona and New Mexico stock aged varieties targeting gastronome segments willing to absorb premium positioning.
- Yogurt:Probiotic cultures in camel milk yogurt target digestive wellness positioning.
- Ice Cream:Frozen dessert formats extend seasonal demand windows through indulgence positioning.
Milk leads volumes today; cheese is gaining share fastest.
End User:
Customer type stratification separates high-frequency household replenishment from intermittent bulk procurement by institutional foodservice operators.
- Retail Consumers:Allergen-sensitive households with lactose intolerance or cow milk protein allergies drive recurring subscription purchases. California and Texas zip codes with pediatric functional medicine practices show highest per-capita consumption intensity.
- Hotels:Boutique hospitality properties in Scottsdale and Santa Fe differentiate breakfast programs with camel milk alternatives.
- Restaurants:Farm-to-table establishments feature camel dairy in tasting menus.
- Cafeterias:Institutional feeding operations pilot camel milk in specialized diet protocols.
Retail consumers anchor current revenue; restaurants show steepest expansion trajectory.
Distribution Channel:
Channel selection dictates regulatory exposure and working capital requirements, with digital-native routes minimizing physical footprint compliance costs.
- Online:Subscription platforms capture lifetime value through automated replenishment while circumventing retail slotting fees. Desert Farms and similar operators leverage California and Texas fulfillment nodes to maintain cold-chain integrity for refrigerated formats.
- Supermarkets:Conventional grocery placement signals mainstream normalization but requires volume guarantees and promotional spending.
- Specialty Stores:Health-food retailers command premium pricing power through educated staff and curated assortments.
- Direct Sales:On-farm pickup and farmers market presence build brand authenticity for agritourism-integrated operations.
Specialty stores dominate current throughput; online channels are climbing the fastest.
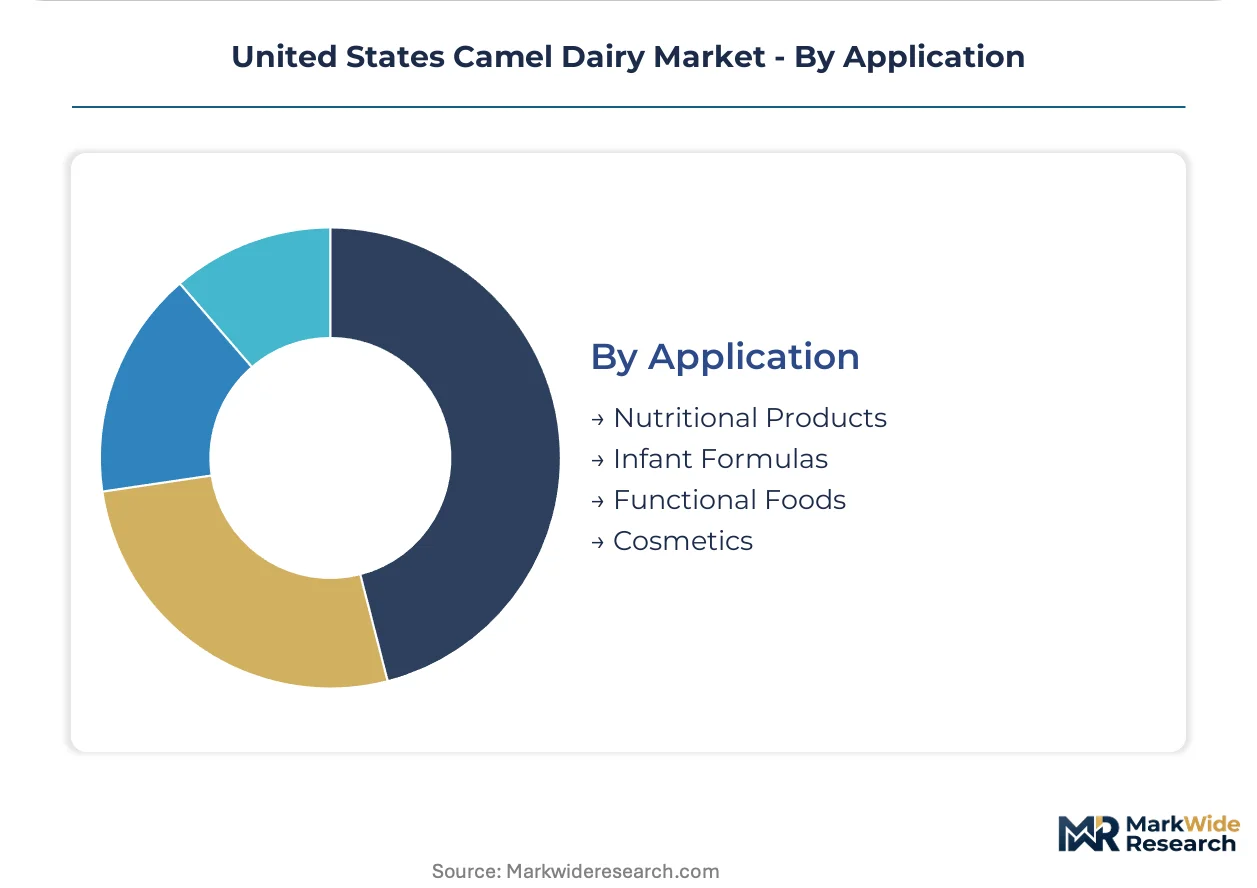
Application:
Application depth ranges from basic nutritional substitution to clinically-informed formulations requiring manufacturing partnerships and pediatric research validation.
- Nutritional Products:Powdered milk and fortified beverages serve adult wellness positioning with established supply chains. Arizona producers utilizing spray-drying technology reach East Coast buyers without refrigerated freight infrastructure.
- Infant Formulas:Pediatric nutrition applications demand stringent protein digestibility documentation and FDA infant formula compliance pathways.
- Functional Foods:Immune-modulating positioning targets autoimmune condition management.
- Cosmetics:Topical formulations leverage camel milk fatty acid profiles in premium skincare.
Nutritional products hold current volume leadership; infant formulas represent the most rapid share ascent.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Imperial Valley and Central Coast host the densest concentration of commercial camel dairies in the United States, with operations clustered within two hours of Los Angeles and San Diego distribution corridors.
California
Los Angeles and San Diego metropolitan households drive premium demand for pasteurized and raw camel milk formats. California Department of Food and Agriculture enforces batch-level testing documentation for intrastate raw milk sales. Oasis Camel Dairy anchors Southern California's agritourism-integrated segment through on-farm educational programming near San Diego.
Texas
Dallas-Fort Worth and Houston allergen-sensitive households sustain subscription-based replenishment through direct-to-consumer channels. Texas Department of State Health Services maintains pasteurization exemptions for on-farm sales while restricting interstate raw milk shipment. Humpback Dairy and Sahara Camel Milk operate ranches within Central Texas hay production zones, reducing feed cost volatility.
Arizona
Phoenix and Tucson wellness-focused consumers absorb spray-dried camel milk powder from regional producers. Arizona Department of Agriculture mandates veterinary inspection protocols for alternative dairy species entering commercial production. River Jordan Camel Dairy and Camel Culture cluster near Phoenix metropolitan distribution nodes, leveraging lower land costs than California competitors.
New Mexico
Santa Fe and Albuquerque boutique hospitality properties differentiate foodservice programs with camel dairy ingredients. New Mexico Livestock Board enforces traceability requirements for raw milk sales at farmers markets and on-farm pickup locations. Camelot Camel Dairy serves Southwestern gastronome segments through aged cheese varieties stocked by Santa Fe specialty retailers.
Colorado
Denver-Boulder corridor functional medicine practices refer pediatric patients to camel milk nutritional products. Colorado Department of Agriculture coordinates with FDA on interstate shipment compliance for pasteurized formats. Nutra Wellness and Camel Milk USA maintain fulfillment infrastructure serving Mountain West direct-to-consumer demand through refrigerated logistics partnerships.
United States Camel Dairy Market Key Industry Players
Regional specialists compete with vertically integrated ranch operations across distribution channel configuration, with market structure fragmenting across state regulatory boundaries that favor localized compliance expertise. Three strategic archetypes dominate: agritourism-integrated producers capturing experiential revenue alongside core dairy sales; direct-to-consumer subscription operators leveraging digital channels to bypass retail markups; and powder-focused processors utilizing spray-drying technology to serve dispersed geographies without cold-chain dependency. Capacity expansion and portfolio diversification toward fermented products represent the dominant competitive moves.
Within the agritourism-integrated tier, Oasis Camel Dairy exemplifies experiential revenue anchoring through educational programming and ranch visitation. Desert Farms occupies the direct-to-consumer subscription archetype, sustaining repeat purchase rates among allergen-sensitive households through automated replenishment. Camel Culture represents the small-batch fermentation specialist, targeting distinctive regional flavor profiles in yogurt and cheese formats.
| Leading Market Players |
|---|
| Humpback Dairy |
| Sahara Camel Milk |
| Desert Farms |
| River Jordan Camel Dairy |
| Camel Culture |
| Oasis Camel Dairy |
| Camel Milk USA |
| Nutra Wellness |
| Camelot Camel Dairy |
| Others |
Cost & Logistics Intelligence
Family-owned ranch operations concentrated in California and Texas exercise tight supply discipline, translating feed cost volatility directly into tiered price positioning across raw milk, pasteurized formats, and shelf-stable derivatives.
Pricing Analysis
Input cost pass-through from drought-affected hay and forage markets drives margin compression for refrigerated liquid formats while powder processors absorb less volatility. Three-tier pricing structure across USDA organic certified, conventional pasteurized, and raw direct-to-consumer tiers separates allergen-sensitive households willing to pay subscription premiums from price-elastic supermarket shoppers. Pricing pressure stems from veterinary specialist scarcity forcing expensive consultant arrangements. Retail consumers through specialty health-food channels show lowest price sensitivity; conventional grocery shoppers exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Los Angeles, Dallas-Fort Worth, and Phoenix anchor hub-and-spoke patterns for refrigerated formats while powder shipments bypass cold-chain dependencies entirely. Domestic supply concentrates in California, Texas, and Arizona where established camel ranches cluster near metropolitan corridors. Feed inputs draw from Southwestern hay production zones, veterinary pharmaceuticals, and packaging materials for subscription fulfillment. Single-source vulnerability runs through concentrated breeding stock among fewer than two hundred commercial operations. Distribution runs through direct-to-consumer subscription platforms, specialty retailers, and agritourism-integrated on-farm pickup.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spray-drying technology adoption compresses per-unit production costs for shelf-stable formats, expanding addressable margin capture beyond metropolitan cold-chain constraints.
For Market Incumbents: Deploy backward integration into captive hay production to insulate feed cost volatility from margin erosion. Consolidate veterinary specialist relationships through academic institution partnerships before consultant rates escalate further. Desert Farms and Oasis Camel Dairy demonstrate how channel control through subscription platforms defends against supermarket price competition.
For New Entrants and Emerging Players: The gap between premium subscription pricing and economy powder tiers offers entry space for Arizona and New Mexico operators leveraging lower land costs. White-space targets include pediatric nutrition formulations requiring FDA infant formula compliance partnerships and boutique hospitality foodservice programs in Santa Fe and Scottsdale. Go-to-market through direct-to-consumer digital channels bypasses retail slotting fee barriers.
For Investors and Strategic Acquirers: Valuations sit cheapest among powder-focused processors utilizing spray-drying technology to serve dispersed geographies without refrigerated logistics infrastructure. Long-term viability frames around consolidation of fragmented state regulatory expertise as FDA alternative dairy nomenclature guidance solidifies. Acquisition target archetype: regional specialists with established USDA organic certification and multi-state distribution permits. Signal to watch: state legislative movements expanding raw milk sales permissions.
| Strategic Initiative | Industry Significance |
|---|---|
| Shelf-Stable Format Expansion | Spray-drying technology enables East Coast market access without refrigerated freight infrastructure. |
| Direct-to-Consumer Channel Buildout | Subscription platforms capture lifetime value from allergen-sensitive households bypassing retail markups. |
| USDA Organic Certification Investment | Premium tier positioning defends margin structure against conventional dairy price competition. |
| Pediatric Nutrition Formulation Development | FDA infant formula compliance pathways open fastest-expanding application segment. |
| Agritourism Integration | On-farm educational programming builds brand loyalty alongside core dairy revenue streams. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with camel dairy ranch operators, specialty health-food retail buyers, veterinary specialists, FDA regulatory affairs consultants, and pediatric functional medicine practitioners combined with secondary validation from USDA organic certification databases, FDA interstate milk shipment standards, state agricultural department inspection protocols, and customs records for imported camel dairy equipment. Triangulation across these sources ensures supply-side herd counts align with demand-side consumption intensity metrics.
Historical trendline analysis of camel milk powder adoption rates, raw milk permit issuance patterns, and subscription platform growth trajectories informed projection construction. Segmentation dimensions modeled include product format, distribution channel configuration, end-user type, and application depth across nutritional products, infant formulas, functional foods, and cosmetics. CAGRs derive from curve-fitting observed adoption velocities against comparable alternative dairy market maturation patterns. Forecast inputs incorporate drought cycle frequency affecting feed costs and FDA guidance evolution timelines for alternative dairy nomenclature.
Caveats apply where state legislative movements on raw milk sales, veterinary specialist supply constraints, or FDA regulatory determinations could materially shift the outlook. Forecasts reflect documented assumptions around technology adoption rates and consumer willingness-to-pay premiums. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Global Quark and Fromage Frais Market
Dairy Products
Dry Buttermilk Market
Dairy Products
North America Whole Milk Powder Market
Dairy Products
United Kingdom Dairy Market
Dairy Products
Middle East and Africa UHT Milk Market
Dairy Products
Dairy Protein Market
Dairy Products
Goat Milk Products Market
Dairy Products
Ricotta Market
Dairy Products
Cheese Packaging Market
Dairy Products
North America Fluid Milk Market
Dairy Products
North America Dairy Market
Dairy Products
Organic Dairy Products Market
Dairy Products
Concentrated Milk Fat Market
Dairy Products
Camel Dairy Market
Dairy Products
Canada Milk Protein Market
Dairy Products
Disposable Curd Cups Market