
 North America Sour Cream Market | 2026-2036
North America Sour Cream Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sour Cream Market Analytics
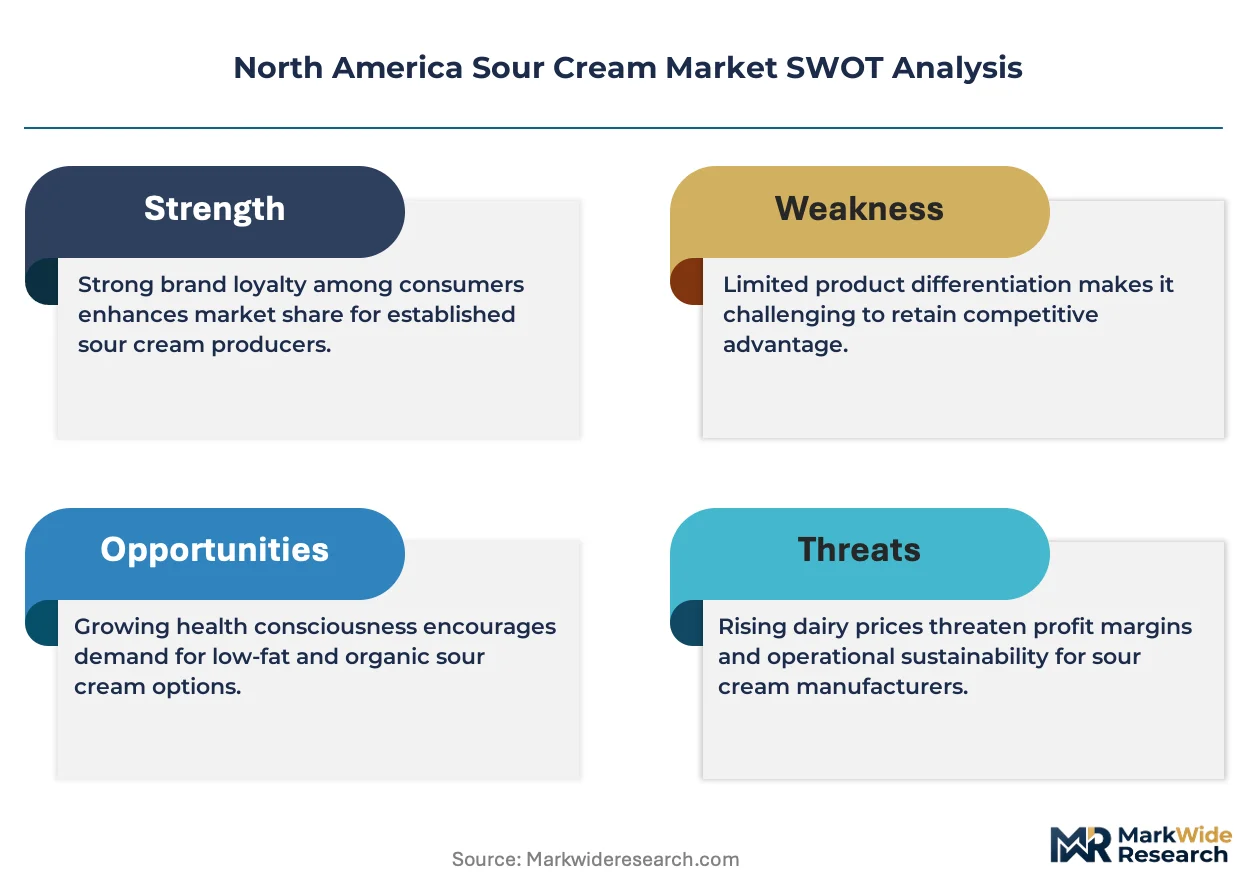
Plant-based cream alternatives is repositioning conventional sour cream economics as oat and coconut-derived formulations capture refrigerated shelf space. HP Hood LLC leverages its New England dairy infrastructure to sustain conventional production scale. Daisy Brand LLC anchors its competitive stance through squeeze-bottle packaging innovation. Saputo Inc competes across private-label and branded tiers with integrated Canadian-U.S. processing assets.
Sour cream denotes a fermented dairy product containing lactic acid bacteria cultured in pasteurized cream, typically achieving pH levels between 4.5 and 4.8 and fat content ranging from 14% to 18% for standard grades. The product functions primarily as a condiment, recipe ingredient, and flavor-delivery vehicle across prepared meals and food manufacturing. Traditional sour cream still occupies the largest revenue pool, though organic variants command premium shelf positioning and expanded distribution in natural-channel supermarkets. Foodservice end users represent the fastest-growing demand segment as Mexican and Tex-Mex restaurant chains expand their sour cream procurement volumes.
FDA standards of identity for sour cream and USDA organic certification requirements govern product composition, labeling claims, and interstate commerce eligibility across the United States. Health Canada and the Canadian Food Inspection Agency enforce parallel dairy processing regulations affecting cross-border supply chains and ingredient sourcing protocols. Stakeholders must monitor evolving plant-based labeling disputes and organic feed-cost volatility to anticipate margin compression points and portfolio rebalancing needs.
Market Dynamics
Plant-based cream alternatives are compressing conventional sour cream shelf space as oat and coconut-derived formulations capture refrigerated dairy cases across major retail banners. This substitution pressure forces incumbent processors to defend volume through packaging innovation and regional distribution density.
Growth Catalysts
- Mexican cuisine proliferation:Tex-Mex and authentic Mexican restaurant chains in the United States are expanding sour cream procurement volumes as tableside and recipe applications multiply.
- USDA organic certification:Premium shelf positioning in natural-channel supermarkets drives reformulation investments and feed-supply chain reconfiguration for certified organic variants.
- Foodservice automation:Squeeze-bottle and portion-control packaging formats reduce labor cost and waste in high-volume commercial kitchen environments.
Market Restraints
- Organic feed cost volatility:Corn and soybean price swings compress margins for certified organic sour cream processors locked into long-term supply contracts.
- Cross-border dairy concentration:Integrated Canadian-U.S. processing assets create exposure to trade policy friction and tariff-rate quota adjustments.
- Plant-based substitution:Oat and coconut cream alternatives achieve price parity in refrigerated cases, diverting trial purchases from conventional dairy.
Strategic Opportunities
- California dairy corridor expansion:Central Valley processing capacity supports West Coast foodservice and retail private-label contract growth.
- FDA plant-based labeling clarity:Pending standards-of-identity enforcement creates first-mover advantage for dairy processors with clean-label conventional positioning.
- Direct-to-foodservice distribution:Bypassing traditional distributor markups through captive delivery fleets captures margin in high-volume Mexican and Tex-Mex chain accounts.
Industry Challenges
- Fermentation technician scarcity:Specialized culture management and pH monitoring skills limit throughput expansion at regional dairy processing facilities.
- Legacy equipment retrofit costs:Cold-chain packaging lines require capital redeployment to accommodate squeeze-bottle and single-serve formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sour Cream Market |
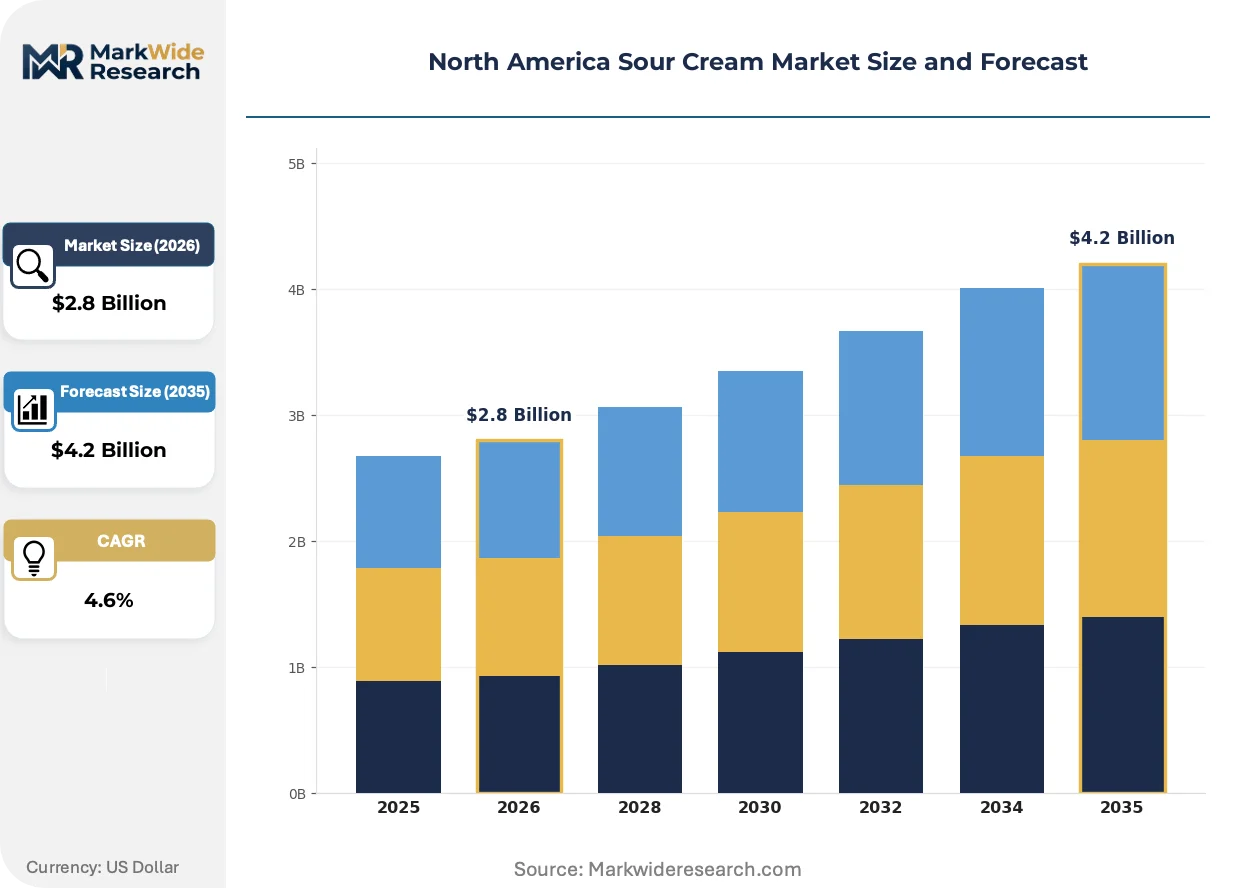
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Reduced Fat, Organic, Flavored Packaging Type: Tubs, Squeeze Bottles, Pouches, Jars Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Foodservice End User: Households, Restaurants, Cafes, Food Manufacturers |
| Companies Covered | HP Hood LLC, Dairy Farmers of America Inc, Daisy Brand LLC, Danone SA, Unilever PLC, The Kraft Heinz Company, Saputo Inc, Redwood Hill Farm & Creamery Inc, Organic Valley, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sour Cream Market Evolving Landscape
Active fermentation control systems and alternative protein formulations are redrawing competitive boundaries in cultured dairy. These shifts compress traditional processing economics while opening premium positioning pathways.
Cold-chain active fermentation monitoring is consolidating quality control protocols across North American dairy processing networks. Mid-scale regional processors are adopting IoT-enabled pH and temperature tracking to reduce batch variation and spoilage loss. This sensor deployment is consolidating supplier relationships toward integrated equipment-culture-service vendors capable of remote diagnostics.
Health Canada's parallel dairy processing regulations to FDA standards are tightening cross-border ingredient sourcing documentation requirements. Dual-jurisdiction compliance costs are rising for processors with integrated Canadian-U.S. assets. The organic certification segment bears the heaviest audit burden as feed-origin traceability rules synchronize across both regulatory regimes.
Foodservice buyers are consolidating procurement contracts toward fewer, larger suppliers with national distribution coverage. Regional dairy processors face exclusion from major Mexican and Tex-Mex chain accounts as these operators reduce vendor counts to simplify logistics. This concentration is most visible in the U.S. Northeast, where HP Hood and Daisy Brand leverage dense refrigerated distribution networks to capture multi-year supply agreements.
North America Sour Cream Market Segmentation
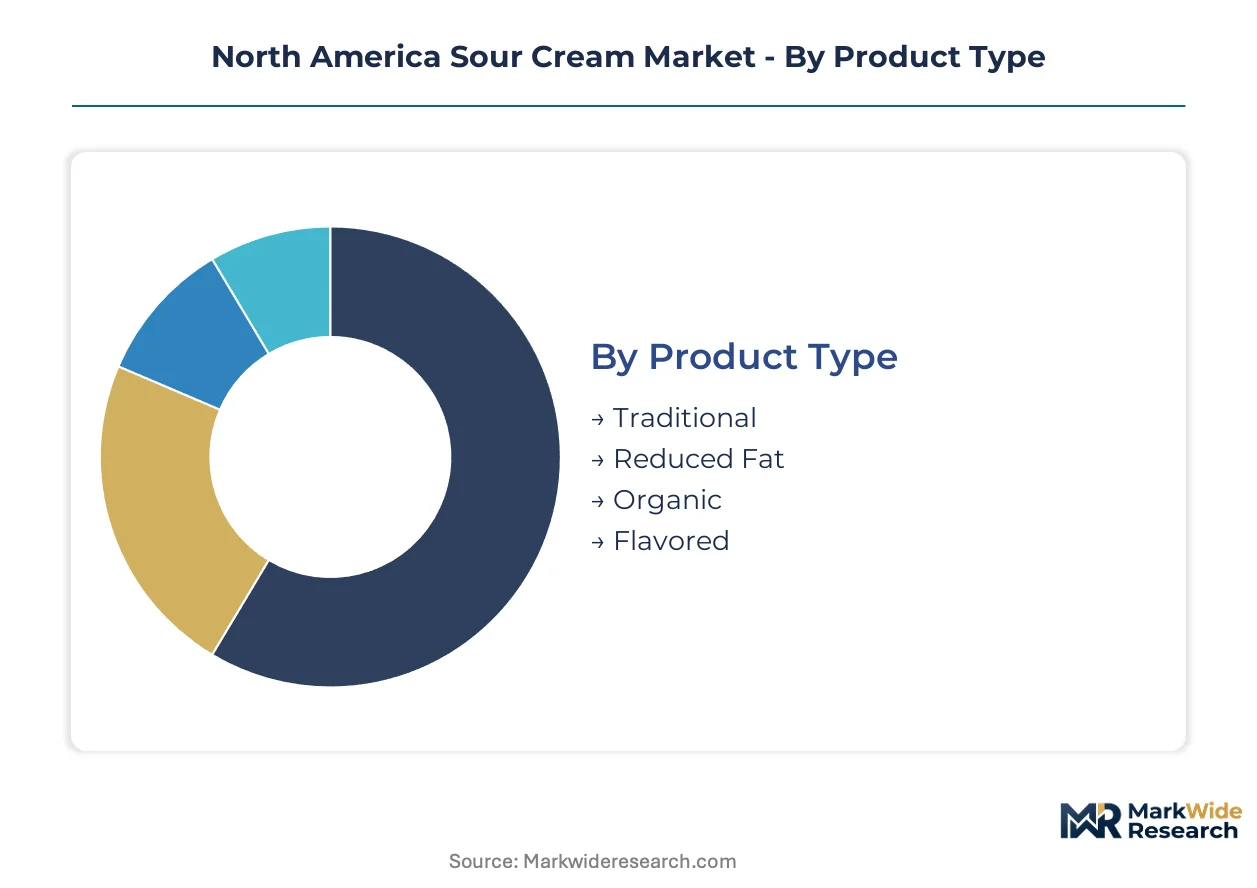
Sour cream processors configure production assets around fat-content specifications and packaging formats that determine cold-chain requirements. Segmentation choices directly govern fermentation vessel sizing, culture selection, and shelf-life targeting across North American dairy networks.
Product Type:
Capital intensity peaks in organic certification infrastructure, where feed-origin traceability and dual-jurisdiction audit compliance demand dedicated processing lines.
- Traditional:Standard-grade sour cream carries 14% to 18% milk fat and pH between 4.5 and 4.8, fermented with mesophilic lactic acid cultures. Northeast and California dairy corridors concentrate volume for retail and foodservice procurement.
- Organic:USDA-certified organic variants require certified organic cream sources and segregated processing equipment. Premium shelf positioning in natural-channel supermarkets absorbs higher feed-cost volatility and compliance audit burdens.
- Reduced Fat:Lower-fat formulations achieve 10% to 12% milk fat through cream separation adjustments before culture inoculation.
- Flavored:Onion, ranch, and jalapeño variants incorporate seasoning blends post-fermentation, requiring additional ingredient handling systems.
Most installed capacity flows through Traditional. Expansion is steepest in Organic.
Packaging Type:
Packaging selection governs line-speed economics, with single-serve formats demanding the highest capital redeployment from legacy tub-filling equipment.
- Tubs:Injection-molded polypropylene containers dominate retail shelf presence in 8-ounce to 24-ounce sizes. High-volume dairy processors in Wisconsin and New York maintain dedicated tub-filling lines with automated lidding and date-coding systems.
- Squeeze Bottles:Foodservice automation drives adoption of inverted polyethylene terephthalate bottles with silicone valve closures. Portion-control precision reduces labor cost and waste in high-volume Mexican and Tex-Mex commercial kitchens.
- Pouches:Flexible stand-up pouches target club-store multipacks and institutional foodservice bulk dispensing.
- Jars:Glass and PET jar formats serve specialty retail and private-label contract manufacturing with premium positioning requirements.
Equipment utilization rates favor Tubs for scale. Squeeze Bottles are climbing the fastest.
Distribution Channel:
Channel selection determines margin structure, with foodservice bypassing traditional distributor markups through captive delivery fleets.
- Supermarkets:Refrigerated dairy cases in conventional and natural-channel banners generate the largest revenue pool. Northeast and California retail concentration supports regional processor distribution density.
- Foodservice:Direct-to-chain procurement from Mexican and Tex-Mex restaurant operators represents the steepest expansion trajectory. Multi-year supply agreements consolidate toward processors with national refrigerated distribution coverage.
- Online Retail:E-commerce chilled fulfillment requires insulated packaging and expedited last-mile logistics.
- Convenience Stores:Smaller format locations stock limited SKUs with higher per-unit pricing and compressed shelf rotation.
Volume concentration sits with Supermarkets. Foodservice is gaining share fastest.
End User:
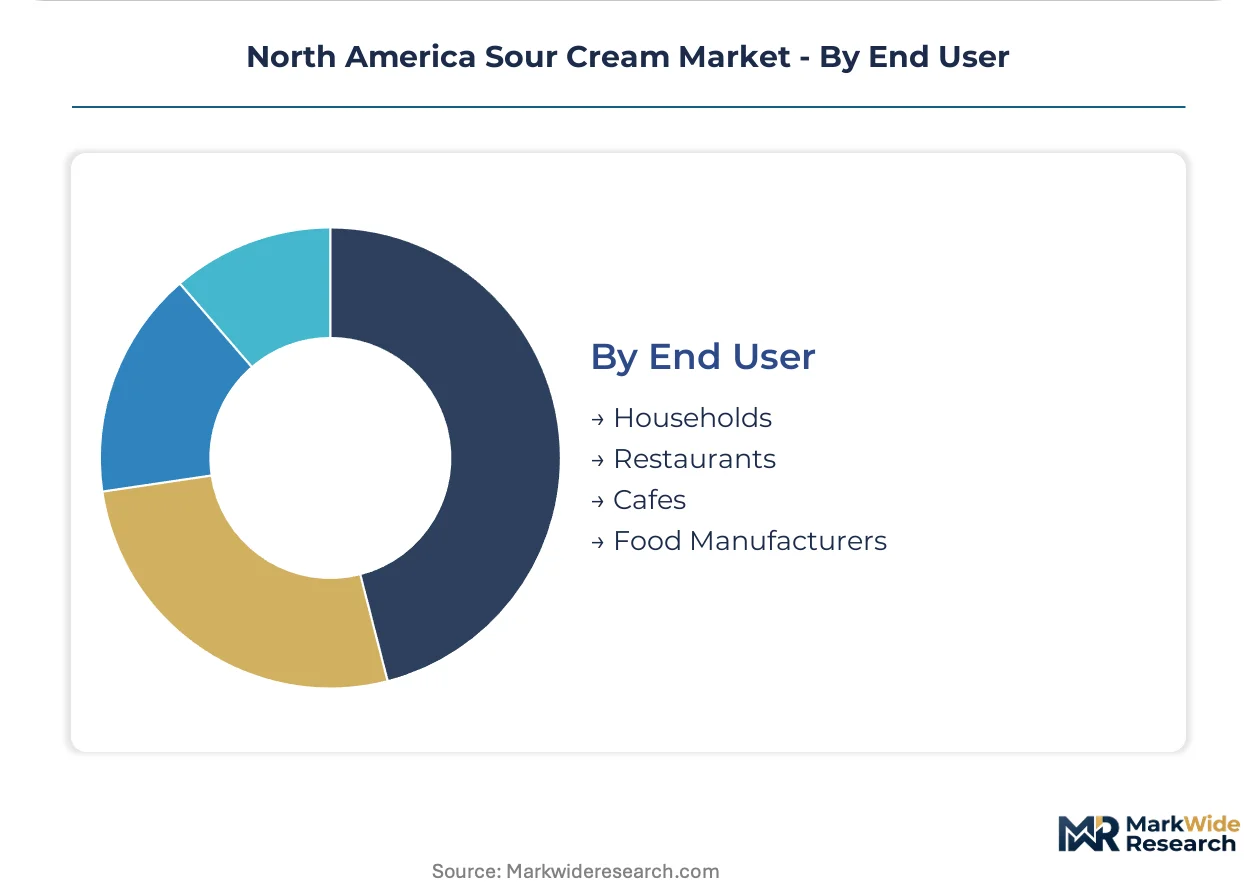
End-user segmentation shapes fermentation batch sizing, with food manufacturers demanding tanker-scale bulk delivery.
- Households:Consumer purchasing concentrates in retail channels for condiment and recipe applications. Squeeze-bottle adoption accelerates in suburban markets with younger demographic profiles.
- Restaurants:Full-service and quick-service Mexican and Tex-Mex chains drive procurement volume growth. Tableside service and kitchen prep applications multiply per-location usage rates.
- Cafes:Limited-service operators incorporate sour cream into breakfast and bakery menu items with moderate volume requirements.
- Food Manufacturers:Industrial users source bulk tanker deliveries for prepared meals, dips, and sauce formulations with extended shelf-life specifications.
Procurement scale peaks with Food Manufacturers. Restaurants are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The California dairy corridor anchors North American sour cream processing capacity, with Central Valley facilities supplying West Coast foodservice and retail networks. Northeast dairy infrastructure sustains dense refrigerated distribution into metropolitan markets. Cross-border integration with Canadian processing assets creates dual-jurisdiction regulatory exposure.
United States
Mexican and Tex-Mex restaurant chain expansion drives procurement volume growth across Texas, Arizona, and California markets. FDA standards of identity for sour cream govern product composition and interstate labeling claims. The Northeast dairy processing belt from Vermont to New York concentrates conventional production scale for retail and foodservice distribution.
Canada
Integrated cross-border supply chains serve U.S. private-label and branded contract manufacturing demand. Health Canada and the Canadian Food Inspection Agency enforce dairy processing regulations affecting ingredient sourcing documentation. Quebec and Ontario dairy cooperatives maintain fermentation capacity for North American market supply.
Mexico
Domestic consumption of crema and sour cream variants rises with quick-service restaurant penetration in Mexico City and Monterrey metro areas. Federal sanitary regulations under COFEPRIS align with FDA export requirements for cross-border dairy trade. The Bajío dairy region supplies processing inputs for both domestic use and U.S.-bound ingredient shipments.
North America Sour Cream Market Competitive Landscape
Capacity expansion dominates the current landscape as processors retrofit legacy tub-filling lines for squeeze-bottle and single-serve formats. The market structure concentrates around integrated dairy cooperatives, multinational consumer packaged goods divisions, and regional private-label specialists. Three archetypes define competitive positioning: scale-driven national distributors, organic-certified premium tier operators, and foodservice-focused packaging innovators. M&A activity and direct-to-foodservice distribution investments represent the dominant competitive moves.
Among North American dairy processors, HP Hood LLC, Daisy Brand LLC, and Saputo Inc occupy distinct archetype positions. HP Hood exemplifies regional infrastructure leverage through New England refrigerated distribution density. Daisy Brand anchors the packaging innovation vector with squeeze-bottle format adoption. Saputo represents cross-border scale integration with Canadian-U.S. processing assets spanning private-label and branded tiers.
| Leading Market Players |
|---|
| HP Hood LLC |
| Dairy Farmers of America Inc |
| Daisy Brand LLC |
| Danone SA |
| Unilever PLC |
| The Kraft Heinz Company |
| Saputo Inc |
| Redwood Hill Farm & Creamery Inc |
| Organic Valley |
| Others |
Value Network & Pricing Analysis
USDA organic certification creates a three-tier pricing structure across premium, standard, and economy levels that manifests in both shelf positioning and supply chain configurations. Premium organic variants command dedicated processing lines and segregated cold-chain logistics, while conventional grades flow through high-volume dairy corridors in the Northeast and California.
Pricing Analysis
Input-cost pass-through from organic feed markets determines margin stability across certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic from conventional and private-label economy offerings. Pricing pressure stems from oat and coconut cream alternatives achieving parity in refrigerated cases. Foodservice buyers exhibit lowest price sensitivity due to portion-control labor savings, while private-label retail procurement shows highest elasticity.
Supply Chain Analysis
Direct-to-foodservice channels handle high-volume Mexican and Tex-Mex chain demand through captive refrigerated fleets. Supply concentrates in the United States, Canada, and Mexico, with cross-border integration creating tariff exposure. Raw material dependencies center on certified organic cream, mesophilic cultures, and polypropylene packaging resins. Single-source vulnerability sits with concentrated organic feed suppliers locked into long-term contracts. Distribution runs through regional dairy cooperatives and national CPG divisions with cold-chain density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA standards of identity enforcement acts as a regulatory compounder, creating first-mover advantage for processors with clean-label conventional positioning as plant-based labeling disputes resolve.
For Market Incumbents: Extend squeeze-bottle format penetration into quick-service Mexican chains before regional processors retrofit legacy tub-filling equipment. Backward integration into certified organic feed sourcing defends margin against commodity price swings. Channel control through captive delivery fleets locks out distributor-dependent competitors. For New Entrants and Emerging Players: Begin with flavored variant development targeting suburban household segments where squeeze-bottle adoption accelerates among younger demographics. White-space exists in jalapeño and ranch seasoning blends for natural-channel supermarkets. Go-to-market through direct-to-foodservice bypass captures margin in underserved Tex-Mex independents. For Investors and Strategic Acquirers: Consolidation pressure builds where fermentation technician scarcity limits throughput expansion at regional facilities. Long-term viability favors processors with integrated Canadian-U.S. assets spanning private-label and branded tiers. Acquisition targets include organic-certified operators with segregated processing infrastructure. Watch FDA plant-based labeling clarity as inflection signal for conventional positioning recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Squeeze-Bottle Format Expansion | Foodservice automation reduces labor cost in high-volume Mexican chain kitchens. |
| Organic Certification Investment | USDA compliance opens premium shelf positioning in natural-channel supermarkets. |
| Direct-to-Foodservice Distribution | Bypassing distributor markups captures margin in consolidated chain procurement. |
| Cross-Border Asset Integration | Canadian-U.S. processing networks hedge regional supply disruptions. |
| Active Fermentation Monitoring | IoT-enabled pH tracking reduces batch variation and spoilage loss. |
Research Methodology
Multiple input streams — fermentation technology vendors, dairy cooperative procurement directors, foodservice chain supply managers, and retail category buyers — were reconciled against USDA organic certification databases, FDA standards of identity filings, and Nielsen retail audit data. Bottom-up volume estimates from processor capacity utilization were cross-referenced with top-down expenditure flows from foodservice procurement databases.
Historical volume trajectories were cross-referenced against panel input from dairy industry executives to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include product type, packaging format, distribution channel, and end-user application. CAGRs were derived from regression analysis of organic certification penetration rates and foodservice automation adoption curves, with cross-border trade flow data and feed-cost volatility indices serving as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including sudden tariff-rate quota adjustments, plant-based labeling litigation outcomes, and organic feed supply shocks from climate events. Forecasts reflect assumptions about Mexican cuisine proliferation and squeeze-bottle adoption velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Gruyere Market
Dairy Products
Whole Milk Powder Market
Dairy Products
Non-Fat Milk Market
Dairy Products
Cheese Crumbles Market
Dairy Products
GCC Cheese Market
Dairy Products
Global Reduced Fat Butter Market
Dairy Products
US Yogurt and Probiotic Drink Market
Dairy Products
United States Casein Market
Dairy Products
Colombia Dairy Market
Dairy Products
Fermented Milk Products Market
Dairy Products
Sheep Milk Cheese Market
Dairy Products
Butter Concentrate Market
Dairy Products
Organic Milk Protein Market
Dairy Products
Low-Fat Sour Cream Market
Dairy Products
Low Fat Cheese Market
Dairy Products
Dairy Carton Market