
 South America Yogurt Market | 2026-2036
South America Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
South America Yogurt Market Analytics
Health-conscious urban consumers is unwinding the historical dominance of price-sensitive household bulk purchasing in South America's yogurt trade. Danone SA leverages its probiotic research infrastructure to command premium shelf positioning in Brazilian supermarkets. Nestlé SA sustains manufacturing scale through multi-category dairy complexes in São Paulo state. Grupo Lala anchors its competitiveness via backward integration into raw milk collection across Mexican and Central American dairy belts that feed southbound distribution.
Yogurt is a fermented milk product manufactured through bacterial culture conversion of lactose to lactic acid, yielding a semi-solid food with titratable acidity typically ranging from 0.9% to 1.2% and live culture counts exceeding 10^6 CFU per gram at production. Greek yogurt commands disproportionate margin pools due to its strained manufacturing process and protein concentration, while organic yogurt captures fastest volume growth among health-store and online retail channels. Plastic cups retain dominant packaging share in supermarket and convenience store environments, though pouch formats gain traction in on-the-go consumption occasions.
ANVISA governs probiotic health claims and dairy safety standards in Brazil, while Argentina's national food regulator enforces comparable labeling and pathogen controls that shape cross-border product standardization. Chile's front-of-pack warning label law pressures reformulation toward reduced sugar content, altering flavor development pipelines across vanilla and strawberry segments. Stakeholders must monitor evolving Mercosur harmonization talks and decide whether to pursue unified regional formulations or maintain country-specific product portfolios.
Market Dynamics
ANVISA's probiotic health claim regulations and Chile's front-of-pack sugar warning labels are compressing formulation flexibility while accelerating clean-label R&D investment across Brazilian and Argentine manufacturing facilities.
Growth Catalysts
- Functional ingredient premiums:Probiotic strain differentiation commands shelf space in São Paulo and Rio de Janeiro supermarkets. Manufacturers leverage live culture density as a positioning tool.
- Cold-chain infrastructure expansion:Refrigerated logistics networks in Colombia's Andean corridor reduce spoilage losses and extend distribution reach into secondary cities.
- ANVISA nutrition transparency mandates:Standardized labeling requirements eliminate information asymmetry and accelerate consumer education on fermented dairy benefits.
Market Restraints
- Raw milk input volatility:Argentine dairy belt weather variability and Brazilian feed cost fluctuations compress processor margins unpredictably.
- Supply concentration in São Paulo state:Multi-category dairy complex dominance creates bottleneck risk for national distribution.
- Substitution by plant-based alternatives:Oat and coconut yogurt formats capture lactose-intolerant and vegan consumer segments in urban centers.
Strategic Opportunities
- Colombian secondary city penetration:Medellín and Cali retail modernization lags behind Bogotá, leaving white space for premium format introduction.
- Pouch format channel innovation:On-the-go consumption occasions in Buenos Aires public transit corridors favor flexible packaging over rigid cups.
- Chilean sugar reduction tailwind:Front-of-pack warning label law creates first-mover advantage for reformulated low-sugar vanilla and strawberry lines.
Industry Challenges
- Microbiology talent scarcity:Live culture strain management and fermentation process control require specialized dairy science expertise concentrated in southern Brazil universities.
- Cross-border Mercosur harmonization delays:Divergent probiotic claim standards between Brazilian and Argentine regulators force dual formulation strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Yogurt Market |
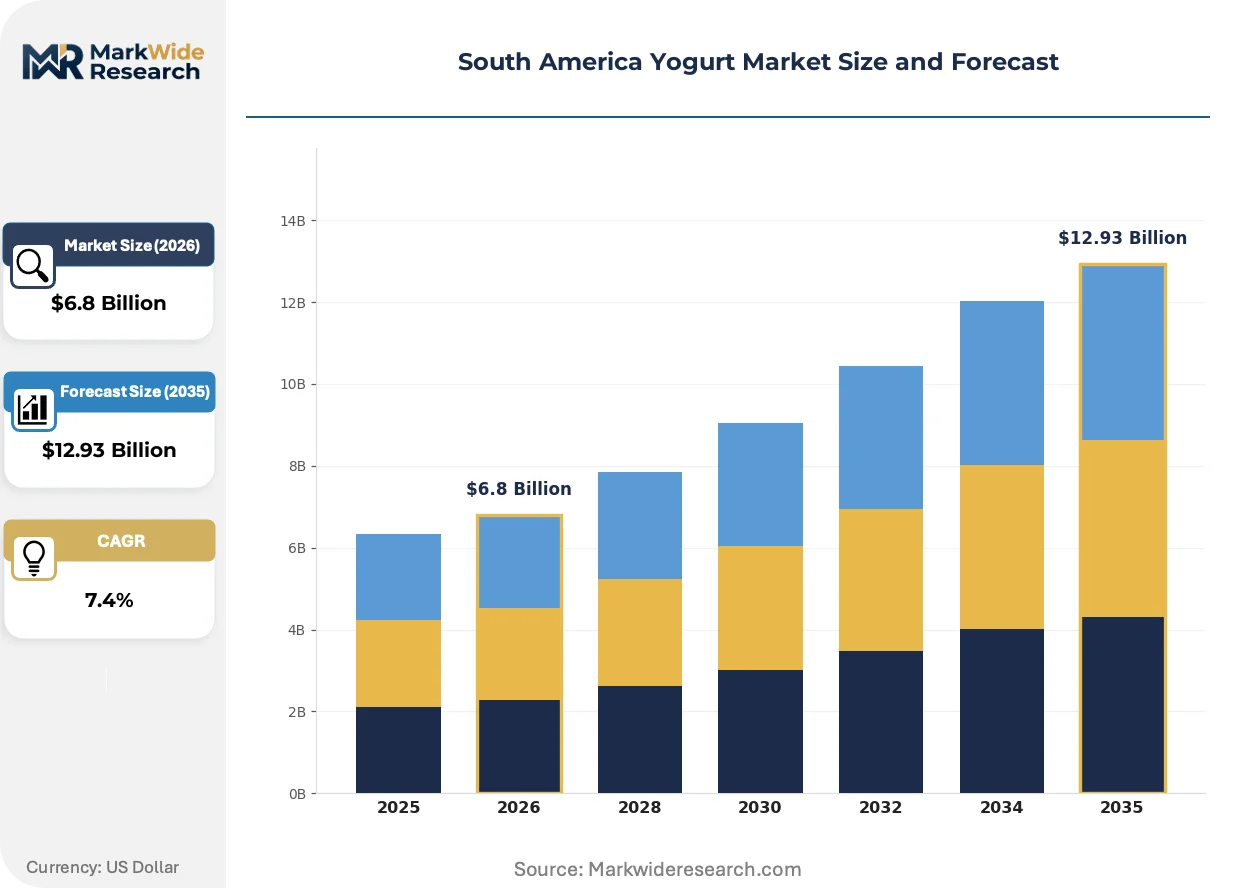
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Greek, Low-Fat, Organic Packaging Type: Plastic Cups, Glass Jars, Tetra Packs, Pouches Flavor: Vanilla, Strawberry, Blueberry, Plain Distribution Channel: Supermarkets, Health Stores, Online Retailers, Convenience Stores |
| Companies Covered | Grupo Lala, Gloria, Danone SA, Chobani, LLC, Yakult Honsha Co., Ltd., Nestlé SA, Alpina, General Mills, Inc., Lactalis Group, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Yogurt Market Evolving Landscape
Strained manufacturing processes and live culture stabilization technologies are redefining margin architecture, while regulatory pressure on sugar content and packaging sustainability forces concurrent reformulation across multiple attribute dimensions.
Aseptic filling technology with extended shelf-life capability is supplanting traditional cold-chain-dependent distribution in Colombia's mountainous interior regions. Mid-sized processors in Bogotá are adopting tetra-pak alternatives to reach convenience stores lacking reliable refrigeration. This shift compresses the historical advantage of vertically integrated dairy giants with captive cold-chain assets.
Chile's Law of Food Labeling and Advertising mandates front-of-pack octagonal warning labels for products exceeding sugar, sodium, or calorie thresholds. Argentine regulators monitor this framework for potential adoption, pressuring formulation teams to recalibrate sweetness profiles. Strawberry and vanilla segments face disproportionate impact given their historical reliance on added sugars for palatability.
Urban Brazilian households are consolidating yogurt purchases into smaller, more frequent transactions through convenience store channels. Traditional weekly supermarket bulk buying erodes as São Paulo and Rio de Janeiro consumers prioritize freshness and variety rotation. This pattern compresses inventory cycles and rewards processors with agile production scheduling and rapid flavor pipeline turnover.
South America Yogurt Market Segmentation
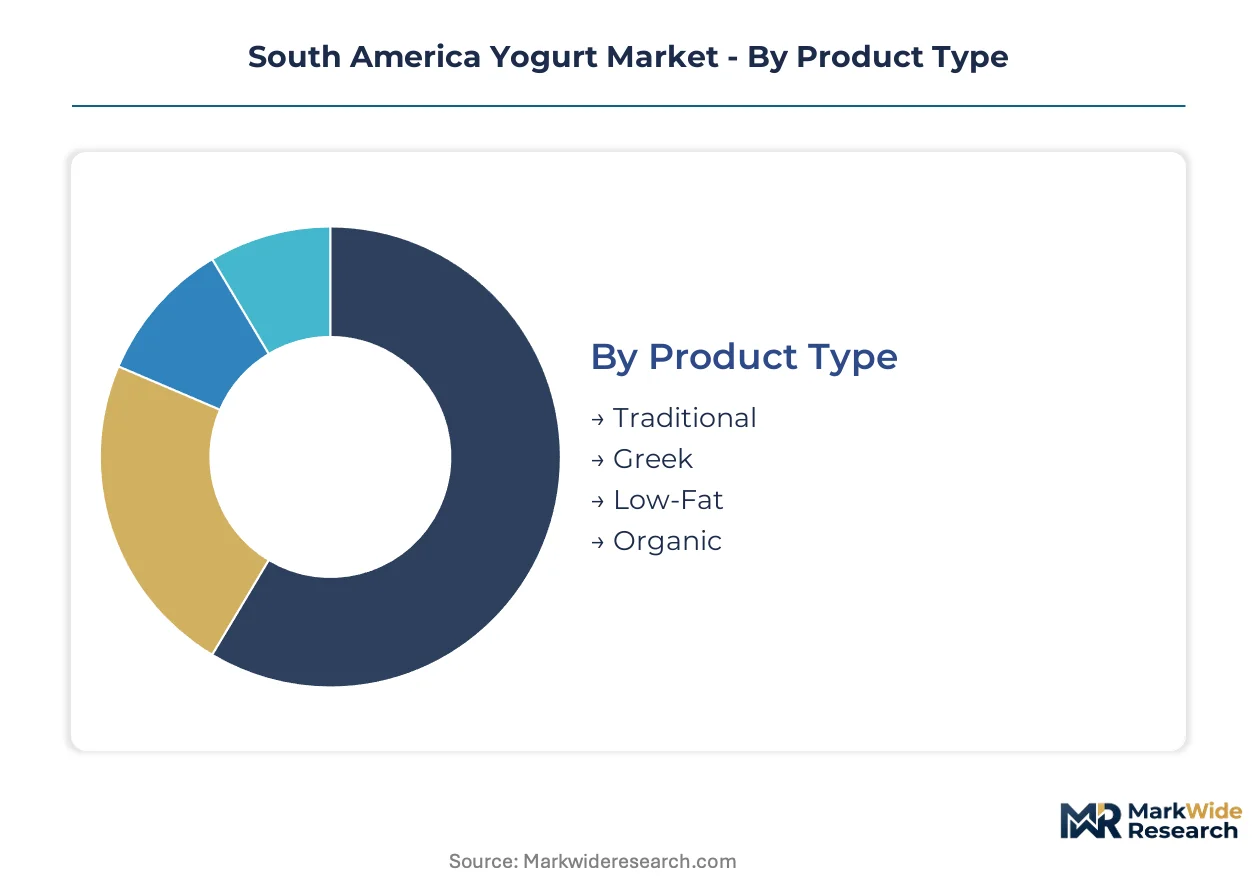
Yogurt segmentation in South America maps directly onto purchasing power gradients and retail infrastructure maturity. Product and packaging choices reveal whether consumers prioritize protein density, convenience portability, or clean-label positioning.
Product Type:
Greek and organic variants command the widest margin spreads, while traditional formats anchor volume throughput in price-sensitive segments.
- Traditional:Standard fermentation without straining yields 0.9% to 1.2% titratable acidity and live culture counts above 10^6 CFU per gram. Brazilian southeastern supermarkets move the highest tonnage of this format through multi-pack promotions targeting household bulk purchasing.
- Greek:Strained manufacturing removes whey to concentrate protein content, creating texture differentiation that supports premium shelf positioning. São Paulo and Rio de Janeiro health-conscious urban consumers drive uptake despite price multiples over standard yogurt.
- Low-Fat:Reduced butterfat formulations appeal to weight-management segments in Colombian Andean cities where altitude-adjusted dietary preferences favor lighter dairy.
- Organic:Certified milk sourcing and live culture guarantees capture fastest expansion among Argentine health-store channels and Brazilian online retailers.
The dominant share belongs to Traditional, while Organic is closing the gap fastest.
Packaging Type:
Cold-chain reliability and retail format penetration dictate which packaging configurations win shelf space in each geography.
- Plastic Cups:Dominant format in Brazilian and Argentine supermarket dairy aisles, offering unit visibility and stackability for high-velocity SKUs. Injection-molded polypropylene withstands refrigeration cycling but faces sustainability scrutiny from ANVISA packaging directives.
- Pouches:Flexible films with spout closures enable on-the-go consumption in Buenos Aires public transit corridors and São Paulo commuter rail networks. Bogotá mid-sized processors favor this format for convenience store penetration where refrigeration is intermittent.
- Glass Jars:Premium positioning vehicle for organic and artisanal lines in Argentine health stores and Chilean specialty retailers.
- Tetra Packs:Aseptic filling technology extends shelf life without continuous cold chain, opening distribution into Colombia's mountainous interior and secondary cities with unreliable refrigeration infrastructure.
Plastic Cups retain volume leadership, though Pouches are expanding most quickly into transit-oriented consumption occasions.
Flavor:
Chile's front-of-pack sugar warning labels are forcing reformulation across historically sweet-dominant segments.
- Strawberry:Highest historical velocity in Brazilian supermarkets, now facing reformulation pressure as added sugar content triggers regulatory thresholds. Manufacturers are recalibrating sweetness profiles with natural fruit concentrates and stevia blends.
- Plain:Unsweetened base for home customization and cooking applications, gaining traction among Colombian health-conscious consumers and Argentine probiotic-focused buyers. Clean label positioning avoids Chilean warning label triggers entirely.
- Vanilla:Traditional flavor development relies on added sugars for palatability, creating vulnerability to sugar reduction mandates across Mercosur harmonization discussions.
- Blueberry:Superfruit positioning supports premium pricing in health-store channels, though supply chain concentration for fruit concentrates creates input cost volatility.
Strawberry maintains the largest share, yet Plain is gaining ground fastest as regulatory pressure intensifies.
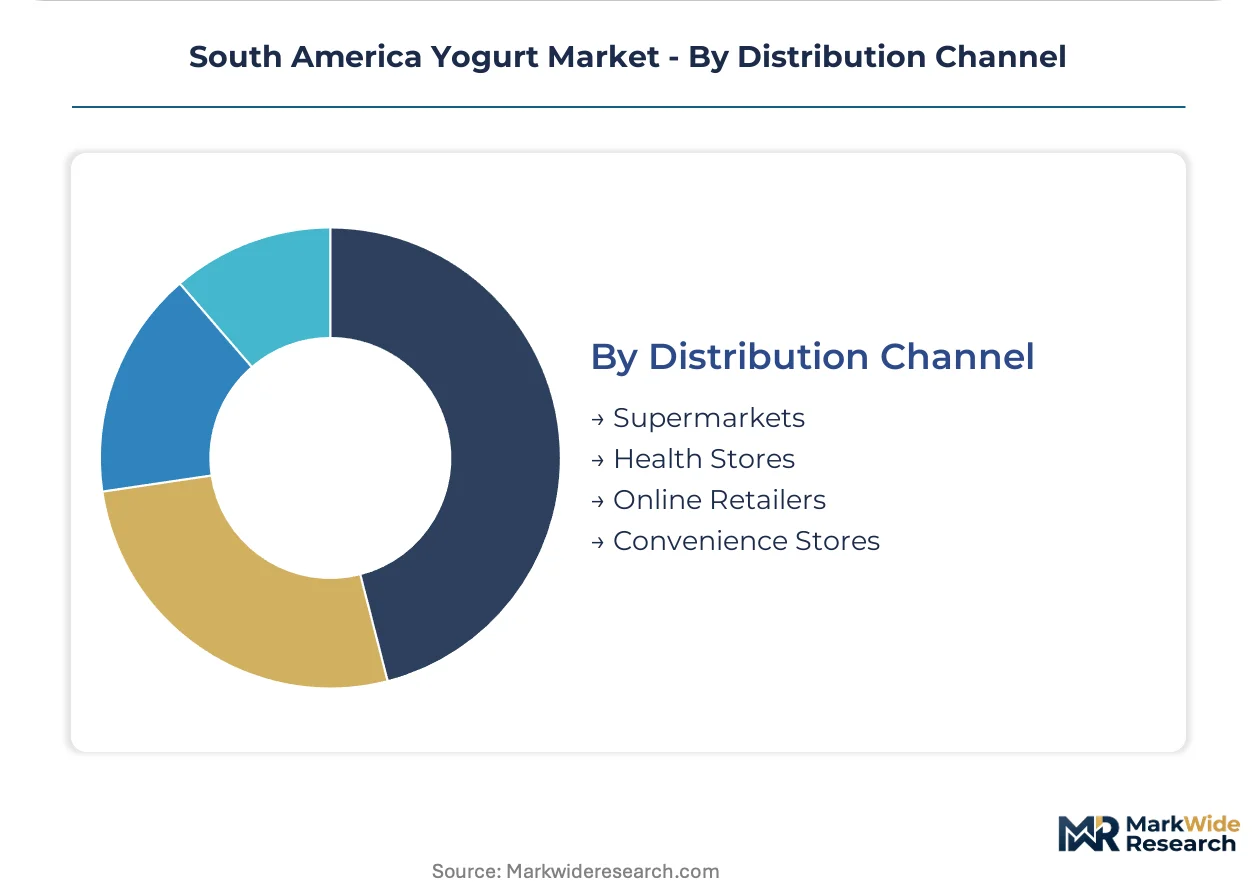
Distribution Channel:
Channel selection determines whether processors compete on margin compression or brand premiumization.
- Supermarkets:Modern retail penetration concentrates in Brazil's southeastern metropolitan corridor, where multi-category dairy complexes and cold-chain infrastructure overlap. Category management fees and slotting allowances compress net margins for smaller processors.
- Online Retailers:Direct-to-home delivery of probiotic and organic formats bypasses traditional retail markups, expanding fastest among São Paulo and Buenos Aires urban professionals with subscription purchasing patterns.
- Health Stores:Specialty retail in Argentine and Colombian urban centers curates organic and functional yogurt assortments, offering premium positioning but limited geographic scale.
- Convenience Stores:Smaller transaction sizes and higher purchase frequency in Brazilian metropolitan areas reward processors with agile production scheduling and rapid flavor pipeline turnover.
Supermarkets dominate transaction volume, while Online Retailers are climbing the fastest as logistics networks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious urban households concentrate most densely in Brazil's southeastern metropolitan corridor, where modern retail penetration and dairy processing clusters overlap. Argentine consumers prioritize probiotic functionality and clean-label positioning, while Colombian demand concentrates in Andean cities with expanding cold-chain infrastructure. Chilean regulatory pressure on sugar content is reshaping formulation priorities across southern cone markets.
Brazil
São Paulo and Rio de Janeiro health-conscious urban consumers drive uptake of functional and probiotic yogurt formats through convenience store channels. ANVISA nutrition labeling mandates eliminate information asymmetry and accelerate consumer education on fermented dairy benefits. The southeastern metropolitan corridor hosts multi-category dairy complexes where cold-chain infrastructure overlaps with modern retail penetration.
Argentina
Buenos Aires commuters favor pouch formats for on-the-go consumption in public transit corridors, displacing traditional weekly supermarket bulk purchasing. The national food regulator enforces labeling and pathogen controls that shape cross-border product standardization with Brazilian standards. Dairy belt weather variability around Santa Fe and Córdoba creates raw milk input volatility that compresses processor margins unpredictably.
Colombia
Medellín and Cali retail modernization lags behind Bogotá, leaving white space for premium format introduction in secondary cities. Refrigerated logistics networks in the Andean corridor reduce spoilage losses and extend distribution reach beyond the capital. Mid-sized processors in Bogotá adopt aseptic filling technology to reach convenience stores lacking reliable refrigeration infrastructure.
Chile
Front-of-pack octagonal warning labels for products exceeding sugar thresholds pressure reformulation toward reduced sugar content in vanilla and strawberry segments. Argentine regulators monitor this framework for potential adoption, altering flavor development pipelines across Mercosur markets. Santiago specialty retailers curate organic and artisanal assortments in glass jar formats for premium positioning.
South America Yogurt Market Competitive Landscape
Player mix skews toward multinational dairy conglomerates with captive probiotic research infrastructure and regional Latin American dairy groups with backward integration into raw milk collection. Market structure consolidates around three strategic archetypes: science-driven functional specialists, scale-optimized multi-category processors, and vertically integrated regional dairy cooperatives. Dominant competitive moves include portfolio diversification into plant-adjacent formats and geographic expansion through cold-chain infrastructure partnerships.
Within the multinational tier, Danone SA and Nestlé SA exemplify science-driven and scale-optimized archetypes respectively, while Grupo Lala anchors the vertically integrated regional cooperative model. Danone SA leverages probiotic research infrastructure to command premium shelf positioning. Nestlé SA sustains manufacturing scale through multi-category dairy complexes. Grupo Lala secures competitiveness via upstream control over raw milk collection across Mexican and Central American dairy belts feeding southbound distribution.
| Leading Market Players |
|---|
| Grupo Lala |
| Gloria |
| Danone SA |
| Chobani, LLC |
| Yakult Honsha Co., Ltd. |
| Nestlé SA |
| Alpina |
| General Mills, Inc. |
| Lactalis Group |
| Others |
Value Network & Pricing Analysis
Aseptic filling technology substituting for cold-chain-dependent distribution is compressing the historical advantage of vertically integrated dairy giants with captive refrigeration assets while simultaneously opening secondary city markets to mid-sized processors with leaner cost structures. This substitution dynamic redraws supply geography toward Colombia's mountainous interior and reshapes pricing economics by decoupling shelf-life premiums from infrastructure ownership.
Pricing Analysis
Cost-plus contracts indexed to Brazilian feed grain futures and Argentine dairy belt spot milk prices govern processor-supplier relationships. Three-tier pricing structure across premium Greek yogurt, standard traditional formats, and economy private-label tiers separates protein concentration levels and live culture guarantees. Pricing pressure stems from oat and coconut yogurt substitution eroding lactose-intolerant consumer willingness to pay dairy premiums. Price-sensitive household bulk purchasers in Brazilian supermarkets exhibit highest elasticity, while probiotic-focused urban professionals in São Paulo show lowest sensitivity.
Supply Chain Analysis
Inventory cycles compress as São Paulo and Rio de Janeiro consumers shift toward smaller, more frequent convenience store transactions. Supply concentrates in Brazil's southeastern dairy complexes, Argentina's Santa Fe-Córdoba belt, and Colombia's Bogotá processing cluster. Raw milk inputs, probiotic culture strains, and fruit concentrate flavorings anchor cost structures. Single-source vulnerability around live culture strain management creates bottleneck risk. Distribution runs through modern retail supermarkets in metropolitan corridors, with refrigerated logistics extending into secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America yogurt market sits at a platform-economics inflection where cold-chain infrastructure partnerships and aseptic technology interoperability are redefining competitive moats beyond manufacturing scale alone.
For Market Incumbents: Compound defensive positioning through captive probiotic research infrastructure and multi-category dairy complex consolidation in São Paulo state. Backward integration into raw milk collection across Brazilian and Argentine dairy belts counters margin compression from feed cost volatility. Channel control through direct convenience store distribution partnerships preserves shelf access against mid-sized processor encroachment. For New Entrants and Emerging Players: ANVISA organic certification fast-tracks premium positioning in Brazilian online retail channels with lower slotting allowance barriers than supermarket entry. Colombian secondary cities—Medellín and Cali—offer white-space penetration with retail modernization lagging Bogotá. Pouch format innovation targeting Buenos Aires public transit corridors provides differentiated go-to-market positioning against cup-format incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated regional cooperatives with upstream milk collection control and downstream cold-chain partnerships across Mercosur markets. Long-term viability hinges on reformulation capabilities for sugar-reduced lines under Chilean warning label precedent spreading through southern cone harmonization. Watch ANVISA probiotic health claim standardization talks as signal for portfolio rationalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Filling Technology Adoption | Extends shelf life without continuous refrigeration, opening Colombia's interior distribution. |
| Probiotic Strain Patent Portfolio Expansion | Commands premium shelf positioning under ANVISA health claim differentiation rules. |
| Secondary City Cold-Chain Partnership | Reduces spoilage losses in Medellín and Cali, enabling premium format introduction. |
| Sugar Reduction Reformulation Program | Preempts Chilean warning label triggers and potential Argentine regulatory adoption. |
| Pouch Format Manufacturing Line Investment | Captures on-the-go consumption in São Paulo commuter rail and Buenos Aires transit corridors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with dairy processing executives, ANVISA regulatory affairs specialists, supermarket category buyers, and cold-chain logistics operators; and secondary validation through Brazilian customs dairy trade records, ANVISA probiotic registration filings, Nielsen retail audit data for South American markets, and SEC 10-K disclosures from multinational dairy conglomerates. Bottom-up volume modeling triangulated against top-down market sizing from production capacity and per-capita consumption benchmarks.
Across the analysis window, the forecasting framework modeled yogurt demand through product type segmentation, packaging format evolution, flavor profile reformulation dynamics, and distribution channel migration patterns. CAGRs were derived from elasticity-adjusted consumption projections and price trajectory assumptions. Forecast inputs incorporated cold-chain infrastructure buildout timelines, ANVISA labeling mandate compliance costs, and Chilean sugar warning label reformulation expenditure patterns.
The analysis sits within stated boundaries; outcomes outside sustained cold-chain investment, stable feed grain pricing, and Mercosur regulatory harmonization progress would require recalibration. Forecasts reflect documented assumptions around urbanization rates and health-conscious consumer cohort expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
Yogurt Drink Market
Dairy Products
North America Organic Dairy Market
Dairy Products
Dry Whole Milk Powder Market
Dairy Products
Butter and Margarine Market
Dairy Products
Kuwait Dairy Products Market
Dairy Products
Milk Retentate Market
Dairy Products
Dairy Concentrates Market
Dairy Products
Disposable Curd Cups Market
Dairy Products
Low Fat Cream Cheese Nutrition Market
Dairy Products
Recombined Milk Products Market
Dairy Products
Evaporated Filled Milk Market
Dairy Products
A2 Milk Market
Dairy Products
GCC Fresh Milk Market
Dairy Products
Green Tea Butter Market
Dairy Products
Milk Fat Fractions Market