
 Low-Fat Sour Cream Market | 2026-2036
Low-Fat Sour Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Fat Sour Cream Market Analytics
Probiotic-enhanced and live-culture specifications is rotating into the premium tier of low-fat sour cream, compelling processors to upgrade fermentation protocols and label claims. Daisy Brand LLC leverages its national refrigerated distribution network to sustain broad retail availability. HP Hood LLC anchors its position in the Northeast through dedicated dairy processing infrastructure. Organic Valley differentiates via certified organic milk sourcing that commands shelf-space premiums in specialty retail channels.
Low-fat sour cream is a cultured dairy product manufactured from milk cream with reduced butterfat content, typically achieved through centrifugal separation before standardization and mesophilic bacterial fermentation at temperatures between 20°C and 30°C. Its primary commercial purpose centers on delivering tangy flavor and creamy texture as a topping, ingredient, or base for dips and dressings while meeting fat-reduction targets. The organic product type segment carries disproportionate margin pools as ingredient traceability commands retail price premiums. Single-serve cups within packaging type are expanding fastest through food service and convenience-oriented retail formats. Supermarkets within distribution channel dominate volume throughput but face share erosion to online retailers as subscription grocery models mature.
FDA standards of identity for sour cream and USDA organic certification requirements shape formulation parameters and label compliance costs for domestic manufacturers. State-level dairy grading programs in Wisconsin and California add secondary quality verification layers that influence processor location decisions. Stakeholders must monitor evolving clean-label enforcement thresholds and fermentation process disclosure rules that could reshape competitive positioning in premium private-label contracts.
Market Dynamics
Clean-label mandates from FDA and USDA are forcing dairy processors to strip stabilizers and artificial additives from low-fat sour cream formulations, compressing formulation flexibility while elevating production costs across the supply base.
Growth Catalysts
- Live-culture premiumization:Mesophilic fermentation protocols with documented CFU counts are commanding shelf-space premiums in specialty retail channels as consumers prioritize digestive health claims.
- Food service menu expansion:Quick-service chains are embedding low-fat sour cream into bowl formats and limited-time offers, pulling volume through commercial kitchens at accelerated clip.
- Centrifugal separation advances:Inline butterfat standardization systems are reducing yield loss during cream reduction, improving processor margins on reduced-fat SKUs.
Market Restraints
- Cream input volatility:Fluid milk price swings at the Chicago Mercantile Exchange transmit directly to low-fat sour cream cost structures, compressing margin predictability for regional processors.
- Fermentation capacity concentration:Cultured dairy production clusters disproportionately in Wisconsin and California, creating geographic supply risk during climate-driven milk production disruptions.
- Plant-based substitution:Cashew and oat-based sour cream alternatives are capturing label-conscious consumers in coastal metropolitan markets, eroding household penetration of dairy-based reduced-fat options.
Strategic Opportunities
- Single-serve food service formats:Portion-control cups are expanding placement in college dining and corporate cafeteria channels where waste reduction drives procurement decisions.
- Organic certification tailwind:USDA organic standards are creating price-insulated demand pools as retailers allocate dedicated refrigerated sets to certified low-fat cultured dairy.
- Probiotic strain differentiation:Lactobacillus acidophilus and Bifidobacterium fortification is opening clinical-nutrition adjacent channels including hospital food service and senior living facilities.
Industry Challenges
- Clean-label reformulation timelines:Removing carrageenan and modified food starch while maintaining viscosity requires 12-18 month sensory validation cycles, delaying product launches.
- Cold-chain integrity maintenance:Live-culture specifications demand unbroken refrigeration from fermentation through retail, elevating logistics costs and spoilage risk in last-mile distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Fat Sour Cream Market |
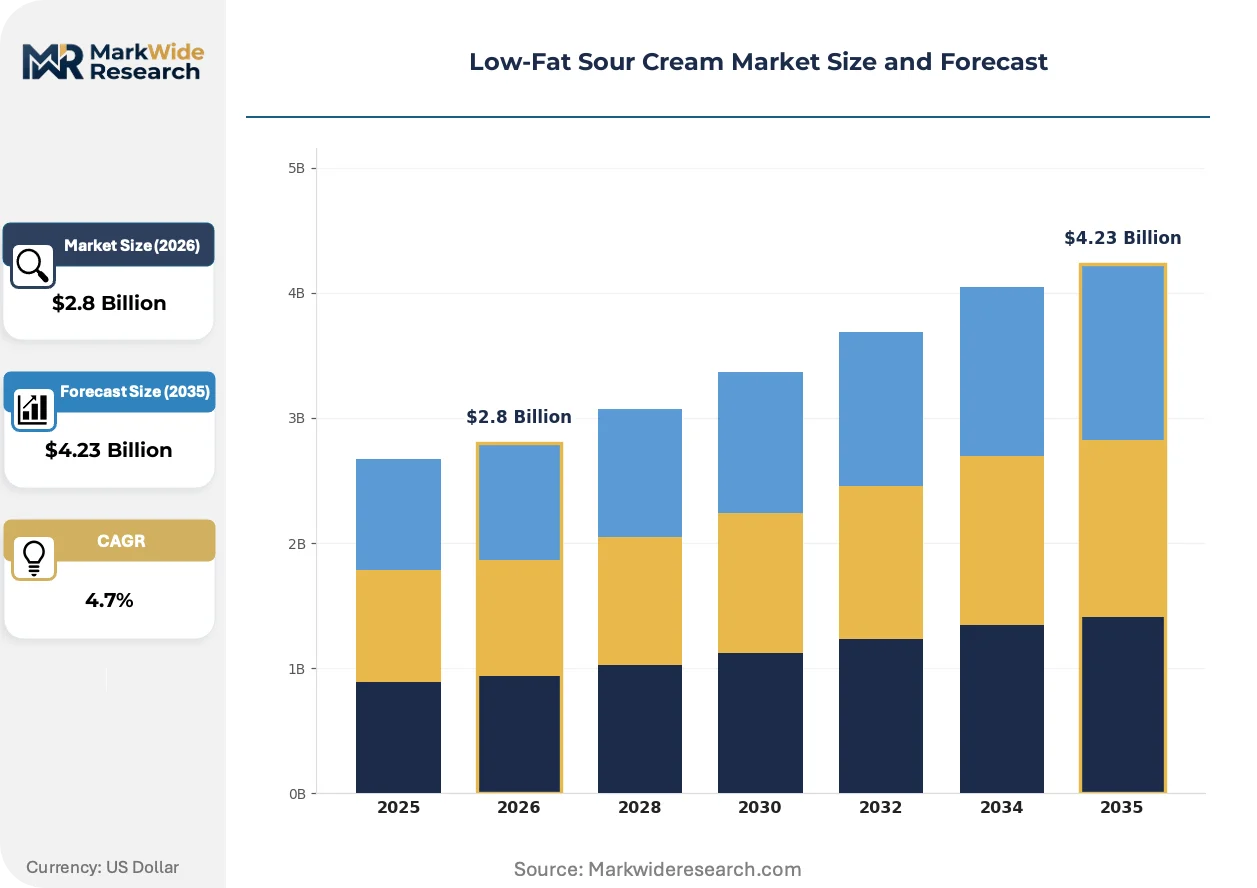
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Organic, Flavored, Dairy-Free Packaging Type: Tubs, Pouches, Single-Serve Cups, Squeeze Bottles End User: Household, Food Service, Retail, Bakeries Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Stores |
| Companies Covered | Daisy Brand LLC, HP Hood LLC, Dairy Farmers of America, Arla Foods amba, Lactalis Heritage Dairy, Land O'Lakes, Organic Valley, Prairie Farms Dairy, Green Valley Creamery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Fat Sour Cream Market Evolving Landscape
Bioprocess engineering and regulatory disclosure requirements are converging to reshape how low-fat sour cream is formulated, labeled, and positioned across retail and food service channels.
High-pressure processing is supplanting traditional thermal pasteurization for live-culture retention in premium low-fat sour cream lines. Specialty retailers and natural grocery chains are adopting HPP-treated SKUs at accelerating rates. This non-thermal intervention is supplanting conventional heat treatment as the gold standard for probiotic viability claims, compressing the addressable market for standard pasteurized alternatives.
FDA standards of identity modernization efforts are tightening allowable ingredient declarations for sour cream and sour cream-type products. Processors face reformulation costs to eliminate non-dairy fat sources and artificial thickeners from standardized products. Organic and clean-label private-label contracts are absorbing disproportionate compliance investment as retailers anticipate enforcement threshold elevation.
Subscription grocery models are rotating refrigerated dairy purchasing from weekly store trips to consolidated direct-to-consumer delivery. Urban households in dense metropolitan corridors are shifting volume toward curated box services that bundle low-fat sour cream with complementary produce and protein. This channel migration is most visible in the Northeast and Pacific Northwest where cold-chain logistics density supports viable unit economics.
Low-Fat Sour Cream Market Segmentation
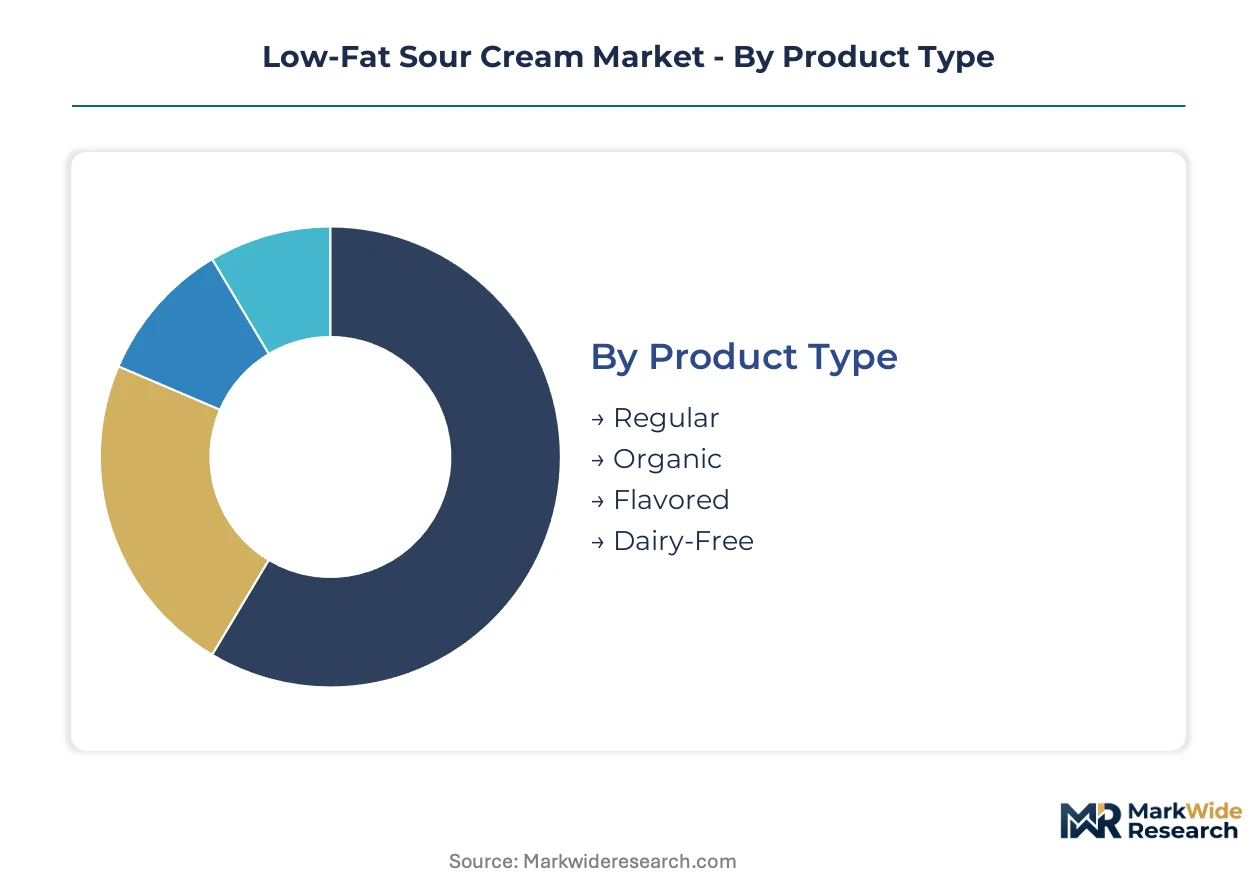
Low-fat sour cream segmentation reveals how substitution pressures from plant-based alternatives and clean-label demands are reshaping category priorities across formulation, packaging, and channel strategies. Understanding which segments face the strongest competitive threat from oat and cashew-based alternatives informs resource allocation and innovation pipelines.
Product Type:
Organic and dairy-free formulations face the most acute substitution pressure from cultured coconut and oat sour cream alternatives, while conventional reduced-fat variants defend share through price positioning and food service volume contracts.
- Regular:Standardized formulations with 50% fat reduction versus full-fat sour cream anchor food service procurement through cost efficiency and recipe consistency. Demand concentrates in quick-service bowl concepts and institutional catering where unit economics override premium positioning.
- Organic:Certified organic milk sourcing with full traceability documentation commands refrigerated shelf-space premiums in specialty retail channels. USDA organic compliance creates price-insulated demand pools as retailers allocate dedicated sets to certified cultured dairy.
- Flavored:Ranch, onion, and herb-infused variants target dip and dressing applications with convenience-oriented positioning.
- Dairy-Free:Cultured plant-based alternatives using coconut, oat, or almond bases compete directly with reduced-fat dairy sour cream in coastal metropolitan markets.
Regular retains volume leadership; dairy-free holds the steepest expansion curve.
Packaging Type:
Cost tier differentiation separates bulk food service formats from premium convenience-oriented packaging, with single-serve units capturing disproportionate margin per ounce through portion-control value propositions.
- Single-Serve Cups:Portion-controlled 2-4 ounce containers reduce waste in college dining, corporate cafeterias, and healthcare food service where procurement prioritizes inventory control and hygiene protocols. Expansion accelerates through grab-and-go retail formats and meal-kit bundling.
- Tubs:Multi-serve plastic containers dominate household replenishment cycles and ingredient-scale food service purchasing through cost-per-ounce efficiency. Midwest and Northeast dairy corridors sustain highest penetration rates.
- Pouches:Flexible film packaging reduces shipping cube and refrigeration load for food service distributors.
- Squeeze Bottles:Controlled-dispense formats target taco shops and fast-casual operators seeking speed-of-service advantages.
Tubs retain volume leadership; single-serve cups hold the steepest expansion curve.
End User:
Customer type segmentation tracks diverging purchase frequencies and quality thresholds between household replenishment and commercial kitchen procurement.
- Food Service:Commercial kitchens, quick-service chains, and institutional feeders pull volume through negotiated supply agreements with specified butterfat standards and live-culture documentation. Menu embedding in limited-time offers and permanent bowl formats drives accelerated offtake.
- Household:Weekly replenishment cycles through supermarket dairy cases sustain baseline demand with moderate price sensitivity and brand loyalty patterns. Penetration concentrates in suburban markets with established reduced-fat dairy consumption habits.
- Retail:Deli and prepared-food counters utilize low-fat sour cream as ingredient and topping in co-located prepared offerings.
- Bakeries:Commercial and artisanal bakeries incorporate reduced-fat sour cream into cake, muffin, and pastry formulations for moisture retention.
Food service retains volume leadership; bakeries hold the steepest expansion curve.
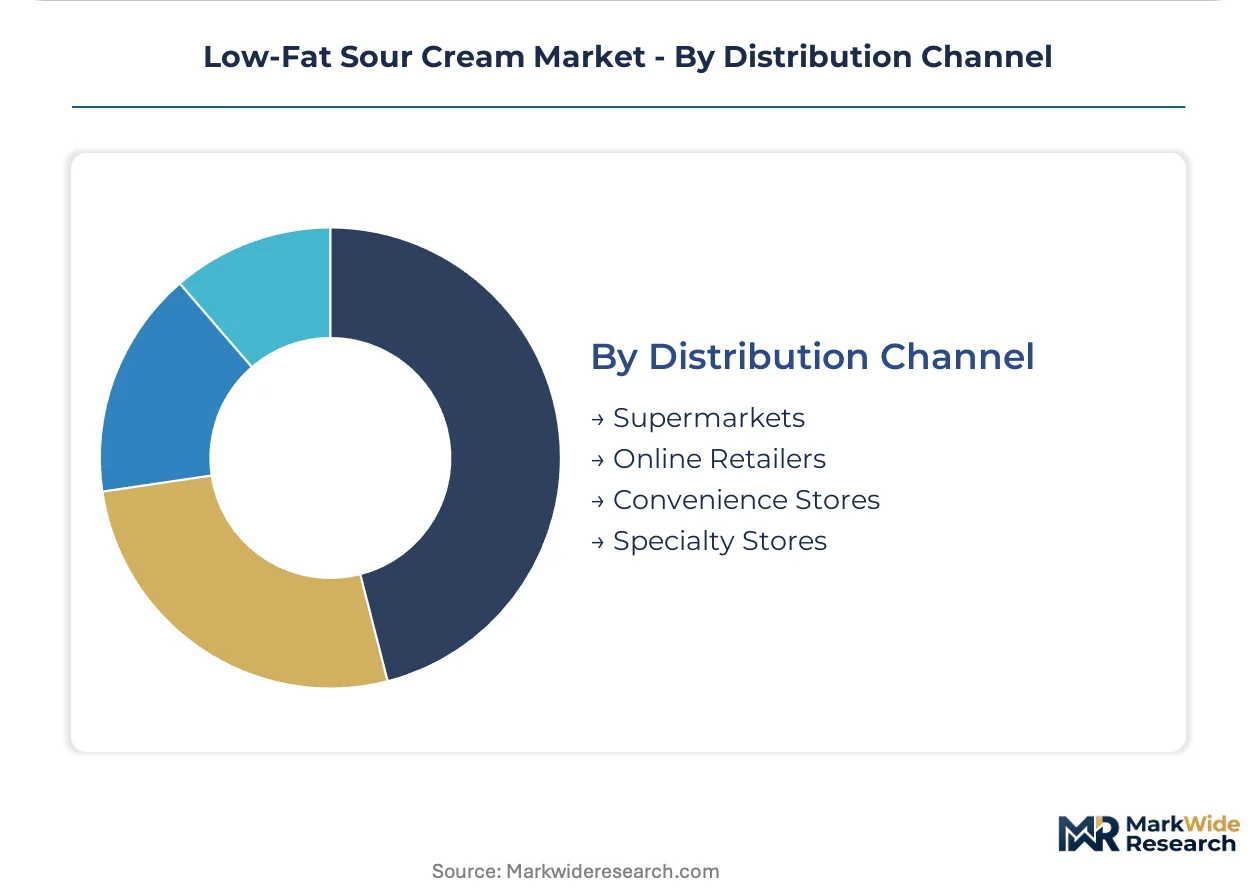
Distribution Channel:
Supply concentration in refrigerated logistics networks favors channels with established cold-chain density, while emerging direct-to-consumer models reshape last-mile economics.
- Supermarkets:Traditional grocery dairy cases sustain highest volume throughput through weekly shopping rituals and impulse purchase placement adjacent to produce and Mexican food sets. Share erosion to online alternatives accelerates in dense urban corridors.
- Online Retailers:Subscription grocery models and curated delivery boxes consolidate refrigerated dairy purchasing with complementary protein and produce bundling. Cold-chain logistics density in Northeast and Pacific Northwest corridors supports viable unit economics.
- Convenience Stores:Limited refrigerated sets prioritize high-velocity SKUs with extended shelf-life specifications.
- Specialty Stores:Natural grocery and gourmet food retailers emphasize organic, probiotic-enhanced, and locally-sourced variants.
Supermarkets retain volume leadership; online retailers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cultured dairy processing clusters concentrate disproportionately in the Upper Midwest and California, creating geographic supply vulnerability during climate-driven milk production disruptions. Refrigerated distribution density shapes viable market penetration, with cold-chain infrastructure determining last-mile economics for live-culture specifications.
United States
Household penetration of reduced-fat cultured dairy remains highest among developed markets, with suburban consumers maintaining weekly replenishment cycles through supermarket dairy cases. FDA standards of identity for sour cream and USDA organic certification requirements shape domestic formulation parameters. Wisconsin and California processing corridors sustain the bulk of national fermentation capacity, with climate volatility increasingly disrupting milk supply predictability.
Canada
Supply-managed dairy frameworks stabilize input costs for low-fat sour cream processors against the volatility seen in liberalized markets. Health Canada and the Canadian Food Inspection Agency enforce compositional standards that align closely with US FDA benchmarks. Ontario and Quebec dairy processing clusters serve domestic demand while maintaining cross-border ingredient trade relationships with US cultured dairy facilities.
Germany
EFSA guidelines on probiotic health claims create stringent substantiation requirements for live-culture marketing in the single largest European dairy market. Bavaria and Baden-Württemberg anchor German sour cream processing, with regional dairy cooperatives maintaining strong private-label supply relationships with discount retail chains. Clean-label preferences accelerate faster than regulatory timelines, pressuring reformulation investments.
France
Traditional crème fraîche consumption patterns create cultural headwinds for low-fat sour cream adoption despite health-conscious demographic shifts. ANSM and DGCCRF enforcement of dairy labeling standards maintains strict separation between fermented cream products. Île-de-France and Auvergne-Rhône-Alpes concentrate food service demand, with Parisian quick-service operators testing reduced-fat formulations in limited-time bowl concepts.
United Kingdom
Post-Brexit regulatory divergence from EU dairy standards creates compliance complexity for processors serving both UK and continental markets. The Food Standards Agency maintains distinct enforcement protocols for live-culture claims and organic certification. London and Southeast England drive premium-tier demand through specialty retail channels, with subscription grocery models penetrating urban corridors faster than national averages.
Low-Fat Sour Cream Market Competitive Landscape
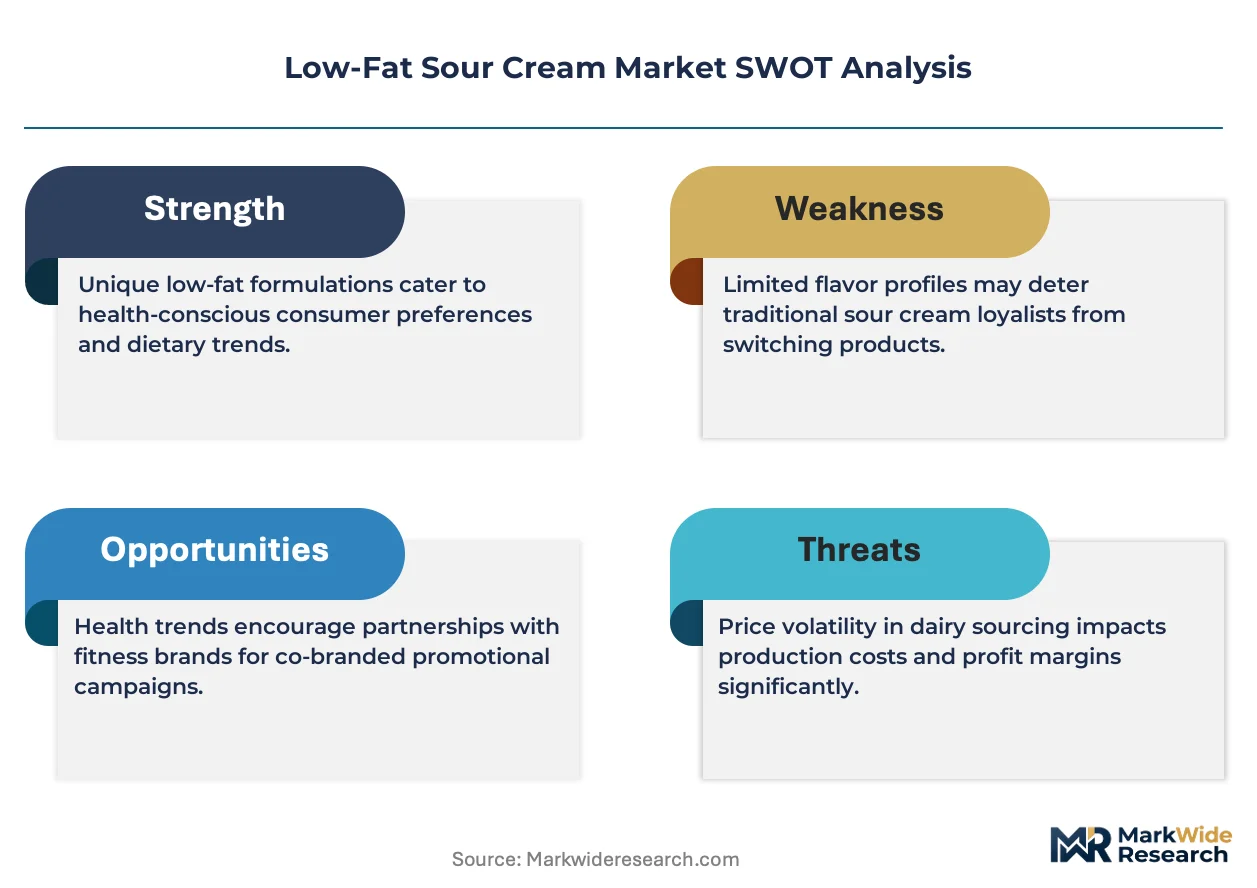
Technology leadership and cost leadership are held by different player archetypes, with mesophilic fermentation expertise and cold-chain density separating premium positioning from commodity supply. The market structure tiers across national refrigerated distribution networks, regional dairy cooperative processing capacity, and specialty organic certification channels. Three archetypes dominate: integrated dairy cooperatives with captive milk supply, national brand houses with direct-store-delivery infrastructure, and organic specialists with traceability premiums. Competitive moves concentrate on clean-label reformulation racing and single-serve food service format expansion.
Within the national brand tier, Daisy Brand LLC and HP Hood LLC exemplify divergent geographic strategies, with one leveraging broad refrigerated distribution and the other anchoring regional processing density. Organic Valley occupies a position within the certified organic archetype, commanding shelf-space premiums through milk sourcing traceability. These three entities represent the competitive spectrum from scale-driven commodity supply to certification-based price insulation.
| Leading Market Players |
|---|
| Daisy Brand LLC |
| HP Hood LLC |
| Dairy Farmers of America |
| Arla Foods amba |
| Lactalis Heritage Dairy |
| Land O'Lakes |
| Organic Valley |
| Prairie Farms Dairy |
| Green Valley Creamery |
| Others |
Value Network & Pricing Analysis
USDA organic certification gates both supplier qualification and price differentiation simultaneously, forcing processors to invest in traceable milk sourcing before accessing premium refrigerated shelf space while conventional formulations compete on thinner margins in food service procurement.
Pricing Analysis
FDA standards of identity dictate the pricing tier structure across organic, probiotic-enhanced, and conventional low-fat sour cream segments. Three-tier pricing structure across premium, standard, and economy levels separates certified organic SKUs with full traceability documentation from live-culture premium lines and commodity food service tubs. Price differentiation rests on certification grade and volume scale, with institutional buyers negotiating contract-based long-term offtake while specialty retail channels absorb shelf-space premiums. Cost compression in the conventional tier is intensifying because fluid milk price volatility at the Chicago Mercantile Exchange transmits directly to processor margins. Food service operators exhibit highest price sensitivity due to recipe-scale volume requirements, whereas specialty retail consumers demonstrate lowest sensitivity when probiotic health claims are substantiated.
Supply Chain Analysis
Refrigerated trucking capacity constraints on the I-80 and I-5 corridors elevate inbound logistics costs for cream sourcing outside the Upper Midwest and California dairy clusters. Geographic supply concentration centers on Wisconsin, California, and New York, where mesophilic fermentation infrastructure and cold-chain distribution networks achieve density. Raw material dependencies draw from fluid milk, active starter cultures, and organic certification compliance documentation. Single-source vulnerability emerges from fermentation capacity clustering in climate-exposed dairy regions, where heat stress and feed cost inflation disrupt milk supply predictability. Distribution runs through direct-store-delivery networks for national brand houses and cooperative logistics pools for regional dairy processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure processing technology disruption is accelerating premium tier rotation as live-culture retention becomes the gold standard for probiotic claims, creating acquisition and innovation urgency across processor tiers.
For Market Incumbents: Fortify cold-chain density in the Northeast and Pacific Northwest corridors where subscription grocery models concentrate demand, while accelerating clean-label reformulation to eliminate carrageenan and modified food starch before FDA enforcement thresholds tighten. Backward integration into captive organic milk supply insulates margin position against commodity price swings. Priority investment in single-serve cup formats captures food service procurement shifts toward portion control and waste reduction. For New Entrants and Emerging Players: White-space opportunities in clinical-nutrition adjacent channels—hospital food service and senior living facilities—offer penetrable entry points where probiotic strain differentiation commands price premiums. Target geographic expansion into secondary metropolitan corridors with underdeveloped specialty refrigerated sets in the Mountain West and Southwest. Go-to-market angle should emphasize Lactobacillus acidophilus and Bifidobacterium fortification with documented CFU counts to bypass incumbent brand loyalty through clinical credibility. For Investors and Strategic Acquirers: FDA standards of identity modernization reshapes the acquisition landscape toward processors with clean-label reformulation capabilities already validated through sensory testing cycles. Long-term viability favors mid-scale organic specialists with established USDA certification and traceable supply relationships over commodity-dependent regional cooperatives. Signal to monitor: enforcement threshold elevation for non-dairy fat sources and artificial thickeners in standardized sour cream products.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | Eliminating carrageenan and modified food starch ahead of FDA enforcement thresholds secures premium private-label contracts. |
| Single-Serve Format Expansion | Portion-control cups capture procurement shifts in college dining and corporate cafeterias where waste reduction drives vendor selection. |
| High-Pressure Processing Adoption | Non-thermal pasteurization for live-culture retention commands shelf-space premiums in specialty retail channels. |
| Organic Certification Investment | USDA organic compliance creates price-insulated demand pools as retailers allocate dedicated refrigerated sets. |
| Probiotic Strain Differentiation | Lactobacillus acidophilus and Bifidobacterium fortification opens clinical-nutrition channels including hospital food service. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dairy processing executives, food service procurement directors, refrigerated distribution logistics managers, and retail category buyers. Secondary validation drew from FDA standards of identity documentation, USDA organic certification databases, Chicago Mercantile Exchange fluid milk pricing data, and SEC filings from publicly traded dairy cooperatives. Bottom-up volume modeling triangulated against top-down category expenditure estimates to reconcile shipment data with consumer purchase patterns.
Across the analysis window, the forecasting framework modeled low-fat sour cream demand through segmentation dimensions spanning product type, packaging format, end-user channel, and distribution pathway. CAGRs were derived from trend extrapolation of historical volume trajectories adjusted for substitution effects from plant-based alternatives and channel migration toward online retail. Industry-specific inputs included fermentation capacity utilization rates, cold-chain logistics cost indices, and clean-label reformulation investment cycles.
Material uncertainties — fluid milk price volatility, climate-driven supply disruptions in Wisconsin and California, and enforcement timing for FDA standards modernization — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding probiotic health claim substantiation requirements and subscription grocery penetration rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
High Protein Yogurt Market
Dairy Products
North America Condensed Milk Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
Canada Dairy Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
United States Yogurt Market
Dairy Products
Global Milk Powder Market
Dairy Products
Reconstituted Milk Market
Dairy Products
Colombia Dairy Market
Dairy Products
Qatar Dairy Products Market
Dairy Products
Europe Chocolate Milk Market
Dairy Products
Low-Calorie Butter Market
Dairy Products
Asia-Pacific Cow Milk Minerals Market
Dairy Products
North America Milk Powder Market
Dairy Products
White Cheese Market