
 Europe Baby Food and Infant Formula Market | 2026-2036
Europe Baby Food and Infant Formula Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Baby Food and Infant Formula Market Intelligence
Millennial parents seeking organic certification is reorganizing demand away from conventional mass-market buyers toward premium-segment purchasers willing to pay for traceable supply chains. Hipp GmbH & Co. Vertrieb KG leverages its German manufacturing base and biodynamic farming partnerships to dominate the organic dry formula category. Danone S.A. competes through specialized medical nutrition subsidiaries including Milupa Nutricia GmbH, which anchors the company's presence in pharmacy channels across France and Germany.
Europe Baby Food and Infant Formula encompasses processed nutritional products designed for infants and toddlers from birth through early childhood, typically manufactured through spray-drying, wet-mix processing, or cold-press pureéing to preserve micronutrient density and achieve shelf-stable formulations. These products serve as breast-milk substitutes or complementary feeding solutions governed by strict compositional standards for protein, fat, carbohydrate, and vitamin-mineral content. Dry formula occupies the largest revenue pool due to logistics efficiency and extended shelf life, while liquid formula represents the fastest-expanding segment as ready-to-feed convenience gains traction among urban dual-income households. Organic ingredient claims command premium positioning across all age-group segments, with 0-6 months products facing the most intensive regulatory scrutiny and 1-3 years applications offering the broadest innovation runway for fortified snack formats.
EFSA maintains centralized scientific oversight of infant formula compositional standards across EU member states, while national regulators including Germany's BfR and France's ANSES enforce country-specific labeling and contaminant thresholds that manufacturers must navigate for market access. The EU Green Deal's Farm to Fork strategy is tightening pesticide residue limits for organic infant food ingredients, directly reshaping agricultural supplier qualification requirements. Stakeholders must monitor pending revisions to the EU Organic Regulation and anticipated alignment between national pharmacy distribution rules to anticipate where formulation and channel investments will yield sustainable returns.
Market Dynamics
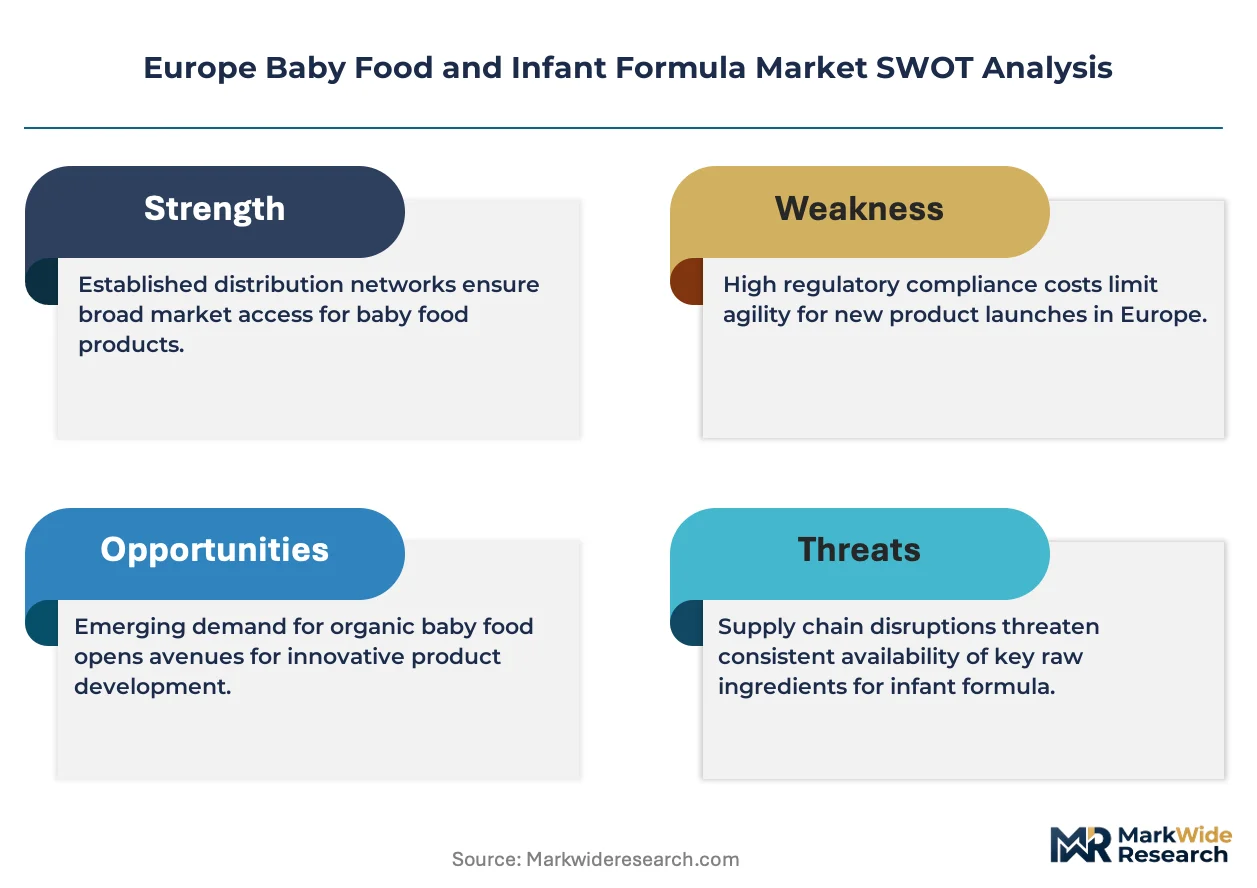
Millennial parents across Germany, France, and the United Kingdom are demanding organic certification and supply-chain transparency, forcing manufacturers to restructure procurement around biodynamic farming partnerships and pharmacy-grade distribution networks.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Tightened pesticide residue limits for organic infant food ingredients are accelerating supplier qualification upgrades across European agricultural networks.
- Pharmacy Channel Expansion:Specialty medical nutrition formulas distributed through pharmacy networks in Germany and France command premium positioning and repeat purchase loyalty.
- Urban Dual-Income Households:Ready-to-feed liquid formula adoption is expanding fastest among time-constrained professional parents in metropolitan France and the United Kingdom.
Market Restraints
- Organic Input Cost Volatility:Biodynamic milk and grain supply fluctuations in Central Europe compress margin stability for certified formula producers.
- EFSA Compositional Scrutiny:Centralized scientific oversight of protein, fat, and micronutrient standards creates lengthy reformulation cycles for new product introductions.
- Regulatory Fragmentation:Divergent national labeling requirements between Germany's BfR and France's ANSES force redundant compliance investments for cross-border distribution.
Strategic Opportunities
- Eastern European Underpenetration:Poland and Romania present expansion white space for premium organic brands seeking pharmacy channel establishment.
- EU Organic Regulation Alignment:Pending revisions to certification standards will advantage early adopters of enhanced traceability systems.
- Fortified Snack Formats:Toddler nutrition products for 1-3 year age groups offer innovation runway beyond intensive 0-6 month regulatory scrutiny.
Industry Challenges
- Specialized Formulation Talent Scarcity:Baby food manufacturers face acute shortages of food scientists with dual expertise in pediatric nutrition and organic processing.
- Legacy Distribution Integration:Established mass-market brands struggle to reconfigure supply chains for pharmacy-grade handling and cold-chain liquid formula logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Baby Food and Infant Formula Market |
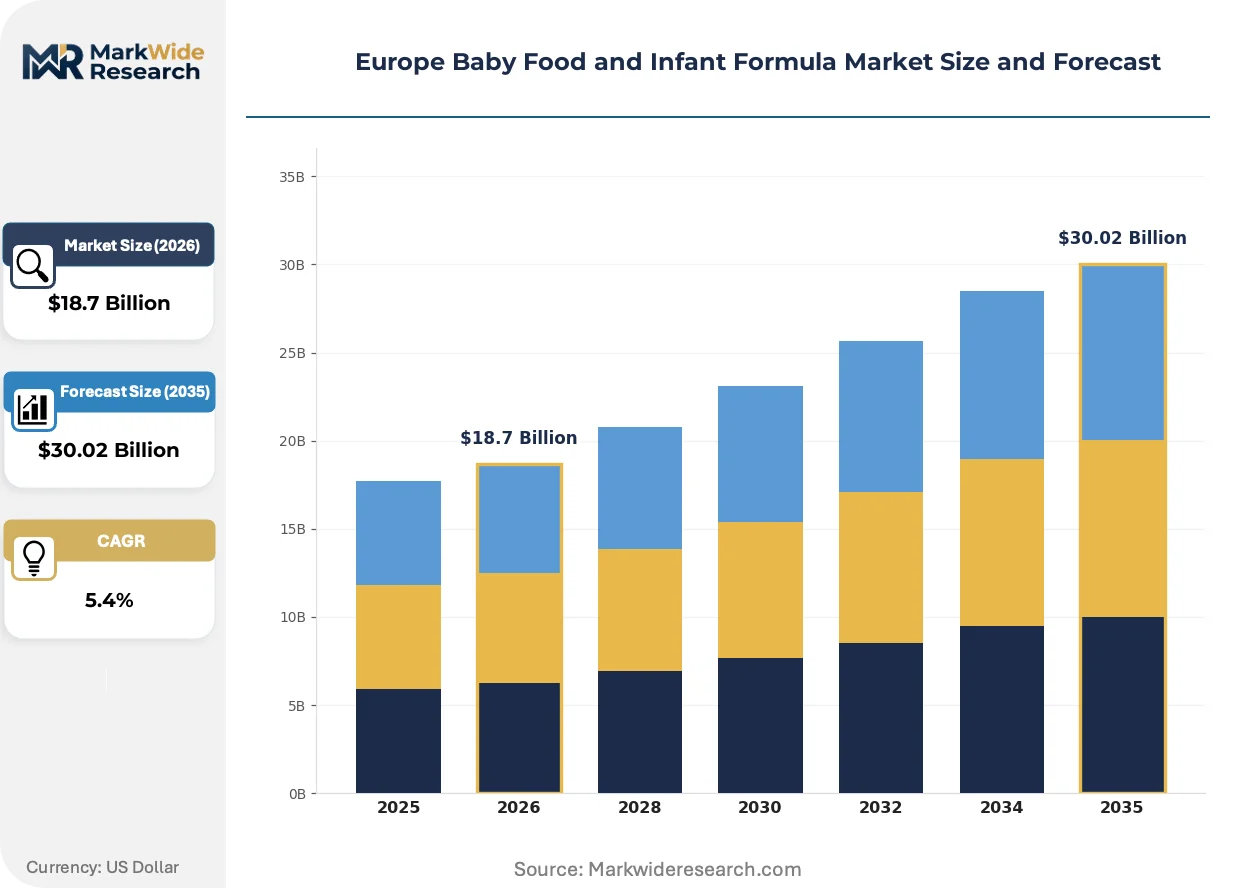
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Formula, Liquid Formula, Cereal-Based, Pureed Food Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Pharmacies Age Group: 0-6 Months, 6-12 Months, 1-3 Years, 3+ Years Ingredients: Organic, Non-GMO, Fortified, Lactose-Free |
| Companies Covered | Hipp GmbH & Co. Vertrieb KG, FrieslandCampina, Nestlé S.A., Hain Celestial Group Inc., Arla Foods Amba, Danone S.A., Milupa Nutricia GmbH, Holle Baby Food GmbH, Abbott Laboratories, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Baby Food and Infant Formula Market Strategic Shifts & Innovations
European infant nutrition is pivoting toward precision fermentation-derived proteins and blockchain-verified organic sourcing, compressing traditional commodity supply relationships while elevating transparency as a purchase determinant.
Spray-drying technology optimized for heat-sensitive bioactive compounds is supplanting conventional high-temperature processing across premium dry formula manufacturing. German and Dutch producers are retrofitting production lines to preserve probiotic viability and native protein structures. This equipment transition is compressing batch yields and extending qualification timelines for contract manufacturers.
EFSA's updated food safety protocols are mandating stricter contaminant thresholds for heavy metals and pesticide residues in infant formula ingredients. Manufacturers must resubmit dossiers for existing products, forcing reformulation investments and extended approval cycles. The 0-6 months segment faces the most intensive compliance burden, with several brands withdrawing SKUs rather than absorbing retesting costs.
Direct-to-subscription purchasing is displacing supermarket bulk buying among affluent urban parents in London, Paris, and Munich. Customized delivery schedules for liquid formula and organic pureés are capturing loyalty through convenience lock-in. Pharmacy chains in Germany are responding with their own subscription platforms to defend their historical channel dominance.
Europe Baby Food and Infant Formula Market Segmentation
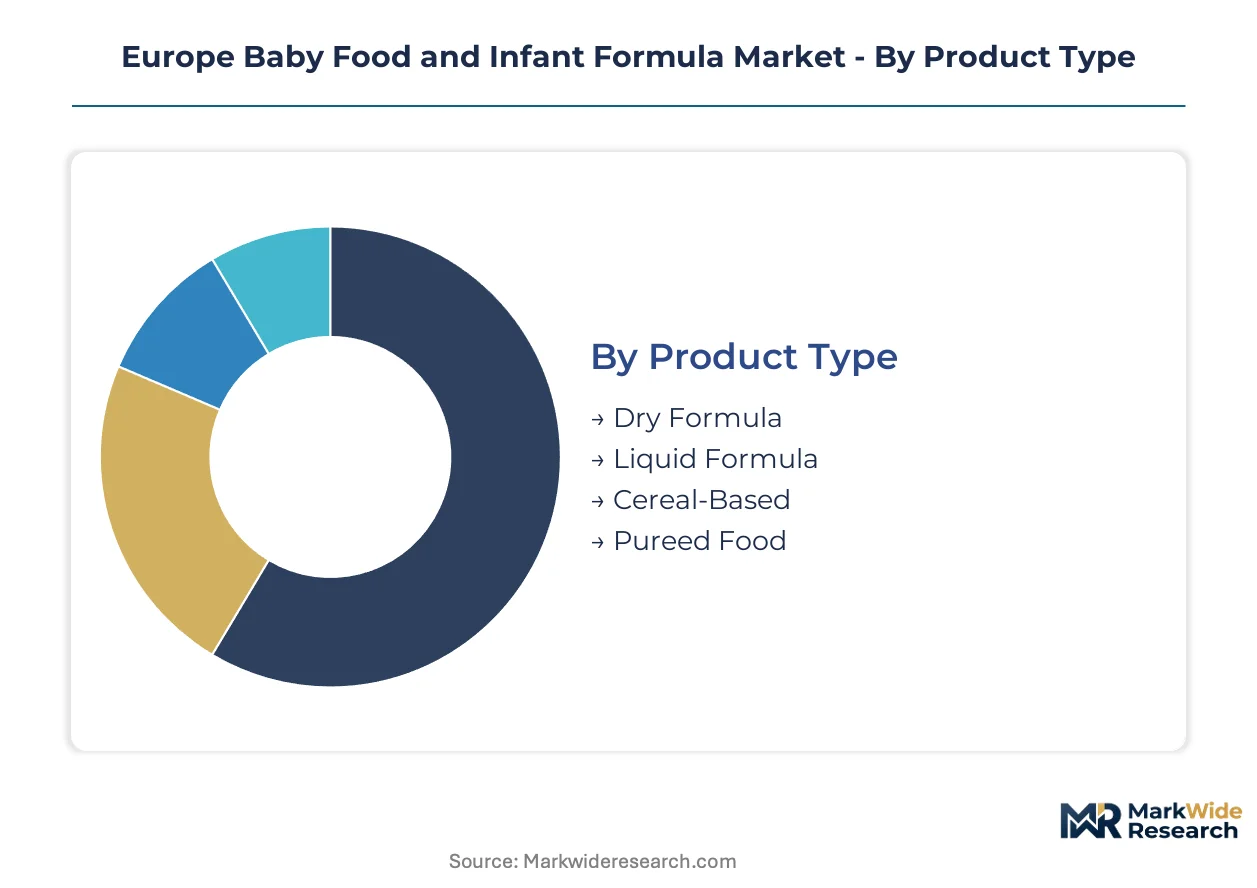
European infant nutrition manufacturers configure production assets and procurement networks around four distinct segmentation axes. Each dimension shapes capital allocation decisions differently—product type determines manufacturing technology, while distribution channel dictates cold-chain infrastructure requirements.
Product Type:
German and Dutch producers dominate dry formula exports across Central and Eastern Europe, while liquid formula output concentrates near metropolitan demand clusters in France and the United Kingdom.
- Dry Formula:Spray-dried and wet-mix processed powders deliver shelf-stable protein-fat-carbohydrate matrices with 18-24 month stability. Pharmacy networks across Germany and Austria anchor premium positioning for hypoallergenic and organic variants. Dry Formula holds the largest share; momentum sits with Liquid Formula.
- Liquid Formula:Ready-to-feed formulations eliminate reconstitution steps through aseptic packaging and sterile liquid handling. Urban dual-income households in Paris, London, and Munich drive adoption where convenience commands price premiums over powder equivalents.
- Cereal-Based:Iron-fortified grain porridges serve as first complementary foods, typically introduced at 4-6 months per WHO guidelines. Eastern European markets show stronger per-capita consumption than Western counterparts.
- Pureed Food:Cold-press or retort-processed fruit-vegetable-meat combinations target 6-12 month transition feeding. Clean-label formulations with single-ingredient transparency are displacing multi-component jars in Nordic markets.
Dry Formula absorbs the majority of production capital; liquid variants capture the steepest expansion trajectory among time-constrained professional parents.
Distribution Channel:
Channel selection in this market follows a cost-to-trust gradient—mass retail captures volume, while pharmacy and specialty channels extract margin through clinical credibility.
- Supermarkets:Hypermarket and grocery chains stock mid-tier conventional formulas with promotional pricing cycles. French and British retailers have expanded private-label organic ranges to compete with branded premiums.
- Online Retail:Direct-to-consumer subscription models with customized delivery frequencies are displacing bulk purchasing among affluent urban parents. German pharmacy chains have launched competing digital platforms to defend channel share.
- Specialty Stores:Organic and natural food retailers stock curated infant nutrition assortments with biodynamic certification emphasis. These outlets concentrate in wealthy urban districts of Copenhagen, Amsterdam, and Vienna.
- Pharmacies:German and French pharmacy networks enforce cold-chain handling standards and provide clinician consultation for specialty medical nutrition formulas. Regulatory frameworks in both countries restrict certain formula categories to pharmacy distribution exclusively.
Pharmacy channels command the highest customer lifetime value; online retail is climbing fastest as subscription convenience locks in repeat purchasing.
Age Group:
Formulation complexity and regulatory scrutiny intensity both decline as age increases, shifting competitive emphasis from compliance precision to taste innovation and packaging convenience.
- 0-6 Months:Breast-milk substitutes face maximum EFSA compositional scrutiny for protein, fat, and micronutrient content. Reformulation cycles for this segment extend 18-24 months due to dossier resubmission requirements.
- 6-12 Months:Complementary feeding products bridge breast milk or formula with solid food introduction. Texture progression from smooth pureés to soft lumps guides product development pipelines.
- 1-3 Years:Toddler milks and fortified snacks operate under lighter regulatory burden, enabling faster flavor and format innovation. This segment offers the broadest runway for functional ingredient claims.
- 3+ Years:Preschool nutrition products overlap with mainstream dairy and snack categories, competing on taste preference rather than clinical positioning. Growth here depends on brand loyalty transfer from earlier life stages.
The 0-6 month segment anchors revenue stability through repeat prescription patterns; 1-3 years applications show the most rapid new product introduction velocity.
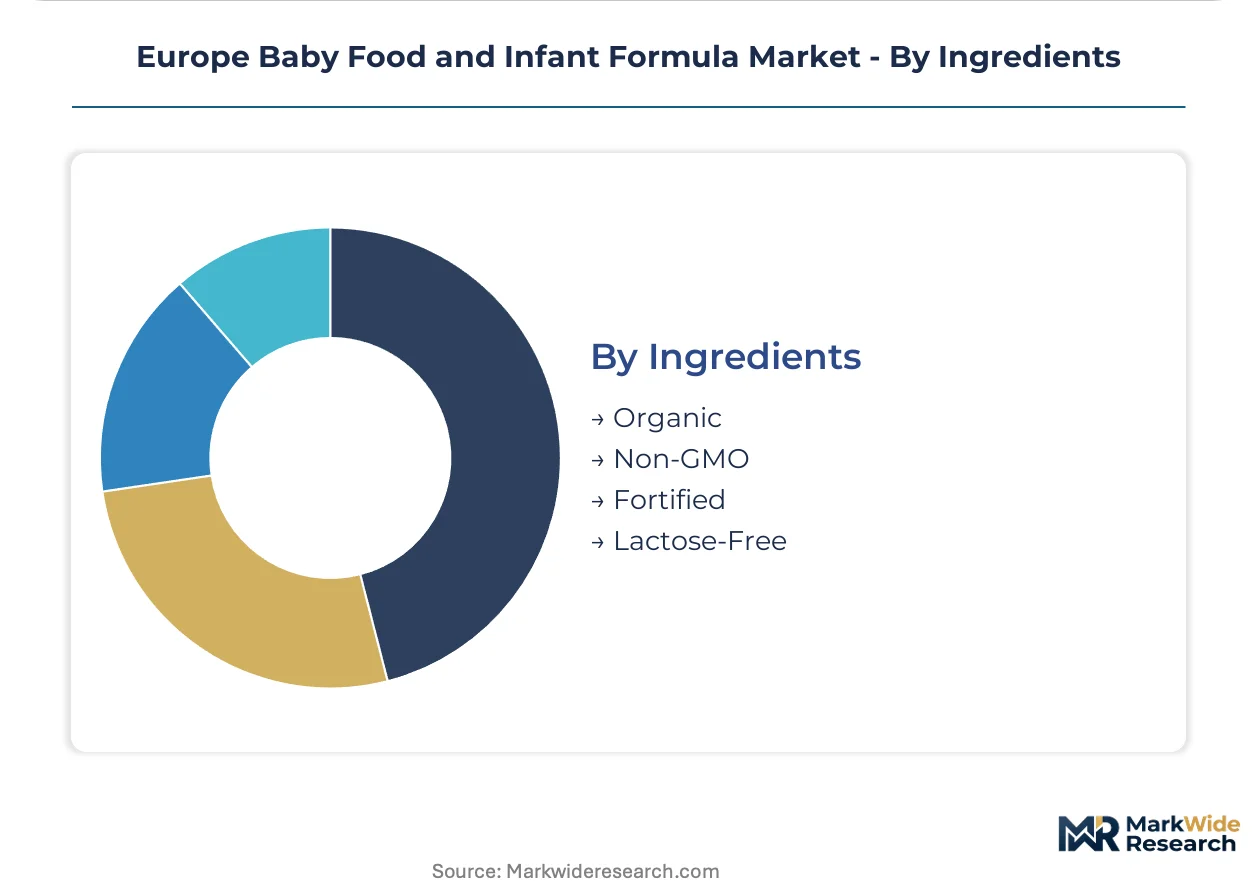
Ingredients:
Input certification tiers stratify pricing power and supplier qualification requirements, with organic and medical-grade specifications demanding multi-year agricultural partnerships.
- Organic:EU Organic Regulation compliance requires biodynamic farming verification and pesticide residue testing below tightened Farm to Fork thresholds. German consumers demonstrate the strongest willingness-to-pay premiums for certified supply chains.
- Non-GMO:Genetically modified ingredient exclusion aligns with clean-label positioning without full organic certification cost burden. This tier captures price-sensitive health-conscious parents in Poland and Spain.
- Fortified:Added vitamins, minerals, and bioactive compounds target specific developmental outcomes. Iron, DHA, and probiotic fortification claims require EFSA health claim authorization.
- Lactose-Free:Hydrolyzed protein or plant-based formulations address diagnosed lactose intolerance and cow's milk protein allergy. Pharmacy distribution dominates due to clinical diagnosis requirements in most EU markets.
Organic claims secure the strongest pricing premiums; fortified formulations are expanding most quickly as functional nutrition science advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health-conscious millennial parents concentrate purchasing power in Germany, France, and the United Kingdom, with pharmacy-distributed specialty formulas commanding loyalty in German-speaking markets and ready-to-feed convenience gaining traction in metropolitan France and Britain.
Germany
Pharmacy channel dominance and biodynamic farming partnerships drive premium organic formula demand. BfR enforces country-specific labeling thresholds that exceed baseline EU requirements. Manufacturing clusters in Bavaria and Baden-Württemberg host spray-drying facilities optimized for heat-sensitive bioactive preservation.
France
Urban dual-income households in Paris accelerate ready-to-feed liquid formula adoption. ANSES maintains separate contaminant thresholds and health claim authorization protocols from German regulators. Pharmacy networks in Lyon and Marseille anchor specialty medical nutrition distribution with clinician consultation services.
United Kingdom
Direct-to-subscription purchasing displaces supermarket bulk buying among affluent London parents. The Food Standards Agency implements post-Brexit divergence from EFSA timelines for novel ingredient approvals. Manchester and Birmingham logistics hubs support cold-chain liquid formula distribution to metropolitan households.
Poland
Emerging organic awareness among Warsaw and Kraków parents creates expansion white space for premium brands. EU Organic Regulation compliance requirements are tightening ahead of Farm to Fork pesticide residue limit revisions. Domestic retailers in Poznań and Wrocław expand biodynamic-certified infant food assortments.
Netherlands
Dutch producers dominate Central and Eastern European dry formula export flows through Rotterdam port logistics. The Netherlands Food and Consumer Product Safety Authority aligns with EFSA while maintaining accelerated approval pathways for innovative formulations. Dairy processing clusters in Friesland supply organic milk inputs to German formula manufacturers.
Europe Baby Food and Infant Formula Market Key Industry Players
Player mix skews toward integrated dairy conglomerates with pediatric nutrition divisions and specialized organic pure-play manufacturers. Market structure shows moderate consolidation at the premium tier alongside fragmentation in private-label and regional organic segments. Strategic archetypes include biodynamic-certified specialists, pharmacy-channel medical nutrition providers, and mass-market diversified food corporations. Dominant competitive moves encompass backward integration into organic dairy farming and subscription platform development to lock in urban household purchasing.
Among German-based organic specialists, Hipp GmbH & Co. Vertrieb KG and Holle Baby Food GmbH exemplify the biodynamic-certified tier with manufacturing proximity to agricultural supply networks. Danone S.A. occupies a position spanning mass-market and medical nutrition segments through its Milupa Nutricia GmbH subsidiary, representing the pharmacy-channel archetype across French and German distribution networks. FrieslandCampina anchors the dairy-integrated conglomerate model with ingredient supply relationships extending into competitor formulations.
| Leading Market Players |
|---|
| Hipp GmbH & Co. Vertrieb KG |
| FrieslandCampina |
| Nestlé S.A. |
| Hain Celestial Group Inc. |
| Arla Foods Amba |
| Danone S.A. |
| Milupa Nutricia GmbH |
| Holle Baby Food GmbH |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
Spray-drying capacity utilization above 85% in Bavarian manufacturing clusters compresses marginal production costs for organic dry formula while simultaneously elevating price floors for liquid variants where aseptic packaging lines remain constrained. This scale asymmetry between powder and ready-to-feed formats concentrates margin capture among German and Dutch producers with backward-integrated dairy networks, forcing smaller competitors toward private-label contract manufacturing or premium organic positioning to escape cost-driven commoditization.
Pricing Analysis
Cost-plus contracts indexed to organic milk powder futures dominate procurement agreements between formula manufacturers and Central European dairy cooperatives. Three-tier pricing structure across premium biodynamic, standard organic, and conventional economy levels segments buyer willingness-to-pay, with German pharmacy channels extracting the highest premiums through clinician consultation bundling. Price erosion runs through economy-tier supermarket SKUs as French and British retailers expand private-label organic ranges. Mass-market conventional buyers exhibit greatest price sensitivity; pharmacy-distributed medical nutrition purchasers show lowest elasticity due to diagnostic gatekeeping requirements.
Supply Chain Analysis
Rotterdam port congestion and container availability constraints on North Sea trade lanes elevate inbound logistics costs for specialty ingredients sourced outside the EU. Manufacturing concentrates in Germany, the Netherlands, and France, with spray-drying facilities clustered in Bavaria and Friesland feeding Central and Eastern European distribution. Organic whey protein and biodynamic grain inputs draw from contracted Austrian and Swiss agricultural partnerships. Single-source vulnerability in probiotic strain supply creates formulation risk for heat-sensitive bioactive claims. Distribution runs through pharmacy networks in German-speaking markets and supermarket-retail hybrid models in France and Britain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European infant nutrition is exiting a regulatory compliance cycle as EFSA dossier resubmissions peak, positioning the market for cyclical recovery driven by Farm to Fork pesticide limit alignment and pharmacy channel expansion into Eastern Europe.
For Market Incumbents: Fortify pharmacy channel control through exclusive clinician consultation partnerships in Germany and France, while deepening backward integration into biodynamic dairy farming to secure organic input cost stability against Central European supply volatility. EFSA's pending contaminant threshold revisions threaten reformulation cost spikes for non-integrated players; captive milk supply hedges this exposure. For New Entrants and Emerging Players: Differentiate on blockchain-verified organic traceability to capture Warsaw and Kraków parents emerging from conventional purchasing into premium awareness. Poland and Romania present the most penetrable white space, with pharmacy channel establishment offering the strongest go-to-market angle given regulatory restrictions on specialty formula distribution. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors spray-drying retrofit specialists with heat-sensitive bioactive preservation capabilities over legacy high-temperature processors. Long-term viability across the projection horizon rests on EU Organic Regulation alignment investments and subscription platform infrastructure. Watch EFSA approval velocity for novel probiotic strains as the inflection signal distinguishing premium formulation leaders from commodity followers.| Strategic Initiative | Industry Significance |
|---|---|
| Biodynamic Farming Partnership | Secures organic milk supply under tightened EU Green Deal pesticide thresholds. |
| Pharmacy Channel Expansion | Captures premium positioning through ANSES and BfR-restricted distribution networks. |
| Spray-Drying Retrofit Investment | Preserves probiotic viability for differentiated heat-sensitive bioactive claims. |
| Subscription Platform Launch | Locks in urban dual-income household repeat purchasing against supermarket displacement. |
| Eastern European Market Entry | Establishes first-mover pharmacy relationships in Poland and Romania growth corridors. |
Research Approach
A spread of perspectives from pediatric nutrition formulators, pharmacy category managers, organic dairy cooperative procurement leads, and EFSA regulatory affairs specialists converged on the working assumptions underlying demand projections and compliance cost estimates. Secondary validation drew from EU Organic Regulation filings, EFSA scientific opinions on infant formula compositional standards, German BfR contaminant monitoring reports, and Nielsen retail audit data across French and British supermarket channels. Bottom-up segment sizing triangulated against top-down market value reconstruction from manufacturer revenue disclosures and trade flow analysis through Rotterdam and Hamburg port records.
Segmentation dimensions modeled include product type, distribution channel, age group, and ingredient certification tier across the analysis window. CAGRs were derived from growth rate reconciliation between historical volume trends and forward-looking capacity expansion announcements. Forecast inputs incorporated EFSA approval pipeline velocity for novel ingredients and Farm to Fork pesticide limit implementation timelines affecting organic agricultural qualification.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement, stable organic input supply from Central European dairy networks, or continued pharmacy channel regulatory protection would require recalibration. Forecasts reflect documented assumptions regarding EFSA dossier processing timelines and biodynamic farming partnership scalability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Baby Cereal-Based Complementary Food Market
Baby Food and Infant Formula
Baby Fruit Puree Market
Baby Food and Infant Formula
Parenteral Formula Market
Baby Food and Infant Formula
Infant Formula Milk Powder Market
Baby Food and Infant Formula
Goat Milk Formula Market
Baby Food and Infant Formula
Global DHA Algae Oil for Infant Formula Market
Baby Food and Infant Formula
Organic Infant Formula Market
Baby Food and Infant Formula
Europe Organic Baby Food Market
Baby Food and Infant Formula
Vietnam Pet Food Market
Baby Food and Infant Formula
Baby Food Products Market
Baby Food and Infant Formula
Human Milk Oligosaccharides in Infant Formula Market
Baby Food and Infant Formula
Indonesia Infant Nutrition Market
Baby Food and Infant Formula
Europe Baby Food Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
Follow on Formula Milk Market
Baby Food and Infant Formula
Pet Milk Replacers Market