
 Halloumi Cheese Market | 2026-2036
Halloumi Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Halloumi Cheese Market Intelligence
Pre-sliced and portion-controlled packaging configurations is consolidating buyer choice across European retail channels, replacing bulk-block purchasing for smaller households. Pittas Dairy Industries leverages its Cypriot production base to sustain authentic positioning in protected-designation markets. Arla Foods competes through scaled dairy supply chains that extend distribution reach into Scandinavian and British supermarkets. Zita Dairies specializes in traditional handmade formats that anchor premium shelf placement in specialty stores.
Halloumi is a semi-hard, brined cheese traditionally produced from a mixture of goat's, sheep's, and sometimes cow's milk, with a characteristic high melting point enabled by its unique protein structure and heating process. Its primary commercial purpose centers on grilling and frying applications where structural integrity under heat distinguishes it from conventional cheeses. Traditional Halloumi dominates volume production and commands the deepest heritage premium, while Flavored Halloumi variants represent the fastest-expanding margin pool as producers differentiate through herb infusions and chili coatings. The Industrial production method leads throughput scale, though Handmade segments retain pricing power in export markets where provenance verification carries regulatory weight.
EU Protected Designation of Origin enforcement through EFSA compliance pathways shapes product labeling and cross-border market access for Cypriot-origin producers. Cyprus national regulators and British Food Standards Agency import protocols jointly determine shelf-life declarations and milk-ratio testing requirements for entry into the United Kingdom. Stakeholders must monitor how post-Brexit UK-EU veterinary agreements affect certification reciprocity and cold-chain documentation standards.
Market Dynamics
The EU Protected Designation of Origin framework for Cypriot halloumi is restructuring supplier compliance obligations and export eligibility across European retail and foodservice channels. This regulatory architecture is forcing producers to reconfigure milk sourcing ratios, labeling protocols, and cold-chain documentation to maintain market access.
Growth Catalysts
- Foodservice menu expansion:United Kingdom and Germany operators are embedding halloumi into brunch formats and vegetarian-forward offerings, pulling volume through commercial kitchens.
- EFSA compliance pathways:The EU's standardized safety assessment protocols are streamlining cross-border certification for Cypriot-origin producers, reducing time-to-shelf in member states.
- Pre-sliced packaging formats:Convenience-oriented portion control is displacing bulk-block purchasing in smaller European households, expanding addressable retail occasions.
Market Restraints
- Milk input volatility:Fluctuating goat and sheep milk availability in Cyprus concentrates supply risk during seasonal production troughs.
- Protected designation enforcement:The EU's strict geographic-origin requirements block non-Cypriot producers from using the halloumi name in protected markets, capping supply expansion.
- Plant-based substitution:Cashew and coconut-derived grilling cheeses are capturing price-sensitive flexitarian segments in Scandinavian and British supermarkets.
Strategic Opportunities
- United Kingdom retail SKU proliferation:British supermarkets are expanding chilled cheese aisle facings for specialty Mediterranean products, creating shelf space for premium-positioned variants.
- Herb and chili infusions:Flavored halloumi variants command margin premiums in specialty stores across Germany and the Netherlands.
- Post-Brexit veterinary agreement evolution:Reciprocity negotiations between British and EU regulators may streamline certification documentation for Cypriot exporters.
Industry Challenges
- Artisan skill scarcity:Traditional handmade production methods require specialized curd-handling expertise that is concentrating among aging producer cohorts in Cyprus.
- Cold-chain reconfiguration:Post-Brexit customs processing at British ports is extending transit times, forcing investments in modified-atmosphere packaging and temperature monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Halloumi Cheese Market |
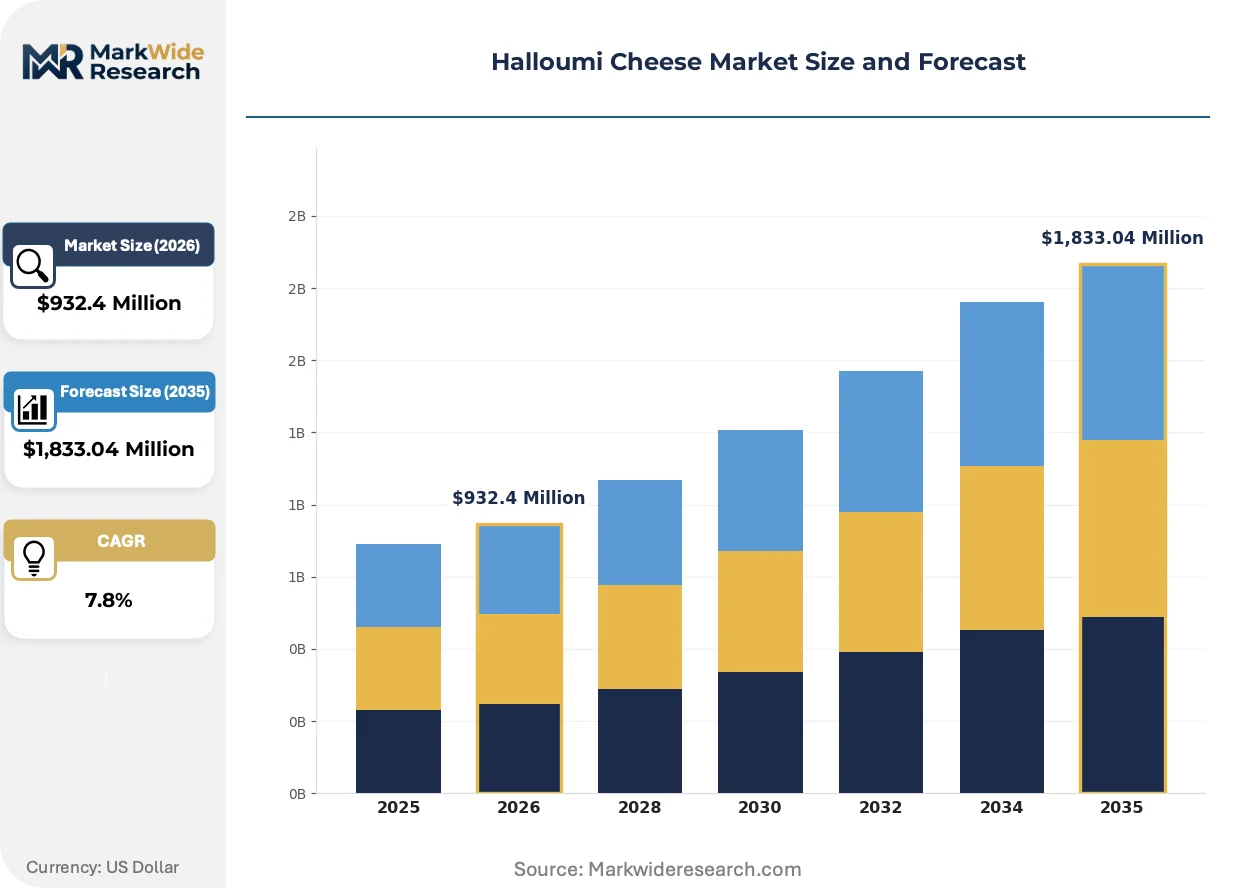
| Market Size in 2026 | $932.4 Million |
| Market Size in 2035 | $1,833.04 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Halloumi, Flavored Halloumi, Organic Halloumi, Grated Halloumi End User: Households, Restaurants, Food Service, Retailers Production Method: Handmade, Industrial, Pasteurized, Raw Milk Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Petrou Bros Dairy Products, Zita Dairies, Arla Foods, Pittas Dairy Industries, Hadjipieris, Almarai, Uhrenholt, Dafni Dairy, Charalambides Christis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Halloumi Cheese Market Strategic Shifts & Innovations
Product format innovation and regulatory compliance automation are restructuring how halloumi reaches European consumers. These forces are compressing production-to-shelf timelines while fragmenting buyer preferences across convenience and authenticity axes.
Modified-atmosphere packaging technology is extending shelf stability for pre-sliced halloumi formats without preservative additives. Scandinavian retailers are adopting these configurations fastest, responding to consumer preference for grab-and-go convenience. The technology is converging with blockchain-enabled provenance tracking to satisfy EFSA traceability requirements while reducing spoilage-related returns.
EFSA's evolving stance on novel cheese processing aids is reshaping allowable ingredient declarations for flavored variants. Industrial producers are reformulating herb coatings and brine solutions to preempt regulatory rejection. Small-scale Cypriot exporters face disproportionate compliance burdens as they lack in-house regulatory affairs capacity to navigate pre-submission consultations.
Foodservice procurement is consolidating toward direct-supplier relationships that bypass traditional dairy distributors. United Kingdom restaurant groups are negotiating volume commitments with Cypriot producers for consistent brunch-menu supply. This disintermediation is most visible in London and Manchester, where multi-site operators prioritize origin verification over distributor breadth.
Halloumi Cheese Market Segmentation
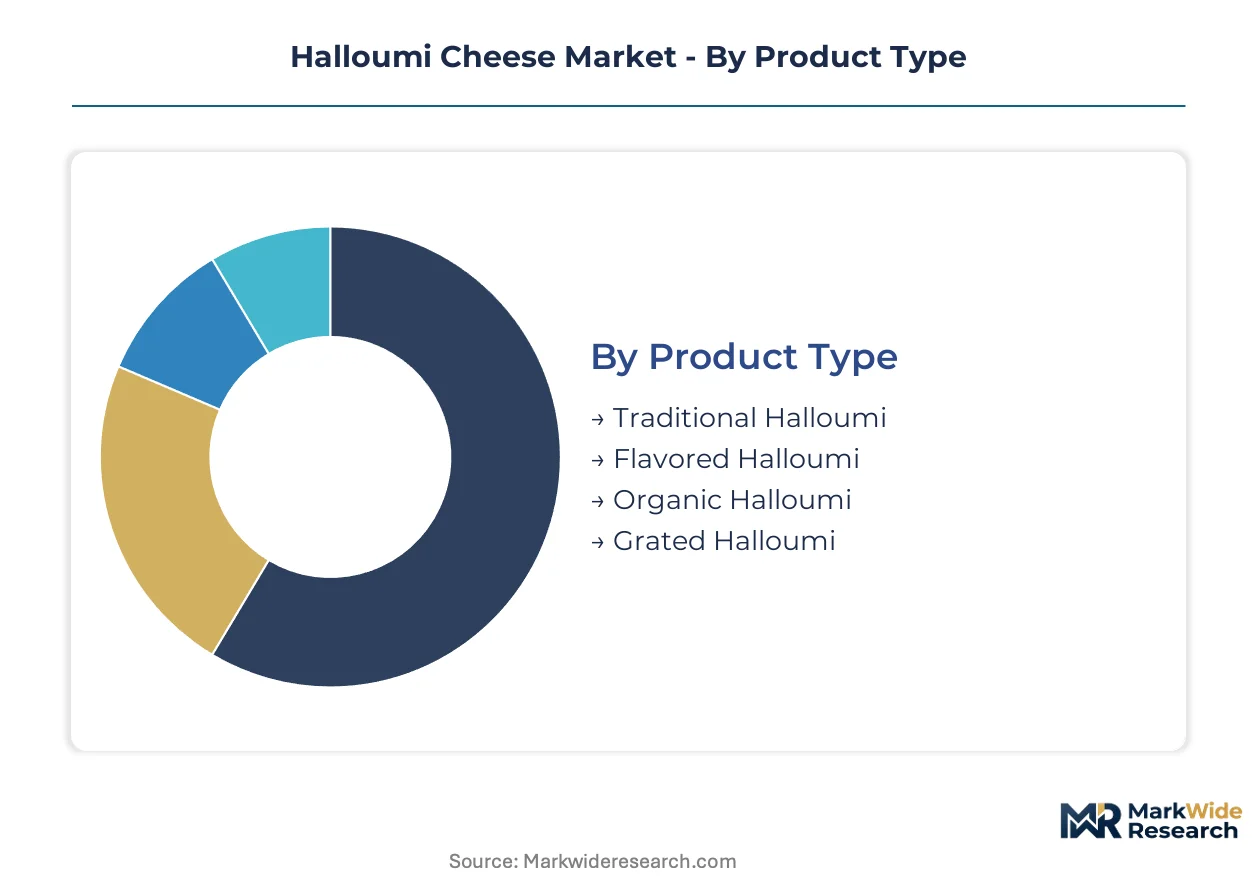
Halloumi's commercial evolution fragments across product formats, production scales, and channel architectures. Each segmentation axis reveals distinct margin pools and compliance burdens that reshape supplier positioning across European retail and foodservice.
Product Type:
Standardization pressure from EU Protected Designation of Origin rules collides with customization demand for flavor differentiation and organic certification across this category.
- Traditional Halloumi:Produced from goat and sheep milk mixtures following Cypriot methods with characteristic layered curd structure and mint leaf packaging. United Kingdom retail chains and German foodservice operators anchor volume procurement here, though milk-ratio enforcement under EFSA protocols is tightening supply eligibility.
- Flavored Halloumi:Herb-infused and chili-coated variants command shelf price premiums in Netherlands specialty stores and Scandinavian supermarkets. British brunch chains are driving commercial kitchen adoption of pre-marinated formats that reduce on-site preparation labor.
- Organic Halloumi:Certified organic milk sourcing restricts batch scale but secures placement in premium British and German retail aisles where provenance labeling carries purchase influence.
- Grated Halloumi:Pre-shredded formats target pizza manufacturing and ready-meal production in industrial food processing facilities across Belgium and France.
Most installed capacity flows through Traditional Halloumi. Expansion is steepest in Flavored Halloumi.
End User:
Volume concentration shifts from household retail toward commercial kitchen procurement as foodservice menu integration deepens across Northern Europe.
- Restaurants:Full-service and fast-casual operators in London and Manchester are locking direct supply contracts with Cypriot producers for consistent brunch-menu availability, bypassing traditional dairy distributors entirely.
- Food Service:Contract catering and institutional kitchens across Germany prioritize portion-controlled formats that streamline inventory management and reduce waste.
- Households:Smaller European households are displacing bulk-block purchasing with pre-sliced retail configurations that address convenience preferences without compromising authenticity claims.
- Retailers:British supermarket chains are expanding chilled cheese aisle facings for Mediterranean specialty products, creating shelf space competition among supplier portfolios.
Procurement volume concentrates in Food Service. Margin expansion is fastest in Restaurants.
Production Method:
Scale economies and regulatory compliance burdens diverge sharply between artisan craft methods and automated industrial throughput.
- Industrial:Automated curd handling and standardized brining systems enable batch consistency for retail private-label supply across Scandinavian markets, though EFSA processing aid approvals constrain ingredient flexibility.
- Handmade:Traditional curd-stretching expertise concentrates among aging producer cohorts in Cyprus, limiting expansion capacity despite premium pricing power in export markets where provenance verification carries regulatory weight.
- Pasteurized:Heat-treated milk protocols satisfy British Food Standards Agency import requirements and extend shelf stability for cross-border distribution into United Kingdom retail channels.
- Raw Milk:Unpasteurized production retains niche positioning in Cypriot domestic consumption and select European specialty stores where local regulations permit.
Throughput dominance sits with Industrial. Handmade commands the steepest price premiums.
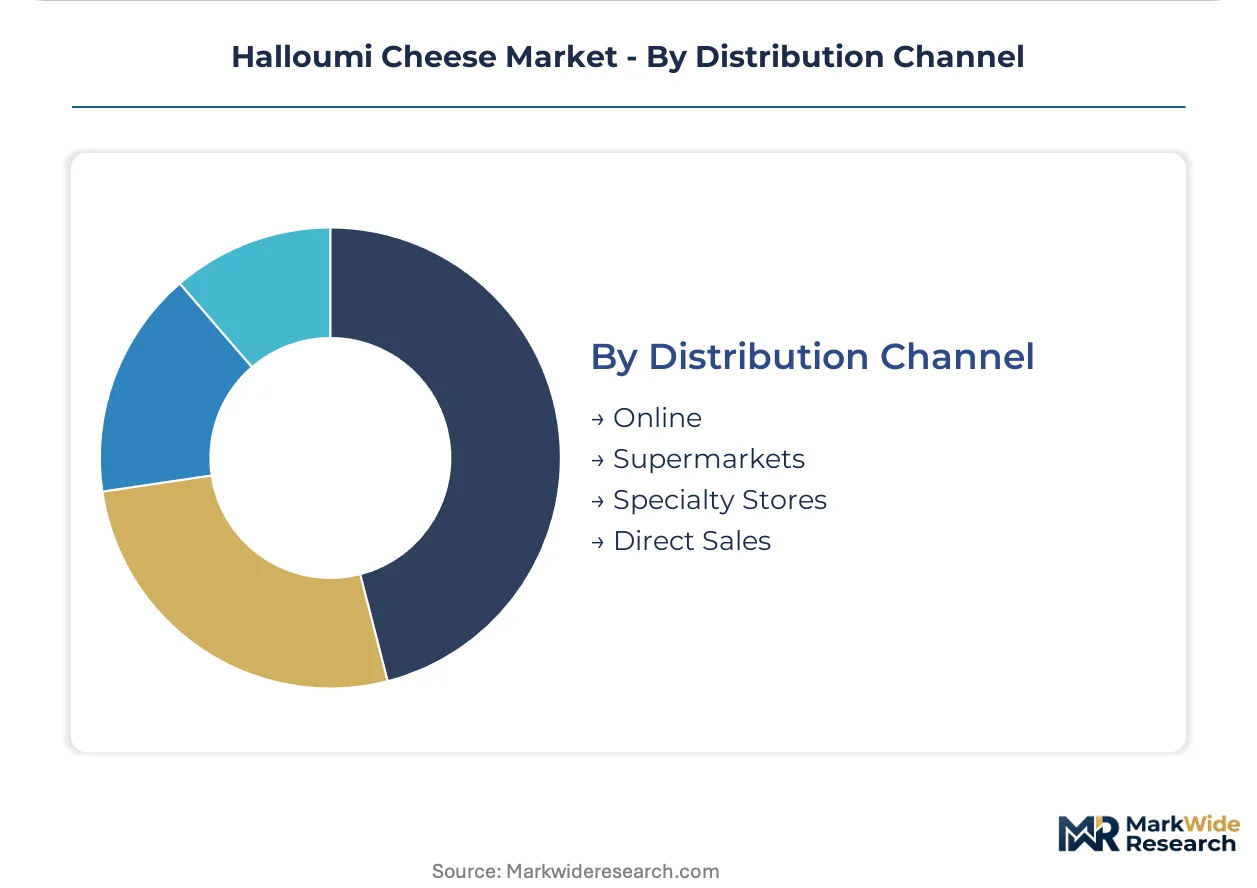
Distribution Channel:
Channel selection determines margin capture versus reach tradeoffs, with direct relationships eroding traditional distributor intermediation.
- Supermarkets:British and German retail chains drive SKU proliferation across chilled cheese aisles, with modified-atmosphere packaging technology enabling extended shelf stability without preservative additives.
- Online:E-commerce penetration is accelerating in Scandinavian markets where subscription cheese boxes and direct-to-consumer shipping circumvent retail slotting fee structures.
- Specialty Stores:Independent Mediterranean grocers in Netherlands and Belgium anchor premium positioning for organic and handmade variants with educated staff enabling origin storytelling.
- Direct Sales:Cypriot producers are negotiating volume commitments directly with United Kingdom restaurant groups, compressing margin extraction by dairy distributors.
Volume flows predominantly through Supermarkets. Online is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Halloumi cheese originated in Cyprus, where layered curd techniques developed over centuries before commercial export networks formed in the late twentieth century. The product's Protected Designation of Origin status now governs where authentic halloumi may be produced and sold.
United Kingdom
British supermarkets have expanded chilled cheese aisle facings for Mediterranean specialty products, with pre-sliced formats displacing bulk-block purchasing among smaller households. The British Food Standards Agency enforces strict milk-ratio testing and shelf-life declaration protocols for Cypriot imports. London and Manchester restaurant groups now negotiate direct supply contracts with Cypriot producers, bypassing traditional dairy distributors entirely.
Germany
German foodservice operators embed halloumi into vegetarian-forward brunch formats and contract catering menus, pulling substantial volume through commercial kitchens. EFSA compliance pathways streamline cross-border certification for Cypriot-origin producers entering German retail channels. Berlin and Hamburg host the densest concentration of Mediterranean specialty grocers, where organic and handmade variants command premium shelf placement.
Netherlands
Dutch specialty stores anchor premium positioning for herb-infused and chili-coated halloumi variants, with educated staff enabling origin storytelling that justifies price premiums. The Dutch Food and Consumer Product Safety Authority applies EU Protected Designation of Origin rules strictly, blocking non-Cypriot producers from using the halloumi name. Rotterdam and Amsterdam distribution hubs facilitate re-export into Scandinavian markets.
Sweden
Swedish retailers adopt modified-atmosphere packaging technology fastest, responding to consumer preference for grab-and-go convenience without preservative additives. The Swedish Food Agency enforces EFSA traceability requirements through blockchain-enabled provenance tracking systems. Stockholm and Gothenburg supermarkets drive SKU proliferation across chilled cheese aisles.
Cyprus
Cypriot producers concentrate traditional handmade capacity among aging producer cohorts with specialized curd-stretching expertise. Cyprus national regulators administer EU Protected Designation of Origin enforcement and milk sourcing ratio compliance. Nicosia and Limassol industrial zones host automated production facilities serving retail private-label supply across Northern European markets.
Halloumi Cheese Market Key Industry Players
Premium-margin players sit above commodity-margin players across authenticity verification and provenance documentation capabilities. The vendor base clusters around three strategic archetypes: Cypriot-origin heritage producers with Protected Designation of Origin access, scaled Nordic dairy conglomerates with retail distribution breadth, and specialty handmade artisans with limited batch capacity. Competitive moves concentrate on direct supply relationship formation with United Kingdom restaurant groups and modified-atmosphere packaging technology adoption for extended shelf stability.
Within the heritage producer tier, Pittas Dairy Industries and Charalambides Christis exemplify Cypriot-origin positioning that satisfies EFSA compliance pathways for protected-designation markets. Arla Foods represents the scale-driven archetype, leveraging Scandinavian dairy supply chains to extend distribution reach into British and German supermarkets. Zita Dairies occupies a specialty position, with traditional handmade formats anchoring premium shelf placement in independent Mediterranean grocers across the Netherlands and Belgium.
| Leading Market Players |
|---|
| Petrou Bros Dairy Products |
| Zita Dairies |
| Arla Foods |
| Pittas Dairy Industries |
| Hadjipieris |
| Almarai |
| Uhrenholt |
| Dafni Dairy |
| Charalambides Christis |
| Others |
Cost & Logistics Intelligence
Family-owned Cypriot heritage producers anchor supply concentration and enforce pricing discipline through Protected Designation of Origin gatekeeping, while scaled Nordic dairy conglomerates compete on volume throughput rather than margin capture. This ownership pattern concentrates authentic production capacity in aging artisan cohorts and industrial zones around Nicosia, forcing buyers to accept premium positioning or switch to non-protected grilling cheese alternatives.
Pricing Analysis
Three-tier pricing structure across premium handmade, standard industrial, and economy private-label levels segments buyer access by provenance verification and milk-ratio compliance. Price differentiation rests on EFSA certification status, organic milk sourcing, and direct-to-restaurant relationship depth. Cost compression in economy tiers is intensifying because British supermarkets are expanding own-label halloumi facings. Foodservice operators show least price sensitivity; smaller households in Scandinavian markets show most.
Supply Chain Analysis
Dual-sourcing requirements from United Kingdom restaurant groups and German contract caterers mandate multi-producer qualification, forcing Cypriot exporters to maintain redundant batch capacity. Supply concentrates in Cyprus, with secondary industrial production in Greece and licensed manufacturing in the United Kingdom for non-protected grilling cheese variants. Raw material dependencies center on seasonal goat and sheep milk availability, mint leaf packaging, and modified-atmosphere film. Single-source vulnerability runs through Cypriot artisan skill concentration. Distribution runs through Rotterdam and Amsterdam re-export hubs into Scandinavian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Halloumi has entered a late-cycle quality phase where British and German buyers prioritize EFSA-verified provenance over price, pulling margin toward authenticated Cypriot-origin supply.
For Market Incumbents: Deepen direct supply relationships with United Kingdom restaurant groups to lock brunch-menu volumes before Nordic dairy conglomerates scale competing offerings. Invest in blockchain-enabled provenance tracking to satisfy EFSA traceability requirements and defend against cashew-derived grilling cheese substitutes. Prioritize modified-atmosphere packaging capacity in Cyprus to capture Scandinavian retail expansion. For New Entrants and Emerging Players: Plant-based cheese analog technology offers a technology-first wedge into price-sensitive flexitarian segments in British and Swedish supermarkets where traditional halloumi pricing excludes trial. Target organic certification gaps in Netherlands specialty stores where educated staff can anchor origin storytelling. Pursue co-manufacturing partnerships with Cypriot industrial producers to bypass Protected Designation of Origin blocking. For Investors and Strategic Acquirers: Scaled dairy conglomerates with Mediterranean distribution infrastructure are the most active acquirer in this space, seeking EFSA-compliant production capacity. Five-to-ten-year viability hinges on post-Brexit veterinary agreement reciprocity stabilizing British import protocols. Watch for Cyprus regulatory enforcement tightening milk-ratio requirements as the inflection signal for supply-constrained premium pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Supply Relationship Formation | Bypasses dairy distributor margin extraction for United Kingdom restaurant group volume commitments. |
| Modified-Atmosphere Packaging Investment | Extends shelf stability for Scandinavian grab-and-go retail without preservative additives. |
| Blockchain Provenance Tracking Deployment | Satisfies EFSA traceability requirements while reducing spoilage-related returns in British supermarkets. |
| Organic Certification Acquisition | Secures premium shelf placement in Berlin and Hamburg Mediterranean specialty grocers. |
| Flavor Infusion R&D Expansion | Captures margin premiums for chili-coated and herb-infused variants in Netherlands retail channels. |
Research Approach
Direct dialogue with Cypriot dairy plant managers, British supermarket category buyers, German foodservice procurement directors, and EFSA regulatory affairs specialists grounded qualitative assessment of Protected Designation of Origin compliance pathways. Secondary validation drew from EU trade statistics, British Food Standards Agency import protocols, Cyprus national dairy production records, and EFSA processing aid approval databases. Bottom-up volume modeling triangulated against top-down consumption estimates across retail and foodservice channels.
Segmented outputs across product type, production method, end user, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs derived from trend extrapolation of pre-sliced format adoption, foodservice menu penetration rates, and organic certification growth curves. Forecast inputs incorporated seasonal milk availability patterns and post-Brexit customs processing timeline assumptions.
The model holds under stable EU-United Kingdom veterinary agreement reciprocity; deviation in Cyprus milk-ratio enforcement stringency or accelerated plant-based substitution in Scandinavian markets would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Middle East and Africa UHT Milk Market
Dairy Products
North America Organic Dairy Market
Dairy Products
Spoonable Yogurt Market
Dairy Products
United Arab Emirates Dairy Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Lactose-Free Sour Cream Market
Dairy Products
Plain Yogurt Market
Dairy Products
Organic Milk Market
Dairy Products
Kuwait Dairy Products Market
Dairy Products
Buttermilk Powder Market
Dairy Products
Milk Mineral Market
Dairy Products
Cheese Shreds Market
Dairy Products
Green Tea Butter Market
Dairy Products
South America Yogurt Market
Dairy Products
Fermented Dairy Products Market
Dairy Products
North America A2 Milk Market