
 Global Grass Fed Dairy Product Market | 2026-2036
Global Grass Fed Dairy Product Market Size, Share, and Industry Trends Forecast 2026-2036
Global Grass Fed Dairy Product Market Intelligence
The replacement of conventional grain-based animal feed with pasture-forage diets is shifting the fundamental cost structure and nutritional profile of dairy products. This transition allows premium branding and higher price points for producers. Organic Valley leverages its cooperative model to secure a consistent supply of certified grass-fed milk. Maple Hill Creamery specializes exclusively in 100% grass-fed dairy, differentiating its brand in a crowded marketplace.
Grass fed dairy products originate from animals that consume a diet composed primarily of fresh pasture or forage. These products are often characterized by higher levels of Conjugated Linoleic Acid (CLA) and omega-3 fatty acids compared to conventional dairy. Among product types, fluid milk and yogurt represent foundational categories with high consumer recognition. Supermarkets remain the dominant distribution channel, but online retail is expanding access to niche and artisanal brands.
Labeling claims and production standards are governed by frameworks like the USDA's grass-fed marketing claim standard and the EU's organic farming regulations. These rules provide consumers with assurance regarding animal welfare and dietary claims, directly influencing purchasing decisions. For producers, navigating the patchwork of national certification requirements is a key operational challenge. Success will hinge on maintaining supply chain integrity and communicating verifiable product benefits to an increasingly discerning consumer base.
Market Dynamics
The market's structure is defined by the operational and economic trade-offs between pasture-based forage systems and conventional grain-fed models. This dynamic is intensified by evolving organic certification standards that dictate land access, animal welfare protocols, and ultimately, production costs.
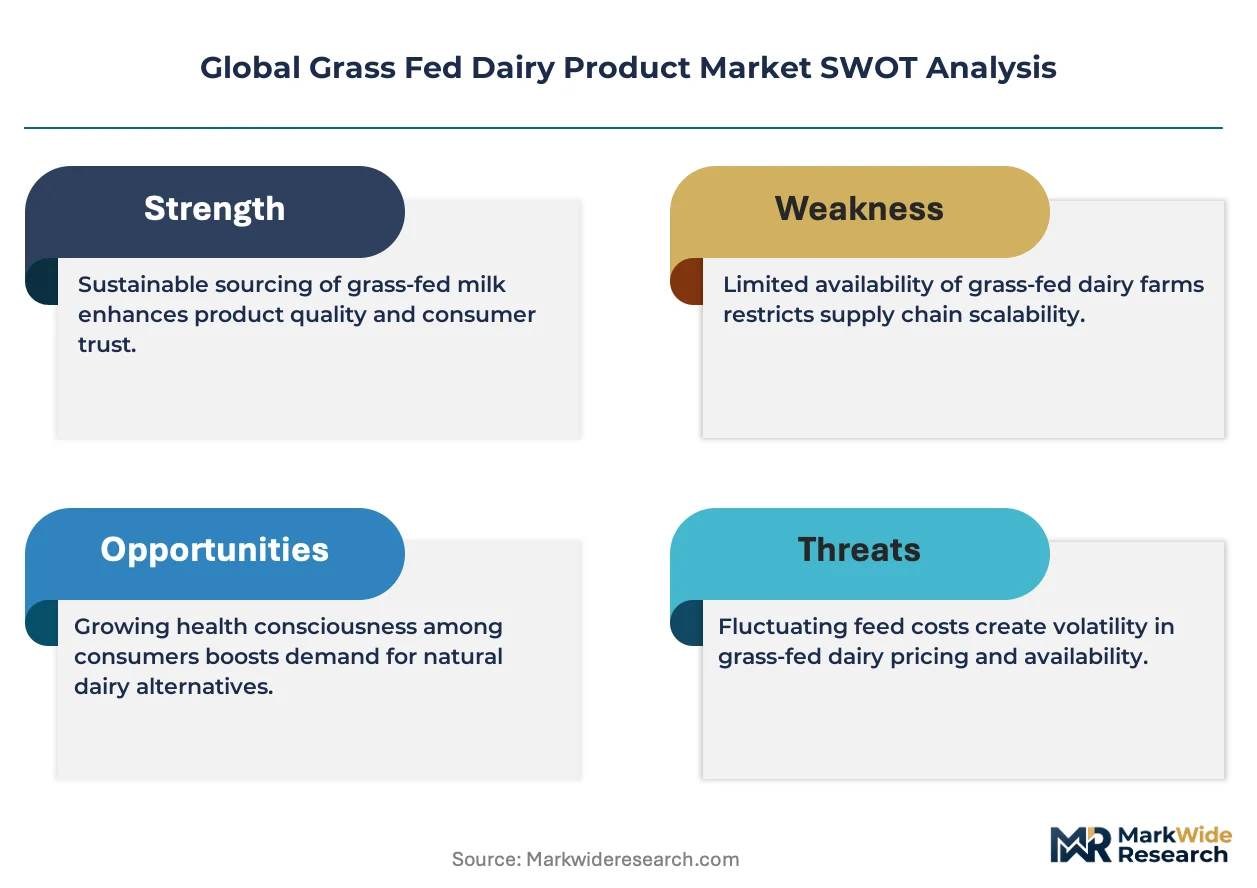
Growth Catalysts
- Nutritional Supplement Demand:The supplement sector’s search for high-protein, clean-label ingredients like milk isolates creates a significant demand stream for grass-fed derivatives.
- Regulatory Frameworks:Organic standards from the EU and USDA reinforce consumer trust in grass-fed claims, justifying premium pricing and creating market barriers.
- Favorable Geographies:Extensive pastureland in Australia and New Zealand supports large-scale production, anchoring the global supply of grass-fed dairy commodities.
Market Restraints
- Higher Production Costs:Pasture-based systems require more land than conventional feedlots, resulting in a higher operational cost structure for dairy producers.
- Supply Chain Constraints:A limited number of certified farms and processors creates supply bottlenecks, restricting the ability to scale production quickly.
- Threat from Substitutes:Plant-based milks, especially from oat and almond, compete on health and sustainability claims, presenting a direct substitution risk.
Strategic Opportunities
- Emerging Market Penetration:Targeting health-conscious consumers in urban centers across China and Southeast Asia offers a major growth avenue for branded products.
- Ingredient Diversification:Developing grass-fed ingredients like lactoferrin opens access to high-value medical nutrition and infant formula end-use markets.
- Channel Innovation:Online direct-to-consumer models allow producers to bypass retail, capture higher margins, and build brand loyalty with end-users.
Industry Challenges
- Certification Complexity:Producers must navigate a fragmented landscape of national and private grass-fed standards, such as those from the American Grassfed Association, creating compliance burdens.
- Climate Vulnerability:Dependence on pasture makes supply chains susceptible to droughts and floods, which can decimate forage availability and disrupt milk production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Grass Fed Dairy Product Market |
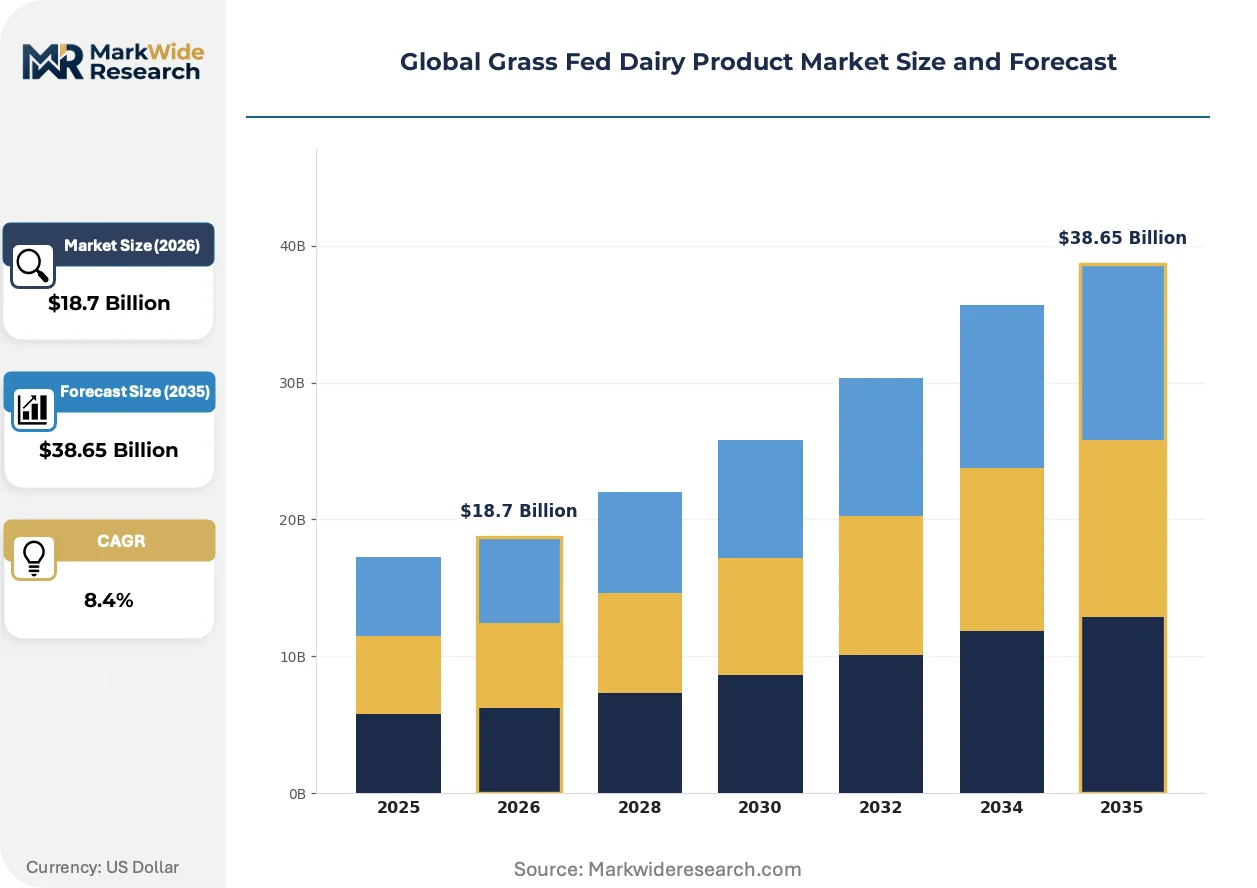
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Butter Application: Dairy Foods, Bakery Products, Nutritional Supplements, Ice Cream Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Direct Sales End User: Households, Food Service, Retailers, Restaurants |
| Companies Covered | Organic Valley, Maple Hill Creamery, Straus Family Creamery, Horizon Organic, Alexandre Family Farm, Vital Farms, Stonyfield Farm, Clover Sonoma, Meyenberg Goat Milk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Grass Fed Dairy Product Market Strategic Shifts & Innovations
Digital traceability and advanced agricultural technologies are fundamentally altering the grass-fed dairy sector. These innovations are enhancing operational efficiency on the farm while providing consumers with verifiable proof of product claims, strengthening brand trust.
Precision agriculture technologies, including soil moisture sensors and satellite pasture monitoring, provide real-time data on forage quality and availability. Dairy cooperatives and large-scale farms are steadily adopting these tools to optimize grazing rotations. This data-driven approach is automating forage management decisions, ensuring consistent feed quality and maximizing land productivity.
Labeling regulations are becoming more stringent to combat unsubstantiated claims in the marketplace. For instance, the USDA's grass-fed marketing claim standard requires detailed documentation to support on-package logos. This affects all brands selling in the United States, forcing them to implement robust supply chain verification systems to maintain consumer confidence and regulatory compliance.
Consumer purchasing behavior is shifting towards a demand for radical transparency regarding product origins and animal welfare. This trend diminishes the impact of traditional advertising, elevating the importance of on-pack QR codes that link to farm-level data. This is most visible in European markets like Germany and France, where shoppers use mobile apps to verify claims at the shelf.
Global Grass Fed Dairy Product Market Segmentation
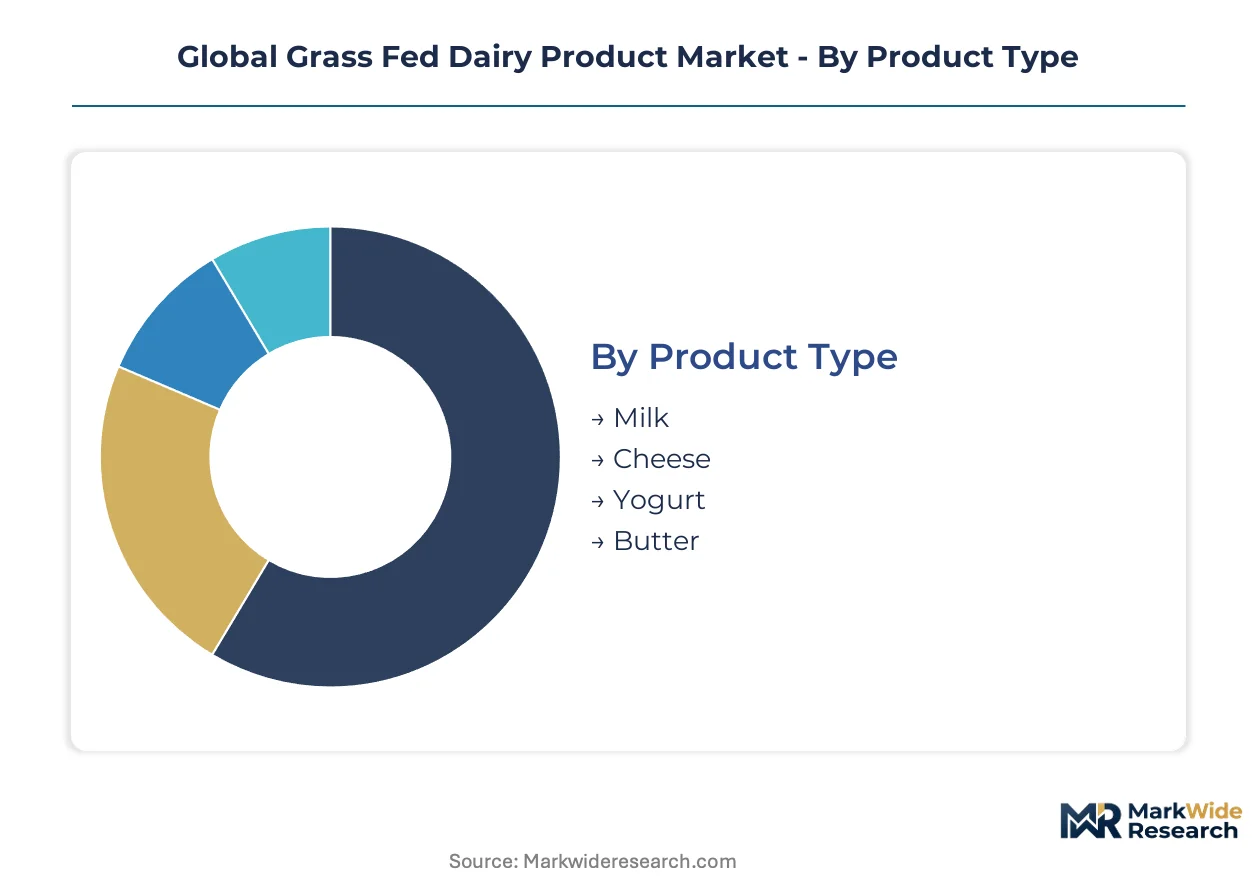
Grass-fed dairy market segmentation reveals distinct value propositions and operational requirements across its various facets. Understanding these categories helps producers align investments with consumer preferences and distribution efficiencies. This analysis highlights the specialized infrastructure needed for different product forms and end-use applications.
Product Type:
The capital intensity required for processing grass-fed dairy varies significantly by product type, influencing production scale and market entry barriers.
- Milk:Fluid milk represents the foundational product, characterized by minimal processing beyond pasteurization and homogenization. Demand concentrates in developed markets like the United States and Europe, driven by daily consumption habits and health consciousness.
- Yogurt:Grass-fed yogurt involves fermentation processes and specific cultures, often requiring specialized equipment for texture and consistency. Its demand is increasing in health-conscious consumer segments globally, fueled by probiotic benefits and clean-label trends.
- Cheese:Grass-fed cheese production requires significant aging infrastructure and specialized cheesemaking techniques.
- Butter:Grass-fed butter, recognized for its higher Conjugated Linoleic Acid content, involves churning cream, a process requiring dedicated equipment.
Most installed capacity flows through Milk. Expansion is steepest in Yogurt.
Application:
The application of grass-fed dairy products dictates pricing tiers and the specific functional attributes required by end-users.
- Nutritional Supplements:This application utilizes grass-fed dairy for high-protein isolates and concentrates, demanding stringent quality control and processing to preserve protein integrity. Demand is strong in North America and Western Europe, driven by an aging population and athletic performance markets.
- Dairy Foods:This segment encompasses direct consumption of grass-fed milk, cheese, and yogurt, where product freshness and sensory attributes are paramount. Consumer interest in these core dairy items is robust across Australia and New Zealand, emphasizing natural ingredients.
- Ice Cream:Grass-fed ice cream leverages the premium perception of its ingredients, targeting consumers seeking indulgent, natural options.
- Bakery Products:Grass-fed dairy ingredients enhance the nutritional profile and flavor of baked goods, appealing to artisanal and health-focused bakeries.
The largest volume of grass-fed dairy products is consumed in Dairy Foods. Nutritional Supplements exhibit rapid uptake.
Distribution Channel:
Different distribution channels cater to distinct customer types, each presenting unique logistical challenges and market access strategies for grass-fed dairy producers.
- Supermarkets:These large-format stores serve as the primary channel for mass-market grass-fed dairy products, relying on established supply chains and brand recognition. This channel dominates sales in urban centers globally, offering convenience and competitive pricing.
- Online Retail:E-commerce platforms provide direct access to niche grass-fed brands and specialized products, often bypassing traditional retail markups. Growth is particularly strong in regions with high internet penetration like China and the United States, enabling wider consumer reach.
- Specialty Stores:Specialty stores, including health food shops, offer curated selections of premium grass-fed dairy, emphasizing provenance and unique product attributes.
- Direct Sales:Direct sales models, such as farm-to-consumer schemes, build strong brand loyalty and allow producers to capture higher margins.
Supermarkets command the largest market share for grass-fed dairy distribution. Online Retail is quickly gaining ground.
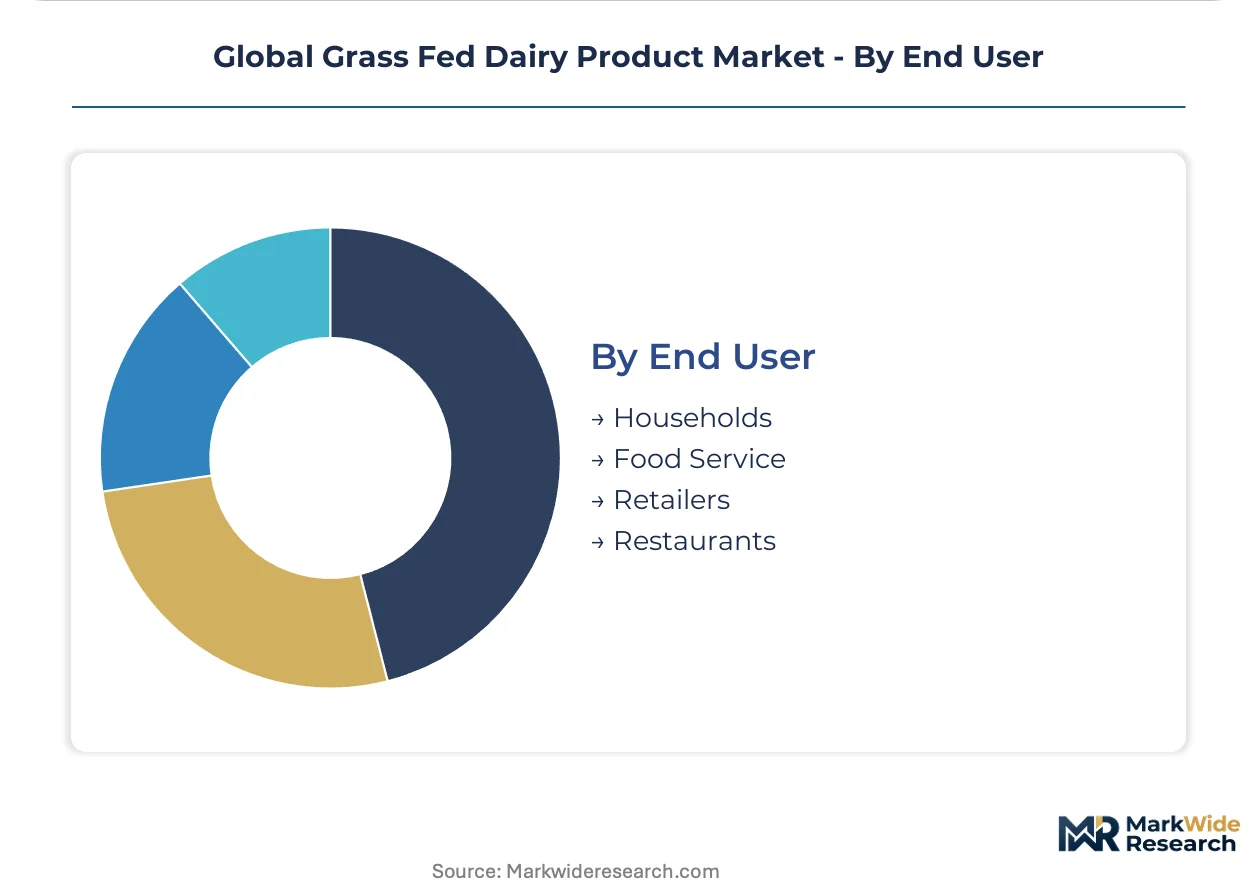
End User:
The end-user segment for grass-fed dairy products significantly influences product formulation, packaging, and the potential for premium pricing and margin capture.
- Households:Individual consumers and families represent the largest end-user group, purchasing grass-fed dairy for direct consumption and home cooking. This segment is driven by health consciousness and ethical considerations, particularly in Western European and North American markets.
- Food Service:This segment includes institutions, catering companies, and cafeterias, requiring bulk quantities and consistent supply of grass-fed dairy ingredients. Demand is expanding in corporate and educational sectors, seeking healthier menu options.
- Retailers:Retailers, distinct from supermarkets, procure grass-fed dairy products for resale, focusing on inventory management and merchandising.
- Restaurants:Restaurants leverage grass-fed dairy to differentiate menus and appeal to customers seeking high-quality, sustainably sourced ingredients.
Households show the highest adoption rate for grass-fed dairy products. Adoption in Food Service is steadily increasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia and New Zealand represent a significant production hub for grass-fed dairy products. Extensive pastureland supports large-scale operations, meeting both domestic and export demand. This region's established infrastructure anchors global supply chains for grass-fed commodities.
Australia
Demand for grass-fed dairy products in Australia stems from a strong consumer preference for natural ingredients and ethical farming. The country's national food standards, overseen by Food Standards Australia New Zealand (FSANZ), ensure product quality and labeling accuracy. Dairy farms in Victoria and Tasmania focus on optimized grazing management to maximize milk yield and nutritional profiles.
New Zealand
New Zealand's grass-fed dairy sector benefits from its pristine environment and a global reputation for high-quality exports. The Ministry for Primary Industries (MPI) enforces strict animal welfare and environmental regulations for dairy farming. The Waikato region, a major dairy hub, sees continuous investment in pasture monitoring technologies to enhance forage quality.
United States
Consumer interest in the United States drives demand for grass-fed fluid milk and yogurt, emphasizing health benefits like higher omega-3s. The USDA's grass-fed marketing claim standard provides a regulatory framework for product labeling and consumer trust. California's dairy industry, particularly in the Central Valley, adapts grazing practices to meet certification requirements.
Germany
Germany exhibits a strong consumer base for organic and grass-fed dairy, prioritizing animal welfare and product transparency. EU organic farming regulations dictate production standards, reinforcing consumer confidence in these premium products. Bavarian dairy cooperatives are integrating advanced traceability systems to provide farm-to-shelf verification.
China
China's emerging market for grass-fed dairy products is fueled by a health-conscious urban population seeking premium nutritional ingredients. The General Administration of Customs of China (GACC) regulates imported dairy products, ensuring safety and compliance. Major cities like Shanghai and Beijing are seeing increased availability of branded grass-fed dairy through online retail channels.
Global Grass Fed Dairy Product Market Key Industry Players
Global majors compete with regional champions across supply chain integrity and brand differentiation within the grass-fed dairy market. The market structure exhibits fragmentation, with numerous smaller, specialized producers alongside larger conventional dairy companies offering grass-fed lines. Strategic archetypes include vertically integrated farm-to-table brands and ingredient suppliers targeting the nutritional supplement sector. Companies pursue strategic partnerships and geographic expansion to secure raw material supply and reach new consumer bases.
Specialists in 100% grass-fed dairy, like Maple Hill Creamery, exemplify brands built entirely on this premium positioning, differentiating themselves in a crowded marketplace. Organic Valley, operating as a cooperative, represents a model focused on securing a consistent supply of certified grass-fed milk from its member farms, ensuring product consistency and ethical sourcing. Straus Family Creamery further occupies a position emphasizing artisanal quality and sustainable farming practices, often targeting niche consumer segments. These companies collectively anchor the market by providing verifiable product benefits to a discerning consumer base, influencing overall market standards.
| Leading Market Players |
|---|
| Organic Valley |
| Maple Hill Creamery |
| Straus Family Creamery |
| Horizon Organic |
| Alexandre Family Farm |
| Vital Farms |
| Stonyfield Farm |
| Clover Sonoma |
| Meyenberg Goat Milk |
Cost & Logistics Intelligence
Global dairy commodity prices, influenced by feed costs and international trade, cascade through the grass-fed dairy supply chain, establishing distinct pricing tiers for premium products. This dynamic shapes producer margins and consumer accessibility.
Pricing Analysis
Input costs for pasture-based feed systems significantly influence the final price points for grass-fed dairy products. Pricing stratifies across premium, standard, and economy tiers, driven by certification level adherence and brand recognition. Pricing pressure stems from competition with conventional dairy and plant-based alternatives. Households, particularly those seeking basic dairy items, exhibit the highest price sensitivity, while nutritional supplement manufacturers show lower sensitivity for specialized ingredients.
Supply Chain Analysis
Regional distribution centers and a hub-and-spoke logistics network manage the flow of grass-fed dairy products from farms to retailers. Geographic supply concentration centers on Australia and New Zealand, which draw from extensive pastureland. Raw material dependencies include fresh pasture forage and specialized processing equipment for products like yogurt. Climate vulnerability, especially droughts and floods, represents a significant structural risk to forage availability. Distribution runs through supermarkets for mass-market products and online retail for niche brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global grass-fed dairy market functions as a stable compounder, driven by sustained consumer demand for health-conscious and ethically sourced food products. This underlying trend ensures consistent, incremental growth.
For Market Incumbents: To counter the threat from plant-based milk substitutes, established dairy brands must invest in robust certification processes and communicate verifiable product benefits. Expanding processing capacity in favorable geographies like New Zealand strengthens supply chain resilience. Deepening vertical integration into feed management technologies ensures consistent forage quality.
For New Entrants and Emerging Players: Online direct-to-consumer platforms offer a powerful channel to reach health-conscious consumers in urban centers across China. Targeting specialized niches like grass-fed infant formula provides a high-value entry point. A go-to-market angle emphasizing farm-to-table traceability builds consumer trust and brand loyalty.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap companies demonstrating strong supply chain integrity and brand differentiation in premium segments. Long-term viability for the sector remains strong over the next five to ten years, supported by evolving consumer preferences. The signal to watch is the adoption rate of advanced traceability technologies across the value chain.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Certified Pastureland | Secures raw material supply and meets stringent organic standards for dairy producers. |
| Invest in Digital Traceability Systems | Enhances consumer trust by providing verifiable proof of product origin and animal welfare. |
| Develop Grass-Fed Protein Isolates | Captures high-value demand from the rapidly expanding nutritional supplements sector. |
| Strengthen Online Retail Presence | Expands market access for niche brands and bypasses traditional retail distribution bottlenecks. |
| Form Strategic Partnerships with Farmers | Ensures consistent supply of certified grass-fed milk and supports ethical sourcing practices. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, validating market size and growth projections. Primary research involved discussions with dairy farm owners, feed suppliers, nutritional supplement formulators, and retail category managers. Secondary validation drew from USDA reports, EU organic farming regulations, and trade association publications like those from the American Grassfed Association. Bottom-up and top-down triangulation ensured data consistency.
The segment-weighting approach informed the market forecast, integrating volume and value projections across the analysis window. Segmentation dimensions included product type, application, distribution channel, end user, and certification level. Compound annual growth rates were derived by assessing historical trends and projected demand drivers. Key forecast inputs included pastureland availability and consumer health trend shifts towards clean-label ingredients.
The model assumes a particular technology adoption path; alternative pathways for precision agriculture tools would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and consumer purchasing behavior. Climate vulnerability, impacting forage supply, and the competitive threat from plant-based alternatives represent specific risk factors. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Africa Yogurt Market
Dairy Products
Sour Cream Market
Dairy Products
Probiotic Cheese Market
Dairy Products
China Lactose-Free Dairy Market
Dairy Products
Global Lipolyzed Butter Fat Market
Dairy Products
Skimmed Milk Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Dairy Concentrates Market
Dairy Products
Low Fat Butter Market
Dairy Products
Probiotic Dairy Products Market
Dairy Products
Milk Protein Hydrolysate Market
Dairy Products
Kefir Market
Dairy Products
Cream and Soft Cheese Market
Dairy Products
North America Organic Dairy Market
Dairy Products
Organic Dairy Market
Dairy Products
Donkey Milk Market