
 Parmesan Cheese Market | 2026-2036
Parmesan Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Parmesan Cheese Market Analytics
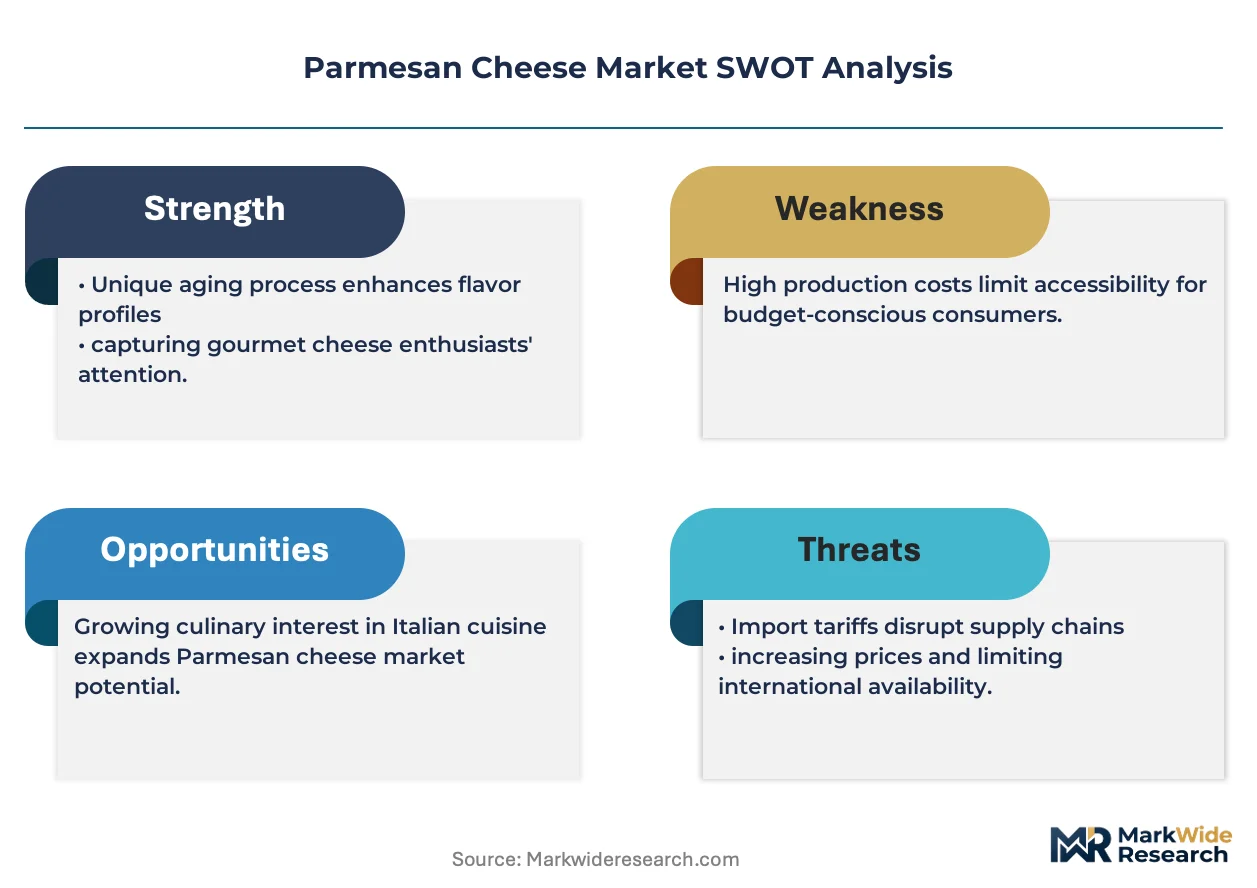
The split between premium aged wheels and mass-market grated formats is hardening as private-label commoditization pressures branded block positioning. Groupe Lactalis leverages its European dairy network to dominate protected-origin production. Saputo Inc. anchors North American supply through large-scale grating and shredding operations. BelGioioso Cheese Inc. differentiates via specialized Italian-style aging in domestic U.S. facilities.
Parmesan cheese denotes a hard, granular cow's milk cheese aged minimum twelve months, with Protected Designation of Origin varieties requiring raw milk, natural whey starter, and copper vat processing to develop crystalline tyrosine deposits and proteolytic flavor compounds. Grated formats lead retail velocity due to convenience positioning, while block sales sustain higher per-unit margins among enthusiast consumers. Food service applications represent the fastest-expanding application channel as restaurant chains standardize back-of-house efficiency. Vacuum-sealed packaging captures premium shelf-life extension, whereas bulk formats dominate institutional procurement.
EU regulations through EFSA and the Parmigiano Reggiano Consortium enforce geographic indication protections that restrict "Parmesan" labeling for non-Italian production entering European markets. The U.S. FDA maintains standards of identity for hard grating cheeses without equivalent geographic restriction, enabling domestic manufacturers to compete under similar nomenclature. Stakeholders must monitor ongoing trade negotiation developments between the European Union and major import markets, as designation enforcement terms could reshape competitive access and labeling requirements across jurisdictions.
Market Dynamics
The split between premium aged wheels and mass-market grated formats is hardening as private-label commoditization pressures branded block positioning. Food service operators are driving format innovation while EU designation enforcement reshapes cross-border trade flows.
Growth Catalysts
- EU Protected Designation of Origin frameworks:The Parmigiano Reggiano Consortium and Grana Padano regulations enforce geographic authentication, creating premium pricing tiers that validate aged hard cheese investments and sustain producer margins across Italian supply chains.
- Food service menu expansion:Restaurant chains in the United States and Canada are standardizing back-of-house efficiency through pre-grated formats, accelerating volume procurement and creating dedicated supply contracts for institutional-grade product.
- Retail convenience positioning:Shredded and grated formats dominate household purchasing patterns as time-constrained consumers prioritize preparation speed over block cheese rituals, driving velocity in mass-market channels.
Market Restraints
- Raw milk input volatility:Fluctuations in Italian dairy farm output and feed cost inflation constrain Parmigiano Reggiano production capacity, limiting supply elasticity for aged wheel inventories.
- Supply concentration in Emilia-Romagna:Protected-origin production clusters within a narrow Italian geography, exposing buyers to regional climate disruption and logistics bottlenecks.
- Plant-based cheese substitution:Fermented protein alternatives from precision fermentation startups are capturing lactose-intolerant and flexitarian consumers in North American retail.
Strategic Opportunities
- Underpenetrated Asian markets:Japan and South Korea show rising appetite for Western aged cheeses through specialty retail and hospitality channels, with limited domestic competition.
- Vacuum-sealed premium packaging:Extended shelf-life technology enables direct-to-consumer subscription models and reduces retail shrink, opening e-commerce white space.
- Carbon labeling alignment:EU Green Deal farm-to-fork traceability requirements favor producers with verified low-methane dairy sourcing, creating differentiation for early adopters.
Industry Challenges
- Affineur skill scarcity:The twelve-to-thirty-six month aging process demands trained palate assessment for quality grading, with fewer apprentices entering traditional Italian cooperatives.
- Copper vat replacement cycles:Protected-origin mandates require capital-intensive equipment that European dairies must maintain or replace under tightening environmental discharge rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parmesan Cheese Market |
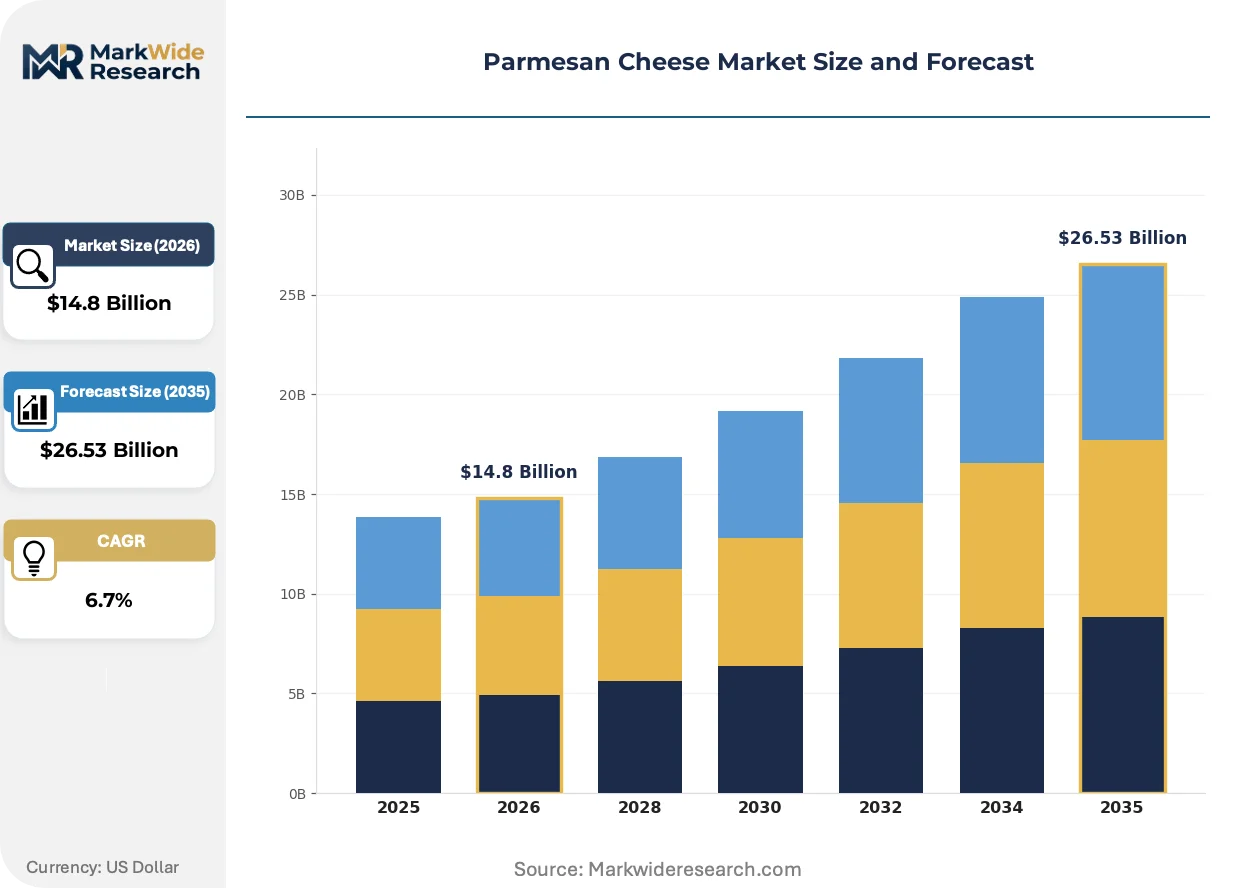
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grated, Block, Shredded, Fresh Application: Culinary, Food Service, Retail, Confectionery Packaging Type: Vacuum Sealed, Bagged, Jarred, Bulk End User: Households, Restaurants, Cafes, Catering Services |
| Companies Covered | Sargento Foods Inc., Arla Foods AMBA, Saputo Inc., Groupe Lactalis, 4C Foods Corp., BelGioioso Cheese Inc., Organic Valley, Parmalat S.p.A, The Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parmesan Cheese Market Evolving Landscape
Automation in grading and packaging is compressing labor intensity while digital traceability systems reshape consumer trust mechanisms. These shifts are altering competitive advantage sources across the value chain.
NIR spectroscopy for real-time quality assessment is consolidating manual grading workflows. Large-scale grating operations in Wisconsin and California are deploying these systems to standardize particle size and moisture detection. This technology is consolidating quality control labor into centralized facilities, reducing per-unit inspection costs and enabling continuous production runs.
EFSA is tightening residue monitoring for veterinary pharmaceuticals in dairy imports, with expanded testing protocols for third-country suppliers. Italian exporters face heightened documentation requirements for whey starter cultures and copper vat maintenance logs. North American manufacturers without equivalent supply chain visibility are encountering border inspection delays and certificate-of-origin disputes.
Direct sourcing from affineurs is displacing traditional distributor layers for specialty food retailers. Boutique grocers in New York and San Francisco are establishing exclusive wheel allocation contracts, bypassing regional wholesalers. This channel compression is most visible in urban coastal markets where provenance storytelling commands shelf placement premiums.
Parmesan Cheese Market Segmentation
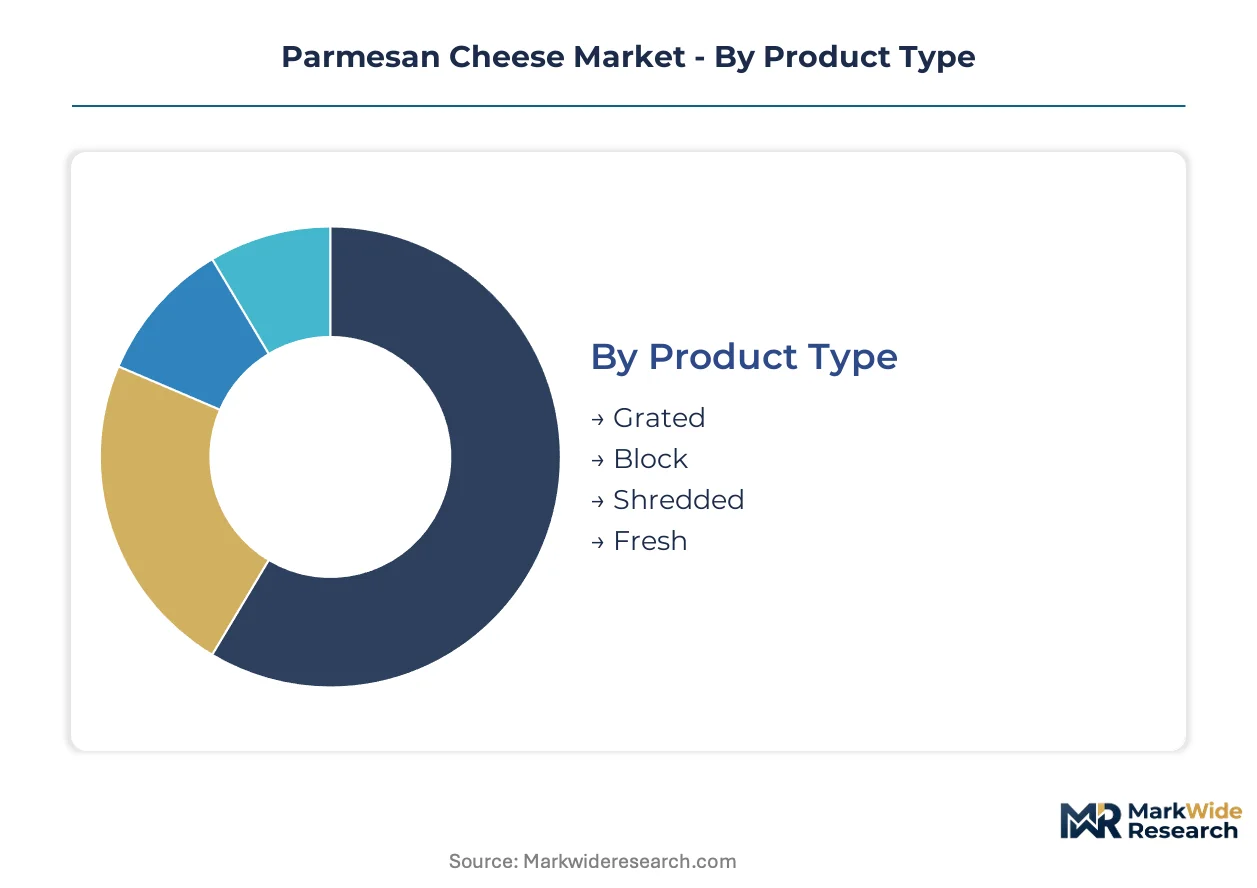
Parmesan cheese segmentation reveals divergent margin structures across convenience-oriented formats versus aging-intensive traditional production. Understanding these splits enables suppliers to align capacity investments with channel-specific velocity patterns and authentication requirements.
Product Type:
Grated and block formats occupy opposite ends of the value chain integration spectrum, with shredded bridging both convenience and authenticity positioning.
- Grated:Pre-ground particles sized for immediate recipe incorporation, typically packaged with anti-caking agents. United States retail channels concentrate procurement here, driven by time-constrained household preparation habits and pizza chain back-of-house standardization.
- Block:Intact wheels or cut portions requiring consumer-side grating, preserving volatile flavor compounds and crystalline texture. Enthusiast segments in specialty grocers sustain demand, with Italian protected-origin wheels commanding authentication premiums through direct affineur relationships.
- Shredded:Ribbon-cut formats balancing convenience with visible cheese identity, common in food service salad and pasta applications.
- Fresh:Unaged or minimally aged varieties with higher moisture content, limited to regional Italian consumption and specialty import channels.
Grated leads volumes today; block is gaining share fastest among premium-positioned retailers.
Application:
End-use concentration determines format specifications, with culinary authenticity requirements diverging sharply from operational efficiency priorities in institutional settings.
- Food Service:Restaurant chains and institutional kitchens drive bulk procurement of pre-processed formats. Back-of-house labor cost reduction in United States quick-service operators accelerates dedicated supply contracts for shredded and grated product.
- Retail:Grocery channels split between mass-market convenience packaging and specialty counter service for authenticated wheels. Private-label commoditization pressures branded positioning in grated segments.
- Culinary:Professional kitchen and recipe-development applications prioritize flavor intensity and melting behavior over cost minimization.
- Confectionery:Niche incorporation into filled chocolates and savory confections, primarily in European artisanal production.
Food service commands procurement scale; retail sustains margin premiums through format diversification.
Packaging Type:
Preservation technology and handling economics segment the market across shelf-life extension and institutional volume requirements.
- Vacuum Sealed:Oxygen-exclusion technology extends retail shelf life for premium block portions, enabling direct-to-consumer subscription models and reducing shrink in specialty channels.
- Bagged:Flexible packaging dominates grated and shredded mass-market distribution, balancing unit economics with resealability for household use.
- Jarred:Rigid containers with moisture barriers for refrigerated grated products, common in United States conventional grocery.
- Bulk:Food service totes and institutional formats prioritize per-pound cost over individual unit presentation.
Vacuum sealed captures premium positioning; bagged maintains volume leadership across retail.
End User:
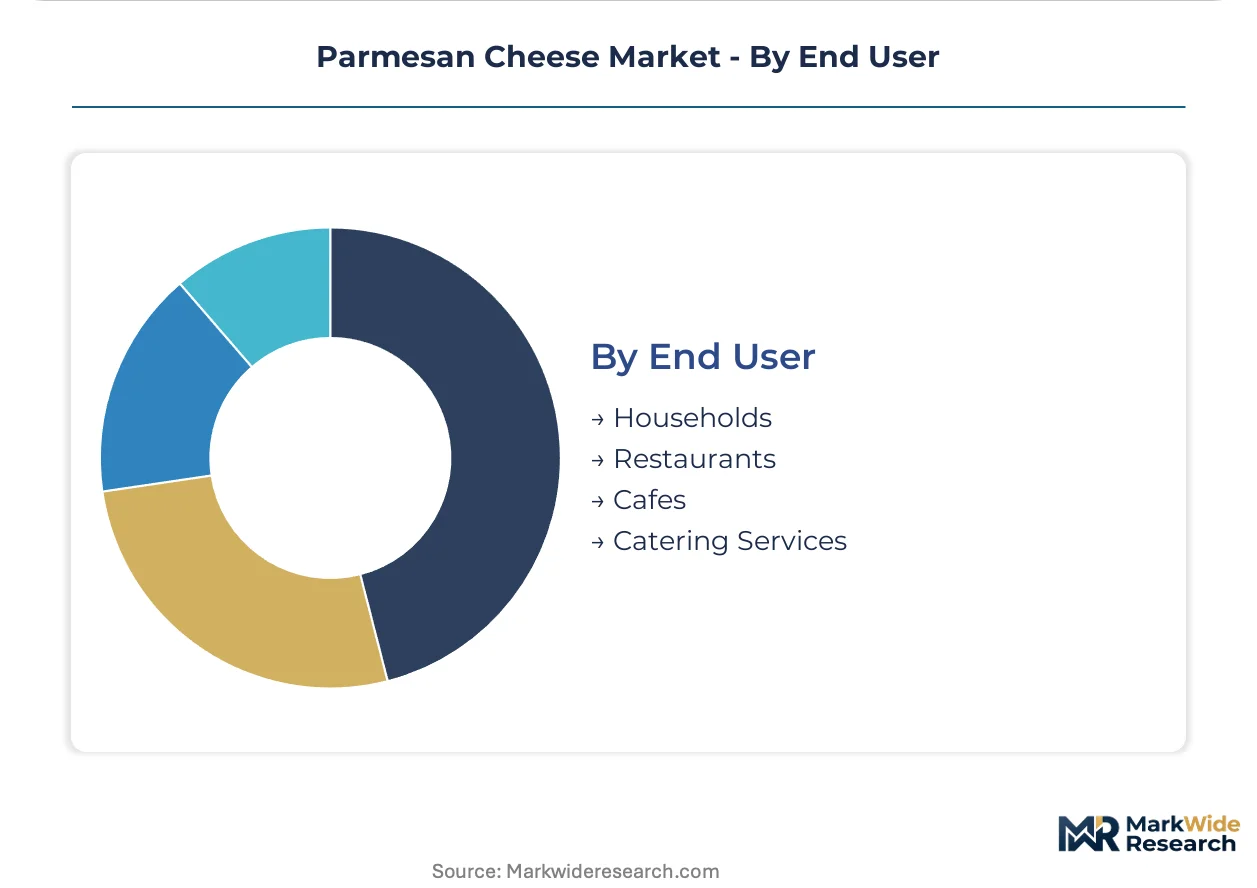
Customer-type segmentation reflects divergent purchasing rhythms, with household convenience orientation contrasting against operational procurement patterns in out-of-home consumption.
- Households:Time-constrained consumers in United States and Canadian markets prioritize grated and shredded formats for weeknight meal preparation, with authentication interest concentrated among urban coastal demographics.
- Restaurants:Chain operators standardize ingredient specifications across locations, creating dedicated supply relationships for institutional-grade product with consistent particle size and moisture parameters.
- Cafes:Limited-service operators with simpler menu applications, often sourcing through broadline distributors rather than direct dairy procurement.
- Catering Services:Event-based volume procurement with seasonal demand spikes, favoring bulk formats and flexible delivery scheduling.
Households anchor retail velocity; restaurants drive food service contract consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian affineurs and Wisconsin master cheesemakers anchor the industry's geographic talent base. Their expertise in copper vat processing and long-aging protocols shapes production quality standards across both protected-origin and domestic supply chains.
United States
Food service chains and retail private-label buyers drive grated format procurement at scale. The FDA maintains standards of identity for hard grating cheeses without geographic restriction, enabling domestic nomenclature parity. Wisconsin and California host large-scale shredding operations supplying institutional accounts.
Italy
Protected-designation wheels from Emilia-Romagna command authentication premiums in specialty import channels. EFSA enforces residue monitoring and traceability documentation for whey starter cultures and copper vat maintenance. Parma and Reggio Emilia concentrate affineur expertise for Parmigiano Reggiano grading.
Canada
Cross-border dairy integration supports ingredient supply for U.S. grating operations while domestic retail concentrates in Ontario and Quebec. Health Canada regulates dairy imports through CFIA inspection protocols. Quebec's specialty cheese sector develops Italian-style aged hard varieties for regional distribution.
Japan
Specialty retail and hospitality channels show expanding appetite for Western aged cheeses with limited domestic competition. METI oversees food import standards and labeling requirements for dairy products. Tokyo and Osaka concentrate high-end restaurant procurement through dedicated importers.
Germany
Retail and food service distribution serves as a gateway for Italian protected-origin wheels into Central European markets. EFSA-aligned regulations enforce geographic indication protections at the border. Munich and Frankfurt anchor wholesale dairy trading for aged hard cheese redistribution.
Parmesan Cheese Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the value chain integration spectrum. Protected-origin wheel aging demands substantial fixed-asset commitment in copper vats and climate-controlled storage, while grated format processors operate with lower capital intensity and faster inventory turns. Three archetypes dominate: Italian cooperative consortia managing geographic indication compliance, North American dairy processors optimizing food service scale, and specialty affineurs cultivating direct retail relationships. Consolidation pressures concentrate procurement leverage among institutional buyers, while authentication differentiation sustains premium positioning for designated-origin suppliers.
Within the North American processing tier, Saputo Inc. and BelGioioso Cheese Inc. exemplify divergent strategic positions. Saputo anchors large-scale grating and shredding capacity serving chain restaurant accounts. BelGioioso occupies a specialty niche through Italian-style aging in domestic U.S. facilities. Groupe Lactalis represents the integrated multinational archetype, leveraging European dairy network density to dominate protected-origin production while extending grated format presence across Atlantic markets.
| Leading Market Players |
|---|
| Sargento Foods Inc. |
| Arla Foods AMBA |
| Saputo Inc. |
| Groupe Lactalis |
| 4C Foods Corp. |
| BelGioioso Cheese Inc. |
| Organic Valley |
| Parmalat S.p.A |
| The Kraft Heinz Company |
| Others |
Value Network & Pricing Analysis
EU Green Deal farm-to-fork traceability requirements gate qualified supply for premium-tier Parmesan access, as verified low-methane dairy sourcing becomes a threshold condition for authentication premiums in protected-origin channels. Buyers without documented carbon-aligned procurement face exclusion from specialty retail allocations where provenance storytelling commands shelf placement premiums.
Pricing Analysis
The bundled-vs-unbundled service split separates wheel-and-aging contracts from commodity grated transactions. Three-tier pricing structure across Parmigiano Reggiano wheels, domestic aged blocks, and private-label grated sustains margin stratification, with certification grade and volume scale as primary price differentiation drivers. Cost compression in mass-market grated segments is intensifying because private-label commoditization pressures branded positioning. Food service chain operators show least price sensitivity through dedicated supply contracts, while household retail purchasers in conventional grocery channels exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Emilia-Romagna's concentrated protected-origin production, where Italian copper vat processing and Wisconsin large-scale grating operations anchor divergent supply tiers. Raw milk inputs draw from Lombardy and Po Valley dairy farms, while whey starter cultures and copper vat equipment rest on narrow supplier bases. Tariff exposure from EU designation enforcement reshapes cross-border trade flows for non-Italian product. Distribution runs through direct affineur relationships for premium wheels and broadline distributors for institutional grated formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Parmesan market reads as a late-cycle quality story, justified by food service chain procurement shifting toward authenticated aged wheels for menu differentiation. This demand migration favors suppliers with verifiable provenance documentation and extended aging capacity.
For Market Incumbents: Extend aging facility footprints in climate-controlled storage to capture authentication premiums, and deepen backward integration into low-methane dairy sourcing to meet EU Green Deal traceability thresholds. Plant-based cheese substitution from precision fermentation startups threatens lactose-intolerant and flexitarian segments in North American retail, making certification investment the priority defensive lever. For New Entrants and Emerging Players: Enter via vacuum-sealed direct-to-consumer subscription models targeting Japan and South Korea specialty retail, where Western aged cheese appetite expands with limited domestic competition. The most penetrable white space sits in Asian hospitality channels seeking exclusive wheel allocation contracts. A provenance-first go-to-market angle bypasses entrenched broadline distribution layers. For Investors and Strategic Acquirers: Valuations sit cheapest among North American grated-format processors facing margin compression from private-label commoditization. Long-term viability across the projection horizon favors specialty affineurs with direct retail relationships and documented carbon labeling alignment. The signal to watch as inflection indicator is EU trade negotiation developments on geographic indication enforcement terms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Methane Dairy Sourcing | EU Green Deal traceability requirements favor early adopters with verified farm-to-fork documentation. |
| Vacuum-Sealed Packaging Technology Deployment | Extended shelf-life enables direct-to-consumer subscription models and reduces retail shrink in specialty channels. |
| NIR Spectroscopy Quality Assessment Implementation | Real-time grading standardizes particle size and moisture detection for food service chain contracts. |
| Direct Affineur Relationship Cultivation | Boutique grocers in coastal markets bypass regional wholesalers for exclusive wheel allocation contracts. |
| Asian Market Distribution Partnership | Tokyo and Osaka hospitality procurement channels show rising appetite with limited domestic competition. |
Research Methodology
Multiple input streams — primary interviews with Italian cooperative affineurs, North American dairy processors, and food service procurement directors; secondary validation through EFSA residue monitoring protocols, Parmigiano Reggiano Consortium documentation, and U.S. FDA standards of identity — were reconciled through bottom-up production capacity modeling and top-down demand triangulation across the analysis window.
Data-stream reconciliation anchored volume and value outputs to product type segmentation across grated, block, shredded, and fresh formats; application channels spanning food service, retail, culinary, and confectionery; and packaging technology tiers from vacuum-sealed premium to bulk institutional. CAGRs were derived from trend extrapolation of aging capacity expansion, format innovation velocity, and trade flow reconfiguration assumptions, with raw milk input volatility and EU designation enforcement as key forecast sensitivities.
Inputs from Italian cooperative consortia and Wisconsin master cheesemakers were available through the study window; gaps in precision fermentation startup production scale data introduce uncertainty bands around plant-based substitution trajectory assumptions. Forecasts reflect documented assumptions on trade negotiation developments and climate disruption frequency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
UHT Whipping Cream Market
Dairy Products
North America Casein Market
Dairy Products
Japan Dairy Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Recombined Milk Market
Dairy Products
Fermented Dairy Products Market
Dairy Products
Milk Fat Fractions Market
Dairy Products
United States Dairy Market
Dairy Products
United Kingdom Dairy Market
Dairy Products
Non-Fat Milk Market
Dairy Products
Global Milk Protein Market
Dairy Products
Disposable Curd Cups Market
Dairy Products
Europe Milk Protein Market
Dairy Products
Global Dairy Market
Dairy Products
Germany Milk Protein Market
Dairy Products
Skimmed Milk Powder Market