
 Table Butter Market | 2026-2036
Table Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Table Butter Market Intelligence
EU F-Gas Regulation is shifting cold-chain compliance costs toward dairy distributors with temperature-sensitive butter inventories. Fonterra Co-operative Group leverages its New Zealand grass-fed sourcing to sustain premium positioning in export markets. Arla Foods amba anchors its European footprint through cooperative farmer ownership, while Amul dominates India's fragmented dairy landscape with village-level collection infrastructure.
Table butter is a water-in-fat emulsion containing minimum 80% milkfat by weight, produced through churning cream until phase inversion yields a semi-solid plastic mass suitable for spreading, cooking, and baking applications. Unsalted variants command margin premiums in artisanal bakery channels where sodium control determines recipe precision, while whipped butter captures volume growth in household segments seeking spreadability without microwave softening. Pouch packaging is displacing traditional sticks in emerging-market convenience stores, altering shelf-life engineering requirements.
FDA standards in the United States mandate minimum milkfat thresholds and prohibit vegetable oil adulteration in products labeled "butter," preserving category integrity against spread substitutes. BIS certification in India enforces microbiological safety limits that determine market access for organized dairy cooperatives and private processors. Stakeholders must monitor evolving fat-standard definitions as plant-based analogs pressure regulatory boundaries across multiple jurisdictions.
Market Dynamics
The EU F-Gas Regulation is forcing cold-chain infrastructure upgrades across butter distribution networks, compressing margins for temperature-dependent logistics while accelerating investment in alternative refrigeration technologies.
Growth Catalysts
- Commercial bakery expansion:Laminated dough performance requirements in commercial kitchens are elevating butter procurement volumes as chefs prioritize fat consistency for croissant and pastry production.
- FSSAI enforcement modernization:India's food safety regulator is tightening microbiological safety protocols, channeling demand toward organized cooperatives with certified cold-chain capabilities.
- Grass-fed positioning:Pasture-based dairy sourcing from New Zealand is commanding premium shelf placement in export markets seeking provenance differentiation.
Market Restraints
- Feed input volatility:Global grain and oilseed price swings directly compress dairy farm margins, transmitting cost pressure through cream supply contracts.
- Plant-based substitution:Oil-in-water emulsion spreads leveraging shea and coconut fractions are capturing price-sensitive household segments in Western European retail.
- Refrigeration compliance burden:The EU F-Gas phase-down timeline is accelerating capital expenditure requirements for distributors maintaining butter inventories near 4°C.
Strategic Opportunities
- Pouch format penetration:Flexible packaging configurations are displacing traditional sticks in Indian convenience stores, enabling single-serve consumption occasions.
- Artisanal channel premiumization:Unsalted variants with sodium-controlled specifications are capturing margin premiums in specialty bakery supply chains.
- Cooperative infrastructure leverage:Village-level collection networks in Gujarat and Maharashtra are creating captive supply advantages for processors with backward integration into raw milk sourcing.
Industry Challenges
- Cold-chain technician scarcity:Qualified refrigeration maintenance personnel are concentrated in urban centers, complicating rural distribution network reliability.
- Packaging shelf-life engineering:Pouch formats require modified atmosphere and barrier film specifications that extend product stability without artificial preservatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Table Butter Market |
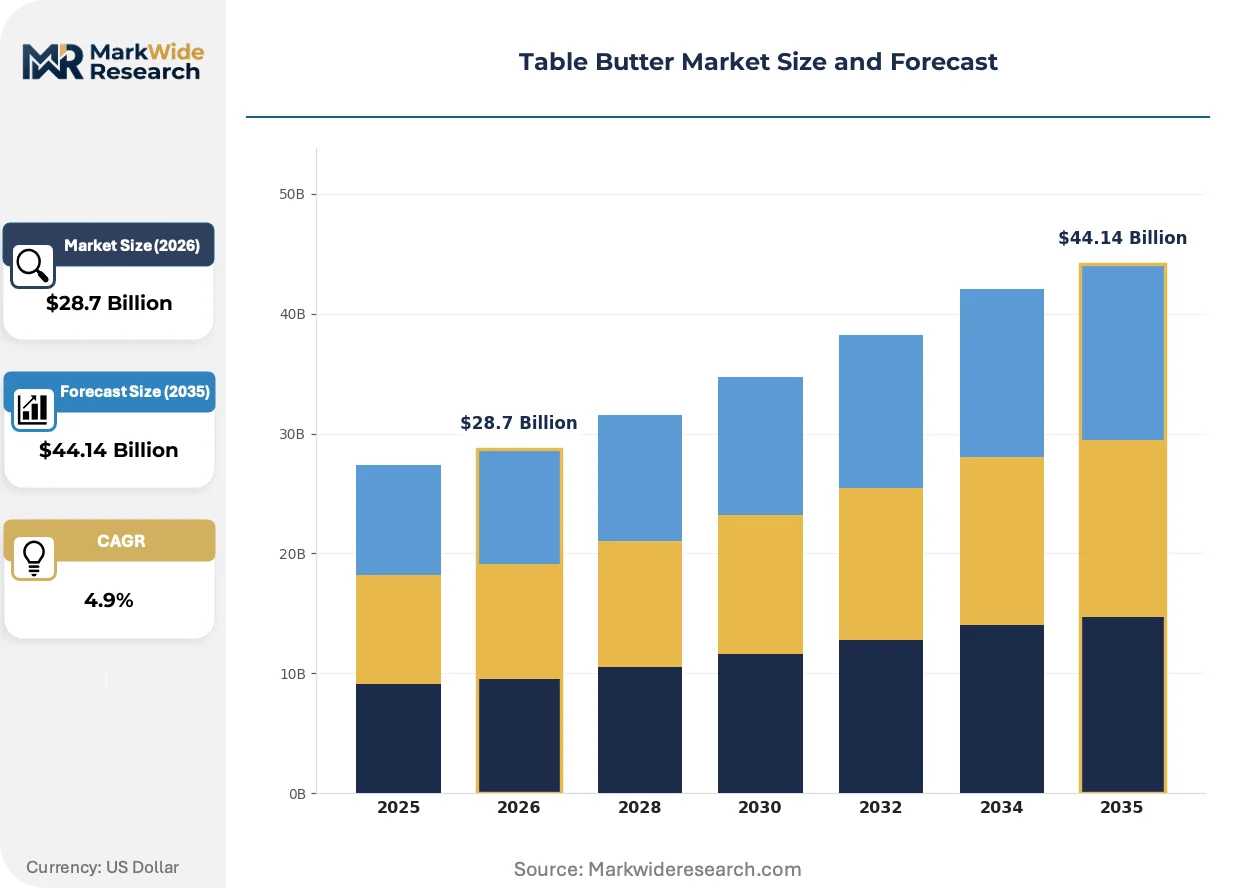
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $44.14 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salted, Unsalted, Whipped, Flavored Packaging Type: Sticks, Tubs, Pouches, Sachets Distribution Channel: Supermarkets, Convenience Stores, Online, Wholesale End User: Households, Food Service, Bakeries, Restaurants |
| Companies Covered | Unilever, Arla Foods amba, Fonterra Co-operative Group, Groupe Lactalis, Land O'Lakes, Ornua Co-operative Ltd., Dairy Farmers of America, The Kraft Heinz Company, Amul, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Table Butter Market Strategic Shifts & Innovations
Processing equipment and packaging formats are converging to address spreadability demands while regulatory pressure on refrigeration chemistry is reshaping capital deployment across distribution infrastructure.
Micro-fixation churn technology is modularizing production line configurations for mid-scale processors. Regional dairy cooperatives in Denmark and Ireland are retrofitting existing creameries with interchangeable processing modules that switch between whipped and traditional butter formats. This modularizing approach is compressing minimum efficient scale thresholds and enabling shorter production runs for specialty variants.
The EU F-Gas Regulation is mandating hydrofluorocarbon phase-downs across transport refrigeration units. Cold-chain operators serving butter inventories are retrofitting vehicle fleets with CO2 transcritical systems or hydrocarbon alternatives ahead of the 2030 compliance deadline. Distributors with cross-border European routes are consolidating temperature-controlled loads to amortize upgraded equipment costs across higher-volume lanes.
Household buyers are prioritizing spreadability without microwave intervention, rotating preference toward aerated and cultured butter formats. Convenience-oriented retail channels in South Korea and Australia are expanding chilled-set allocations for whipped variants that maintain plasticity at standard refrigeration temperatures. This behavior shift is compressing traditional block butter shelf space in urban supermarket formats.
Table Butter Market Segmentation
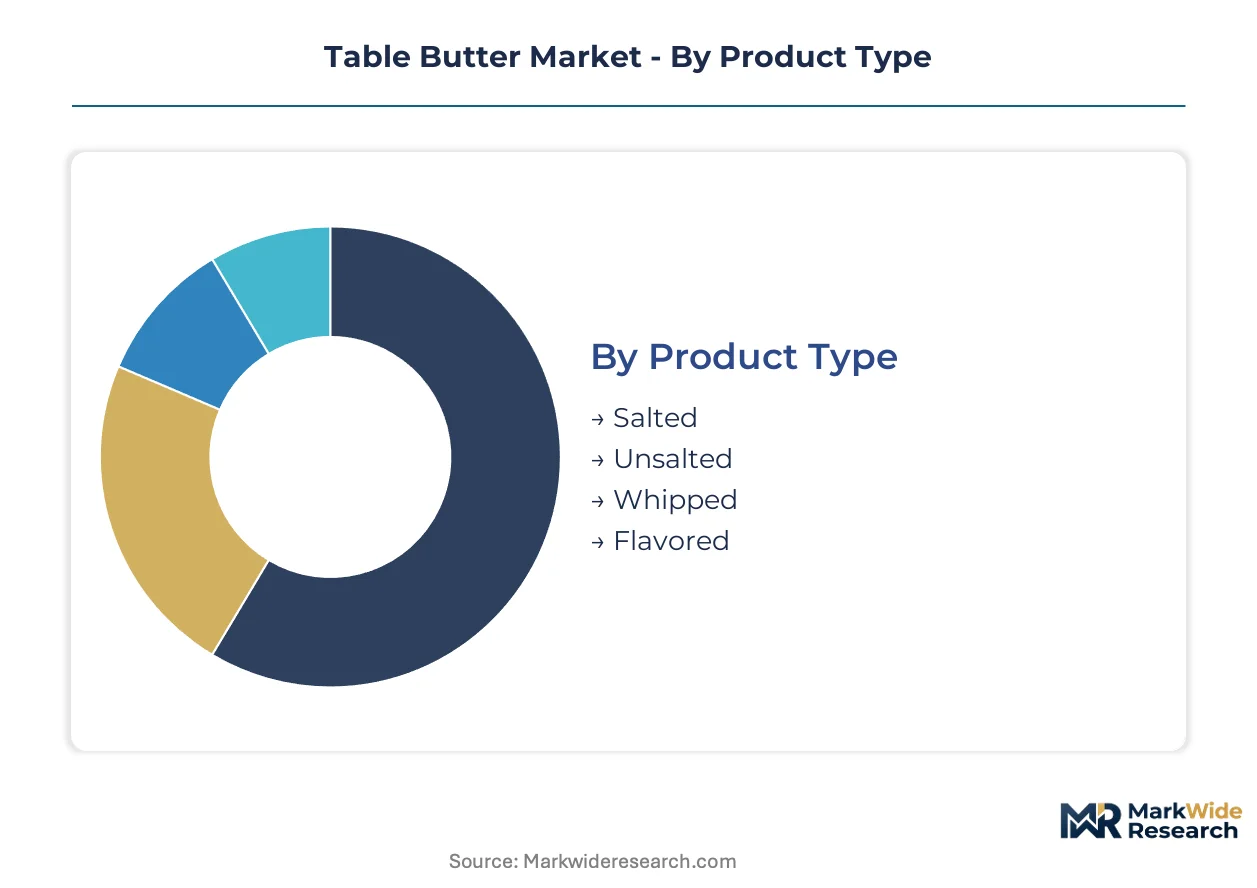
Segmentation in table butter reveals how product specifications, packaging economics, and channel access determine margin capture across distinct use cases. Procurement patterns diverge sharply between industrial bakeries seeking fat consistency and households prioritizing spreadability at refrigeration temperatures.
Product Type:
Unsalted variants operate as standalone inputs requiring precise sodium control, while whipped and flavored formats embed convenience functionality directly into the product architecture.
- Salted:Standard 1.5-2% sodium chloride content extends shelf stability and masks flavor variations from seasonal cream sourcing. Volume concentrates in price-sensitive household segments across India's tier-2 cities where Amul's cooperative distribution maintains cost leadership.
- Unsalted:Contains no added sodium, delivering butterfat purity for laminated dough applications where recipe precision determines pastry texture. Demand clusters in commercial bakery supply chains across France and Denmark, where chefs reject salt interference in fermentation-controlled preparations.
- Whipped:Nitrogen or air incorporation reduces density by 25-40%, improving spreadability at 4°C without microwave softening.
- Flavored:Compound butters with herb, spice, or cultured additions target premium retail and food service channels.
Volume placements concentrate in Salted; the faster expansion belongs to Whipped.
Packaging Type:
Packaging economics stratify by cost tier, with stick formats commanding equipment amortization advantages and pouch configurations minimizing unit economics for emerging-market penetration.
- Sticks:Individually wrapped quarter-pound units wrapped in parchment or foil laminate, optimized for precise measurement in recipe-driven baking. Procurement dominates North American retail where legacy refrigeration infrastructure favors rigid format stacking density.
- Tubs:Wide-mouth polypropylene containers with snap-fit lids, enabling direct-table serving and resealability. Adoption concentrates in South Korean and Australian urban households where chilled-set whipped butter dominates supermarket allocations.
- Pouches:Flexible multilayer films with modified atmosphere barriers, displacing sticks in Indian convenience stores where single-serve occasions drive trial.
- Sachets:Single-serve foil sachets targeting airline catering, institutional food service, and hospitality minibars where portion control eliminates waste.
Stick formats retain the largest installed base; pouches are climbing the fastest as emerging-market retail modernizes.
Distribution Channel:
Channel selection maps directly to customer type, with supermarkets and wholesale serving embedded bulk users while online and convenience stores capture fragmented household demand.
- Supermarkets:Temperature-controlled dairy cases with dedicated butter set providing brand comparison and promotional visibility. Volume concentrates in Western European retail where retailer private labels compete with Arla and Fonterra on shelf placement.
- Convenience Stores:Limited SKU count with ambient-to-chilled conversion requirements, favoring long-life or UHT-stable formats. Penetration accelerates across India's urban corridors where Amul's cooperative network enables daily replenishment of pouch and sachet units.
- Online:Direct-to-consumer and quick-commerce platforms requiring insulated packaging and cold-chain last-mile fulfillment.
- Wholesale:Bulk 25kg blocks and 10kg tubs serving food manufacturers, bakery chains, and institutional kitchens with direct-from-procurement pricing.
Supermarkets anchor volume throughput; online channels are gaining share fastest as quick-commerce infrastructure matures.
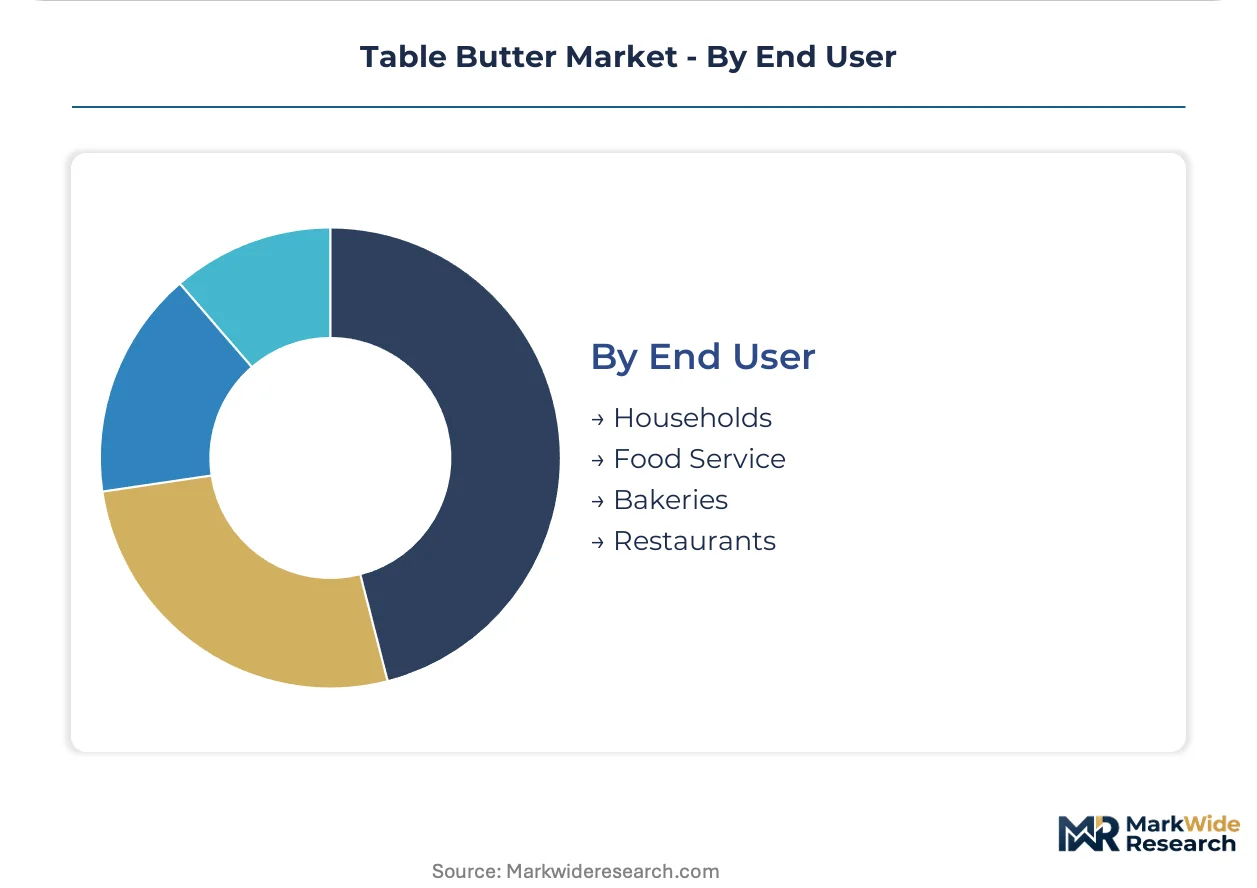
End User:
End-user segmentation separates specification-driven commercial procurement from convenience-oriented household purchasing, with bakeries and restaurants occupying distinct operational requirements.
- Households:Individual consumers selecting on spreadability, price point, and brand familiarity, with whipped variants displacing traditional blocks in refrigerator-dependent markets. Demand clusters in South Korea and Australia where chilled-set plasticity determines repeat purchase.
- Food Service:Broadline distributors serving hotels, cafeterias, and contract catering with standardized SKUs and volume pricing agreements. Procurement concentrates through Sysco and US Foods networks across North American institutional channels.
- Bakeries:Laminated dough specialists requiring fat consistency for croissant and puff pastry production, with unsalted specifications for fermentation control.
- Restaurants:Fine-dining and casual operators sourcing compound butters and portion-controlled formats for plate finishing and sauce enrichment.
Households generate the highest absolute volume; bakeries show the steepest expansion trajectory as artisanal and commercial pastry production scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's dairy cooperative zones anchor India's table butter concentration, channeling village-level milk collection through organized processing infrastructure that reshapes per capita availability.
United States
FDA milkfat standards preserve category integrity against vegetable oil adulteration in commercial bakery procurement. The agency's labeling enforcement creates compliance thresholds for spread substitutes. Wisconsin and California dairy belts concentrate cream supply contracts serving laminated dough specialists.
India
FSSAI microbiological safety modernization channels demand toward cooperatives with certified cold-chain capabilities. The regulator's enforcement tightens market access protocols for organized processors. Gujarat's village-level collection networks create captive supply advantages through backward integration into raw milk sourcing.
Germany
EU F-Gas Regulation mandates hydrofluorocarbon phase-downs across transport refrigeration units serving temperature-sensitive butter inventories. ECHA compliance timelines accelerate fleet retrofitting with CO2 transcritical systems. Bavaria's dairy processing clusters retrofit creameries with modular equipment switching between whipped and traditional formats.
France
EFSA fat-standard definitions face pressure from plant-based analogs seeking regulatory boundary adjustments. The agency's evolving stance on emulsion classification determines category integrity. Brittany's artisanal bakery supply chains demand unsalted variants with sodium-controlled specifications for fermentation precision.
New Zealand
Fonterra's grass-fed sourcing commands premium shelf placement in export markets seeking provenance differentiation. The country's pastoral dairy systems sustain export positioning through pasture-based production claims. Canterbury's processing infrastructure anchors bulk butter output for Asian food service channels.
Table Butter Market Key Industry Players
New Zealand producers anchor one tier; European cooperative specialists hold premium positioning through farmer-ownership structures. The market structures around three tiers: scale-driven commodity processors, provenance-differentiated exporters, and cooperative-owned domestic champions. Strategic archetypes include grass-fed premium exporters, village-integrated emerging-market leaders, and diversified dairy conglomerates. Competitive moves concentrate on cold-chain infrastructure partnerships and modular processing technology licensing.
Among cooperative-structured players, Fonterra Co-operative Group exemplifies grass-fed export positioning, Arla Foods amba represents European farmer-owned consolidation, and Amul occupies the emerging-market integration archetype through village-level collection density. These three anchors demonstrate how ownership structure maps to geographic market access.
| Leading Market Players |
|---|
| Unilever |
| Arla Foods amba |
| Fonterra Co-operative Group |
| Groupe Lactalis |
| Land O'Lakes |
| Ornua Co-operative Ltd. |
| Dairy Farmers of America |
| The Kraft Heinz Company |
| Amul |
| Others |
Cost & Logistics Intelligence
Commercial bakery procurement specifications for fat consistency in laminated dough are compressing supplier lead times and forcing cream processors to hold buffer inventories near major urban production clusters, elevating working capital costs that transmit into contract premiums.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as industrial bakeries penalize suppliers exceeding 72-hour delivery windows for unsalted variants. Three-tier pricing structure across premium grass-fed, standard commercial-grade, and economy private-label tiers stratifies by provenance certification and cold-chain documentation. Pricing pressure stems from feed input volatility transmitting through cream supply agreements. Price-sensitive household segments in India's tier-2 cities resist premium positioning, while artisanal bakery channels absorb specification-driven premiums without volume erosion.
Supply Chain Analysis
Direct-to-food-service channels handle bulk institutional demand through broadline distributors, while retail-bound volumes flow through temperature-controlled third-party logistics networks. Geographic supply concentrates in New Zealand, the European Union, and India as dominant cream-processing jurisdictions. Raw material flows draw from seasonal pasture availability, grain-fed dairy operations, and village-level cooperative collection networks. Single-source vulnerability runs through specialized refrigeration equipment dependent on hydrofluorocarbon phase-down timelines. Distribution runs through cooperative-owned infrastructure in emerging markets and diversified dairy conglomerates in developed economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold-chain technician scarcity caps distribution network expansion, propping margin structures for incumbents with qualified maintenance density in rural corridors.
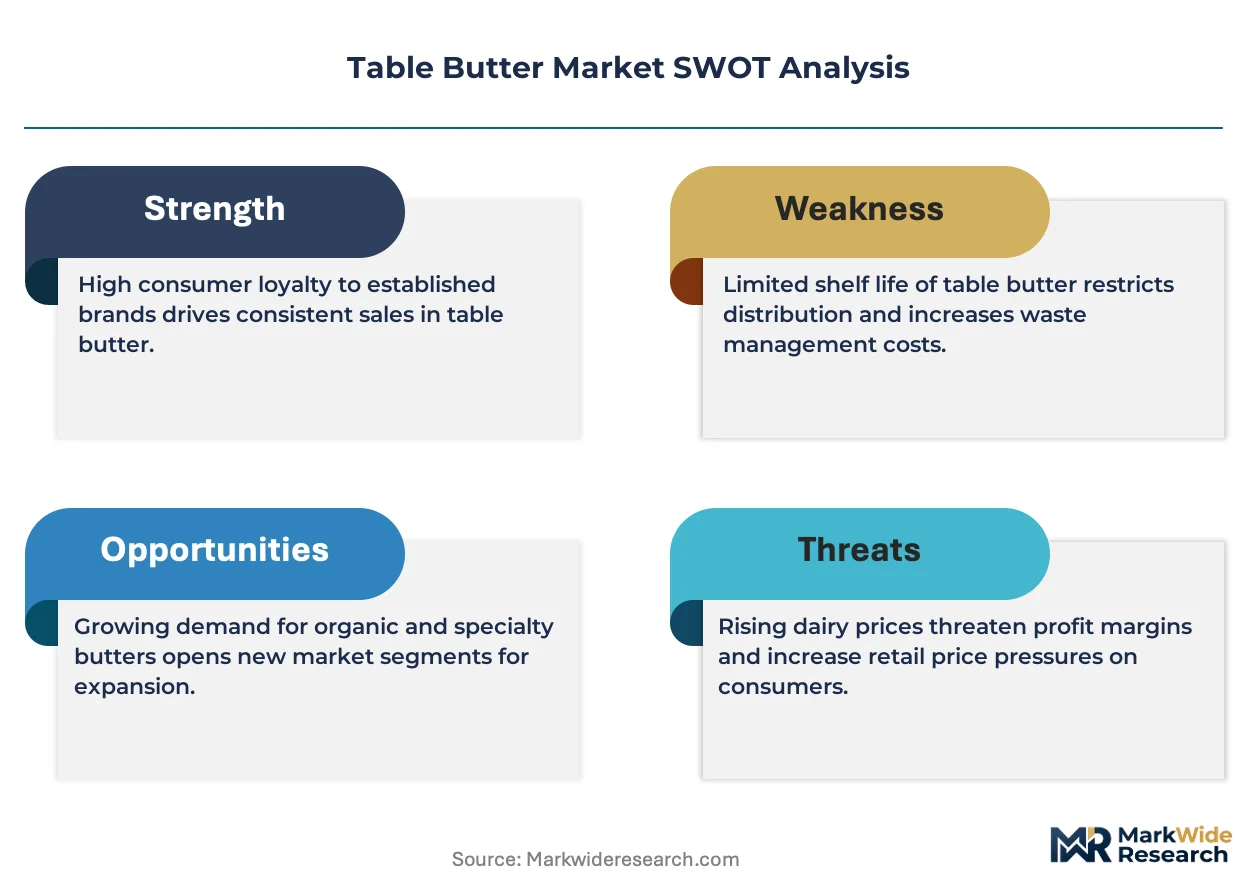
For Market Incumbents: Deploy modular processing technology licensing to capture retrofit demand from mid-scale cooperatives seeking format flexibility between whipped and traditional butter production. Consolidate position by acquiring village-level collection networks in Gujarat and Maharashtra before FSSAI enforcement modernization completes. Channel control through cooperative ownership structures defends against private-label encroachment from diversified dairy conglomerates. For New Entrants and Emerging Players: Quick-commerce platforms represent the most penetrable route for chilled last-mile fulfillment in South Korean and Australian urban households seeking spreadability-optimized formats. Target artisanal bakery supply chains in France and Denmark with sodium-controlled unsalted specifications where incumbent cooperatives maintain legacy block-butter allocations. Pursue white-label manufacturing partnerships with established cold-chain operators to bypass capital-intensive fleet retrofit requirements. For Investors and Strategic Acquirers: The window for entry favors grass-fed provenance exporters with captive pastureland and Asian food service channel relationships. Long-term viability hinges on regulatory arbitrage between EU F-Gas compliance costs and emerging-market enforcement gaps. Monitor EFSA fat-standard definition proceedings as the inflection signal determining plant-based analog boundary pressure and category integrity duration.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Partnership | CO2 transcritical fleet retrofits ahead of EU F-Gas 2030 deadlines secure distribution continuity for temperature-sensitive inventories. |
| Modular Processing Technology Licensing | Interchangeable creamery equipment compresses minimum efficient scale and enables specialty format production for regional cooperatives. |
| Village-Level Collection Network Acquisition | Backward integration into Gujarat and Maharashtra raw milk sourcing creates captive supply advantages under tightening FSSAI protocols. |
| Grass-Fed Provenance Certification Program | Pasture-based production claims command premium shelf placement in Asian export markets seeking differentiation from grain-fed alternatives. |
| Pouch Format Shelf-Life Engineering | Modified atmosphere barrier films extend product stability without preservatives, enabling single-serve penetration in Indian convenience retail. |
Research Approach
Document review covered EU regulatory filings, FSSAI enforcement circulars, and dairy cooperative annual reports, complemented by interviews with creamery operations managers, cold-chain logistics directors, bakery procurement heads, and food service distribution executives. Secondary validation drew from customs trade data, refrigeration equipment manufacturer disclosures, and retail audit databases. Bottom-up volume modeling triangulated against top-down macroeconomic consumption indicators.
Cross-referencing historical production trends against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, packaging format, distribution channel, and end-user application. CAGRs were derived from trend extrapolation moderated by regulatory compliance cost trajectories and feed input price cycle assumptions. Industry-specific forecast inputs incorporated F-Gas phase-down capital expenditure timelines and FSSAI modernization enforcement intensity.
The model holds under stable regulatory enforcement schedules and uninterrupted pasture-to-processor supply flows; deviation in grain price volatility or refrigeration technician availability would shift volume and value outputs. Forecasts reflect documented base-case assumptions subject to revision. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Goat Milk Powder Market
Dairy Products
Evaporated Milk Market
Dairy Products
Fermented Dairy Products Market
Dairy Products
Dairy Concentrates Market
Dairy Products
Probiotic Yogurt Market
Dairy Products
Enzyme Modified Cheese Market
Dairy Products
Skimmed Milk Market
Dairy Products
Filled Cheese Market
Dairy Products
Oman Dairy Products and Juice Market
Dairy Products
Citrus Yogurt Market
Dairy Products
Natural Cheese Market
Dairy Products
Low Fat Butter Market
Dairy Products
US Cheese Market
Dairy Products
Low Fat Cheese Market
Dairy Products
Reconstituted Milk Market
Dairy Products
Ready-To-Use Cheese Market