
 Ricotta Market | 2026-2036
Ricotta Market Size, Share, and Industry Trends Forecast 2026-2036
Ricotta Market Analytics
Multi-format packaging is broadening buyer choice in ricotta retail, as brands move beyond standard tubs toward portion-controlled pouches and resealable jars. Saputo Inc. leverages its North American dairy network to secure milk supply contracts that stabilize input costs. Organic Valley differentiates through certified organic ricotta lines that command shelf space in premium supermarket channels. Lactalis American Group, Inc. anchors its position via cold-chain distribution scale that reaches food service operators across multiple states.
Ricotta denotes a fresh whey cheese produced through coagulation of whey proteins, typically containing 5-15% milk fat and yielding a moist, granular curd texture prized for its mild flavor and high moisture content. Fresh Ricotta dominates volume sales in retail channels where short shelf life aligns with frequent purchase cycles, while Organic Ricotta captures expanding margin pools as certification requirements tighten across dairy supply chains. The Food Service segment within End User classification exhibits structural momentum as restaurants incorporate ricotta into both traditional Italian applications and fusion menu development.
The USDA enforces Grade A pasteurized milk standards that govern ricotta whey sourcing and processing hygiene, while the FDA oversees labeling requirements under the Federal Food, Drug, and Cosmetic Act. The EU's EFSA dairy hygiene regulations shape import eligibility for non-European ricotta producers seeking access to Italian and French retail markets. Stakeholders must monitor evolving clean-label disclosure mandates and alternative protein competition as factors that will reshape procurement priorities and product positioning decisions.
Market Dynamics
Whey protein recovery technology is consolidating ricotta production economics, enabling smaller dairies to achieve scale-equivalent yields while EU clean-label mandates force ingredient transparency reforms across export supply chains.
Growth Catalysts
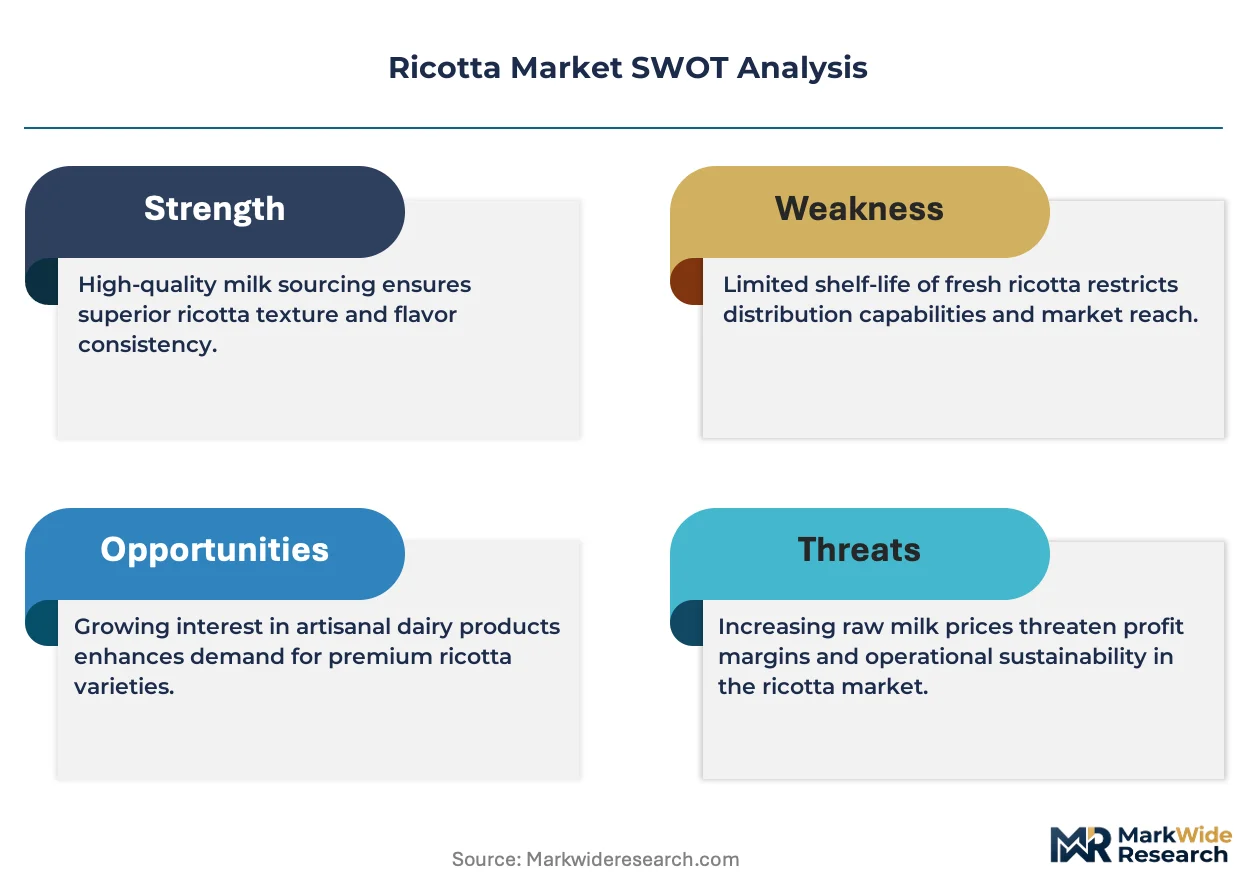
- Artisanal Bakery Expansion:Restaurant chains in Italy and France are expanding ricotta procurement for pasta fillings and desserts, creating dedicated supplier programs that stabilize volume commitments.
- USDA Grade A Standards:Federal pasteurized milk requirements are elevating processing hygiene benchmarks, enabling compliant domestic producers to access food service contracts previously dominated by imports.
- Organic Certification Pipeline:Tightening dairy supply chain certification requirements are expanding margin pools for producers who secure organic ricotta designation through accredited third-party verification.
Market Restraints
- Whey Supply Concentration:Italian regional dairies control the majority of traditional whey-sourced ricotta feedstock, creating input bottlenecks for new market entrants lacking established supplier relationships.
- Fresh Product Perishability:Short shelf life constraints limit distribution radius for unpasteurized varieties, compressing addressable market geography for small-batch producers.
- Plant-Based Substitution:Almond and cashew-based dairy alternatives are capturing label-conscious consumers in North American retail channels, displacing conventional ricotta in vegan menu applications.
Strategic Opportunities
- Resealable Packaging Formats:Portion-controlled pouches and jar formats are opening convenience-oriented retail segments previously underserved by standard tub presentations.
- Fusion Cuisine Adoption:Restaurant operators in Australia and Canada are incorporating ricotta into non-Italian applications, expanding usage occasions beyond traditional lasagna and cannoli preparations.
- Cold-Chain Infrastructure Investment:Expanded refrigerated logistics networks in emerging markets are enabling fresh ricotta distribution to food service operators previously limited to shelf-stable alternatives.
Industry Challenges
- Coagulation Expertise Shortage:Skilled whey curd technicians are concentrated among aging producer workforces in Emilia-Romagna, constraining quality replication at new facilities.
- Multi-Jurisdiction Labeling Complexity:Divergent FDA and EFSA disclosure requirements force dual packaging runs for export-oriented producers, inflating compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ricotta Market |
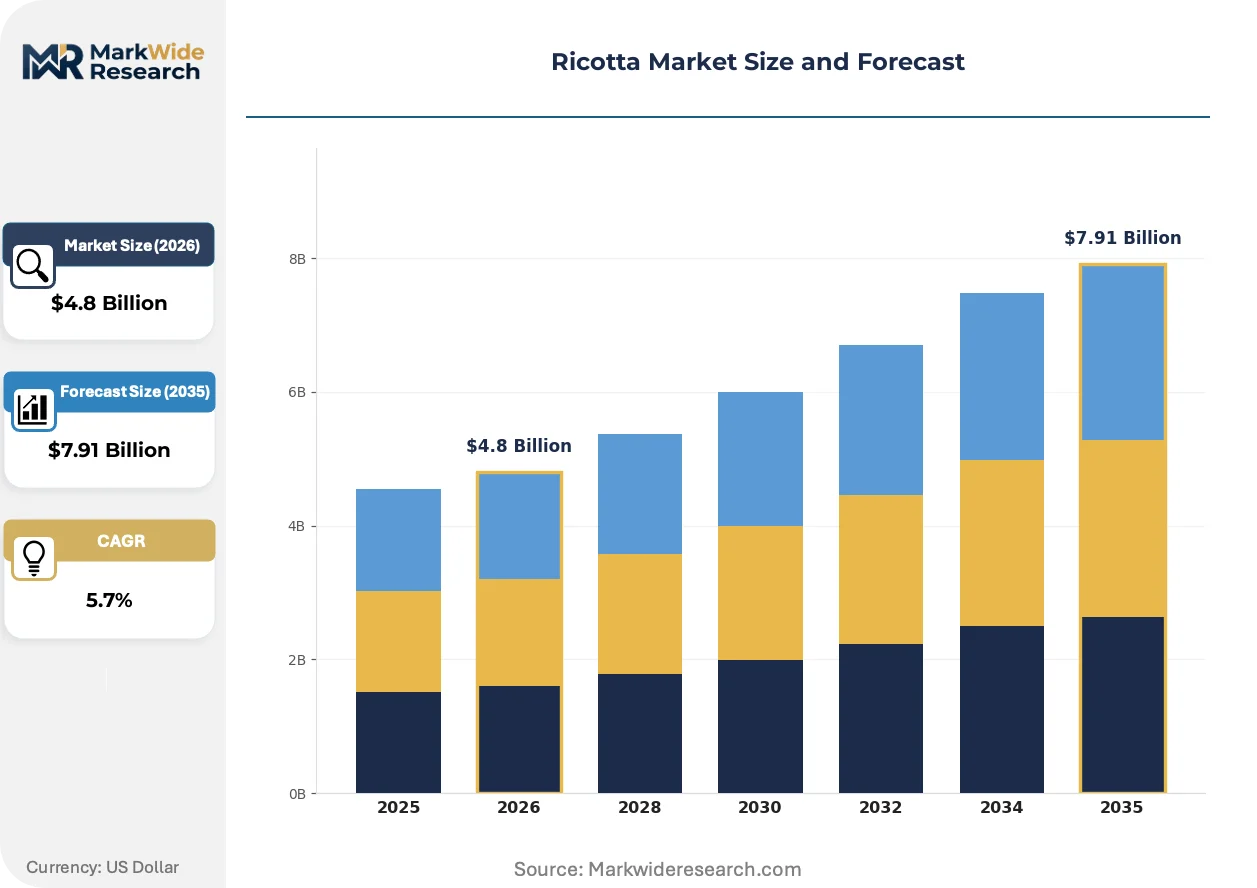
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Ricotta, Ricotta Salata, Flavored Ricotta, Organic Ricotta Packaging Type: Buckets, Tubs, Pouches, Jars Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Food Service End User: Households, Restaurants, Catering Services, Bakeries |
| Companies Covered | Saputo Inc., Organic Valley, Lactalis American Group, Inc., Lyrical Foods, Inc., Crystal Farms, Sargento Foods Incorporated, Granarolo S.p.A., Tofutti Brands Inc., Calabro Cheese Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ricotta Market Evolving Landscape
Processing automation and packaging engineering are compressing production-to-shelf timelines while regulatory disclosure mandates reshape competitive positioning around ingredient provenance claims.
Continuous whey protein recovery systems are consolidating small-batch ricotta economics by extracting higher curd yields from residual dairy streams. Mid-scale producers in Wisconsin and Lombardy are retrofitting these units to match artisanal quality at commercial volumes. The technology is consolidating regional supply bases by enabling formerly volume-constrained dairies to serve multi-state food service contracts.
EFSA dairy hygiene regulations are tightening import eligibility criteria for non-European ricotta seeking Italian and French retail placement. Third-country producers must now demonstrate equivalent pasteurization and traceability protocols to access protected designation markets. North American exporters are responding by securing dual USDA-EFSA facility certifications to maintain continental shelf access.
Food service procurement is compressing supplier rosters as restaurant groups consolidate ricotta purchasing under national distribution agreements. Broadline distributors are displacing direct dairy relationships for mid-size restaurant chains seeking simplified invoice and delivery logistics. This concentration is most visible in United States casual dining, where corporate menu standardization mandates single-source ingredient qualification.
Ricotta Market Segmentation
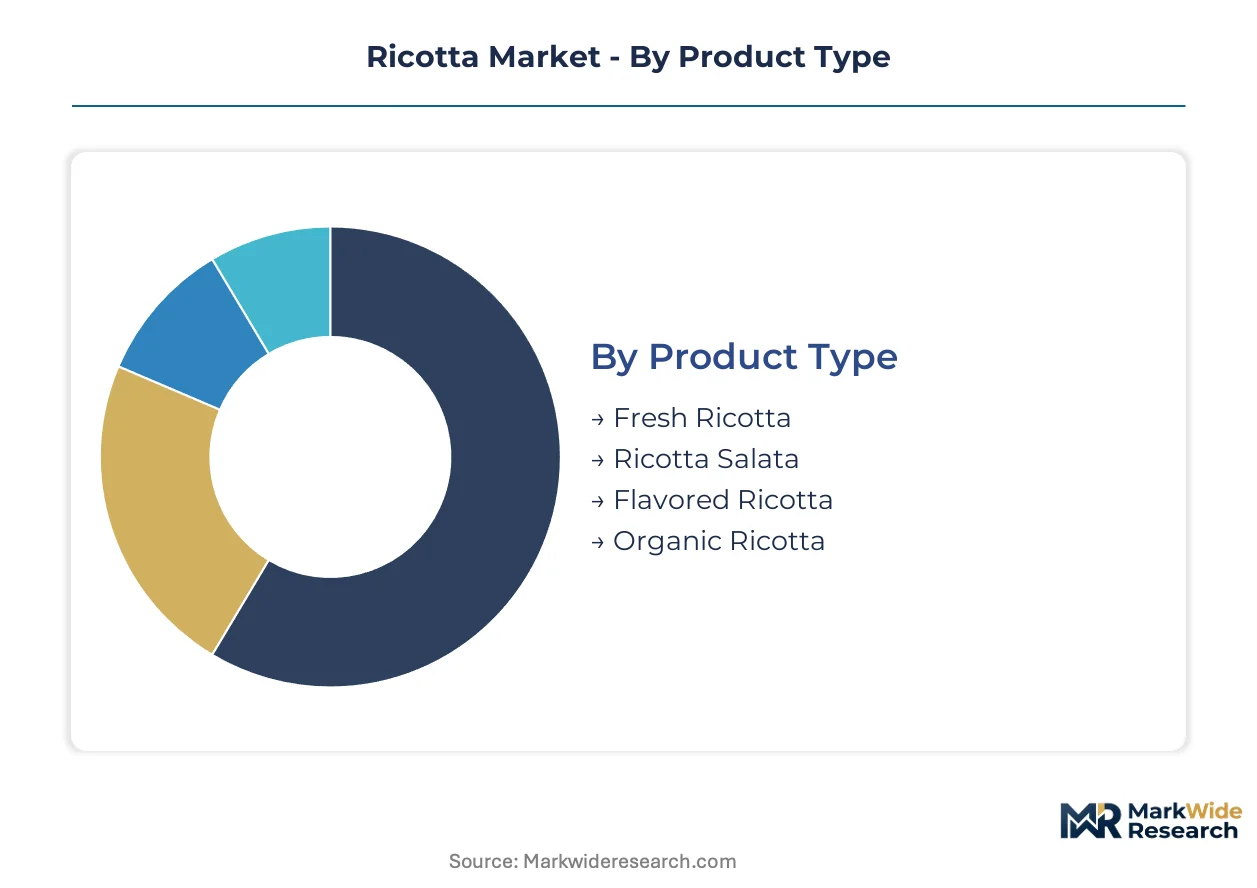
Ricotta producers face divergent margin pressures across product formats and channel structures. Segmentation reveals where supply chain investments concentrate and which buyer categories command premium positioning.
Product Type:
Traditional whey-sourced production methods anchor supply concentration in Emilia-Romagna and Lombardy, creating tiered cost structures across freshness grades and certification levels.
- Fresh Ricotta:Moist, granular curd with 5-15% milk fat content delivers the mild flavor profile prized for lasagna and cannoli applications. Italian households and restaurant chains in France absorb the majority of volume, though perishability constraints compress distribution radius for unpasteurized varieties.
- Organic Ricotta:Certified organic lines command shelf space in premium supermarket channels across Germany and the Netherlands. Tightening dairy supply chain certification requirements are expanding margin pools for producers who secure accredited third-party verification.
- Ricotta Salata:Aged, pressed, and salted variant with extended shelf life serves grating applications in southern Italian cuisine.
- Flavored Ricotta:Herb-infused and sweetened variants target convenience-oriented retail segments in North American markets.
Fresh Ricotta absorbs the bulk of installed capacity; Organic Ricotta is expanding most quickly.
Packaging Type:
Cost tier differentiation separates commodity tub formats from premium convenience engineering, with resealable and portion-controlled designs capturing expanding margin pools.
- Tubs:Standard polyethylene containers dominate retail shelf presence through economies of scale in molding and filling operations. Supermarket chains in Italy and Spain specify tub formats for private-label ricotta lines.
- Pouches:Flexible portion-controlled formats reduce per-use waste and extend consumer purchase cycles. Australian and Canadian retailers are adopting pouch presentations for organic ricotta lines targeting single-person households.
- Buckets:Bulk food service containers serve restaurant procurement through broadline distributors.
- Jars:Glass resealable presentations occupy premium positioning in specialty store channels.
Tubs command the highest production volume; pouches are climbing the fastest among format innovations.
Distribution Channel:
Application-based channel segmentation separates impulse retail purchases from planned food service procurement, with cold-chain requirements filtering producer eligibility.
- Supermarkets:Multi-format retail chains in Italy, France, and Germany consolidate ricotta category management under centralized dairy buyers. Clean-label disclosure mandates are reshaping shelf placement criteria for conventional versus organic lines.
- Food Service:Broadline distributors are displacing direct dairy relationships for mid-size restaurant chains seeking simplified invoice and delivery logistics. Corporate menu standardization in United States casual dining mandates single-source ingredient qualification.
- Online Retailers:E-commerce platforms expand addressable geography for shelf-stable ricotta salata variants.
- Specialty Stores:Italian delis and cheese mongers in urban clusters preserve artisanal procurement relationships.
Supermarkets absorb the bulk of installed capacity; Food Service is gaining share fastest through distributor consolidation.
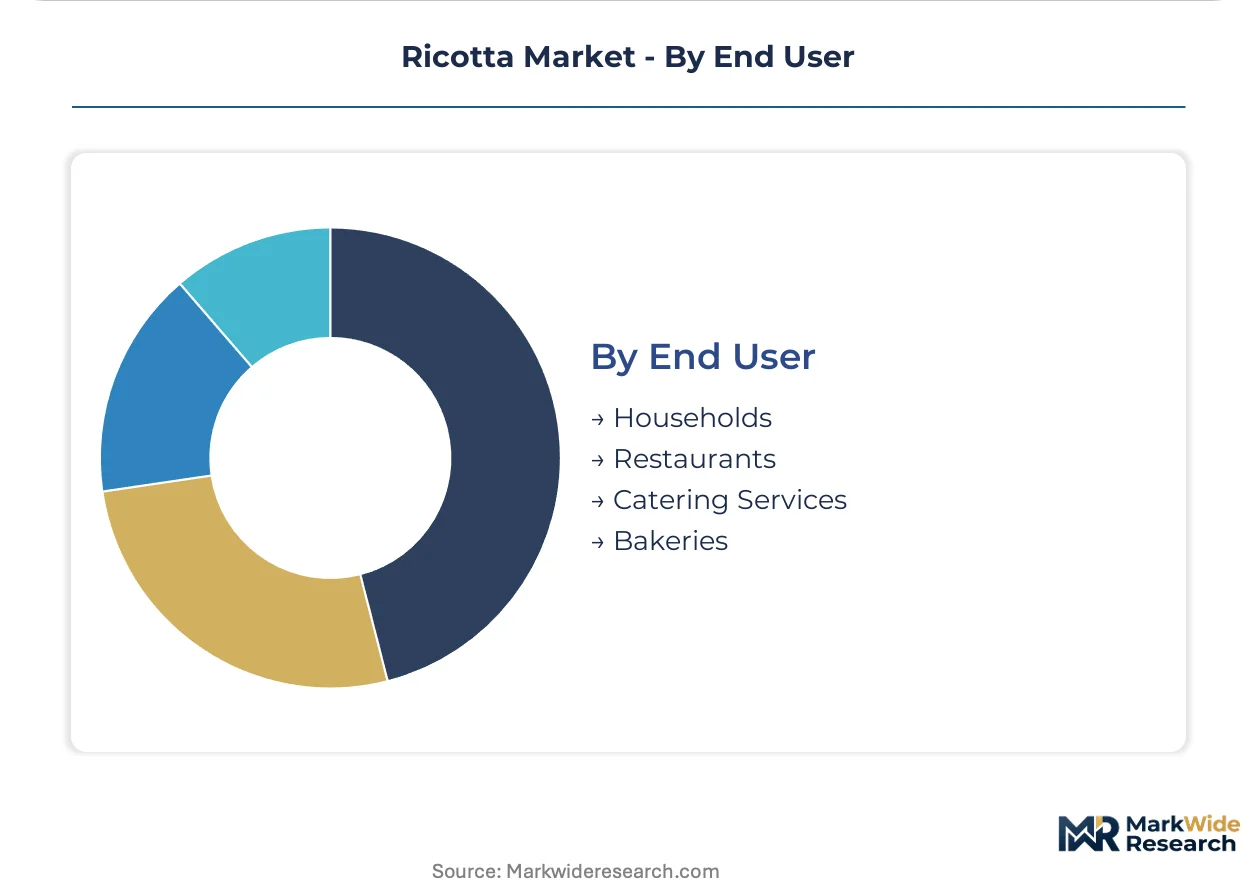
End User:
Customer type segmentation aligns product specifications with usage intensity, separating high-volume commercial operators from discretionary household purchasers.
- Restaurants:Italian and French restaurant chains are expanding dedicated ricotta supplier programs that stabilize volume commitments. Fusion menu development in Australia and Canada is incorporating ricotta into non-Italian applications.
- Bakeries:Artisanal bakery expansion drives procurement for pasta fillings and dessert preparations. Skilled whey curd technician scarcity in Emilia-Romagna constrains quality replication at new facilities.
- Households:Weekly purchase cycles align with fresh ricotta shelf life in Italian domestic consumption patterns.
- Catering Services:Event-based demand concentrates in metropolitan clusters with established Italian diaspora populations.
Restaurants absorb the bulk of installed capacity; Bakeries are expanding most quickly through artisanal positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Emilia-Romagna's agri-food special economic zone concentrates traditional ricotta production infrastructure, drawing whey supply contracts from Lombardy and Veneto dairies. Tax incentives for heritage food manufacturing anchor capacity expansion decisions across northern Italy.
Italy
Artisanal bakery chains in Bologna and Modena expand ricotta procurement for filled pasta and dessert applications. EFSA dairy hygiene regulations enforce pasteurization and traceability protocols for export eligibility. The Po Valley dairy cluster maintains whey-sourced production dominance through generational coagulation expertise concentrated in Parma and Reggio Emilia provinces.
United States
Restaurant groups in Chicago and New York standardize ricotta specifications for corporate menu rollouts. USDA Grade A pasteurized milk requirements elevate processing hygiene benchmarks for domestic producers. Wisconsin's dairy belt retrofits continuous whey recovery systems to serve multi-state food service contracts.
France
Supermarket chains in Lyon and Marseille allocate premium shelf space to organic ricotta lines. EFSA clean-label disclosure mandates reshape import criteria for Italian and non-European suppliers. The Rhône-Alpes retail corridor consolidates category management under centralized dairy buyers demanding dual certification.
Germany
Organic certification demand in Berlin and Munich expands margin pools for verified ricotta producers. EU Green Deal agricultural standards tighten dairy supply chain sustainability requirements. The Bavarian distribution hub channels fresh ricotta through cold-chain networks reaching food service operators across central Europe.
Australia
Fusion cuisine adoption in Sydney and Melbourne incorporates ricotta into non-Italian menu applications. The country's national food standards regulator enforces labeling requirements for imported dairy products. Victorian cold-chain infrastructure investments enable fresh distribution to restaurant operators previously limited to shelf-stable alternatives.
Ricotta Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation characterizes the upper tier where multi-category dairy operators leverage cold-chain scale and milk supply contracts. Three archetypes define competitive positioning: diversified dairy conglomerates with backward integration into whey sourcing, organic-certified specialists commanding premium retail channels, and regional artisanal producers serving protected designation markets. Dominant competitive moves include strategic partnerships with broadline distributors and capacity expansion through continuous whey recovery technology deployment.
Among North American dairy conglomerates, Saputo Inc. and Lactalis American Group, Inc. occupy positions defined by distribution scale and supply network control. Organic Valley exemplifies the certified-specialist archetype through accredited third-party verification. These three companies represent contrasting strategic approaches: diversified scale operations versus premium-channel positioning versus organic certification pipeline development.
| Leading Market Players |
|---|
| Saputo Inc. |
| Organic Valley |
| Lactalis American Group, Inc. |
| Lyrical Foods, Inc. |
| Crystal Farms |
| Sargento Foods Incorporated |
| Granarolo S.p.A. |
| Tofutti Brands Inc. |
| Calabro Cheese Co. |
| Others |
Value Network & Pricing Analysis
Food service distributors in the United States and broadline operators in Italy command pricing leverage through consolidated procurement volumes, anchoring contract-based offtake structures that reward scale commitments with preferential whey sourcing terms. This buyer concentration compresses margin pools for mid-tier producers while amplifying premium capture for certified organic and artisanal-grade suppliers.
Pricing Analysis
Short lead-time premiums apply to fresh ricotta deliveries for restaurant chains operating just-in-time kitchen inventories, while spot-market discounts emerge for bulk bucket formats nearing shelf-life thresholds. Three-tier pricing structure across premium organic, standard Grade A, and economy private-label tiers differentiates based on certification level and cold-chain reliability. Pricing pressure stems from plant-based almond and cashew alternatives capturing label-conscious consumers in North American retail channels. Quick-service restaurant procurement teams exhibit highest price sensitivity, whereas artisanal bakeries in Emilia-Romagna absorb premiums for provenance-verified whey sourcing.
Supply Chain Analysis
Refrigerated freight costs escalate distribution economics for fresh ricotta crossing the Alps or traversing Australian interstate corridors, compressing addressable radius for unpasteurized varieties. Italy, the United States, and Australia anchor global production capacity, with Italian regional dairies controlling traditional whey feedstock and Wisconsin retrofitting continuous recovery systems. Whey protein concentrate, milk fat, and food-grade salt constitute critical input dependencies. Single-source vulnerability concentrates in Emilia-Romagna's aging technician workforce, constraining quality replication at new facilities. Distribution runs through broadline food service networks displacing direct dairy relationships for mid-size restaurant chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous whey protein recovery systems are displacing legacy batch coagulation methods, consolidating production economics for mid-scale dairies while artisanal expertise scarcity in Emilia-Romagna preserves premium positioning for heritage producers.
For Market Incumbents: Deploy cold-chain infrastructure expansion to defend food service contracts against regional artisanal challengers. Secure dual USDA-EFSA facility certifications to maintain continental shelf access as EFSA hygiene regulations tighten import eligibility. Anchor milk supply contracts through backward integration into whey sourcing networks that stabilize input cost volatility against commodity dairy fluctuations. For New Entrants and Emerging Players: Enter via portion-controlled pouch formats targeting single-person households in Australian and Canadian retail channels, a white-space segment underserved by standard tub presentations. Target organic certification pipelines in Germany and the Netherlands where tightening supply chain requirements expand margin pools for verified producers. Pursue fusion cuisine partnerships with Sydney and Melbourne restaurant operators incorporating ricotta into non-Italian applications. For Investors and Strategic Acquirers: The window for entry favors organic-certified specialists with accredited third-party verification and established premium supermarket shelf placement. Long-term viability hinges on cold-chain scale and generational coagulation expertise replication capability. Monitor EFSA clean-label disclosure mandate implementation as the signal indicating accelerated consolidation pressure on non-compliant import-oriented producers.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Whey Recovery Deployment | Wisconsin and Lombardy dairies retrofit systems to match artisanal quality at commercial volumes. |
| Dual Certification Investment | USDA-EFSA facility qualifications enable North American exporters to maintain Italian retail access. |
| Resealable Packaging Engineering | Portion-controlled pouches and jars capture convenience-oriented retail segments beyond standard tubs. |
| Organic Certification Pipeline | Accredited third-party verification commands premium shelf space in German and Dutch supermarkets. |
| Fusion Cuisine Partnership | Sydney and Melbourne restaurant operators expand ricotta usage beyond traditional Italian applications. |
Research Methodology
Trade databases, dairy processing equipment manufacturer disclosures, and EFSA regulatory filings formed the secondary backbone of this analysis, cross-referenced against primary interviews with whey curd technicians, broadline food service procurement directors, organic certification auditors, and restaurant chain menu development executives. Bottom-up production capacity tallies across Emilia-Romagna, Wisconsin, and Victoria were triangulated against top-down consumption estimates derived from customs records and retail audit data.
Historical trendline analysis of ricotta production volumes and pricing trajectories informed the analytical framework applied across the projection horizon. Segmentation modeling incorporated product type tiers, packaging format innovations, distribution channel structures, and end-use application intensity. CAGRs were derived from curve-fitting approaches calibrated against whey protein recovery technology adoption rates and clean-label regulatory implementation timelines.
Revisions become necessary when EFSA hygiene regulation enforcement intensifies, plant-based substitution accelerates beyond current trajectories, or generational expertise transfer fails in Emilia-Romagna production clusters. Forecasts reflect documented assumptions about cold-chain infrastructure buildout and organic certification pipeline expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
North America Organic Dairy Market
Dairy Products
North America Yogurt Market
Dairy Products
Spoonable Yogurt Market
Dairy Products
Low-Fat Sour Cream Market
Dairy Products
Probiotic Yogurt Market
Dairy Products
Europe Milk Protein Market
Dairy Products
Butter Fat Fraction Market
Dairy Products
South America Dairy Market
Dairy Products
Germany Casein and Caseinates Market
Dairy Products
Cream Market
Dairy Products
Sour Milk Drinks Market
Dairy Products
GCC Camel Dairy Market
Dairy Products
GCC Casein Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
Mozzarella Cheese Market
Dairy Products
Japan Dairy Market