
 Fermented Milk Products Market | 2026-2036
Fermented Milk Products Market Size, Share, and Industry Trends Forecast 2026-2036
Fermented Milk Products Market Foresight
Asset-light contract manufacturing and third-party dairy processing agreements is tilting competitive dynamics toward firms that avoid capital-heavy plant ownership. Danone leverages its captive strain libraries and regional co-packing networks to preserve margin flexibility across European markets. Nestlé anchors its position through backward integration into dairy farming cooperatives in key sourcing zones. Yakult Honsha differentiates via dedicated probiotic research infrastructure and controlled distribution through its direct-to-consumer channel model.
Fermented milk products denote dairy substrates transformed by defined bacterial cultures—typically Lactobacillus, Streptococcus, or Bifidobacterium species—yielding lactic acid coagulation, pH reduction below 4.6, and characteristic organoleptic profiles. These products serve nutritional, digestive health, and culinary preparation functions across retail and institutional food systems. Yogurt occupies the dominant value position within product type segmentation, sustained by refrigerated distribution ubiquity and flavor format proliferation. Kefir generates accelerated growth momentum among dietary supplement users seeking higher microbial diversity counts. The food service end user segment captures concentrated margin pools through portion-controlled formats and customized fat-content specifications for hospitality procurement.
EFSA health claim verification requirements and FDA GRAS notifications for novel probiotic strains shape product development timelines and cross-border market access conditions for fermented milk suppliers. Japan's FOSHU regulatory framework and China's SAMR dairy safety standards impose additional strain-specific documentation burdens on international entrants. Stakeholders must monitor evolving strain-level substantiation demands and regional labeling divergence to align R&D pipelines with compliant commercialization pathways.
Market Dynamics
Asset-light contract manufacturing is tilting competitive dynamics toward firms that avoid capital-heavy plant ownership, forcing legacy dairy processors to restructure fixed-cost bases or surrender margin to specialized co-packers.
Growth Catalysts
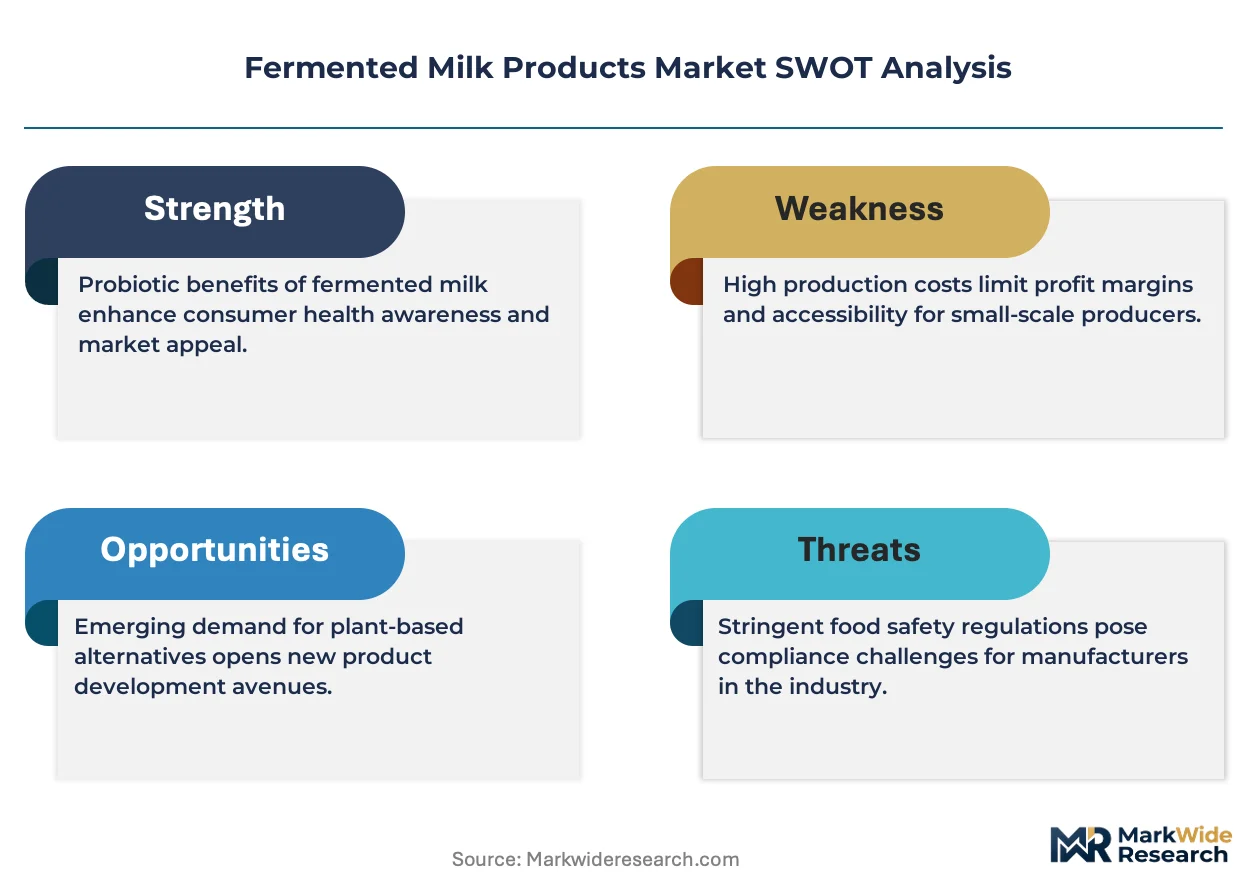
- EFSA health claim verification:European probiotic substantiation requirements are accelerating R&D investment in strain-specific clinical trials, elevating barriers for commoditized suppliers.
- Direct-to-consumer channel expansion:Controlled distribution models bypass traditional retail slotting fees and capture first-party consumption data for formulation refinement.
- Asia-Pacific retail modernization:Cold-chain infrastructure buildout in Vietnam, Indonesia, and the Philippines is unlocking refrigerated probiotic access for urban middle-class households.
Market Restraints
- Milk powder input volatility:Global dairy commodity swings compress margin predictability for processors locked into annual retail price contracts.
- Strain documentation burdens:Japan's FOSHU framework and China's SAMR dairy safety standards impose multi-year approval timelines that freeze product pipelines for international entrants.
- Plant-based substitution:Oat and almond fermented alternatives are capturing shelf space in European and North American conventional retail channels.
Strategic Opportunities
- India's FSSAI modernization:Simplified probiotic health claim pathways under 2022 dairy regulation amendments are opening formal market access for documented strains.
- Food service customization:Portion-controlled formats with specified fat-content and live culture counts are capturing hospitality procurement contracts.
- Precision fermentation convergence:Cell-culture-derived dairy proteins combined with traditional bacterial fermentation are enabling novel texture and nutritional profiles.
Industry Challenges
- Microbiome talent scarcity:Qualified strain isolation and stability specialists command premium compensation, constraining mid-tier processor expansion.
- Legacy ERP integration:Batch-level traceability requirements for FDA Food Safety Modernization Act compliance clash with decades-old dairy plant software architectures.
- Cross-border licensing friction:Proprietary strain intellectual property disputes between European culture houses and Asian processors are delaying joint venture timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fermented Milk Products Market |
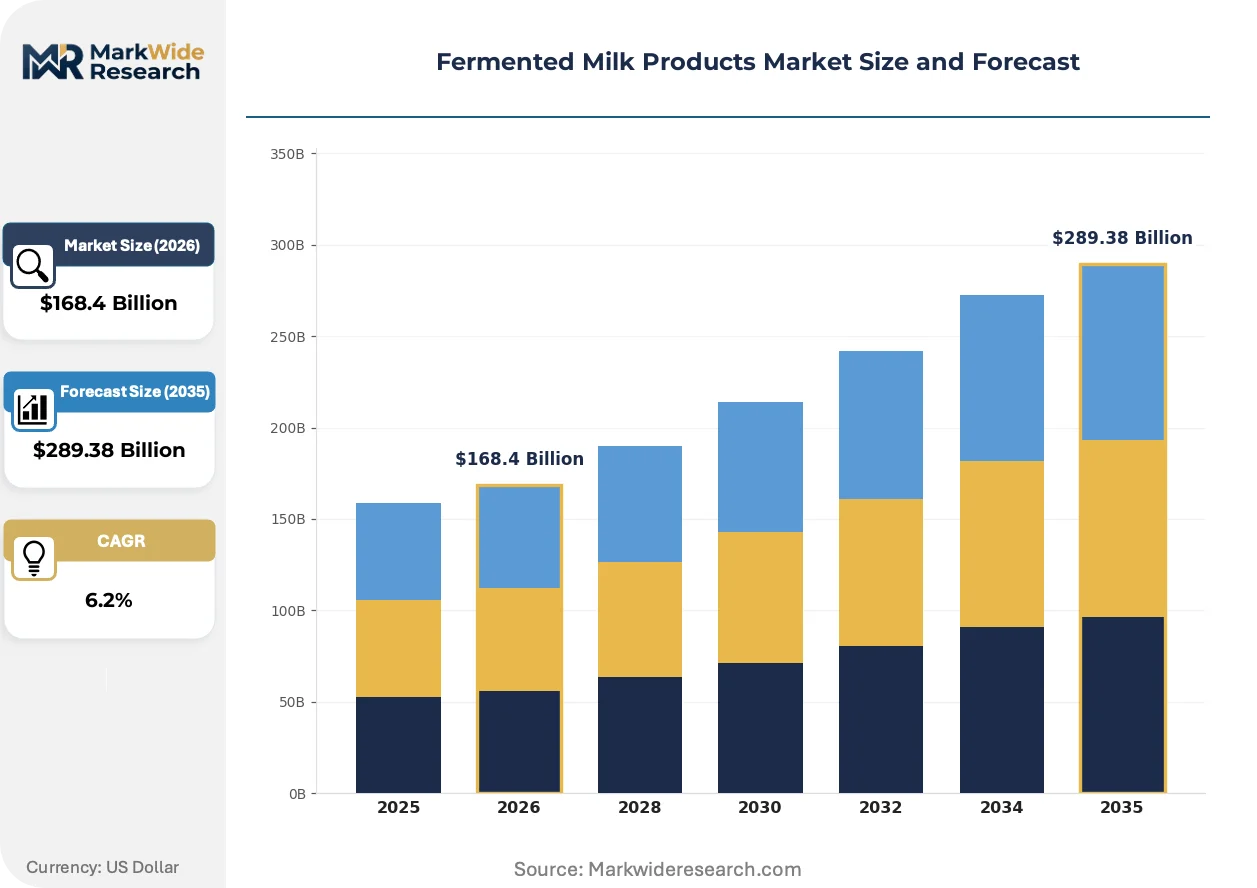
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $289.38 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yogurt, Kefir, Fromage Blanc, Labneh End User: Retail Consumers, Food Service, Healthcare Institutions, Dietary Supplement Users Packaging Type: Glass Containers, Plastic Bottles, Tetra Packs, Bulk Packaging Distribution Channel: Supermarkets, Online Retail, Specialty Shops, Direct Sales |
| Companies Covered | Danone, Nestlé, Lactalis, FrieslandCampina, Chobani, Arla Foods, Yakult Honsha, Emmi, Fonterra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fermented Milk Products Market Shifts & Advancements
Live culture preservation technology and strain specificity are reshaping how fermented milk products differentiate at shelf, compressing the window between laboratory discovery and commercial scale-up.
Aseptic fermentation with post-process probiotic addition is migrating from pharmaceutical-grade facilities to mainstream dairy operations. Premium yogurt and kefir manufacturers in Germany and South Korea are adopting this approach to guarantee labeled CFU counts through expiration. The technology is compressing spoilage risk and extending distribution radius for ambient-stable probiotic formats.
China's SAMR has tightened strain-level registration requirements for imported fermented milk products, mandating full genomic sequencing and safety dossiers. This policy is forcing multinational suppliers to maintain parallel product formulations—one for China with documented strains, another for markets with lighter registration burdens. European exporters with captive culture libraries are absorbing compliance costs; commodity traders are retreating.
Hospital and elder-care procurement departments are consolidating supplier relationships around single-source fermented nutrition contracts with outcome-linked pricing. This buying-pattern shift is displacing fragmented purchasing across retail and institutional channels in Japan and the Netherlands. Manufacturers with clinical trial data and dietitian training programs are capturing these concentrated accounts.
Fermented Milk Products Market Segmentation
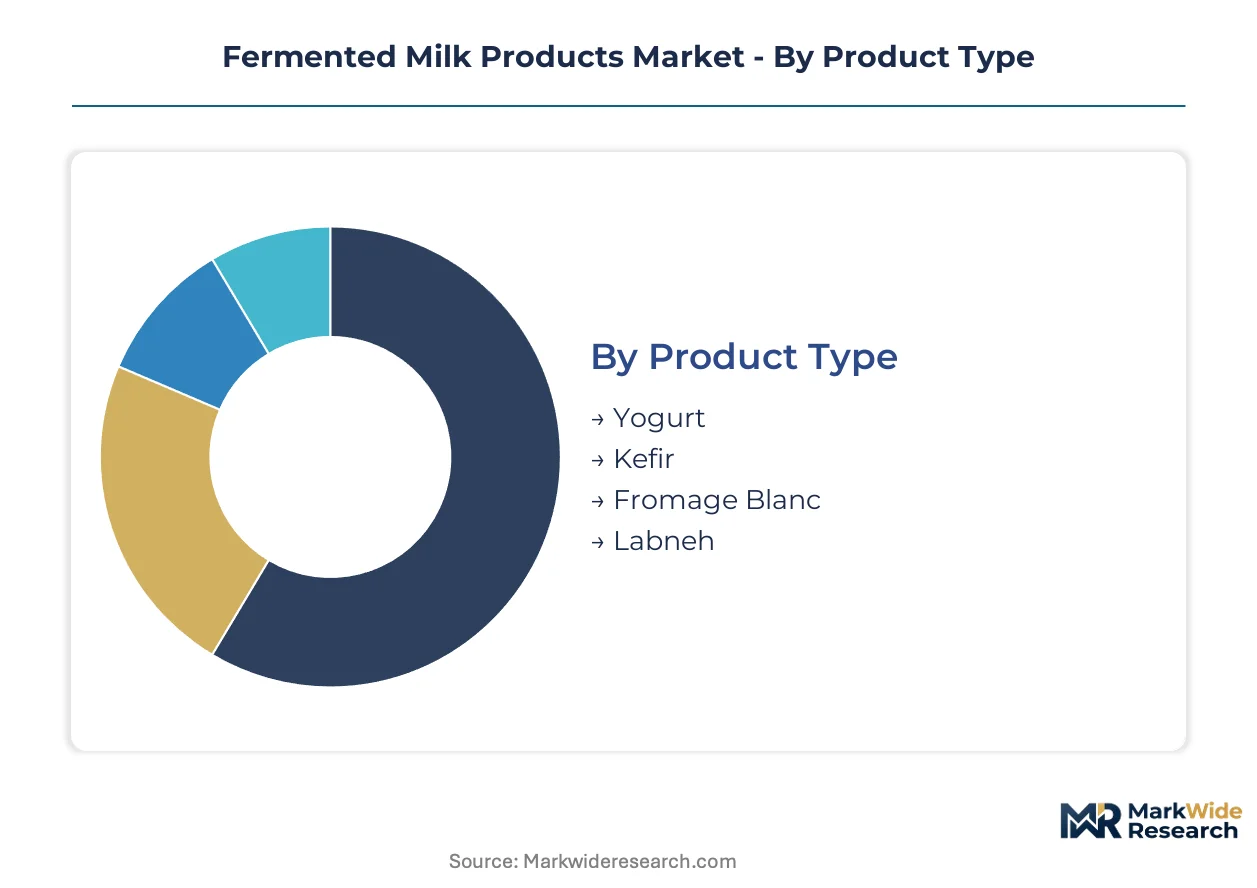
Fermented milk products fragment across four distinct dimensions that determine margin capture and supply chain configuration. Product type defines manufacturing complexity and strain specificity requirements. End-user orientation dictates packaging format, shelf-life engineering, and regulatory compliance burden.
Product Type:
Cost tier stratification across fermented milk formats reflects processing intensity, culture maintenance expense, and cold-chain dependency.
- Yogurt:Lactic acid fermentation by Lactobacillus delbrueckii subsp. bulgaricus and Streptococcus thermophilus produces the characteristic gelled texture and pH below 4.6. Retail consumers in Japan and South Korea drive premium Greek-style and drinkable variants through convenience store channels. Strain-specific health claim documentation under EFSA guidelines elevates R&D investment for functional positioning.
- Kefir:Symbiotic fermentation involving multiple yeast and bacterial species yields higher microbial diversity counts and effervescent carbonation. Dietary supplement users in Germany and the United States are rotating toward kefir for digestive wellness applications beyond conventional yogurt. Aseptic post-fermentation probiotic addition is extending ambient-stable distribution reach.
- Fromage Blanc:Fresh acid-set cheese with minimal aging retains high moisture content and mild lactic flavor profile. French and Belgian retail channels maintain strongest per-capita consumption.
- Labneh:Strained yogurt with elevated protein density serves culinary preparation functions across Middle Eastern food service procurement. Lebanese and Saudi Arabian hospitality distributors specify fat-content gradations for institutional contracts.
Yogurt holds installed capacity. Kefir is rotating up the share rankings.
End User:
Application-specific requirements determine formulation precision, packaging sterilization standards, and outcome documentation obligations.
- Retail Consumers:Mass-market households purchase single-serve and family-format products through supermarket and online retail channels. Flavor proliferation and clean-label positioning drive repeat purchase in South Korean and Vietnamese urban markets.
- Food Service:Hospitality procurement contracts specify portion-controlled formats with customized fat-content and live culture counts for menu integration. German and Dutch institutional buyers are consolidating around single-source suppliers with dietitian training programs.
- Healthcare Institutions:Hospital and elder-care nutrition departments demand clinical trial data supporting patient outcomes. Japanese procurement is shifting toward outcome-linked pricing models with documented strain efficacy.
- Dietary Supplement Users:High-CFU-count kefir and concentrated probiotic shots target wellness-focused consumers seeking microbial diversity beyond standard yogurt. Direct-to-consumer subscription models bypass traditional retail slotting fees.
Retail consumers anchor volume. Healthcare institutions are climbing the fastest in margin contribution.
Packaging Type:
Volume throughput and shelf-life engineering requirements dictate material selection and capital equipment allocation across production facilities.
- Glass Containers:Premium positioning in specialty shops and direct sales channels leverages perceived purity and reusability. German and Swiss organic retailers specify glass for high-margin skyr and Icelandic-style products.
- Plastic Bottles:Drinkable yogurt and kefir formats dominate convenience store and supermarket refrigerated sections. South Korean and Indonesian cold-chain expansion is unlocking PET bottle distribution for ambient-stable aseptic fills.
- Tetra Packs:Aseptic carton technology enables unrefrigerated distribution for UHT-treated fermented milk in emerging markets with limited cold infrastructure. Vietnamese retail modernization is absorbing tetra-packed probiotic formats.
- Bulk Packaging:Food service and healthcare institutional channels receive 5-20 liter bag-in-box or pail formats for portioning at point of use. Dutch hospital procurement contracts specify bulk delivery with traceability batch coding.
Plastic bottles hold installed capacity. Tetra packs are gaining share fastest in emerging market expansion.
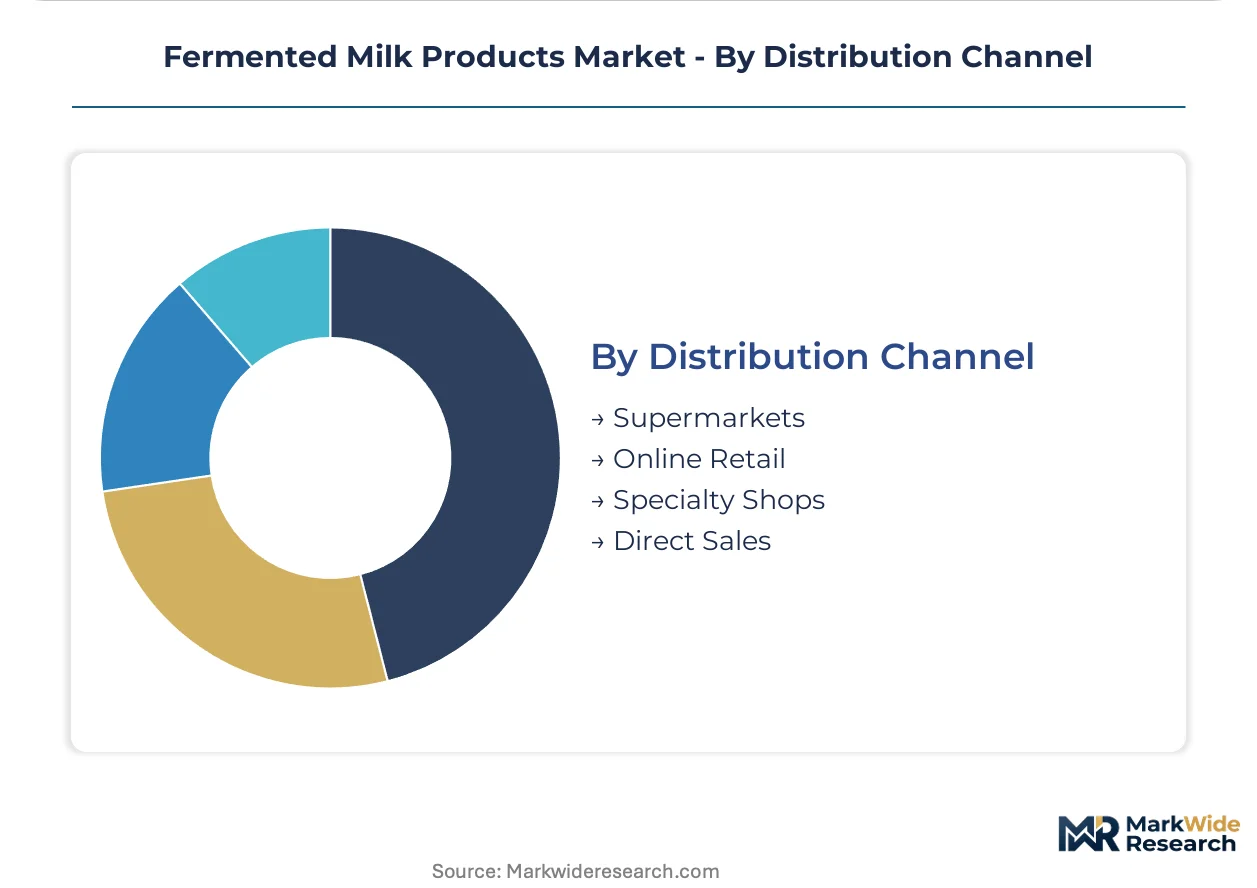
Distribution Channel:
Customer type concentration and margin capture potential determine channel investment priority and working capital allocation.
- Supermarkets:Refrigerated dairy case placement commands slotting fees and promotional spending for mass-market yogurt penetration. Japanese and South Korean convenience-store-format supermarkets dominate urban probiotic access.
- Online Retail:Cold-chain logistics integration enables subscription-based kefir and functional yogurt delivery with first-party consumption data capture. German and United States direct-to-consumer platforms are displacing conventional retail for premium positioning.
- Specialty Shops:Organic and artisanal fermented milk products with heritage strain claims target wellness-focused households. French fromageries and Middle Eastern delicatessens maintain curated assortment depth.
- Direct Sales:Yakult-style home delivery networks and healthcare institutional contracting bypass retail intermediaries. Japanese and Dutch elder-care facilities source through dedicated distribution with outcome documentation.
Supermarkets hold installed capacity. Online retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in fermented milk products tilt toward surplus producers with documented strain libraries and cold-chain infrastructure. Import dependency concentrates in emerging markets where domestic processing capacity lags probiotic demand expansion.
Japan
Functional food consumption drives per-capita probiotic penetration through convenience store channels and direct-to-home delivery networks. The country's FOSHU regulatory framework mandates strain-specific efficacy documentation for health claim authorization. Tokyo and Osaka metropolitan clusters concentrate R&D facilities for lactic acid bacteria isolation and stability testing.
Germany
Organic dairy conversion and kefir diversification sustain premium format growth among wellness-focused retail consumers. EFSA health claim verification requirements under EU Regulation 1924/2006 shape product development timelines for cross-border market access. Bavarian and Baden-Württemberg processing corridors host specialized co-packing facilities for aseptic fermentation with post-process probiotic addition.
United States
Greek yogurt market maturation and plant-based substitution pressures are redirecting investment toward high-CFU kefir and medical nutrition formats. FDA GRAS notification pathways for novel probiotic strains determine commercialization speed for culture suppliers. Upstate New York and Idaho dairy belts anchor contract manufacturing capacity for national brand distribution.
China
Urban middle-class expansion and cold-chain infrastructure buildout are unlocking refrigerated probiotic access beyond tier-one cities. SAMR dairy safety standards impose full genomic sequencing requirements for imported strain registration. Yangtze River Delta and Pearl River Delta manufacturing zones concentrate domestic yogurt production for local brand proliferation.
India
FSSAI modernization under 2022 dairy regulation amendments is simplifying probiotic health claim pathways for documented strains. Traditional dahi consumption patterns create foundation for branded fermented milk conversion in metropolitan markets. Maharashtra and Gujarat dairy cooperatives are expanding processing capacity for formal sector probiotic distribution.
Fermented Milk Products Market Competitive Landscape
On the supply side, the industry is consolidating around culture library ownership and co-packing network scale, with mid-tier processors surrendering margin to specialized fermentation contractors. Two strategic archetypes dominate: integrated dairy cooperatives with backward farming control and asset-light brand operators leveraging third-party manufacturing. Competitive moves center on strain intellectual property licensing and cold-chain distribution partnerships.
Within the integrated multinational tier, Danone and Nestlé exemplify divergent supply architectures—Danone through regional co-packing networks preserving margin flexibility, Nestlé through cooperative farming integration in key sourcing zones. Yakult Honsha occupies a distinct position with dedicated probiotic research infrastructure and controlled direct-to-consumer distribution.
| Leading Market Players |
|---|
| Danone |
| Nestlé |
| Lactalis |
| FrieslandCampina |
| Chobani |
| Arla Foods |
| Yakult Honsha |
| Emmi |
| Fonterra |
| Others |
Supply & Pricing Matrix
Undercapacity in South Korean aseptic fermentation facilities is forcing contract manufacturers to prioritize high-margin probiotic strains, compressing slotting availability for mid-tier dairy processors and elevating price premiums for guaranteed production slots.
Pricing Analysis
Healthcare institutional buyers anchor pricing stratification across premium, standard, and economy tiers. Premium positioning rests on EFSA-verified health claim documentation and clinical trial substantiation, while commodity yogurt segments compete on volume scale and cold-chain efficiency. Pricing pressure stems from milk powder input volatility and plant-based substitution in European retail channels. Dietary supplement users exhibit lowest price sensitivity, prioritizing CFU count guarantees over per-unit cost.
Supply Chain Analysis
Specialized co-packers in Germany, South Korea, and the Netherlands hold dominant contract-manufacturing capacity for aseptic post-fermentation probiotic addition. Raw material flows draw from New Zealand dairy powder, European culture house strain libraries, and Indonesian cold-chain packaging components. Single-source vulnerability concentrates in proprietary strain intellectual property controlled by Japanese and European culture suppliers. Distribution feeds through direct-to-consumer subscription platforms and consolidated healthcare procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is tilting toward consolidated healthcare procurement departments in Japan and the Netherlands, fragmenting traditional retail channel influence and forcing suppliers to absorb outcome-documentation costs.
For Market Incumbents: Pre-empt plant-based substitution by accelerating precision fermentation partnerships that blend cell-culture dairy proteins with traditional bacterial cultures. Secure captive strain libraries through exclusive licensing with European culture houses before Asian processors consolidate access. Deepen backward integration into dairy farming cooperatives in New Zealand and Bavaria to insulate margin from commodity volatility.
For New Entrants and Emerging Players: Build out direct-to-consumer kefir subscription models targeting German and United States wellness households, bypassing supermarket slotting fees and capturing first-party consumption data. India's FSSAI-modernized probiotic health claim pathway offers the most penetrable regulatory entry point for documented strains. Position around microbial diversity counts exceeding conventional yogurt specifications.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among asset-light brand operators with captive subscription channels and proprietary strain licensing agreements. Five-to-ten-year viability favors targets with EFSA-substantiated health claim portfolios rather than commodity private-label processors. Monitor SAMR strain registration approval timelines as inflection signal for China market access feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Acquisition | Exclusive access to EFSA-documented cultures locks out commodity competitors from premium positioning. |
| Aseptic Fermentation Scale-Up | Post-process probiotic addition capacity extends distribution radius for ambient-stable formats. |
| Direct-to-Consumer Channel Launch | Subscription models bypass retail intermediaries and generate first-party formulation feedback. |
| Healthcare Procurement Contracting | Outcome-linked pricing with Dutch and Japanese elder-care facilities captures concentrated margin pools. |
| Precision Fermentation Partnership | Cell-culture dairy protein integration enables novel texture profiles beyond conventional fermentation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA health claim registers, SAMR strain approval databases, and dairy cooperative production disclosures. Interviews with probiotic R&D directors, healthcare procurement managers, contract manufacturing operations heads, and cold-chain logistics specialists were cross-validated against FDA GRAS notification filings and FSSAI regulatory amendments. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, and distribution channel dimensions.
Forecast inputs span strain-specific health claim substantiation timelines, cold-chain infrastructure buildout trajectories, and regulatory approval pathway durations across the analysis window. Segmentation modeling incorporated product type complexity tiers, end-user documentation obligations, packaging sterilization standards, and channel margin capture potential. CAGRs were derived from elasticity-adjusted demand projections and capacity-constrained supply assumptions, with precision fermentation adoption curves and plant-based substitution rates as scenario variables.
Stress conditions across milk powder price volatility bands, SAMR approval timeline extensions, and EFSA health claim rejection probabilities were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding strain stability technology maturation and healthcare procurement consolidation trajectories. Quarterly review of SAMR strain registration queue lengths and EFSA opinion publication cadence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Disposable Curd Cups Market
Dairy Products
Halloumi Cheese Market
Dairy Products
Sour Milk Drinks Market
Dairy Products
Halal Cheese Market
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
Europe Dairy Based Beverages Market
Dairy Products
Butter Fat Fraction Market
Dairy Products
Organic Cheese Powder Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
Buttermilk Powder Market
Dairy Products
North America Dairy Desserts Market
Dairy Products
GCC UHT Milk Market
Dairy Products
United Kingdom Dairy Market
Dairy Products
Sheep Milk Market
Dairy Products
Yogurt Drink Market
Dairy Products
GCC Dairy Market