
 Bakery Cases Market | 2026-2036
Bakery Cases Market Size, Share, and Industry Trends Forecast 2026-2036
Bakery Cases Market Outlook
NSF/ANSI Standard 7 certification for commercial refrigerators and freezers is reorganizing competitive dynamics in the bakery cases sector, filtering out suppliers lacking validated temperature performance documentation. Federal Industries sustains market presence through extensive vertical integration across metal fabrication and refrigeration assembly. True Manufacturing Co., Inc. anchors its position with domestic U.S. manufacturing scale and broad distribution network coverage. Hussmann Corporation differentiates through technology leadership in energy-efficient refrigeration systems for retail environments.
Bakery cases are enclosed display units engineered to maintain controlled temperature, humidity, and visibility for baked goods, typically constructed with tempered glass panels, insulated metal frames, and forced-air or gravity-coil refrigeration systems operating between 35°F and 40°F for preservation or 150°F to 180°F for heated holding. Their primary commercial purpose centers on extending product freshness windows while enabling visual merchandising that drives impulse purchases at point-of-sale locations. Refrigerated cases command the largest installed base due to universal requirements for cream-filled and perishable item storage, while heated cases represent the fastest-expanding category as grab-and-go hot pastry programs proliferate in convenience-oriented retail formats. Glass-front configurations continue to dominate material specifications for visibility optimization, though metal framing gains share in high-traffic environments demanding structural durability.
The U.S. Environmental Protection Agency's SNAP program and the Department of Energy's commercial equipment efficiency standards jointly constrain refrigerant selection and energy consumption benchmarks for bakery case manufacturers serving the North American market. European manufacturers face parallel constraints through the F-Gas Regulation and Ecodesign requirements administered by the European Commission, while China's Ministry of Ecology and Environment enforces dual carbon goals that shape domestic production standards. Stakeholders must monitor evolving refrigerant phase-down schedules and efficiency tier upgrades across these jurisdictions to align product development roadmaps with compliance timelines and avoid stranded inventory positions.
Market Dynamics
Supermarket chains are expanding fresh bakery footprints and upgrading display infrastructure, forcing case manufacturers to reconcile energy efficiency mandates with merchandising visibility requirements across refrigerated and heated product lines.
Growth Catalysts
- DOE Commercial Refrigeration Standards:U.S. Department of Energy efficiency mandates are accelerating replacement cycles for legacy equipment and pulling demand toward low-GWP refrigerant systems with improved insulation.
- China's Western-Style Retail Formats:Rapid urbanization across tier-one and tier-two cities is driving bakery case installations as domestic supermarket chains replicate European fresh-food merchandising concepts.
- Grab-and-Go Hot Pastry Programs:Convenience-oriented retail formats are expanding heated holding case deployments to capture impulse purchases at point-of-sale locations.
Market Restraints
- Copper and Aluminum Input Volatility:Refrigeration coil manufacturing faces margin compression from base metal price swings that resist full pass-through to price-sensitive retail buyers.
- NSF/ANSI Standard 7 Certification Barriers:Third-party validation requirements for temperature performance documentation filter out smaller fabricators lacking testing infrastructure.
- Refrigerant Phase-Down Schedules:EPA SNAP program constraints and EU F-Gas Regulation timelines create inventory stranding risk for cases using phased refrigerants.
Strategic Opportunities
- India's Organized Retail Expansion:FSSAI food safety enforcement and modern trade format growth create first-mover positioning for case suppliers establishing local assembly partnerships.
- IoT-Enabled Remote Monitoring Convergence:Integration of temperature logging sensors with predictive maintenance platforms enables subscription-based service revenue models.
- EU Ecodesign Tier Upgrades:European Commission efficiency mandate escalations reward early movers with certified product portfolios ahead of 2027 compliance deadlines.
Industry Challenges
- Refrigeration Technician Shortages:Specialized servicing capabilities for low-GWP systems remain concentrated among limited contractor networks, constraining aftermarket support scaling.
- Legacy Control System Integration:Retrofitting smart monitoring hardware into installed base cases requires protocol bridging that extends deployment timelines and elevates field failure rates.
- Dual Certification Complexity:Simultaneous NSF/ANSI 7 and UL safety compliance pathways demand redundant testing expenditures that disproportionately burden mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakery Cases Market |
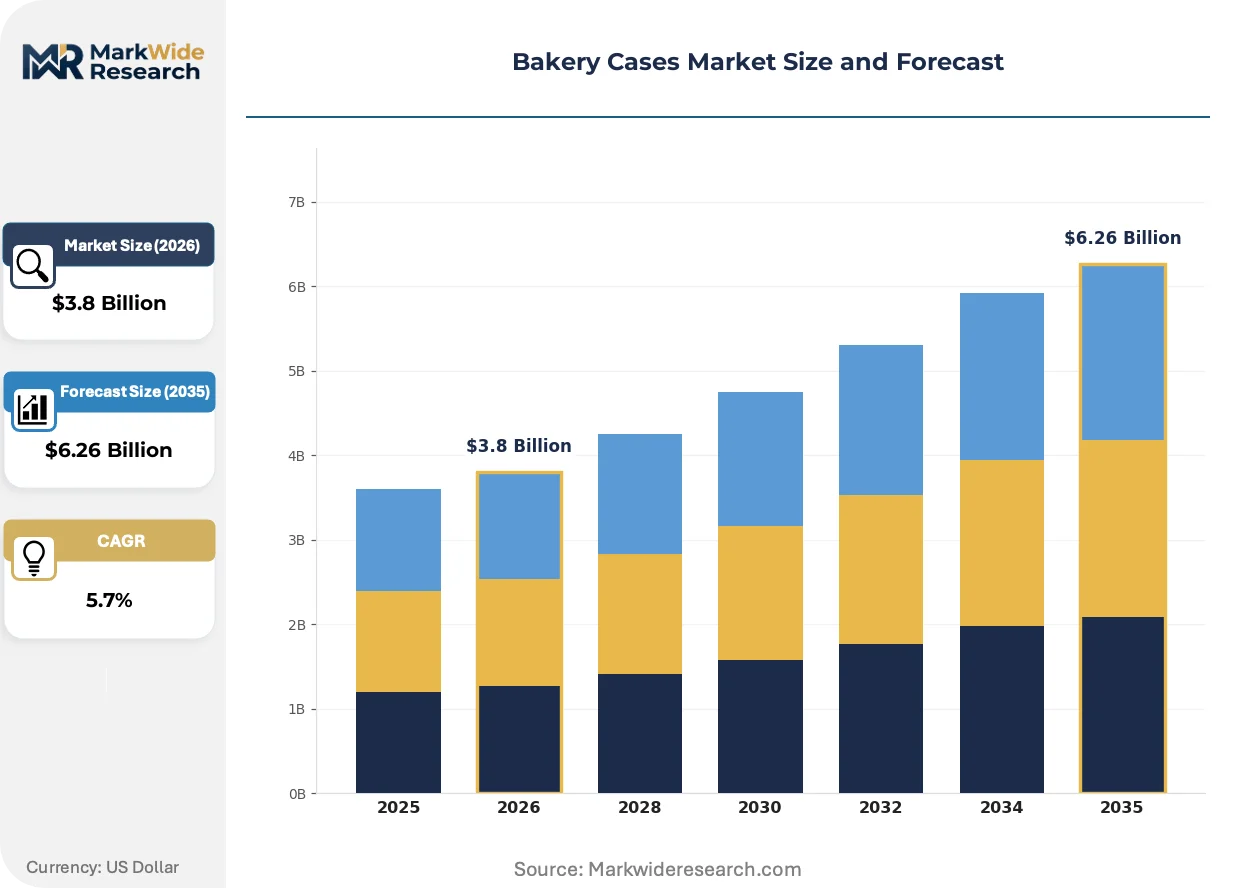
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Display Cases, Refrigerated Cases, Heated Cases, Bakery Showcases End User: Retail Bakeries, Supermarkets, Cafés, Restaurants Material: Glass, Metal, Wood, Plastic Size: Countertop, Full-Height, Half-Height, Custom Size |
| Companies Covered | Federal Industries, Turbo Air, True Manufacturing Co., Inc., Vollrath Company, Standex International Corporation, Structural Concepts Corporation, Hussmann Corporation, AHT GmbH, Hillphoenix, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakery Cases Market Strategic Shifts
Refrigeration architecture is fragmenting into modular, serviceable subsystems that separate display engineering from cooling performance, enabling independent upgrade cycles and challenging integrated case manufacturers.
Gravity-coil refrigeration is decomposing the traditional forced-air monopoly in bakery case cooling. Artisan bakery chains and specialty retailers are adopting gravity-coil systems for humidity-sensitive croissant and pastry preservation. This technology is decomposing the standardized case platform model by enabling humidity-zone customization that forced-air systems cannot replicate without energy penalties.
The EPA SNAP program and EU F-Gas Regulation are synchronizing refrigerant transition timelines across North America and Europe. Natural refrigerant architectures using CO2 and hydrocarbon propellants are capturing specification share in new-build supermarket projects. Refrigerated case lines using HFC-404A and R-507 face accelerated obsolescence as these jurisdictions enforce parallel phase-down schedules through 2030.
Supermarket procurement teams are consolidating bakery case specifications under national facilities management contracts rather than decentralized store-level purchasing. This buyer concentration is compressing vendor rosters and elevating total-cost-of-ownership analytics over upfront equipment pricing. The shift is most visible in U.S. and German grocery chains where centralized sustainability scoring now governs refrigeration equipment selection.
Bakery Cases Market Segmentation
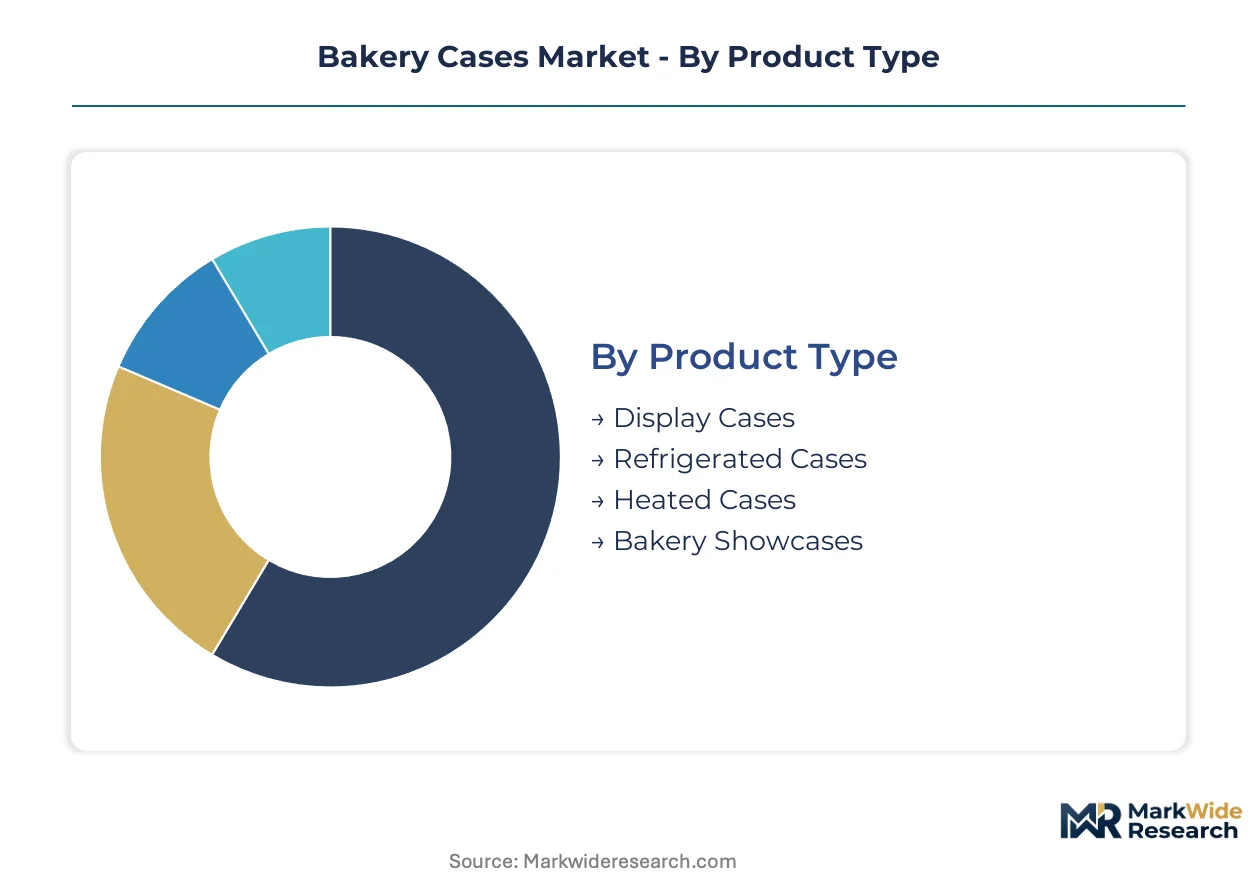
Bakery case procurement patterns diverge sharply across temperature requirements, merchandising formats, and installation constraints. Regulatory pressure on refrigerant chemistry and energy efficiency is fragmenting product architectures, while end-user scale determines whether buyers prioritize standardized platforms or custom-engineered solutions.
Product Type:
EPA SNAP program constraints and EU F-Gas Regulation phase-down schedules are forcing divergent engineering investments across temperature-controlled versus ambient display architectures.
- Refrigerated Cases:Forced-air and gravity-coil cooling systems maintain 35°F to 40°F for cream-filled and perishable preservation. Supermarket chains in Germany and France are consolidating procurement under national facilities contracts that mandate low-GWP refrigerant compatibility.
- Heated Cases:Forced-air convection or radiant heat systems operate between 150°F and 180°F for grab-and-go pastry holding. Convenience-oriented formats in U.S. urban corridors are deploying these at point-of-sale locations to capture impulse traffic.
- Display Cases:Ambient temperature units prioritize visual merchandising without active climate control. Specialty retailers in Japan favor these for short-shelf-life items with rapid inventory turns.
- Bakery Showcases:Hybrid configurations combine refrigerated base storage with ambient display shelving. Artisan bakery chains in Italy specify these for mixed-product merchandising.
Established volume favors refrigerated cases; emerging adoption favors heated cases.
End User:
Procurement scale and technical sophistication separate centralized national buyers from fragmented independent operators.
- Supermarkets:National facilities management contracts govern refrigeration equipment selection with centralized sustainability scoring. U.S. and German grocery chains are compressing vendor rosters around total-cost-of-ownership analytics.
- Retail Bakeries:Independent operators prioritize upfront equipment pricing over lifecycle efficiency. China's tier-one and tier-two cities are driving installations as domestic chains replicate European fresh-food concepts.
- Cafés:Limited footprint constraints favor countertop and half-height configurations. Grab-and-go program expansion in South Korean convenience formats is accelerating heated case deployments.
- Restaurants:Back-of-house integration requirements dominate specification, with NSF/ANSI Standard 7 certification filtering out smaller fabricators lacking testing infrastructure.
Procurement concentration favors supermarkets; format experimentation favors cafés.
Material:
Durability requirements and visibility optimization trade off differently across high-traffic versus boutique environments.
- Glass:Tempered panels maximize product visibility for impulse merchandising. Front configurations continue to dominate specifications despite structural limitations in high-traffic settings.
- Metal:Insulated frames provide structural durability for heavy-use retail environments. Supermarket chains in the United States specify these for extended service life under continuous operation.
- Wood:Aesthetic warmth targets premium positioning in artisan bakery formats. Italian and French specialty retailers favor these for brand differentiation.
- Plastic:Lightweight construction enables mobility and reconfiguration. Temporary and seasonal installations in Japan utilize these for operational flexibility.
Visibility optimization favors glass; structural durability favors metal.
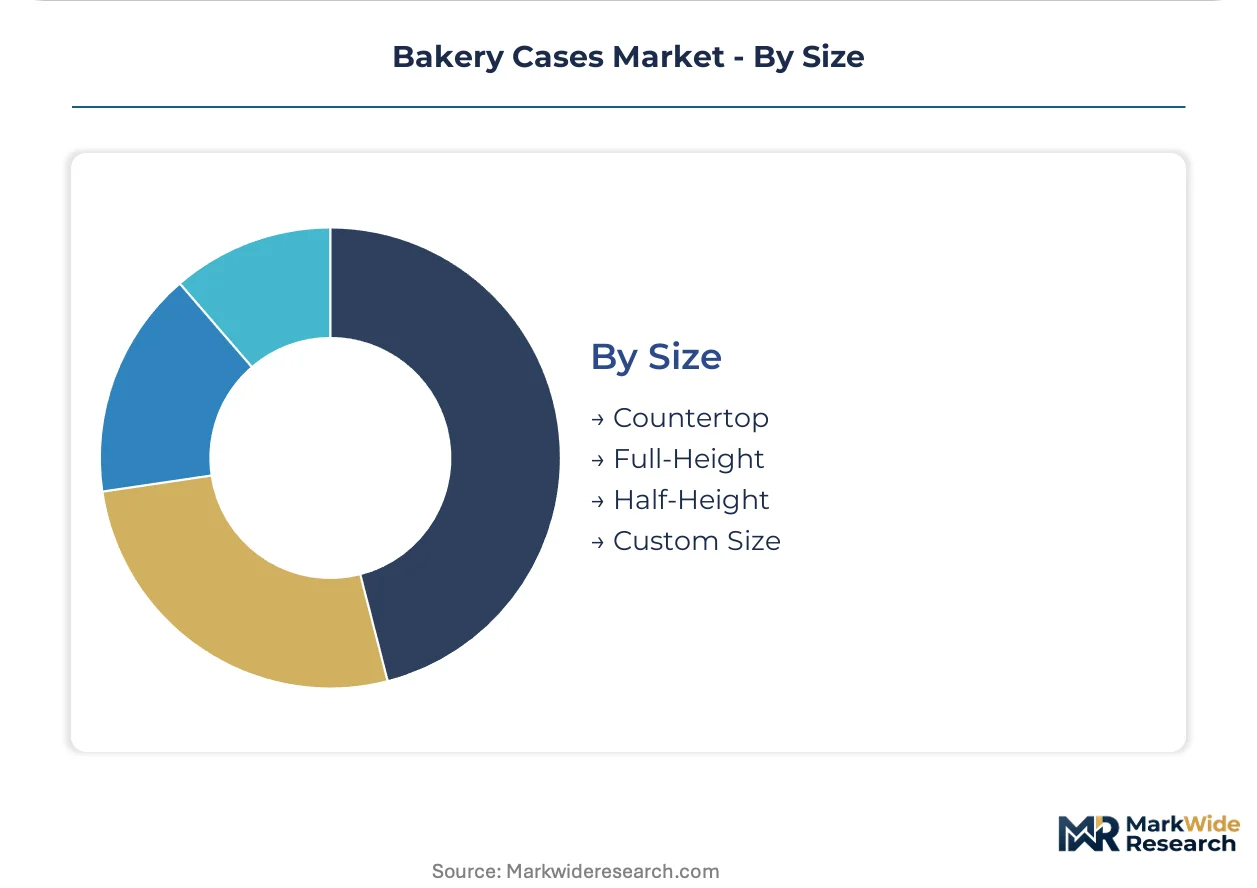
Size:
Real estate constraints and product mix breadth determine dimensional requirements across installation environments.
- Full-Height:Vertical merchandising maximizes product facings per linear foot of floor space. Large-format supermarkets in Germany deploy these for extensive fresh bakery footprints.
- Countertop:Compact footprints adapt to space-constrained cafés and convenience formats. South Korean urban retail is concentrating specification here.
- Half-Height:Intermediate scale balances visibility with spatial efficiency. Mid-size retail bakeries in China's tier-two cities favor these for mixed-product display.
- Custom Size:Bespoke engineering addresses non-standard architectural constraints. High-end hotel and restaurant chains in Japan specify these for integrated design schemes.
Standardization economics favor full-height; spatial adaptation favors custom size.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermarket chains and retail bakeries concentrate procurement authority differently across major economies, with centralized facilities management governing large-format deployments while independent operators drive fragmented demand in emerging markets.
United States
Grab-and-go hot pastry programs at convenience stores and urban cafés are accelerating heated case deployments. The EPA SNAP program constrains refrigerant selection for new installations. Texas and Florida supermarket expansions are pulling refrigerated case demand toward low-GWP systems with improved insulation.
China
Domestic supermarket chains in tier-one and tier-two cities are replicating European fresh-food merchandising concepts. The Ministry of Ecology and Environment enforces dual carbon goals that shape domestic production standards. Shanghai and Beijing retail clusters are driving bakery case installations across Western-style bakery formats.
Germany
Large-format grocers are consolidating bakery case procurement under national facilities contracts with centralized sustainability scoring. The EU F-Gas Regulation and Ecodesign requirements constrain equipment specifications. Bavaria and North Rhine-Westphalia supermarket chains are compressing vendor rosters around total-cost-of-ownership analytics.
Japan
Specialty retailers favor ambient display units for short-shelf-life items with rapid inventory turns. METI standards govern commercial refrigeration efficiency benchmarks. Tokyo and Osaka convenience formats are accelerating heated case deployments for grab-and-go programs.
India
Modern trade format growth and FSSAI food safety enforcement are creating first-mover positioning for case suppliers. Organized retail expansion in Maharashtra and Karnataka is driving installations as domestic chains adopt Western-style bakery retail formats.
Bakery Cases Market Competitive Environment
Player mix skews toward vertically integrated metal fabricators with captive refrigeration assembly capabilities. The vendor base separates into three tiers: multinational refrigeration specialists with national account coverage, mid-scale domestic manufacturers serving regional supermarket chains, and boutique fabricators targeting artisan bakery formats. Strategic moves concentrate on backward integration into coil manufacturing and geographic expansion through distribution partnerships.
Among U.S.-based manufacturers, Federal Industries and True Manufacturing Co., Inc. exemplify the vertically integrated archetype with domestic fabrication scale. Hussmann Corporation occupies a position within the energy-efficient systems tier. AHT GmbH represents European engineering-focused participation. These anchors illustrate how regulatory pressure on refrigerant chemistry and efficiency standards is filtering competitive positioning toward capital-intensive players with certification infrastructure.
| Leading Market Players |
|---|
| Federal Industries |
| Turbo Air |
| True Manufacturing Co., Inc. |
| Vollrath Company |
| Standex International Corporation |
| Structural Concepts Corporation |
| Hussmann Corporation |
| AHT GmbH |
| Hillphoenix, Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with supermarket chains lock in refrigeration coil supply and price visibility across volatile aluminum and copper indexation cycles. These arrangements shield tier-one manufacturers from spot market swings while compressing margins for mid-tier fabricators lacking backward integration into metal forming.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate procurement between case manufacturers and supermarket chains. Three-tier pricing structure across NSF-certified premium, standard commercial, and uncertified economy levels separates Federal Industries and True Manufacturing from regional competitors. Pricing pressure stems from copper and aluminum input volatility that resists full pass-through to price-sensitive retail bakeries. Independent operators exhibit highest price sensitivity; national grocery chains prioritize total-cost-of-ownership analytics over upfront equipment pricing.
Supply Chain Analysis
Port congestion along Shanghai-Ningbo and Los Angeles-Long Beach corridors elevates inbound logistics costs for imported refrigeration compressors and tempered glass panels. Manufacturing gravity centers on China, the United States, and Germany for finished case assembly, with Mexico emerging for U.S.-bound production. Coil winding draws from copper cathode suppliers in Chile and aluminum smelters in Canada. Single-source vulnerability concentrates in low-GWP compressor technology from limited European suppliers. Distribution runs through national facilities management contracts rather than decentralized store-level purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigeration case servicing and IoT-enabled predictive maintenance subscriptions are expanding faster than hardware shipments, creating durable recurring revenue layers that improve customer lifetime value metrics.
For Market Incumbents: Fortify certification infrastructure against NSF/ANSI Standard 7 barriers that filter out smaller competitors. Deepen backward integration into refrigeration coil manufacturing to offset copper and aluminum price volatility. Expand captive servicing networks to address technician shortages for low-GWP system maintenance. For New Entrants and Emerging Players: NSF/ANSI 7 certification fast-track through third-party testing partnerships enables market entry without redundant capital expenditure. India's organized retail expansion in Maharashtra and Karnataka offers the most penetrable white space, with FSSAI enforcement creating compliance-based differentiation. Lead with countertop and half-height configurations for space-constrained café formats in South Korean urban corridors. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated metal fabricators with captive refrigeration assembly and established national account coverage. The five-to-ten year viability window favors players with certified low-GWP product portfolios ahead of EPA SNAP and EU F-Gas phase-down completion. Monitor refrigerant transition timelines as the critical inflection signal for inventory stranding risk and replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Manufacturing | Captive copper and aluminum forming insulates margins from LME volatility and secures supply continuity. |
| IoT Platform Integration | Remote temperature monitoring with predictive maintenance enables subscription revenue attachment to hardware sales. |
| NSF/ANSI 7 Certification Investment | Third-party validation documentation filters out smaller fabricators and consolidates vendor rosters around certified players. |
| Geographic Expansion through Distribution Partnerships | Local assembly partnerships in India and China reduce logistics exposure and accelerate compliance with domestic efficiency standards. |
| Natural Refrigerant Architecture Transition | CO2 and hydrocarbon systems capture specification share in new-build supermarket projects ahead of HFC phase-down deadlines. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, commercial refrigeration trade association reports, and EPA SNAP regulatory dockets. Interviews with supermarket facilities managers, refrigeration equipment procurement leads, aftermarket service technicians, and NSF certification auditors informed demand-side validation. Customs and trade data on aluminum and copper coil imports provided supply-side cross-checks. Bottom-up installation tracking across tier-one and tier-two Chinese cities triangulates against top-down manufacturer shipment estimates.
Segmentation dimensions modeled include temperature requirement architecture, end-user procurement scale, material durability specifications, and dimensional constraints across installation environments. CAGRs were derived from regression analysis of historical replacement cycles, regulatory compliance deadlines, and format expansion trajectories across the projection horizon. Forecast inputs incorporate DOE efficiency standard escalation timelines, EU Ecodesign tier upgrade schedules, and urbanization-driven retail format penetration in emerging markets.
Decision-makers should treat outputs as directional under assumptions of sustained supermarket footprint expansion and refrigerant transition adherence; material deviation in copper price trajectories or phase-down acceleration would warrant model refresh. Practitioners should keep alternative scenarios live as EPA SNAP enforcement intensity and EU F-Gas Regulation amendment cycles evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Pie Shells Market
Bakery Products
Europe Sourdough Market
Bakery Products
Premixed Bread Flour Market
Bakery Products
Sweet Biscuits Market
Bakery Products
India Cake Market
Bakery Products
Sourdough Market
Bakery Products
Biscuit Mixes Market
Bakery Products
Pizza Dough Balls Market
Bakery Products
Teaseed Cake Market
Bakery Products
Marzipan Market
Bakery Products
Low Calorie Bread Market
Bakery Products
Batter and Breader Premixes Market
Bakery Products
Global Cake Mix Market
Bakery Products
Fortified Bakery Market
Bakery Products
Low Fat Bran Muffins Market
Bakery Products
Doughnuts Market