
 Natural Cheese Market | 2026-2036
Natural Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Cheese Market Analysis
Plant-based casein alternatives is realigning traditional whey recovery economics as dairy processors adapt ingredient streams. Lactalis Group leverages captive milk supply networks across France to secure raw material continuity. Arla Foods anchors its cooperative structure in Scandinavian sourcing, sustaining farmer-guaranteed volumes. Fonterra Co-operative Group dominates Oceania milk powder channels, extending its natural cheese ingredient reach into Asian food manufacturing.
Natural cheese comprises fermented curd from milk coagulated by rennet or bacterial cultures, aged under controlled temperature and humidity to develop flavor profiles and textural integrity. Its primary commercial purpose centers on delivering unprocessed dairy identity in retail, foodservice, and industrial formulations where ingredient transparency commands premium positioning. Cheddar occupies the largest volume share among product types, reflecting its versatility across melting applications and extended shelf stability. Shredded form is gaining traction in foodservice channels where labor reduction drives procurement decisions. Vacuum-sealed packaging captures margin concentration by preserving freshness during extended distribution cycles.
FDA dairy identity standards enforce milkfat minimums and restrict artificial additives in products labeled natural cheese within the United States. EFSA and EU Green Deal frameworks mandate methane reduction targets and sustainable feed sourcing across European dairy operations, reshaping farm-level compliance costs. USDA organic certification and state-level dairy pricing orders in Wisconsin and California further stratify market access tiers. Stakeholders must monitor evolving feed-input costs and carbon-accounting requirements as procurement criteria tighten across retail and foodservice buyer specifications.
Market Dynamics
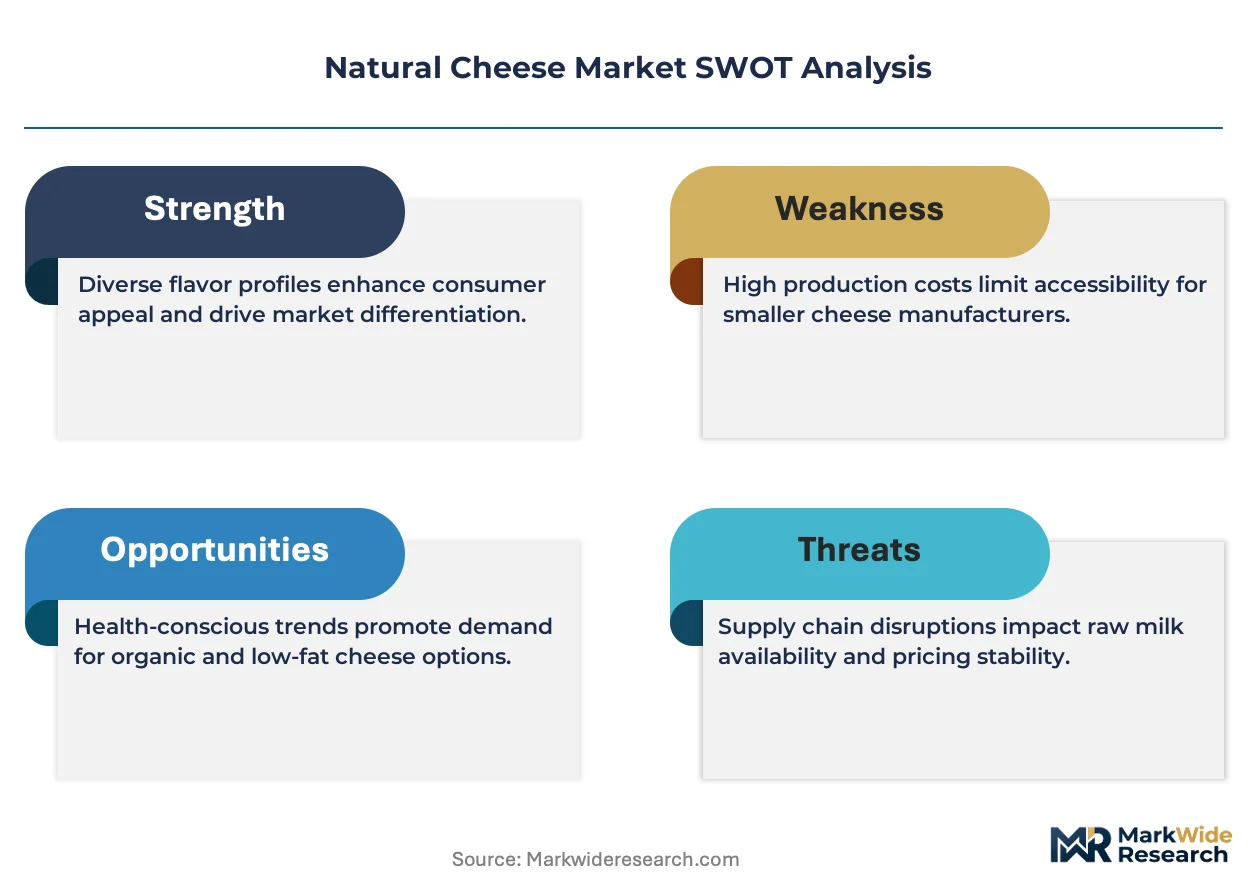
Clean-label mandates from EU Green Deal frameworks are forcing dairy processors to restructure feed sourcing and methane accounting across their supplier networks, compressing margin structures while opening premium positioning for compliant producers.
Growth Catalysts
- EU Green Deal methane targets:Member states now enforce binding emission reductions across dairy herds, creating certified supply scarcity that commands price premiums in German and French retail channels.
- Foodservice labor automation:Pre-shredded and portion-controlled natural cheese formats are displacing block cutting in quick-service restaurant back-of-house operations, driving volume concentration in industrial shredding facilities.
- Plant-based casein convergence:Precision fermentation-derived dairy proteins are entering ingredient streams, enabling hybrid natural cheese formulations that reduce conventional milkfat dependence while maintaining label claims.
Market Restraints
- Feed input cost volatility:Soybean and alfalfa price swings in Black Sea and North American sourcing regions transmit directly to farm-gate milk costs, compressing processor margins without corresponding retail price elasticity.
- Artisan capacity concentration:Traditional aged cheddar and alpine-style production remains clustered in Wisconsin, Somerset, and Emilia-Romagna, creating geographic supply vulnerability to climate-induced milk yield fluctuations.
- FDA identity standard friction:Strict milkfat minimums and additive prohibitions block formulation flexibility for reduced-fat natural cheese positioned against plant-based alternatives in US retail.
Strategic Opportunities
- Asian food manufacturing integration:Japanese and South Korean processed food producers are expanding natural cheese inclusion in ready-meal and bakery applications, creating export demand for Oceania and European commodity-grade cheddar.
- USDA organic certification arbitrage:Organic feed cost premiums are narrowing against conventional inputs in California and Wisconsin, enabling mid-scale dairies to capture retail shelf-space gains in US natural and specialty grocery.
- Direct-to-foodservice channel development:Specialized distributors are bypassing traditional wholesale layers to supply pizzeria and casual dining chains with customized shred blends and portion specifications.
Industry Challenges
- Aging workforce in farm operations:Master cheesemaker and herd management expertise is concentrating near retirement age in French PDO zones and Vermont artisan clusters, constraining quality consistency in premium segments.
- Carbon accounting system integration:Dairy cooperatives face complex data collection requirements across fragmented farm footprints to satisfy EU CSRD disclosure mandates and buyer procurement specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Cheese Market |
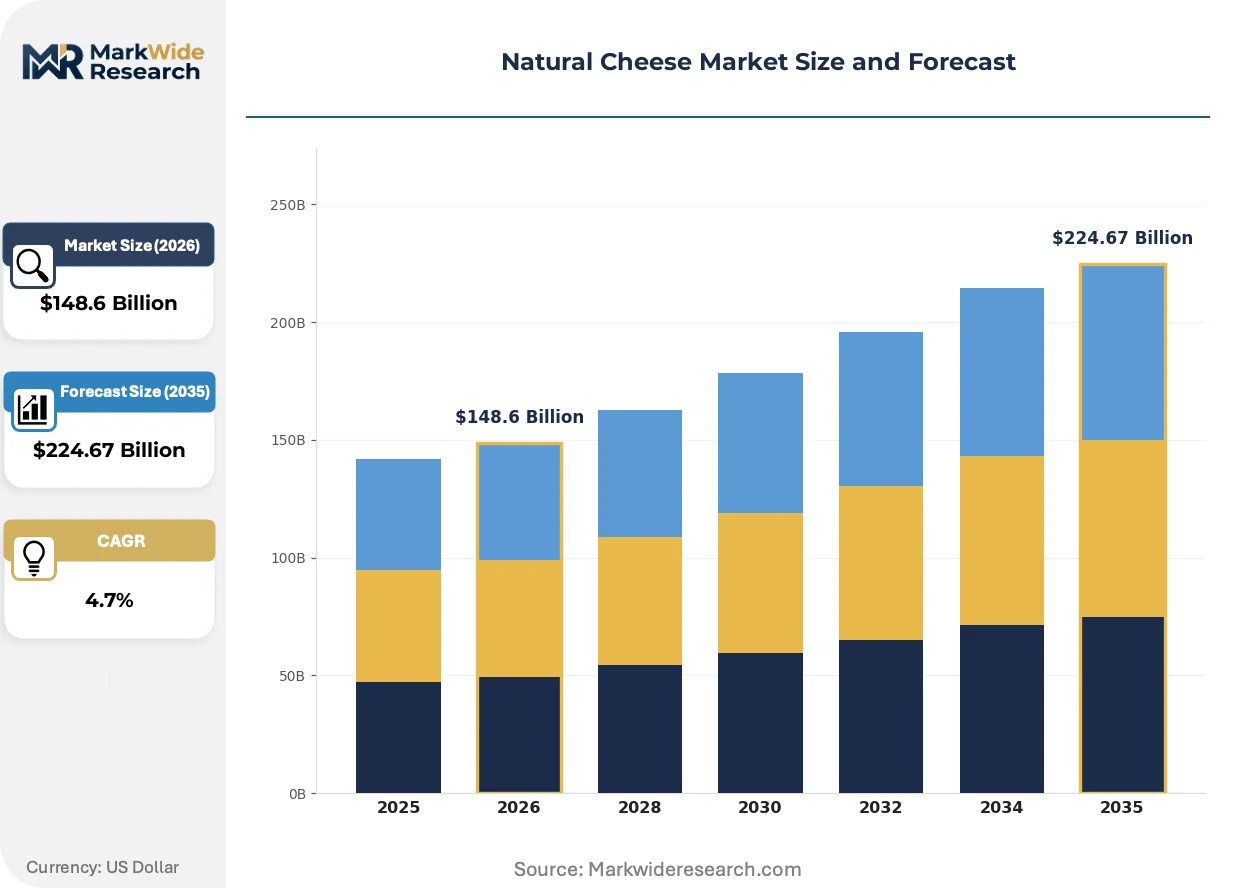
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $224.67 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheddar, Mozzarella, Gouda, Parmesan Form: Block, Shredded, Sliced, Grated Packaging Type: Vacuum Sealed, Plastic Wrap, Bulk, Retail Packs End User: Households, Foodservice, Manufacturers, Retailers |
| Companies Covered | Lactalis Group, Saputo Inc., Arla Foods, Fonterra Co-operative Group, Dairy Farmers of America, Kraft Heinz, Hilmar Cheese Company, Leprino Foods, Bel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Cheese Market Emerging Trajectories
Digital monitoring systems and biological process controls are converging across natural cheese production, enabling precision maturation management and supply chain traceability that reshape competitive differentiation beyond traditional origin branding.
Smart aging environments equipped with IoT-enabled humidity and temperature sensors are consolidating quality control functions previously distributed across manual cellar management. Italian grana and Dutch gouda producers are deploying these systems at scale, reducing batch-to-batch variation and compressing the skilled labor intensity of extended maturation programs.
EFSA novel food approval pathways for precision fermentation ingredients are consolidating regulatory clarity for hybrid natural cheese formulations. European processors are accelerating dossier submissions for fermented casein and whey proteins, enabling product launches that maintain dairy identity while reducing conventional milk volume dependence in formulations targeting climate-conscious buyers.
Ingredient transparency specifications from retail and foodservice procurement teams are consolidating supplier qualification criteria around third-party audit standards. Clean-label requirements now extend to feed sourcing and animal welfare documentation, with French and German retail chains demanding farm-level traceability that smaller cooperatives struggle to digitize without shared platform investments.
Natural Cheese Market Segmentation
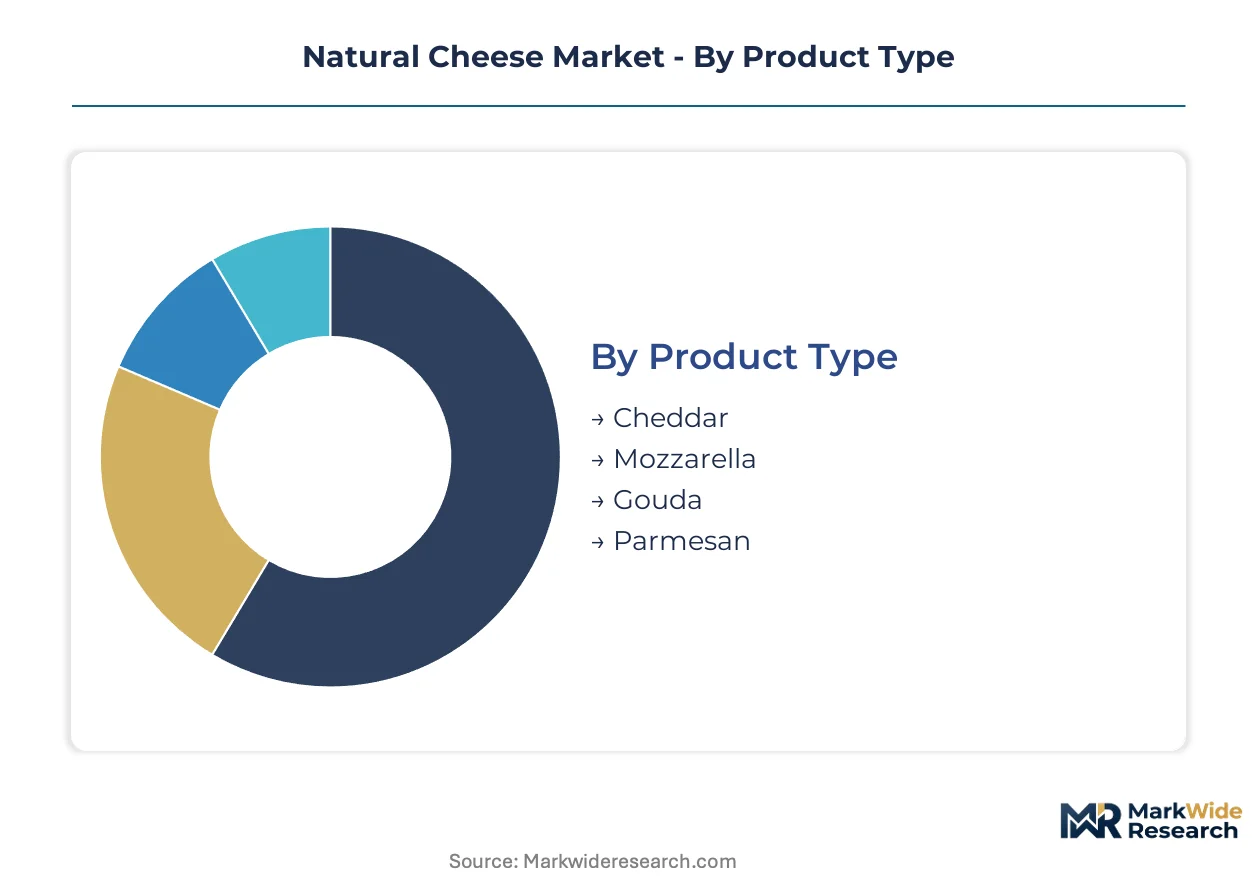
Natural cheese segmentation determines compliance pathways, margin structures, and channel access. Each dimension carries distinct certification burdens from FDA identity standards to EU Green Deal methane accounting. Procurement teams weight these categories differently across retail, foodservice, and industrial buyer specifications.
Product Type:
Cheddar and mozzarella carry FDA milkfat minimums and EU PDO geographical protections, while gouda and parmesan face additional aging documentation requirements under EFSA frameworks.
- Cheddar:Fermented curd aged under controlled humidity develops sharp flavor profiles across 3-24 month maturation cycles. Foodservice demand concentrates in quick-service restaurant melt applications across the United States, where labor automation drives shredded format procurement.
- Mozzarella:High-moisture pasta filata structure delivers stretch functionality critical for pizza applications. Italian and American pizzeria chains in Germany and France are expanding portion-controlled fresh mozzarella programs, tightening moisture specification compliance.
- Gouda:Dutch-origin washed-curd cheese with semi-hard texture ranging from young to aged variants. EFSA feed documentation requirements apply to protected designation origin supply.
- Parmesan:Granular hard cheese requiring minimum aging periods under Italian PDO protocols. Extended maturation creates carbon accounting complexity for EU CSRD disclosure mandates.
Leading the category by volume: Cheddar. Growing fastest: Mozzarella.
Form:
Block formats retain highest margin capture for artisan producers, while shredded and sliced forms concentrate industrial volume through foodservice automation economics.
- Block:Traditional cutting format preserving moisture integrity during extended distribution. Wisconsin and Somerset creameries dominate aged cheddar block production for specialty retail channels.
- Shredded:Pre-cut formats eliminating back-of-house labor in pizzeria and casual dining operations. Quick-service chains in the United States are standardizing proprietary shred blends with anti-caking specifications.
- Sliced:Uniform thickness portions for sandwich assembly and deli applications. Retail deli counters in France and Germany prefer sliced emmental and gouda for platter configurations.
- Grated:Fine particle size for topping and ingredient dispersion. Italian food manufacturers integrate grated parmesan into ready-meal formulations for Japanese and South Korean export markets.
Highest margin concentration: Block. Steepest volume expansion: Shredded.
Packaging Type:
Vacuum-sealed formats command shelf-life premiums, while bulk configurations minimize unit costs for industrial food manufacturing procurement.
- Vacuum Sealed:Oxygen-exclusion technology extending freshness through 90-180 day distribution cycles. Premium retail positioning in German and French supermarkets requires modified atmosphere compliance documentation.
- Plastic Wrap:Cost-efficient barrier protection for short-turnover retail segments. Conventional grocery channels in the United States favor overwrapped blocks for price-competitive positioning.
- Bulk:Foodservice totes and industrial totes for manufacturing integration. Pizza chains and processed food producers in Japan source bulk shredded cheddar through Oceania export channels.
- Retail Packs:Consumer-portioned formats with label transparency specifications. USDA organic certification appears on retail packs in California and Wisconsin natural grocery segments.
Widest retail penetration: Vacuum Sealed. Fastest foodservice adoption: Bulk.
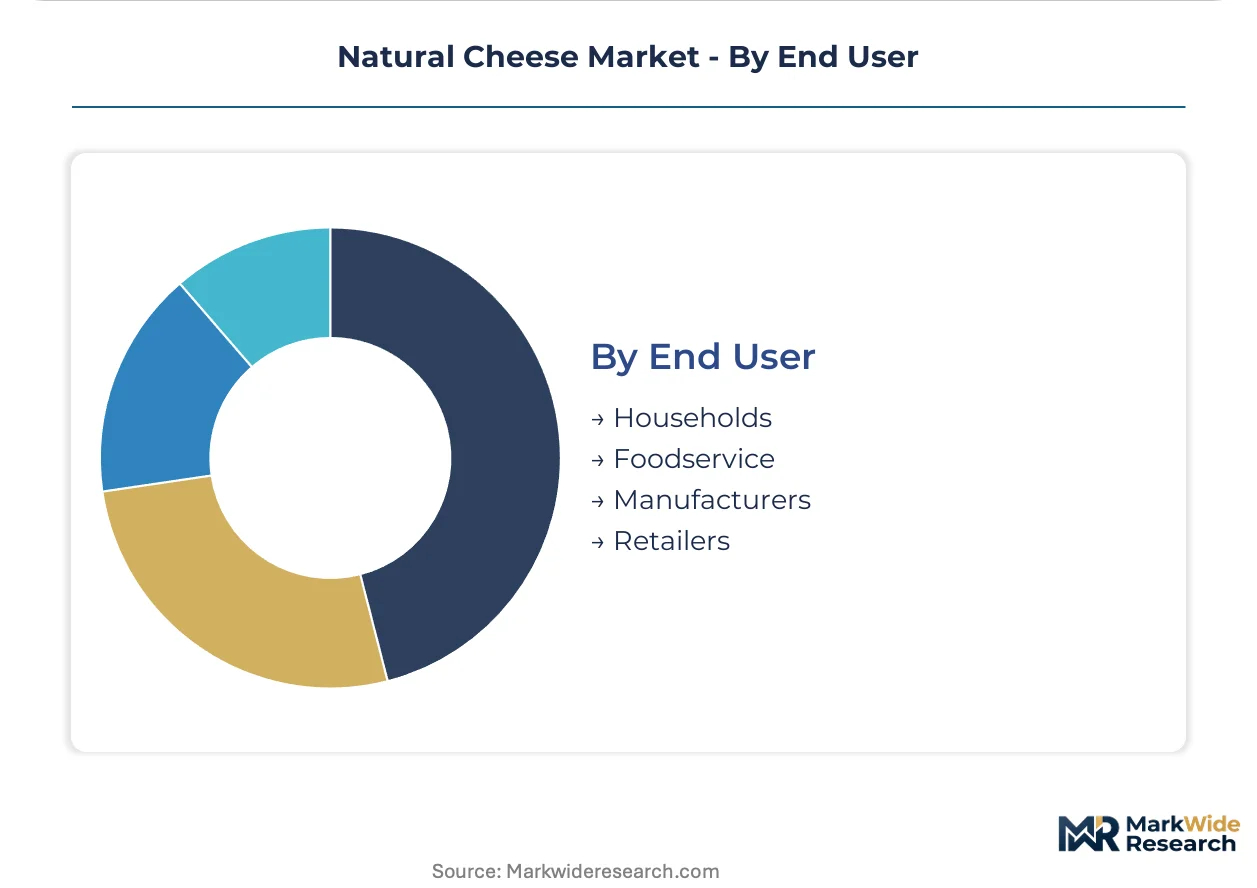
End User:
Household and foodservice segments diverge sharply on certification visibility, with manufacturers and retailers intermediating compliance documentation across supply tiers.
- Households:Consumer-direct purchases through grocery and specialty retail channels. Clean-label preferences in French and German households drive farm-level traceability demands.
- Foodservice:Restaurant, catering, and institutional procurement with labor-cost optimization priorities. Pre-shredded and portion-controlled formats are displacing block cutting in United States quick-service back-of-house operations.
- Manufacturers:Processed food and ready-meal producers integrating natural cheese as ingredient inputs. Japanese and South Korean bakery and convenience food manufacturers are expanding cheddar inclusion rates.
- Retailers:Private-label and branded assortment curators setting supplier qualification criteria. French and German retail chains now mandate third-party audit standards extending to feed sourcing documentation.
Largest volume absorption: Foodservice. Fastest procurement specification tightening: Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wisconsin's dairy processor tax credit zone concentrates natural cheese production infrastructure, drawing milk supply from surrounding Upper Midwest feedlot operations into aging and packaging facilities.
United States
Quick-service restaurant chains in the Midwest and Southeast are expanding proprietary shred blend specifications for back-of-house automation. FDA dairy identity standards enforce milkfat minimums that constrain reduced-fat formulation flexibility. Wisconsin and California anchor production gravity, with Hilmar Cheese Company and Leprino Foods operating large-scale shredding and portion-control facilities serving national pizza chains.
Germany
Retail chains in Bavaria and North Rhine-Westphalia are tightening farm-level traceability requirements for private-label gouda and emmental assortments. EU Green Deal methane reduction targets bind dairy cooperatives to documented feed sourcing and herd management protocols. The Münsterland cheese cluster faces compliance cost pressure as EFSA documentation requirements extend to protected designation origin supply chains.
France
PDO-protected cheddar and alpine-style production in Auvergne-Rhône-Alpes commands shelf-space premiums in Parisian specialty retail. ANSM and DGCCRF enforcement of origin labeling intensifies documentation burdens for Comté and Beaufort maturation cellars. Lactalis Group leverages captive milk networks across Normandy and Brittany to secure raw material continuity for export-grade formulations.
Italy
Grana padano and parmesan producers in Emilia-Romagna are deploying IoT-enabled aging environments to reduce batch-to-batch variation and skilled labor intensity. EFSA novel food approval pathways for precision fermentation ingredients are consolidating regulatory clarity for hybrid formulations. The Po Valley dairy belt concentrates aging infrastructure within 150 kilometers of Modena and Parma processing facilities.
Japan
Processed food manufacturers in Kanto and Kansai are expanding natural cheese inclusion rates in ready-meal and bakery applications for domestic and export markets. METI import standards and labeling requirements shape procurement specifications for Oceania-sourced commodity cheddar. Tokyo-based distributors are consolidating direct-to-manufacturer channels that bypass traditional wholesale layers for bulk shredded formats.
Natural Cheese Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with cooperative structures dominating milk supply security while publicly traded processors concentrate foodservice channel development. The vendor base organizes around three archetypes: captive milk supply cooperatives, diversified dairy conglomerates, and specialized shredding and ingredient processors. M&A activity targets regional creamery networks for PDO access, while capacity expansion concentrates in automated shredding and portion-control facilities serving quick-service restaurant specifications.
Within the cooperative archetype, Fonterra Co-operative Group and Arla Foods exemplify farmer-owned structures that anchor milk supply security through guaranteed volume arrangements. Lactalis Group occupies a position among diversified dairy conglomerates with integrated processing and distribution spanning multiple geographies. These three entities represent distinct strategic postures: cooperative governance prioritizing farmer returns, private capital deployment across brand portfolios, and hybrid structures balancing member equity with commercial expansion.
| Leading Market Players |
|---|
| Lactalis Group |
| Saputo Inc. |
| Arla Foods |
| Fonterra Co-operative Group |
| Dairy Farmers of America |
| Kraft Heinz |
| Hilmar Cheese Company |
| Leprino Foods |
| Bel Group |
| Others |
Supply Flow & Price Mechanics
EU Green Deal methane reduction mandates gate access to premium-tier natural cheese pricing by restricting qualified milk supply to documented low-emission herds, compressing availability while amplifying price premiums for compliant producers serving German and French retail channels.
Pricing Analysis
Lead-time-driven pricing stratifies across maturation duration, with extended-aged cheddar and parmesan commanding premiums for inventory commitment while young gouda and mozzarella trade at discounts reflecting spot availability. Three-tier pricing structure across PDO-certified premium, standard commercial grade, and private-label economy levels differentiates by certification depth and farm-level traceability documentation. Pricing pressure stems from feed input cost volatility transmitting through Black Sea and North American alfalfa sourcing regions without corresponding retail price elasticity. Foodservice buyers exhibit highest price sensitivity due to volume procurement and shred-format commoditization, while specialty retail channels absorb premium positioning with limited elasticity.
Supply Chain Analysis
Master cheesemaker and herd management workforce availability constrains capacity expansion in French PDO zones and Vermont artisan clusters, where aging expertise concentrates near retirement age. Raw milk supply draws from Wisconsin, Normandy, and Emilia-Romagna production belts, with whey recovery economics shifting as plant-based casein alternatives enter ingredient streams. Single-source vulnerability runs through Italian grana padano aging cellars concentrated within 150 kilometers of Modena. Distribution runs through specialized foodservice distributors bypassing traditional wholesale layers for direct pizzeria and casual dining chain supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation-derived dairy proteins are displacing conventional milkfat dependence in hybrid natural cheese formulations, marking a technology-transition phase that reconfigures ingredient sourcing and margin structures across the value chain.
For Market Incumbents: Acquire regional creamery networks holding PDO designations in Auvergne-Rhône-Alpes and Emilia-Romagna to secure origin-protected supply scarcity against precision fermentation entrants. Invest in IoT-enabled aging environment deployment to reduce skilled labor intensity and compress batch-to-batch variation in extended maturation programs.
For New Entrants and Emerging Players: Direct-to-foodservice digital channels enable bypass of wholesale layers for customized shred blend supply to mid-scale pizzeria chains in Japan and South Korea. Target commodity-grade cheddar export demand from Oceania-sourced bulk formats for processed food manufacturing integration in Kanto and Kansai industrial corridors.
For Investors and Strategic Acquirers: EFSA novel food approval submissions for fermented casein ingredients are the leading indicator that hybrid formulation viability is consolidating, signaling platform transition timing. Mid-scale cooperatives with digitized farm-level traceability infrastructure represent prime acquisition archetypes as EU CSRD disclosure mandates tighten procurement qualification criteria.
| Strategic Initiative | Industry Significance |
|---|---|
| PDO Creamery Network Acquisition | Secures scarce origin-protected supply capacity against fermentation-based substitutes in French and Italian markets. |
| IoT Aging Environment Deployment | Reduces skilled labor dependence and batch variation in Emilia-Romagna grana padano maturation cellars. |
| Direct-to-Foodservice Channel Development | Bypasses wholesale margin layers for proprietary shred specification supply to quick-service restaurant chains. |
| Precision Fermentation Dossier Submission | EFSA approval pathways enable hybrid formulation launches maintaining dairy identity with reduced milk volume. |
| Farm-Level Traceability Digitization | Satisfies EU CSRD and retail procurement audit standards extending to feed sourcing documentation. |
Methodological Framework
Document review covered FDA dairy identity standards, EFSA novel food approval pathways, and EU Green Deal methane accounting frameworks, complemented by interviews with dairy cooperative procurement directors, foodservice chain category managers, and precision fermentation technology developers. Secondary sources included USDA organic certification databases, customs trade records for Oceania cheddar exports, and SEC filings from publicly traded dairy processors. Bottom-up volume modeling triangulated against top-down value projections across the analysis window.
Segment-level projections incorporated product type, form factor, packaging configuration, and end-user channel dynamics across the projection horizon. CAGRs were derived from trend extrapolation anchored to disclosed volume movements and pricing trajectories. Feed input cost indices and carbon accounting compliance burdens served as industry-specific forecast modifiers.
The model holds under stable regulatory enforcement of EU Green Deal targets and continued FDA identity standard maintenance; deviation in EFSA approval timelines for precision fermentation ingredients or abrupt feed commodity price shocks would shift volume and value trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
United Arab Emirates Dairy Market
Dairy Products
North America Condensed Milk Market
Dairy Products
China Milk Protein Market
Dairy Products
Organic Cheese Powder Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
Non-Fat Milk Market
Dairy Products
Global Cultured Dairy Products Market
Dairy Products
Green Tea Butter Market
Dairy Products
Asia-Pacific Casein and Caseinates Market
Dairy Products
Yogurt and Probiotic Drink Market
Dairy Products
Recombined Milk Products Market
Dairy Products
Reduced Lactose Whey Market
Dairy Products
United States Dairy Market
Dairy Products
Plain Yogurt Market
Dairy Products
Mozzarella Cheese Market
Dairy Products
Kefir Market