
 Ultra High Temperature Milk Market | 2026-2036
Ultra High Temperature Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra High Temperature Milk Market Intelligence
The expansion of online retail channels is rewriting traditional distribution models for UHT milk, enabling direct-to-consumer sales and broader geographic reach. Major producers are adapting to this shift. Lactalis Group extends its market presence through a diverse portfolio catering to both retail and food service. Danone Group leverages its brand strength in specialized products like lactose-free and organic UHT milk. Nestle SA competes on a global scale by optimizing its supply chain for mass-market penetration.
Ultra High Temperature milk is a dairy product that undergoes a thermal processing treatment at approximately 135–150°C for a few seconds. This process, known as UHT pasteurization, achieves commercial sterility, allowing the milk to be stored without refrigeration for several months. Flavored and lactose-free product types are capturing increased consumer interest. The market's structure depends on packaging, where Tetra Pak cartons dominate due to superior aseptic performance and logistical efficiency compared to plastic bottles or pouches.
Food safety and labeling regulations create the framework for market access and product formulation. In the United States, the FDA's Pasteurized Milk Ordinance governs processing standards. The European Union's regulations on food contact materials strictly control packaging integrity. China's State Administration for Market Regulation (SAMR) enforces GB standards for imported dairy products. Producers must navigate these divergent standards while managing consumer preferences for natural ingredients and sustainable packaging.
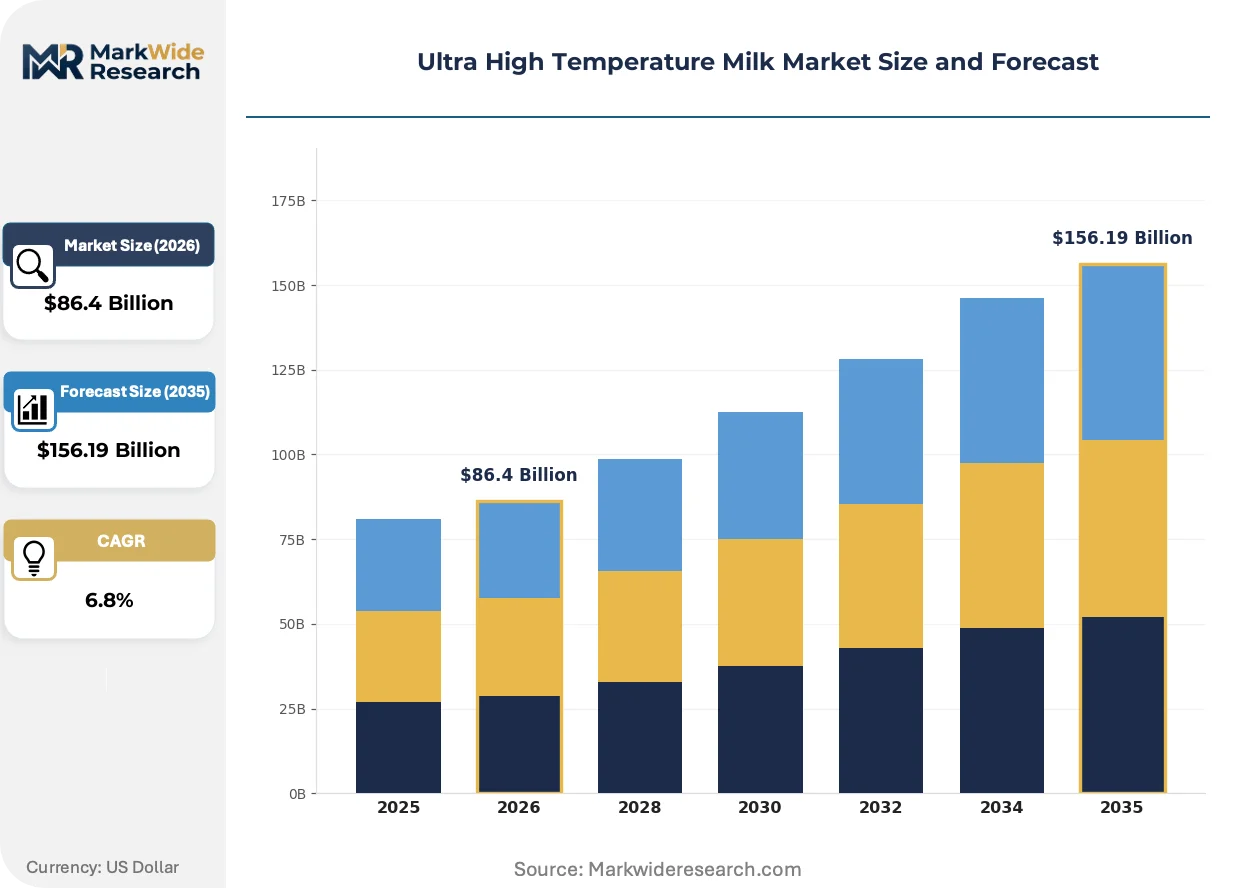
Market Dynamics
The central dynamic in the Ultra High Temperature milk market is the interplay between the logistical necessity of shelf-stability and evolving consumer demands for naturalness and nutritional value, pushing innovation in both processing technology and product formulation.
Growth Catalysts
- Food Service Demand:The expansion of coffee chains and quick-service restaurants, particularly in Asia-Pacific, creates consistent, large-volume demand for UHT milk as a shelf-stable, reliable ingredient for beverages and cooking.
- Aseptic Packaging Innovation:Advancements in multilayer carton technology, led by firms like Tetra Pak, enhance oxygen barriers and incorporate more sustainable materials, improving product quality and appealing to environmentally conscious consumers.
- Rural Market Access:In developing regions like rural China and India, where cold chain logistics are inconsistent, UHT milk provides essential access to safe, long-lasting dairy products for millions of consumers.
Market Restraints
- Consumer Taste Preference:A persistent perception in mature markets, such as North America and Western Europe, that UHT processing imparts a "cooked" flavor, making it less desirable than fresh pasteurized milk.
- Energy-Intensive Processing:The UHT pasteurization process consumes significant thermal energy, exposing producers to cost volatility linked to fluctuations in electricity and natural gas prices, thereby impacting margins.
- Competition from Plant-Based Alternatives:The rapid growth of shelf-stable plant-based milks, such as oat, almond, and soy, presents a direct substitution threat, competing for the same shelf space and consumer segments.
Strategic Opportunities
- Functional Fortification:There is a significant opportunity to develop UHT milk variants enriched with proteins, vitamins, and probiotics, targeting health-conscious consumers and creating higher-margin, value-added products.
- Specialty Coffee Market:Creating barista-specific UHT milk formulations that offer superior frothing performance and a neutral taste profile can capture a lucrative niche within the global coffee shop industry.
- E-Commerce Channel Expansion:Leveraging online retail and subscription models to sell specialized UHT products, like organic or lactose-free options, directly to consumers, bypassing traditional retail limitations.
Industry Challenges
- Supply Chain Integrity:Ensuring the sterility of the product from the processing plant through to the end-user requires a flawless aseptic packaging and handling chain, where any breach can lead to widespread spoilage and recalls.
- Navigating Divergent Regulations:Managing compliance with disparate international standards, such as the FDA's Pasteurized Milk Ordinance, EU food contact material rules, and China's GB standards, increases complexity for global producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra High Temperature Milk Market |
| Market Size in 2026 | $86.4 Billion |
| Market Size in 2035 | $156.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Cream, Skimmed, Flavored, Organic, Lactose-Free Packaging Type: Tetra Pak, Carton Box, Plastic Bottle, Glass Bottle, Pouch End User: Food Service, Household, Institutional, Dairy Processing, Hospitality Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Wholesale Suppliers, Specialty Stores |
| Companies Covered | Danone Group, Arla Foods, Nestle SA, Grupo Lala, Sodiaal Group, Lactalis Group, Inner Mongolia Yili Group Company Limited, Parmalat S.p.A., Fonterra Co-operative Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra High Temperature Milk Market Strategic Shifts & Innovations
Product development is shifting from UHT milk as a basic commodity to a versatile platform for specialized nutrition and functional benefits. This evolution is driven by parallel advancements in processing methods and a deeper understanding of consumer dietary preferences.
Advanced filtration technologies, particularly microfiltration, are being used prior to thermal treatment. Food service and premium dairy brands are adopting this process to reduce the initial bacterial load in raw milk. This innovation is hybridizing the sensory profile of fresh milk with the extended shelf life of U.S.T. products, creating a new premium category that commands higher prices.
European Union regulations, specifically the framework governing food contact materials, are tightening requirements for substances used in multilayer aseptic packaging. This is forcing packaging manufacturers to invest in R&D for new, compliant barrier polymers and adhesives that do not compromise product safety or shelf life. Dairy producers exporting to or operating within the EU are most affected, needing to ensure their entire packaging supply chain adheres to these strict standards.
Direct-to-consumer subscription services are disrupting traditional distribution for specialized dairy products. Instead of relying solely on grocery store shelf placement, brands focused on organic, grass-fed, or lactose-free UHT milk are building direct relationships with customers via online platforms. This trend is most prominent in metropolitan areas of North America and Western Europe with robust last-mile delivery infrastructure.
Ultra High Temperature Milk Market Segmentation
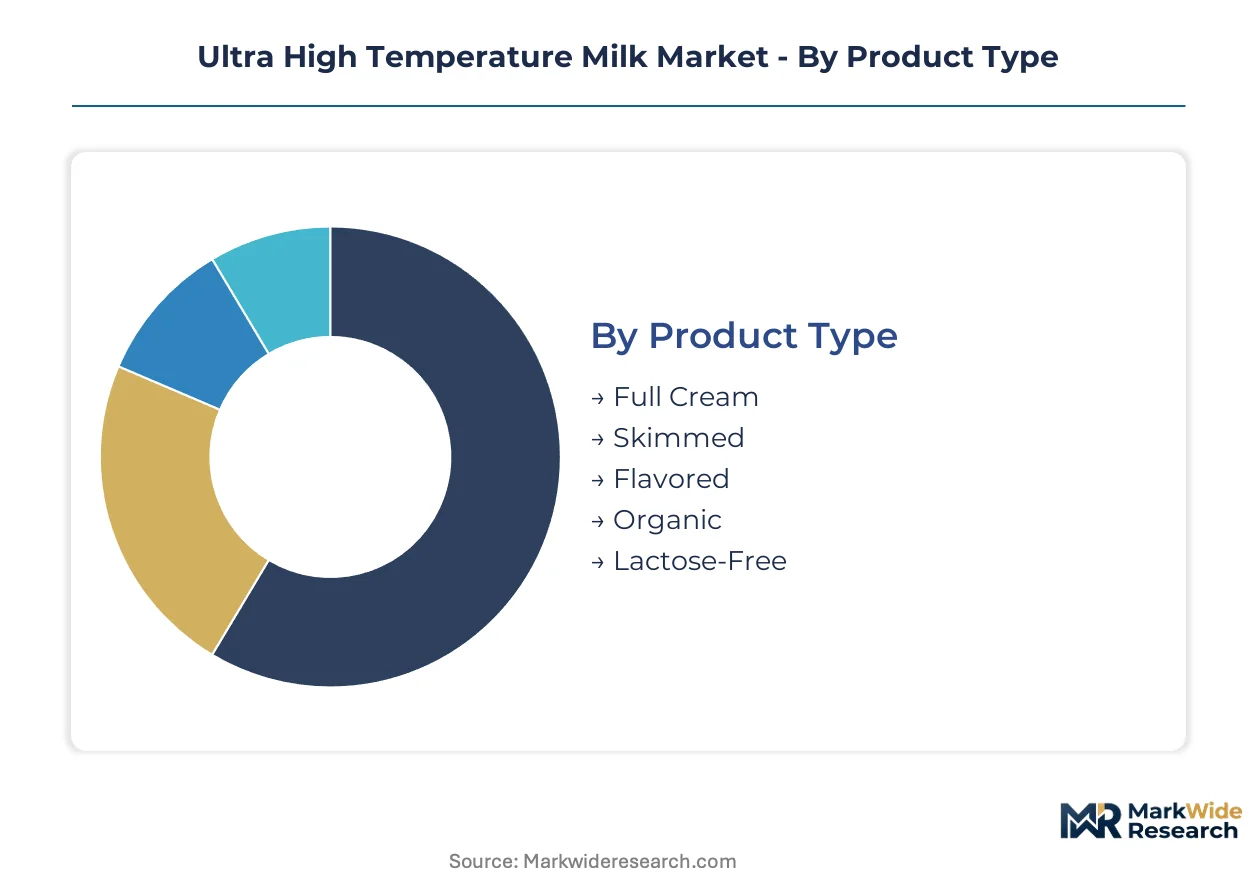
Segmentation within the Ultra High Temperature milk market illuminates the diverse consumer needs and operational demands that shape product development and distribution strategies. Understanding these distinct segments allows producers to tailor offerings, optimize supply chains, and effectively target growth opportunities across various end-user applications and geographic regions.
Product Type:
The after-sales service intensity for UHT milk product types varies significantly based on their specialized formulations and target consumer segments, requiring distinct marketing and consumer education efforts.
- Flavored:UHT milk infused with various flavors like chocolate or vanilla, appealing to younger demographics and impulse purchases. Demand concentrates in developing economies such as India and China, driven by rising disposable incomes and a preference for convenient, sweet beverages.
- Lactose-Free:Milk processed to remove or break down lactose, catering to individuals with lactose intolerance. Demand concentrates in North America and Western Europe, supported by health awareness and specialized dietary needs.
- Full Cream:Standard UHT milk with its natural fat content, widely consumed for general household use.
- Skimmed:UHT milk with reduced fat content, favored by health-conscious consumers for calorie management.
- Organic:UHT milk sourced from organic-certified farms, appealing to consumers seeking natural and sustainable options.
By volume, Full Cream leads. By growth pace, Lactose-Free is ahead.
Packaging Type:
Supply concentration within UHT milk packaging types is dictated by specialized manufacturing capabilities and material science expertise, particularly in aseptic barrier technologies.
- Tetra Pak:Aseptic multilayer cartons designed for extended shelf life without refrigeration, offering superior barrier properties. Demand concentrates in global food service and retail channels, driven by logistical efficiency and product integrity.
- Plastic Bottle:High-density polyethylene (HDPE) or PET bottles, often used for smaller serving sizes or specific market segments. Demand concentrates in regions like the United States, where consumer preference for resealable and transparent packaging remains strong.
- Carton Box:Generic carton packaging, often a cost-effective alternative to proprietary aseptic systems.
- Glass Bottle:Premium packaging option offering perceived freshness and recyclability, though heavier and more fragile.
- Pouch:Flexible packaging providing cost efficiency and reduced material usage, common in parts of Asia.
Tetra Pak maintains the largest market share. Plastic Bottle exhibits the steepest expansion trajectory.
End User:
Application diversity defines the end-user segments for UHT milk, reflecting varied requirements for volume, shelf life, and ingredient functionality across different consumption environments.
- Food Service:Bulk UHT milk supplied to restaurants, cafes, and catering operations for beverages, cooking, and baking. Demand concentrates in Asia-Pacific, particularly China, due to the rapid expansion of coffee chains and quick-service restaurants.
- Household:Packaged UHT milk purchased by individual consumers for home consumption. Demand concentrates in developing regions where cold chain infrastructure is less established, ensuring access to safe dairy.
- Institutional:UHT milk supplied to schools, hospitals, and government facilities for large-scale nutritional programs.
- Dairy Processing:UHT milk used as an ingredient in further processed dairy products like yogurt or desserts, extending their shelf life.
- Hospitality:UHT milk provided in hotels, resorts, and travel accommodations for guest convenience and extended storage.
Food Service commands significant purchasing power. Household purchases are expanding most quickly.
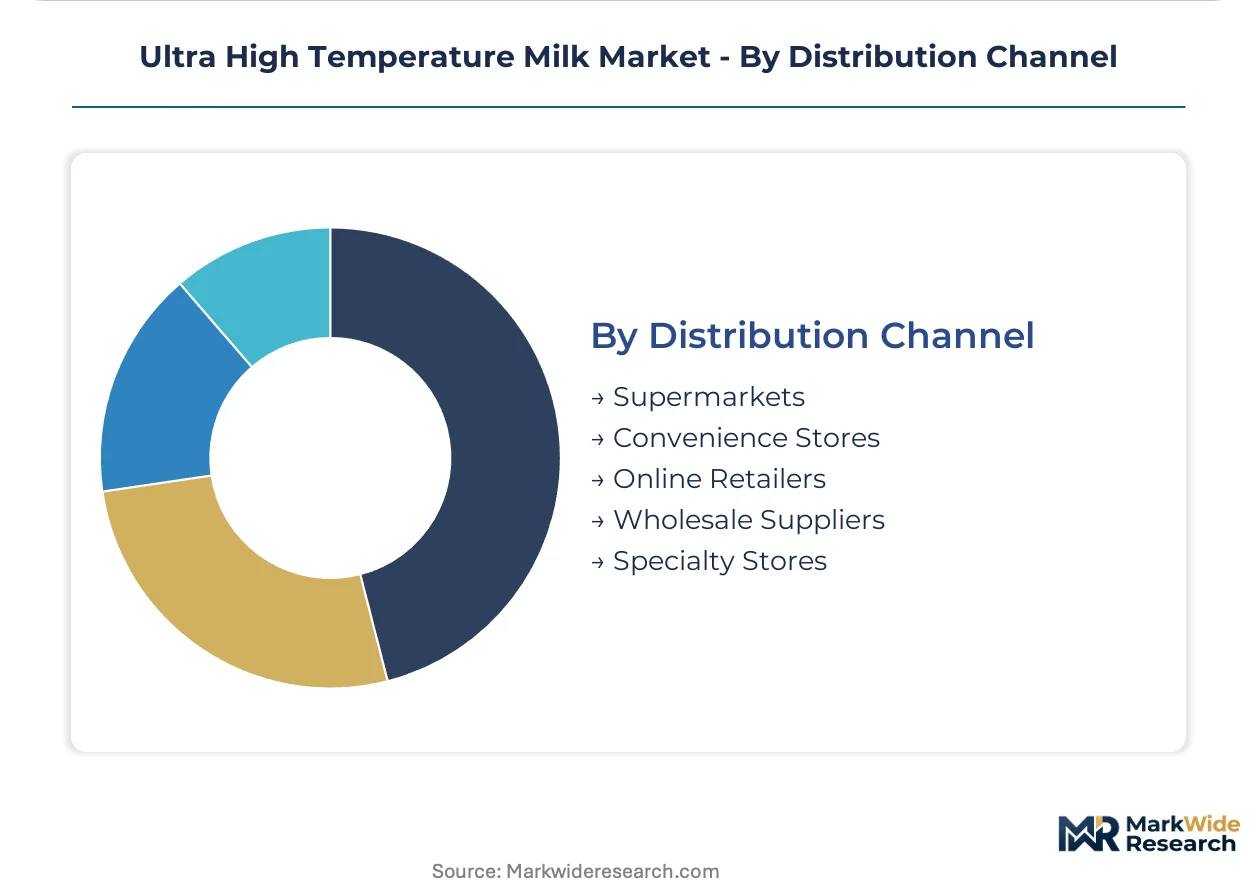
Distribution Channel:
Customer type significantly influences the preferred distribution channels for UHT milk, ranging from mass-market accessibility to specialized direct engagement models.
- Supermarkets:Large retail outlets offering a wide selection of UHT milk products for conventional consumer purchasing. Demand concentrates across mature markets in Western Europe and North America, serving as primary grocery destinations.
- Online Retailers:E-commerce platforms and direct-to-consumer services delivering UHT milk, particularly specialized variants, to customers. Demand concentrates in metropolitan areas globally, driven by convenience and subscription models.
- Convenience Stores:Smaller retail formats providing quick access to UHT milk for immediate consumption or small purchases.
- Wholesale Suppliers:Distributors supplying UHT milk in bulk to food service, institutional clients, and smaller retailers.
- Specialty Stores:Niche retail outlets focusing on organic, health, or gourmet products, including premium UHT milk.
Supermarkets represent the largest volume channel. Online Retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global network of shipping lanes and intermodal freight corridors underwrites the broad geographic reach of UHT milk. This infrastructure enables producers to distribute shelf-stable products across diverse markets. Efficient logistics are critical for accessing regions with varying cold chain capabilities.
China
Rural market access and rising disposable incomes drive significant demand for UHT milk in China. The State Administration for Market Regulation (SAMR) enforces GB standards for imported dairy products, ensuring quality. The Yangtze River Delta region, including Shanghai, sees substantial investment in modern processing facilities.
India
Increasing urbanization and a preference for convenient, sweet beverages fuel demand for flavored UHT milk in India. The Food Safety and Standards Authority of India (FSSAI) regulates dairy product quality and labeling. Major metropolitan areas like Mumbai and Delhi serve as key hubs for UHT milk distribution and consumption.
United States
Demand for lactose-free UHT variants and a consumer preference for plastic bottle packaging influence the U.S. market. The FDA's Pasteurized Milk Ordinance (PMO) governs UHT processing standards. California's dairy industry adapts to produce diverse UHT products for both domestic and export markets.
Germany
Sustainable packaging preferences and a strong market for organic UHT milk characterize the German landscape. European Union regulations on food contact materials strictly control packaging integrity. Bavaria, a major dairy-producing state, focuses on high-quality UHT milk production and innovation.
Brazil
Household consumption and a growing food service sector drive UHT milk demand across Brazil. ANVISA, the national health surveillance agency, oversees food safety and labeling for dairy products. The Southeast region, including São Paulo, represents a significant hub for UHT milk consumption and distribution.
Ultra High Temperature Milk Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing critical packaging and ingredients. The UHT milk market features a tiered structure, with large multinational dairy corporations alongside specialized regional players. Strategic archetypes include mass-market producers, premium organic brands, and functional product innovators. Dominant competitive moves involve portfolio diversification and geographic expansion.
Global dairy giants such as Lactalis Group, Danone Group, and Nestle SA exemplify the large-scale, diversified approach to the UHT milk market. These companies occupy a position at the forefront of product innovation and market penetration. Their extensive portfolios cater to various consumer segments worldwide, leveraging established brand strength.
| Leading Market Players |
|---|
| Danone Group |
| Arla Foods |
| Nestle SA |
| Grupo Lala |
| Sodiaal Group |
| Lactalis Group |
| Inner Mongolia Yili Group Company Limited |
| Parmalat S.p.A. |
| Fonterra Co-operative Group Limited |
| Others |
Cost & Logistics Intelligence
Bavaria's dairy production capacity and processing innovation influence pricing power for premium UHT milk across Europe. This regional concentration affects the cost structures for specialized products, impacting their market accessibility.
Pricing Analysis
Volume-discounted pricing structures dominate for bulk UHT milk, particularly in food service channels. Price differentiation stems from brand premium for organic or lactose-free variants and geographic delivery costs to remote regions. Pricing pressure stems from the energy-intensive UHT processing, exposing producers to fluctuations in electricity and natural gas prices. Household consumers of standard UHT milk exhibit higher price sensitivity compared to buyers of specialty UHT products.
Supply Chain Analysis
Major dairy companies like Lactalis Group and Nestle SA concentrate UHT milk manufacturing capacity in strategic locations such as China, India, and Germany. The supply chain sources raw milk from regional farms and relies on specialized aseptic packaging from firms like Tetra Pak. Commodity price volatility for energy inputs presents a structural risk for UHT milk production. Distribution runs through a hybrid model, combining traditional retail with expanding online direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UHT milk market faces a scarcity in advanced aseptic packaging and specialized product formulation capabilities. This gap limits the development of new, value-added offerings and efficient market penetration.
For Market Incumbents: Build brand loyalty and supply chain efficiency to counter the threat from plant-based alternatives. Diversify product portfolios with functional fortifications and organic certifications to capture higher-margin segments. Invest in sustainable packaging R&D to align with consumer preferences and evolving EU regulations.
For New Entrants and Emerging Players: Rural market access in developing economies like India and China represents significant underpenetration. Target specialized niches such as barista-specific UHT milk or fortified variants for health-conscious consumers. Leverage e-commerce channels and subscription models for direct access to urban metropolitan consumers.
For Investors and Strategic Acquirers: Long-term, this sits as a stable growth commodity with value-add potential, driven by evolving consumer dietary needs and logistical efficiencies. Prioritize acquisition targets with proprietary aseptic packaging technologies or strong portfolios in functional and organic UHT milk. Monitor advanced filtration technology adoption rates as an inflection indicator for premiumization trends.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification | Expands market reach by catering to diverse consumer preferences for flavored and lactose-free options. |
| Aseptic Packaging R&D | Enhances product shelf life and reduces environmental impact, appealing to conscious consumers. |
| E-commerce Channel Expansion | Bypasses traditional retail limitations, enabling direct sales of specialized UHT products. |
| Functional Ingredient Fortification | Creates higher-margin products by targeting health-conscious consumers with added nutritional benefits. |
| Regional Market Entry | Captures new demand in developing economies with inconsistent cold chain infrastructure. |
Research Approach
A spread of perspectives from dairy producers, packaging manufacturers, food service operators, and regulatory bodies converged on the working assumptions for the UHT milk market. Primary interviews with industry stakeholders were combined with secondary validation from government food safety regulations and financial filings of major players. This approach utilized both bottom-up and top-down triangulation methods.
The analytical framework balanced demand-side drivers, such as evolving consumer preferences and food service expansion, against supply-side constraints like processing capacity and raw milk availability. Segmentation dimensions modeled included product type, packaging type, end user, distribution channel, and regional economic development. Compound annual growth rates were derived by extrapolating historical trends and integrating future market dynamics. Raw milk prices and aseptic packaging material costs served as key industry-specific forecast inputs.
Practitioners should monitor commodity price volatility, evolving food safety regulations, and rapid shifts in consumer dietary preferences for early signals of market revision. Forecasts reflect assumptions documented across the analysis window. Quarterly review of packaging innovations and plant-based milk adoption trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Spoonable Yogurt Market
Dairy Products
Lactose Market
Dairy Products
Condensed Whey Market
Dairy Products
Goat Milk Products Market
Dairy Products
Asia-Pacific Dairy Protein Market
Dairy Products
Flavored Yogurt Market
Dairy Products
North America Milk Powder Market
Dairy Products
Kefir Market
Dairy Products
Evaporated Filled Milk Market
Dairy Products
South America Flavored Milk Market
Dairy Products
Dairy Based Dressings Market
Dairy Products
UHT Whipping Cream Market
Dairy Products
Soluble Milk Protein Market
Dairy Products
Low Cholesterol Cheese Market
Dairy Products
Ready-To-Use Cheese Market
Dairy Products
Spicy Dairy Products Market