
 Pasteurized Eggs Market | 2026-2036
Pasteurized Eggs Market Size, Share, and Industry Trends Forecast 2026-2036
Pasteurized Eggs Market Analysis
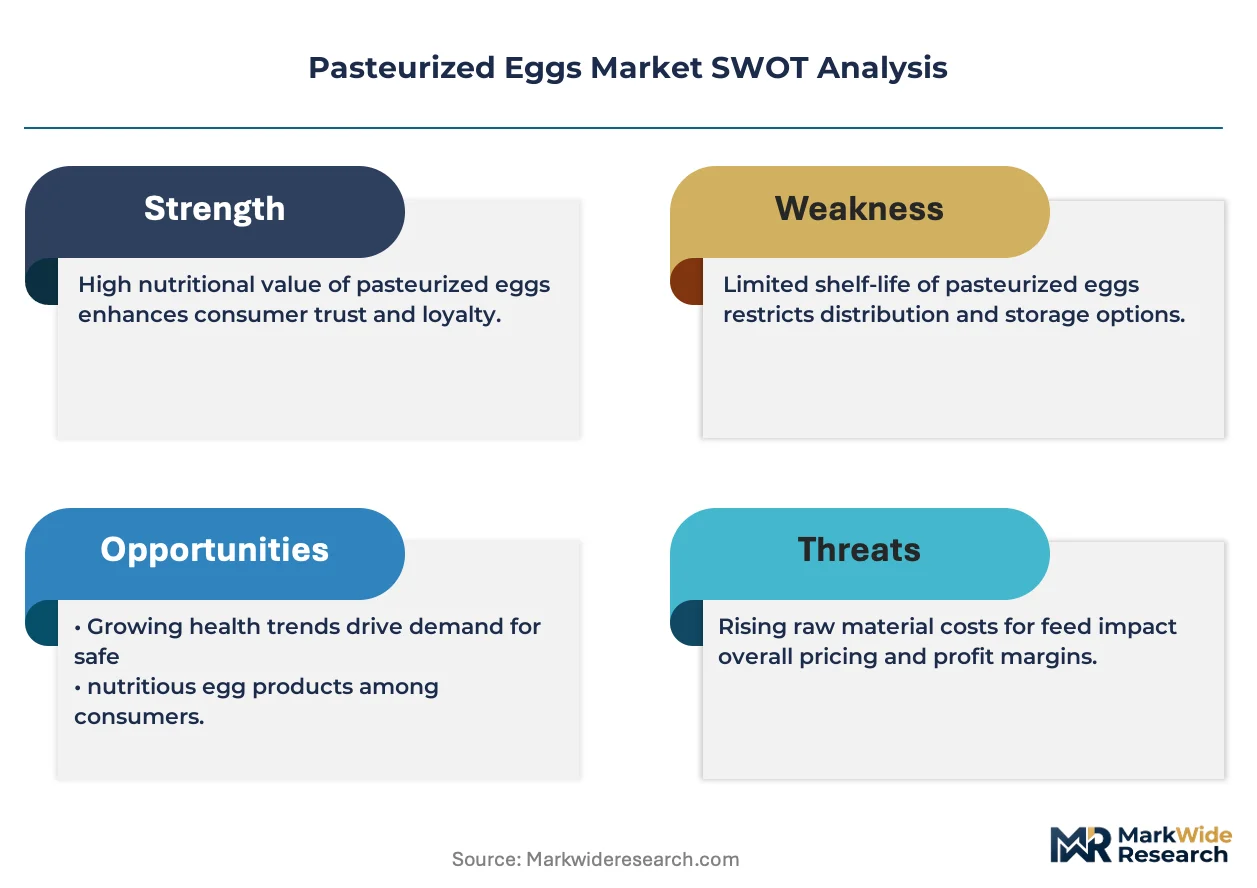
The FDA Egg Safety Rule is restructuring capital requirements for new pasteurization facilities, forcing entrants to invest in validated thermal processing systems before market access. National Pasteurized Eggs Inc leverages proprietary warm-water pasteurization technology to dominate the premium shell egg segment. Cal-Maine Foods, Inc. anchors supply security through backward integration into layer hen operations across multiple states. Sanovo Egg Group competes on liquid egg fractionation capacity, supplying industrial bakeries with standardized albumen and yolk blends.
Pasteurized eggs are shell or liquid eggs subjected to controlled heat treatment that eliminates Salmonella enteritidis without coagulating the proteins, maintaining functional whipping and binding properties essential for mayonnaise, hollandaise, and meringue production. Liquid egg leads product type revenue due to food processor demand for portion-controlled, pathogen-free inputs in high-volume sauce manufacturing. Shell eggs retain premium positioning in retail cartons and clamshells where consumer perception of freshness drives price acceptance. Dried egg occupies a specialized niche in bakery applications requiring extended shelf stability and reduced cold-chain dependency.
USDA grading standards and FSIS labeling requirements shape product differentiation and interstate commerce compliance for pasteurized egg sellers. The FDA Egg Safety Rule and state-level agricultural department inspections create a dual-layer compliance environment that favors operators with established quality management systems. Stakeholders must monitor evolving state adoption of cage-free mandates, as these housing transitions ripple through layer flock management and pasteurized egg supply planning.
Market Dynamics
The FDA Egg Safety Rule is compressing facility approval timelines and forcing pasteurization operators to pre-commit capital before revenue validation, restructuring entry economics for thermal processing infrastructure.
Growth Catalysts
- Foodservice pathogen liability:Institutional cafeterias and hospital foodservice operations mandate pasteurized inputs to eliminate Salmonella exposure risk in raw-egg preparations.
- Warm-water pasteurization:Continuous-flow thermal systems reduce protein denaturation while achieving 5-log pathogen reduction, preserving functional properties for mayonnaise and meringue production.
- Ready-to-eat meal expansion:Refrigerated sauce manufacturers source liquid pasteurized eggs for portion-controlled, cold-chain-stable inputs in hollandaise and aioli formulations.
Market Restraints
- Layer feed cost volatility:Corn and soybean meal price swings transmit directly to egg production economics, compressing pasteurization facility margins during commodity spikes.
- Mississippi River corridor concentration:Bulk liquid egg processing clusters along this waterway create geographic supply vulnerability to flooding and barge transport disruptions.
- Protein functionality ceiling:Thermal treatment irreversibly degrades albumen whipping capacity above threshold temperatures, limiting substitution in angel food cake and soufflé applications.
Strategic Opportunities
- Cage-free mandate acceleration:California's Proposition 12 and similar state laws force housing transitions that pasteurization operators can leverage for premium positioning in retail shell egg segments.
- Extended shelf-life liquid blends:High-pressure processing convergence with thermal pasteurization enables 90-day refrigerated stability for food processor bulk procurement.
- Direct-to-bakery distribution:Bypassing traditional dairy distributors, pasteurized egg suppliers establish tanker-truck relationships with industrial bread and pastry manufacturers.
Industry Challenges
- FSIS dual-jurisdiction compliance:Facilities must simultaneously satisfy FDA Egg Safety Rule microbial standards and USDA grading protocols, extending certification timelines.
- Skilled thermal process engineering scarcity:Validating kill-step parameters requires expertise in computational fluid dynamics and Salmonella thermal inactivation kinetics that outpaces training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pasteurized Eggs Market |
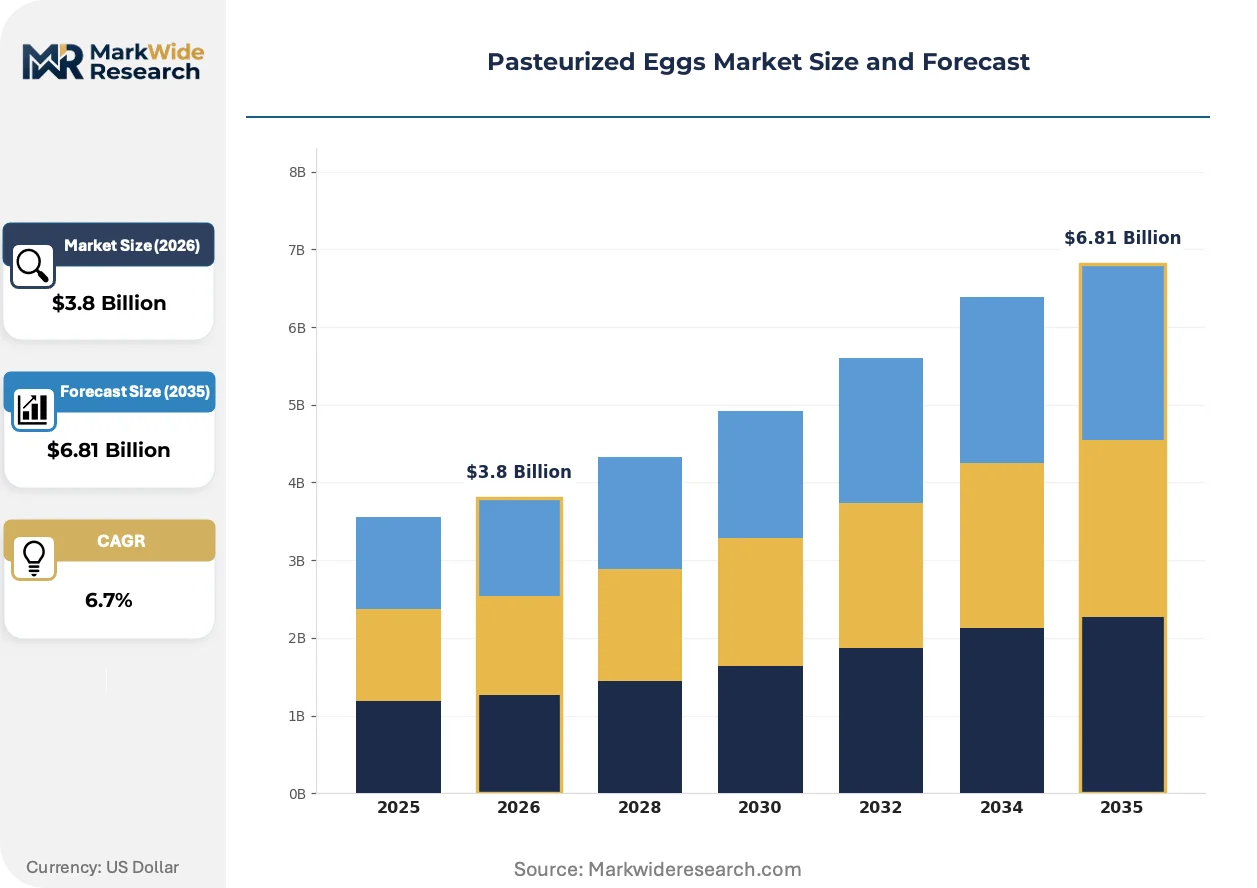
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shell Eggs, Liquid Egg, Dried Egg, Frozen Egg End User: Food Service, Retail, Bakeries, Food Processors Packaging Type: Cartons, Tetra Packs, Bulk Packaging, Clamshells Application: Baking, Sauces, Dressings, Beverages |
| Companies Covered | National Pasteurized Eggs Inc, Glaum Egg Ranch Company, Hickman's Family Farms Company, Stiebrs Farms Company, Wilcox Farms Company, Willamette Egg Company, Sanovo Egg Group, Cal-Maine Foods, Inc., Rose Acre Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pasteurized Eggs Market Emerging Trajectories
Processing technology convergence and regulatory stringency are compressing the viable technology set while expanding the addressable application base for pathogen-free egg products.
Radio-frequency pasteurization is electrifying shell egg treatment by delivering volumetric heating that reduces thermal exposure time by half compared to conventional warm-water immersion. Premium retail packagers in the Northeast are piloting this technology to preserve albumen clarity in cage-free cartons. The structural consequence is compressing capital recovery periods for high-throughput facilities while raising the performance floor for market participation.
The FDA Egg Safety Rule's 2010 preventive controls framework continues tightening through draft guidance on environmental monitoring and corrective action documentation. Layer operations must now implement Salmonella enteritidis vaccination protocols and biosecurity audits as preconditions for pasteurized egg facility supply contracts. Small-to-mid-sized producers in the Southeast are consolidating to spread compliance infrastructure costs across larger volume bases.
Food processor procurement patterns are consolidating supplier relationships around full-line liquid egg fractionation capabilities rather than single-product sourcing. Industrial bakeries now specify standardized albumen solids content and yolk color indices in master service agreements, displacing spot-market purchasing. This specification intensity concentrates most visibly in the upper Midwest, where large-scale bread and frozen dough manufacturers operate captive R&D kitchens for ingredient validation.
Pasteurized Eggs Market Segmentation
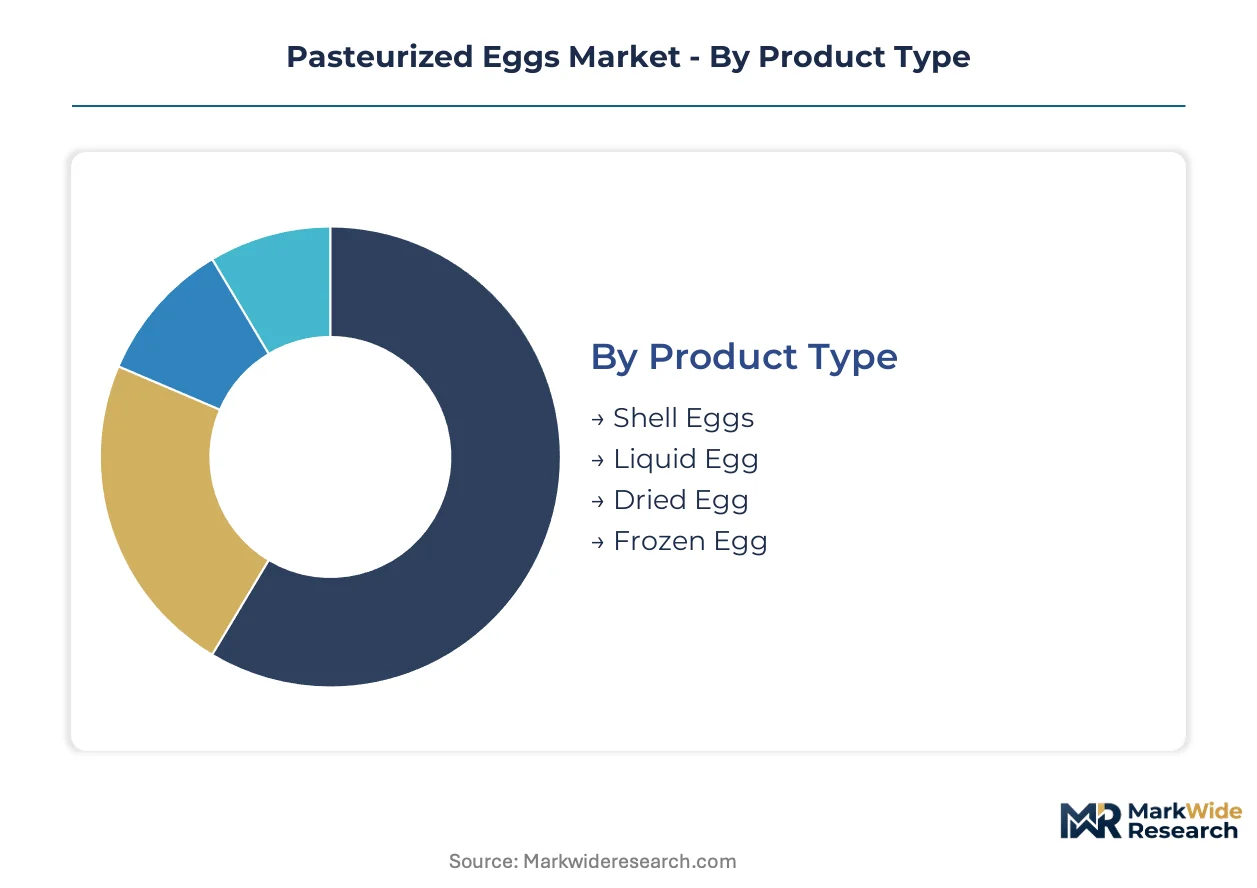
Pasteurized egg suppliers configure production lines around four distinct segment hierarchies that determine equipment investment, margin structure, and customer relationship intensity. Each segmentation axis reveals divergent growth trajectories and competitive intensity patterns across the value chain.
Product Type:
Volume leadership concentrates in liquid formats where food processors standardize procurement, while shell eggs command retail premium positioning through freshness signaling and cage-free certifications.
- Liquid Egg:Pumpable albumen-yolk blends deliver precise solids content control for industrial mayonnaise and hollandaise manufacturers. Demand clusters in the upper Midwest where refrigerated tanker infrastructure supports direct-to-bakery distribution. High-pressure processing extensions now push refrigerated stability toward ninety-day windows.
- Shell Eggs:In-shell warm-water pasteurization preserves consumer perception of farm-fresh integrity while eliminating Salmonella risk for raw-egg preparations. Premium retail positioning in the Northeast and California leverages Proposition 12 cage-free mandates as differentiation anchors.
- Dried Egg:Spray-dried powders serve bakery applications requiring ambient storage and extended shelf stability without cold-chain dependency.
- Frozen Egg:Blast-frozen blocks and pails target institutional foodservice operations with intermittent demand patterns and freezer capacity.
Mature deployment sits with liquid egg fractionation systems. Newer deployment is concentrated in radio-frequency shell egg pasteurization pilot facilities.
End User:
Procurement specification intensity varies sharply across customer types, with industrial buyers demanding certificate-of-analysis documentation while retail channels prioritize packaging differentiation.
- Food Processors:Master service agreements now mandate standardized albumen solids percentages and yolk color indices validated through captive R&D kitchens. Contract structures emphasize year-round supply security over spot-market flexibility.
- Food Service:Hospital cafeterias and institutional kitchens mandate pasteurized inputs to eliminate pathogen liability in raw-egg menu items. HACCP compliance documentation drives supplier consolidation toward multi-product portfolios.
- Bakeries:Industrial bread and frozen dough manufacturers source liquid blends for portion-controlled incorporation into sponge cake and pastry formulations.
- Retail:Supermarket chains specify cage-free and organic certifications alongside pasteurization status, compressing margin for undifferentiated shell egg offerings.
Established volume relationships dominate food processor accounts. Expanding most quickly are food service mandates driven by institutional liability frameworks.
Packaging Type:
Packaging selection directly determines distribution economics and shelf-life extension potential across temperature-controlled supply chains.
- Bulk Packaging:Stainless steel totes and bag-in-box systems minimize unit costs for high-volume sauce manufacturers with dedicated receiving infrastructure.
- Cartons:Standard twelve-count fiber packaging serves conventional retail channels with established cold-case turnover velocities.
- Clamshells:Transparent hinged containers showcase albumen clarity and shell integrity for premium cage-free positioning in specialty grocery.
- Tetra Packs:Aseptic brick packaging extends ambient shelf stability for liquid egg exports and emergency foodservice stockpiling.
Conventional formats anchor retail volume. Emerging deployment concentrates in bulk liquid systems for direct processor tanker delivery.
Application:
Functional protein requirements dictate thermal treatment intensity, with emulsification applications tolerating higher pasteurization temperatures than foam-dependent formulations.
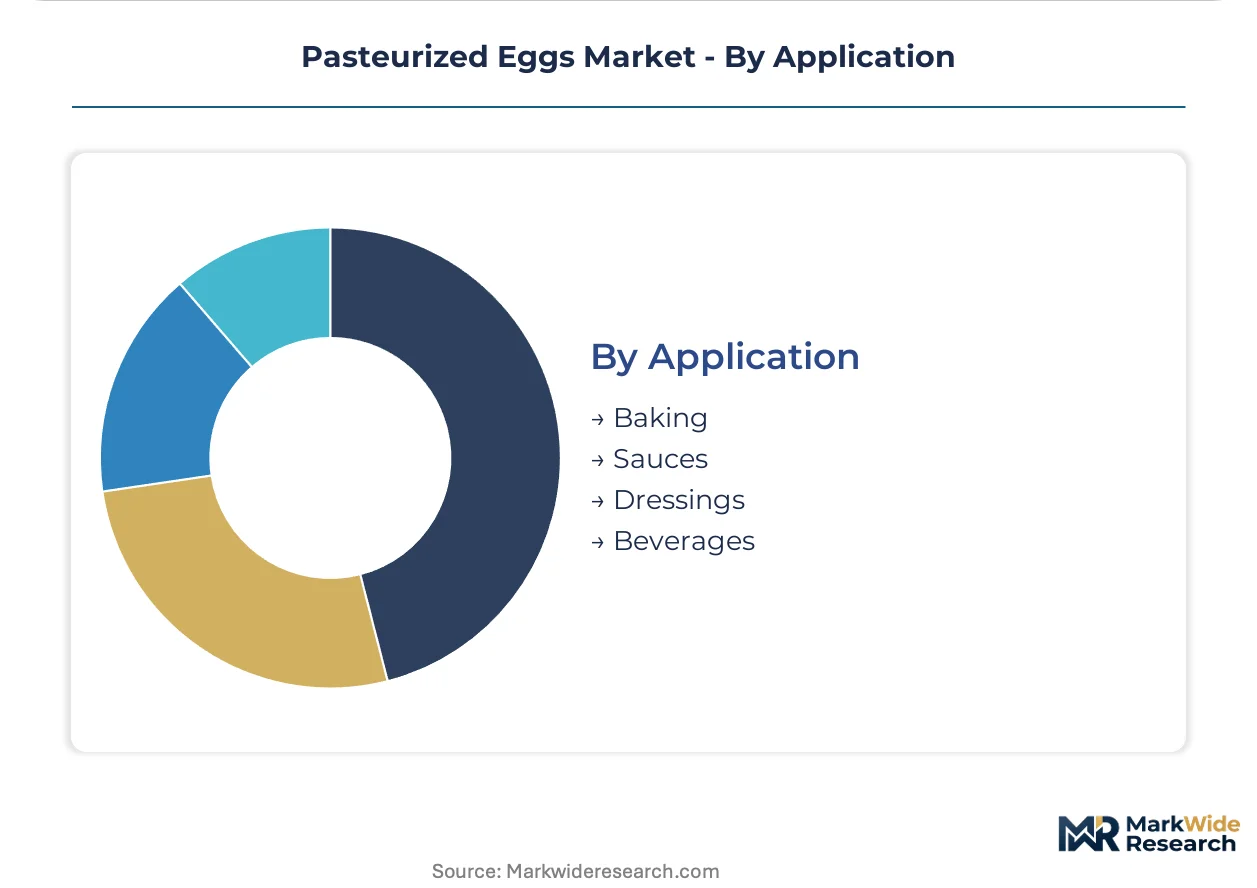
- Sauces:Mayonnaise and hollandaise production demands pathogen elimination without protein coagulation that would break oil-in-water emulsions. Continuous-flow thermal systems achieve five-log reduction while preserving lecithin functionality.
- Baking:Angel food cake and soufflé applications face substitution limits as thermal treatment degrades albumen whipping capacity above threshold temperatures.
- Dressings:Refrigerated aioli and Caesar formulations source liquid pasteurized eggs for portion-controlled cold-chain stability.
- Beverages:Eggnog and protein shake applications represent niche demand for high-solids yolk blends with extended refrigerated dating.
Steepest expansion trajectory appears in sauce manufacturing where processor consolidation amplifies specification intensity. Mature demand patterns persist in seasonal beverage applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest Enterprise Zones in the United States concentrate pasteurization facility investment through tax abatements tied to food safety infrastructure. Facility location decisions track layer hen density and refrigerated distribution corridor access.
United States
Institutional foodservice contracts drive volume commitments from hospital cafeterias and university dining systems. The FDA Egg Safety Rule mandates validated thermal processing systems for interstate commerce. Iowa and Ohio processing clusters supply liquid egg fractions to upper Midwest industrial bakeries through direct tanker distribution.
Germany
Industrial mayonnaise manufacturers specify standardized albumen solids content in procurement agreements. EFSA guidelines on Salmonella control in egg products shape facility design standards. Bavarian processing plants serve Central European sauce manufacturers with extended shelf-life liquid blends.
Japan
Convenience store chains demand pasteurized eggs for raw-egg menu items including tamago kake gohan. METI food safety standards require documented kill-step validation for thermal processing systems. Kanto region facilities supply Tokyo metropolitan area retail and foodservice channels.
United Kingdom
Supermarket private-label programs specify cage-free and organic certifications alongside pasteurization status. FSA egg safety guidance requires environmental monitoring protocols for layer operations. Midlands processing clusters distribute shell and liquid formats through national retail distribution networks.
Netherlands
European export-oriented liquid egg fractionation capacity concentrates near Rotterdam port infrastructure. EU hygiene regulations for egg products mandate HACCP-based process controls. Randstad region facilities supply industrial bakeries across Benelux and Northern France with standardized yolk blends.
Pasteurized Eggs Market Vendor Landscape
United States producers anchor one tier; European specialists hold another through differentiated fractionation capabilities. The vendor base separates into integrated layer-pasteurization operators, standalone processing facilities, and liquid egg fractionation specialists. Three archetypes dominate: backward-integrated egg producers with captive pasteurization capacity, independent toll processors serving regional brands, and multi-national fractionators supplying industrial food processors. Capacity expansion and cage-free housing transitions constitute the dominant competitive moves reshaping supply positioning.
Within the integrated producer tier, National Pasteurized Eggs Inc and Cal-Maine Foods, Inc represent archetypes of scale-driven market presence. Sanovo Egg Group occupies a position among fractionation specialists serving industrial bakery accounts. These three entities exemplify the strategic divergence between shell egg premium positioning and liquid egg commodity supply.
| Leading Market Players |
|---|
| National Pasteurized Eggs Inc |
| Glaum Egg Ranch Company |
| Hickman's Family Farms Company |
| Stiebrs Farms Company |
| Wilcox Farms Company |
| Willamette Egg Company |
| Sanovo Egg Group |
| Cal-Maine Foods, Inc. |
| Rose Acre Farms |
| Others |
Supply Flow & Price Mechanics
Family-owned layer operations across the Midwest and Southeast anchor supply discipline through conservative expansion financing and long-term feed procurement contracts, insulating pasteurized egg pricing from the volatility seen in leveraged corporate structures. Their capital restraint limits spot-market dumping during commodity downturns, preserving margin architecture for thermal processing investments.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to liquid egg tanker deliveries within seventy-two hours of order placement, while spot inventory discounts of eight to twelve percent clear excess shell egg volume ahead of date-code expiration. Contract-based long-term offtake dominates institutional procurement, with price differentiation resting on cage-free certification tier and yolk color index specifications. Cost compression in conventional shell eggs is intensifying because California Proposition 12 compliance costs transmit unevenly across state supply bases. Food processors exhibit lowest price sensitivity due to liability-driven specification rigidity, while undifferentiated retail shell egg buyers demonstrate highest elasticity.
Supply Chain Analysis
Workforce availability constraints in Iowa and Ohio processing corridors limit expansion velocity for high-throughput pasteurization facilities, compressing effective capacity growth below equipment installation rates. Supply concentrates in the United States, Germany, and the Netherlands, with raw material dependencies on corn and soybean meal layer feed, stainless steel processing equipment, and refrigerated transport chassis. Single-source vulnerability sits with Mississippi River barge corridors for bulk liquid egg movement north to industrial bakeries. Distribution runs through direct tanker relationships with food processors alongside traditional dairy distributor networks serving institutional foodservice accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive layer hen supply determines pasteurization facility utilization security and contract renewal rates. Players pursue upstream control over breeding stock and pullet rearing to lock in cage-free transition timelines.
For Market Incumbents: To counter radio-frequency pasteurization technology disruption from Northeast pilot facilities, backward integration into pullet rearing operations secures cage-free supply commitments ahead of state mandate deadlines. Incumbents should anchor multi-year liquid egg fractionation contracts with upper Midwest industrial bakeries, leveraging existing tanker infrastructure to raise switching costs for processor procurement teams. For New Entrants and Emerging Players: Radio-frequency shell egg pasteurization equipment offers a technology-first wedge into premium retail channels where albumen clarity preservation commands shelf price premiums. White-space targets include direct-to-bakery distribution bypassing dairy distributor markups in secondary Midwest markets, and high-pressure processing convergence for ninety-day refrigerated stability blends. A go-to-market angle emphasizing kill-step documentation for hospital foodservice HACCP compliance accelerates initial account penetration. For Investors and Strategic Acquirers: FDA draft guidance release on environmental monitoring corrective action documentation is the leading indicator that compliance infrastructure scale requirements will trigger consolidation among Southeast mid-sized producers. Long-term viability over the next decade favors integrated layer-pasteurization operators with captive cage-free supply and validated thermal processing systems already deployed. Acquisition targets should display established quality management systems spanning both FDA Egg Safety Rule and USDA grading protocols. Watch for state-level cage-free mandate adoption velocity as the signal for supply constraint timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pullet Rearing | Secures cage-free layer supply ahead of California Proposition 12 ripple effects across state lines. |
| Radio-Frequency Pasteurization Deployment | Halves thermal exposure time to preserve albumen functionality for premium Northeast retail positioning. |
| Direct Tanker Distribution Networks | Bypasses dairy distributor markups to capture margin in industrial bakery liquid egg procurement. |
| High-Pressure Processing Convergence | Extends refrigerated shelf stability toward ninety days for food processor bulk procurement security. |
| Multi-Product Portfolio Expansion | Consolidates hospital foodservice accounts around HACCP documentation and liability elimination. |
Methodological Framework
USDA layer flock inventory reports, FDA Egg Safety Rule guidance documents, and SEC 10-K filings from publicly traded egg producers formed the secondary backbone, cross-referenced with primary interviews involving pasteurization facility operations managers, institutional foodservice procurement directors, and industrial bakery ingredient buyers. Bottom-up and top-down triangulation validated volume estimates against layer hen population data and processing capacity utilization surveys.
Bottom-up modeling tracked segment-level demand from food processors, foodservice operators, bakeries, and retail channels across the projection horizon, while top-down analysis anchored total market size against USDA egg product disappearance data. Segmentation dimensions included product type, end user, packaging format, and application functional requirements. CAGRs were derived from trend extrapolation of cage-free housing transition timelines and pasteurization facility investment patterns. Forecast inputs incorporated corn and soybean meal price volatility assumptions alongside state-level cage-free mandate adoption schedules.
Several conditions sit outside the modeled scope, including extreme weather disruptions to Mississippi River transport corridors and rapid shifts in FDA environmental monitoring enforcement intensity. Forecasts reflect assumptions about layer flock productivity rates and thermal processing equipment commissioning timelines. Material deviation in feed commodity price spikes or state mandate acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Europe Food Service Market
Food Service
India Quick Service Restaurant Market
Food Service
Virtual Kitchen Market
Food Service
Restaurants and Mobile Food Services Market
Food Service
Plates Market
Food Service
Belgium HRI Market
Food Service
Pizza Oven Market
Food Service
Inflight Catering Market
Food Service
Quick-Service Restaurants Market
Food Service
Chained Consumer Foodservice Market
Food Service
Commercial Air Fryer Oven Market
Food Service
Meal Kit Delivery Services Market
Food Service
Restaurant Glassware Market
Food Service
Shaker Bottles Market
Food Service
Online Catering Market
Food Service
Commercial Ice Dispenser Market