
 Cheese Crumbles Market | 2026-2036
Cheese Crumbles Market Size, Share, and Industry Trends Forecast 2026-2036
Cheese Crumbles Market Analytics
FSMA dairy safety rules is shifting the cost-of-entry calculus for new processors. Kraft Heinz leverages its refrigerated distribution network to sustain national retail placement. Saputo Cheese anchors North American supply through its multi-plant mozzarella and specialty cheese infrastructure. Montchevre specializes in goat cheese crumbles, occupying the fast-expanding organic and artisan grade tiers.
Cheese crumbles denote pre-broken cheese pieces, typically 2-8 millimeters in size, produced via mechanical dicing or crumbling of aged, semi-firm, or firm cheese blocks for food manufacturing and foodservice applications. The grade dimension stratifies sharply: organic and artisan grades command premium shelf positioning, while conventional crumbles dominate volume in foodservice channels. Blue cheese and feta crumbles lead the product type split, with goat cheese crumbles recording the fastest trajectory in specialty retail.
The FDA enforces pathogen controls through FSMA preventive rules, while USDA dairy grading standards shape product classification and interstate commerce eligibility. The EU's REACH and hygiene package regulations govern crumbles exported to European food manufacturers, adding compliance layers for international suppliers. Stakeholders must monitor how dual domestic and export regulatory burdens reshape margin structures across conventional versus certified organic production lines.
Market Dynamics
Quick-service restaurant chains now mandate pre-portioned cheese formats to compress assembly times, while FSMA dairy safety rules elevate capital requirements for new processing entrants. This dual pressure from downstream operational demands and upstream regulatory compliance is restructuring competitive viability across conventional and specialty production tiers.
Growth Catalysts
- FSMA Preventive Controls:The FDA's pathogen control mandates are consolidating processing capacity toward larger facilities with validated HACCP systems, squeezing out sub-scale operators and concentrating volume among compliant manufacturers.
- Foodservice Automation:Quick-service chains deploy crumbled formats at drive-thru and digital-order assembly stations to eliminate knife-work and reduce cross-contamination risk during peak throughput windows.
- California Central Valley Cluster:Proximity to fluid milk supply, whey processing infrastructure, and cold-chain distribution nodes creates cost advantages for crumbles production serving West Coast foodservice density.
Market Restraints
- Input Cost Volatility:Class III milk price fluctuations and aging warehouse requirements for block cheese create margin compression that small processors cannot hedge through forward contracting.
- Supply Concentration Risk:Multi-plant dairy processors control refrigerated distribution networks, limiting retail placement access for regional crumbles specialists without captive cold-chain assets.
- Technical Shelf-Life Limitation:Moisture migration in crumbled formats accelerates mold proliferation versus intact blocks, constraining export viability to extended-transit markets without modified atmosphere packaging investment.
Strategic Opportunities
- Organic Certification Tailwind:USDA organic dairy standards create price premiums in specialty retail channels, with goat cheese crumbles capturing fastest velocity in natural grocery placement.
- Direct-to-Foodservice Platforms:Independent distributors and restaurant supply cooperatives are disintermediating traditional broadline distribution for artisan-grade crumbles in metropolitan culinary markets.
- EU Export Alignment:REACH and hygiene package compliance investments open formulated crumbles access to European food manufacturing customers seeking pre-processed dairy inputs.
Industry Challenges
- Sanitation Engineering Talent Scarcity:FSMA-compliant facility design and environmental monitoring protocol implementation require specialized dairy safety engineers in short supply across rural processing geographies.
- Certification Timeline Compression:Organic and SQF certification audits create 12-18 month market entry delays for new product lines, advantaging incumbent certified processors.
- Legacy Equipment Integration:Mechanical dicing lines require retrofitting for allergen segregation protocols, forcing capital allocation between new automation and compliance-modified existing assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheese Crumbles Market |
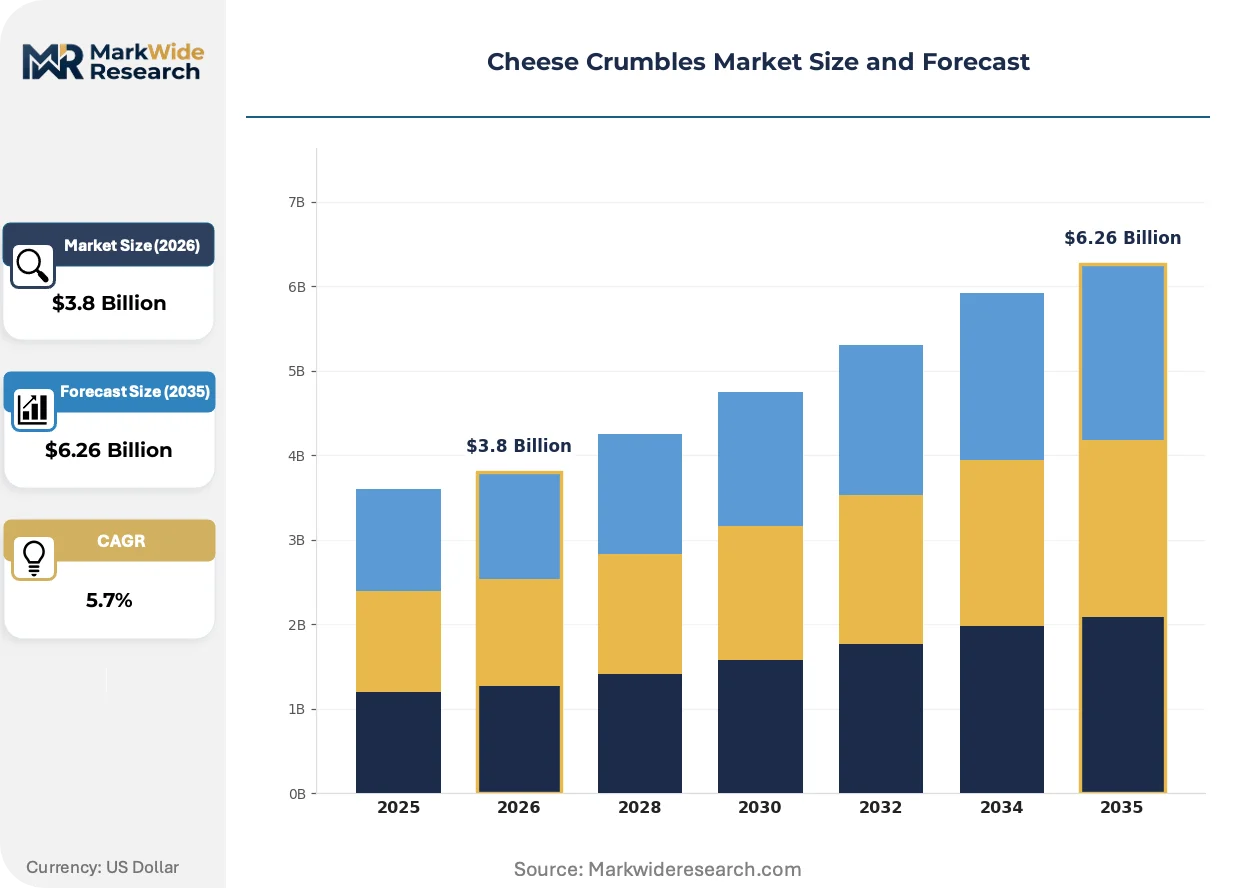
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blue Cheese, Feta, Goat Cheese, Cheddar Packaging Type: Plastic Containers, Vacuum Packs, Pouches, Jars End Use: Restaurants, Food Service, Retail, Catering Grade: Organic, Aged, Artisan, Conventional |
| Companies Covered | Arla Foods, Kraft Heinz, Saputo Cheese, Boar's Head, DeJong Cheese, Litehouse, Montchevre, Salemville, President Cheese, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheese Crumbles Market Evolving Landscape
Automation and regulatory precision are converging to reshape how crumbles are produced, certified, and procured. Equipment vendors and dairy processors are co-developing systems that embed compliance documentation directly into manufacturing execution.
Vision-guided robotic crumbling systems are automating size-grading and foreign-object detection previously performed by manual inspection. Quick-service restaurant suppliers deploy these systems to achieve 2-8 millimeter consistency specifications at throughput rates exceeding 10,000 pounds per hour. This automation is compressing labor cost structures while generating real-time lot traceability data required by FSMA record-keeping mandates.
REACH and EU hygiene package regulations are forcing reformulation of anti-caking agents and surface treatments for crumbles exported to European food manufacturers. Suppliers must substitute silicon dioxide alternatives and document absence of nanomaterials in accordance with ECHA substance registration requirements. Organic and artisan-grade processors face the steepest compliance burden, as their ingredient restrictions limit technical solutions available to conventional competitors.
Centralized procurement by multi-unit restaurant chains is displacing distributed purchasing through independent distributors. National account specifications now mandate crumbled formats with certified lot tracking and specified co-manufacturer audit scores. This concentration is most visible in California, where quick-service chain density drives volume commitments that reshape production scheduling across Central Valley processing plants.
Cheese Crumbles Market Segmentation
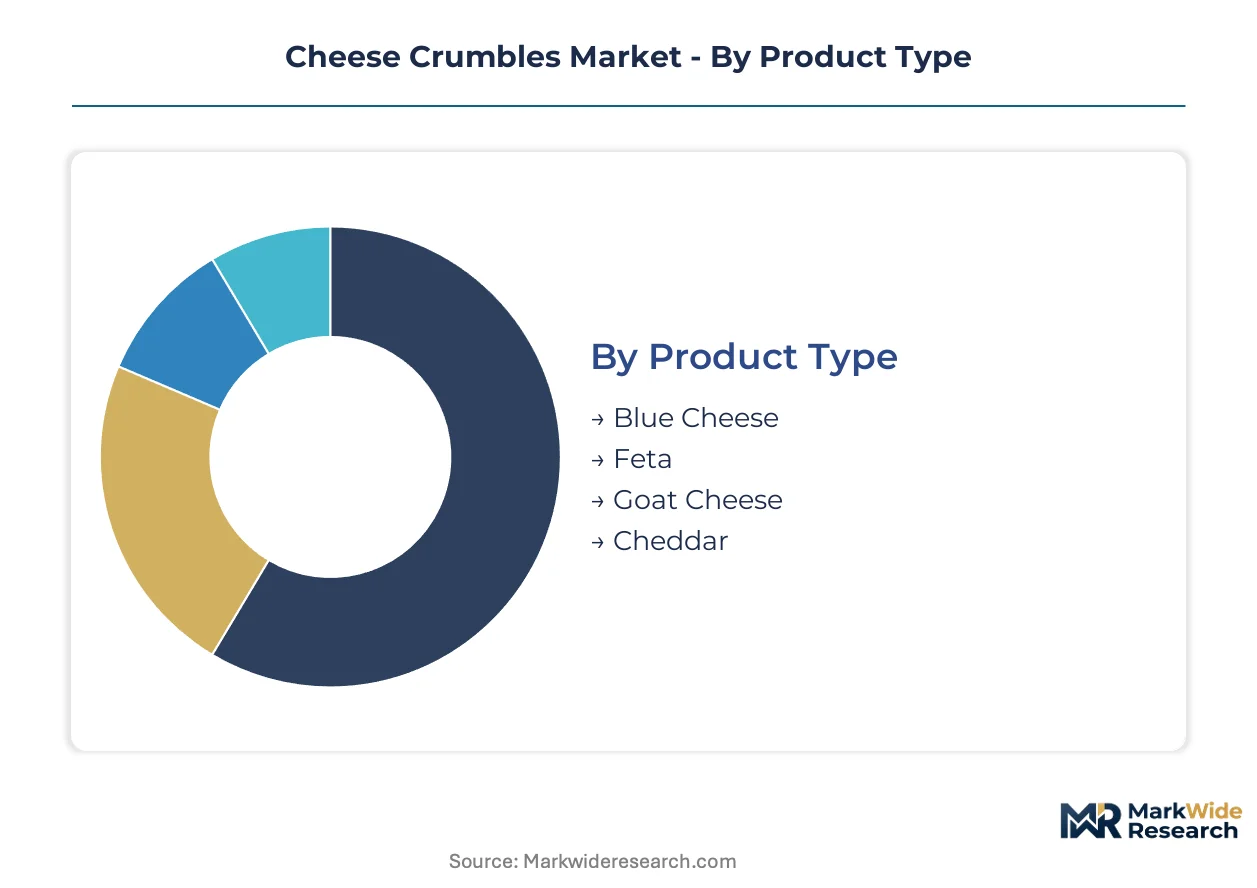
Cheese crumbles segmentation reflects divergent buyer priorities across foodservice automation, retail certification tiers, and export compliance requirements. Each dimension captures distinct margin structures and capital intensity thresholds that reshape processor viability.
Product Type:
Buyers select product types based on flavor intensity requirements, melting behavior specifications, and end-use application constraints.
- Blue Cheese:Aged cultures deliver sharp, pungent profiles with distinctive veining. Quick-service salad chains specify blue cheese crumbles for portion-controlled topping applications where flavor concentration reduces per-serving costs.
- Feta:Brined curd structure provides crumbly texture without mechanical processing, preserving moisture integrity in hot applications. Mediterranean fast-casual concepts drive volume through gyro and grain-bowl assembly lines.
- Goat Cheese:Chèvre variants offer lower lactose content and tangy profiles for specialty retail placement.
- Cheddar:Firm aged blocks crumble mechanically to uniform 2-8 millimeter specifications for industrial food manufacturing.
Blue cheese leads volumes today; goat cheese is gaining share fastest.
Packaging Type:
Packaging selection hinges on shelf-life extension requirements, foodservice throughput speed, and retail visibility needs.
- Plastic Containers:Rigid polyethylene terephthalate tubs with resealable lids dominate retail dairy cases. Club stores and conventional grocers specify this format for stackability and consumer convenience in high-velocity cheese aisles.
- Vacuum Packs:Thermoformed barrier films with modified atmosphere flushing extend refrigerated shelf life. Foodservice distributors favor vacuum packs for reduced spoilage in extended distribution cycles serving remote restaurant locations.
- Pouches:Flexible stand-up bags with zip closures target natural grocery channels and portion-controlled foodservice dispensing.
- Jars:Glass containers with metal lids position in specialty and gift-market tiers where visual presentation commands premium positioning.
Vacuum packs lead volumes today; pouches are expanding most quickly.
End Use:
End-use segmentation separates buyers by operational scale, specification stringency, and procurement centralization patterns.
- Restaurants:Independent and small-chain operators purchase through broadline distributors with variable lot-size flexibility. California Central Valley processors maintain direct relationships with quick-service franchisees seeking certified supply continuity.
- Food Service:Multi-unit institutional contracts mandate FSMA-compliant documentation and specified co-manufacturer audit scores. This channel concentrates procurement power among national account managers at major dairy processors.
- Retail:Supermarket chains and club stores require USDA organic certification or artisan-grade positioning for shelf placement.
- Catering:Event-service operators prioritize bulk formats and extended holding stability for off-premise preparation.
Food service leads volumes today; retail is climbing the fastest.
Grade:
Grade differentiation reflects certification burden, input sourcing constraints, and achievable price realization.
- Organic:USDA-certified dairy standards mandate pasture access, feed restrictions, and processing segregation. Montchevre and specialty goat cheese processors capture premium velocity in natural grocery channels where certification drives purchase decisions.
- Aged:Extended warehouse holding develops flavor complexity and firm texture suitable for mechanical crumbling. This grade commands mid-tier pricing between conventional commodity and certified organic tiers.
- Artisan:Small-batch production with traditional cultures and manual handling protocols targets culinary professionals and specialty retail.
- Conventional:Commodity-grade production without certification constraints serves high-volume foodservice and industrial food manufacturing applications.
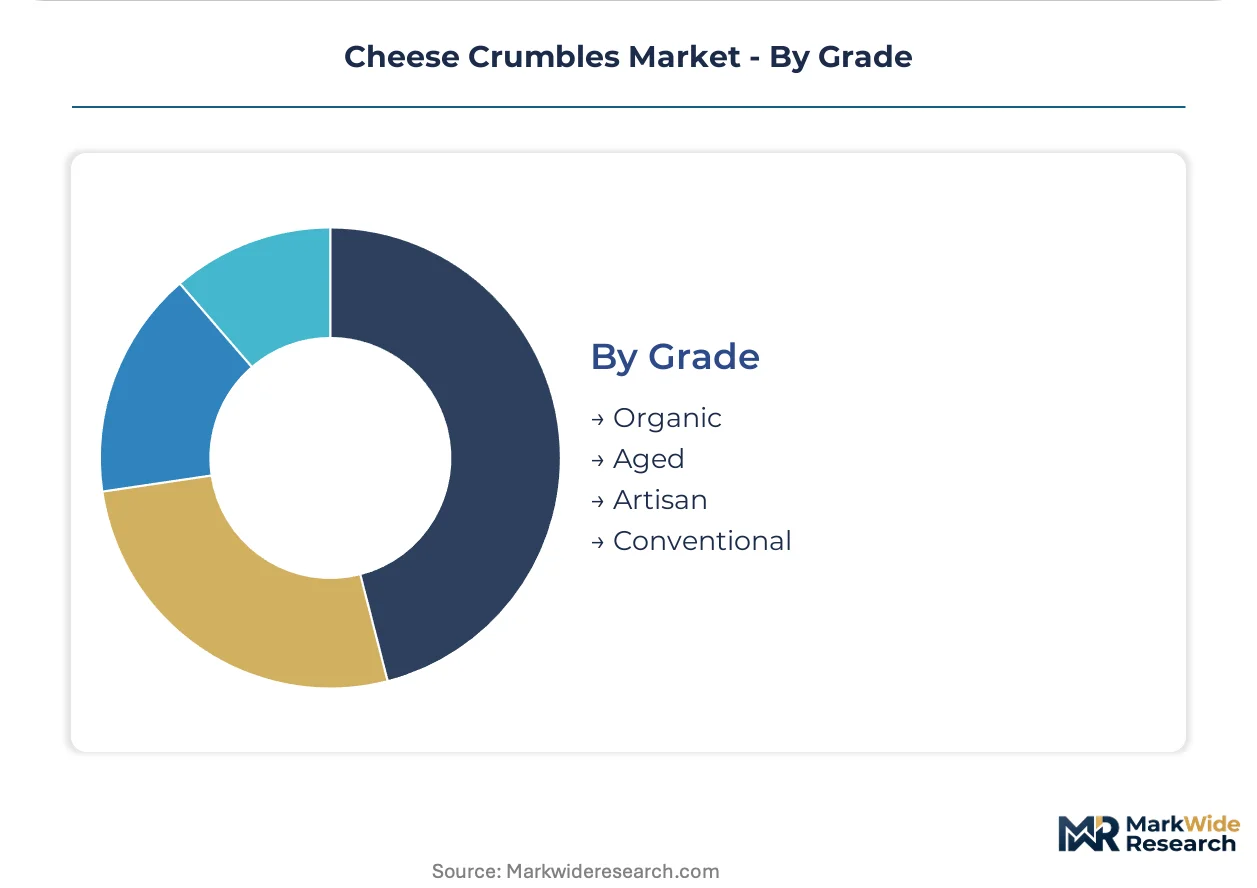
Conventional leads volumes today; organic shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy processing talent pools concentrate in Wisconsin's Master Cheesemaker corridor and California's Central Valley, anchoring North American production capacity for crumbled formats.
United States
Quick-service restaurant chains drive procurement centralization through national account specifications. FDA FSMA preventive controls mandate validated HACCP systems for interstate dairy commerce. California's Central Valley processing cluster leverages fluid milk proximity and cold-chain nodes to serve West Coast foodservice density.
Germany
Industrial food manufacturers source pre-processed dairy inputs for ready-meal and bakery applications. ECHA REACH regulations govern anti-caking agent formulations for crumbles exported to European customers. Bavaria's dairy cooperatives maintain specialized aging facilities for blue cheese varieties destined for foodservice channels.
France
Artisan cheese traditions sustain demand for goat cheese crumbles in specialty retail and culinary professional segments. ANSM hygiene regulations shape processing facility design for export-oriented producers. The Auvergne-Rhône-Alpes region hosts traditional chèvre processors expanding into crumbled format production.
Canada
Supply management frameworks stabilize fluid milk pricing for crumbles processors versus volatile US Class III markets. Health Canada dairy safety standards align with FDA preventive controls for cross-border supply continuity. Quebec's specialty cheese infrastructure supports organic and artisan-grade crumbled production for North American distribution.
Australia
Food manufacturing export orientation drives crumbles production for Asian market access. TGA dairy standards and FSANZ food safety codes regulate processing for international shipment. Victoria's Gippsland dairy region supplies milk solids to crumbles facilities serving Southeast Asian quick-service chains.
Cheese Crumbles Market Competitive Landscape
The competitive structure tilts toward multi-plant dairy processors with captive refrigerated distribution networks. Consolidation pressures squeeze regional specialists lacking cold-chain assets or FSMA-compliant documentation systems. Two archetypes dominate: scale-driven national account suppliers and certified-organic specialty processors. Competitive moves center on co-manufacturer audit score attainment for chain restaurant procurement and organic certification timeline acceleration.
Within the scale-driven tier, Kraft Heinz and Saputo Cheese occupy positions defined by refrigerated distribution reach and multi-plant mozzarella infrastructure. Montchevre exemplifies the specialty archetype, anchoring organic and artisan-grade goat cheese crumbles velocity in natural grocery channels. These three represent the structural split between commodity foodservice supply and premium retail certification tiers.
| Leading Market Players |
|---|
| Arla Foods |
| Kraft Heinz |
| Saputo Cheese |
| Boar's Head |
| DeJong Cheese |
| Litehouse |
| Montchevre |
| Salemville |
| President Cheese |
| Others |
Value Network & Pricing Analysis
Quick-service chain procurement centralization now mandates certified lot tracking and specified co-manufacturer audit scores, forcing suppliers to absorb FSMA compliance costs and consolidate production into validated facilities. This buyer-driven specification tightening compresses margins for sub-scale processors while concentrating pricing power among multi-plant operators with captive cold-chain assets.
Pricing Analysis
Packaged-versus-bulk service bundling separates foodservice contract structures from retail spot purchasing, with vacuum-packed formats commanding logistics premiums for extended distribution cycles. Three-tier pricing structure across organic, artisan, and conventional grades reflects certification burden and input sourcing constraints, with USDA organic standards extracting steepest premiums. Cost compression in conventional tiers intensifies as Class III milk price volatility outpaces hedging capabilities of regional specialists. Foodservice distributors exhibit highest price sensitivity due to centralized national account negotiations, while natural grocery channels absorb organic premiums with lower volume elasticity.
Supply Chain Analysis
Dual-sourcing qualification requirements from multi-unit restaurant chains now mandate redundant supplier validation, stretching FSMA-compliant facility capacity across California, Wisconsin, and Quebec production clusters. Milk solids, aging warehouse capacity, and modified atmosphere packaging films constitute critical input dependencies. Single-source vulnerability concentrates in California Central Valley fluid milk supply during seasonal drought periods. Distribution runs through refrigerated broadline networks for foodservice, direct-to-retail for club stores, and independent distributor cooperatives for artisan-grade metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cheese crumbles market has entered a late-cycle quality phase where quick-service chains now specify crumbled formats with certified documentation, shifting procurement preference toward premium-grade supply assurance over commodity spot purchasing.
For Market Incumbents: Anticipate margin compression from FSMA compliance cost escalation by accelerating organic certification timelines and consolidating co-manufacturer relationships into exclusive long-term arrangements. Defensive positioning requires backward integration into fluid milk supply in California Central Valley and SQF certification investment ahead of audit score threshold tightening by national account managers. For New Entrants and Emerging Players: Direct-to-foodservice digital platforms offer the most penetrable route for artisan-grade crumbles, bypassing broadline distribution concentration through restaurant supply cooperatives in metropolitan culinary markets. Target goat cheese crumbles in natural grocery channels where Montchevre's premium positioning leaves mid-tier organic white space, leveraging portion-controlled pouch formats for velocity differentiation. For Investors and Strategic Acquirers: Asymmetric upside sits with certified-organic processors possessing established pasture-access dairy supply and existing USDA accreditation, as organic certification timelines create 12-18 month entry barriers. Long-term viability over the next decade hinges on FSMA-compliant facility assets with validated HACCP systems and refrigerated distribution reach. Watch quick-service chain specification tightening as the inflection signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Acceleration | USDA pasture-access standards capture premium velocity in natural grocery placement ahead of competitor timelines. |
| FSMA-Compliant Facility Investment | FDA preventive controls validation secures national account eligibility with quick-service chain procurement managers. |
| Direct-to-Foodservice Platform Launch | Independent distributor cooperatives disintermediate broadline concentration for artisan-grade metropolitan market access. |
| Backward Integration into Fluid Milk | California Central Valley milk supply control hedges Class III price volatility and secures aging warehouse allocation. |
| EU Export Compliance Investment | REACH and hygiene package alignment opens formulated crumbles access to European food manufacturing customers. |
Research Methodology
Coverage spans United States, Canada, Germany, France, and Australia, with primary inputs from each market gathered through structured interviews with dairy processing plant managers, quick-service chain procurement directors, foodservice distributor category buyers, and organic certification auditors. Secondary validation draws from FDA FSMA guidance documents, USDA dairy grading standards, ECHA REACH substance registrations, customs trade data for dairy exports, and SEC filings of publicly traded dairy processors. Bottom-up volume modeling triangulates against top-down category spend estimates.
Granularity-level modeling disaggregates volume and value across product type, packaging format, end-use channel, and grade certification tiers, with additional dimensioning by regional production cluster and regulatory compliance burden. CAGRs derive from segment-specific growth trajectories calibrated to input cost elasticity and buyer procurement centralization patterns across the projection horizon. Forecast inputs incorporate Class III milk price futures curves, quick-service chain unit expansion plans, and organic dairy herd conversion rates.
Regulatory enforcement intensity, fluid milk price volatility, and quick-service chain specification tightening are the dominant revision risks to modeled outcomes. Deviation in FDA FSMA audit enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Canada Dairy Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Sheep Milk Market
Dairy Products
Goat Milk Products Market
Dairy Products
Textured Butter Market
Dairy Products
North America Casein and Caseinate Market
Dairy Products
Kefir Market
Dairy Products
Global Yogurt Market
Dairy Products
Parmesan Cheese Market
Dairy Products
Drinkable Yogurt Market
Dairy Products
Lactose-Free Cheese Market
Dairy Products
Evaporated Milk Market
Dairy Products
Mexico Whey Protein Market
Dairy Products
Europe Drinkable Yogurt Market
Dairy Products
Europe Chocolate Milk Market
Dairy Products
Germany Milk Protein Market