
 North America Microspheres Market | 2026-2036
North America Microspheres Market Size, Share, and Industry Trends Forecast 2026-2036
North America Microspheres Market Intelligence
ISO 10993 biocompatibility certification is bifurcating the competitive landscape into qualified medical-grade suppliers and commodity producers locked out of high-value segments. 3M leverages its materials science platform to sustain dual positions in industrial coatings and medical-grade polymer microspheres. Potters Industries anchors the glass microsphere segment through controlled density products serving buoyancy and insulation applications. Momentive specializes in surface-functionalized silica microspheres that command premium positioning in chromatography and diagnostic assays.
Microspheres are spherical particles ranging from one micron to one millimeter in diameter, engineered from glass, polymer, ceramic, or metallic compositions through processes such as emulsion polymerization, spray drying, or sol-gel synthesis, serving functions including controlled release, density modification, reflectivity enhancement, and cell separation. Glass microspheres retain dominant volume share in automotive lightweighting and oilfield applications where compressive strength and chemical resistance justify higher unit costs. Polymer microspheres represent the fastest-expanding category as biodegradable PLGA and PCL formulations displace conventional excipients in parenteral drug delivery systems developed by pharmaceutical contract manufacturers. The application split between drug delivery and cosmetics reveals divergent margin structures, with pharmaceutical applications requiring GMP-validated production commanding three to five times the unit economics of personal care formulations.
FDA 21 CFR Part 211 current good manufacturing practice requirements and USP Chapter 788 particulate matter standards govern injectable microsphere production, while EPA TSCA Section 5 premanufacture notifications constrain novel polymer introductions. Health Canada's ICH Q3D elemental impurity guidelines and PMRA pesticide formulation standards add compliance layers for cross-border suppliers serving Canadian agricultural and pharmaceutical markets. Stakeholders must monitor evolving FDA guidance on complex generic drug-device combination products incorporating microsphere depots, as draft policy shifts will determine which controlled-release platforms secure abbreviated approval pathways.
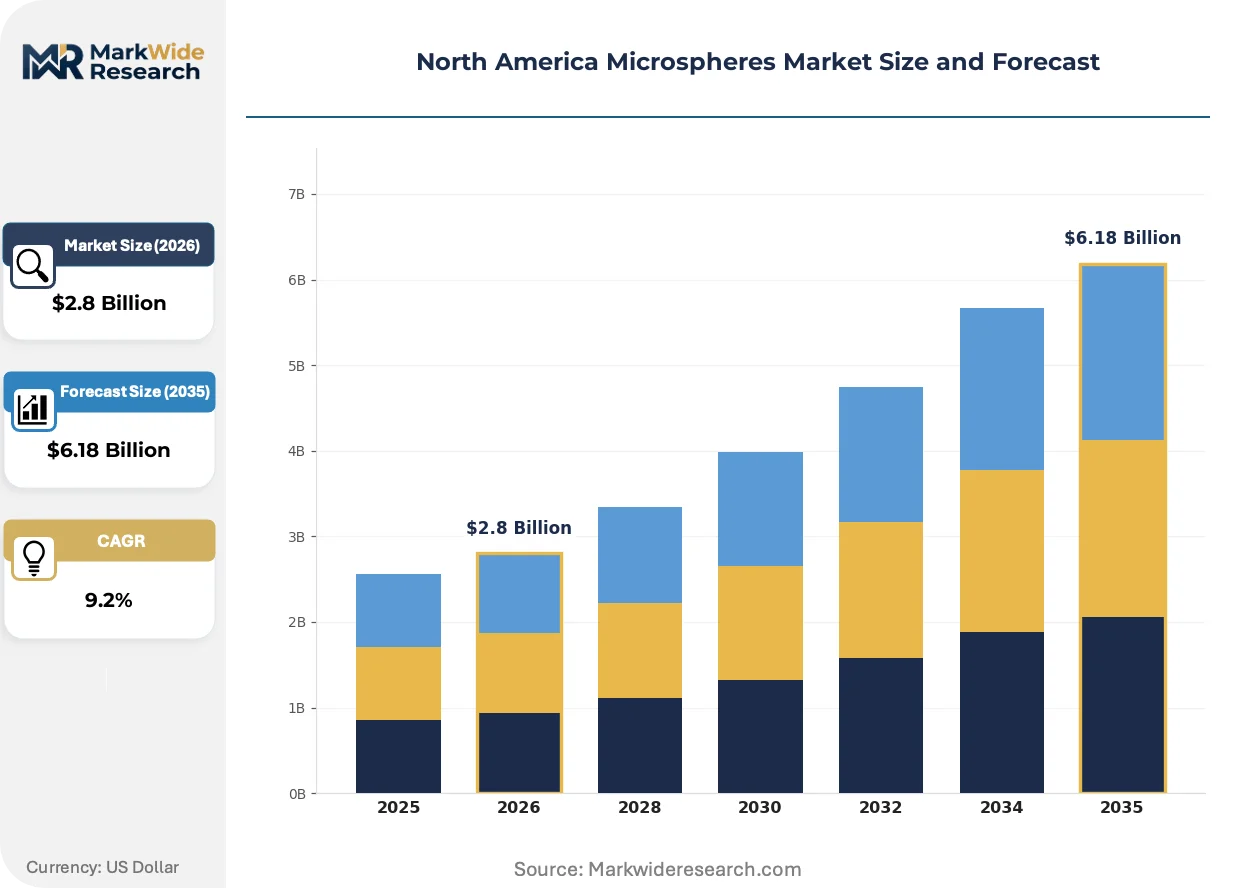
Market Dynamics
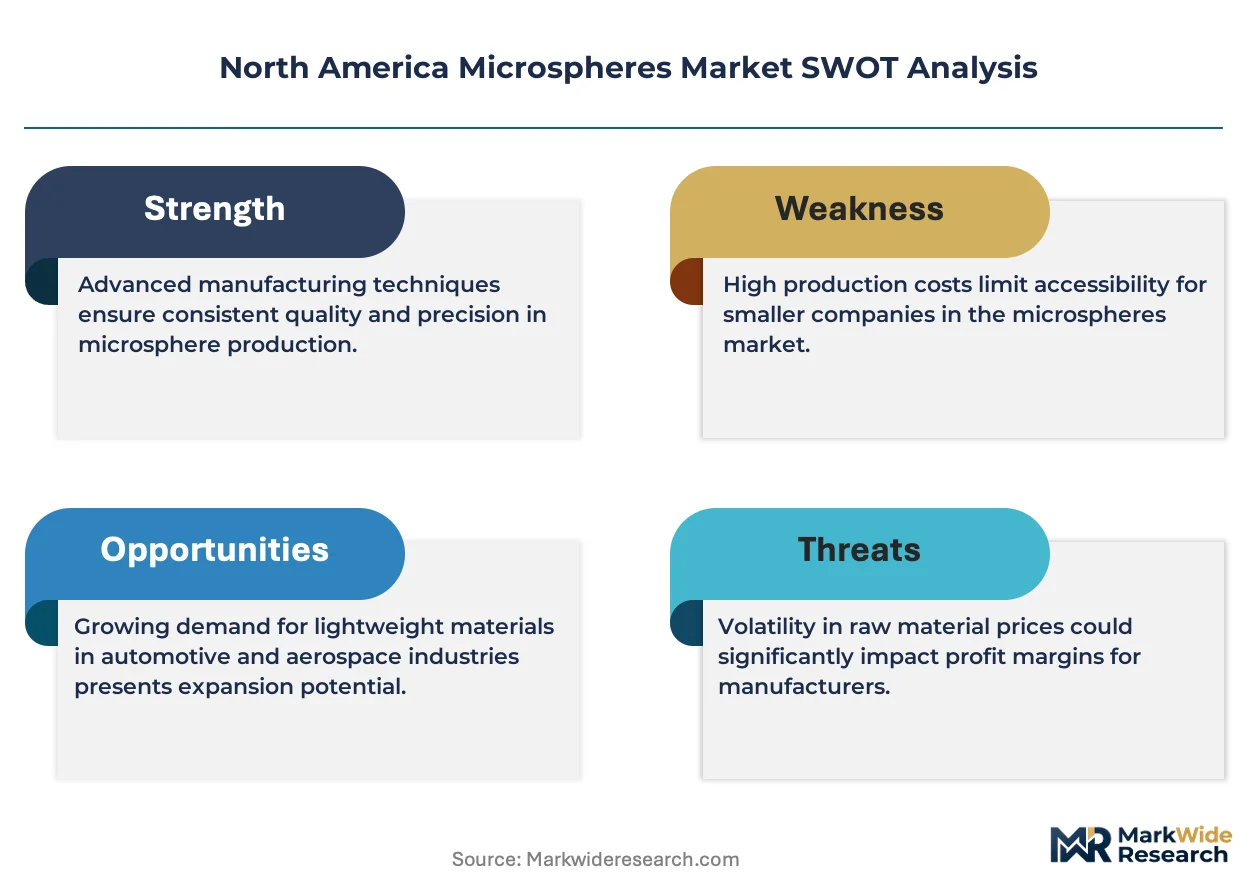
FDA quality standards for injectable microsphere products are tightening material purity requirements and reshaping supplier qualification protocols across the United States and Canada. This regulatory pressure is bifurcating the competitive landscape into qualified medical-grade suppliers and commodity producers locked out of high-value pharmaceutical segments.
Growth Catalysts
- Controlled-release formulations:Pharmaceutical drug delivery systems are expanding usage across the United States and Canada as parenteral depots gain regulatory traction for chronic disease management.
- Biodegradable PLGA and PCL formulations:These engineered polymers are displacing conventional excipients in parenteral drug delivery systems developed by pharmaceutical contract manufacturers.
- Northeast biotechnology clusters:Demand concentrates around Boston and the New Jersey corridor where contract manufacturing organizations cluster alongside research institutions.
Market Restraints
- Silica precursor cost volatility:Sol-gel synthesis feedstock prices fluctuate with energy markets, compressing margins for surface-functionalized diagnostic-grade microspheres.
- Single-source supply concentration:High-purity glass microsphere production for oilfield applications depends on a limited supplier base in the southeastern United States.
- USP Chapter 788 particulate matter standards:These stringent requirements create regulatory friction for novel polymer introductions seeking injectable approval pathways.
Strategic Opportunities
- Canadian agricultural formulations:Health Canada's PMRA pesticide formulation standards create compliance layers that favor cross-border suppliers with established quality systems.
- Complex generic drug-device combinations:FDA draft guidance on abbreviated approval pathways for microsphere depot platforms will determine which controlled-release systems secure first-mover advantage.
- Surface functionalization convergence:Chromatography and diagnostic assay applications are driving demand for hybrid polymer-silica architectures with dual binding chemistries.
Industry Challenges
- GMP-validated production talent scarcity:Pharmaceutical-grade microsphere manufacturing requires specialized process engineers familiar with FDA 21 CFR Part 211 current good manufacturing practice requirements.
- ISO 10993 biocompatibility certification timelines:Extended testing protocols for medical-grade polymer microspheres delay product commercialization by 18-24 months.
- Legacy excipient integration complexity:New biodegradable microsphere platforms face formulation challenges when replacing established controlled-release matrices in approved drug products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Microspheres Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.18 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Polymer, Ceramic, Metallic, Hybrid, Biodegradable Application: Drug Delivery, Cosmetics, Medical Imaging, Coatings, Adhesives, Agriculture End User Industry: Pharmaceuticals, Personal Care, Biotechnology, Manufacturing, Research Laboratories Distribution Channel: Direct Sales, Online Platforms, Distributors, Specialty Stores, Scientific Suppliers |
| Companies Covered | 3M, Potters Industries, Trelleborg, Akzo Nobel, Luminex, Nouryon, Cospheric, Momentive, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Microspheres Market Strategic Shifts & Innovations
Biodegradable polymer architectures are fragmenting traditional excipient supply relationships as pharmaceutical formulators seek tunable degradation kinetics. Three distinct developments are reshaping competitive positioning in material platforms, regulatory pathways, and procurement models.
PLGA microsphere synthesis is fragmenting the parenteral drug delivery landscape by enabling tunable release profiles from weeks to months. Contract manufacturing organizations in the Northeast United States are adopting these platforms at accelerating pace for peptide and protein formulations. This capability expansion is compressing demand for conventional polymeric excipients and eroding their incumbent supply relationships.
Health Canada's ICH Q3D elemental impurity guidelines are tightening cross-border supplier qualification requirements for pharmaceutical and agricultural microsphere applications. The industrial consequence is a compliance burden that favors established medical-grade producers with validated quality systems over commodity entrants. Canadian agricultural formulation suppliers are responding by consolidating procurement around pre-qualified vendors with dual pharmaceutical-agricultural certification.
Buyer concentration among biotechnology clusters is compressing switching cycles and unbundling after-sales technical support from material supply contracts. Large pharmaceutical developers now demand dedicated formulation scientists embedded within microsphere supplier organizations. This service model shift is most visible in the Boston-New Jersey corridor where contract manufacturing organizations negotiate multi-year partnership agreements with technical performance milestones.
North America Microspheres Market Segmentation
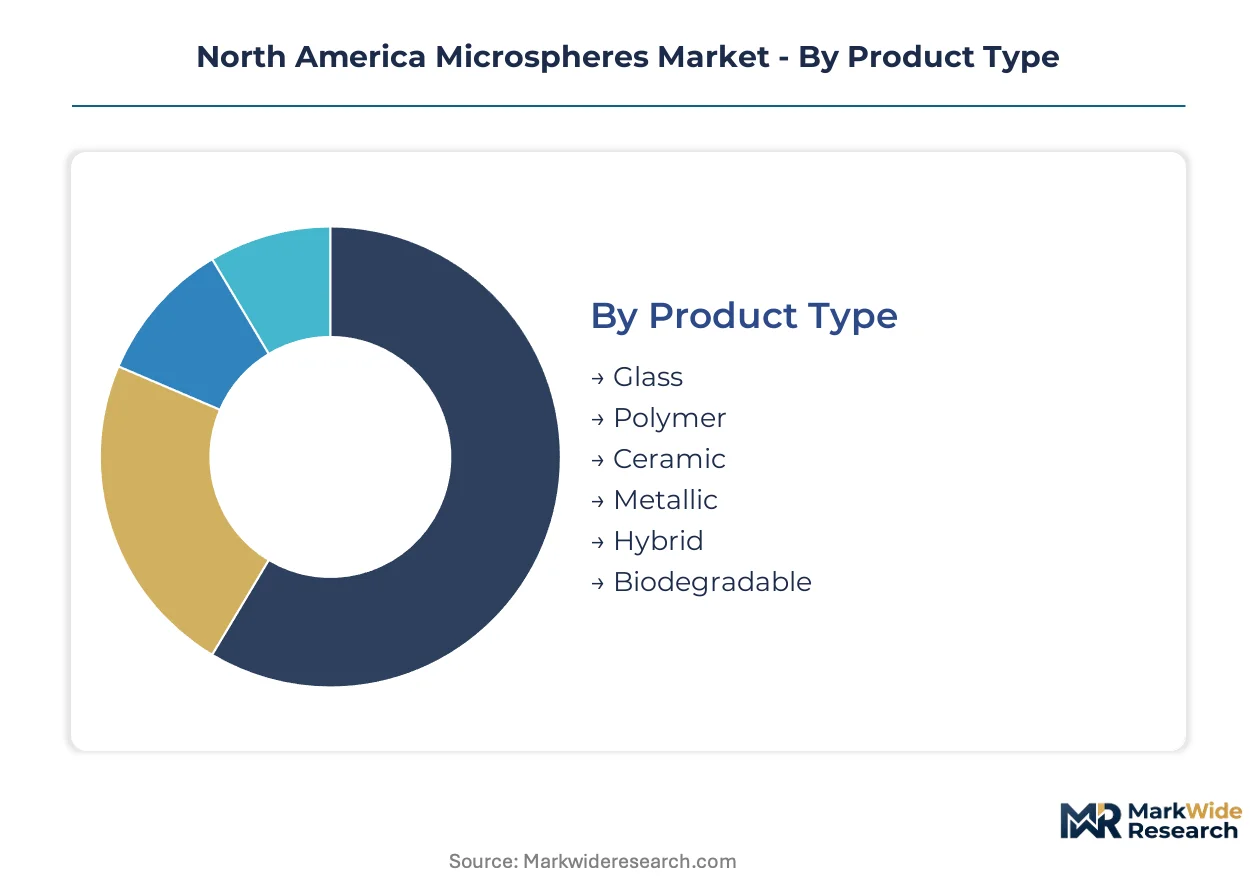
Segmentation in the North America microspheres market reveals divergent margin structures and regulatory requirements across material platforms. Pharmaceutical-grade formulations command premium positioning while industrial applications compete on volume scale and technical specifications.
Product Type:
Domestic production concentrates on medical-grade polymer and biodegradable formulations serving FDA-regulated applications, while glass and ceramic microspheres draw significant import dependency for oilfield and industrial uses.
- Glass:Borosilicate and soda-lime compositions deliver compressive strength exceeding 20,000 psi for oilfield cementing and automotive underbody coatings. Demand clusters in the Permian Basin and Gulf Coast where hydraulic fracturing operations require density-modifying additives.
- Polymer:Polystyrene and polymethyl methacrylate microspheres enable precise size distribution for diagnostic assays and liquid chromatography. Northeast biotechnology clusters in Massachusetts and New Jersey absorb the majority of high-purity production for immunoassay development.
- Ceramic:Alumina and zirconia microspheres serve high-temperature insulation and grinding media applications with thermal stability above 1,000°C.
- Metallic:Aluminum and nickel-coated hollow spheres provide electromagnetic shielding and conductive fillers for aerospace composites.
- Hybrid:Core-shell architectures combine polymer flexibility with inorganic surface functionality for specialized chromatography resins.
- Biodegradable:PLGA and PCL formulations enable tunable degradation kinetics from weeks to months for parenteral drug depots.
Glass microspheres hold the largest share; momentum sits with biodegradable formulations expanding most quickly in controlled-release applications.
Application:
Cost tier stratification separates pharmaceutical applications requiring GMP validation from commodity industrial uses competing on unit economics.
- Drug Delivery:Injectable microsphere depots for peptide and protein formulations require ISO 10993 biocompatibility certification and FDA 21 CFR Part 211 compliance. Contract manufacturing organizations in the Boston-New Jersey corridor dominate procurement for long-acting antipsychotic and diabetes therapies.
- Cosmetics:Silica and polymer microspheres provide optical blurring and texture modification in color cosmetics and skincare. Formulation houses in California and New York drive demand for sensory-enhancing additives.
- Medical Imaging:Radiopaque and echogenic microspheres serve as contrast agents for ultrasound and computed tomography procedures.
- Coatings:Reflective glass microspheres enhance retroreflectivity for highway safety markings and traffic signage.
- Adhesives:Spacer-grade microspheres control bond line thickness in electronics assembly and automotive panel bonding.
- Agriculture:Encapsulated pesticide and fertilizer formulations enable controlled release aligned with crop growth cycles.
Drug delivery commands the steepest pricing tier; cosmetics applications demonstrate the highest volume elasticity.
End User Industry:
Customer type fragmentation splits procurement between centralized pharmaceutical quality organizations and decentralized industrial purchasing.
- Pharmaceuticals:Large molecule developers and generic manufacturers require validated supply chains with dedicated quality agreements. FDA pre-approval inspections and drug master file submissions govern supplier selection.
- Personal Care:Multinational cosmetic houses and independent beauty brands prioritize sensory performance and regulatory compliance for EU and Asian export markets.
- Biotechnology:Cell therapy and gene editing companies utilize magnetic microspheres for cell separation and purification workflows.
- Manufacturing:Automotive, aerospace, and electronics producers specify microspheres for lightweighting and functional surface modification.
- Research Laboratories:Academic and government institutions procure small-batch specialty grades for assay development and materials science research.
Pharmaceuticals generate the highest revenue per kilogram; biotechnology represents the fastest-expanding customer segment.
Distribution Channel:
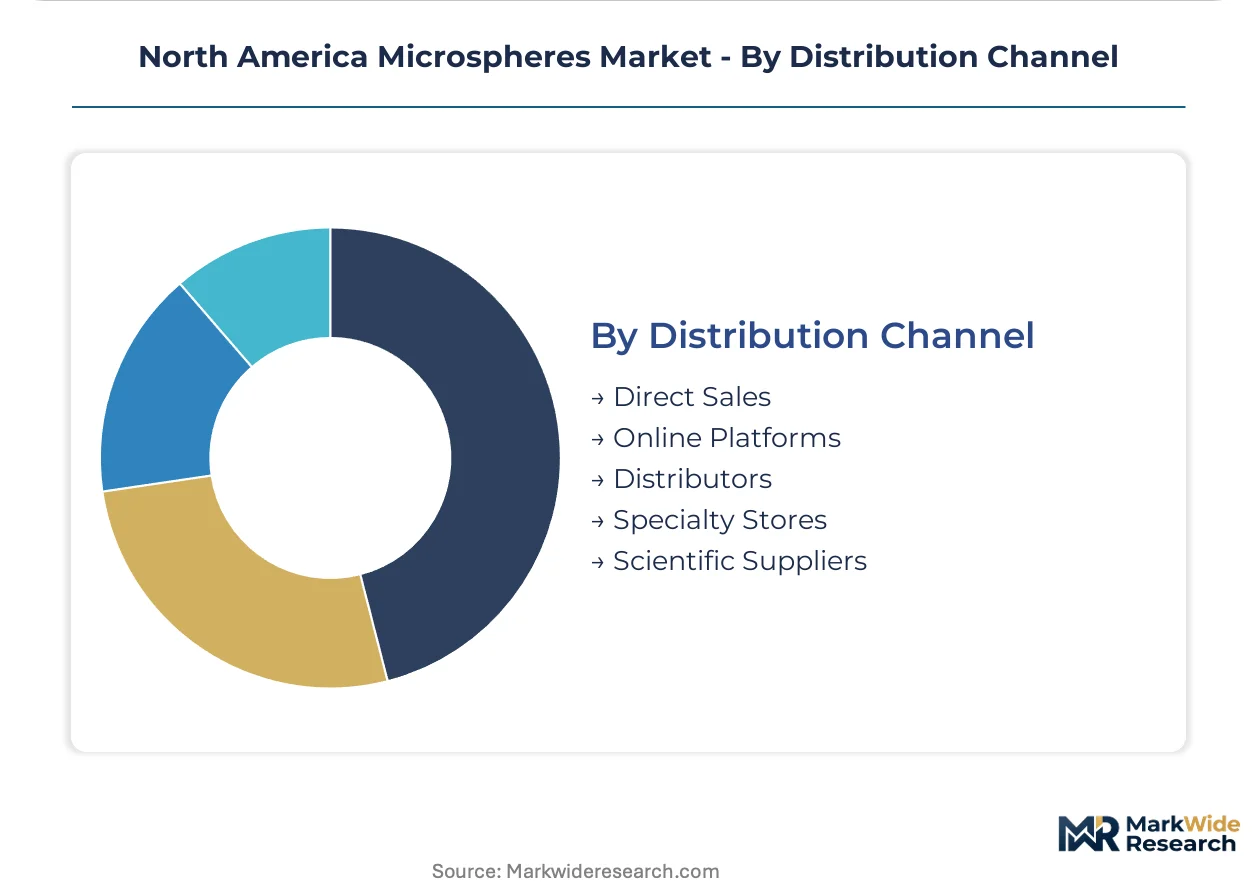
Supply concentration favors direct relationships for pharmaceutical-grade materials while industrial segments tolerate multi-tier distribution.
- Direct Sales:Pharmaceutical and biotechnology customers negotiate multi-year supply agreements with technical support embedded in contract terms. Field application scientists co-develop formulations at customer sites.
- Online Platforms:Research-grade and small-batch industrial microspheres move through e-commerce channels with rapid fulfillment and technical documentation access.
- Distributors:Regional industrial distributors stock commodity glass and ceramic grades for oilfield and coatings customers.
- Specialty Stores:Local scientific supply houses serve academic researchers with catalog-standard products and expedited shipping.
- Scientific Suppliers:Integrated laboratory supply companies bundle microspheres with consumables and instrumentation for core facility customers.
Direct sales capture the majority of pharmaceutical value; online platforms are climbing the fastest in research-grade procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract manufacturers and biotechnology developers concentrate procurement in coastal metropolitan corridors, while oilfield service operators anchor demand in hydrocarbon-producing basins. Regional supply chains bifurcate between FDA-regulated medical-grade production and industrial-scale commodity fabrication.
United States
Injectable drug depots and diagnostic assay development drive pharmaceutical-grade polymer consumption. FDA 21 CFR Part 211 compliance requirements filter supplier participation in parenteral applications. The Boston-New Jersey corridor hosts contract manufacturing organizations that co-develop controlled-release formulations with embedded supplier technical staff.
Canada
Cross-border agricultural formulation demand supports encapsulated pesticide and fertilizer microsphere consumption. Health Canada's PMRA standards and ICH Q3D elemental impurity guidelines create dual compliance layers for suppliers. Ontario-based formulators consolidate procurement around vendors with pre-validated pharmaceutical quality systems.
Northeast Corridor
Biotechnology clusters in Massachusetts and New Jersey generate concentrated demand for high-purity polystyrene and polymethyl methacrylate grades. State-level environmental regulations in New York and New Jersey constrain solvent-based microsphere synthesis operations. Academic medical centers in Boston and Philadelphia anchor research-grade procurement for cell separation workflows.
Permian Basin and Gulf Coast
Hydraulic fracturing operations in Texas and Louisiana consume borosilicate glass microspheres for density-modifying cement slurries. EPA TSCA reporting requirements govern novel polymer introductions for oilfield chemistry applications. Midland-Odessa and Houston serve as distribution nodes for high-compressive-strength grades used in deep-well completions.
California
Cosmetic formulation houses in Los Angeles and the Bay Area drive demand for sensory-enhancing silica and polymer microspheres. California's Proposition 65 chemical disclosure requirements shape material selection for personal care applications. Silicon Valley biotechnology firms utilize magnetic microspheres for cell therapy purification processes.
North America Microspheres Market Key Industry Players
Player mix skews toward diversified materials conglomerates with dual industrial-medical positions alongside specialized medical-grade pure-plays. Market structure exhibits tiered consolidation where FDA-qualified suppliers command pricing premiums and commodity producers compete on volume scale. Strategic archetypes include vertically integrated materials platforms, contract manufacturing-integrated suppliers, and research-grade specialty producers. Competitive dynamics center on ISO 10993 certification acquisition and embedded technical service partnerships with pharmaceutical developers.
Among diversified materials platforms, 3M occupies a position spanning industrial coatings and medical-grade polymer microspheres. Potters Industries anchors the glass microsphere segment through density-controlled product lines. Momentive sits within the surface-functionalized silica tier serving chromatography and diagnostic assay applications. These three exemplify how materials science capabilities translate across regulatory boundaries while maintaining distinct competitive positioning in premium versus commodity segments.
| Leading Market Players |
|---|
| 3M |
| Potters Industries |
| Trelleborg |
| Akzo Nobel |
| Luminex |
| Nouryon |
| Cospheric |
| Momentive |
| Merck KGaA |
| Others |
Cost & Logistics Intelligence
Minimum efficient scale in PLGA synthesis runs above 500 kilograms per batch, concentrating production among three domestic suppliers and establishing cost floors that commodity entrants cannot undercut without sacrificing FDA 21 CFR Part 211 compliance. This scale threshold bifurcates supply into validated pharmaceutical-grade tiers and price-competitive industrial grades serving coatings and agriculture.
Pricing Analysis
Cost-plus contracts with silica precursor indexation dominate glass microsphere procurement for oilfield applications, insulating buyers from energy-market volatility while compressing supplier margins during feedstock spikes. Pricing stratifies across medical-grade, industrial-grade, and research-grade tiers, with ISO 10993 certification commanding three-fold premiums over unvalidated alternatives. Cost compression in industrial polymer grades is intensifying as Asian imports capture coatings market share. Biotechnology clusters in Massachusetts exhibit the lowest price sensitivity due to embedded technical service requirements, while agricultural formulators in the Canadian prairies prioritize unit economics over performance specifications.
Supply Chain Analysis
Strategic stockpiling of high-purity borosilicate microspheres prevails among Permian Basin operators facing single-source concentration in southeastern US glass production, whereas pharmaceutical buyers favor just-in-time delivery with vendor-managed inventory clauses. Domestic manufacturing draws from German silica precursors, Chinese rare-earth coatings, and Canadian petroleum-derived polymer feedstocks. Tariff exposure on Chinese-sourced diagnostic-grade polystyrene microspheres creates supply vulnerability for Northeast immunoassay developers. Distribution runs through direct technical sales for pharmaceutical applications and regional industrial distributors for oilfield and coatings segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized process engineers capable of GMP-validated microsphere synthesis represent the scarcest capability layer, with lead times for qualified talent extending 18 months and constraining capacity expansion across the North American supply base.
For Market Incumbents: Shield pharmaceutical-grade positioning by accelerating ISO 10993 certification acquisition for next-generation biodegradable platforms before draft FDA guidance on complex generic drug-device combinations crystallizes competitive barriers. Prioritize backward integration into PLGA polymer production to capture margin erosion from feedstock suppliers. Embedded technical service teams in the Boston-New Jersey corridor should expand to preempt contract manufacturing organizations from unbundling formulation support. For New Entrants and Emerging Players: Technical service gaps in Canadian agricultural microsphere formulations present accessible entry points where established pharmaceutical suppliers under-invest after-sales support. Target Ontario-based pesticide formulators seeking dual pharmaceutical-agricultural certification to streamline cross-border procurement. Pursue partnership-based go-to-market models with regional distributors holding PMRA pre-qualification relationships rather than direct sales investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract manufacturing-integrated suppliers with captive formulation development capabilities and established FDA drug master file portfolios. Long-term viability rests on biodegradability platform breadth rather than single-polymer dependence. Watch for FDA draft guidance finalization on microsphere depot abbreviated approval pathways as the inflection signal determining which controlled-release platforms secure sustainable competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Certification Acquisition | FDA biocompatibility standards filter qualified suppliers from commodity competitors in injectable segments. |
| Backward Integration into PLGA Production | Captive polymer supply insulates margins from sol-gel precursor volatility and tightens quality control. |
| Embedded Technical Service Expansion | Dedicated formulation scientists at customer sites lock in multi-year pharmaceutical supply agreements. |
| Canadian Agricultural Market Entry | Health Canada PMRA dual-certification requirements favor cross-border suppliers with validated quality systems. |
| Hybrid Polymer-Silica Architecture Development | Dual-binding chemistry platforms capture chromatography and diagnostic assay premium positioning. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical formulation scientists, contract manufacturing organization procurement directors, oilfield chemistry technical leads, and agricultural formulation regulatory affairs managers. Secondary validation drew from FDA 510(k) filings, Health Canada PMRA registration databases, USPTO patent landscapes, and SEC 10-K disclosures from diversified materials conglomerates. Bottom-up volume modeling triangulated against top-down market sizing from trade customs data and industry association production surveys.
Across the projection horizon, analytical frameworks segmented volume and value outputs by material platform, application tier, end-user industry procurement structure, and distribution channel concentration. CAGRs were derived from regression analysis of historical production capacity utilization, patent filing velocity in biodegradable polymer architectures, and regulatory approval pathway timelines for controlled-release formulations. Modeled inputs incorporated silica precursor price indices, biotechnology cluster employment growth, and hydraulic fracturing activity metrics from the Permian Basin.
Underlying assumptions cover sustained FDA enforcement of 21 CFR Part 211 quality standards, stable Health Canada-EPA regulatory equivalence for cross-border agricultural products, and continued Northeast biotechnology cluster expansion, with deviation risk concentrated in single-source glass microsphere supply disruption and draft FDA guidance timeline delays. Revision becomes warranted when biodegradable polymer patent litigation or tariff restructuring on Chinese diagnostic-grade imports crosses materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Vulcanized Fiber Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Global PU Films Market
Specialty Materials
Barium Borate Market
Specialty Materials
Hornbeam Market
Specialty Materials
Niobium Pentoxide Market
Specialty Materials
Carrageenan Film Market
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Europe Polyether Ether Ketone (Peek) Market
Specialty Materials
Mica Sheet Market
Specialty Materials
Global Montan Wax Market
Specialty Materials
United States Microspheres Market
Specialty Materials
Eptfe in Spotlight-Poly-Vents Market
Specialty Materials
Battery Separator Films Market
Specialty Materials
Reflective Polarizing Films Market