
 Barium Borate Market | 2026-2036
Barium Borate Market Size, Share, and Industry Trends Forecast 2026-2036
Barium Borate Market Analytics
Defense contractors are gaining procurement share as commercial laser OEMs retrench, and the Barium Borate Market is bifurcating between security-cleared suppliers and commercial distributors. CASTECH Inc. dominates high-damage-threshold crystal production for directed-energy programs. EKSMA Optics leverages its Baltic manufacturing base to sustain cost-competitive polishing operations. Raicol Crystals specializes in flux-grown barium borate for tunable visible and UV laser systems.
Barium borate is a birefringent inorganic compound synthesized through high-temperature solid-state reaction of barium carbonate and boric oxide, typically yielding beta-barium borate crystals with transparency from 190 nm to 3,500 nm for frequency conversion and electro-optic modulation. Single crystalline forms command premium positioning due to exacting phase-matching requirements in femtosecond laser systems, while polycrystalline grades serve cost-sensitive optical isolator applications. The Lasers application segment anchors volume demand through diode-pumped solid-state and ultrafast system builds, whereas Nonlinear Optics represents the fastest-growing margin pool as quantum photonics researchers specify custom aperture geometries.
REACH compliance in Europe and RoHS substance restrictions constrain borate purity thresholds and trace heavy-metal certification burdens on importers. China's GB standards and MEE environmental assessments govern effluent discharge from crystal growth facilities, directly affecting production economics for domestic suppliers. Stakeholders must monitor evolving export control classifications for nonlinear optical materials, as dual-use technology designations increasingly determine which crystal vendors qualify for defense photonics contracts.
Market Dynamics
Dual-use technology export controls are fragmenting supplier qualification pathways, forcing crystal manufacturers to choose between defense-cleared production lines and commercial-scale operations.
Growth Catalysts
- Directed-energy weapons procurement:Pentagon and allied defense ministries are accelerating nonlinear optical component orders for laser weapon demonstrators, pulling high-damage-threshold crystal demand.
- China's dual carbon goals:Stricter MEE environmental assessments are consolidating domestic borate processing capacity, tightening global feedstock availability and elevating prices for compliant material.
- Femtosecond laser proliferation:Ultrafast system builders in Germany's Jena-Munich precision optics cluster are expanding phase-matched crystal orders for micromachining and medical device fabrication.
Market Restraints
- Barium carbonate price volatility:Feedstock costs swing with Chinese mining quota adjustments, compressing margins for flux-grown crystal producers dependent on imported ore.
- Flux-growth capacity concentration:Viable melt-growth facilities cluster in Fujian and Shandong provinces, creating single-point-of-failure risk for beta-barium borate supply.
- Lithium niobate substitution:Electro-optic modulator designers are specifying lithium niobate-on-insulator wafers for telecom applications, displacing bulk borate crystals in some frequency conversion roles.
Strategic Opportunities
- Quantum photonics research:Custom aperture geometries for entangled photon generation represent an emerging specification tier with premium pricing power.
- India's PLI scheme:Production-linked incentives for semiconductor and photonics manufacturing are attracting crystal polishing and coating investments to offset Chinese supply concentration.
- UV-C laser disinfection:Post-pandemic municipal water treatment specifications are opening new volume demand for 266 nm generation optics.
Industry Challenges
- Optical coating technician scarcity:Ion-beam sputtering specialists capable of depositing anti-reflective stacks on hygroscopic borate surfaces command wage premiums that inflate finished component costs.
- ITAR compliance timeline:Security clearance processing for crystal growth engineers stretches 18-24 months, throttling defense contractor scaling plans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barium Borate Market |
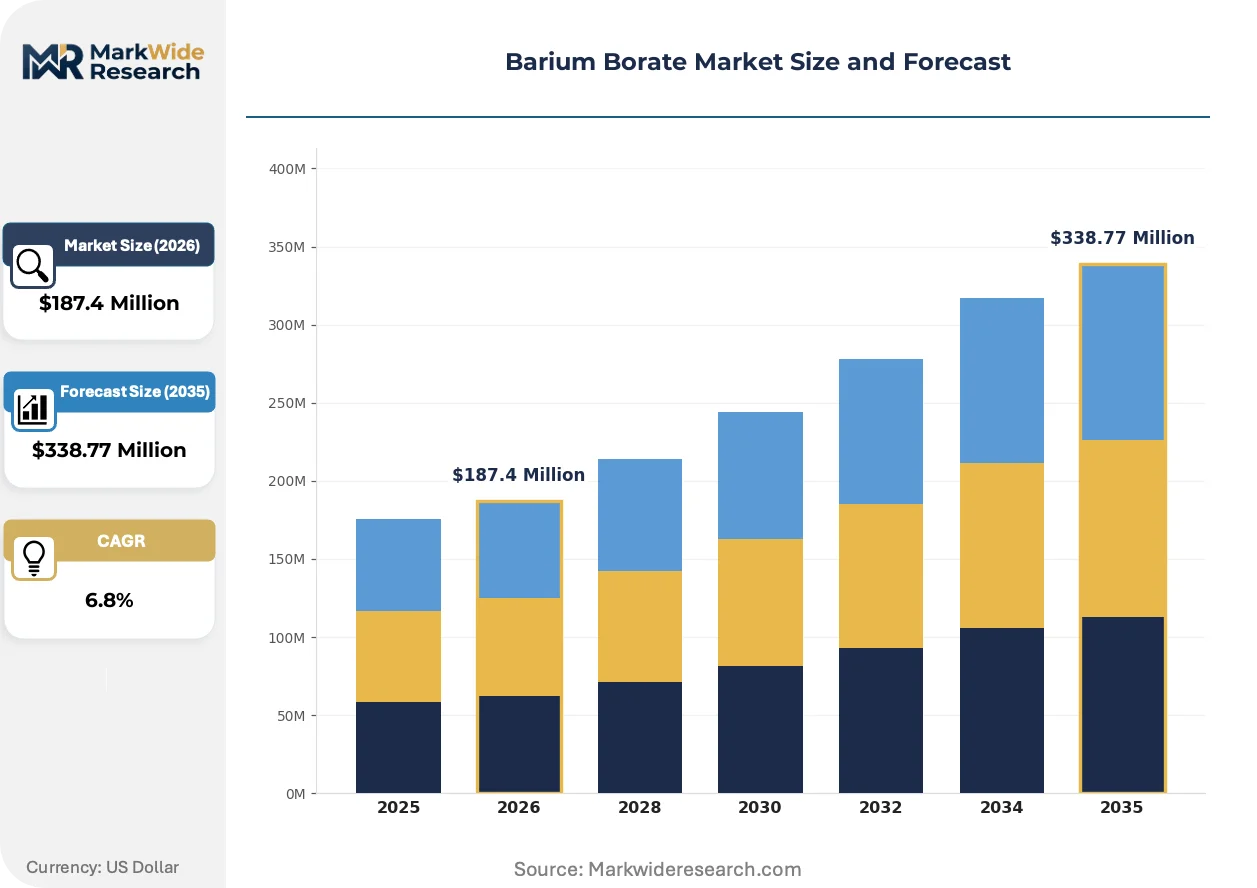
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Crystalline, Polycrystalline, Glassy, Amorphous Application: Lasers, Optics, Nonlinear Optics, Chemical Catalysts End User: Aerospace, Electronics, Photonics, Research Institutions Form: Powder, Granules, Flakes, Crystals |
| Companies Covered | CASTECH Inc., EKSMA Optics, Inrad Optics, Raicol Crystals, American Elements, Altechna, Cristal Laser, Newlight Photonics, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barium Borate Market Evolving Landscape
Process convergence between semiconductor lithography and nonlinear optics is compressing crystal specification tolerances while expanding addressable wavelength ranges.
Thin-film barium borate coatings deposited by pulsed laser ablation are replacing bulk crystals in compact frequency converters for handheld LIDAR units. Automotive tier-1 suppliers are qualifying these sub-millimeter optical stacks for next-generation ADAS modules. The technology is miniaturizing traditional bulk-crystal architectures into wafer-scale integrable formats.
REACH substance restrictions and RoHS trace-heavy-metal certification are forcing importers to document borate provenance through batch-level ICP-MS analysis. European laser system integrators are rejecting uncertified crystalline material, redirecting procurement toward ECHA-registered suppliers. This regulatory friction is accelerating consolidation among distributors capable of maintaining compliant documentation chains.
Security-cleared procurement officers at prime defense contractors are disintermediating traditional optical component distributors, establishing direct technical relationships with crystal growth houses. Specifications now flow through classified channels before commercial release, compressing information asymmetry between end-users and manufacturers. This pattern concentrates most visibly in US directed-energy programs, where program offices embed engineers at qualified supplier facilities.
Barium Borate Market Segmentation
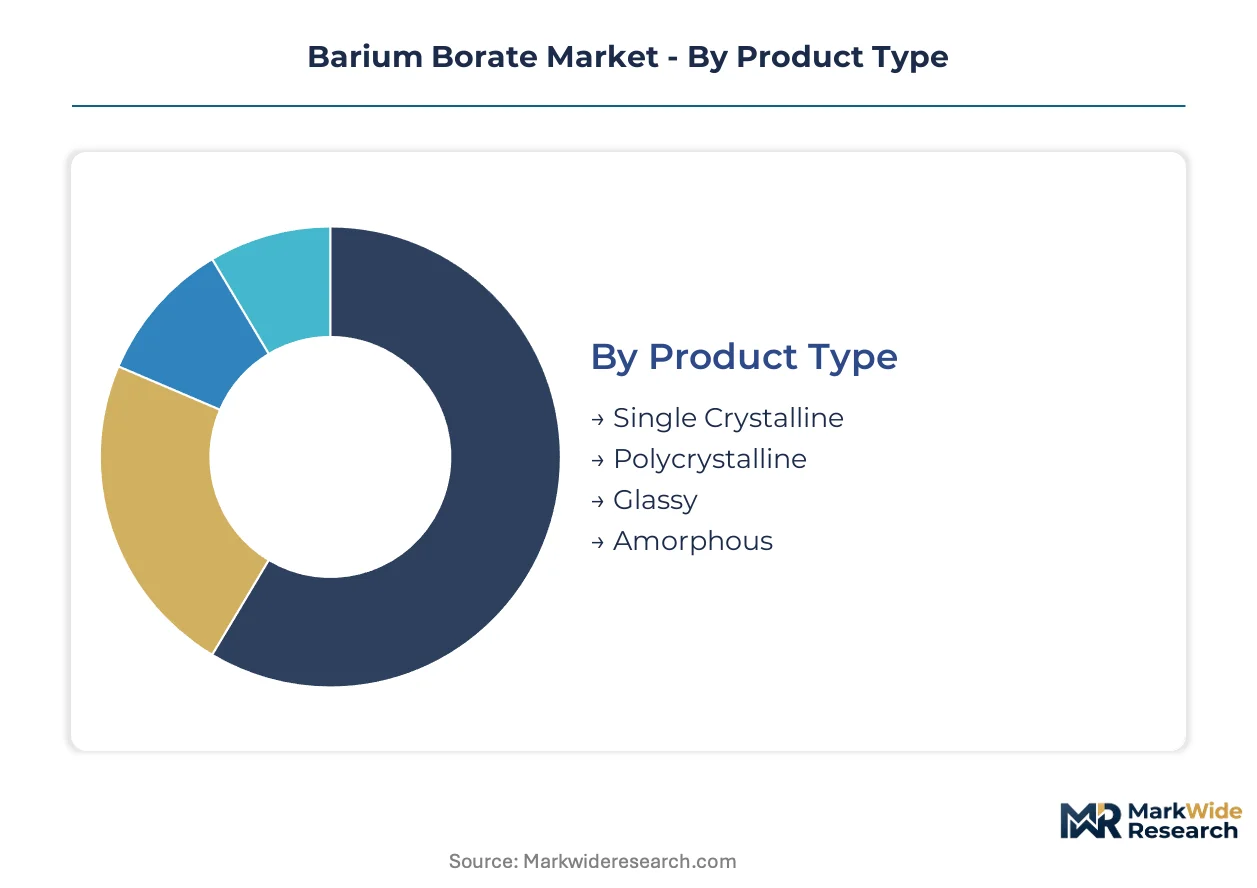
Barium borate crystallography dictates procurement pathways across defense, semiconductor, and research verticals. Specification tolerances vary dramatically by end-use, creating tiered supply chains where certified grades command substantial premiums over industrial material.
Product Type:
REACH and RoHS substance restrictions differentiate certification burdens across crystalline grades, with ECHA-registered suppliers capturing premium positioning in European procurement channels.
- Single Crystalline:Beta-barium borate crystals grown via flux methods deliver exacting phase-matching for femtosecond laser systems. German precision optics integrators in Jena and Munich specify these grades for micromachining applications where birefringence control determines system performance.
- Polycrystalline:Aggregated crystal structures serve cost-sensitive optical isolators and bulk frequency converters. Chinese MEE environmental assessments are consolidating domestic processing capacity, tightening feedstock availability for compliant polycrystalline material.
- Glassy:Vitrified forms enable rapid prototyping in research settings requiring non-crystalline borate matrices.
- Amorphous:Disordered atomic structures suit specialized coating applications where isotropic properties outweigh optical precision requirements.
Single Crystalline handles the majority of throughput; Nonlinear Optics applications are expanding most quickly on specification intensity.
Application:
Cost stratification separates defense-cleared contracts from commercial-scale procurement, with security-cleared production lines carrying 40-60% overhead premiums.
- Lasers:Diode-pumped solid-state and ultrafast system builds anchor volume demand through frequency conversion and Q-switching functions. Pentagon directed-energy programs are accelerating nonlinear optical component orders for laser weapon demonstrators, pulling high-damage-threshold crystal requirements.
- Nonlinear Optics:Quantum photonics researchers specify custom aperture geometries for entangled photon generation, establishing an emerging specification tier with premium pricing power. UV-C laser disinfection specifications for municipal water treatment are opening new volume demand for 266 nm generation optics.
- Optics:Conventional beam manipulation and polarization control applications serve established industrial laser markets.
- Chemical Catalysts:Borate acidity and thermal stability support heterogeneous catalysis in specialty chemical synthesis.
Lasers handles the majority of throughput; Nonlinear Optics is climbing the fastest on research funding intensity.
End User:
Customer concentration in defense photonics creates qualification bottlenecks, with ITAR compliance timelines stretching 18-24 months for crystal growth engineers.
- Aerospace:Directed-energy weapons procurement and satellite-based laser communication systems specify radiation-hardened crystalline grades. US defense contractors are disintermediating traditional distributors to establish direct technical relationships with qualified growth houses.
- Electronics:Semiconductor lithography and inspection equipment manufacturers drive demand for sub-nanometer surface quality specifications.
- Photonics:Telecom and datacom module builders represent a contracting segment as lithium niobate-on-insulator wafers displace bulk borate crystals in electro-optic modulator applications.
- Research Institutions:National laboratories and university consortia purchase custom geometries for fundamental quantum optics investigations.
Aerospace handles the majority of throughput; Research Institutions is gaining share fastest on quantum technology investment.
Form:
Supply concentration in Fujian and Shandong provinces creates single-point-of-failure risk for crystal feedstock, elevating strategic importance of alternative polishing investments.
- Powder:Finely milled borate serves ceramic precursor and coating feedstock applications where particle size distribution controls sintering behavior.
- Granules:Intermediate sizing supports melt-casting operations and bulk optical component fabrication.
- Flakes:Thin crystalline plates enable rapid prototyping and specialized thermal management substrates.
- Crystals:Finished optical components require ion-beam sputtering specialists capable of depositing anti-reflective stacks on hygroscopic surfaces, with technician scarcity inflating finished component costs.
Crystals handles the majority of throughput; Powder is expanding most quickly on coating application diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in borate feedstock logistics, while the Rhine-Main-Danube corridor connects German precision optics clusters to continental European defense contractors. These infrastructure assets shape procurement geography across the barium borate value chain.
United States
Pentagon directed-energy programs drive classified crystal procurement through ITAR-cleared channels. The Department of Defense accelerates vendor qualification for high-damage-threshold optical components. Albuquerque's directed-energy research corridor hosts prime contractors embedding engineers at qualified growth facilities.
Germany
Jena-Munich precision optics clusters anchor European demand for phase-matched femtosecond laser crystals. REACH substance restrictions and RoHS trace-heavy-metal certification constrain import pathways. Thuringia's laser technology valley concentrates system integrators specifying exacting birefringence tolerances.
China
Fujian and Shandong provinces concentrate flux-growth capacity for beta-barium borate production. MEE environmental assessments and dual carbon goals tighten effluent discharge standards from crystal growth facilities. Xiamen's photonics industrial park consolidates domestic polishing and coating operations.
Japan
Semiconductor lithography equipment manufacturers specify sub-nanometer surface quality for frequency conversion optics. METI industrial standards govern optical material purity thresholds for telecom applications. Kyushu's precision manufacturing belt hosts electro-optic modulator fabricators.
India
PLI scheme incentives attract photonics component investments to offset Chinese supply concentration. DGFT import licensing frameworks govern strategic material procurement for defense applications. Bengaluru's semiconductor ecosystem incubates crystal polishing ventures serving research institutions.
Barium Borate Market Competitive Landscape
Listed leaders compete with private specialists across certification-tier segmentation, creating a bifurcated supply structure. Security-cleared production lines carry substantial overhead premiums compared to commercial-scale operations. Three archetypes dominate: defense-cleared crystal growth houses, cost-competitive Baltic-region polishers, and diversified chemical conglomerates with optical material divisions. Capacity expansion and strategic technology licensing represent the primary competitive vectors as vendors navigate export control fragmentation.
Within the defense-cleared tier, CASTECH Inc. and Inrad Optics exemplify specialized positioning around high-damage-threshold specifications. Among European-based fabricators, EKSMA Optics and Raicol Crystals occupy positions reflecting geographic manufacturing advantages. Merck KGaA represents diversified chemical conglomerate participation through legacy optical materials portfolios.
| Leading Market Players |
|---|
| CASTECH Inc. |
| EKSMA Optics |
| Inrad Optics |
| Raicol Crystals |
| American Elements |
| Altechna |
| Cristal Laser |
| Newlight Photonics |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
REACH substance restrictions and RoHS trace-heavy-metal certification gate both supplier qualification and price differentiation simultaneously, with ECHA-registered vendors commanding substantial premiums over uncertified competitors while European laser system integrators reject non-compliant material entirely.
Pricing Analysis
Volume-discount tiering separates defense-cleared production lines carrying 40-60% overhead premiums from commercial-scale operations serving cost-sensitive optical isolator applications. Pricing stratifies across ITAR-certified, REACH-registered, and industrial-grade tiers, with certification level and quality grade as primary differentiation drivers. Cost compression in flux-grown crystal production is intensifying because Chinese mining quota adjustments swing barium carbonate feedstock costs. Research institutions and municipal water treatment procurement show highest price sensitivity, while Pentagon directed-energy programs demonstrate lowest.
Supply Chain Analysis
China and Germany anchor beta-barium borate supply, with Fujian and Shandong provinces concentrating flux-growth capacity and Jena-Munich clusters dominating precision optics integration. The supply chain draws from barium carbonate ore, boric oxide, and specialized ion-beam sputtering equipment as critical inputs. Single-source vulnerability concentrates in Chinese crystal growth facilities, creating chokepoint risk for global feedstock availability. Distribution runs through security-cleared channels for defense contractors and ECHA-registered distributors for European commercial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lithium niobate-on-insulator wafers threaten bulk borate displacement in telecom electro-optic modulators, forcing incumbents to defend substitution-prone positions while capturing premium niches resistant to material switching.
For Market Incumbents: Fortify ITAR-cleared production lines against lithium niobate substitution by embedding engineers at prime defense contractor facilities and deepening backward integration into barium carbonate refining to offset Chinese quota volatility. Prioritize quantum photonics research partnerships for custom aperture geometries with premium pricing power. For New Entrants and Emerging Players: Differentiate on India's PLI scheme incentives for semiconductor and photonics manufacturing, establishing crystal polishing ventures in Bengaluru to bypass Chinese supply concentration. Target UV-C laser disinfection specifications for municipal water treatment as the most penetrable volume segment, leveraging coating application diversification as the primary go-to-market angle. For Investors and Strategic Acquirers: Evolving export control classifications for nonlinear optical materials reshape the acquisition landscape, concentrating viable targets among security-cleared growth houses with established defense photonics relationships. Long-term viability hinges on dual-use technology designation durability and quantum technology investment trajectories. Monitor ITAR compliance timeline compression for crystal growth engineers as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| ITAR Certification Investment | Unlocks Pentagon directed-energy procurement channels with 18-24 month security clearance processing. |
| Backward Integration into Feedstock | Mitigates barium carbonate price volatility from Chinese mining quota adjustments. |
| Quantum Photonics Partnership | Captures premium pricing for custom aperture geometries in entangled photon generation research. |
| India PLI Scheme Utilization | Offsets Fujian-Shandong supply concentration through Bengaluru polishing and coating investments. |
| ECHA Registration Completion | Enables European procurement access as REACH substance restrictions tighten import pathways. |
Research Methodology
A spread of perspectives from crystal growth engineers, defense procurement officers, laser system integrators, and optical coating technicians converged on the working assumptions underlying this analysis. Primary fieldwork combined with secondary validation from customs/trade data, SEC 10-K filings of diversified chemical conglomerates, and MEE environmental assessment disclosures. Bottom-up crystal production estimates and top-down defense spending trajectories were triangulated against REACH registration databases.
Segmentation dimensions modeled include crystalline grade tier, application vertical, end-user industry, and regional regulatory cluster across the projection horizon. CAGRs were derived from demand elasticity analysis for femtosecond laser proliferation and directed-energy weapons procurement. Forecast inputs incorporated flux-growth capacity utilization rates and lithium niobate substitution coefficients in telecom applications.
The analysis sits within stated boundaries; outcomes outside sustained quantum technology investment intensity or abrupt dual-use technology reclassification would require recalibration. Forecasts reflect documented assumptions regarding MEE environmental assessment stringency and Pentagon procurement acceleration. Recalibration cycles align with material shifts in export control classifications and feedstock quota adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Colloidal Silica Market
Specialty Materials
Solar Control Films Market
Specialty Materials
Fumed Silica Market
Specialty Materials
Global Montan Wax Market
Specialty Materials
Global Beeswax Market
Specialty Materials
Methyl Silicone Market
Specialty Materials
Edge Banding Materials Market
Specialty Materials
South America Polyether Ether Ketone (Peek) Market
Specialty Materials
Specialty Silica Market
Specialty Materials
Activated Carbon Bags Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Ballistic Protection Materials Market
Specialty Materials
Polyetherimide (PEI) Market
Specialty Materials
Acrylic Fine Particle Market
Specialty Materials
Special Graphite Market
Specialty Materials
Global Flexible Substrates Market