
 Europe Warm Edge Spacer Market | 2026-2036
Europe Warm Edge Spacer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Warm Edge Spacer Market Analysis
Market Context
Modular spacer-bar bundling with gas-filled glazing units is rebalancing how fenestration contractors specify warm edge systems across European projects. HELIMA GmbH leverages its German manufacturing base to sustain supply continuity for thermal break spacer profiles serving Central European window fabricators. Ensinger anchors demand for high-performance polyamide spacer compounds through compound expertise and tight quality specifications. Thermoseal Group competes on channel breadth, controlling distribution reach across UK and Irish glazing supply chains.
Technical Definition and Segment Structure
Europe warm edge spacer refers to a thermally optimized linear profile inserted between panes in insulating glass units to minimize conductive heat loss at the glass perimeter, typically fabricated from stainless steel, polyamide composites, or coated aluminum with thermal conductivity below 0.2 W/mK. The primary commercial purpose is to reduce linear thermal transmittance (psi-value) at the glazing edge, enabling window systems to meet stricter U-value thresholds under the Energy Performance of Buildings Directive. Stainless steel spacer configurations currently occupy the premium tier of product type segmentation, while polyamide variants are gaining traction in residential applications where cost-performance balance matters most. Thermal break technology leads the technology segmentation as the default specification for mid-to-high performance facades, with vacuum insulated spacers representing a narrower but higher-margin niche concentrated in passive house-certified projects.
Regulatory Frame and Outlook
The EU Green Deal and F-Gas Regulation are tightening embodied energy and thermal performance requirements for building components, directly elevating warm edge spacer specification rates in new construction and deep renovation. ECHA REACH compliance and CE marking obligations under the Construction Products Regulation shape material selection, testing protocols, and market access for spacer manufacturers distributing across member states. Stakeholders should monitor how national transposition of the Energy Performance of Buildings Directive recalibrates minimum psi-value thresholds, as this will determine whether low-conductivity adhesive-based spacers displace conventional thermal break designs in mass-market residential glazing.
Market Dynamics
Renovation waves across Germany, France, and the Netherlands are compressing specification timelines for thermally efficient glazing systems, forcing spacer manufacturers to align production cycles with national retrofit program procurement calendars.
Growth Catalysts
- EU Green Deal implementation:National building codes are tightening U-value thresholds for window replacements, mandating warm edge spacers in publicly funded renovation projects across member states.
- Deep renovation subsidies:Germany's federal KfW funding programs and France's MaPrimeRénov' scheme are covering incremental costs for high-performance glazing in residential retrofits.
- F-Gas Regulation phase-down:The restriction on high-global-warming-potential insulating gases is elevating demand for gas-tight spacer designs that maintain thermal performance with alternative fills.
Market Restraints
- Stainless steel price volatility:Raw material fluctuations for premium spacer substrates are compressing margins on high-performance product lines.
- Supply concentration in Central Europe:German and Austrian compounders control polyamide resin supply for thermal break spacers, creating geographic dependency risk.
- CE marking complexity:Divergent national interpretations of Construction Products Regulation testing protocols are extending time-to-market for new spacer formulations.
Strategic Opportunities
- Eastern European retrofit lag:Poland and Romania remain underpenetrated for warm edge specification, offering first-mover positioning as EU cohesion funds flow to building efficiency.
- Passive house certification convergence:The alignment of PHI and PHIUS standards is creating cross-border demand for ultra-low psi-value spacer systems.
- Direct-to-fabricator digital channels:Online specification tools are bypassing traditional distribution layers, enabling spacer producers to capture margin from mid-sized window manufacturers.
Industry Challenges
- Thermal simulation expertise shortage:Fenestration engineers capable of psi-value calculation and whole-window U-value optimization are in short supply across fabricator networks.
- Dual certification burden:Spacer manufacturers must maintain separate test data packages for CE marking and national passive house institute approvals, duplicating validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Warm Edge Spacer Market |
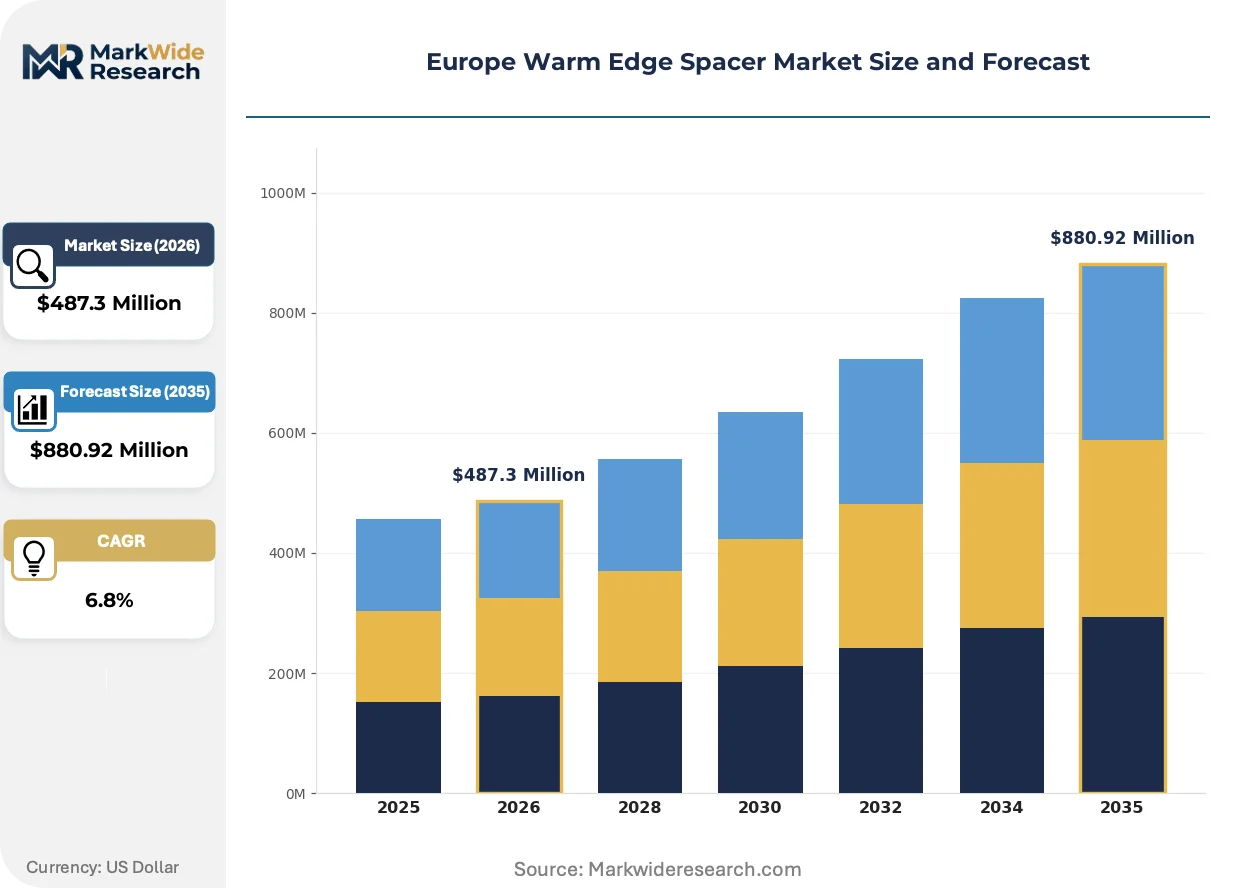
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Stainless Steel, Polyamide, Others Application: Residential, Commercial, Industrial, Decorative Technology: Thermal Break, Vacuum Insulated, Low Conductivity, Adhesive End User: Manufacturers, Contractors, Architects, Homeowners |
| Companies Covered | Alu Pro Srl, HELIMA GmbH, Ensinger, Thermoseal Group, Quanex Building Products, SWISSPACER, Fenzi Group, Allmetal, Technoform, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Warm Edge Spacer Market Emerging Trajectories
Material science advances and regulatory stringency are converging to redefine performance benchmarks for perimeter thermal breaks in insulating glass units.
Adhesive-based flexible spacers with integrated desiccant are rewriting competitive dynamics in residential glazing. Mid-sized window fabricators in the Netherlands and Belgium are adopting these systems to reduce inventory complexity and accelerate unit assembly. The technology is compressing lead times for custom glazing configurations while challenging rigid stainless steel and polyamide formats on cost.
The EU F-Gas Regulation's stepped phase-down of hydrofluorocarbon blowing agents is forcing reformulation of thermal break compounds and gas barrier adhesives. Manufacturers are accelerating validation of alternative spacer materials compatible with CO₂ and hydrocarbon insulating gas fills. Facade contractors in Germany and France report extended specification review cycles as project teams verify long-term seal integrity under new gas fill regimes.
Building owners are consolidating glazing procurement across multi-site portfolios, shifting specification authority from local installers to centralized technical teams. National housing associations in the UK and social housing providers in France now mandate warm edge compliance in standard technical specifications, removing discretion from project-level decision-makers. This concentration is compressing price negotiation leverage for smaller regional window fabricators.
Europe Warm Edge Spacer Market Segmentation
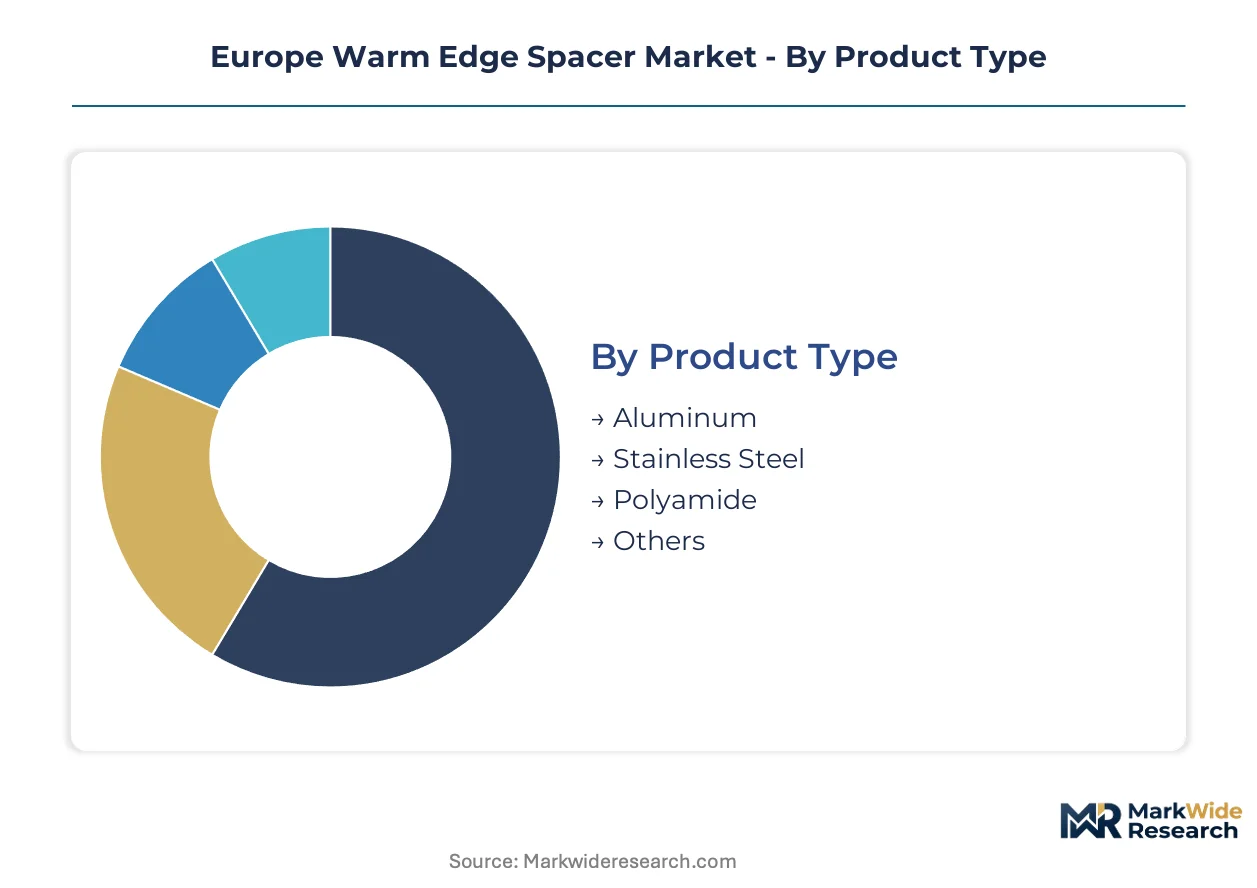
Warm edge spacer specification varies sharply by substrate chemistry, building application, and thermal performance tier. Procurement patterns diverge across these axes as fabricators balance cost, psi-value targets, and assembly automation compatibility.
Product Type:
Material conductivity and corrosion resistance define competitive positioning across substrate categories.
- Stainless Steel:Austenitic grades with thin-wall profiles achieve psi-values below 0.04 W/mK while maintaining structural rigidity for automated bending. German facade contractors specify these for high-rise commercial projects where thermal bridge minimization outweighs material cost premiums.
- Polyamide:Glass-reinforced polyamide 6.6 compounds with thermal conductivity near 0.20 W/mK dominate residential retrofits in France and the Netherlands. The segment gains from injection molding scalability and compatibility with roll-forming equipment at mid-sized window fabricators.
- Aluminum:Coated aluminum spacers with thermal break inserts retain cost advantage in economy-tier glazing for social housing programs.
- Others:Hybrid composite profiles and bio-based polymer formulations serve niche passive house-certified projects requiring embodied carbon reduction.
Mature deployment sits with aluminum thermal break configurations. Newer deployment is concentrated in polyamide and stainless steel systems as psi-value thresholds tighten.
Application:
Building typology dictates performance tier, volume scale, and specification authority.
- Residential:Single and multi-family retrofits across Germany's KfW-funded programs drive volume demand for mid-range warm edge systems. Housing associations in France now mandate warm edge compliance in standard technical specifications, removing project-level discretion.
- Commercial:Office and retail facades in the Netherlands and Belgium prioritize ultra-low psi-values for BREEAM and WELL certification compliance. Centralized procurement teams at institutional investors control specification authority.
- Industrial:Manufacturing facilities and logistics warehouses specify durable spacer systems for large-format glazing with minimal maintenance access.
- Decorative:Heritage restoration and architectural feature glazing employ slim-profile warm edge solutions where sightline aesthetics constrain spacer width.
Volume concentrates in residential retrofits. Margin expansion is steepest in commercial facade applications.
Technology:
Thermal performance mechanism determines manufacturing complexity and gas fill compatibility.
- Thermal Break:Discrete metal profiles with polyamide inserts remain the default specification for mid-performance facades. The technology dominates current production capacity at Central European spacer manufacturers.
- Vacuum Insulated:Micro-porous core materials with edge seals achieve psi-values approaching zero for passive house-certified projects. German and Austrian component suppliers control validation data for PHI approval.
- Low Conductivity:Advanced polymer formulations and aerogel-filled profiles bridge performance between thermal break and vacuum systems.
- Adhesive:Butyl-based flexible spacers with integrated desiccant are gaining share in residential glazing for inventory simplification and accelerated IG unit assembly.
Specification authority rests with thermal break designs. Technology transition is accelerating toward adhesive and vacuum insulated formats.
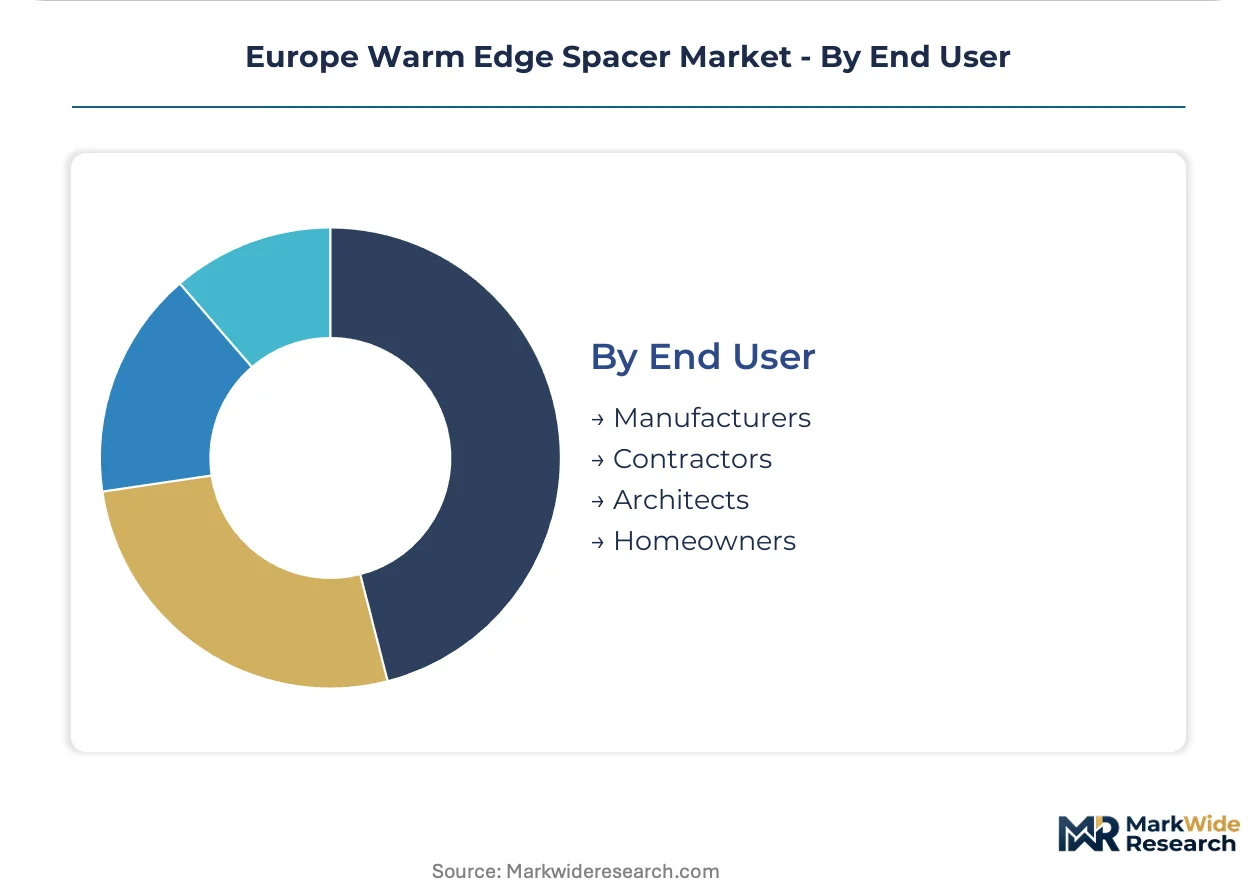
End User:
Decision-making proximity to installation and technical sophistication shape procurement behavior.
- Manufacturers:Window and IG unit fabricators in Germany, France, and the Netherlands source spacers through annual framework agreements with volume commitments. Technical teams evaluate psi-value test data and CE marking compliance.
- Contractors:Fenestration installation firms in Belgium and Austria increasingly specify warm edge upgrades as part of deep renovation packages. Margin capture depends on client education and thermal imaging documentation.
- Architects:Facade designers on commercial projects in the UK and Ireland mandate warm edge compliance in performance specifications, constraining contractor substitution.
- Homeowners:Individual property owners in subsidized retrofit programs select warm edge options through installer recommendations rather than independent technical evaluation.
Procurement consolidation is strongest among manufacturers. Direct homeowner specification remains limited to high-net-worth passive house self-builds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of warm edge spacer compounds concentrates in German and Austrian industrial corridors, while consumption spreads across Western European renovation markets. This geographic split creates supply chain dependencies that manufacturers navigate through regional distribution hubs.
Germany
KfW-funded residential retrofits and commercial facade replacements drive sustained procurement of thermal break spacer systems. The federal government's Building Energy Act tightens U-value thresholds for window replacements in existing stock. Manufacturing clusters in Bavaria and North Rhine-Westphalia host polyamide compounders and precision metal fabricators supplying Central European window fabricators.
France
MaPrimeRénov' subsidies accelerate warm edge specification in social housing and private residential renovations nationwide. The RE2020 environmental regulation mandates embodied carbon calculations for new construction, elevating low-conductivity spacer formats. Industrial concentration around Lyon and the Île-de-France region supports glazing supply chains serving the national renovation wave.
Netherlands
Stringent building code requirements for nearly zero-energy buildings push specification toward ultra-low psi-value spacer configurations. The national Climate Agreement targets deep renovation of existing housing stock by 2050. The Randstad conurbation anchors demand from institutional investors consolidating multi-site glazing procurement across residential portfolios.
United Kingdom
Social housing providers and national housing associations now mandate warm edge compliance in standard technical specifications. The Future Homes Standard phases in stricter thermal performance requirements for new residential construction. Distribution networks concentrated in the Midlands and Southeast serve retrofit contractors and IG unit fabricators.
Poland
EU cohesion fund inflows for building efficiency create first-mover opportunities as warm edge penetration remains below Western European levels. The national KPO recovery plan allocates resources to residential energy renovation programs. Industrial glazing clusters in the Silesian and Greater Poland voivodeships supply window systems for domestic and export markets.
Europe Warm Edge Spacer Market Vendor Landscape
The competitive structure tilts toward compound specialists and metal fabricators with captive distribution networks. German and Austrian manufacturers anchor supply for polyamide-based thermal break systems, while UK and Irish distributors control channel access for mid-market residential applications. Three archetypes dominate: integrated material compounders, precision metal processors, and regional distribution specialists. Capacity expansion and direct-to-fabricator digital specification tools represent the dominant competitive moves reshaping channel economics.
Among German-based manufacturers, HELIMA GmbH and Ensinger occupy positions within the compound specialist archetype, leveraging proximity to Central European window fabricators. Thermoseal Group exemplifies the distribution-focused model, controlling supply chain reach across UK and Irish glazing markets. These three companies represent contrasting strategic approaches to market access—material expertise versus channel control—without overlapping territorial focus.
| Leading Market Players |
|---|
| Alu Pro Srl |
| HELIMA GmbH |
| Ensinger |
| Thermoseal Group |
| Quanex Building Products |
| SWISSPACER |
| Fenzi Group |
| Allmetal |
| Technoform |
| Others |
Supply Flow & Price Mechanics
Captive integration of polyamide compounding with precision metal fabrication anchors supply positioning and pricing power for German and Austrian manufacturers serving the EU Green Deal compliance tier. This vertical control over thermal break formulations lets compounders defend premium positioning against stainless steel alternatives while KfW-funded procurement compresses mid-market price bands.
Pricing Analysis
Margin tightening in polyamide residential tiers reflects KfW and MaPrimeRénov' subsidy-driven volume procurement. Three-tier pricing structure across PHI-certified, CE-marked, and economy aluminum thermal break levels separates specification authority. Cost compression accelerates in standard residential segments as housing associations consolidate framework agreements. Social housing providers exhibit highest price sensitivity; passive house-certified self-builds show lowest.
Supply Chain Analysis
CE marking and PHI certification gating restricts viable supply to German, Austrian, and Swiss compounders with validated test data packages. Polyamide 6.6 resin, stainless steel strip, and butyl adhesive sealants constitute critical input dependencies. Single-source vulnerability concentrates in Central European polyamide resin supply. Distribution runs through regional glazing supply houses and direct-to-fabricator digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Warm Edge Spacer Market functions as a cost-of-compliance arena where F-Gas Regulation phase-down and Energy Performance of Buildings Directive transposition erect regulatory moats favoring validated incumbents over unqualified entrants.
For Market Incumbents: To counter adhesive-based flexible spacer displacement in residential retrofits, secure backward integration into desiccant-integrated polymer formulations and accelerate PHI dual-certification for vacuum insulated formats. Channel control through annual framework agreements with Dutch and Belgian fabricators remains essential for volume defense. For New Entrants and Emerging Players: Direct-to-fabricator specification platforms offer the lowest-friction entry vector for Polish and Romanian retrofit markets where EU cohesion fund flows outpace local supply capacity. Target housing association procurement teams with psi-value calculation tools and thermal imaging documentation packages rather than competing on spacer unit cost. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to building envelope specialists seeking thermal break capabilities. Five-to-ten year viability hinges on F-Gas Regulation alignment and alternative gas fill validation. Monitor national EPBD transposition timelines as the inflection signal for low-conductivity adhesive spacer displacement rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyamide Compounding | Captive resin supply secures margin control against Austrian and German incumbent pricing power. |
| PHI Vacuum Insulated Spacer Validation | Passive house certification unlocks premium positioning in Netherlands and German deep renovation pipelines. |
| Direct-to-Fabricator Digital Specification Platform | Bypasses UK and Irish distribution layers where Thermoseal Group controls channel economics. |
| Alternative Gas Fill Compatibility Program | F-Gas Regulation compliance enables continued specification as CO₂ and hydrocarbon fills displace HFCs. |
| Eastern European Distribution Hub Establishment | First-mover positioning in Poland and Romania captures EU cohesion fund building efficiency allocations. |
Methodological Framework
Document review covered EU regulatory filings, national building code transpositions, and Construction Products Regulation test standards, complemented by interviews with fenestration procurement managers at German housing associations, technical directors at Dutch IG unit fabricators, and regulatory affairs leads at polyamide compounders. Secondary validation drew from ECHA REACH registrations, KfW program disbursement data, and EPBD national implementation reports. Bottom-up volume estimates from fabricator capacity and top-down expenditure flows from renovation subsidy programs were triangulated.
Segment-level value outputs across product type, application, technology, and end-user dimensions were generated through the projection horizon. CAGRs were derived from elasticity modeling against regulatory threshold changes and subsidy program scaling. Key inputs included psi-value adoption curves by building code tier, gas fill transition timelines under F-Gas Regulation phase-down schedules, and housing association procurement consolidation rates.
Inputs from regulatory agency guidance documents and national renovation program administrators were available through the study window; gaps in real-time fabricator inventory data and project-level specification decisions introduce uncertainty bands around near-term volume estimates. Forecasts reflect documented assumptions on EPBD transposition timing and cohesion fund disbursement velocity. A model refresh is warranted upon material change in F-Gas Regulation enforcement or national psi-value threshold recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
N-Methyl Pyrrolidone Market
Chemicals & Materials
Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market
Chemicals & Materials
Global Hydrogen Fluoride Market
Chemicals & Materials
Europe Super Hydrophobic Coatings Market
Chemicals & Materials
Global Molten Sulfur Market
Chemicals & Materials
Global Blowing Agent Market
Chemicals & Materials
PCR Polyolefins Market
Chemicals & Materials
Global Silicone Adhesives Market
Chemicals & Materials
Global Antimony Market
Chemicals & Materials
Global Calcium Formate Market
Chemicals & Materials
Lip Seals Market
Chemicals & Materials
North America Aluminium Powder Market
Chemicals & Materials
Mesitylene Market
Chemicals & Materials
Flurbiprofen Market
Chemicals & Materials
Lithium Foil Market
Chemicals & Materials
Cold Seal Adhesives Market