
 Global Montan Wax Market | 2026-2036
Global Montan Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Global Montan Wax Market Foresight
Technical service contracts for wax modification and custom esterification is rebalancing how suppliers capture value beyond commodity sales. ROMONTA GmbH leverages captive lignite sourcing in eastern Germany to sustain feedstock security across volatile energy markets. VÖLPKER Spezialprodukte GmbH anchors its position through pharmaceutical-grade certification paths that command premium positioning in European cosmetics channels. Clariant competes on dispersion technology leadership, extending its reach into water-based coating systems where wax emulsion performance determines formulation adoption.
Montan wax is a hard, high-melting fossil wax extracted from lignite through solvent refining, yielding a complex mixture of long-chain esters, free acids, and resins with melting points typically between 80°C and 88°C. Its primary commercial purpose centers on surface modification—imparting gloss, abrasion resistance, and anti-blocking properties to coatings, polishes, and thermoplastic compounds. Refined grades dominate value capture due to stringent color and acid-value specifications demanded by automotive polishes and printing ink formulations, while sulfonated wax variants occupy faster-growing niches in leather finishing and metalworking fluids where emulsification stability is critical. Fractionated wax segments concentrate margin pools in the United States and Germany, where specialty chemical houses supply tailored cuts for electrical insulation compounds.
REACH registration requirements enforced by ECHA mandate full substance characterization for montan wax imports into Europe, elevating compliance costs for unrefined feedstock traders while advantaging integrated refiners with in-house analytical capabilities. EPA Toxic Substances Control Act reporting in the United States imposes parallel disclosure burdens on processors handling lignite-derived streams, shaping where new capacity locates. China's GB standards for wax products administered by SAMR are converging toward international purity benchmarks, reducing arbitrage opportunities for lower-grade exports. Stakeholders must monitor regulatory divergence between these jurisdictions to determine whether centralized refining investments or distributed blending networks offer superior returns.
Market Dynamics
Automotive coating formulators are consolidating specification power around water-based dispersion performance, forcing montan wax suppliers to prove emulsion stability under tighter VOC ceilings rather than compete on commodity price alone.
Growth Catalysts
- REACH substance characterization mandates:ECHA registration requirements for montan wax imports into Europe favor integrated refiners with captive analytical labs, compressing trader margins and consolidating supply relationships.
- Water-based coating conversion:Formulators in Germany and China are replacing solvent-borne systems with wax emulsions that demand sulfonated montan grades for stability at high solids loading.
- Leather finishing chemical demand:Metalworking fluid compounders in India are specifying emulsifiable wax esters for synthetic coolant packages serving automotive stamping operations.
Market Restraints
- Lignite feedstock concentration:ROMONTA GmbH controls captive lignite deposits in eastern Germany, creating single-source dependency for European refined wax supply during energy market volatility.
- Petroleum wax substitution pressure:Paraffin and microcrystalline wax producers in the United States are targeting coating applications with lower-cost blends that sacrifice some hardness performance.
- EPA TSCA disclosure burdens:Processors handling lignite-derived streams in the United States face elevated compliance costs that deter new entrant investment in domestic refining capacity.
Strategic Opportunities
- India specialty chemical import substitution:Domestic formulators in Mumbai and Ahmedabad are seeking qualified local wax emulsion suppliers to reduce reliance on European sulfonated grade imports.
- Pharmaceutical-grade certification paths:European cosmetics channels are demanding USP-grade montan esters for lip care and dermatological applications, creating premium positioning for certified refiners.
- GB standards convergence in China:SAMR purity benchmarks are aligning with international specifications, enabling qualified exporters to capture share previously held by lower-grade regional suppliers.
Industry Challenges
- REACH analytical capability gaps:Smaller traders lack in-house substance characterization capacity to complete ECHA dossiers, forcing costly third-party outsourcing or market exit.
- Emulsion formulation integration complexity:Water-based coating houses require dedicated technical service to match wax dispersion rheology with proprietary resin systems, stretching supplier R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Montan Wax Market |
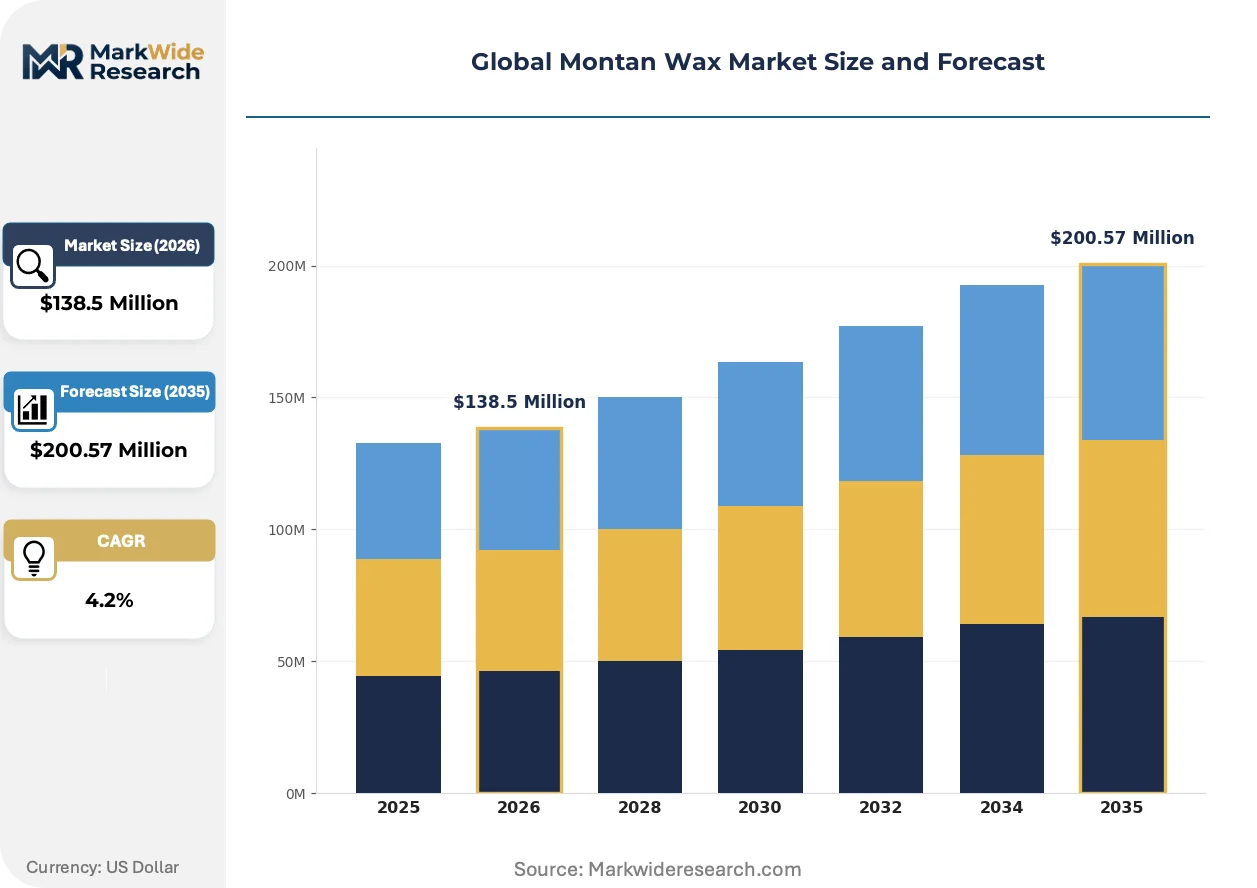
| Market Size in 2026 | $138.5 Million |
| Market Size in 2035 | $200.57 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined, Unrefined, Fractionated, Sulfonated Wax, Ester Wax Application: Candle Manufacturing, Polishes, Lubricants, Paints, Printing Inks, Adhesives End User Industry: Packaging, Automotive Aftermarket, Cosmetics, Textile Manufacturers, Electrical Insulation Packaging Type: Barrels, Bags, Drums, Blocks, Granules |
| Companies Covered | Yunphos, VÖLPKER Spezialprodukte GmbH, ROMONTA GmbH, ALTANA, Paramelt B.V., Clariant, Poth Hille, Mayur Dyes & Chemicals Corporation, Carmel Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Montan Wax Market Shifts & Advancements
Process intensification in wax refining and esterification chemistry is compressing batch cycle times while raising purity thresholds, enabling suppliers to serve just-in-time coating formulator demands without holding excessive finished goods inventory.
Supercritical CO2 extraction technology is absorbing residual bitumen and resin fractions from crude montan wax at lower temperatures than conventional solvent refining. German specialty chemical houses are adopting this method to produce odor-free grades for food-contact packaging applications. The process is absorbing market share from hexane-based refiners unable to meet tightening EPA emission thresholds.
China's GB standards administered by SAMR are converging toward REACH-equivalent purity specifications for wax imports, eliminating arbitrage windows for unrefined feedstock traders. Domestic processors in Shandong and Jiangsu provinces are investing in laboratory infrastructure to demonstrate compliance. This regulatory alignment is compressing price dispersion between import and domestic grades.
Coating formulators are consolidating purchase specifications around single-source technical service contracts rather than multi-vendor commodity sourcing. Automotive OEM direct coating operations in Germany and the United States are requiring dedicated wax modification support for water-based polish formulations. This buyer concentration is visible most acutely in Stuttgart and Detroit metropolitan supplier qualification processes.
Global Montan Wax Market Segmentation
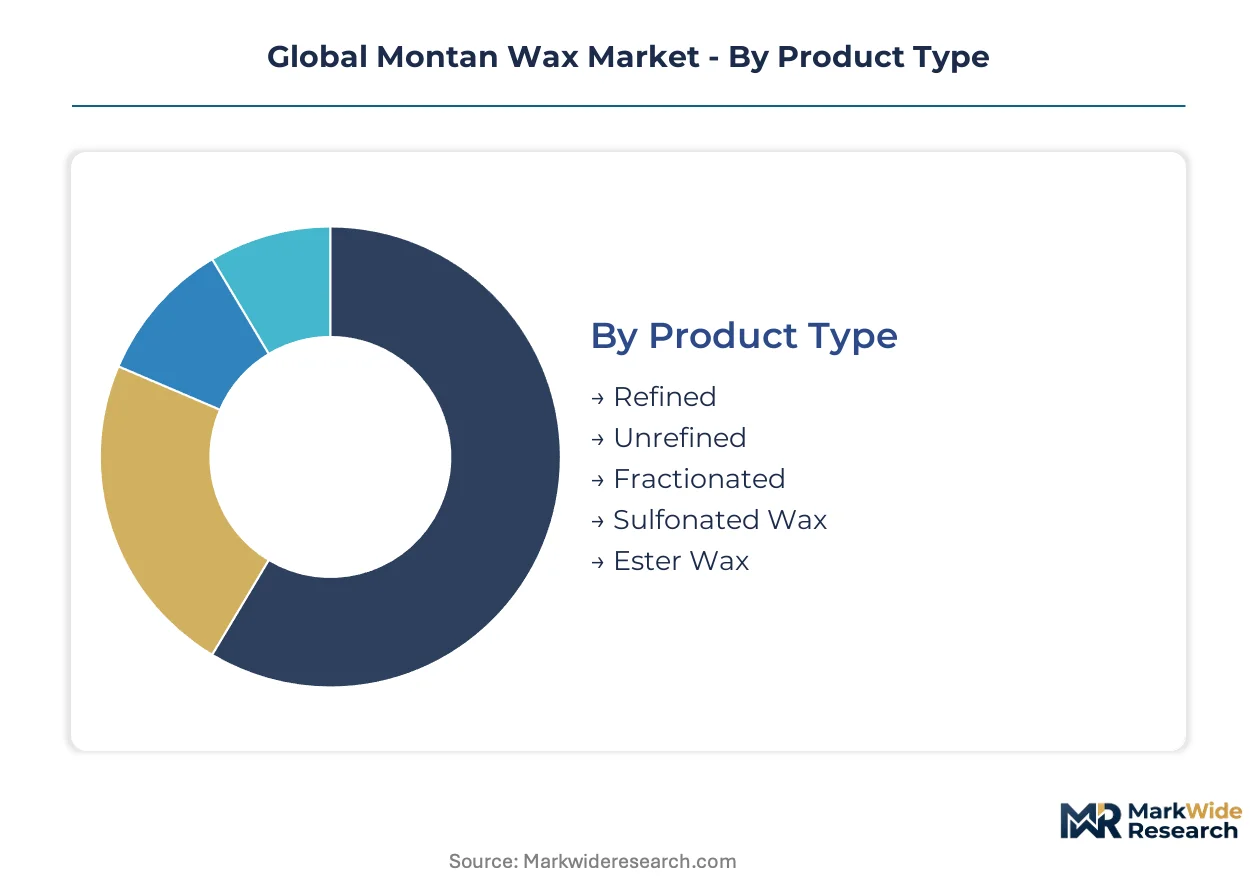
Montan wax segmentation reveals how value migrates toward specification-grade products as coating formulators consolidate around water-based dispersion performance. Supply concentration in refined grades and sulfonated variants shapes where margin pools concentrate across automotive, cosmetics, and packaging channels.
Product Type:
Supply concentration in eastern Germany and Shandong province determines which grades achieve scale economies in REACH-compliant refining.
- Refined:Solvent-processed grades meeting acid-value specifications below 15 mg KOH/g and color thresholds under 3 Gardner units. German automotive polish formulators in Stuttgart specify these grades for OEM coating operations where gloss retention and scratch resistance command premium positioning.
- Sulfonated Wax:Emulsifiable variants produced through sulfonation of crude montan fractions, yielding anionic surfactant properties critical for water-based leather finishing and metalworking fluid stability. Demand concentrates in Indian automotive stamping coolant packages and European waterborne coating conversions where VOC ceilings tighten.
- Unrefined:Crude lignite-extracted material with higher resin and bitumen content, serving lower-specification applications in emerging market candle manufacturing and industrial lubricant blending where color and odor tolerances permit.
- Fractionated:Distillation-separated cuts isolating specific ester chain lengths for electrical insulation compounders requiring precise melting point control in transformer and cable applications.
- Ester Wax:Chemically modified grades through alcohol esterification of montan acids, producing pharmaceutical-grade materials for European cosmetics channels demanding USP certification for lip care and dermatological formulations.
Today's leader: Refined grades. Tomorrow's challenger: Sulfonated wax variants.
Application:
Cost tier differentiation separates specification-driven automotive and cosmetics applications from commodity-oriented candle and adhesive uses.
- Polishes:Automotive aftermarket applications in Germany and the United States drive volume for high-gloss, abrasion-resistant formulations. Water-based dispersion requirements are compressing solvent-borne alternatives and favoring sulfonated grade suppliers with dedicated technical service capabilities.
- Printing Inks:Anti-blocking and rub resistance specifications in offset and gravure inks concentrate demand for refined montan grades with controlled particle size distribution. Chinese packaging converters in Guangdong province are consolidating purchases around single-source technical contracts.
- Candle Manufacturing:Lower-purity unrefined grades serve cost-sensitive producers in India and Southeast Asia where petroleum wax substitution pressure limits montan penetration.
- Lubricants:Metalworking and wire-drawing applications specify emulsifiable ester waxes for synthetic coolant packages, particularly in Indian automotive component manufacturing.
- Paints:Surface modification for gloss and durability in industrial coatings, with European formulators replacing solvent-borne systems with wax emulsion alternatives.
- Adhesives:Hot-melt and pressure-sensitive formulations utilizing montan wax for viscosity control and open-time adjustment in packaging and construction applications.
Specification power concentrates in polishes and printing inks; candle manufacturing faces steepest substitution pressure.
End User Industry:
Volume concentration in automotive aftermarket channels is displacing traditional packaging dominance as coating performance requirements tighten.
- Automotive Aftermarket:High-performance polishes and protective coatings for vehicle refinishing and maintenance. German OEM direct operations and US detailer supply chains specify refined grades with dedicated formulation support, creating technical service barriers for commodity suppliers.
- Cosmetics:Pharmaceutical-grade ester wax demand for lip care, creams, and dermatological applications. European channels require USP certification paths that only integrated refiners with captive analytical capabilities can satisfy.
- Packaging:Food-contact and general packaging coatings utilizing odor-free refined grades, with supercritical CO2 extraction technology gaining share from hexane-based refining for compliance with tightening EPA emission thresholds.
- Electrical Insulation:Fractionated wax cuts for cable filling compounds and transformer insulation, concentrated in German and US specialty chemical houses serving utility infrastructure.
- Textile Manufacturers:Sizing and finishing applications for yarn lubrication and fabric softening, primarily in Indian and Chinese textile clusters.
Automotive aftermarket anchors current volume. Cosmetics represents the steepest expansion trajectory for certified grades.
Packaging Type:
Customer type segmentation separates bulk industrial procurement from specialty chemical handling requirements.
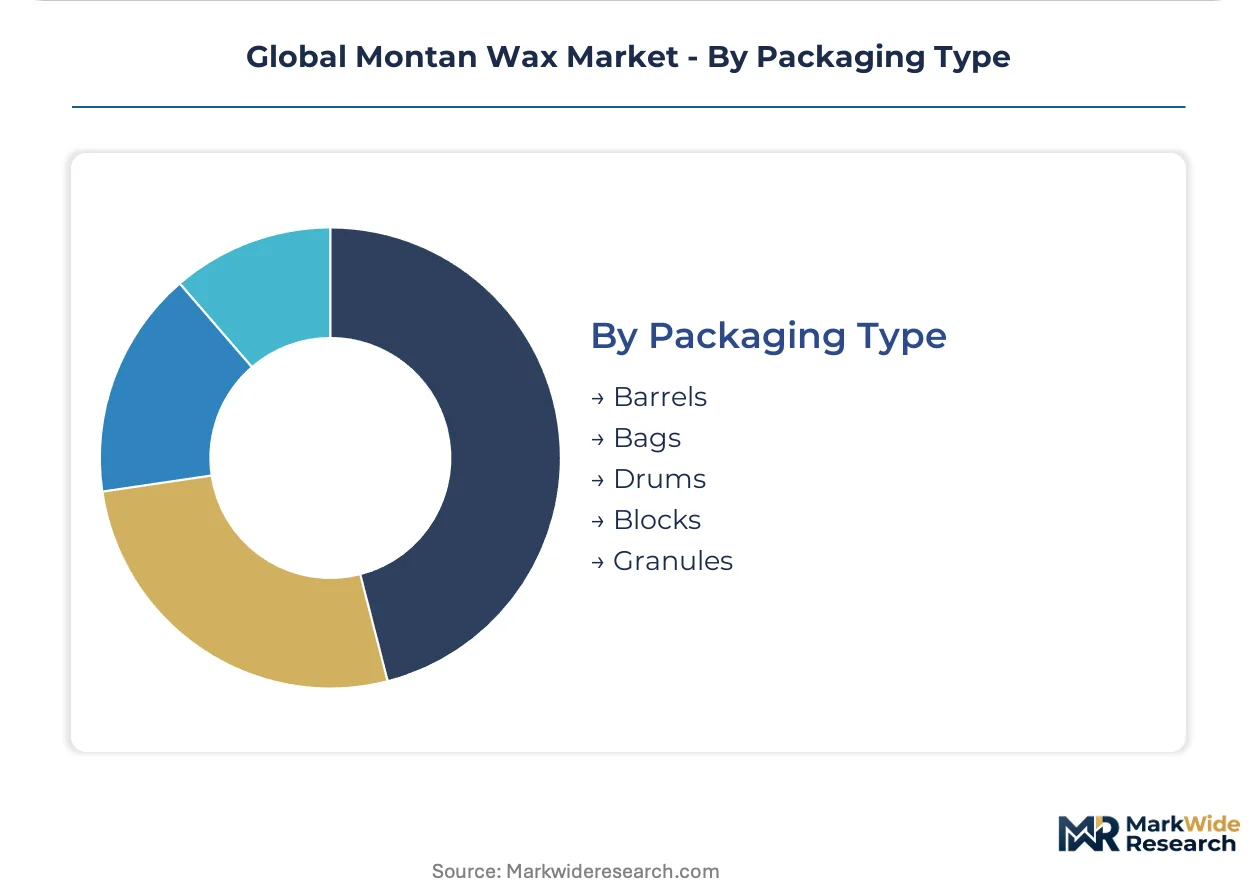
- Granules:Free-flowing form enabling automated dosing in coating and adhesive manufacturing, preferred by high-volume German and Chinese formulators with integrated compounding operations.
- Blocks:Standard industrial format for melting and blending operations across lubricant and polish manufacturers.
- Drums:Intermediate bulk packaging for specialty chemical distributors serving mid-tier coating houses and cosmetics compounders.
- Barrels:Large-volume containment for integrated refiners supplying captive downstream operations or major automotive polish producers.
- Bags:Powder or flake packaging for smaller-scale textile and adhesive formulators with manual handling processes.
Granules dominate automated manufacturing integration. Drums retain flexibility for specialty chemical distribution networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands captive lignite reserves and integrated refining infrastructure, while China scales domestic capacity to serve coating and packaging converters. India imports specialty grades for automotive and leather chemicals. The United States maintains fractionation expertise for electrical insulation. Regulatory divergence across these markets determines where value concentrates.
Germany
Automotive polish formulators in Stuttgart specify refined montan grades for OEM coating operations, while leather finishing houses in Ludwigshafen demand sulfonated variants. REACH substance characterization mandates enforced by ECHA compress trader margins and consolidate supply relationships around integrated refiners. ROMONTA GmbH leverages captive lignite deposits in eastern Saxony-Anhalt to sustain feedstock security across volatile energy markets.
China
Packaging converters in Guangdong province consolidate purchases around single-source technical contracts for printing ink applications. GB standards administered by SAMR are converging toward REACH-equivalent purity specifications, eliminating arbitrage windows for unrefined feedstock traders. Domestic processors in Shandong and Jiangsu provinces invest in laboratory infrastructure to demonstrate compliance with tightening benchmarks.
United States
Fractionated wax segments concentrate margin pools where specialty chemical houses supply tailored cuts for electrical insulation compounds serving utility infrastructure. EPA Toxic Substances Control Act reporting imposes disclosure burdens on processors handling lignite-derived streams, deterring new entrant investment in domestic refining capacity. Automotive OEM direct coating operations in Detroit metropolitan areas require dedicated wax modification support for water-based polish formulations.
India
Metalworking fluid compounders in Mumbai and Ahmedabad specify emulsifiable wax esters for synthetic coolant packages serving automotive stamping operations. Domestic formulators seek qualified local wax emulsion suppliers to reduce reliance on European sulfonated grade imports. The country's national chemical regulator evaluates alignment with international purity benchmarks for specialty wax imports.
Global Montan Wax Market Competitive Landscape
Top-tier vendors anchor integrated refining with captive feedstock, while mid-scale specialists compete on technical service contracts for custom esterification. The vendor base stratifies across three tiers: lignite-integrated refiners with analytical capabilities, specialty chemical houses with pharmaceutical-grade certification paths, and regional traders facing REACH compliance compression. Two dominant competitive moves are reshaping positioning: backward integration into captive lignite sourcing and dedicated technical service teams for water-based emulsion formulation support.
Among Germany-based integrated refiners, ROMONTA GmbH and VÖLPKER Spezialprodukte GmbH exemplify divergent archetypes. ROMONTA occupies a position anchored by captive lignite deposits in eastern Germany, representing the feedstock-security vector. VÖLPKER sits within the pharmaceutical-grade certification tier, exemplifying premium positioning through analytical capability investment. Swiss-based Clariant anchors the dispersion technology leadership archetype, extending reach into water-based coating systems where emulsion performance determines formulation adoption.
| Leading Market Players |
|---|
| Yunphos |
| VÖLPKER Spezialprodukte GmbH |
| ROMONTA GmbH |
| ALTANA |
| Paramelt B.V. |
| Clariant |
| Poth Hille |
| Mayur Dyes & Chemicals Corporation |
| Carmel Industries |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between pharmaceutical-grade ester wax and commodity unrefined material manifests in both pricing power and supply chain configuration. REACH-compliant refiners in Germany command premium positioning through captive analytical capabilities, while traders of lower-purity grades face margin compression from regulatory compliance costs and petroleum wax substitution.
Pricing Analysis
Capacity additions in Shandong province are reshaping price floors for standard refined grades, forcing legacy European suppliers to differentiate through technical service bundling. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, with USP-grade ester wax capturing the widest spreads. Cost compression in unrefined segments is intensifying because Indian candle manufacturers substitute petroleum wax blends. Price sensitivity concentrates in packaging converters, while automotive OEM polish formulators exhibit lowest elasticity due to performance specifications.
Supply Chain Analysis
Single-source vulnerability sits with ROMONTA GmbH's captive lignite deposits in eastern Saxony-Anhalt, where energy market volatility threatens feedstock security for European refined wax supply. Geographic concentration centers on Germany, China, and the United States, with raw material dependencies drawing from lignite extraction, solvent refining infrastructure, and sulfonation capacity. Tariff exposure on specialty grade imports into India creates supply chain risk for Mumbai metalworking fluid compounders. Distribution runs through integrated refiners serving direct automotive OEM relationships and specialty chemical distributors supplying mid-tier coating houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through supercritical CO2 extraction adoption, which reduces solvent costs and unlocks food-contact packaging premiums previously inaccessible to hexane-based refiners.
For Market Incumbents: Lock in feedstock security through backward integration into captive lignite deposits or long-term offtake agreements with eastern German mines. Defend against petroleum wax substitution by embedding technical service teams within Stuttgart and Detroit automotive OEM coating operations, converting specification power into switching costs. For New Entrants and Emerging Players: Enter via pharmaceutical-grade certification paths for European cosmetics channels, where USP-grade ester wax supply scarcity creates penetrable white space. Target Indian domestic wax emulsion production for automotive stamping coolant packages, leveraging import substitution demand in Mumbai and Ahmedabad. Go-to-market through toll manufacturing partnerships with Shandong processors seeking REACH-equivalent analytical capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH analytical capability gaps force smaller traders toward exit or acquisition by integrated refiners. Long-term viability favors specialty chemical houses with dispersion technology leadership in water-based coating systems. Acquisition target archetype: mid-scale German refiners with captive lignite access and underutilized sulfonation capacity. Signal to watch: ECHA enforcement intensity on substance characterization dossiers as indicator of compliance-cost-driven consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lignite Sourcing | ROMONTA GmbH's captive deposits in Saxony-Anhalt insulate margin from energy volatility. |
| Supercritical CO2 Extraction Adoption | German specialty houses capture food-contact packaging share from hexane-based competitors. |
| Pharmaceutical-Grade Certification Investment | USP-grade ester wax unlocks premium positioning in European cosmetics channels. |
| Technical Service Team Expansion | Dedicated formulation support binds Stuttgart automotive OEMs through water-based polish conversion. |
| Joint Venture in Indian Emulsion Production | Domestic sulfonated grade manufacturing reduces European import dependency for Mumbai compounders. |
Research Methodology
Bottom-up coating formulator demand modeling reconciled against top-down lignite extraction and refining capacity tracking forms the analytical core. Primary interviews with plant managers at German integrated refiners, procurement leads at Stuttgart automotive OEM coating operations, technical R&D directors at Indian metalworking fluid compounders, and distribution channel partners in Shandong province combined with secondary validation from customs/trade data, Cefic chemical industry reports, SEC 10-K filings of specialty chemical houses, and SAMR GB standards documentation.
Historical trendline analysis of refined grade, sulfonated wax, and ester wax volume trajectories established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry concentration, packaging format preference, and regional production hub structure. CAGRs were derived through regression analysis against automotive aftermarket polish consumption and water-based coating conversion rates, with inputs from EPA TSCA disclosure burden indices and ECHA registration timelines.
Inputs from primary stakeholder interviews were available through the study window; gaps in real-time Indian domestic emulsion production capacity data introduce uncertainty bands around import substitution velocity assumptions. Forecasts reflect documented assumptions on regulatory convergence timelines and coating formulator consolidation behavior. Specific risk factors that could revise projections include REACH enforcement intensity escalation, petroleum wax blend performance improvements, and energy market volatility affecting lignite extraction economics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
North America Solar Control Window Films Market
Specialty Materials
Super Engineering Plastics Market
Specialty Materials
ePTFE Electronic Film Market
Specialty Materials
Retro Reflective Materials Market
Specialty Materials
Jesmonite Market
Specialty Materials
Asia-Pacific Green Sic Market
Specialty Materials
EVA Interlayer for Photovoltaic Market
Specialty Materials
Spermaceti Wax Market
Specialty Materials
Conductive Plastics Market
Specialty Materials
Polyphenylsulfone Market
Specialty Materials
Glass Ionomer Cement Market
Specialty Materials
Teschemacherite Market
Specialty Materials
Cadmium Sulfide Market
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
Electrode Paste Market
Specialty Materials
Semiconductor O-Rings Market