
 Battery Separator Films Market | 2026-2036
Battery Separator Films Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Separator Films Market Outlook
Project finance tied to integrated battery gigafactories is rewriting competitive entry barriers for separator suppliers. Asahi Kasei leverages captive polymer supply chains to sustain margin stability across Asian production nodes. SK Innovation anchors its position through backward integration into petrochemical feedstocks. Toray Industries competes via bi-axial orientation expertise accumulated in membrane divisions.
Battery separator films are microporous membranes, typically 10-40 µm thick, manufactured from polyolefin resins through dry stretching or wet extrusion processes to enable ion transport while preventing internal short circuits. Polyethylene dominates high-energy-density automotive cells due to superior shutdown behavior at elevated temperatures. Composite and ceramic-coated variants represent the fastest-growing product category as OEMs demand thermal runaway resistance beyond baseline polypropylene specifications. The thickness segment below 20 µm captures premium pricing in consumer electronics where volumetric energy density governs design.
FDA oversight of manufacturing equipment and EPA emissions rules affect US-based extrusion lines, while REACH compliance in Europe restricts certain plasticizers and additives in separator formulations. China's MIIT enforces GB standards for battery safety that cascade into separator performance requirements. Korea's MFDS coordinates with METI-aligned Japanese standards to harmonize cross-border qualification protocols. Stakeholders must track how solid-state battery timelines alter separator relevance versus incremental liquid-electrolyte improvements.
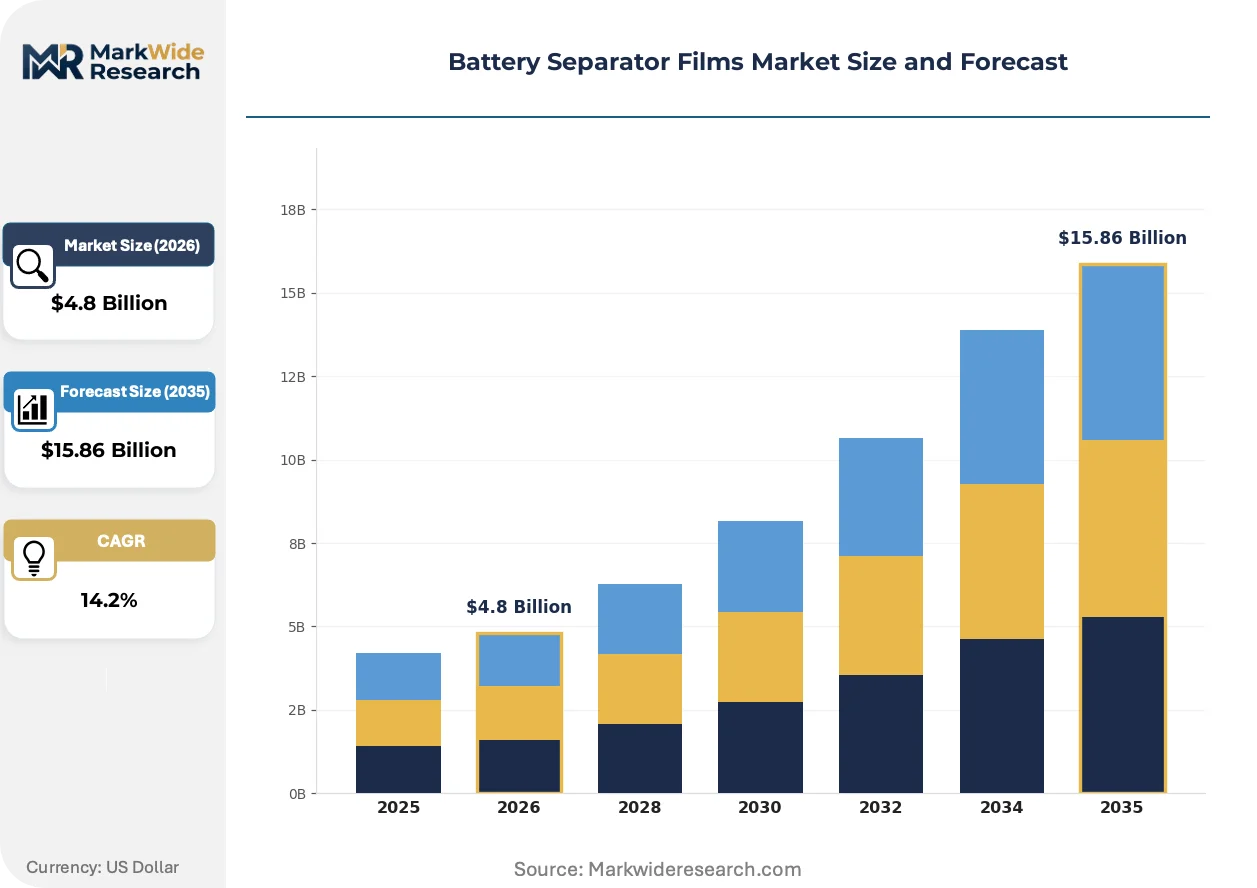
Market Dynamics
Automotive OEMs are consolidating separator procurement around integrated gigafactory complexes, forcing suppliers to co-locate extrusion capacity within 500 kilometers of cell assembly lines. This geographic lock-in is compressing qualification timelines and rewriting margin structures across the value chain.
Growth Catalysts
- EU Battery Regulation:Mandatory recycled content thresholds and carbon footprint declarations are accelerating demand for certified low-emission separator production lines.
- Solid-state battery pilot programs:Automotive OEMs in Germany and Japan are qualifying next-generation separators for sulfide-based electrolyte architectures.
- Ulsan manufacturing cluster:Concentrated cathode and cell capacity in South Korea is pulling dedicated separator extrusion investments into the region.
Market Restraints
- Ultra-high molecular weight polyethylene supply:Captive polymer production by integrated petrochemical groups limits independent separator manufacturers' feedstock access.
- China MIIT safety certification:Extended GB standard validation timelines for imported separator films create entry friction for non-domestic suppliers.
- Dry stretching process limitations:Thickness uniformity below 12 µm remains technically constrained versus wet extrusion alternatives.
Strategic Opportunities
- India PLI scheme for ACC:Advanced cell chemistry incentives are attracting separator joint ventures into Gujarat and Tamil Nadu manufacturing corridors.
- Ceramic-polymer hybrid architectures:Thermal barrier coatings are opening premium pricing tiers for separator-cathode interface optimization.
- Direct OEM contracting:Bypassing traditional trading house intermediaries in Japan and South Korea is unlocking volume commitments with technical co-development clauses.
Industry Challenges
- Cleanroom operator scarcity:Microporous membrane production requires specialized contamination control expertise that outpaces technical training program output.
- Dual qualification burden:Simultaneous automotive and consumer electronics certification cycles strain R&D bandwidth at mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Separator Films Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Composite, Ceramics End User: Automotive, Consumer Electronics, Industrial, Energy Storage Thickness: Below 20 µm, 20-30 µm, 30-40 µm, Above 40 µm Technology: Cast Film, Bi-axial Orientation, Coated, Others |
| Companies Covered | Sumitomo Chemical, ENTEK, Toray Industries, Celgard, W-SCOPE Corporation, Asahi Kasei, UBE Corporation, Freudenberg Performance Materials, SK Innovation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Separator Films Market Strategic Shifts
Separator technology is bifurcating between commodity polyolefin supply for mass-market cells and engineered composite structures for thermal runaway mitigation. Process innovation and regulatory pressure are converging to redefine performance thresholds.
Ceramic-coated polyethylene separators is hybridizing baseline shutdown safety with alumina-silica thermal barriers. European automotive OEMs are specifying these architectures for 800-volt platform cells. The technology is hybridizing formerly distinct safety and energy density optimization paths into unified product specifications.
REACH restrictions on perfluorinated additives are forcing reformulation of wet extrusion process aids. Separator manufacturers are substituting bio-based dispersants and revalidating pore size distributions. European suppliers face the steepest compliance cost curves, while Asian producers with captive chemical synthesis capabilities are absorbing transitions faster.
Cell manufacturers are unbundling separator supply from cathode material bundles and negotiating direct long-term offtake agreements. Trading houses in Tokyo and Seoul are losing intermediary margin capture. South Korea's battery manufacturing cluster exhibits the most advanced direct contracting structures, with OEMs locking in decade-plus supply commitments.
Battery Separator Films Market Segmentation
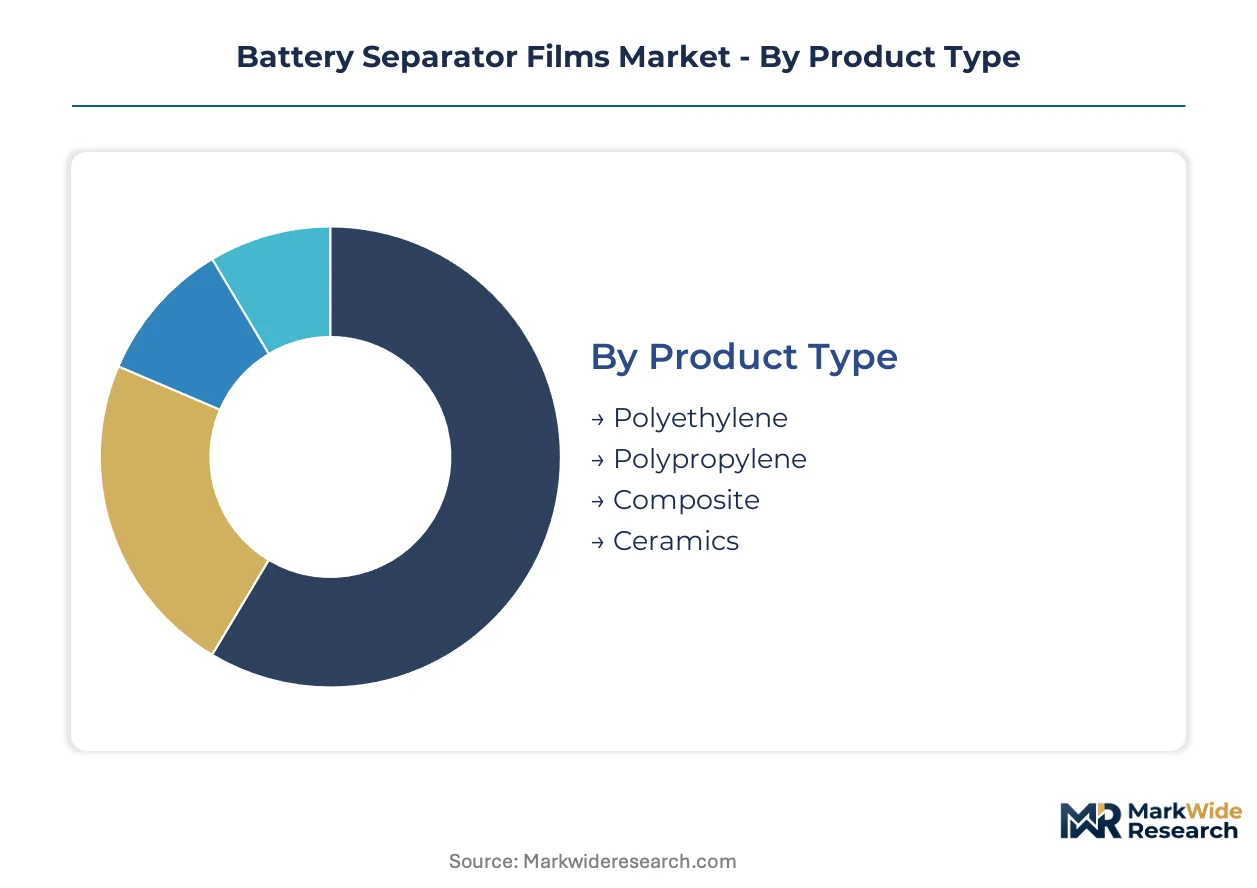
Battery separator films serve divergent performance requirements across automotive traction cells, compact consumer electronics, and grid-scale storage systems. Material selection, thickness optimization, and manufacturing technology each create distinct competitive arenas with specialized qualification barriers and margin structures.
Product Type:
Use cases span from cost-sensitive mass-market cells to thermally engineered premium architectures demanding shutdown precision and flame resistance.
- Polyethylene:Microporous membranes manufactured through wet extrusion deliver superior shutdown behavior at elevated temperatures, making them indispensable for high-energy-density automotive cells. Demand concentrates in South Korea's Ulsan manufacturing cluster where SK Innovation and LG Energy Solution specify PE substrates for 800-volt platform batteries.
- Composite:Hybrid ceramic-polymer architectures combine baseline polyolefin mechanical properties with alumina-silica thermal barriers, commanding premium pricing tiers for thermal runaway mitigation. European automotive OEMs are mandating these specifications for next-generation battery packs under EU Battery Regulation carbon footprint thresholds.
- Polypropylene:Dry-stretched membranes offer cost advantages in consumer electronics and industrial applications where shutdown temperatures above 130°C suffice.
- Ceramics:Freestanding ceramic separators address extreme temperature applications in aerospace and specialty energy storage, though brittleness limits mainstream adoption.
The dominant share belongs to Polyethylene, while Composite is closing the gap fastest.
End User:
Customer segments diverge sharply in procurement scale, qualification timelines, and technical co-development expectations.
- Automotive:OEMs negotiate decade-plus offtake agreements with technical performance clauses, consolidating procurement around integrated gigafactory complexes. Cell manufacturers in Germany, Japan, and South Korea are unbundling separator supply from cathode bundles and contracting directly with extrusion specialists.
- Consumer Electronics:Smartphone and laptop manufacturers prioritize volumetric energy density, driving specification of sub-20 µm separators with premium pricing. Procurement cycles remain shorter than automotive, with annual volume commitments replacing long-term structures.
- Industrial:Forklift, power tool, and medical device applications balance cost and cycle life requirements, typically specifying 20-30 µm polypropylene substrates.
- Energy Storage:Grid-scale battery installations emphasize cost per kilowatt-hour and calendar life over power density, favoring thicker separators with optimized cost structures.
Automotive commands the largest revenue pool, though Energy Storage is expanding most quickly as utility-scale deployments accelerate.
Thickness:
Thickness selection directly trades off ionic conductivity, mechanical integrity, and volumetric packing efficiency in cell design.
- Below 20 µm:Ultra-thin membranes maximize energy density in premium consumer electronics and compact automotive modules. Wet extrusion dominates production given dry stretching limitations on thickness uniformity below 12 µm.
- 20-30 µm:The standard automotive specification balances manufacturing yield with electrochemical performance, capturing the highest production volumes across Asian extrusion lines.
- 30-40 µm:Industrial and energy storage applications favor this range for enhanced puncture resistance and simplified handling during high-speed cell assembly.
- Above 40 µm:Specialty applications including supercapacitors and certain lithium-metal architectures require thicker substrates for dendrite suppression.
The 20-30 µm range holds the dominant position, while Below 20 µm is gaining share fastest as OEMs push energy density boundaries.
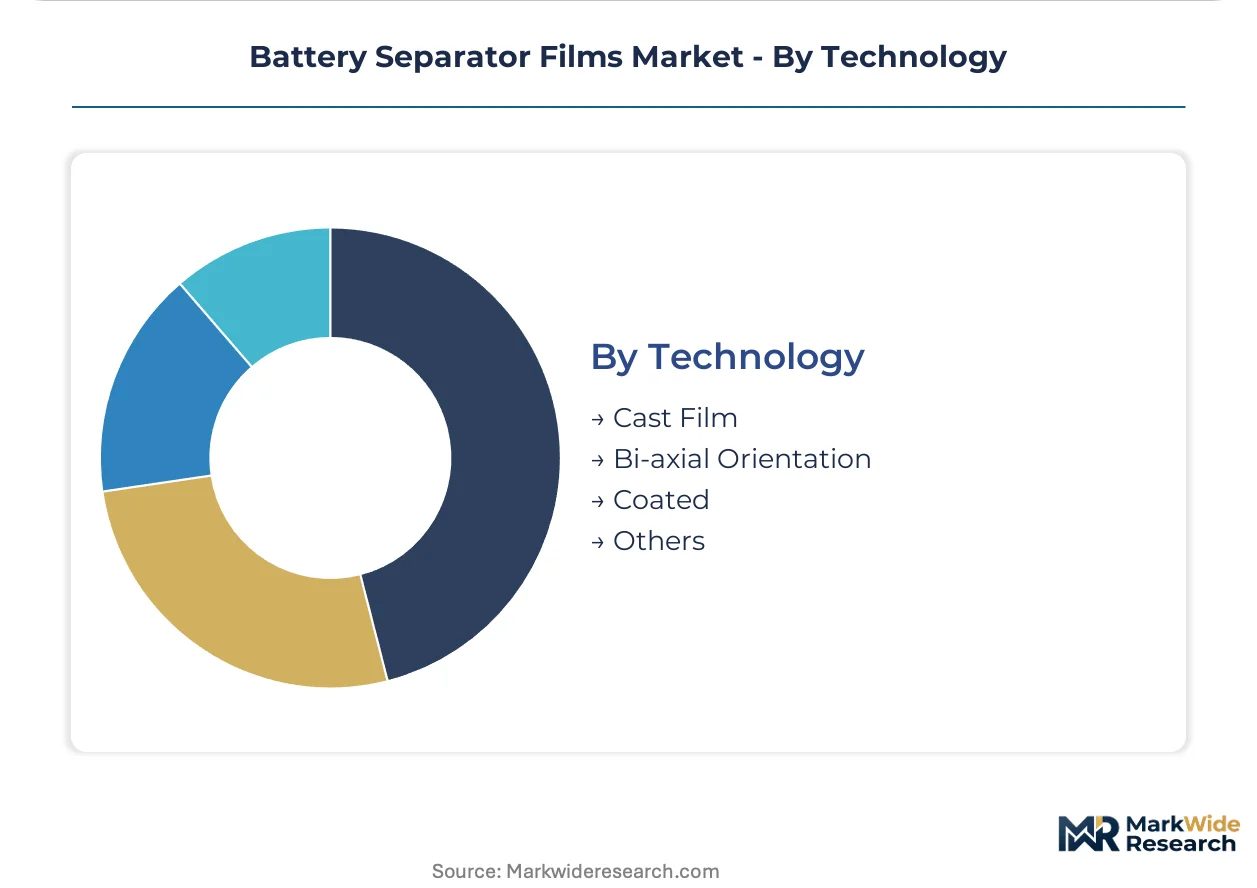
Technology:
Manufacturing process selection determines pore structure control, scalability, and compatibility with coating modifications.
- Bi-axial Orientation:Toray Industries and Japanese competitors leverage decades of membrane division expertise to produce highly uniform pore distributions. This dry process achieves superior mechanical strength for thin-gauge automotive specifications.
- Coated:Ceramic and polymer coating lines represent the fastest-expanding capacity investments, enabling thermal barrier functionality on commodity substrates. Asahi Kasei anchors this segment through captive polymer supply chains integrated with coating operations.
- Cast Film:Wet extrusion through solvent-based processes dominates polyethylene production, though REACH restrictions on perfluorinated additives are forcing European suppliers into costly reformulation cycles.
- Others:Electrospinning and phase inversion methods serve niche research and specialty applications without commercial scale.
Bi-axial Orientation retains the largest installed base, though Coated capacity is climbing the fastest as thermal runaway resistance becomes mandatory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese separator manufacturers capture pricing premiums through integrated petrochemical supply chains, while European suppliers absorb steeper compliance costs under REACH additive restrictions. This asymmetry is redrawing procurement flows across automotive battery supply chains.
China
Domestic cell manufacturers are scaling separator procurement for NCM and LFP chemistries under MIIT-enforced GB battery safety standards. The dual carbon goals framework is tightening emissions thresholds for extrusion line operators. Manufacturing concentrates in the Yangtze River Delta where polymer feedstock integration with refining complexes accelerates cost-competitive expansion.
South Korea
SK Innovation and LG Energy Solution are consolidating separator procurement within the Ulsan-Gwangju manufacturing corridor for 800-volt automotive platforms. MFDS coordinates with METI-aligned Japanese standards to harmonize cross-border qualification protocols. Dedicated extrusion investments are following cathode and cell capacity into the southeastern industrial belt.
Japan
Trading house intermediaries in Tokyo are losing margin capture as cell manufacturers negotiate direct long-term offtake agreements with extrusion specialists. METI standards alignment with Korean MFDS protocols is streamlining dual qualification burdens. Bi-axial orientation expertise accumulated in membrane divisions anchors competitive positioning in thin-gauge automotive specifications.
Germany
Automotive OEMs are qualifying next-generation separators for sulfide-based solid-state electrolyte architectures under EU Battery Regulation recycled content mandates. Extended ECHA validation timelines for imported separator films create entry friction for non-European suppliers. Production gravity is shifting toward integrated gigafactory complexes in Lower Saxony and Baden-Württemberg.
United States
FDA oversight of manufacturing equipment and EPA emissions rules are affecting domestic extrusion line economics for separator production. The Inflation Reduction Act is pulling battery supply chain investments toward the Southeast and Midwest manufacturing corridors. Cleanroom operator scarcity is constraining microporous membrane production expansion across technical training program bottlenecks.
Battery Separator Films Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in petrochemical feedstock and membrane process control. The separator market structures around three tiers: integrated chemical conglomerates with captive polymer supply, independent extrusion specialists with coating capabilities, and trading house intermediaries losing intermediary margin capture. Strategic moves concentrate on backward integration into ultra-high molecular weight polyethylene supply and co-location of extrusion capacity within 500 kilometers of cell assembly lines.
Among Japanese chemical conglomerates, Toray Industries and Asahi Kasei occupy positions anchored in decades of membrane division expertise and captive polymer supply chains respectively. Sumitomo Chemical exemplifies the diversified materials group archetype with cross-divisional process technology transfer capabilities. SK Innovation represents the Korean integrated petrochemical-to-battery value chain model with upstream control over feedstock supply. These three anchors illustrate how geographic industrial clustering and backward integration depth determine competitive positioning in qualification-intensive automotive supply chains.
| Leading Market Players |
|---|
| Sumitomo Chemical |
| ENTEK |
| Toray Industries |
| Celgard |
| W-SCOPE Corporation |
| Asahi Kasei |
| UBE Corporation |
| Freudenberg Performance Materials |
| SK Innovation |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor's freight cost volatility feeds directly into separator pricing power at Asian extrusion hubs and downstream price differentiation between ceramic-coated premium tiers and commodity polyolefin substrates. Supply concentration in South Korea's Ulsan-Gwangju corridor amplifies this dynamic, as logistics expenses compound captive polymer advantages for integrated producers while independent manufacturers absorb margin compression.
Pricing Analysis
The customization-premium spread between configured-to-order ceramic-polymer hybrids and standard polyethylene substrates runs through contract-based long-term offtake agreements with volume scale and certification tier as primary price differentiation drivers. Pricing pressure stems from automotive OEM consolidation around gigafactory complexes, forcing margin absorption at mid-scale extrusion specialists. Consumer electronics buyers exhibit highest price sensitivity due to annual procurement cycles, while automotive platforms with decade-plus commitments show lowest sensitivity.
Supply Chain Analysis
Ultra-high molecular weight polyethylene feedstock availability anchors supply chain configuration, with China, South Korea, and Japan commanding polymer production concentration. Separator manufacturing draws from petrochemical derivatives, ceramic coating inputs, and precision extrusion equipment, creating raw material dependencies that rest on integrated chemical conglomerates. Single-source vulnerability around UHMWPE supply creates structural risk, while distribution runs through direct OEM contracting that displaces traditional trading house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Battery Separator Films Market functions as a defensive-moat arena where regulatory entrenchment through multi-year automotive qualification protocols creates formidable switching costs for incumbent suppliers.
For Market Incumbents: Build captive feedstock moats through backward integration into UHMWPE production or joint ventures with petrochemical groups. Solid-state battery pilot programs threaten separator relevance, requiring R&D investment in sulfide-compatible architectures. Co-locate extrusion capacity within 500 kilometers of emerging gigafactory complexes in Germany and the US Southeast to defend qualification timelines. For New Entrants and Emerging Players: Pursue white-space opportunities in India's Gujarat-Tamil Nadu manufacturing corridors under PLI scheme incentives for advanced cell chemistry. The energy storage segment offers most penetrable entry point given less stringent qualification burdens than automotive. Target direct contracting with utility-scale battery developers bypassing established trading networks. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized membrane division assets and stranded bi-axial orientation expertise. Long-term viability hinges on ceramic-coating technology transitions over commodity polyolefin exposure. Watch solid-state battery commercialization timelines as inflection signal for separator relevance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into UHMWPE | Captive polymer supply secures margin stability against petrochemical group pricing power. |
| Ceramic Coating Capacity Expansion | Thermal barrier functionality commands premium tiers under EU Battery Regulation thresholds. |
| Gigafactory Co-location Investment | Geographic lock-in within 500 kilometers compresses automotive qualification timelines. |
| Direct OEM Contracting Structure | Bypassing Tokyo and Seoul trading houses unlocks volume commitments with technical co-development clauses. |
| Solid-State Separator Qualification | Sulfide-based electrolyte compatibility preserves relevance as liquid-electrolyte architectures face displacement. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with extrusion line engineers, automotive cell procurement directors, petrochemical feedstock managers, and cleanroom operations specialists. Secondary validation drew from MIIT GB standard filings, REACH additive restriction updates, customs trade data for polyolefin resin flows, and SEC disclosures from integrated chemical conglomerates. Bottom-up capacity assessments and top-down demand modeling were triangulated to establish market boundaries.
Calibration against historical capacity utilization rates and announced gigafactory investment pipelines anchored the analytical framework across the analysis window. Segmentation dimensions modeled include material substrate type, thickness tier, coating technology, end-use application, and regional production cluster. CAGRs were derived from slope-intercept analysis of capacity expansion announcements against qualified demand pipelines, with ceramic-coating adoption curves and solid-state battery penetration assumptions as industry-specific forecast inputs.
Sensitivities concentrate around solid-state battery commercialization timelines, REACH reformulation cost pass-through rates, and UHMWPE feedstock availability disruptions. Forecasts reflect documented assumptions regarding qualification protocol harmonization between MFDS and METI standards. Cross-checking against IEA battery supply chain investment trackers is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Nanocapsules Market
Specialty Materials
Latin America International CEP Market
Specialty Materials
Global Beeswax Market
Specialty Materials
Super Engineering Plastics Market
Specialty Materials
Teschemacherite Market
Specialty Materials
Activated Carbon Bags Market
Specialty Materials
PCB Prepreg Material Market
Specialty Materials
United States Neoprene Market
Specialty Materials
Conductive Carbon Black Market
Specialty Materials
Polyester Medical Films Market
Specialty Materials
Global Ajinomoto Build-Up Film Substrate Market
Specialty Materials
Global Consumer Foam Market
Specialty Materials
EMI and RFI Shielding Materials Market
Specialty Materials
North America Solar Control Window Films Market
Specialty Materials
Hornbeam Market
Specialty Materials
Magnesium Fluoride Market