
 United States Microspheres Market | 2026-2036
United States Microspheres Market Size, Share, and Industry Trends Forecast 2026-2036
United States Microspheres Market Intelligence
ASTM D2840 qualification for hollow glass microspheres in buoyancy applications is collapsing the supplier base to firms with certified testing infrastructure. Potters Industries LLC leverages its vertically integrated glass manufacturing to sustain supply continuity for aerospace buoyancy modules. 3M Company competes through proprietary glass bubble technology that dominates deep-sea oilfield applications.
Microspheres are spherical particles ranging from one to one thousand micrometers in diameter, engineered from glass, polymer, ceramic, or metallic compositions through processes such as flame spheroidization or emulsion polymerization. They function primarily as lightweight fillers, controlled-release carriers, or reflective agents across industrial and biomedical systems. Glass microspheres command the largest volume share due to mature oilfield and automotive demand, while polymer microspheres capture premium margins in pharmaceutical controlled-release formulations. Microfluidics-based manufacturing represents the fastest-expanding technology segment, enabling monodisperse particle distributions that solvent evaporation methods cannot replicate.
FDA oversight of complex drug-device combinations shapes pharmaceutical microsphere specifications, while EPA regulations on volatile organic compounds constrain solvent-based manufacturing pathways. OSHA crystalline silica standards directly affect glass microsphere production economics and facility capital requirements. Stakeholders must monitor how FDA guidance on complex generic equivalence evolves, as this determines whether polymer microsphere investments qualify for abbreviated approval pathways or require full clinical programs.
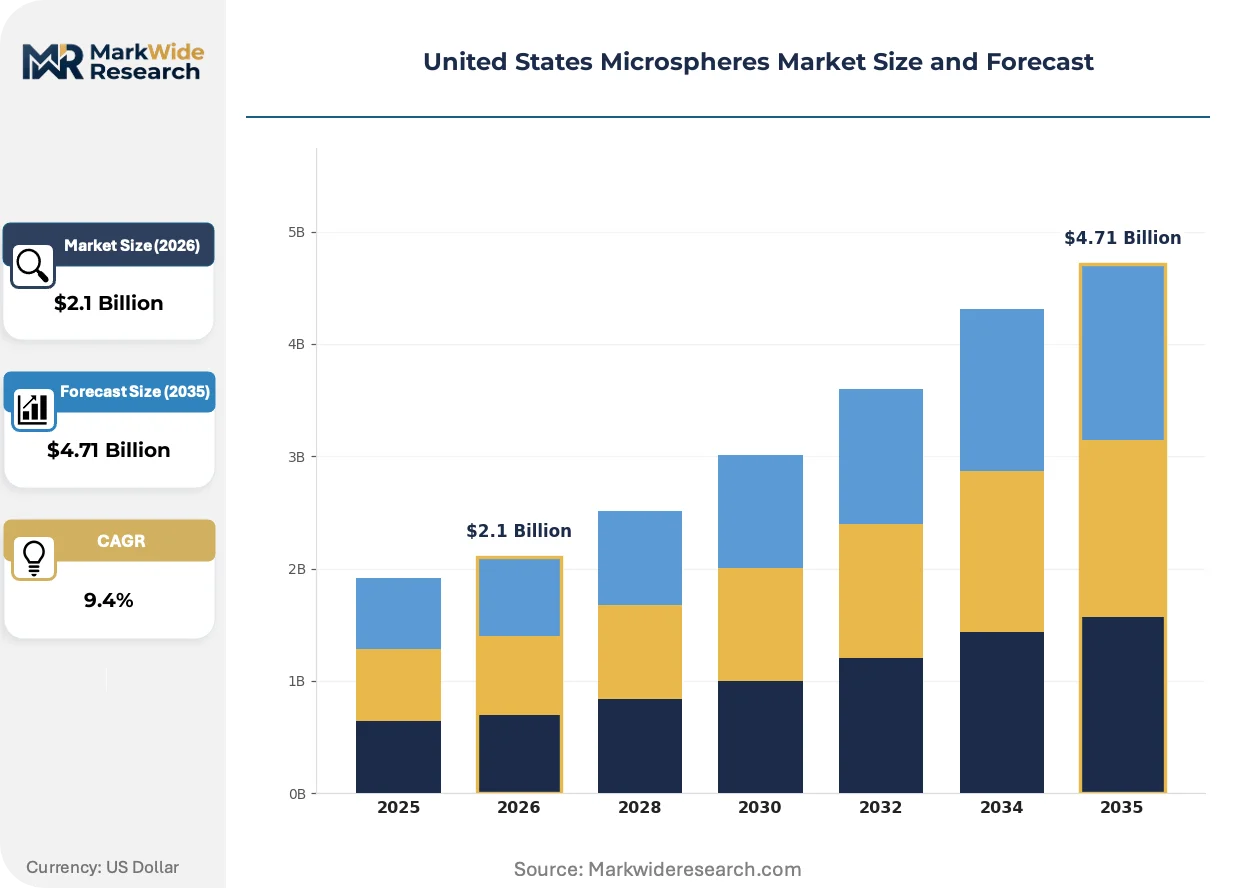
Market Dynamics
ASTM D2840 qualification requirements are collapsing the hollow glass microsphere supplier base to firms with certified testing infrastructure, concentrating supply among vertically integrated manufacturers while pharmaceutical demand for controlled-release formulations pulls polymer microsphere capacity toward FDA-regulated facilities.
Growth Catalysts
- Controlled-Release Drug Delivery:Pharmaceutical manufacturers are expanding microsphere use in parenteral and oral formulations to achieve sustained therapeutic plasma levels. FDA guidance on complex generic equivalence creates abbreviated approval pathways for polymer microsphere-based therapeutics.
- Deep-Sea Oilfield Applications:Offshore drilling operators in the Gulf of Mexico deploy hollow glass microspheres in buoyancy modules for subsea pipeline insulation. Proprietary glass bubble technology enables pressure-rated performance at extreme ocean depths.
- Massachusetts Biotech Clusters:Greater Boston's concentration of contract development and manufacturing organizations drives specialized demand for monodisperse polymer microspheres. Microfluidics-based manufacturing infrastructure expands to serve cell therapy and biologics formulation requirements.
Market Restraints
- OSHA Crystalline Silica Standards:Glass microsphere production facilities face elevated capital requirements for dust control and worker protection infrastructure. Compliance costs compress margins for mid-scale manufacturers without captive raw material supply.
- Solvent-Based Manufacturing Constraints:EPA regulations on volatile organic compounds limit expansion of traditional emulsion polymerization capacity. Alternative aqueous and supercritical CO2 processes require substantial process revalidation timelines.
- Substitute Lightweight Fillers:Expanded perlite and cenospheres compete for automotive underbody coating applications. Price-sensitive end-users in commodity construction materials switch to lower-cost alternatives when performance specifications permit.
Strategic Opportunities
- Cell Therapy Ex Vivo Expansion:Bioprocess engineers are adopting polymer microspheres as microcarriers for adherent cell culture. This emerging application opens capacity expansion opportunities for GMP-qualified manufacturers.
- New Jersey Pharmaceutical Corridor:Contract manufacturing organizations in the Interstate 95 corridor seek qualified microsphere suppliers for complex generic development programs. Proximity to FDA headquarters accelerates regulatory consultation cycles.
- Biodegradable Polymer Platforms:PLGA and PLA microsphere formulations align with sustainability mandates in medical device packaging. Federal procurement preferences for bio-based materials create demand pull in defense and veterans health applications.
Industry Challenges
- Monodisperse Particle Distribution Expertise:Microfluidics manufacturing requires specialized engineering talent scarce in traditional solvent evaporation facilities. Recruitment competition from semiconductor and advanced materials sectors elevates compensation costs.
- Drug-Device Combination Validation:FDA oversight of complex products demands integrated quality systems spanning pharmaceutical and device regulations. Dual-pathway compliance extends development timelines and capital deployment requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Microspheres Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Microspheres, Glass Microspheres, Ceramic Microspheres, Metallic Microspheres Application: Medical Applications, Cosmetics, Food Additives, Aerospace End User: Pharmaceutical Companies, Research Laboratories, Cosmetic Manufacturers, Automotive Suppliers Technology: Emulsion Polymerization, Solvent Evaporation, Spray Drying, Microfluidics |
| Companies Covered | Potters Industries LLC, Cospheric LLC, 3M Company, Luminex Corporation, Mo-Sci Corporation, Chase Corporation, Nouryon, Thermo Fisher Scientific, Momentive Performance Materials, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Microspheres Market Strategic Shifts & Innovations
Microfluidics manufacturing is decomposing traditional batch production economics while regulatory pressure on solvent emissions accelerates process innovation. Demand concentration in coastal pharmaceutical clusters reshapes distribution infrastructure requirements.
Microfluidics-based droplet generation is decomposing the historical trade-off between particle uniformity and production throughput. Biopharmaceutical contract manufacturers in Massachusetts and North Carolina are adopting continuous-flow systems to produce monodisperse PLGA microspheres with coefficient of variation below five percent. This precision enables predictable drug release kinetics that batch solvent evaporation cannot replicate, compressing formulation development timelines for complex generic sponsors.
FDA draft guidance on complex generic equivalence is tightening evidentiary standards for polymer microsphere-based formulations. The agency now requires demonstration of in vitro release profile similarity and in vivo bioequivalence for abbreviated new drug applications. Generic developers in New Jersey and California are responding by investing in specialized analytical capabilities including asymmetric flow field-flow fractionation and single-particle optical sizing.
Pharmaceutical procurement teams are consolidating microsphere supplier relationships to reduce qualification burden and secure capacity allocation. Large molecule developers in the Boston-Cambridge cluster now require dedicated manufacturing suites with audit rights rather than catalog purchases from distributors. This concentration of buying power is visible most acutely in parenteral controlled-release programs where supply continuity carries clinical trial timeline risk.
United States Microspheres Market Segmentation
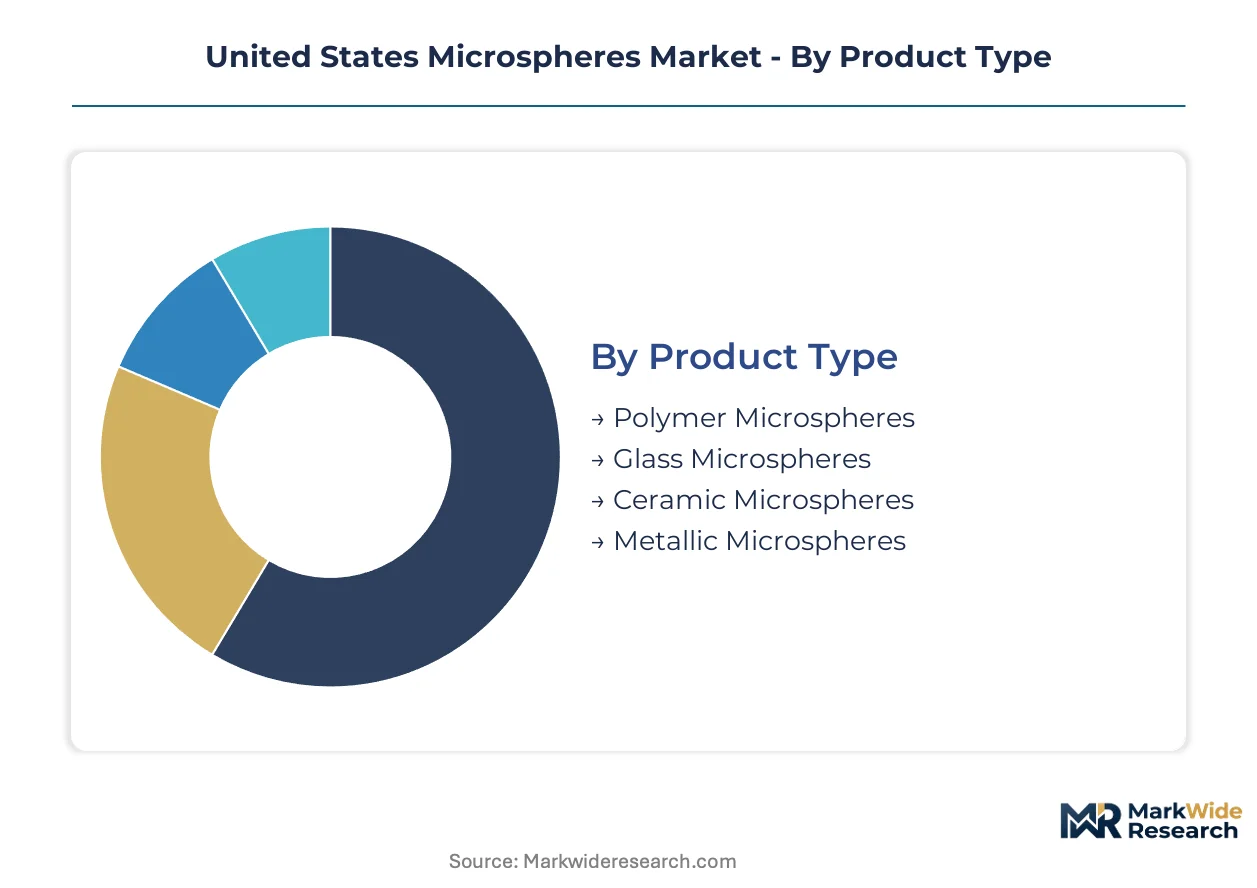
Microsphere segmentation in the United States reflects divergent regulatory pathways across pharmaceutical, aerospace, and industrial applications. Product specifications vary sharply between FDA-regulated drug delivery systems and ASTM-qualified buoyancy modules.
Product Type:
FDA oversight of complex generic formulations creates divergent compliance burdens across material categories, with polymer microspheres facing abbreviated approval pathways unavailable to glass or ceramic alternatives.
- Polymer Microspheres:Engineered from PLGA, PLA, and acrylic copolymers through emulsion or microfluidic processes. Demand concentrates in Massachusetts biotech clusters for parenteral controlled-release formulations, where FDA guidance on bioequivalence drives investment in monodisperse manufacturing infrastructure.
- Glass Microspheres:Manufactured from soda-lime or borosilicate glass via flame spheroidization, with hollow variants qualified to ASTM D2840 for buoyancy applications. Gulf of Mexico offshore operators deploy these in subsea pipeline insulation modules, where pressure-rated performance specifications favor suppliers with vertically integrated glass manufacturing.
- Ceramic Microspheres:Produced from alumina, zirconia, or fly ash through high-temperature processing. Automotive underbody coatings in Michigan and Ohio represent the primary demand concentration.
- Metallic Microspheres:Fabricated from aluminum, nickel, or specialty alloys through atomization or electrodeposition. Defense contractors in California and Texas specify these for electromagnetic shielding applications.
Established volume favors Glass Microspheres; emerging adoption favors Polymer Microspheres.
Application:
Application segmentation tracks end-use concentration across coastal pharmaceutical corridors and energy-producing regions, with regulatory complexity escalating from cosmetic formulations to drug-device combinations.
- Medical Applications:Controlled-release drug delivery, cell therapy microcarriers, and diagnostic assays. New Jersey pharmaceutical corridor contracts dominate procurement, with CDMOs requiring dedicated GMP manufacturing suites and audit rights rather than catalog distribution.
- Aerospace:Lightweight structural fillers, syntactic foams, and radar-absorbing materials. California and Washington State defense contractors drive specifications for qualified suppliers with AS9100 certification.
- Cosmetics:Exfoliating agents, optical diffusers, and texture modifiers. Formulators in New York and Los Angeles prioritize sensory performance and regulatory safety data.
- Food Additives:Encapsulation carriers for flavors, vitamins, and probiotics. GRAS self-determination pathways constrain supplier qualification requirements relative to pharmaceutical applications.
Medical Applications command premium pricing; Aerospace maintains the steepest expansion trajectory through defense procurement.
End User:
End user segmentation reveals procurement consolidation patterns, with large pharmaceutical developers extracting dedicated capacity commitments that mid-scale research laboratories cannot match.
- Pharmaceutical Companies:Multinational developers and generic sponsors in New Jersey and California seeking polymer microspheres for abbreviated new drug applications. FDA consultation proximity accelerates regulatory timelines for complex generic equivalence demonstrations.
- Research Laboratories:Academic and government facilities requiring small-batch, high-customization supply. Massachusetts and Maryland institutions drive demand for monodisperse particles with coefficient of variation below five percent.
- Cosmetic Manufacturers:Formulation houses in New York and Florida prioritizing aesthetic performance and rapid scale-up capacity.
- Automotive Suppliers:Tier-1 coating applicators in Michigan and Ohio specifying lightweight fillers for underbody corrosion protection and sound dampening.
Pharmaceutical Companies dominate value capture; Research Laboratories generate disproportionate technology pull.
Technology:
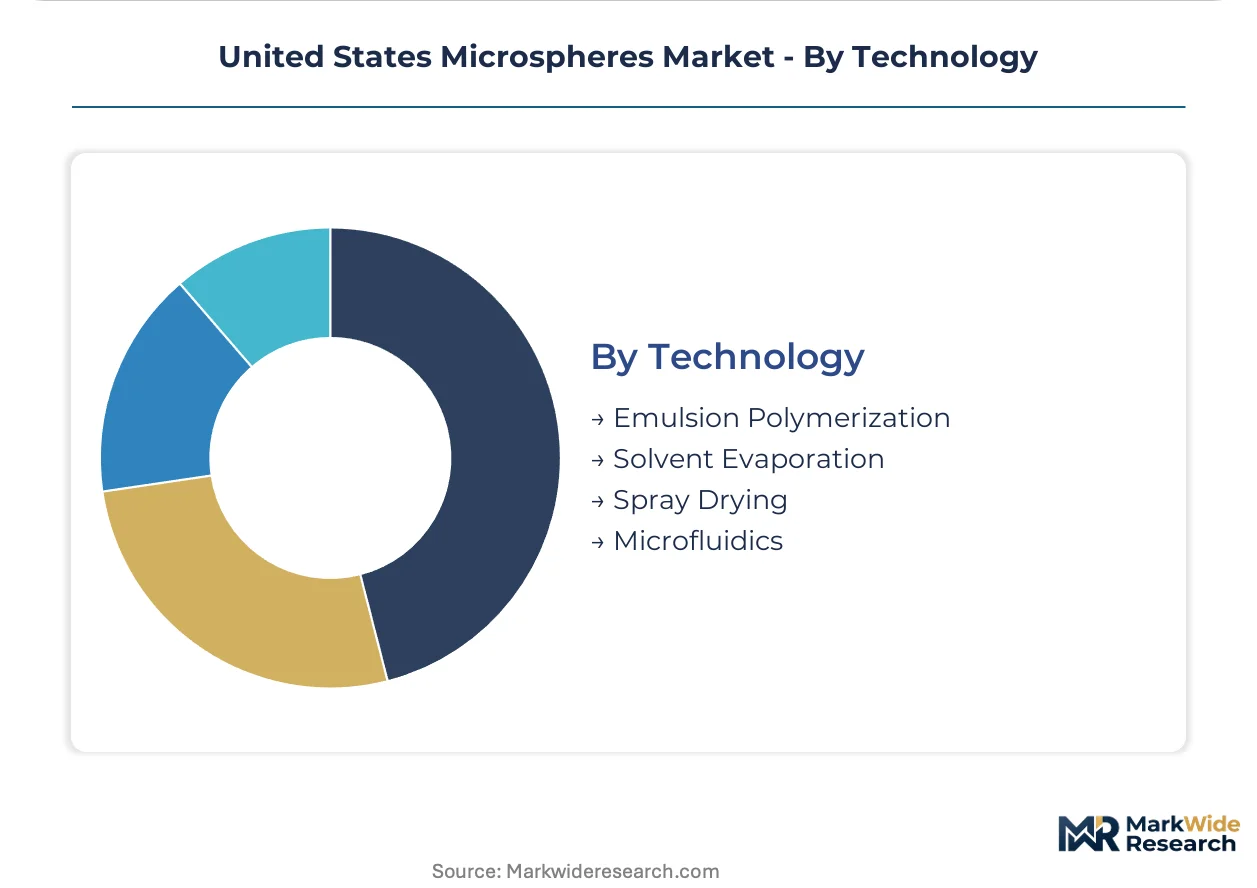
Technology segmentation tracks manufacturing process maturity against regulatory pressure on solvent emissions, with continuous-flow systems displacing batch production in high-specification applications.
- Microfluidics:Continuous droplet generation enabling monodisperse particle distributions with coefficient of variation below five percent. North Carolina and Massachusetts contract manufacturers adopt these systems for cell therapy and biologics formulation requirements.
- Emulsion Polymerization:Conventional batch processing for polymer microspheres with broader size distributions. EPA volatile organic compound regulations constrain capacity expansion in legacy facilities.
- Solvent Evaporation:Traditional pharmaceutical manufacturing for PLGA microspheres. Process revalidation timelines extend as sponsors migrate toward aqueous or supercritical CO2 alternatives.
- Spray Drying:High-throughput particle formation for food and cosmetic applications. Lower regulatory burden relative to pharmaceutical pathways supports margin compression in commodity segments.
Microfluidics is climbing the fastest; Spray Drying retains volume leadership in non-regulated segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal procurement preferences for bio-based materials and state-level biotech incentives are redistributing microsphere demand across domestic manufacturing corridors. The Interstate 95 pharmaceutical belt and Gulf Coast energy infrastructure anchor contrasting supply requirements.
New Jersey Pharmaceutical Corridor
Contract development organizations along Interstate 95 consume polymer microspheres for complex generic formulations. FDA headquarters proximity accelerates regulatory consultation cycles for abbreviated new drug applications. Newark and Princeton clusters host dedicated GMP manufacturing suites with audit rights demanded by large molecule developers.
Massachusetts Biotech Cluster
Greater Boston's concentration of cell therapy developers pulls monodisperse microsphere capacity toward microcarrier applications. State life sciences tax incentives support microfluidics manufacturing infrastructure expansion. Cambridge and Worcester facilities serve biologics formulation requirements with coefficient of variation specifications below five percent.
Gulf of Mexico Energy Corridor
Offshore drilling operators in Louisiana and Texas deploy hollow glass microspheres in subsea pipeline buoyancy modules. Bureau of Safety and Environmental Enforcement oversight shapes pressure-rated performance specifications. Houma and Port Fourchon fabrication yards source from suppliers with vertically integrated glass manufacturing.
North Carolina Research Triangle
Contract manufacturers in Raleigh-Durham adopt continuous-flow microfluidics systems for pharmaceutical microsphere production. EPA volatile organic compound regulations constrain legacy solvent-based capacity expansion. RTP facilities specialize in PLGA formulations for parenteral controlled-release programs.
California Defense-Aerospace Belt
Southern California contractors specify metallic microspheres for electromagnetic shielding in defense applications. AS9100 certification requirements filter supplier qualification to aerospace-qualified manufacturers. San Diego and Los Angeles County facilities serve Navy and Air Force procurement programs.
United States Microspheres Market Key Industry Players
Player mix skews toward specialty material conglomerates with captive raw material supply and precision manufacturing subsidiaries. Three structural tiers have crystallized: vertically integrated glass manufacturers with ASTM-certified testing infrastructure, pharmaceutical-focused polymer specialists with FDA-registered facilities, and diversified technology conglomerates leveraging proprietary formulation platforms. Consolidation pressure operates through acquisition of microfluidics capabilities and dedicated GMP suite construction rather than commodity capacity expansion.
Within the vertically integrated tier, Potters Industries LLC and 3M Company exemplify contrasting supply strategies. Potters anchors glass microsphere production through captive soda-lime manufacturing, while 3M occupies a position defined by proprietary glass bubble technology. Cospheric LLC represents the precision fabrication archetype, specializing in monodisperse particle distributions for research and pharmaceutical applications. These three entities collectively illustrate how certification requirements and end-use specifications fragment competitive positioning across non-interchangeable supply segments.
| Leading Market Players |
|---|
| Potters Industries LLC |
| Cospheric LLC |
| 3M Company |
| Luminex Corporation |
| Mo-Sci Corporation |
| Chase Corporation |
| Nouryon |
| Thermo Fisher Scientific |
| Momentive Performance Materials |
| Others |
Cost & Logistics Intelligence
Polymer microsphere substitution for glass alternatives in Massachusetts cell therapy applications simultaneously concentrates procurement toward FDA-registered facilities and compresses price premiums for non-certified supply. This material transition rewards suppliers with captive GMP infrastructure while eroding margins for commodity glass manufacturers serving legacy oilfield demand.
Pricing Analysis
Certification level creates the primary spread across the United States Microspheres Market, with FDA-registered polymer microspheres commanding substantial premiums over ASTM-qualified glass alternatives. Three-tier pricing structure separates GMP-validated pharmaceutical grades from industrial specifications and uncertified commodity supply. Cost compression in hollow glass microspheres is intensifying because expanded perlite and cenospheres capture price-sensitive automotive coating applications. Research laboratories exhibit the highest price sensitivity due to fragmented procurement and small-batch requirements, while pharmaceutical companies accept premium pricing for dedicated manufacturing suites with audit rights.
Supply Chain Analysis
Borosilicate raw material access from Pennsylvania and Ohio glass manufacturing corridors anchors domestic hollow microsphere production, while pharmaceutical-grade PLGA polymer feedstock draws from specialized chemical manufacturers in Texas and Louisiana. Soda-lime glass cullet, boron oxide, and pharmaceutical-grade lactide monomers constitute the critical input trinity. Single-source vulnerability concentrates in certified testing infrastructure for ASTM D2840 qualification, where only vertically integrated manufacturers maintain compliant facilities. Distribution runs through direct contractual relationships for pharmaceutical applications and distributor networks for industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the United States Microspheres Market creates specialized niche opportunities as FDA guidance on complex generic equivalence splinters demand into certification-specific procurement silos. This regulatory-driven demand segmentation rewards focused capability investments over broad commodity positioning.
For Market Incumbents: Fortify ASTM D2840 certification infrastructure against emerging microfluidics competitors by expanding captive glass manufacturing capacity in the Gulf Coast corridor. Secure dedicated GMP suite commitments from New Jersey contract development organizations before pharmaceutical procurement consolidation hardens supplier relationships. Vertical integration into borosilicate raw material supply protects margin structure against energy cost volatility.
For New Entrants and Emerging Players: Differentiate on microfluidics manufacturing precision for Massachusetts cell therapy microcarrier applications, where coefficient of variation specifications below five percent remain underserved. Target North Carolina Research Triangle contract manufacturers seeking continuous-flow PLGA production capacity as EPA volatile organic compound regulations constrain legacy solvent-based expansion. Pursue partnership-first go-to-market positioning with audit-rights agreements rather than catalog distribution.
For Investors and Strategic Acquirers: Capital is best deployed toward precision fabrication specialists with microfluidics capabilities and existing GMP qualifications, as pharmaceutical demand concentration accelerates through the forecast window. Acquisition targets should demonstrate established relationships with Interstate 95 corridor contract manufacturing organizations and scalable continuous-flow manufacturing infrastructure. Monitor FDA draft guidance finalization on complex generic equivalence as the primary inflection signal for polymer microsphere investment viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidics Manufacturing Scale-Up | Enables monodisperse PLGA supply for Massachusetts cell therapy developers requiring sub-five-percent coefficient of variation. |
| GMP Suite Dedication with Audit Rights | Secures capacity allocation from New Jersey pharmaceutical corridor sponsors facing clinical trial timeline risk. |
| ASTM D2840 Certification Investment | Preserves hollow glass microsphere supply position for Gulf of Mexico offshore buoyancy module fabricators. |
| Backward Integration into Borosilicate Supply | Reduces raw material cost exposure for glass microsphere producers serving pressure-rated deep-sea applications. |
| Aqueous Process Technology Transition | Aligns polymer microsphere production with EPA volatile organic compound emission constraints affecting legacy facilities. |
Research Approach
The analysis maps hollow glass, polymer, ceramic, and metallic microsphere sub-sectors, each validated through pharmaceutical procurement managers, aerospace materials engineers, oilfield supply chain directors, and bioprocess development scientists. Primary intelligence combined structured interviews with secondary validation against FDA guidance documents, EPA enforcement databases, ASTM standards publications, and Bureau of Safety and Environmental Enforcement incident reports. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across the projection horizon.
Consistency checks validated outputs against external benchmarks including customs trade data for borosilicate glass imports, pharmaceutical manufacturing facility registration databases, and defense procurement disclosure records. The analytical framework modeled segmentation across material composition, application category, end-user type, and manufacturing technology throughout the forecast period. CAGRs derived from regression analysis of historical capacity expansion patterns against regulatory filing velocity and contract manufacturing organization facility build-out announcements.
Material uncertainties — FDA guidance finalization timelines, EPA enforcement intensity on solvent emissions, and offshore drilling permit issuance rates — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as regulatory consultation outcomes and federal bio-based procurement preference implementations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Specialty Polyamides Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
Polyetherimide (PEI) Market
Specialty Materials
Nanocapsules Market
Specialty Materials
Hydrolysis Stable Polyester Films Market
Specialty Materials
Specialty and High Performance Films Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Jesmonite Market
Specialty Materials
PCB Prepreg Material Market
Specialty Materials
Global Graphic Film Market
Specialty Materials
Polyimide Foam Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Latin America International CEP Market
Specialty Materials
Metalized Biaxially Oriented Polypropylene Films Market
Specialty Materials
Specialty Silicone Market
Specialty Materials
Global PMMA Microspheres Market