
 Europe Silica Sand for Glass Making Market | 2026-2036
Europe Silica Sand for Glass Making Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Silica Sand for Glass Making Market Foresight
Belgium is reconfiguring its silica sand processing corridor to serve premium flat glass demand across the Benelux and northern France. Sibelco leverages deep quarry reserves in the Ardennes to sustain long-term supply contracts with float glass producers. Quarzwerke Group anchors German container glass output through integrated beneficiation plants in the Lower Rhine region. Imerys Refractory Minerals differentiates via specialized low-iron grades for solar glass foundries.
Europe silica sand for glass making refers to high-purity quartz sand with silica content typically exceeding 98.5%, processed through washing, screening, and acid leaching to remove iron oxides and alumina that compromise optical clarity. This material furnishes the primary silicon dioxide feedstock for melting in glass furnaces operating at temperatures above 1500°C. Container glass commands the largest volume share across the grade spectrum, though low-iron silica for solar panel applications captures the fastest expansion trajectory as photovoltaic manufacturing scales in Europe. Specialty glass segments including borosilicate and optical grades concentrate margin pools where Premium grade specifications justify higher purification investments.
REACH registration requirements and the EU Green Deal carbon border adjustments are elevating compliance costs for silica sand beneficiation and glass furnace operations across Europe. ECHA oversight of crystalline silica workplace exposure limits is reshaping mining automation investments and respiratory protection protocols. The F-Gas Regulation phases down hydrofluorocarbon use in glass manufacturing ancillary systems, indirectly pressuring energy efficiency upgrades. Stakeholders must monitor evolving CSRD disclosure mandates on Scope 3 emissions from quarry to furnace as supply chain transparency becomes a procurement differentiator.
Market Dynamics
The EU Green Deal's carbon border adjustment mechanism is restructuring procurement priorities across European glass manufacturing, forcing furnace operators to audit Scope 3 emissions from quarry to melt. This regulatory pressure is concentrating supply relationships around beneficiation plants with verified low-carbon processing credentials.
Growth Catalysts
- EU Green Deal carbon border adjustments:Glass furnace operators now prioritize silica sand suppliers with documented carbon footprints, accelerating contract consolidation toward integrated quarry-beneficiation assets in Belgium and Germany.
- Solar panel manufacturing expansion:Low-iron silica sand procurement is intensifying as photovoltaic foundries scale across Spain, Italy, and Eastern Europe to serve domestic renewable energy targets.
- F-Gas Regulation phase-down:Hydrofluorocarbon restrictions in ancillary glass manufacturing systems are pressuring energy efficiency upgrades that favor premium-grade feedstock with consistent melt characteristics.
Market Restraints
- Energy cost volatility:Natural gas and electricity price spikes in Germany and Italy have compressed margins for energy-intensive acid leaching and thermal beneficiation processes.
- Ardennes quarry concentration:Premium flat glass supply chains depend heavily on Sibelco's deep reserves in southern Belgium, creating geographic single-point vulnerability for Benelux and northern France float glass producers.
- REACH registration burdens:ECHA oversight of crystalline silica workplace exposure limits is elevating compliance costs and automation investments for mid-scale processors without captive testing facilities.
Strategic Opportunities
- Eastern European solar glass clusters:Poland, Czechia, and Hungary offer underdeveloped low-iron silica sand beneficiation capacity to serve incoming photovoltaic manufacturing investments.
- CSRD disclosure mandates:Corporate Sustainability Reporting Directive requirements are creating procurement differentiators for suppliers with transparent quarry-to-furnace emissions tracking.
- Dry beneficiation technology convergence:Electrostatic separation combined with optical sorting is opening retrofit opportunities at legacy wet-processing plants seeking water and energy savings.
Industry Challenges
- Process automation skill gaps:Mining operations struggle to recruit technicians capable of maintaining sensor-based sorting equipment and automated respiratory protection systems mandated by ECHA exposure protocols.
- Beneficiation plant capex cycles:Acid leaching circuit upgrades and filtration system replacements require capital deployment timelines that misalign with glass furnace operators' annual contract renegotiation windows.
- Multi-jurisdiction certification complexity:Silica sand processors serving cross-border supply chains must reconcile divergent national implementations of REACH registration and workplace safety standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Silica Sand for Glass Making Market |
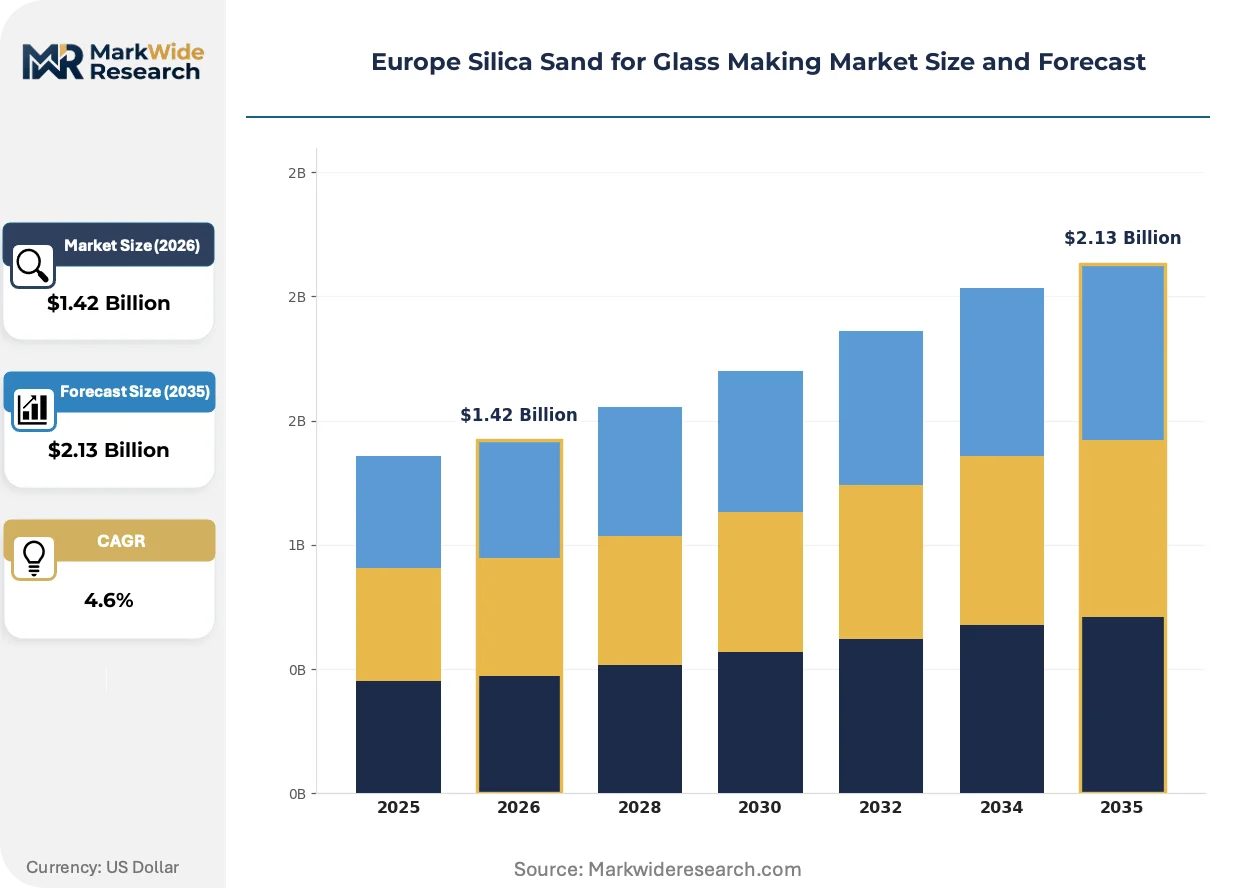
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Container Glass, Flat Glass, Fiberglass, Specialty Glass End User: Construction, Automotive, Electronics, Aerospace Application: Building & Construction, Solar Panels, Packaging, Lighting Grade: Premium, Standard, Low-iron, Others |
| Companies Covered | Covia Holdings, Imerys Refractory Minerals, Sibelco, Tochu Corporation, Holcim AG, Quarzwerke Group, Euroquarz GmbH, Terengganu Silica Consortium, U.S. Silica, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Silica Sand for Glass Making Market Shifts & Advancements
European silica sand beneficiation is pivoting toward precision processing technologies that guarantee iron oxide thresholds below 100 ppm for solar glass applications. This technical escalation is compressing the viable supplier base while rewarding integrated operators with captive laboratory verification capabilities.
Optical sorting technology is migrating from pilot installations to standard configuration at premium-grade beneficiation plants serving float glass producers. Ardennes-based processors are adopting near-infrared spectrum analyzers to detect and eject iron-bearing minerals at throughputs exceeding 100 tonnes per hour. This capability is enabling real-time grade certification that satisfies solar foundry procurement specifications without batch sampling delays.
REACH registration requirements and the EU Green Deal's carbon border adjustment mechanism are elevating documentation burdens across the value chain. ECHA oversight of crystalline silica workplace exposure limits is mandating automated dust suppression and continuous air monitoring at quarry operations. Container glass segments in Germany and Italy are responding by consolidating supply relationships with processors offering pre-certified emission audits.
Glass furnace operators are unbundling long-term silica sand contracts into shorter-term agreements with price-adjustment clauses tied to energy and carbon costs. This procurement pattern is displacing traditional multi-year fixed-price arrangements that dominated flat glass supply chains. The shift is most visible in France and Spain, where float glass producers now negotiate quarterly volume commitments with spot-market flexibility for premium low-iron grades.
Europe Silica Sand for Glass Making Market Segmentation
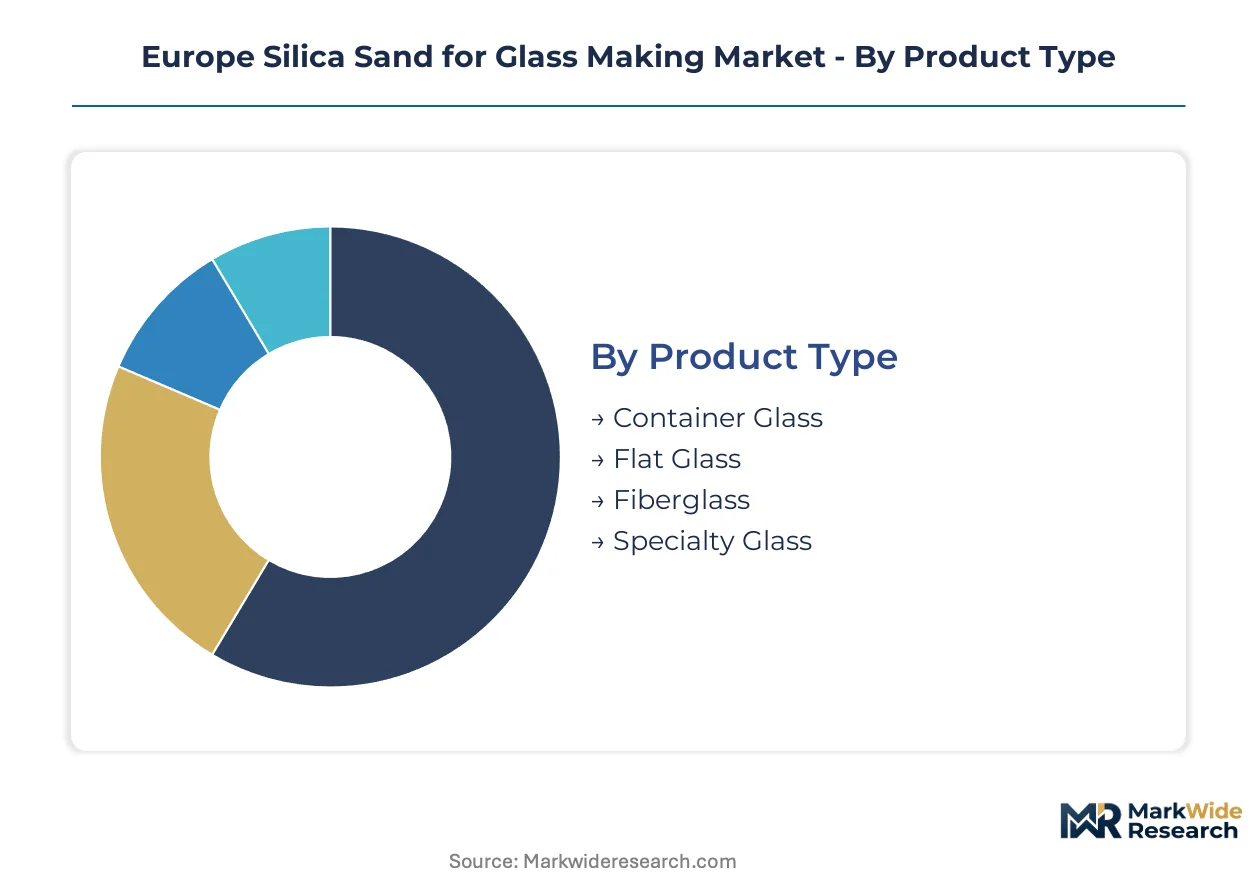
Silica sand specifications diverge sharply across glass manufacturing verticals, with iron content thresholds and particle size distributions determining furnace compatibility. Procurement contracts in Europe increasingly tie grade certification to specific end-use performance requirements rather than generic purity benchmarks.
Product Type:
Application volume determines the cost tier structure across glass manufacturing feedstock demand.
- Container Glass:Standard-grade silica sand with 98.5-99.2% SiO₂ content furnishes bottle and jar production across Germany and Italy. Procurement concentrates at integrated beneficiation plants serving Owens-Illinois and Verallia furnace clusters in the Lower Rhine and Lombardy regions.
- Flat Glass:Premium-grade material with sub-200 ppm iron oxide specifications feeds float glass lines in Belgium and France. Saint-Gobain and AGC procurement teams audit Ardennes quarry output for optical clarity metrics before furnace delivery.
- Fiberglass:Controlled particle size distribution between 100-600 microns supports E-glass and C-glass reinforcement fiber production. Demand clusters at PPG and Johns Manville facilities in the Netherlands and Germany.
- Specialty Glass:Ultra-high purity grades exceeding 99.8% SiO₂ serve borosilicate laboratory ware and optical lens foundries. Schott AG in Mainz and Heraeus in Hanau anchor European demand for these stringent specifications.
Container Glass holds installed capacity. Flat Glass is rotating up the share rankings.
End User:
Customer type segmentation reveals divergent procurement sophistication across industrial verticals.
- Construction:Float glass for architectural glazing and container glass for building materials dominate volume. German and French construction recovery cycles directly influence quarterly silica sand contract negotiations.
- Automotive:Laminated windshield and tempered side glass specifications demand consistent iron oxide levels below 150 ppm. BMW and Volkswagen supply chain audits now extend to Tier 3 silica sand beneficiation emissions documentation.
- Electronics:LCD substrate and semiconductor packaging glass requires ultra-low alkali content below 0.1% Na₂O. Corning and AGC Display Solutions procurement in Germany drives premium-grade demand.
- Aerospace:Specialized borosilicate and quartz glass for cockpit displays and optical systems represents marginal volume but maximum purity requirements. Thales and Airbus supply chains source through qualified Swiss and German processors.
Construction maintains volume leadership. Electronics is climbing the fastest as display manufacturing reshoring accelerates.
Application:
Geography shapes where specific application demand concentrates across European glass manufacturing corridors.
- Building & Construction:Architectural glazing and insulation fiberglass absorb standard and premium grades across Benelux and northern France. Belgian float glass exports serve Dutch and German construction markets.
- Solar Panels:Photovoltaic cover glass specifications mandate iron oxide below 100 ppm for maximum light transmission. Spanish and Italian solar manufacturing investments are pulling low-iron silica sand through Mediterranean processing routes.
- Packaging:Food and beverage container glass production clusters in Italy, Germany, and France drive consistent standard-grade demand. Heineken and Diageo supply chain sustainability audits now cover silica sand Scope 3 emissions.
- Lighting:LED encapsulation and traditional lamp glass represents declining volume but persistent specialty grade requirements. Signify in the Netherlands and Osram in Germany anchor residual demand.
Building & Construction commands existing infrastructure. Solar Panels is gaining share fastest as renewable manufacturing scales.
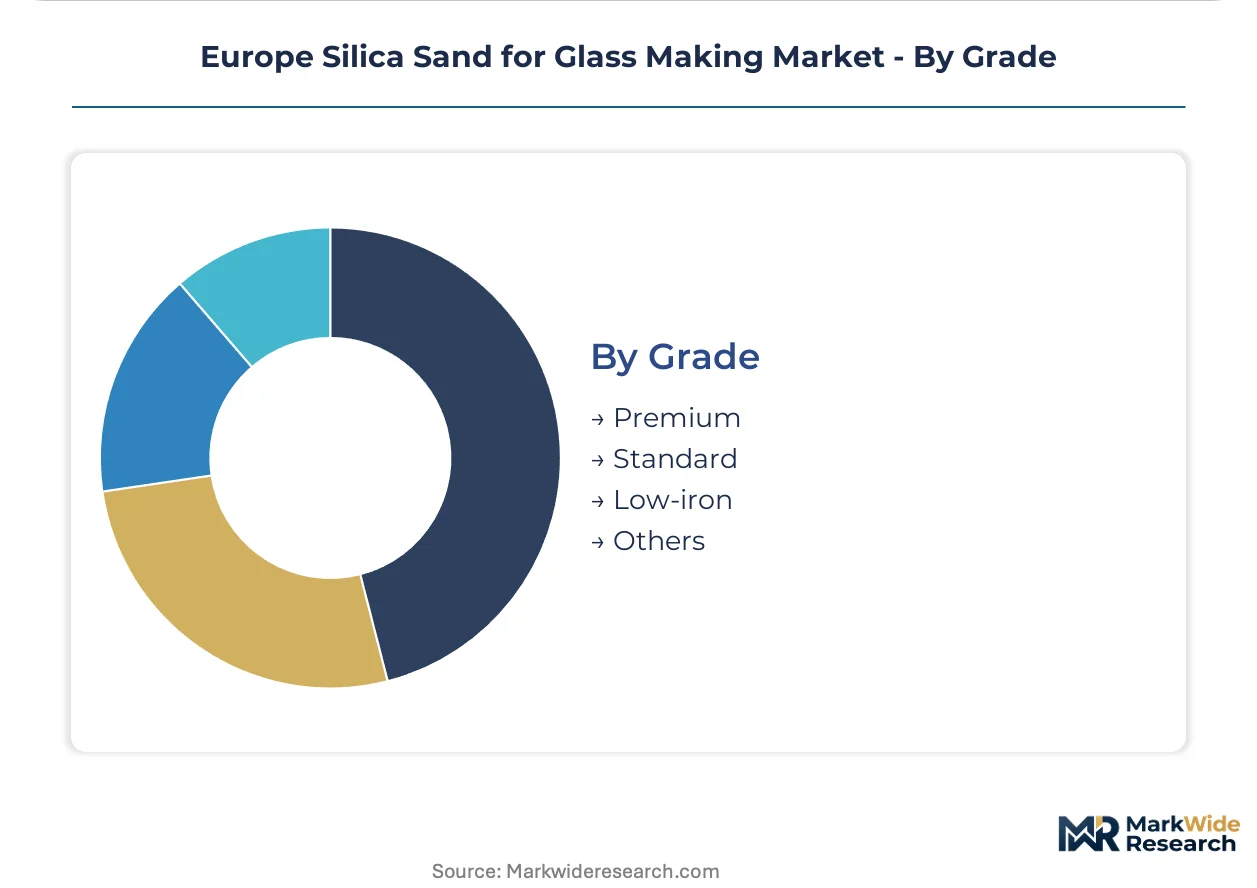
Grade:
Margin structure stratifies sharply across purity tiers, with certification costs determining viable supplier participation.
- Premium:Sub-150 ppm iron oxide with controlled alumina below 0.5% serves float glass and high-performance container applications. Sibelco and Imerys dominate supply through captive laboratory verification networks in Belgium and France.
- Standard:200-800 ppm iron oxide tolerance accommodates general container and construction fiberglass production. Quarzwerke Group and regional German processors compete on logistics efficiency and energy cost hedging.
- Low-iron:Below 100 ppm specifications with dedicated acid leaching circuits target solar glass and premium optical applications. Eastern European beneficiation capacity in Poland and Czechia is expanding to capture photovoltaic demand growth.
- Others:Custom blends and intermediate specifications serve niche pharmaceutical and technical glass segments. Swiss and Austrian processors specialize in small-batch certification for laboratory and medical device manufacturers.
Standard grade retains volume dominance. Low-iron is expanding most quickly as solar glass specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Meuse-Scheldt delta port complex underwrites Belgium's central role in European silica sand distribution, connecting Ardennes quarry output to float glass furnaces across the Benelux and northern France.
Germany
Container glass furnaces in the Lower Rhine region consume standard-grade silica sand from integrated beneficiation plants serving Owens-Illinois and Verallia operations. ECHA oversight of crystalline silica workplace exposure limits is mandating automated dust suppression systems at quarry operations. Quarzwerke Group anchors supply security through captive processing assets in North Rhine-Westphalia.
Belgium
Sibelco leverages deep quarry reserves in the Ardennes to sustain long-term supply contracts with premium flat glass producers. The EU Green Deal's carbon border adjustment mechanism is elevating documentation burdens for cross-border shipments to French float glass lines. The Meuse River corridor concentrates beneficiation capacity serving Saint-Gobain procurement teams.
France
Float glass production clusters in northern France pull premium-grade material through Belgian processing routes. CSRD disclosure mandates are reshaping procurement relationships around transparent quarry-to-furnace emissions tracking. The Dunkirk industrial zone represents a concentration point for architectural glazing feedstock demand.
Italy
Container glass manufacturers in Lombardy and Tuscany drive consistent standard-grade procurement from Mediterranean processing routes. F-Gas Regulation phase-down pressures are accelerating energy efficiency upgrades at furnace operations. The Porto Marghera industrial district hosts specialty glass foundries requiring ultra-low iron specifications.
Spain
Solar panel manufacturing investments across Castilla-La Mancha and Andalusia are pulling low-iron silica sand through expanding Mediterranean beneficiation capacity. Domestic renewable energy targets under the EU Green Deal are scaling photovoltaic foundry operations. The Seville corridor is emerging as a processing hub for sub-100 ppm iron oxide grades.
Europe Silica Sand for Glass Making Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream where beneficiation technology and quarry reserve quality determine contract viability. The vendor base stratifies across three tiers: integrated multinationals with captive laboratory networks, regional processors with logistics advantages, and niche specialists serving solar glass specifications. Two dominant competitive moves are reshaping positioning: consolidation around low-carbon processing credentials and technology licensing for dry beneficiation retrofits.
Among Belgium-based operators, Sibelco exemplifies the integrated multinational archetype through deep Ardennes reserves and captive verification capabilities. Imerys Refractory Minerals occupies a position within the specialty-grade tier, differentiating via low-iron specifications for solar applications. Quarzwerke Group represents the regional scale archetype, anchoring German container glass supply chains through Lower Rhine beneficiation assets.
| Leading Market Players |
|---|
| Covia Holdings |
| Imerys Refractory Minerals |
| Sibelco |
| Tochu Corporation |
| Holcim AG |
| Quarzwerke Group |
| Euroquarz GmbH |
| Terengganu Silica Consortium |
| U.S. Silica |
| Others |
Supply & Pricing Matrix
Ardennes quarry concentration risk determines both pricing tier spreads and supply chain shape across European silica sand markets. Belgian reserve dominance compresses premium-grade margins for northern French float glass producers while elevating standard-grade leverage for German container glass operators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates low-iron solar grades from container glass feedstock and construction fiberglass material. Price differentiation centers on certification grade and volume scale, with solar foundries paying premiums for sub-100 ppm iron oxide guarantees. Cost compression in standard-grade tiers is intensifying because energy price volatility squeezes acid leaching margins. Container glass manufacturers exhibit highest price sensitivity, while solar panel producers prioritize optical clarity over unit economics.
Supply Chain Analysis
EU Green Deal carbon border adjustments function as export-control regime analogs, restricting furnace operator procurement to documented low-carbon beneficiation sources. Supply concentrates in Belgium, Germany, and Italy, with raw material dependencies on natural gas for thermal processing, sulfuric acid for leaching circuits, and specialized filtration media. Single-source vulnerability pervades the Ardennes-to-Dunkirk corridor where Saint-Gobain procurement draws from Sibelco captive reserves. Distribution runs through Rhine-Meuse-Scheldt delta port complexes serving Benelux and northern France float glass clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
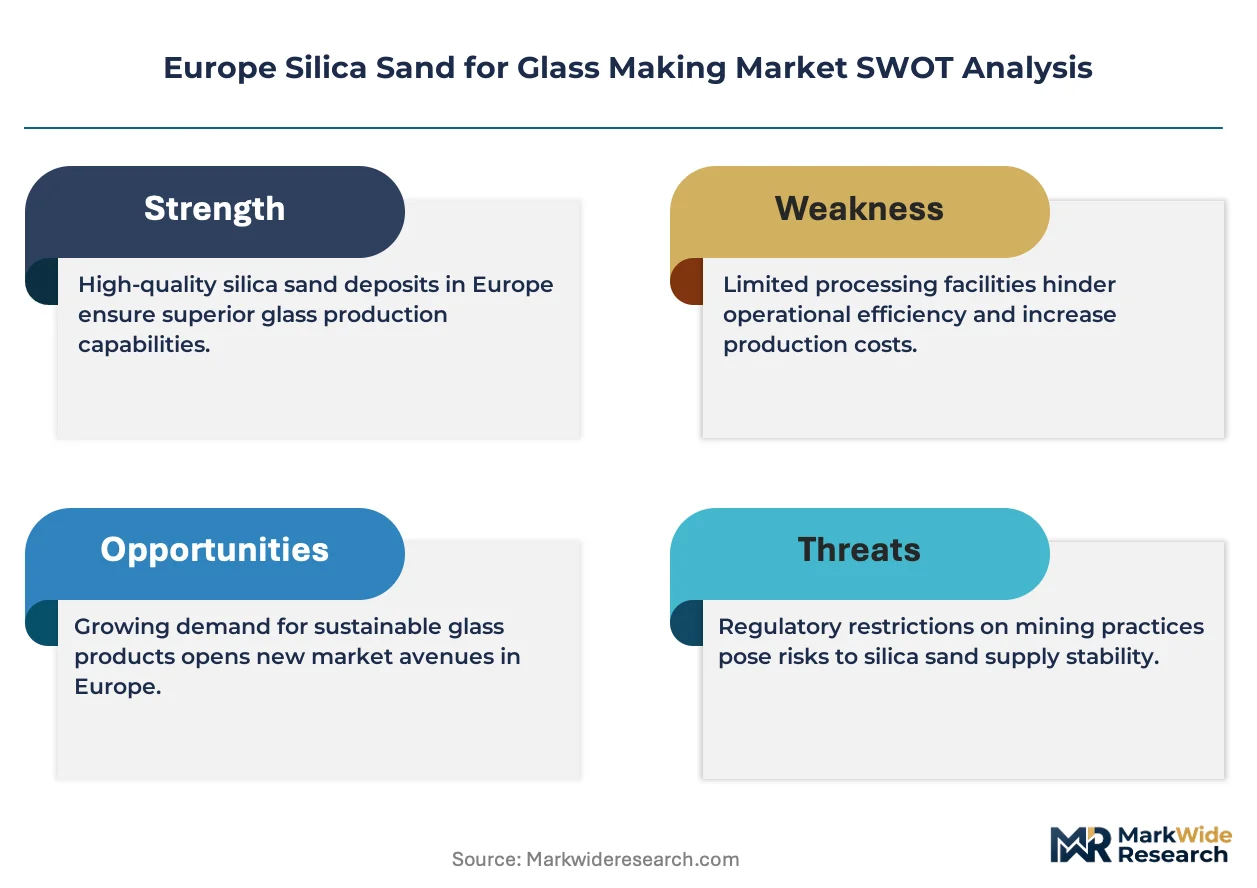
European silica sand markets constitute a defensive-moat story anchored in regulatory entrenchment. ECHA workplace exposure protocols and REACH registration requirements erect compliance barriers that favor incumbent processors with captive laboratory networks.
For Market Incumbents: Build certification moats through CSRD-aligned emissions tracking systems that pre-empt procurement audits from automotive OEM supply chains. Consolidate acid leaching capacity in Lower Rhine beneficiation corridors to capture container glass contract renewals. Vertical integration into optical sorting technology insulates against dry beneficiation retrofit competition from Eastern European entrants. For New Entrants and Emerging Players: Pursue solar glass white space in Poland and Czechia where photovoltaic manufacturing investments outpace local low-iron beneficiation capacity. Target Spanish Andalusian processing corridors as the most penetrable geography given expanding Castilla-La Mancha solar foundry demand. Lead with dry electrostatic separation go-to-market positioning that promises water and energy savings versus legacy wet-processing incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated quarry-beneficiation operators with verified carbon footprints. Long-term viability across the projection horizon rests on CSRD disclosure readiness and solar grade certification capabilities. Acquisition target archetype: mid-scale Ardennes or Lower Rhine processors with laboratory verification networks. The signal to watch is automotive OEM Tier 3 audit expansion into silica sand Scope 3 emissions documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quarry Reserves | Sibelco's Ardennes captive supply secures long-term Saint-Gobain float glass contracts against carbon border adjustment disruption. |
| Dry Beneficiation Technology Licensing | Electrostatic separation retrofits at wet-processing plants unlock water savings for ECHA compliance in water-stressed Mediterranean corridors. |
| CSRD-Aligned Emissions Certification | Transparent quarry-to-furnace tracking differentiates suppliers in BMW and Volkswagen supply chain audits. |
| Solar Grade Capacity Expansion | Sub-100 ppm iron oxide circuits in Eastern Europe capture photovoltaic demand from Polish and Czech manufacturing investments. |
| Long-Term Supply Agreements with Price Adjustment | Quarterly volume commitments with energy-cost clauses displace fixed-price contracts in French and Spanish float glass procurement. |
Research Methodology
The analysis maps container glass, flat glass, fiberglass, and specialty glass sub-sectors, each validated through glass furnace procurement managers, beneficiation plant operations directors, and ECHA regulatory affairs specialists. Primary interviews with Saint-Gobain and AGC supply chain executives combined with secondary validation through EU customs trade data, ECHA REACH registration databases, and Cefic chemical industry reports. Bottom-up volume modeling triangulated against top-down glass production capacity estimates across the projection horizon.
Assumptions held fixed include EU Green Deal carbon border adjustment implementation timelines and F-Gas Regulation phase-down schedules, while energy price trajectories and solar manufacturing capacity buildouts varied across scenarios. Segmentation dimensions modeled encompass grade tier, end-use application, and regional production cluster. CAGRs derived from production capacity expansion announcements and furnace utilization rates, with solar glass specification tightening and automotive OEM audit expansion as key industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing and electricity cost volatility would shift the trajectory for acid leaching and thermal beneficiation economics. Forecasts reflect documented assumptions on regulatory compliance cost pass-through and photovoltaic manufacturing reshoring momentum. Material shifts in ECHA crystalline silica exposure limit enforcement or EU carbon border adjustment scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glass Vials Market
Glass
Global Glass Tempering System Market
Glass
Glass Mat Thermoplastic Market
Glass
Patterned Glass Market
Glass
Coated Solar Control Glass Market
Glass
Solar PV Glass Market
Glass
Glass Balustrade Lamination Market
Glass
Solar Reflective Glass Market
Glass
Optical Glass Market
Glass
Optical Lens Material Market
Glass
Europe Flat Glass Market
Glass
Glass Insulator Market
Glass
Europe Sapphire Glass Market
Glass
Global Flat Glass Market
Glass
Silica Sand Market
Glass
Global Glass Flake Coatings Market