
 Carrageenan Film Market | 2026-2036
Carrageenan Film Market Size, Share, and Industry Trends Forecast 2026-2036
Carrageenan Film Market Outlook
Biopolymer extraction and film-casting technology is fragmenting as batch processors, continuous casters, and electrospinning lines compete for different end-use specifications. Cargill leverages its hydrocolloid supply chain to secure captive kappa-carrageenan feedstock for film-grade material. MCPI Corporation anchors Philippine production with integrated seaweed farming and refining operations near Tawi-Tawi.
Carrageenan film denotes a thin, flexible barrier manufactured from sulfated galactan polysaccharides extracted from red seaweed, typically 50-200 microns thick, with oxygen permeability ranging from 0.5 to 5.0 cm³ μm/m² day kPa depending on plasticizer content and cation crosslinking. These films function primarily as moisture-regulating, gas-selective barriers in food and pharmaceutical packaging where synthetic polymer replacement drives specification. Edible films carry the broadest volume base due to direct food-contact approval and dissolution in aqueous environments, while composite films command margin premiums through layered hydrocolloid-protein architectures that extend shelf stability. Pharmaceutical packaging applications are gaining fastest traction as blister-compatible formulations meet USP Class VI biocompatibility thresholds.
The FDA governs food-contact substances under 21 CFR 175.105 and 176.170, while the EU EFSA evaluates novel food-contact materials including seaweed-derived barriers under the Framework Regulation EC 1935/2004. BIS in India mandates migration testing for packaging films in contact with fatty foods, creating compliance cost tiers that favor exporters with certified laboratory networks. Stakeholders must track evolving compostability certifications and marine biodegradability standards as procurement specifications harden.
Market Dynamics
Food processors in Indonesia and the Philippines are dismantling synthetic packaging contracts as EU Packaging and Packaging Waste Regulation enforcement hardens. Marine-derived barriers now compete directly with petroleum-based films on total cost of ownership.
Growth Catalysts
- EU EFSA Framework Regulation EC 1935/2004:Novel food-contact material approvals for seaweed-derived barriers accelerate procurement timelines for European food brands seeking synthetic alternatives.
- Seaweed farming clusters:Integrated cultivation-to-refining operations in Tawi-Tawi and Sulawesi secure captive kappa-carrageenan feedstock at scale for film-grade extraction.
- Electrospinning line deployment:Continuous nanofiber casting technology reduces oxygen permeability variance below 0.3 cm³ μm/m² day kPa for pharmaceutical blister applications.
Market Restraints
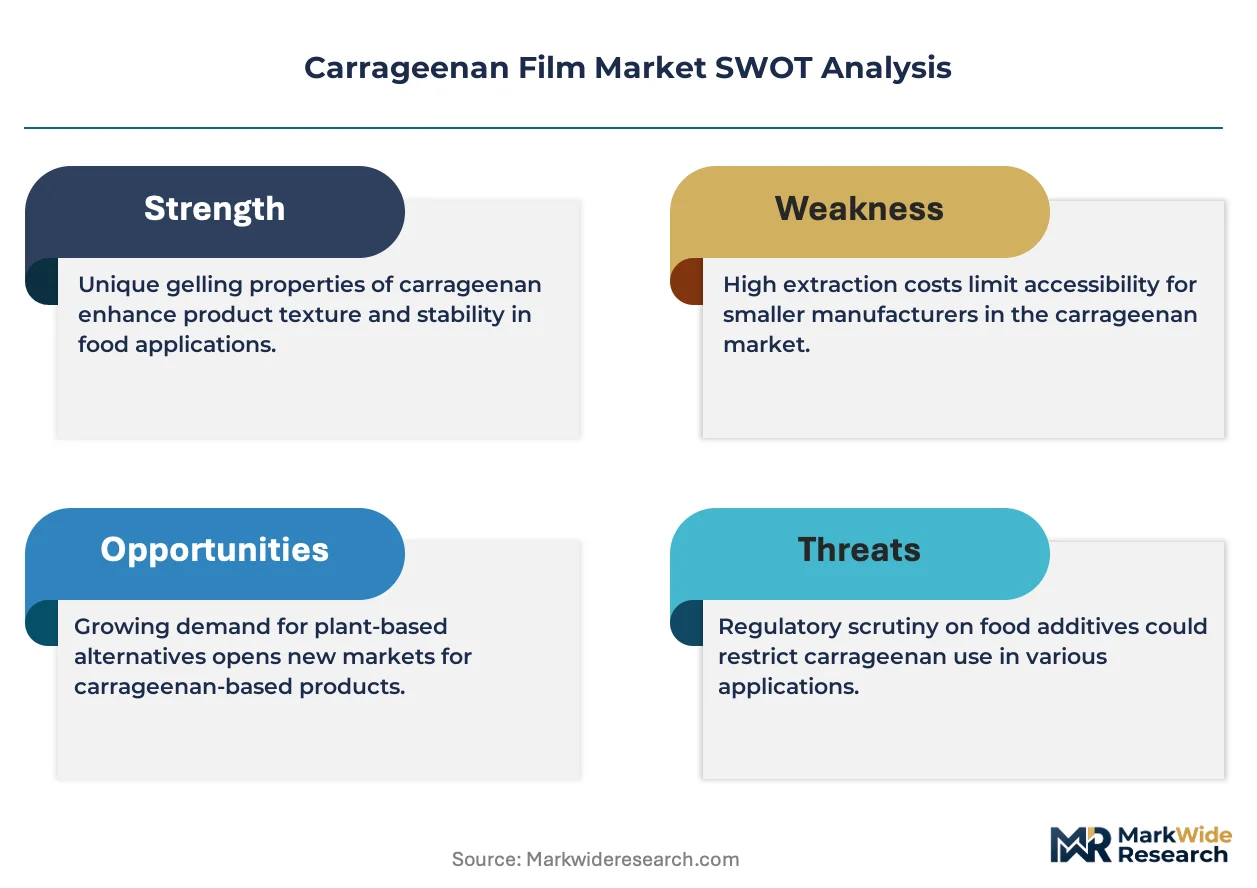
- Red seaweed supply concentration:Kappaphycus alvarezii harvest volatility in the Sulu Sea creates raw material price swings that compress processor margins.
- Batch processing legacy infrastructure:Film-casting equipment designed for synthetic polymers requires retrofit capital exceeding $2 million per line for hydrocolloid compatibility.
- BIS migration testing mandates:India's fatty food-contact certification adds 14-18 week compliance timelines that disadvantage small-batch exporters without certified laboratory networks.
Strategic Opportunities
- Pharmaceutical blister packaging:USP Class VI biocompatibility thresholds create premium positioning for carrageenan-polyvinyl alcohol composite films in Southeast Asian manufacturing.
- Marine biodegradability certification:TÜV Austria OK biodegradable MARINE and BPI compostability standards unlock municipal procurement channels in coastal European cities.
- Protein-hydrocolloid lamination:Layered gelatin-carrageenan architectures extend refrigerated meat shelf stability, capturing share from ethylene vinyl alcohol copolymers in ASEAN cold chains.
Industry Challenges
- Crosslinking chemistry expertise:Potassium chloride and calcium lactate cation selection for film mechanical properties requires polymer scientists with marine polysaccharide specialization, a talent pool concentrated in Philippine state universities.
- Compostability audit fragmentation:Divergent home versus industrial composting certification requirements across German DIN, Australian AS, and American ASTM standards force redundant testing budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carrageenan Film Market |
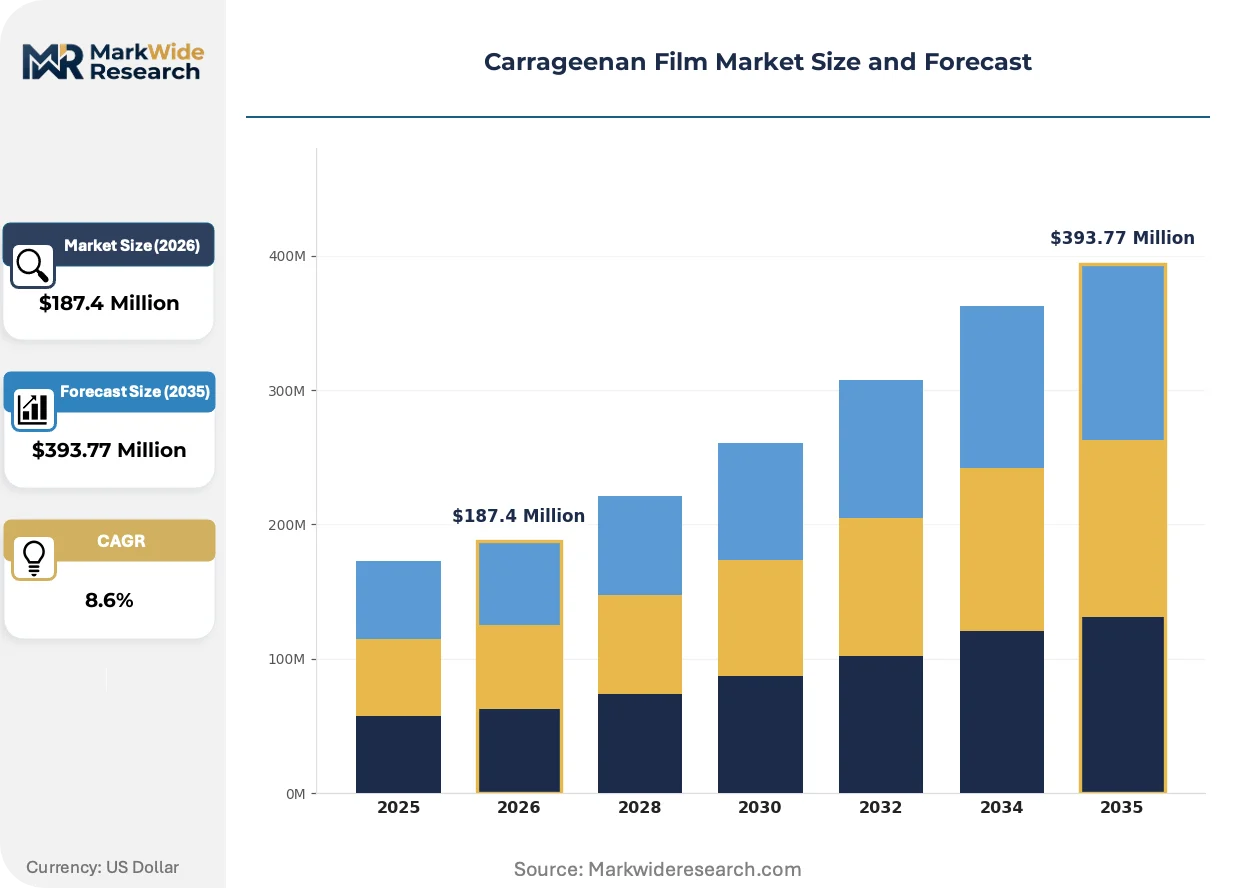
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Edible Films, Non-Edible Films, Coatings, Laminates Application: Food Preservation, Pharmaceutical Packaging, Cosmetics, Agriculture Formulation: Hydrocolloid-Based, Composite Films, Biodegradable Options, Thermoplastic Composites End User: Food Industry, Healthcare, Personal Care, Agricultural Sector |
| Companies Covered | Cargill, MCPI Corporation, CP Kelco, Marcel Carrageenan, TBK Manufacturing Corporation, DuPont, Ingredion, CEAMSA, Gelymar S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carrageenan Film Market Strategic Shifts
Film manufacturing is fragmenting across three competing process architectures. Each technology trajectory serves distinct end-use specifications with irreversible capital commitments.
Electrospun nanofiber membranes are migrating from laboratory-scale pilot lines to continuous production systems. Pharmaceutical packaging buyers in Germany and Switzerland now specify sub-100 nanometer fiber diameters for moisture-regulating blister packs. This migration from batch casting to roll-to-roll nanofiber production compresses lead times from 12 weeks to 72 hours for custom barrier specifications.
REACH Annex XVII restrictions on microplastics in single-use items force reformulation of conventional multilayer films. ECHA enforcement timelines accelerate substitution mandates for petroleum-derived barriers in food-contact applications. Dutch and Danish retailers now require marine biodegradability documentation for private-label packaging, shifting procurement specifications upstream to raw material suppliers.
Direct farm-to-processor contracting is replacing spot market seaweed purchasing. Indonesian and Philippine farming cooperatives now negotiate three-year offtake agreements with fixed kappa-content specifications. This behavioral shift concentrates supply planning functions within processor procurement teams and marginalizes independent traders in the Tawi-Tawi and South Sulawesi supply corridors.
Carrageenan Film Market Segmentation
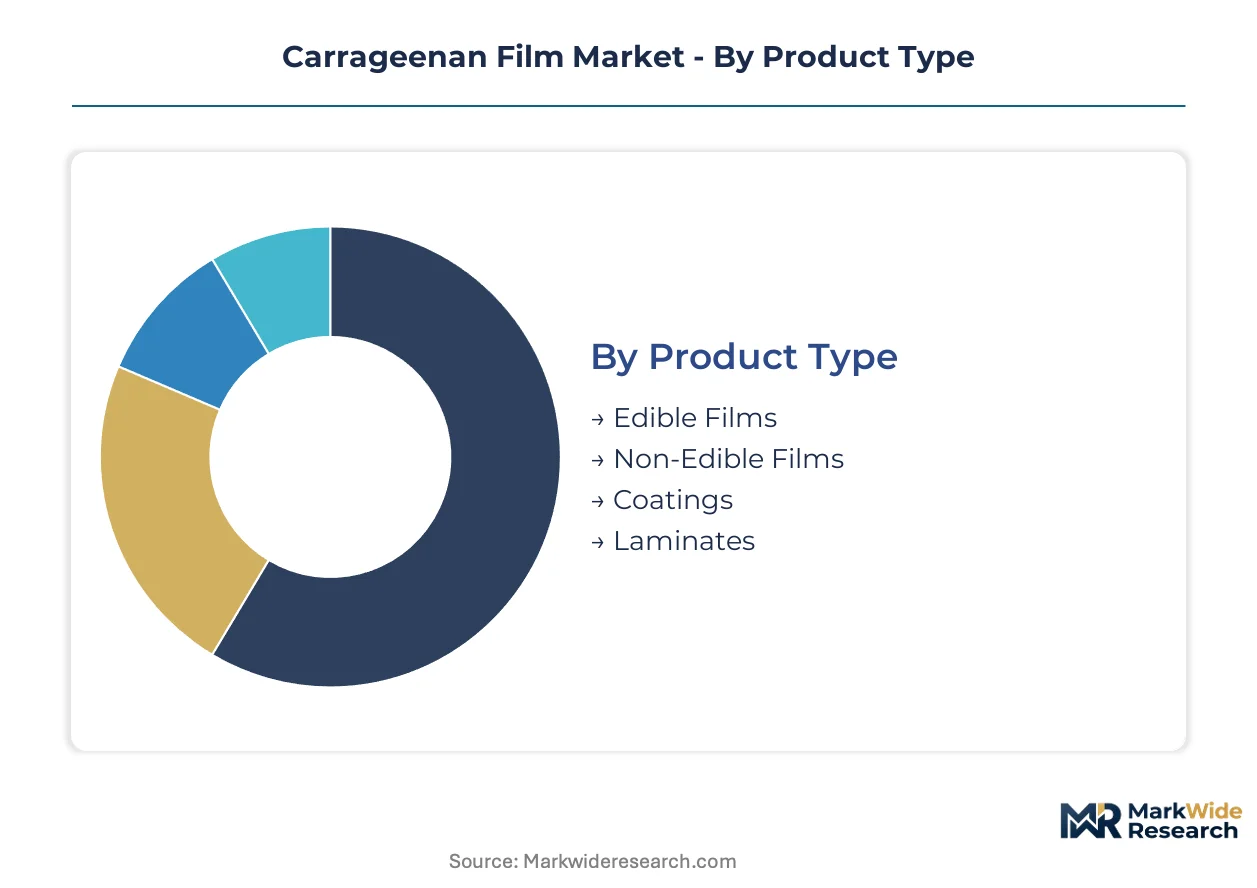
Carrageenan film specifications diverge sharply across end-use requirements, with pharmaceutical and food-contact applications demanding incompatible testing protocols and certification timelines. Procurement teams navigate four distinct segmentation axes where technical specifications, regulatory pathways, and supply chain configurations intersect differently.
Product Type:
Cycle times range from immediate dissolution for edible formats to multi-year qualification runs for pharmaceutical laminates, compressing or extending capital recovery windows accordingly.
- Edible Films:Direct food-contact formulations dissolve in aqueous environments within 30-120 seconds, enabling single-serve packaging for instant noodle seasonings and confectionery in Indonesia and Vietnam. Demand clusters with ASEAN food processors dismantling synthetic wrap contracts under EU Packaging and Packaging Waste Regulation enforcement timelines.
- Non-Edible Films:Barrier specifications prioritize oxygen permeability below 1.0 cm³ μm/m² day kPa through potassium chloride crosslinking, serving pharmaceutical blister applications where USP Class VI biocompatibility thresholds create 18-24 month approval cycles. German and Swiss buyers now specify sub-100 nanometer fiber diameters from continuous electrospinning lines.
- Coatings:Surface-applied hydrocolloid layers extend refrigerated meat shelf stability in Philippine cold chains, competing with ethylene vinyl alcohol copolymers on total cost of ownership.
- Laminates:Layered gelatin-carrageenan architectures command margin premiums through protein-hydrocolloid synergies in premium cosmetic packaging.
Edible films anchor the volume base while non-edible formats gain share at the steepest rate as pharmaceutical qualification pipelines mature.
Application:
Margin structures invert across applications, with food preservation running on thin conversion spreads and pharmaceutical packaging capturing certification-premium pricing tiers.
- Food Preservation:Moisture-regulating barriers for fresh produce and seafood dominate procurement volumes in Indonesian and Philippine processing corridors, where farm-to-processor contracting now replaces spot market seaweed purchasing.
- Pharmaceutical Packaging:Blister-compatible formulations meeting USP Class VI thresholds attract Southeast Asian manufacturing investment from European generics producers seeking EMA-aligned supply chains.
- Cosmetics:Marine biodegradability documentation from TÜV Austria OK biodegradable MARINE unlocks Dutch and Danish retailer procurement channels for private-label skincare packaging.
- Agriculture:Seed coating and controlled-release fertilizer applications remain nascent, constrained by BIS migration testing mandates for soil-contact materials in India.
Food preservation generates the highest absolute volumes while pharmaceutical packaging delivers the steepest margin expansion trajectory.
Formulation:
Raw material sourcing strategies bifurcate between captive seaweed farming operations and spot market hydrocolloid purchasing, with formulation choice locking in supply chain configurations.
- Hydrocolloid-Based:Kappa-carrageenan extraction from Kappaphycus alvarezii dominates Philippine production through integrated Tawi-Tawi farming and refining operations, securing feedstock at fixed kappa-content specifications.
- Composite Films:Layered hydrocolloid-protein architectures extend shelf stability beyond single-component barriers, capturing share from synthetic multilayer films as REACH Annex XVII microplastic restrictions harden.
- Biodegradable Options:Marine biodegradability certification to BPI and TÜV Austria standards enables municipal procurement in coastal European cities with organic waste diversion mandates.
- Thermoplastic Composites:Carrageenan-polyvinyl alcohol blends for heat-sealable pharmaceutical applications require retrofit capital exceeding $2 million per line for hydrocolloid compatibility.
Hydrocolloid-based formulations retain volume leadership while composite films climb the fastest as layered architectures displace conventional multilayer petroleum-derived barriers.
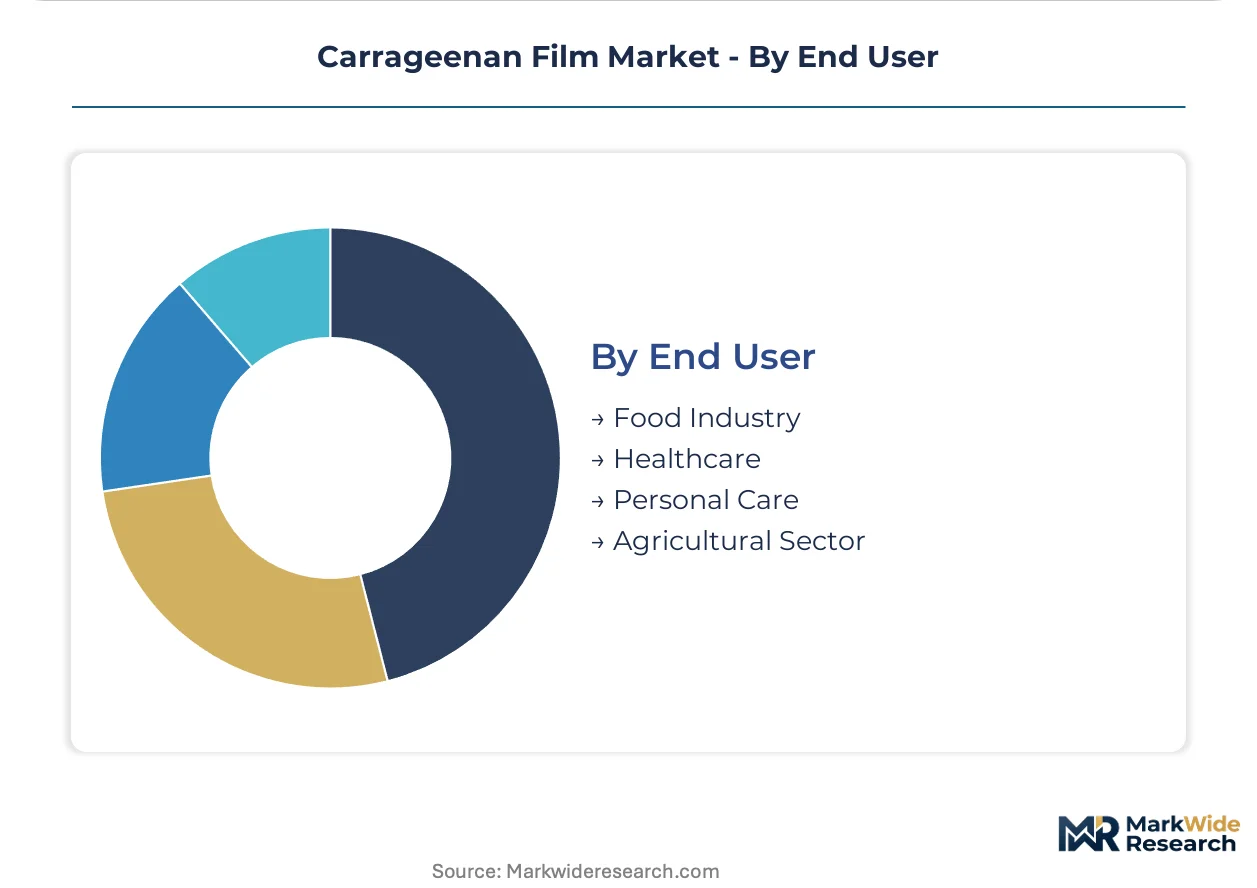
End User:
Procurement sophistication varies dramatically, with healthcare buyers demanding audit trails from seaweed farm to finished film while agricultural purchasers prioritize unit cost minimization.
- Food Industry:Southeast Asian processors in Indonesia and the Philippines are dismantling synthetic packaging contracts as EU enforcement hardens, with three-year offtake agreements now standard for kappa-content specifications.
- Healthcare:Pharmaceutical manufacturers specify continuous nanofiber casting technology with oxygen permeability variance below 0.3 cm³ μm/m² day kPa, compressing lead times from 12 weeks to 72 hours for custom barrier specifications.
- Personal Care:Cosmetic brands require marine biodegradability documentation upstream to raw material suppliers as Dutch and Danish retailers shift procurement specifications.
- Agricultural Sector:Seed coating applications remain price-sensitive, with Indian BIS fatty food-contact certification adding 14-18 week compliance timelines that disadvantage small-batch exporters.
Food industry procurement anchors volume while healthcare demand expands most quickly as pharmaceutical qualification pipelines accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Philippine exports of refined kappa-carrageenan feedstock supply German pharmaceutical blister manufacturers and Dutch food packaging converters. The Sulu-to-Rotterdam corridor dominates maritime hydrocolloid trade flows. Indonesian farming cooperatives now ship semi-processed seaweed directly to Vietnamese film-casting facilities.
Germany
Pharmaceutical packaging buyers in Frankfurt and Basel specify sub-100 nanometer fiber diameters for moisture-regulating blister packs. ECHA enforces REACH Annex XVII microplastic restrictions on conventional multilayer films. Continuous electrospinning line deployment near Düsseldorf compresses custom barrier lead times from 12 weeks to 72 hours.
Philippines
Integrated seaweed farming and refining operations in Tawi-Tawi secure captive kappa-carrageenan at fixed content specifications. The national Food and Drug Administration aligns with USP Class VI biocompatibility thresholds for export qualification. MCPI Corporation anchors production capacity through three-year offtake agreements with Sulawesi farming cooperatives.
Netherlands
Dutch retailers require marine biodegradability documentation upstream to raw material suppliers for private-label packaging. The EU Packaging and Packaging Waste Regulation enforcement hardens procurement specifications for petroleum-based plastic alternatives. Rotterdam logistics hubs coordinate distribution to coastal European cities with organic waste diversion mandates.
Indonesia
Farm-to-processor contracting replaces spot market purchasing across Sulawesi and South Kalimantan seaweed clusters. BIS migration testing mandates for fatty food-contact materials add compliance timelines that disadvantage small-batch exporters. Surabaya film-casting facilities retrofit synthetic polymer lines for hydrocolloid compatibility at capital exceeding $2 million per installation.
Switzerland
Swissmedic pharmaceutical packaging standards attract Southeast Asian manufacturing investment from European generics producers. Swiss buyers specify oxygen permeability variance below 0.3 cm³ μm/m² day kPa for barrier applications. Basel-area procurement teams audit supply chains from seaweed farm to finished film for EMA-aligned qualification.
Carrageenan Film Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent technology trajectories. The vendor base separates into consolidated hydrocolloid suppliers with captive seaweed farming and batch-processing equipment fabricators serving niche pharmaceutical specifications. Three archetypes dominate: integrated farming-to-refining operators, continuous casting technology licensors, and composite formulation specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves as qualification timelines extend.
Within the integrated operator archetype, Cargill and MCPI Corporation exemplify channel-controlling positions through upstream feedstock security. CP Kelco occupies a specialist tier focused on kappa-carrageenan extraction for film-grade applications. These three entities represent contrasting geographic and structural configurations: a diversified agribusiness conglomerate, a Philippine-based integrated operator, and a hydrocolloid-focused extraction specialist.
| Leading Market Players |
|---|
| Cargill |
| MCPI Corporation |
| CP Kelco |
| Marcel Carrageenan |
| TBK Manufacturing Corporation |
| DuPont |
| Ingredion |
| CEAMSA |
| Gelymar S.A. |
| Others |
Value Chain & Pricing Dynamics
Red seaweed harvest volatility in the Sulu Sea compresses processor margins while simultaneously widening pricing spreads between spot-market dependent and vertically integrated producers. This raw material instability forces buyers into three-year offtake agreements with fixed kappa-content specifications, reshaping procurement cost structures across edible and pharmaceutical-grade tiers.
Pricing Analysis
Batch casting equipment retrofits versus continuous electrospinning line deployment creates a technology-generation pricing gap that stratifies market tiers. Three-tier pricing structure across pharmaceutical-grade, food-contact certified, and edible commodity levels reflects oxygen permeability variance and USP Class VI qualification status. Cost compression in edible film segments stems from Indonesian farming cooperative expansion, while pharmaceutical buyers show minimal price sensitivity due to 18-24 month approval cycle investments. Food processors in ASEAN cold chains exhibit highest price elasticity, switching between gelatin-carrageenan laminates and synthetic alternatives on total cost of ownership calculations.
Supply Chain Analysis
Extended payment terms from Dutch and German pharmaceutical buyers now stretch Philippine processor working capital cycles, accelerating supply-chain finance facility adoption. Raw material sourcing draws from Tawi-Tawi, Sulawesi, and South Kalimantan seaweed clusters, with kappa-carrageenan extraction feeding film-grade refining operations. Kappaphycus alvarezii supply concentration in Philippine and Indonesian waters creates single-source vulnerability during monsoon harvest disruptions. Distribution runs through Rotterdam logistics hubs for European pharmaceutical and food packaging converters, with Surabaya film-casting facilities serving ASEAN regional demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation enforcement fragments procurement specifications across marine biodegradability tiers, creating specialist niches for certified producers and technology licensors alike. This regulatory-driven demand segmentation rewards focused capability development over broad synthetic film replacement strategies.
For Market Incumbents: Entrench feedstock security through captive seaweed farming expansion in Tawi-Tawi and Sulawesi corridors, locking in kappa-content specifications ahead of harvest volatility. Deepen pharmaceutical qualification pipelines by investing in continuous electrospinning capacity near Basel and Frankfurt, compressing custom barrier lead times against batch-processing competitors. Certification investment in TÜV Austria OK biodegradable MARINE standards opens municipal procurement channels that synthetic film incumbents cannot access. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical blister packaging applications where USP Class VI biocompatibility thresholds create 18-24 month qualification barriers for commodity producers. Target white-space opportunities in protein-hydrocolloid lamination for refrigerated meat shelf extension, displacing ethylene vinyl alcohol copolymers in ASEAN cold chains. Go-to-market leverage rests on direct farm-to-processor contracting with Indonesian cooperatives, bypassing spot market price swings that compress legacy processor margins. For Investors and Strategic Acquirers: REACH Annex XVII microplastic restriction timelines reshape the acquisition landscape toward electrospinning technology licensors and integrated farming-to-refining operators with marine biodegradability certifications. Long-term viability across the analysis window favors targets with backward integration into seaweed cultivation and established European pharmaceutical buyer relationships. Watch ECHA enforcement acceleration against conventional multilayer films as the primary inflection signal for substitution-driven demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Farming | Captive kappa-carrageenan supply from Tawi-Tawi insulates processors against Sulu Sea harvest volatility. |
| Continuous Electrospinning Line Deployment | Roll-to-roll nanofiber production near Düsseldorf compresses pharmaceutical barrier lead times from weeks to hours. |
| Marine Biodegradability Certification | TÜV Austria OK biodegradable MARINE unlocks Dutch municipal procurement with organic waste diversion mandates. |
| Pharmaceutical Qualification Pipeline Investment | USP Class VI biocompatibility approval cycles secure premium positioning with Swissmedic-regulated buyers. |
| Direct Farm-to-Processor Contracting | Three-year offtake agreements with Sulawesi cooperatives replace spot market purchasing and stabilize input costs. |
Study Parameters
Operator-level perspectives from seaweed farm managers, film-casting plant engineers, pharmaceutical packaging procurement leads, and EU regulatory affairs specialists anchored the qualitative base for this analysis. Primary fieldwork combined with secondary validation from EFSA framework documentation, BIS migration testing protocols, FDA 21 CFR food-contact substance filings, and customs trade data for hydrocolloid exports. Bottom-up capacity assessments across Philippine and Indonesian refining operations were triangulated against top-down demand modeling from European pharmaceutical and food packaging end-use sectors.
Scenario-bracketing around REACH Annex XVII enforcement timelines, red seaweed harvest volatility bands, and pharmaceutical qualification pipeline maturities framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, application, formulation chemistry, and end-user procurement sophistication, with regional regulatory cluster variations capturing EU, Indian, and ASEAN compliance pathway differences. CAGRs were derived from installed capacity expansion schedules, substitution elasticity estimates for synthetic film displacement, and buyer switching cost assessments in pharmaceutical blister packaging.
Stress conditions across Sulu Sea monsoon intensity, ECHA microplastic restriction acceleration, and potassium chloride crosslinking chemistry talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding farm-to-processor contracting adoption rates and electrospinning technology diffusion curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
EVA Interlayer for Photovoltaic Market
Specialty Materials
Jesmonite Market
Specialty Materials
Ballistic Protection Materials Market
Specialty Materials
Absorbent Booms and Socks Market
Specialty Materials
Europe Acrylic Sheet Market
Specialty Materials
Specialty Silicone Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
Polyphenylsulfone Market
Specialty Materials
Alginate Films Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Carbon Mold Market
Specialty Materials
Global Montan Wax Market
Specialty Materials
Erbium-169 Market
Specialty Materials
Europe Microspheres Market
Specialty Materials
Silicone Film Market
Specialty Materials
ePTFE Electronic Film Market