
 Hornbeam Market | 2026-2036
Hornbeam Market Size, Share, and Industry Trends Forecast 2026-2036
Hornbeam Market Foresight
Furniture manufacturing is pivoting toward denser hardwoods as oak prices climb and consumers seek distinctive grain patterns. DoTerra International leverages its botanical sourcing infrastructure to secure hornbeam-derived extracts for aromatherapy formulations. Young Living Essential Oils sustains competitive pressure through vertical control over distillation partnerships in Eastern European supply zones. Healingherbs Ltd. anchors its market position with specialized Bach flower remedy applications using Carpinus betulus extracts.
Hornbeam (Carpinus betulus) is a dense, fine-grained deciduous hardwood with a Janka hardness exceeding 2,000 lbf, making it suitable for wear-resistant applications where maple or birch fall short. The timber's interlocked grain and exceptional shock resistance serve tool handle manufacturers and piano action components. Lumber and veneer segments dominate volume flows, with premium-grade material commanding margin pools in musical instrument fabrication. Hardwood destined for flooring competes on density credentials against imported tropical species facing sustainability scrutiny. Industrial-grade hornbeam supplies plywood mills serving mass cabinetry producers, though this tier faces margin compression from engineered wood substitutes.
The EU Timber Regulation (EUTR) and Forest Stewardship Council (FSC) chain-of-custody standards shape market access across European trading blocs, with non-compliant shipments facing border detention. Germany's KBA and France's CNIL do not regulate this sector, though national forestry codes in Poland and Romania govern harvesting quotas and replanting mandates. Stakeholders must monitor evolving EU Deforestation Regulation (EUDR) geolocation requirements that will tighten traceability obligations for hornbeam processors sourcing from mixed forest stands.
Market Dynamics
The EU Deforestation Regulation (EUDR) geolocation mandates are forcing processors to rebuild traceability systems for mixed forest stands, compressing margins for small-scale Polish and Romanian suppliers unable to fund compliance infrastructure.
Growth Catalysts
- EUDR Traceability Mandates:Large German furniture manufacturers are consolidating procurement around certified suppliers, accelerating chain-of-custody investments across Podlaskie forestry cooperatives.
- Oak Price Escalation:European furniture makers are reformulating product lines around hornbeam's comparable density and distinctive grain, redirecting volume from traditional oak specifications.
- Sustainable Forestry Cooperatives:Poland's Warmia-Mazury region has scaled certified harvesting capacity through cooperative aggregation models that pool smallholder quotas.
Market Restraints
- Supply Concentration Risk:Premium-grade hornbeam suitable for musical instrument action components concentrates in specific Polish forest districts, creating single-source vulnerability for Steinway and Bösendorfer suppliers.
- Engineered Wood Substitution:Mass cabinetry producers in Romania and Bulgaria are displacing industrial-grade hornbeam plywood with oriented strand board and medium-density fiberboard in cost-sensitive specifications.
- EUTR Documentation Burden:Due diligence requirements impose fixed compliance costs that disproportionately burden traders moving volumes below 500 cubic meters annually.
Strategic Opportunities
- Underpenetrated German Tool Handle Segment:Hand tool manufacturers in Solingen and Remscheid are testing hornbeam against traditional hickory for chisel and plane handles, with initial trials showing superior shock absorption.
- EU Green Deal Public Procurement:National government furniture tenders in Austria and Czechia are mandating FSC-certified domestic hardwoods, creating preferential market access for compliant hornbeam suppliers.
- Digital Chain-of-Custody Platforms:Blockchain-enabled timber tracking systems are converging with satellite forest monitoring, enabling real-time geolocation verification that satisfies emerging EUDR requirements.
Industry Challenges
- Specialized Sawmilling Skill Shortage:Interlocked grain patterns require experienced sawyers to prevent tear-out during processing, and training programs in Eastern European forestry regions have not kept pace with retirement rates.
- FSC Certification Timeline Compression:Group certification audits for smallholder cooperatives now face 18-month backlogs, delaying market access for new Polish entrants seeking to supply German manufacturers.
- Kiln Drying Infrastructure Gap:Investment in controlled drying facilities capable of handling hornbeam's high initial moisture content exceeds the capital capacity of most Romanian independent sawmills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hornbeam Market |
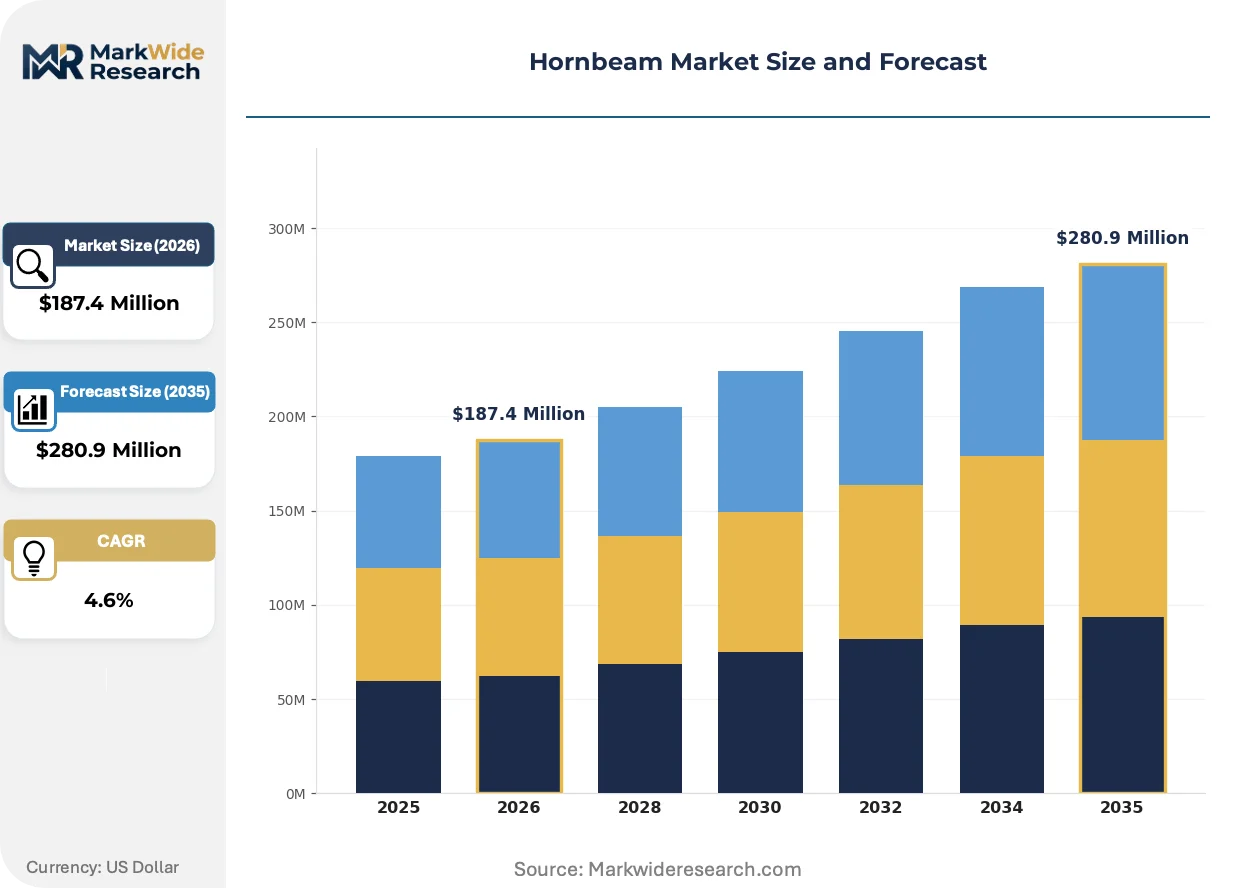
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardwood, Lumber, Plywood, Veneer Application: Furniture, Flooring, Cabinetry, Musical Instruments End User: Manufacturers, Carpenters, Artisans, Retailers Quality Grade: Premium, Select, Industrial, Standard |
| Companies Covered | India Aroma Oils and Company, The Bach Centre, India Essential Oils, DoTerra International, Young Living Essential Oils, Healingherbs Ltd., Bio Lonreco, Elma Skin Care, Totally Natural Skincare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hornbeam Market Shifts & Advancements
Processing technology and verification systems are restructuring competitive advantage in European hardwood supply chains. Innovations concentrate on traceability automation and precision manufacturing that reduce yield loss.
Near-infrared spectroscopy for real-time density grading is decentralizing quality assessment from centralized laboratories to sawmill lines. Austrian veneer producers are adopting portable NIR units to sort incoming logs before cutting, reducing premium-grade waste by enabling precise cutting pattern selection. This technology is decentralizing decision authority from quality control managers to floor operators.
The EU Deforestation Regulation's phased implementation through 2025 is mandating polygon-level geolocation for all timber placements. German importers are requiring suppliers to submit GPS coordinates of harvest sites before contract execution, shifting compliance verification upstream. Musical instrument manufacturers face the strictest documentation requirements, with some Steinway suppliers investing in drone-based forest mapping to satisfy due diligence protocols.
Direct mill-to-manufacturer contracting is displacing traditional timber auction systems in Poland and Romania. Large German furniture groups are negotiating multi-year offtake agreements with specific forestry cooperatives, bypassing wholesale traders. This pattern is most visible in the chair frame segment, where Thonet and other established manufacturers seek supply security amid tightening certified timber availability.
Hornbeam Market Segmentation
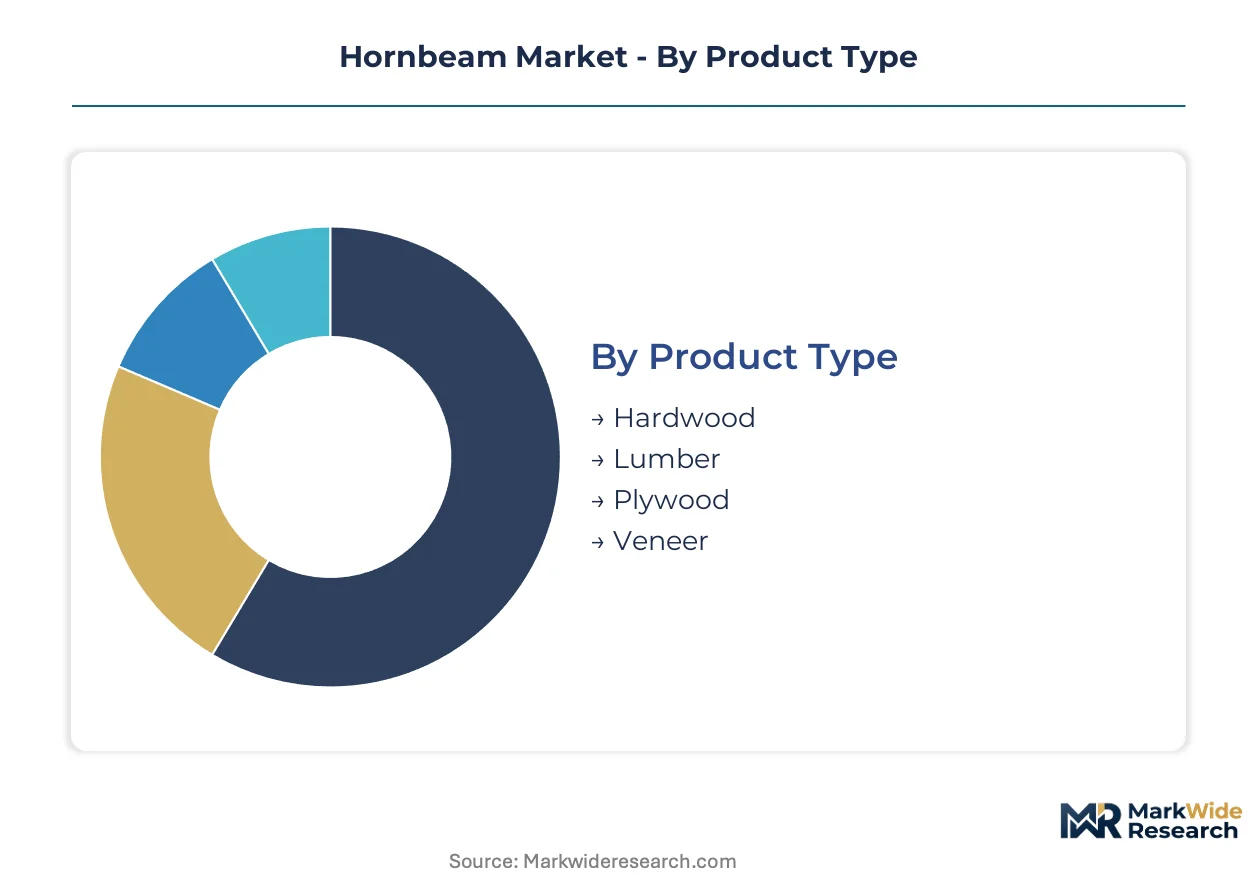
Hornbeam's density variability and certification requirements create sharp tier boundaries that reshape procurement economics. Segmentation reveals where FSC chain-of-custody investments concentrate and which grades escape EUDR documentation burdens.
Product Type:
FSC certification burdens fall heaviest on veneer and lumber exports to German furniture manufacturers, while plywood bound for Romanian cabinetry faces lighter documentation thresholds.
- Hardwood:Raw timber with Janka hardness exceeding 2,000 lbf serves tool handle manufacturers in Solingen and Remscheid. Polish forestry cooperatives in Podlaskie supply certified volumes to Austrian hand tool producers facing EU Green Deal procurement mandates.
- Lumber:Dimension stock graded for furniture frames commands premium positioning among Thonet and other German chair manufacturers reformulating product lines away from escalating oak prices. Interlocked grain requires specialized sawmilling skill concentrated in aging Polish sawyer cohorts.
- Plywood:Industrial-grade material feeds mass cabinetry producers in Romania and Bulgaria, though oriented strand board substitution compresses margins in cost-sensitive specifications.
- Veneer:Thin-sliced decorative faces for premium furniture applications. Austrian producers deploy portable near-infrared spectroscopy units to sort incoming logs before cutting, reducing waste through precise cutting pattern selection.
Leading the category by volume: Lumber. Growing fastest: Veneer.
Application:
End-use differentiation tracks density requirements and surface finish specifications that determine which grades qualify.
- Furniture:Chair frames and structural components leverage hornbeam's shock resistance and distinctive grain patterns. German manufacturers in Thuringia and Bavaria are expanding procurement as oak prices climb.
- Flooring:Wear-resistant surfaces compete against tropical imports facing sustainability scrutiny. Density credentials support positioning in premium residential segments.
- Cabinetry:Mass producers in Romania and Bulgaria favor industrial-grade plywood, though engineered wood substitutes capture cost-sensitive volume.
- Musical Instruments:Piano action components require premium-grade material with specific grain orientation. Steinway and Bösendorfer suppliers face strictest EUDR documentation requirements, with some investing in drone-based forest mapping.
Dominant by revenue: Furniture. Expanding most quickly: Musical Instruments.
End User:
Customer type determines contract structure, with large manufacturers negotiating multi-year offtake agreements while artisans purchase through fragmented wholesale channels.
- Manufacturers:Large German furniture groups and tool producers negotiate direct mill-to-manufacturer contracts, bypassing traditional timber auction systems. Multi-year agreements with Polish forestry cooperatives secure certified supply amid tightening availability.
- Carpenters:Small-scale builders and contractors purchase through regional distributors. EUTR documentation burdens disproportionately burden traders moving volumes below 500 cubic meters annually.
- Artisans:Custom furniture makers and luthiers seek premium and select grades with specific aesthetic characteristics. Limited volume requirements exclude them from direct cooperative purchasing.
- Retailers:Home improvement chains and specialty wood suppliers stock standard and industrial grades for consumer DIY segments.
Largest volume concentration: Manufacturers. Fastest channel expansion: Artisans.
Quality Grade:
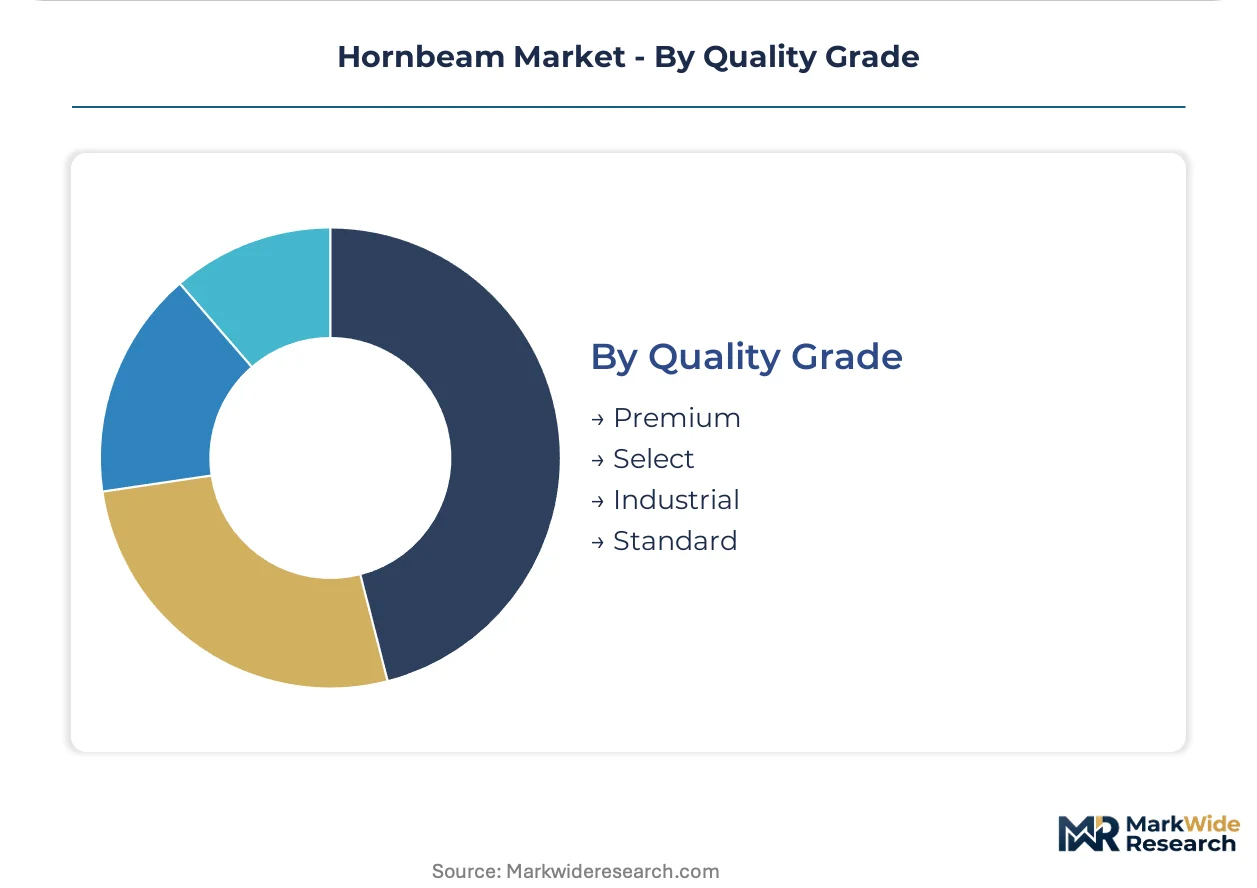
Grade boundaries align with end-use performance requirements and certification tiers that determine market access.
- Premium:Defect-free material with straight grain and uniform color for musical instrument action components and high-end veneer. Supply concentrates in specific Polish forest districts, creating single-source vulnerability.
- Select:Minimal defects suitable for visible furniture surfaces and flooring. Warmia-Mazury cooperatives have scaled certified harvesting capacity through aggregation models.
- Industrial:Sound knots and color variation acceptable for structural plywood and hidden components. Faces margin compression from engineered wood substitutes.
- Standard:General construction grade with permitted defects for non-structural applications and secondary processing.
Highest margin pool: Premium. Steepest expansion trajectory: Select.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's Podlaskie Special Economic Zone incentives have concentrated hornbeam processing capacity near Białystok, drawing German furniture manufacturers seeking EUTR-compliant supply chains. This zone structure replicates across Austrian and Romanian border regions where EU Cohesion Fund grants support certified timber infrastructure.
Poland
Furniture frame manufacturers in Warmia-Mazury source certified hornbeam through cooperative aggregation models. The country's State Forests National Forest Holding administers harvesting quotas under strict replanting mandates. Białystok sawmills process premium-grade material for Steinway piano action components, facing EUDR geolocation documentation requirements.
Germany
Solingen hand tool producers test hornbeam against hickory for chisel handles, driven by EU Green Deal public procurement mandates for FSC-certified domestic hardwoods. The KBA does not regulate this sector. Thuringia and Bavaria furniture clusters negotiate multi-year offtake agreements directly with Polish forestry cooperatives, bypassing wholesale auction systems.
Austria
Vienna-based veneer producers deploy portable near-infrared spectroscopy units to sort incoming Polish hornbeam logs before cutting. The country's Federal Ministry of Agriculture and Forestry enforces chain-of-custody standards aligned with EU Timber Regulation. Upper Austrian cabinetry manufacturers face margin pressure from engineered wood substitutes in cost-sensitive specifications.
Romania
Transylvanian plywood mills serving mass cabinetry producers confront displacement by oriented strand board from Bulgarian competitors. The country's Ministry of Environment and Climate Change governs harvesting permits under national forestry codes. Independent sawmills in Maramureș lack capital for kiln drying infrastructure capable of handling hornbeam's high initial moisture content.
France
Alsace furniture artisans seek premium hornbeam grades with specific aesthetic characteristics, excluded from direct cooperative purchasing by limited volume requirements. The CNIL does not regulate this sector. Grand Est regional authorities implement EU Deforestation Regulation traceability protocols ahead of 2025 full implementation deadlines.
Hornbeam Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with essential oil extractors commanding premium positioning against industrial timber traders. The vendor base concentrates around three strategic archetypes: botanical sourcing specialists leveraging existing aromatic supply infrastructure, certified forestry cooperatives pooling smallholder quotas, and precision sawmilling operators with interlocked grain processing expertise. Dominant competitive moves include backward integration into distillation partnerships and multi-year offtake contracting that bypasses traditional timber auction channels.
Among botanical specialists, DoTerra International and Young Living Essential Oils occupy positions representing vertical control over Eastern European supply zones, while Healingherbs Ltd. exemplifies the Bach flower remedy application niche. These entities anchor the essential oil extraction tier, contrasting with unnamed Polish forestry cooperatives that aggregate certified harvesting capacity. The competitive dynamic pits aroma-therapy brand equity against timber certification credibility, with divergent margin structures reflecting end-use value capture in finished formulations versus raw material supply.
| Leading Market Players |
|---|
| India Aroma Oils and Company |
| The Bach Centre |
| India Essential Oils |
| DoTerra International |
| Young Living Essential Oils |
| Healingherbs Ltd. |
| Bio Lonreco |
| Elma Skin Care |
| Totally Natural Skincare |
| Others |
Supply & Pricing Matrix
German furniture manufacturers negotiating multi-year offtake agreements anchor pricing power in this market, with contract structures favoring long-term volume commitments over spot-market transactions. Their consolidation around certified Polish suppliers has compressed spot-market liquidity and widened spreads between documented and undocumented material.
Pricing Analysis
Short lead-time premiums command substantial markups as Steinway and Bösendorfer suppliers compete for limited premium-grade hornbeam with verified geolocation documentation. Three-tier pricing structure across premium, standard, and economy levels separates musical instrument-grade material from furniture frame stock and industrial plywood feedstock. Cost compression in the industrial tier is intensifying because oriented strand board substitutes capture volume in Romanian mass cabinetry. Mass cabinetry producers exhibit highest price sensitivity, while musical instrument manufacturers accept premiums for documented chain-of-custody.
Supply Chain Analysis
Single-source vulnerability sits with premium-grade hornbeam suitable for piano action components, which concentrates in specific Podlaskie forest districts. Geographic supply concentration centers on Poland, Romania, and Austria, with Polish forestry cooperatives feeding German and Austrian manufacturers. Raw material flows draw from managed forest stands in Warmia-Mazury, independent Transylvanian plywood mills, and Upper Austrian veneer operations. Regulatory restriction risk looms as EUDR geolocation mandates tighten traceability obligations. Distribution runs through direct mill-to-manufacturer contracting that displaces traditional timber auction systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive control over certified harvesting capacity to secure EUDR-compliant supply. The winners will lock in multi-year cooperative partnerships before FSC certification backlogs clear.
For Market Incumbents: Deepen backward integration into Polish forestry cooperatives through equity stakes or exclusive offtake arrangements, insulating against Steinway suppliers' drone-based mapping investments that raise compliance barriers. Accelerate kiln drying infrastructure deployment in Maramureș before independent Romanian sawmills secure external capital. Engineered wood substitution in Bulgarian cabinetry poses the most severe volume threat to industrial-grade positioning. For New Entrants and Emerging Players: Blockchain-enabled timber tracking systems offer a technology-first wedge into documentation-intensive segments where large German furniture groups struggle with EUDR polygon-level geolocation mandates. Target artisan luthiers and custom furniture makers excluded from direct cooperative purchasing by volume minimums. A go-to-market angle emphasizing real-time satellite verification can bypass incumbent certification backlogs. For Investors and Strategic Acquirers: The window for entry favors precision sawmilling operators with interlocked grain processing expertise, as aging Polish sawyer cohorts create capability scarcity. Long-term viability hinges on securing FSC group certification infrastructure before EU Deforestation Regulation full implementation. Watch for drone-based forest mapping adoption rates among Steinway suppliers as an inflection indicator for documentation cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forestry Cooperatives | Secures EUDR-compliant hornbeam supply for Thonet and other German chair manufacturers facing tightening certified timber availability. |
| Blockchain-Enabled Timber Tracking Deployment | Enables real-time geolocation verification that satisfies emerging EU Deforestation Regulation requirements for mixed forest stands. |
| Kiln Drying Infrastructure Investment | Addresses hornbeam's high initial moisture content processing gap that exceeds capital capacity of most Romanian independent sawmills. |
| Near-Infrared Spectroscopy Adoption | Allows Austrian veneer producers to sort incoming Polish logs before cutting, reducing premium-grade waste through precise pattern selection. |
| FSC Group Certification Acceleration | Overcomes 18-month audit backlogs delaying market access for new Polish entrants seeking to supply German manufacturers. |
Research Methodology
Multi-period observation of hornbeam procurement contract structures, FSC certification timelines, and EUDR implementation milestones anchored the trend analysis, supplemented by interviews with forestry cooperative managers, Austrian veneer production directors, German furniture procurement leads, and Polish sawmill operators. Secondary validation drew from EU Timber Regulation enforcement reports, Forest Stewardship Council audit disclosures, Polish State Forests harvesting quota publications, and Austrian Federal Ministry of Agriculture chain-of-custody guidance. Bottom-up volume modeling across product tiers and top-down demand aggregation from end-use applications were triangulated against trade flow data.
Input-output matrices mapped hornbeam flows from Podlaskie and Warmia-Mazury forest regions through sawmilling and veneer processing stages to German furniture manufacturers, Austrian tool producers, and Romanian cabinetry mills across the analysis window. Segmentation dimensions modeled included product type, application, quality grade, and end-user category, with cross-elasticities against oak and tropical hardwood substitutes incorporated. CAGRs were derived from trend extrapolation adjusted for regulatory implementation phasing and substitution dynamics. Near-infrared spectroscopy adoption curves and drone-based forest mapping penetration rates informed technology diffusion assumptions.
Several conditions sit outside the modeled scope, including potential revisions to EU Deforestation Regulation implementation timelines, unforeseen shifts in oak price trajectories that could reverse substitution patterns, and breakthrough advances in engineered wood performance that accelerate displacement of industrial-grade plywood. Forecasts reflect assumptions about cooperative aggregation model scalability and sawyer training program expansion that may prove optimistic. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
UK Lab-Grown Diamonds Market
Specialty Materials
Cadmium Sulfide Market
Specialty Materials
Eptfe in Spotlight-Poly-Vents Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Nanocapsules Market
Specialty Materials
Edge Banding Materials Market
Specialty Materials
Activated Carbon Bags Market
Specialty Materials
Latin America International CEP Market
Specialty Materials
Vegan Wax Market
Specialty Materials
Dysprosium Oxide Sputtering Target Market
Specialty Materials
Advanced Green Septa Market
Specialty Materials
Global Cellulose Esters Market
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
Barium Fluoride Market
Specialty Materials
Specialty Carbon Black Market
Specialty Materials
Polyphenylsulfone Market