
 Talc Alternatives Market | 2026-2036
Talc Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Talc Alternatives Market Analytics
Technical advisory and formulation support services is rebalancing how raw material suppliers capture value beyond commodity powder sales. Imerys leverages its mineral processing heritage to anchor supply security for kaolin-based substitutes across European cosmetics corridors. Evonik Industries sustains specialty silica competencies that differentiate performance in pharmaceutical-grade applications. Cargill competes through agricultural feedstock control, extending corn starch availability into personal care channels.
Talc alternatives comprise inorganic and organic substitutes engineered to replicate talc's lamellar structure, oil absorption capacity, and silky tactile properties in formulations; kaolin delivers comparable platelet morphology with controlled particle size distribution, while corn starch offers biodegradable rheology modification at 5-15 micron fineness. The powder form segment dominates current volume owing to direct substitutability in existing blending equipment, though liquid suspensions are gaining fastest as wet-process cosmetics manufacturing expands. Kaolin occupies the largest margin pool among product types due to mining concentration and processing complexity, whereas talc-free powder blends attract premium positioning in clean-label personal care.
REACH classification revisions and FDA cosmetic ingredient scrutiny are tightening purity benchmarks for asbestos-free certification, compelling reformulation investments across North American and European supply chains. ECHA's ongoing substance evaluation and EPA talc assessment protocols are reshaping import documentation and third-party testing requirements. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which alternative chemistries will receive preferential market access.
Market Dynamics
REACH classification revisions on talc carcinogenicity are forcing cosmetics formulators across Europe to validate substitute chemistries through accelerated stability testing, redirecting procurement budgets toward certified kaolin and starch suppliers with documented asbestos-free chain-of-custody.
Growth Catalysts
- ECHA Substance Evaluation:REACH restrictions on talc classification in Europe are redirecting procurement toward certified alternatives with validated purity documentation.
- Clean-Label Personal Care:Cosmetics formulators are accelerating adoption of plant-derived substitutes as consumer ingredient transparency demands intensify.
- German Manufacturing Clusters:Technical validation programs in Germany have expanded, concentrating demand for performance-qualified talc alternatives.
Market Restraints
- Kaolin Mining Concentration:Processing complexity and geographic concentration of high-grade deposits create supply security vulnerabilities for European cosmetics corridors.
- Reformulation Costs:FDA cosmetic ingredient scrutiny and asbestos-free certification requirements compel significant R&D investment before market access.
- Performance Gaps:Corn starch alternatives face humidity stability limitations that restrict deployment in certain pharmaceutical-grade applications.
Strategic Opportunities
- Wet-Process Manufacturing:Liquid suspension formats are gaining fastest as wet-process cosmetics manufacturing expands beyond powder-centric legacy infrastructure.
- Pharmaceutical-Grade Silica:Specialty silica competencies differentiate performance in pharmaceutical-grade applications where lamellar structure replication is critical.
- EU Green Deal Alignment:Agricultural feedstock control extends corn starch availability into personal care channels with favorable sustainability credentials.
Industry Challenges
- Third-Party Testing Bottlenecks:EPA talc assessment protocols and ECHA documentation requirements have created certification backlogs extending reformulation timelines.
- Particle Size Distribution Control:Replicating talc's 5-15 micron fineness and silky tactile properties requires precision processing equipment that demands significant capital deployment.
- Regulatory Divergence Monitoring:Stakeholders must track purity benchmark variations between FDA cosmetic rules and REACH restrictions to maintain multi-jurisdictional compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Talc Alternatives Market |
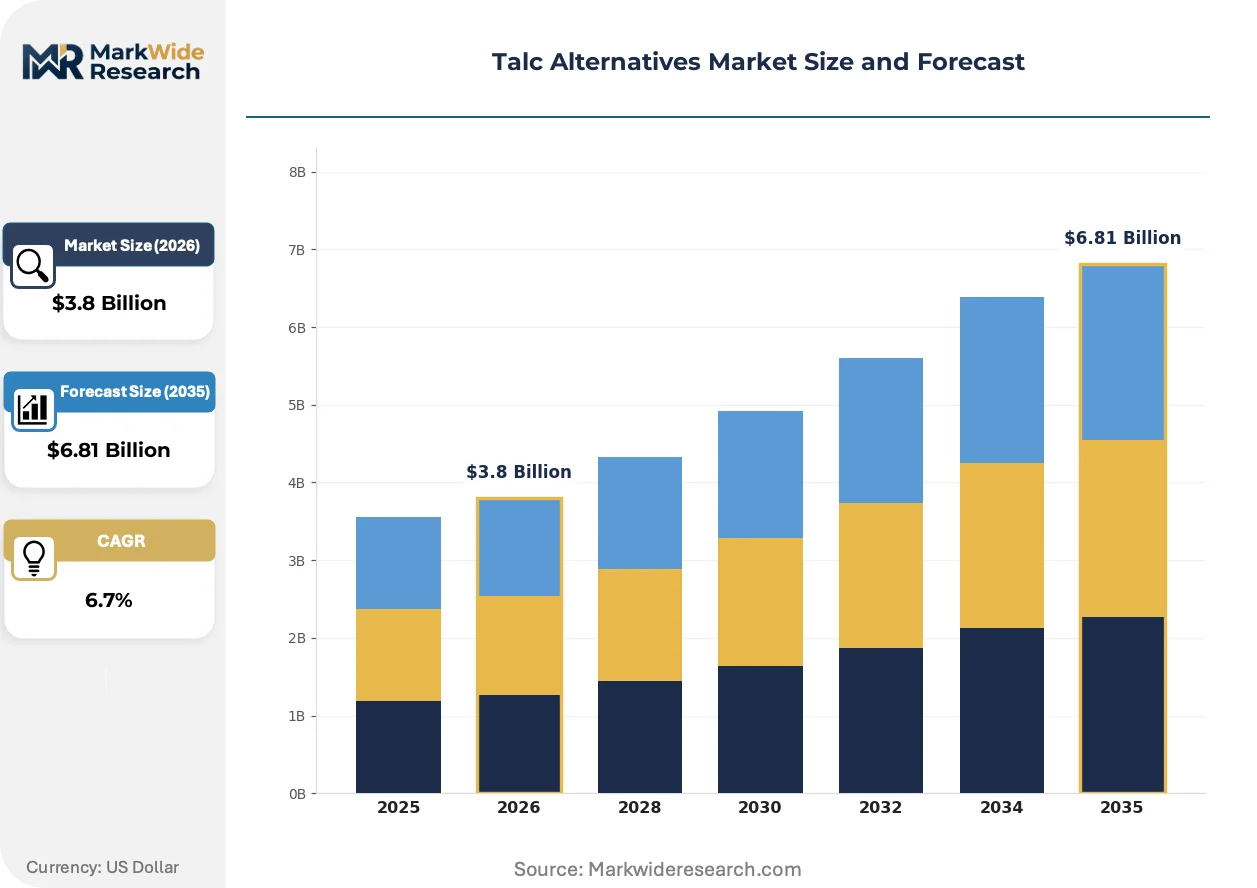
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kaolin, Corn Starch, Arrowroot Powder, Talc-Free Powders Application: Cosmetics, Pharmaceuticals, Food Industry, Personal Care Form: Powder, Granules, Liquid, Paste End User: Manufacturers, Consumers, Retailers, Distributors |
| Companies Covered | Cabot Corporation, Ingredion, Nouryon, Beneo, ADM, Evonik Industries, Cargill, Tata and Lyle, Imerys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Talc Alternatives Market Evolving Landscape
Formulation science is actively reshaping how mineral and botanical substitutes replicate talc's sensory signature, with wet-process manufacturing methods and surface-modified particles displacing conventional dry-blending approaches across premium personal care lines.
Surface-modified kaolin with silane coupling agents is converging with nano-scale particle engineering to deliver oil absorption capacity matching legacy talc grades. Specialty chemical suppliers serving French and German cosmetics houses are scaling these modified platelet structures fastest. The convergence is compressing performance premiums previously commanded by unmodified mineral alternatives.
REACH authorization procedures and ECHA's ongoing substance evaluation are tightening purity benchmarks for asbestos-free certification across European supply chains. Import documentation requirements now mandate third-party testing at multiple processing stages. Wet-process cosmetics manufacturers in Germany and France are responding by qualifying liquid suspension formats that bypass powder-handling contamination risks entirely.
Buyer concentration among clean-label personal care brands has compressed switching cycles for raw material qualification. Direct supplier relationships are displacing distributor intermediaries for certified alternative sourcing. This pattern is most visible in German manufacturing clusters where technical validation programs have institutionalized single-source partnerships with documented chain-of-custody.
Talc Alternatives Market Segmentation
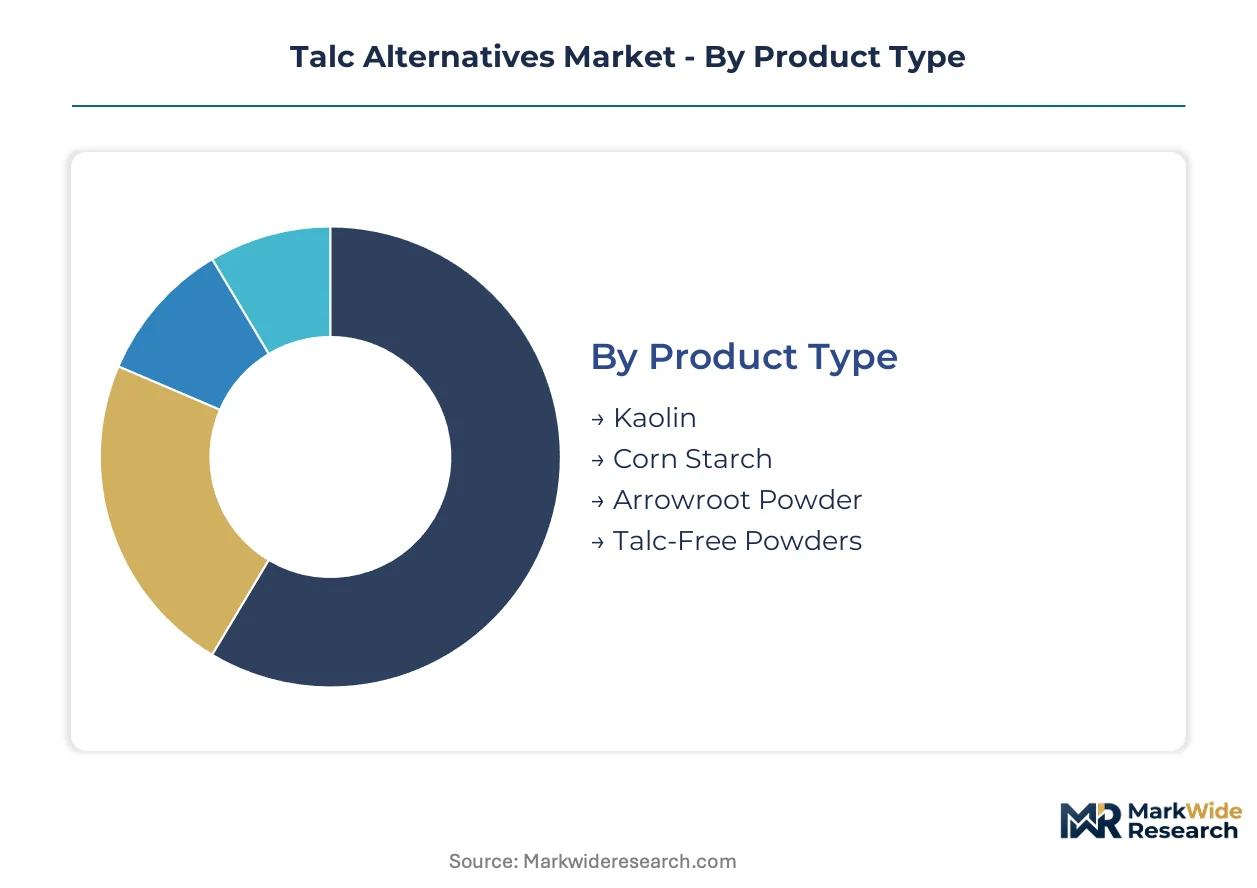
Segmentation in talc alternatives reveals how capital deployment and technical validation requirements fragment procurement patterns across mineral and botanical substitutes. Formulators select alternatives based on lamellar structure replication, oil absorption capacity, and regulatory documentation depth rather than commodity pricing alone.
Product Type:
Kaolin mining and processing infrastructure demands the heaviest capital intensity among all product categories, with beneficiation circuits and particle classification systems requiring sustained equipment investment.
- Kaolin:Platelet morphology with controlled particle size distribution delivers comparable lamellar structure to talc. German cosmetics manufacturers concentrate procurement here due to REACH-mandated asbestos-free certification and established mining corridors in Bavaria and Saxony.
- Corn Starch:Biodegradable rheology modification at 5-15 micron fineness serves clean-label personal care demands. Agricultural feedstock control by Cargill and ADM anchors supply security for North American formulators seeking plant-derived positioning.
- Arrowroot Powder:Tropical tuber-derived alternative with lower processing intensity than modified starches; Brazilian and Thai sourcing dominates for natural cosmetics channels.
- Talc-Free Powders:Engineered blends combining multiple mineral and botanical substrates; premium positioning attracts reformulation investment from clean-label brands seeking differentiated sensory profiles.
Kaolin absorbs the bulk of installed capacity; talc-free powder blends are expanding most quickly as clean-label positioning commands formulation priority.
Application:
Pharmaceutical-grade applications impose the steepest purity benchmarks and documentation burdens, filtering supplier participation to those with validated quality management systems.
- Cosmetics:Face powders, eyeshadows, and body products require oil absorption capacity and silky tactile properties. French and German formulators drive specification development through wet-process manufacturing expansion.
- Pharmaceuticals:Tablet excipients and topical formulations demand lamellar structure replication with validated asbestos-free chain-of-custody. Evonik's specialty silica competencies anchor European supply for this segment.
- Food Industry:Anti-caking and texturizing applications favor corn starch and arrowroot for GRAS status and clean-label compatibility.
- Personal Care:Deodorants, body powders, and baby products concentrate demand for plant-derived substitutes as consumer transparency intensifies.
Cosmetics commands the largest absolute volume; pharmaceuticals maintains the tightest supplier qualification barriers.
Form:
Powder handling infrastructure dominates legacy capital deployment, though wet-process equipment represents the fastest-growing investment category for cosmetics manufacturers.
- Powder:Direct substitutability in existing blending equipment preserves formulation continuity. Dry-process manufacturing clusters in Germany and France maintain this format's volume dominance despite contamination handling risks.
- Liquid:Suspension formats bypass powder-handling contamination risks and align with wet-process cosmetics expansion. Surface-modified particle engineering enables stable dispersion for premium personal care lines.
- Granules:Intermediate processing format for bulk pharmaceutical and food applications; limited cosmetics relevance due to sensory limitations.
- Paste:Pre-dispersed concentrates for specialized topical formulations; niche positioning in pharmaceutical compounding.
Powder retains the deepest installed base; liquid suspensions are climbing the fastest as wet-process manufacturing displaces legacy infrastructure.
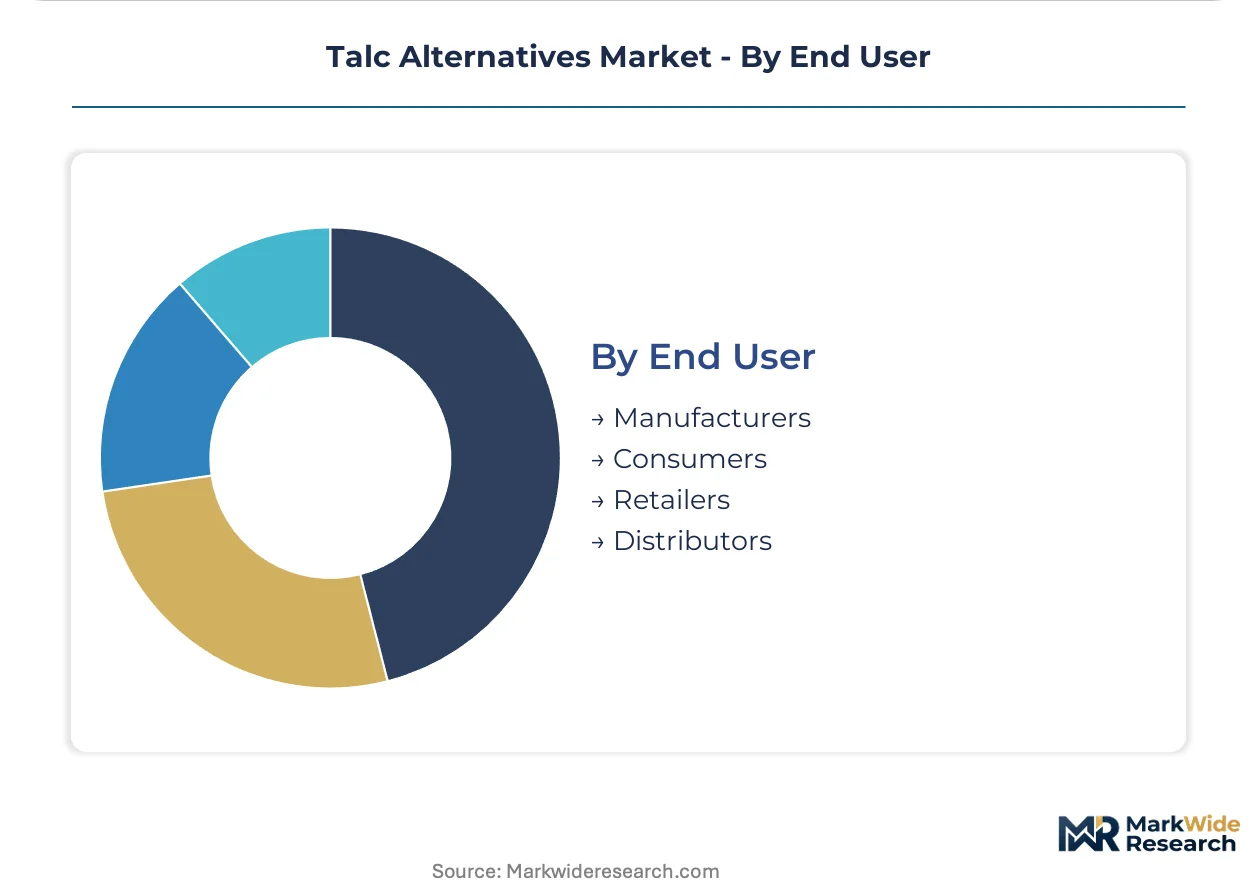
End User:
Manufacturer procurement patterns concentrate technical validation investment, while retailer and consumer channels fragment demand across certification tiers.
- Manufacturers:Cosmetics and pharmaceutical formulators drive bulk procurement with documented purity requirements. Direct supplier relationships displace distributor intermediaries for certified alternative sourcing in German manufacturing clusters.
- Consumers:Clean-label personal care brands compress switching cycles through ingredient transparency demands. Indie beauty brands in France and California anchor this segment's growth trajectory.
- Retailers:Private-label personal care lines seek mid-tier alternatives with basic asbestos-free documentation; price sensitivity limits premium product adoption.
- Distributors:Regional chemical distributors serve smaller formulators lacking direct supplier relationships; inventory consolidation challenges fragment service levels.
Manufacturers absorb the bulk of technical validation investment; consumer-facing brands are expanding most quickly as clean-label positioning reshapes procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of kaolin concentrates in Bavaria and Saxony contrasts with consumption pull from French cosmetics houses and North American clean-label brands. This geographic mismatch creates logistics premiums that advantage integrated suppliers with multi-site processing networks.
Germany
REACH restrictions on talc classification have concentrated technical validation investment in Bavarian manufacturing clusters. ECHA substance evaluation protocols now mandate third-party asbestos-free documentation at multiple processing stages. Clean-label personal care formulators in Munich and Hamburg have institutionalized direct supplier partnerships with documented chain-of-custody.
France
French cosmetics houses drive specification development for wet-process manufacturing expansion in the Île-de-France region. ANSM pharmaceutical-grade purity benchmarks filter supplier participation to those with validated quality management systems. Surface-modified kaolin with silane coupling agents scales fastest among specialty chemical suppliers serving Paris-based premium personal care lines.
United States
FDA cosmetic ingredient scrutiny compels reformulation investment across North American supply chains before market access. EPA talc assessment protocols have created certification backlogs extending timelines for alternative qualification. Corn starch availability extends into personal care channels through agricultural feedstock control by Midwest-based processors serving clean-label brands in California and New York.
Brazil
Arrowroot powder sourcing from tropical tuber cultivation concentrates in São Paulo state export corridors. ANVISA pharmaceutical regulations align with FDA purity benchmarks for asbestos-free certification in topical formulations. Natural cosmetics channels in Rio de Janeiro and Minas Gerais anchor demand for lower-processing-intensity botanical alternatives.
India
Domestic kaolin processing infrastructure serves pharmaceutical excipient demand from CDSCO-regulated tablet manufacturers. BIS standards for cosmetic-grade mineral purity create documentation requirements that favor established mining corridors in Rajasthan and Gujarat. Personal care formulators in Maharashtra accelerate plant-derived substitute adoption as consumer ingredient transparency intensifies in Mumbai and Pune markets.
Talc Alternatives Market Competitive Landscape
Capital-heavy mineral processors compete with asset-light agricultural feedstock traders for formulation partnerships. The supplier base stratifies between integrated mining operators with beneficiation circuits and specialty distributors with certification documentation capabilities. Three archetypes dominate: kaolin miners with geographic deposit control, starch processors with crop origination networks, and silica specialists with surface-modification competencies. Competitive moves concentrate on backward integration into raw material sourcing and strategic partnerships with wet-process cosmetics manufacturers.
Within the integrated mineral processing tier, Imerys and Evonik Industries exemplify divergent specialization paths—one anchored in European mining heritage with multi-site kaolin networks, the other in pharmaceutical-grade silica competencies with surface-modification capabilities. Cargill occupies a distinct position through agricultural feedstock control that extends corn starch availability into personal care channels with documented sustainability credentials. These three represent how capital deployment and technical validation depth fragment competitive positioning across substitute chemistries.
| Leading Market Players |
|---|
| Cabot Corporation |
| Ingredion |
| Nouryon |
| Beneo |
| ADM |
| Evonik Industries |
| Cargill |
| Tata and Lyle |
| Imerys |
| Others |
Value Network & Pricing Analysis
Kaolin feedstock indices from Bavarian mining corridors cascade through beneficiation cost structures into three distinct pricing tiers for cosmetics formulators. REACH-mandated asbestos-free certification premiums compress margins at the standard grade while pharmaceutical-grade silica commands sustained premiums through Evonik's surface-modification competencies.
Pricing Analysis
Margin tightening in standard-grade kaolin reflects beneficiation circuit bottlenecks at Saxony processing facilities. Three-tier pricing structure across pharmaceutical-grade, certified cosmetic-grade, and industrial-grade levels segments buyer archetypes by documentation depth. Cost-down pressure on corn starch alternatives accelerates as Cargill's agricultural feedstock control consolidates origination networks. Indie beauty brands in California exhibit highest price sensitivity; German pharmaceutical formulators show lowest sensitivity due to regulatory compliance premiums.
Supply Chain Analysis
Direct-to-manufacturer channels handle bulk procurement from Imerys and Evonik for German cosmetics corridors. Geographic supply concentrates in Germany, France, and the United States for processed kaolin and specialty silica. Raw material dependencies include high-grade kaolin deposits, silane coupling agents for surface modification, and pharmaceutical-grade corn feedstock. Single-source vulnerability around Bavarian beneficiation infrastructure creates supply security risks. Distribution runs through certified chemical distributors serving smaller formulators lacking direct supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-grade kaolin deposit depletion and beneficiation capacity constraints prop pricing premiums across European supply chains. Formulators face procurement rationing without documented chain-of-custody investments.
For Market Incumbents: Lock in multi-year offtake agreements with Bavarian mining operators before deposit depletion accelerates. Backward integration into surface-modification capabilities defends against Evonik's pharmaceutical-grade silica dominance. Certification investment in ECHA-compliant asbestos-free documentation preserves access to German manufacturing clusters facing REACH enforcement tightening. For New Entrants and Emerging Players: Launch via liquid suspension formats targeting wet-process cosmetics manufacturers in France's Île-de-France region. Arrowroot powder sourcing from Brazilian São Paulo corridors offers the most penetrable white-space for natural cosmetics channels. Direct supplier partnerships with indie beauty brands in California bypass distributor intermediaries and compress qualification timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap kaolin processors with stranded beneficiation assets in Saxony. Long-term viability hinges on wet-process manufacturing adoption rates across European cosmetics houses. Monitor ECHA substance evaluation acceleration as the inflection signal for regulatory-driven procurement shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surface-Modification Capabilities | Evonik's silane coupling agent competencies anchor pharmaceutical-grade pricing premiums. |
| Long-term Supply Agreement with Agricultural Feedstock Controllers | Cargill's corn origination networks secure plant-derived substitute availability for clean-label brands. |
| Capacity Expansion in Wet-Process Suspension Formats | French cosmetics houses in Île-de-France drive fastest adoption of liquid dispersion technologies. |
| Green Certification Program Alignment with EU Green Deal | EU Green Deal sustainability credentials differentiate corn starch positioning in personal care channels. |
| Joint Venture for Asbestos-Free Chain-of-Custody Documentation | ECHA-mandated third-party testing requirements institutionalize certification partnerships in German clusters. |
Research Methodology
Independent corroboration across customs trade data, ECHA substance evaluation filings, and SEC 10-K disclosures underwrites the qualitative findings. Primary interviews with cosmetics formulators, pharmaceutical procurement leads, kaolin beneficiation plant managers, and specialty chemical distributors combined with secondary validation from trade association reports. Bottom-up volume triangulation across product types and top-down value reconciliation anchored the market sizing.
Rate-of-change decomposition across the projection horizon isolates volume drivers from pricing dynamics. Segmentation dimensions modeled include product type, application, form, and end-user procurement authority. CAGRs derived from regression analysis of historical feedstock pricing and regulatory enforcement intensity. Industry-specific forecast inputs include REACH authorization timelines and wet-process manufacturing capacity expansion announcements.
Regulatory enforcement acceleration, kaolin deposit depletion rates, and wet-process adoption velocity are the dominant revision risks. Forecasts reflect assumptions around ECHA documentation requirement stability and corn feedstock availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Middle East and Africa Anti-Friction Coatings Market
Specialty Materials
Charge Generation Materials (CGM) Market
Specialty Materials
Spermaceti Wax Market
Specialty Materials
Carbon Blacks for Non-Rubber Applications Market
Specialty Materials
Cadmium Sulfide Market
Specialty Materials
Polyimide Foam Market
Specialty Materials
Global Flexible Substrates Market
Specialty Materials
Non-Semiconductor Neon Market
Specialty Materials
Specialty Silica Market
Specialty Materials
Nitrocellulose Market
Specialty Materials
ePTFE Electronic Film Market
Specialty Materials
APAC Fluoroelastomer Market
Specialty Materials
Special Graphite Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Shape Memory Polymer Market
Specialty Materials
Light Diffusion Materials Market