
 North America Aluminum Market | 2026-2036
North America Aluminum Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aluminum Market Insights
Secondary aluminum smelting is narrowing the cost gap with primary production across North American supply chains. Novelis Inc leverages its automotive sheet capacity to anchor rolling supply for Detroit-area OEMs. Alcoa Corporation sustains bauxite-to-ingot integration across its Atlantic operations. Constellium NV specializes in aerospace-grade plate and extrusion for Boeing and Airbus tier-one suppliers.
Aluminum is a silvery-white, non-ferrous metallic element with atomic number 13, valued for its density of 2.70 g/cm³, natural corrosion resistance from oxide passivation, and electrical conductivity at 61% of copper by volume. Primary production relies on the Hall-Héroult electrolytic reduction of alumina, while secondary recovery uses remelting to achieve 95% energy savings versus virgin smelting. Sheet products dominate value capture in automotive and packaging end uses where surface quality and gauge tolerance drive specification. Extrusions lead growth in structural and thermal applications as building codes tighten envelope performance requirements. Secondary grade aluminum expands fastest where closed-loop recycling partnerships with beverage brands and automakers secure scrap supply.
The EPA enforces emissions benchmarks that favor aluminum substitution for heavier ferrous materials in transportation equipment. The US Department of Commerce administers Section 232 tariffs that reshape import flows from Canadian and Mexican smelters under USMCA rules. OSHA mandates govern molten metal handling and potline worker exposure limits across primary production facilities. Stakeholders must track how carbon border adjustments and state-level clean electricity standards redefine competitive positioning between domestic recycling and imported primary metal.
Market Dynamics
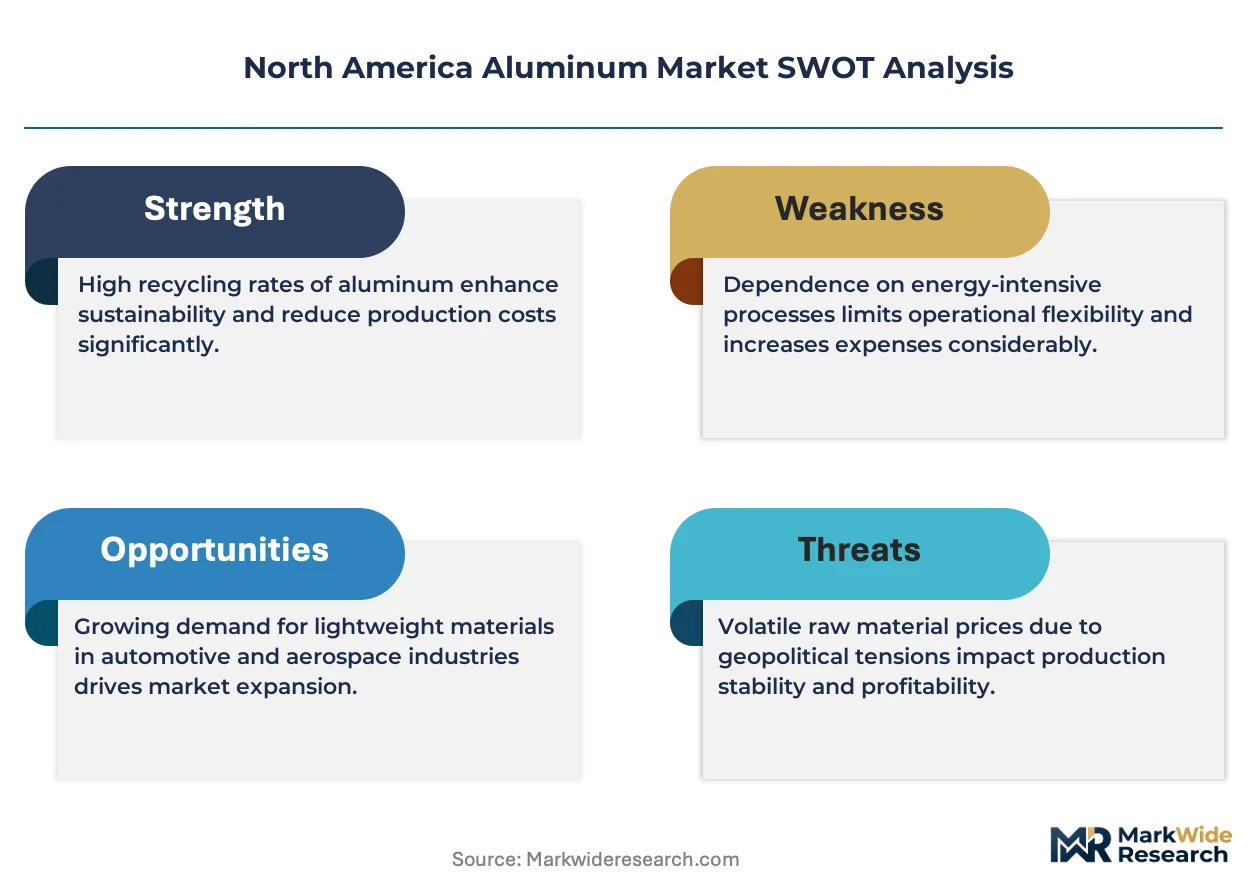
Automotive lightweighting mandates from the EPA are compressing design cycles and forcing rapid aluminum substitution for steel body structures across Detroit and southern US assembly corridors.
Growth Catalysts
- Corporate Average Fuel Economy standards:The EPA's tightening fleet efficiency benchmarks compel automakers to adopt aluminum-intensive body-in-white architectures. Sheet aluminum penetration accelerates in pickup trucks and SUVs.
- Closed-loop beverage recycling:Major brands now contract directly for post-consumer scrap supply, securing feedstock for secondary smelters. This partnership model stabilizes raw material costs.
- Electric vehicle platform expansion:Battery enclosure and thermal management applications consume extruded and cast aluminum at double the rate of internal combustion architectures.
Market Restraints
- Primary aluminum energy intensity:Hall-Héroult smelting requires 13,500-17,000 kWh per metric ton, exposing producers to volatile electricity pricing in deregulated US Midwest and Quebec markets.
- Canadian ingot concentration:Quebec and British Columbia smelters supply over 70% of North American primary metal, creating geographic supply risk during winter grid stress or labor disputes.
- Steel industry cost competition:Advanced high-strength steel alloys retain cost advantage in A- and B-pillar applications where crash performance dominates material selection.
Strategic Opportunities
- Mexican automotive assembly expansion:OEMs are adding aluminum stamping and casting capacity in Nuevo León and Guanajuato to serve USMCA-compliant regional supply chains.
- Building envelope thermal codes:IECC 2021 and ASHRAE 90.1 updates mandate improved curtain wall performance, driving demand for thermally broken aluminum extrusions in commercial construction.
- Secondary smelter carbon advantage:Remelt operations achieve 95% energy reduction versus primary production, positioning recyclers to capture carbon border adjustment benefits.
Industry Challenges
- Potline maintenance technician scarcity:Primary smelters face retirements of experienced Hall-Héroult operators without sufficient apprenticeship pipeline replacement in Kentucky and Texas.
- Automotive qualification timelines:OEMs require 18-24 month alloy certification cycles for new sheet grades, delaying commercialization of recycled-content automotive specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aluminum Market |
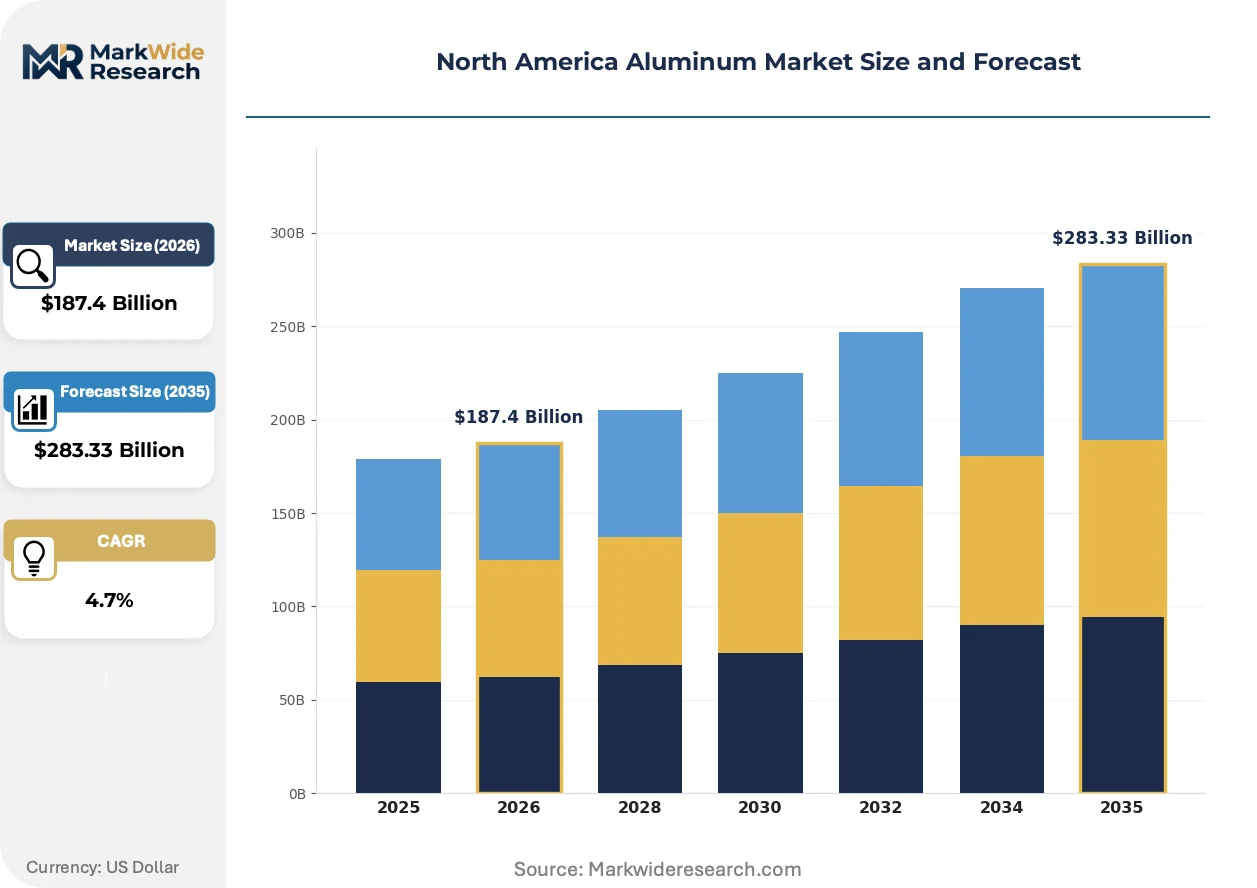
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $283.33 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet, Extrusions, Foil, Casting End User: Aerospace, Automotive, Construction, Packaging Application: Structural, Electrical, Thermal, Decorative Grade: Primary, Secondary, Alloys, Others |
| Companies Covered | Kaiser Aluminum Corporation, Constellium NV, Alcoa Corporation, Reliance Steel & Aluminum Co, Norsk Hydro ASA, Novelis Inc, Arconic Inc, Gränges Americas Inc, Century Aluminum Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aluminum Market Trends and Innovations
Digital process control and regulatory carbon accounting are converging to reshape how aluminum producers compete on emissions transparency and alloy traceability across the value chain.
Artificial intelligence-driven potline monitoring is digitizing electrolytic cell management in primary smelters. Alcoa's Atlantic operations and Quebec competitors now deploy sensor arrays predicting anode effects and bath chemistry drift. This predictive capability compresses unplanned downtime and reduces per-ton energy consumption.
The EPA's proposed carbon intensity disclosure rules for federal procurement are tightening supply chain documentation requirements. Domestic recyclers gain preference in Department of Defense and General Services Administration aluminum purchases. Secondary producers accelerate mass-balance certification to capture this public-sector demand.
Fleet buyers now contract directly for low-carbon aluminum certificates rather than purchasing commodity-grade metal through distributors. This disintermediation concentrates procurement power among large automakers and beverage bottlers. The US Southeast sees fastest adoption where automotive assembly clusters enable just-in-time toll processing arrangements.
North America Aluminum Market Segmentation
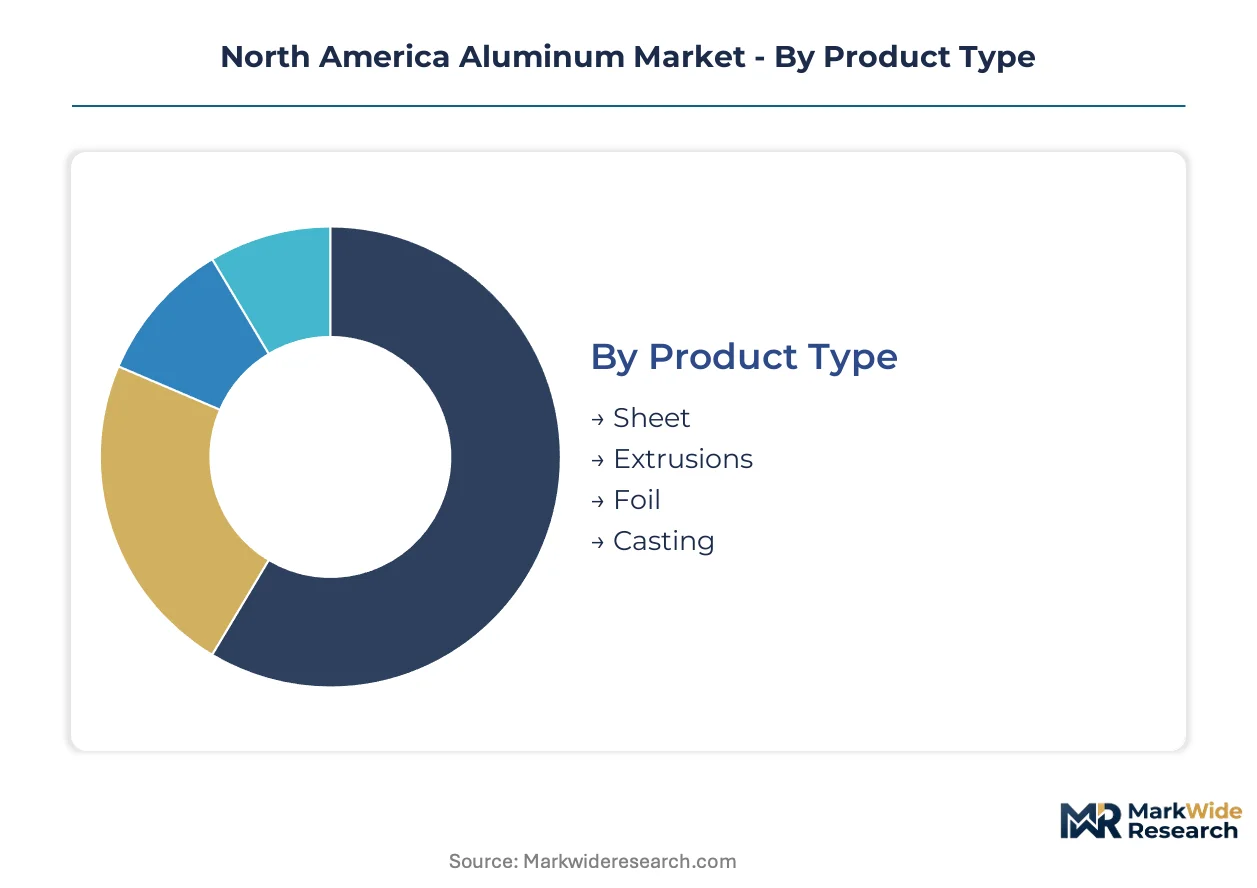
Aluminum segmentation across North America reflects divergent technical specifications, supply chain configurations, and customer service intensity. Each category isolates distinct margin profiles and competitive dynamics that reshape procurement patterns among Detroit automakers, Gulf Coast aerospace fabricators, and Southeast beverage packagers.
Product Type:
After-sales service intensity varies sharply across product categories, with automotive sheet demanding just-in-time technical support and foil requiring minimal field intervention.
- Sheet:Rolled flat products with tight gauge tolerance and surface quality specifications dominate automotive body-in-white applications. Demand concentrates in the US Southeast where Novelis and Arconic operate rolling mills adjacent to Ford, GM, and Mercedes-Benz assembly plants, driven by EPA Corporate Average Fuel Economy mandates for lightweighting.
- Extrusions:Pressed profiles with complex cross-sections enable thermal management and structural framing. Demand clusters in Mexican border states and Ontario where building envelope codes and electric vehicle battery enclosure specifications are tightening simultaneously.
- Foil:Ultra-thin rolled stock below 0.2mm serves pharmaceutical blister packs and flexible food packaging with standardized specifications requiring limited technical support.
- Casting:Molten metal poured into molds produces engine blocks, transmission housings, and wheel components for internal combustion and electric vehicle platforms across Kentucky and Tennessee foundry corridors.
By volume, Sheet leads. By growth pace, Extrusions is ahead.
End User:
Cost tier stratification separates specification-heavy aerospace and automotive segments from price-sensitive construction and packaging buyers.
- Aerospace:Plate and extrusion grades certified to AMS and ASTM standards serve Boeing, Airbus, and Bombardier tier-one suppliers. Demand concentrates in Washington State, Quebec, and Kansas where heat treatment and ultrasonic testing capabilities anchor qualified supply chains.
- Automotive:Body sheet, structural extrusions, and cast components penetrate pickup trucks, SUVs, and electric vehicle platforms. OEM qualification cycles spanning 18-24 months lock in supplier relationships across Michigan, Ohio, and Alabama assembly corridors.
- Construction:Window framing, curtain wall systems, and roofing applications compete against vinyl and steel on installed cost across Texas, Florida, and California commercial building markets.
- Packaging:Beverage can sheet and foil stock operate on thin margins with high volume throughput, where closed-loop recycling partnerships with Coca-Cola and PepsiCo stabilize scrap feedstock costs.
Automotive commands the highest value per ton. Packaging moves the greatest mass.
Application:
Customer type fragmentation splits the market between specification-driven engineering procurement and commodity purchasing with minimal technical oversight.
- Structural:Load-bearing extrusions and castings in transportation and building frameworks require finite element analysis validation and weldability certification.
- Electrical:Bus bar and conductor applications leverage aluminum's 61% copper conductivity by volume with lower density, penetrating utility transmission and data center power distribution.
- Thermal:Heat exchanger fins, battery cooling plates, and LED housings exploit high thermal conductivity with corrosion-resistant surface treatments.
- Decorative:Anodized architectural panels and appliance trim prioritize aesthetic uniformity over mechanical performance with shorter qualification cycles.
Structural applications generate the deepest supplier relationships. Thermal use cases are expanding most quickly.
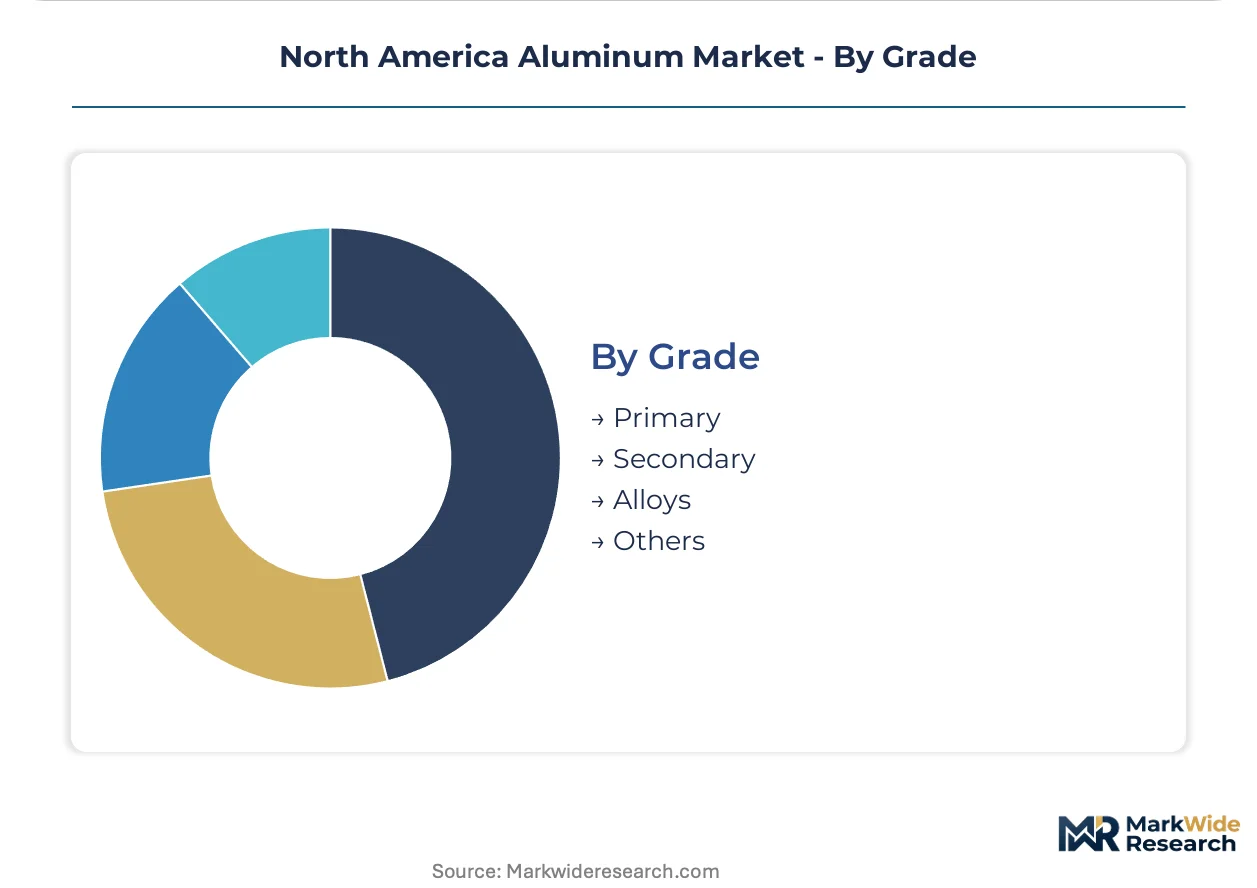
Grade:
Supply concentration dynamics concentrate primary metal in Quebec smelters while secondary recovery clusters near automotive and beverage manufacturing corridors.
- Primary:Hall-Héroult electrolytic metal from bauxite feedstock delivers consistent purity for aerospace and high-performance automotive specifications. Quebec and British Columbia smelters supply over 70% of North American primary ingot.
- Secondary:Remelt scrap achieves 95% energy reduction versus primary production, positioning recyclers to capture carbon border adjustment benefits and Department of Defense low-carbon procurement preferences.
- Alloys:Silicon, magnesium, and copper additions tailor strength, formability, and corrosion resistance for specific end-use certifications.
- Others:Master alloys and hardeners enable foundry customization of melt chemistry for specialized casting applications.
Primary grade still dominates aerospace qualification. Secondary is gaining share fastest as automakers accelerate recycled-content targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian primary smelters in Quebec and British Columbia export ingot to US rolling mills and automotive stamping plants across the Midwest and Southeast. Mexican extrusion and casting facilities feed just-in-time assembly lines in Nuevo León and Baja California for duty-free re-export under USMCA rules.
United States
EPA Corporate Average Fuel Economy standards and NHTSA safety regulations compress design cycles for aluminum-intensive vehicle platforms. The US Southeast anchors demand, with Novelis and Arconic rolling mills clustered near Ford, GM, and Mercedes-Benz assembly plants in Kentucky, Tennessee, and Alabama.
Canada
Hydro-Québec's low-carbon electricity supply underpins primary smelting economics for aerospace and automotive specification metal. Quebec and British Columbia smelters concentrate over 70 percent of North American primary ingot capacity, exposing buyers to winter grid stress and labor negotiation risks.
Mexico
OEM aluminum stamping and casting capacity expands in Nuevo León and Guanajuato to serve USMCA-compliant regional supply chains. Mexican federal energy reform debates and state-level industrial electricity pricing shape competitiveness against US border-state recyclers.
North America Aluminum Market Competitive Landscape
On the supply side, the industry is consolidating around integrated primary-to-rolled-product chains and specialized secondary recyclers. Three archetypes dominate: bauxite-to-ingot integrated majors, automotive sheet specialists with toll-processing relationships, and regional scrap-fed remelters. Capacity expansion and backward integration into scrap collection represent the two dominant competitive moves.
Among North American-integrated producers, Alcoa Corporation exemplifies the bauxite-to-ingot archetype across Atlantic operations. Novelis Inc and Constellium NV occupy positions within the automotive and aerospace specification tiers respectively. Kaiser Aluminum Corporation represents the specialized rolled-products model serving distribution and industrial end uses.
| Leading Market Players |
|---|
| Kaiser Aluminum Corporation |
| Constellium NV |
| Alcoa Corporation |
| Reliance Steel & Aluminum Co |
| Norsk Hydro ASA |
| Novelis Inc |
| Arconic Inc |
| Gränges Americas Inc |
| Century Aluminum Company |
| Others |
Pricing and Supply Chain Analysis
Quebec's hydro-powered smelter corridor concentrates over 70 percent of North American primary ingot capacity, translating upstream electricity cost advantages into pricing leverage over Midwest and Southeast rolling mills dependent on toll-processed feedstock.
Pricing Analysis
Primary versus secondary generation pricing gaps are widening as carbon border adjustment mechanisms reshape procurement premiums. Three-tier pricing structure across aerospace-certified primary, automotive-grade recycled, and commodity construction metal separates specification-heavy buyers from price-sensitive packaging segments. Cost compression in standard-grade sheet is intensifying because Chinese semi-finished product diversion under Section 232 tariff engineering erodes domestic mill margins. Packaging buyers exhibit highest price sensitivity, while aerospace OEMs absorb premiums for AMS-certified plate with minimal volume negotiation.
Supply Chain Analysis
USMCA rules-of-origin enforcement and EPA carbon intensity disclosure requirements for federal procurement are restricting cross-border flow configurations. Quebec and British Columbia smelters anchor primary metal supply, while Kentucky and Tennessee secondary remelters feed automotive closed-loop partnerships. Bauxite alumina, electricity, and scrap aluminum constitute the critical input triad. Single-source vulnerability concentrates in winter grid stress episodes when Hydro-Québec prioritizes residential load over industrial contracts. Distribution runs through toll-processing arrangements where rolling mills convert ingot to specification sheet adjacent to Detroit-area OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as electric vehicle platform diversification splinters legacy steel-aluminum substitution economics into battery enclosure, thermal management, and body-in-white niches with divergent alloy specifications.
For Market Incumbents: Build captive scrap collection moats through direct beverage brand partnerships and automotive shredder residue offtake agreements. Alcoa and Novelis should accelerate Kentucky and Tennessee secondary capacity additions before carbon border adjustments fully activate. Threat of Chinese semi-finished product circumvention through Mexican toll-processing demands enhanced USMCA certification investment. Channel control over qualified automotive sheet supply constitutes the critical defensive lever.
For New Entrants and Emerging Players: Establish a beachhead in thermally broken extrusion supply for IECC 2021-compliant commercial envelope retrofits across Texas and Florida. Secondary smelter carbon accounting services and mass-balance certification represent underdeveloped white-space where recyclers lack technical documentation capacity. Direct contracting with fleet buyers for low-carbon aluminum certificates bypasses distributor intermediation and captures procurement power concentration.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among secondary remelters with closed-loop beverage partnerships and long-term automotive toll-processing arrangements. Five-to-ten year viability favors recyclers positioned for Department of Defense low-carbon procurement preference expansion. Acquisition target archetype: regional scrap-fed remelters with automotive qualification pipeline progress and underutilized rolling capacity. Watch for EPA carbon intensity disclosure rule finalization as inflection indicator for public-sector demand shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Secondary Smelter Capacity Expansion | Kentucky and Tennessee recyclers capture carbon border adjustment benefits before Quebec primary metal. |
| Closed-Loop Scrap Partnership | Coca-Cola and PepsiCo direct contracts stabilize feedstock costs against LME volatility. |
| Automotive Sheet Qualification Investment | Novelis and Arconic compress 18-24 month OEM certification cycles for recycled-content grades. |
| Mexican Extrusion Facility Buildout | Nuevo León and Guanajuato plants serve USMCA-compliant regional supply chains for EV platforms. |
| Potline Digital Process Control Deployment | Alcoa's Atlantic operations reduce per-ton energy consumption through AI-driven anode effect prediction. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with aluminum industry stakeholders and systematic secondary validation across regulatory and trade databases. Primary fieldwork encompassed smelter operations directors, automotive OEM procurement leads, beverage packaging supply chain managers, and rolling mill technical sales executives. Secondary sources included USGS mineral commodity summaries, EPA enforcement and disclosure filings, USITC trade flow databases, and SEC 10-K filings from publicly traded producers. Bottom-up alloy-grade volume estimates and top-down regional consumption patterns underwent iterative triangulation.
Forecast inputs incorporated vehicle production platform data, building code adoption timelines, and electricity pricing scenarios across the analysis window. Segmentation modeling spanned product type, end-use industry, grade tier, and regional production cluster dimensions. CAGRs derived from slope-log regression against historical price-volume elasticities and substitution coefficient trajectories. Industry-specific inputs included EPA Corporate Average Fuel Economy compliance pathway assumptions and USMCA rules-of-origin evolution.
Sensitivities concentrate around Quebec winter grid reliability, Section 232 tariff scope expansion, and automotive OEM recycled-content target acceleration. Forecasts reflect documented assumptions regarding smelter capacity utilization and scrap generation rates. Material shifts in federal carbon border adjustment implementation timing or Hydro-Québec industrial electricity pricing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Lightweight Aluminium Pistons Market
Metals
Lithium Tungstate Market
Metals
Cerium Market
Metals
Global Copper Market
Metals
Reconditioned Steel Drums Market
Metals
Aluminium Rolled Products Market
Metals
North America and Europe Metal Powder Market
Metals
Aluminum Slugs Market
Metals
Silver Sulphate Market
Metals
Qatar Metalworking Market
Metals
Barium Market
Metals
Ferrosilicon Market
Metals
Steel Salvage Drums Market
Metals
Metal Forging Market
Metals
Copper and Copper Alloy Foil Market
Metals
Global Copper Sputtering Target Market